LuxeAnalyst

vip
Active for: 0.7y
Peak Tier 0
Student,crypto lover
The U.S. economy in 2026 presents a picture of surface-level resilience masking deeper structural tension. Multiple institutional forecasts converge on growth around 2% to 2.4%, yet inflation persists above the Federal Reserve's target, and the central bank remains caught between competing risks.
According to IMF projections, U.S. growth is expected at 2.3% in 2026 and 2.2% in 2027, supported by fiscal policy, accommodative financial conditions, and continued technology-related business investment . Guggenheim similarly sees real GDP growth around 2% for both years, underpinned by artificial i
WhyFay
The U.S. economy in 2026 presents a picture of surface-level resilience masking deeper structural tension. Multiple institutional forecasts converge on growth around 2% to 2.4%, yet inflation persists above the Federal Reserve's target, and the central bank remains caught between competing risks.
According to IMF projections, U.S. growth is expected at 2.3% in 2026 and 2.2% in 2027, supported by fiscal policy, accommodative financial conditions, and continued technology-related business investment . Guggenheim similarly sees real GDP growth around 2% for both years, underpinned by artificial intelligence capital expenditures . Goldman Sachs recently lowered its 12-month recession probability from 25% to 15%, citing labor market resilience and reduced geopolitical risk following the U.S.-Iran ceasefire .
The inflation picture is more complex. Core PCE inflation has remained elevated in 2026, with year-over-year readings expected to end the year above 3% . The Federal Reserve's June projections revised its 2026 PCE inflation forecast upward from 2.7% to 3.6%, and core PCE from 2.7% to 3.3% . Tariff effects have receded, but new inflationary impulses have emerged from AI capital expenditure spillovers and energy price pass-through .
This has placed the Fed in a holding pattern. The federal funds rate has remained at 3.50%-3.75% since December 2025, and most economists surveyed by Reuters expect no cuts through 2026 . The Fed's June projections raised the median policy rate expectation for end-2026 from 3.4% to 3.8% . A near-85% majority of economists polled predicted the rate would remain steady through the third quarter . Fed Chair Kevin Warsh faces a divided committee, with some officials favoring cuts and others concerned about inflation persistence .
The underlying concern is the narrowness of U.S. growth drivers. Guggenheim notes that with weak real income growth, the expansion relies increasingly on tech investment and wealth-driven consumer spending. Any disruption to the AI investment thesis could present a downside risk . Goldman Sachs also attributes its more optimistic growth revision to AI investment momentum and real income gains from lower natural gas prices .
Globally, the IMF lowered its 2026 world growth forecast to 3.0% from 3.1% in April, while holding the U.S. forecast steady . The U.S. position as a net energy exporter has limited the impact of Middle East conflict on its economy compared to other regions .
The trajectory ahead depends on whether inflation moderates as the Fed expects, and whether the AI-driven investment cycle continues to offset weaker consumer fundamentals. The debate between economists projecting cuts versus hikes reflects genuine uncertainty rather than consensus, and the Fed's wait-and-see approach appears likely to persist until one set of risks clearly dominates.
#AugustCoreCPIBeatsExpectations ##ShareWeekly

GS+0.90%
$GBPJPY $USDJPY $EURJPY
The Yen Awakens: How Japan's Quiet Tightening Is Rewriting the Rules of Global Finance
Good morning. If you are reading this from a trading floor in London, a hedge fund office in New York, or a treasury desk in Singapore, the chart that should be commanding your attention this week is not the S&P 500 or the price of Brent crude. It is the Japanese yen. After years of languishing at levels that made it the world's favourite funding currency, the yen has staged a rally that is forcing investors across every asset class to reconsider long-held assumptions. The curr
SinCity
$GBPJPY ‌$USDJPY ‌$EURJPY ‌
The Yen Awakens: How Japan's Quiet Tightening Is Rewriting the Rules of Global Finance
Good morning. If you are reading this from a trading floor in London, a hedge fund office in New York, or a treasury desk in Singapore, the chart that should be commanding your attention this week is not the S&P 500 or the price of Brent crude. It is the Japanese yen. After years of languishing at levels that made it the world's favourite funding currency, the yen has staged a rally that is forcing investors across every asset class to reconsider long-held assumptions. The currency strengthened to its highest level since February against the dollar this week, touching 152.89 per dollar before settling near 153.48, a move that has surprised even seasoned market participants. Behind this shift lies a simple but profound reality: the Bank of Japan is no longer the outlier it once was.
For much of the past decade, Japan occupied a unique position in the global financial architecture. It was the economy that refused to normalise. While the Federal Reserve, the European Central Bank, and the Bank of England raised rates to combat post-pandemic inflation, the BOJ held its policy rate at minus 0.1 percent, maintaining a commitment to ultra-loose monetary conditions that made the yen the cheapest major currency to borrow. This divergence created one of the most lucrative and persistent trades in modern finance: the yen carry trade. Investors would borrow yen at near-zero cost, convert the proceeds into higher-yielding currencies, and pocket the difference. Estimates suggest that cross-border yen borrowing, a proxy for the carry trade, reached a record 360 trillion yen, or roughly 2.35 trillion dollars, as of March, according to an analysis by Jefferies based on Bank for International Settlements data. This was the largest carry-trade build-up in three decades, and it became a foundational pillar of global risk appetite.
That pillar is now under strain. The BOJ has already raised its policy rate to 1.0 percent, and market expectations point overwhelmingly toward another quarter-point increase to 1.25 percent at the conclusion of its two-day meeting on September 18. According to Tokyo Tanshi data, the odds of this hike stand at 97 percent, up from just 52 percent a month ago. More significantly, a Bloomberg survey of 52 economists found that every single one expects a September move, and nearly half anticipate the BOJ will now raise rates once per quarter, a dramatic acceleration from the previous pace of one hike every six months. The terminal rate expectation has settled around 1.75 percent, implying three more increases beyond September. This is not a marginal adjustment. It is a fundamental shift in the cost of the world's most important funding currency.
The yen's rally is already triggering visible consequences. "The carry trade is vulnerable because this unwind is happening before the BOJ has even delivered its expected hike," said Charu Chanana, chief investment strategist at Saxo, as reported by Reuters. "Some yen shorts have already been cut, but positioning still looks sizeable, so further yen strength can turn a gradual reduction in leverage into a much faster, self-reinforcing unwind." The yen has marched nearly 5 percent higher so far in September against the usual carry-trade favourites, including the Mexican peso and the Turkish lira. A further unwind, according to State Street's Masahiko Loo, could push the dollar-yen pair toward the mid-140s given the substantial outstanding short position.
The implications for global markets are neither hypothetical nor distant. When investors borrow in yen to fund positions in higher-yielding assets, a rising yen makes those loans more expensive to repay. If the appreciation is sharp enough, it can force leveraged funds to sell those assets to cover losses, creating a feedback loop that amplifies volatility across equities, bonds, and currencies. This is precisely what happened in August 2024, when a BOJ rate hike sent shockwaves through global markets for days. The stakes this time are arguably higher. The carry trade has grown larger, the positioning more crowded, and the geopolitical backdrop more fragile. Oil prices above 100 dollars a barrel, an active conflict between the United States and Iran, and an uncertain American inflation trajectory all compound the risk.
Yet it would be a mistake to frame this solely as a story of impending crisis. The yen's appreciation reflects something more constructive: the gradual normalisation of an economy that has spent a generation in the wilderness of deflation and stagnation. Japan's consumer price inflation has remained above the BOJ's 2 percent target, running between 2.5 and 3 percent in recent government data. The central bank has acknowledged that its economy "has recovered moderately," though it also cautioned that exports will be affected by higher tariffs stemming from American trade policy. Real GDP grew at an annualised 1.1 percent in the April-June quarter, marking a third consecutive quarter of positive growth, though private consumption and capital investment both softened. The Nikkei 225 has hit record highs, buoyed by the Fed's recent rate cut and the broader reflation narrative.
The political dimension adds another layer of complexity. Prime Minister Shigeru Ishiba is stepping down, and the ruling Liberal Democratic Party is holding a leadership election, with five candidates expected to enter the race. The BOJ itself has cited domestic political uncertainty as a risk factor. The outcome of this leadership contest will shape fiscal policy in the months ahead and could influence the pace of monetary tightening. Meanwhile, the United States has shown a willingness to intervene in currency markets alongside Japan, as it did in July when the yen hit 40-year lows. U.S. Treasury Secretary Scott Bessent has referred to the potential for additional Japanese intervention, and ECB policymaker Joachim Nagel has indicated that coordinated action could be welcomed under certain circumstances. This cooperative stance suggests that the major economies are not indifferent to the yen's trajectory and are prepared to act if disorderly moves threaten financial stability.
What should a careful observer watch in the coming weeks? First, the BOJ's policy statement on September 18 and Governor Ueda's subsequent press conference. The language used will matter as much as the rate decision itself. If the BOJ signals that further hikes are contingent on data and proceed gradually, the yen may stabilise. If it hints at a faster pace, the carry-trade unwind could accelerate. Second, the reaction of global equity markets, particularly in the United States, where high-valuation technology stocks have benefited disproportionately from cheap yen funding. Third, the trajectory of oil prices. If Brent crude remains above 100 dollars, the inflationary pressure on Japan, a major energy importer, will intensify, reinforcing the case for tighter policy.
The deeper truth is that the era of free money from Japan is ending. For years, the yen carry trade served as a quiet subsidy for global risk assets, allowing investors to borrow cheaply and chase returns elsewhere. That subsidy is now being withdrawn, not abruptly, but steadily and deliberately. The world is adjusting to a Japan that is no longer the exception to the rules of monetary orthodoxy. How smoothly that adjustment proceeds will depend on the wisdom of policymakers, the resilience of markets, and the willingness of investors to recognise that the landscape has changed. The yen's awakening is not a crisis. It is a correction. And corrections, however uncomfortable, are how markets rediscover equilibrium.
NFA ✔️ DYOR 🔎
#AugustCoreCPIBeatsExpectations #ShareWeekly
GBPJPY+0.16%
USDJPY+0.34%
EURJPY+0.06%
SPX500-0.48%
US500-0.49%
A shepherd, while grazing his goats, noticed that some wild goats had joined his flock. When evening came, he locked them all together in his pen.
The next day, a huge storm broke out, and the shepherd couldn't let the animals out. To keep the newly arrived wild goats in the pen and get used to him, he put plenty of the best feed in front of them. He gave his old goats, however, just enough to keep them from dying, thinking they were always under his care.
When the storm ended and the gate opened, the wild goats started running towards the mountains without even looking back. The shepherd angr
User_any
A shepherd, while grazing his goats, noticed that some wild goats had joined his flock. When evening came, he locked them all together in his pen.
The next day, a huge storm broke out, and the shepherd couldn't let the animals out. To keep the newly arrived wild goats in the pen and get used to him, he put plenty of the best feed in front of them. He gave his old goats, however, just enough to keep them from dying, thinking they were always under his care.
When the storm ended and the gate opened, the wild goats started running towards the mountains without even looking back. The shepherd angrily shouted after them:
"I took better care of you than my own goats, I gave you the best feed, you ungrateful wretches!"
One of the wild goats turned and gave this unforgettable reply:
"That's exactly why we're running away! You gave us the best feed, which you never gave your old goats. We know very well that when other new goats arrive in your pen tomorrow, you'll neglect us and give them the best feed too!"
🤔 People who neglect their long-time loyal friends for the sake of newly acquired friendships or personal gain cannot be trusted. Those who try to please newcomers will eventually lose their true friends as well.
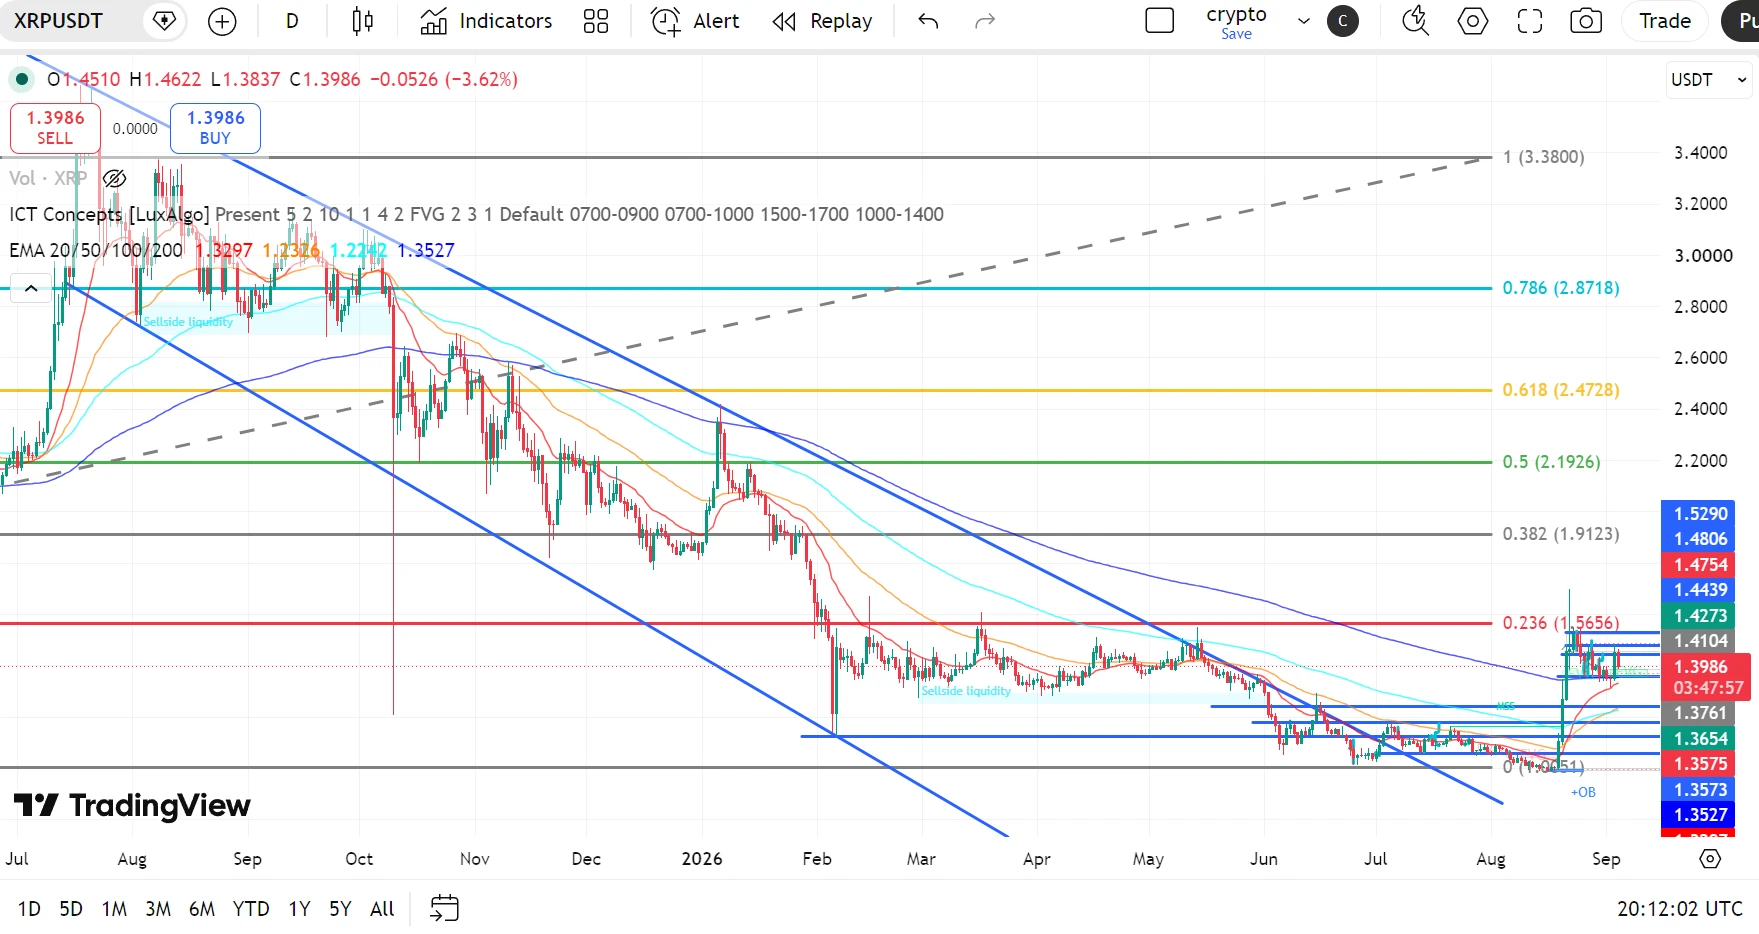
XRP Technical Outlook: XRP Holds Breakout Zone as Bulls Target $1.56–$1.91
XRP is showing a strong bullish recovery after breaking out from the prolonged descending structure. Price has reclaimed the $1.35–$1.38 area and is currently holding around the $1.40 region.
The latest market structure remains constructive, but XRP needs to clear the $1.4104–$1.4439 resistance cluster for the bullish move to gain stronger confirmation. Recent market analysis also identifies the $1.35–$1.40 area as an important demand/support region.
📈 EMA Structure
- 20 EMA: $1.3297
- 50 EMA: $1.2326
- 100 EMA: $1.224
asiftahsin
XRP Technical Outlook: XRP Holds Breakout Zone as Bulls Target $1.56–$1.91
XRP is showing a strong bullish recovery after breaking out from the prolonged descending structure. Price has reclaimed the $1.35–$1.38 area and is currently holding around the $1.40 region.
The latest market structure remains constructive, but XRP needs to clear the $1.4104–$1.4439 resistance cluster for the bullish move to gain stronger confirmation. Recent market analysis also identifies the $1.35–$1.40 area as an important demand/support region.
📈 EMA Structure
- 20 EMA: $1.3297
- 50 EMA: $1.2326
- 100 EMA: $1.2242
- 200 EMA: $1.3527
XRP is currently trading above all four major EMAs.
The most important development is the recovery above the 200 EMA at $1.3527 and the subsequent expansion above the short-term EMA structure.
The 20 EMA at $1.3297 is now an important dynamic support level and could act as major trend support if XRP experiences a deeper correction.
📐 Fibonacci Levels
Key Fibonacci levels:
- 0.236: $1.5656
- 0.382: $1.9123
- 0.5: $2.1926
- 0.618: $2.4728
- 0.786: $2.8718
- 1.0: $3.3800
XRP has reclaimed the lower Fibonacci region, while the next major higher-timeframe Fibonacci resistance is positioned at $1.5656.
A sustained move above the current resistance cluster could therefore open the path toward the 0.236 Fibonacci level at $1.5656.
🟢 Bullish Scenario
XRP has broken out from the long-term descending structure and is now attempting to build acceptance above the $1.38–$1.40 area.
Immediate resistance:
- $1.4104
- $1.4273
- $1.4439
- $1.4754
- $1.4806
- $1.5290
A clean breakout and sustained close above $1.4439–$1.4806 would strengthen the bullish continuation setup.
🎯 Target 1: $1.4806
🎯 Target 2: $1.5290
🎯 Target 3: $1.5656 — 0.236 Fibonacci
🎯 Target 4: $1.9123 — 0.382 Fibonacci
A confirmed breakout above $1.5656 would significantly improve the medium-term structure and potentially open the way toward the $1.91 region.
🔴 Pullback Scenario
After the recent sharp expansion, a retest of the reclaimed breakout area would be normal.
Key supports:
- $1.3761
- $1.3654
- $1.3575
- $1.3527 — 200 EMA
- $1.3297 — 20 EMA
The $1.35–$1.38 zone is particularly important.
If XRP holds this area during a pullback, the current breakout structure remains intact.
A sustained loss of $1.3527 would weaken the immediate bullish setup and could expose the $1.3297 20 EMA.
🧠 Market Structure & Liquidity
XRP spent an extended period trading inside a broad descending structure before forming a prolonged consolidation near the $1.35 area.
The recent price action shows a liquidity sweep around the $1.35 region, followed by strong bullish expansion and a market-structure shift.
Price has now broken above the previous descending trend structure and is holding near the $1.40 region.
This creates an important:
Breakout → Retest → Continuation
sequence.
The main upside liquidity and resistance area is currently concentrated around $1.4104–$1.4806.
📊 RSI Momentum
RSI (14): 60.09
RSI has recovered strongly and remains above the neutral 50 level.
This confirms positive bullish momentum without being deeply overbought. A continued RSI hold above 50–55 would favor further upside.
A sharp rejection accompanied by RSI falling below 50 would indicate weakening momentum.
🎯 Key Levels
🔴 Major Resistance: $1.4104 → $1.4273 → $1.4439 → $1.4754–$1.4806 → $1.5290 → $1.5656
🟢 Major Support: $1.3761 → $1.3654 → $1.3575 → $1.3527
📉 Dynamic EMA Support: $1.3297 — 20 EMA | $1.3527 — 200 EMA
🚀 Upside Targets: $1.4806 → $1.5290 → $1.5656 → $1.9123
📌 Final Outlook
XRP's structure has improved significantly following the breakout from the prolonged descending structure.
The $1.35–$1.38 zone is now the key short-term support area. As long as XRP holds above this region, the bullish structure remains valid.
The immediate battle is around $1.4104–$1.4806. A confirmed breakout above this zone could accelerate the move toward $1.5290 → $1.5656, followed by $1.9123.
However, rejection from resistance followed by a sustained loss of $1.3527 would weaken the immediate bullish momentum and increase the probability of a deeper retracement toward the $1.33 area.
Bias: 🟢 Bullish above $1.3527. A breakout above $1.4806 could open the path toward $1.5656, with $1.9123 as the next major Fibonacci target.
$XRP
repost-content-media
XRP+0.71%
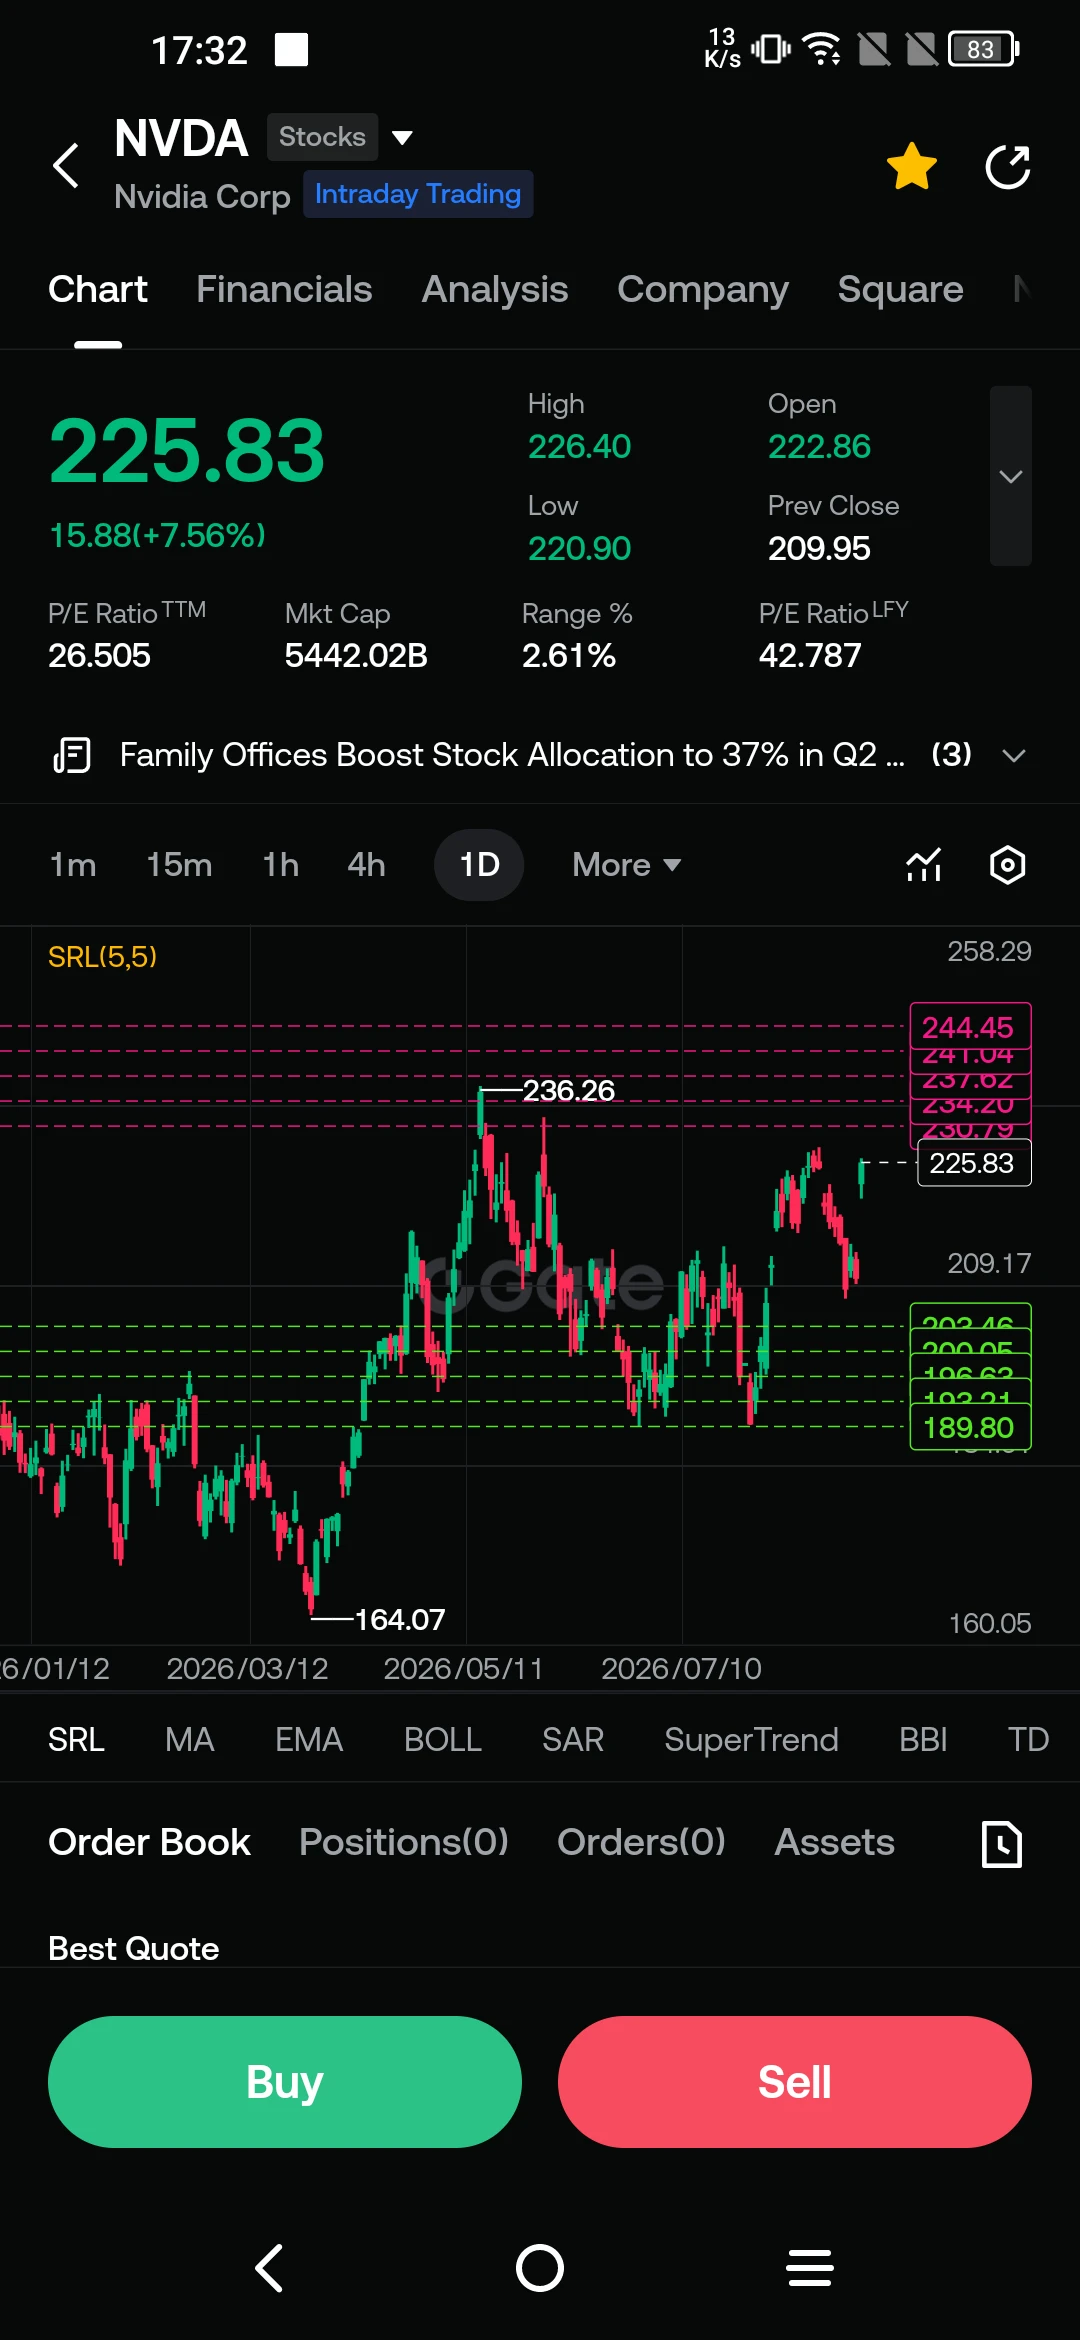
$NVDA ‌Nvidia (NVDA) stock is trading at $230.37, up 0.86% in intraday trading. The daily range is between $229.85 and $234.75, having opened at $231.09. The company, which closed at $228.40 yesterday, has a total market capitalization of $5.55 trillion ($5,549.98 billion), with a Price-to-Earnings (P/E) ratio of 29.195 and a year-to-date P/E ratio of 47.13.
On the technical side, the positive alignment of moving averages continues to support the price from below. On the daily chart, the 5-day moving average (MA5) is at $224.31, the 10-day moving average (MA10) is at $219.84, and the 30-day
WhyFay
$NVDA ‌Nvidia (NVDA) stock is trading at $230.37, up 0.86% in intraday trading. The daily range is between $229.85 and $234.75, having opened at $231.09. The company, which closed at $228.40 yesterday, has a total market capitalization of $5.55 trillion ($5,549.98 billion), with a Price-to-Earnings (P/E) ratio of 29.195 and a year-to-date P/E ratio of 47.13.
On the technical side, the positive alignment of moving averages continues to support the price from below. On the daily chart, the 5-day moving average (MA5) is at $224.31, the 10-day moving average (MA10) is at $219.84, and the 30-day moving average (MA30) is at $215.46. The upward momentum, starting from the $164.07 low tested in April, is consolidating the price near the $236.26 peak resistance.
Supply Commitments and High-Bandwidth Memory (HBM) Dynamics
The most critical data highlighted in the company's official SEC filings is the long-term order commitments to the supply chain. Nvidia's total long-term supply commitments have reached $279 billion, with approximately $267 billion allocated to memory and manufacturing capacity supply until the end of fiscal year 2029. This massive order backlog provides a cash flow guarantee that directly supports the revenue outlook and share performance of major memory manufacturers like Micron (MU).
An examination of the maturity structure of supply agreements reveals a timeline that the market should follow:
Near-Term Order Concentration: Previously committed supply obligations are concentrated at levels of approximately $88 billion annually until fiscal years 2028 and 2029.
Fiscal Year 2030 Decline: By fiscal year 2030, the current backlog of committed orders is projected to sharply decline to $6 billion.
Market Pricing Risk Architecture: If high-priced new memory and foundry contracts for the post-2029 period are not renewed, capital markets may prematurely price this situation between the end of 2028 and the beginning of 2029.
Corporate Governance and Supply Chain Strategy
Nvidia management defines these massive procurement commitments not as passive obligations, but as strategic infrastructure reservations that maintain a competitive advantage in the AI hardware market. The fact that HBM capacity, critical for high-performance computing and GPU architectures, is reserved years in advance ensures foundry capacity and provides uninterrupted deliveries for the company.
You can track these long-term contract dynamics in the global semiconductor sector, Nvidia (NVDA) stock price levels, and order book depth in real-time through the Gate platform.
#Nvidia #NVDA #Micron #Semiconductors #MarketUpdate
$NVDA ‌ DYOR 🔎 NFA ✔️
NVDA-0.09%
MU-0.51%
  • 1
$TSLA ‌TSLA shares are trading down 6.36% at $352.41 in intraday trading. The daily trading range is between $351.34 and $364.68, with the stock opening at $362.07. The company, which closed at $376.35 yesterday, has a total market capitalization of $1.39 trillion ($1,391.74 billion), and its Price/Earnings (P/E) ratio is recorded at 325.54.
In terms of technical indicators, short-term moving averages show the pressure on the price and potential support levels. The MA5 level at $361.95 and the MA10 level at $355.80 are forming resistance just above the current price, while the MA30 level at $
WhyFay
$TSLA ‌TSLA shares are trading down 6.36% at $352.41 in intraday trading. The daily trading range is between $351.34 and $364.68, with the stock opening at $362.07. The company, which closed at $376.35 yesterday, has a total market capitalization of $1.39 trillion ($1,391.74 billion), and its Price/Earnings (P/E) ratio is recorded at 325.54.
In terms of technical indicators, short-term moving averages show the pressure on the price and potential support levels. The MA5 level at $361.95 and the MA10 level at $355.80 are forming resistance just above the current price, while the MA30 level at $337.36 represents the lower support line. Although the upward reaction that started from the $297.38 low tested in August continues, a consolidation process is underway below the $453.40 peak recorded in May.
Internal developments and operational processes are focused on autonomous driving technologies and commercialization steps. The Cybercab and Robotaxi fleet operations launched in Austin, Texas, symbolize Tesla's transformation strategy beyond its identity as an automotive manufacturer, becoming a high-margin software and autonomous transportation platform. Mileage data accumulation in the FSD (Full Self-Driving) system, subscription model revenues, and growth in energy storage units are among the factors supporting the company's financial stability against fluctuations in traditional vehicle deliveries.
Macroeconomic pressures are affecting the overall state of the automotive and electric vehicle (EV) sector. The restrictive effect of the high interest rate environment on vehicle loans and increasing global market competition (especially from China-based manufacturers and BYD moves) are limiting traditional vehicle sales volumes. Despite price competition in the sector, Tesla's AI infrastructure, vertically integrated production model, and emphasis on its charging network stand out as key factors differentiating the company from the rest of the industry.
Market valuation discussions continue to revolve around whether the company should be priced as an automotive manufacturer or an AI platform. You can track the real-time price flow, order book balance, and technical indicators for Tesla (TSLA) stock via the Gate platform.
#Tesla #TSLA #MarketUpdate #TechStocks
$TSLA ‌ DYOR 🔎 NFA ✔️
TSLA+0.51%
  • 2
$XTIUSD ‌Crude oil prices have shown a significant upward trend in recent days. WTI is trading at $86.39, while Brent oil is finding buyers at $92.14. Both types of oil have gained between 2.3% and 2.8%.
So what's behind this rise? Let's look at developments in the last 24 hours and the past week.
Events in the Last 24 Hours
Production Cuts: Cyberattacks targeting energy infrastructure in the Gulf of Mexico by the US and increased hurricane activity in the region triggered supply concerns.
Surprise Demand from Japan: The Bank of Japan's announcement of a currency swap agreement for energy imp
SinCity
$XTIUSD ‌Crude oil prices have shown a significant upward trend in recent days. WTI is trading at $86.39, while Brent oil is finding buyers at $92.14. Both types of oil have gained between 2.3% and 2.8%.
So what's behind this rise? Let's look at developments in the last 24 hours and the past week.
Events in the Last 24 Hours
Production Cuts: Cyberattacks targeting energy infrastructure in the Gulf of Mexico by the US and increased hurricane activity in the region triggered supply concerns.
Surprise Demand from Japan: The Bank of Japan's announcement of a currency swap agreement for energy imports positively impacted expectations regarding oil demand in Asian markets.
Restocking Movements: Signals that the US Department of Energy may purchase to replenish strategic oil reserves supported prices.
Key Developments of the Last Week
OPEC+ Meeting: The OPEC+ group held a technical meeting this week to assess market conditions. The signals from the meeting indicated that current production cuts will continue.
Inventory Data: Data from the US Energy Information Administration showed that crude oil inventories decreased more than market expectations last week. The decline in inventories reinforced the perception of strong demand.
Production Challenges in Libya: Technical problems at production facilities in Libya caused a supply loss of approximately 300,000 barrels per day. This further narrowed the already limited global supply surplus.
Near-Term Watch Out For
US Data: Weekly jobless claims and growth data will provide clues about the trajectory of oil demand.
Chinese Purchases: China's new economic stimulus package may increase energy imports. This could support prices upwards.
Japanese Decisions: The Bank of Japan's monetary policy decisions will affect oil pricing in yen.
The oil market continues its upward trend with supply-side cuts and optimistic expectations regarding demand. In the coming days, OPEC+ signals and US inventory data will be decisive in determining the direction of prices.
The information shared here is not investment advice. Do your own research.
XTIUSD+2.48%
BZ+2.19%
  • 1
$XAGUSD The Anatomy of the Decline in Gold and Silver: The Fed, Geopolitics, and New Demand
The precious metals market has been under intense selling pressure in recent days. Gold is trading down 0.50% at $4,432, and silver is down 0.21% at $66.20. Both metals are attempting to recover after the sharp losses experienced on Friday.
Signals from the Fed
The main pressure on precious metals stemmed from Federal Reserve Chairman Kevin Warsh's speech at the Jackson Hole symposium. Warsh emphasized that inflation has not yet reached the desired level, clearly stating that the Fed is not finished un
SinCity
$XAGUSD The Anatomy of the Decline in Gold and Silver: The Fed, Geopolitics, and New Demand
The precious metals market has been under intense selling pressure in recent days. Gold is trading down 0.50% at $4,432, and silver is down 0.21% at $66.20. Both metals are attempting to recover after the sharp losses experienced on Friday.
Signals from the Fed
The main pressure on precious metals stemmed from Federal Reserve Chairman Kevin Warsh's speech at the Jackson Hole symposium. Warsh emphasized that inflation has not yet reached the desired level, clearly stating that the Fed is not finished until the 2% target is reached.
These statements caused markets to raise the probability of a rate hike at the September meeting from 35% to 57-60%. The expectation of a rate hike reduces the attractiveness of non-yielding assets like gold and silver. The US 10-year Treasury yield rose to 4.73%, while the dollar index strengthened to 99.71.
Geopolitical Tensions
The recent military tensions between the US and Iran have driven up oil prices and added a new element of uncertainty to the markets. WTI rose to $86.39 and Brent to $92.14, reigniting inflation concerns. High energy prices make it difficult for central banks to ease monetary policy.
New Areas of Demand
While precious metals are under pressure in the short term, new areas of demand are emerging in the medium to long term.
A Major Move from South Korea: Mirae Asset Financial Group plans to build a digital asset business worth 150 trillion won (approximately $109 billion) through its Digital X platform. This plan aims to tokenize gold, silver, and electricity. Mirae Asset's customer assets of 1,500 trillion won constitute a significant resource for achieving this goal.
Türkiye's Gold Move: The Central Bank of the Republic of Turkey held a lira-for-6-ton gold swap auction. This move demonstrates the role gold plays in reserve management strategies.
Short and Medium-Term Outlook
Technically, gold experienced a sharp 3.2% drop on Friday. This was the largest daily loss since early June. Despite this, gold gained approximately 10% in August, exhibiting its strongest monthly performance since January.
Experts are setting the $4,300-$4,700 range for gold and $70-$85 for silver as their base scenario for the upcoming period. In an optimistic scenario, gold has the potential to rise to $5,000-$5,600 and silver to $95-120.
The upcoming US non-farm payroll data will be critical for the Fed's September decision. Weak data could reduce expectations of interest rate hikes, supporting precious metals.
The information shared here is not investment advice. Do your own research.
XAGUSD-0.82%
XAUUSD-0.38%
$NVDA #NVIDIAEarnings
Nvidia's Q2 2027 Earnings Report: Record Revenue, Cash Flow Pressure
In its earnings report released on August 26th, NVDA exceeded its own guidance ($91 billion) with revenue of $96.2 billion, representing a 106% year-over-year increase. Data center revenue grew 117% year-over-year to $89 billion, accounting for almost all of the total. Gross margins remained at 75%, while guidance for Q3 was set at 74% – signaling a slight easing in margins.
The main focus was on cash flow: Cash flow from operations fell 52% quarter-over-quarter, and free cash flow decreased by 56%; a
User_any
$NVDA #NVIDIAEarnings
Nvidia's Q2 2027 Earnings Report: Record Revenue, Cash Flow Pressure
In its earnings report released on August 26th, NVDA exceeded its own guidance ($91 billion) with revenue of $96.2 billion, representing a 106% year-over-year increase. Data center revenue grew 117% year-over-year to $89 billion, accounting for almost all of the total. Gross margins remained at 75%, while guidance for Q3 was set at 74% – signaling a slight easing in margins.
The main focus was on cash flow: Cash flow from operations fell 52% quarter-over-quarter, and free cash flow decreased by 56%; a $22.3 billion increase in receivables and inventory buildup delayed cash conversion. Long-term debt increased from $7.5 billion to $32.4 billion, with $24.9 billion in borrowing during the quarter.
Post-Earnings Strategic Moves:
• Strategic partnership and minority stake investment with Cloverleaf Infrastructure – focusing on cooling and energy infrastructure
• Multi-year partnership with SB Energy for the PORTS Technology Campus – $105 billion guaranteed obligation for ~4.25 GW of capacity where OpenAI will be a tenant
• CEO Jensen Huang: “We have entered the AI infrastructure era. Now, computing power itself is revenue.”
👉 The growth story continues unabated. However, the balance to watch in the coming quarters will be whether accounts receivable and inventory accumulation are converted to cash and whether the decline in margin guidance is permanent. Although the stock experienced sharp volatility after the earnings report, the momentum in data center demand is the main supporting factor.
DYOR 🔎 NFA ✔️
#GateStockInsightsChallenge #NVIDIAEarnings
#Gate
repost-content-media
NVDA-0.09%
$NVDA 🧐
NVIDIA's $160 Billion Move: Inventory and Supply Revolution
Everyone Focused on the Record $96 Billion Revenue in the Financial Statement, But the Real Bomb Was the Supply and Inventory Figures
In NVIDIA's second-quarter financial statement, attention was drawn to the record revenue of $96.2 billion. However, two data points hidden deep within the financial statements reveal the true scale of the company's strategic move.
Huge Leap in Supply Obligations
In one quarter, supply obligations jumped from $119 billion to $279 billion. This represents a net $160 billion in new commitments,
User_any
$NVDA 🧐
NVIDIA's $160 Billion Move: Inventory and Supply Revolution
Everyone Focused on the Record $96 Billion Revenue in the Financial Statement, But the Real Bomb Was the Supply and Inventory Figures
In NVIDIA's second-quarter financial statement, attention was drawn to the record revenue of $96.2 billion. However, two data points hidden deep within the financial statements reveal the true scale of the company's strategic move.
Huge Leap in Supply Obligations
In one quarter, supply obligations jumped from $119 billion to $279 billion. This represents a net $160 billion in new commitments, 66% more than a single quarter's revenue. Of this amount, $92 billion will be paid this fiscal year, with the remainder spread over the next two years.
Striking Change in Inventory Dynamics
The change in inventory items clearly demonstrates NVIDIA's production strategy. Raw material inventory has increased from $3.8 billion in January to $11.3 billion – almost threefold. Work-in-process inventory rose to $13.4 billion, while finished-in-shipment inventory fell from $8.8 billion to $6.9 billion. This shows that the company sells what it produces immediately but has stockpiled record levels of raw materials for upcoming production.
Margin Dynamics and Future Guidance
Gross margin remained stable at 75%, while the company provided guidance of 74% for the next quarter. This marks the first conscious margin decline in the current cycle. The main reasons cited for the decline are rising memory prices and the Rubin platform transition process.
The Strategic Vision Behind the Move
At the heart of all these commitments is CEO Jensen Huang's clear vision: "These systems are no longer PCs or phones, they are revenue-generating assets." NVIDIA sees capital and infrastructure as the only constraints hindering demand and is working to remove this bottleneck with all its financial tools.
Growing Ecosystem
With strategic moves announced after the earnings report, the company is building a massive ecosystem in the triangle of "financing + supply chain + software." The $105 billion guarantee to SB Energy, the hundreds of millions of dollars investment in Cloverleaf, and the $12.9 billion acquisition of Hugging Face stand out as concrete steps in this strategy.
Critical Indicators to Watch
The most critical indicator for investors to watch in the coming period will be the speed at which these supply obligations are converted into cash. Furthermore, whether the 60-day DSO trend in receivables continues will be decisive for the company's cash flow health. With these strategic moves, NVIDIA is not only meeting current demand but also taking steps to secure future growth.
DYOR 🔎 NFA ✔️
#NVIDIAEarnings #GateStockInsightsChallenge
repost-content-media
NVDA-0.09%
  • 1
NVIDIA's Silent Invasion: Expanding Its Kingdom by Acquiring Rivals
NVIDIA's Real Move Beyond Revenue Figures: A Strategy to Turn Rivals into "Friends"
While everyone focused on NVIDIA's record revenue of $96.2 billion in its second-quarter earnings report, the company's real strategic move is happening far beyond the financial statements. NVIDIA continues to expand its ecosystem by acquiring rivals or forming strategic partnerships.
1. Hugging Face: A $12.9 Billion Open Source Acquisition
NVIDIA is reportedly agreeing to acquire the open-source AI platform Hugging Face for $12.9 billion. This
User_any
NVIDIA's Silent Invasion: Expanding Its Kingdom by Acquiring Rivals
NVIDIA's Real Move Beyond Revenue Figures: A Strategy to Turn Rivals into "Friends"
While everyone focused on NVIDIA's record revenue of $96.2 billion in its second-quarter earnings report, the company's real strategic move is happening far beyond the financial statements. NVIDIA continues to expand its ecosystem by acquiring rivals or forming strategic partnerships.
1. Hugging Face: A $12.9 Billion Open Source Acquisition
NVIDIA is reportedly agreeing to acquire the open-source AI platform Hugging Face for $12.9 billion. This will be one of the company's largest acquisitions to date.
Strategic Significance:
Hugging Face is at the heart of the developers' ecosystem, housing approximately 3 million open models and 1 million datasets. While closed-source companies like NVIDIA, OpenAI, and Anthropic develop their own chips, NVIDIA aims to connect independent developers to its hardware by investing in the open-source ecosystem. The price tag (86 times the annualized revenue of approximately $150 million) suggests NVIDIA is making this acquisition for strategic control, not revenue.
Critical Point: Hugging Face currently supports AMD and Intel chips as well. Whether the platform can maintain its neutrality after the acquisition is the biggest question mark.
2. Rebellions: Secret Meetings with South Korea's Favorite
According to Bloomberg, NVIDIA CEO Jensen Huang has personally met with South Korean AI chip startup Rebellions. Possibilities include a technical partnership, investment, or a direct acquisition.
Who is Rebellions?
The company is valued at $2.3 billion and its investors include SK Hynix and Samsung Ventures. Developing AI inference-focused NPUs – this represents a large-volume market that will complement NVIDIA's strength in training. It also utilizes Samsung's 4nm manufacturing – potentially opening a second supply chain for NVIDIA besides TSMC.
Regulatory Risk: South Korea considers semiconductors a strategic asset; the US Department of Justice could also scrutinize NVIDIA's dominance from an antitrust perspective.
3. The Big Picture: The "Transform the Enemy" Strategy
In 2025, NVIDIA made a similar deal with Groq, absorbing its engineering team while leaving the company independent. It is now applying the same pattern with Rebellions and Hugging Face.
CEO Jensen Huang's secret formula: Instead of eliminating competitors, make them part of the ecosystem. This will:
• Send a message to regulators: "We are not monopolizing, we are cooperating"
• Expand the talent pool
• Reduce the need for customers to seek alternatives
Investor Note
The company announced a commitment to $18 billion in equity investments by fiscal year 2027. This shows that NVIDIA is taking determined steps towards becoming not just a chip vendor, but also the financier and architect of the entire AI ecosystem.
Risk to Watch: The integration of these acquisitions and the reaction of the open-source community will be the most critical points to watch in the coming period.
All assessments and comments here are purely personal and are absolutely not investment advice.
#NVIDIAEarnings #GateStockInsightsChallenge
repost-content-media
NVDA-0.09%
SK Hynix-5.68%
TSM+1.13%
AMD+2.54%
INTC+2.63%
$SKHYNIX #SKHynixSurgesOver5%
NVIDIA Earnings Ignite Asia: Korean Semiconductor Giants Rise
SK Hynix Rises Over 5%, Samsung Over 3%; KOSPI Approaches 7,000
NVIDIA's second-quarter earnings for fiscal year 2027 sent shockwaves not only through the US market but also across the global semiconductor market. During Asian trading hours, leading South Korean memory manufacturers surged following NVIDIA's better-than-expected results and strong guidance.
At the open, SK Hynix shares gained over 5%, while Samsung Electronics rose more than 3%. This momentum pushed the KOSPI index up by approximately
User_any
$SKHYNIX #SKHynixSurgesOver5%
NVIDIA Earnings Ignite Asia: Korean Semiconductor Giants Rise
SK Hynix Rises Over 5%, Samsung Over 3%; KOSPI Approaches 7,000
NVIDIA's second-quarter earnings for fiscal year 2027 sent shockwaves not only through the US market but also across the global semiconductor market. During Asian trading hours, leading South Korean memory manufacturers surged following NVIDIA's better-than-expected results and strong guidance.
At the open, SK Hynix shares gained over 5%, while Samsung Electronics rose more than 3%. This momentum pushed the KOSPI index up by approximately 3%, bringing it closer to the 7,000 level.
NVIDIA Effect: Better-than-Expected Earnings
NVIDIA's announced quarterly revenue of $96.2 billion significantly exceeded market expectations of $92.2 billion. Data center revenues exceeded expectations, reaching $89 billion, while earnings per share also surpassed estimates at $2.22. The company's guidance of approximately 70% growth for fiscal year 2028 significantly exceeded the market's expectation of around 45%.
These strong results were interpreted as a direct demand signal for memory manufacturers in Asia. SK Hynix and Samsung are key suppliers of high-bandwidth memory (HBM) used in NVIDIA's AI chips.
A New Era in the Memory Market
NVIDIA's results also highlight the dynamics within the memory sector. The trillion-dollar investment appetite for AI infrastructure is causing significant increases in memory prices. Manufacturers like SK Hynix and Samsung have increased their pricing power due to demand exceeding supply. Analysts suggest that the supply constraint in memory could continue until 2027, creating a favorable market environment for major manufacturers.
Asian Markets Rise and Restore Confidence
The rise in the KOSPI index reflects not only optimism towards the semiconductor sector but also the confidence generated by NVIDIA's results. Investors, previously concerned by the semiconductor sell-off in the US and NVIDIA's prolonged downtrend, have begun to take positions in light of the strong balance sheet and guidance.
The recovery in Korean semiconductor stocks, in particular, stands out as a result of NVIDIA's strong message regarding AI demand. Company-specific developments such as Samsung and SK Hynix's share buybacks also had a positive impact on the index.
#NVIDIAEarnings #GateStockInsightsChallenge
DYOR 🔎 NFA ✔️
repost-content-media
#GateStockInsightsChallenge $MRVL ‌Marvell (MRVL) Special Analysis: The Silent Winner of the AI War?
MRVL Announces Second Quarter FY2027 Earnings Today: Market Expectations $2.71 Billion in Revenue and $0.93 in Earnings Per Share
Marvell Technology is announcing its second-quarter results for fiscal year 2027 after market close on August 27. Wall Street expects the company to report approximately $2.71 billion in revenue (a 35% increase year-over-year) and adjusted earnings per share of $0.93 (a 39% increase year-over-year). The average 1-year price target among analysts is $269; the most o
User_any
#GateStockInsightsChallenge $MRVL ‌Marvell (MRVL) Special Analysis: The Silent Winner of the AI War?
MRVL Announces Second Quarter FY2027 Earnings Today: Market Expectations $2.71 Billion in Revenue and $0.93 in Earnings Per Share
Marvell Technology is announcing its second-quarter results for fiscal year 2027 after market close on August 27. Wall Street expects the company to report approximately $2.71 billion in revenue (a 35% increase year-over-year) and adjusted earnings per share of $0.93 (a 39% increase year-over-year). The average 1-year price target among analysts is $269; the most optimistic estimate is $400, and the most pessimistic is $195. The stock has risen 225% in the last year and reached a market capitalization of $218 billion.
1. The "Intel Legacy" Strategy: Why is Marvell Different?
Instead of being a "single giant" like NVIDIA and AMD, Marvell is spread across 5 distinct AI growth engines. This strategy positions the company at different levels of the AI ecosystem:
Scale-out Optics: As AI clusters expand, the need for optical connectivity increases exponentially. Marvell is a critical provider of these connections between data centers.
Scale-up Optics: Larger AI models require higher bandwidth for inter-chip communication. Marvell's solutions in this area play a significant role in overcoming performance bottlenecks.
Data Center Interconnect: Data center interconnection (DCI) solutions constitute a significant portion of Marvell's revenue.
Ethernet Switching: Ethernet switching solutions, which form the backbone of AI networks, are one of Marvell's traditionally strong areas.
Custom Silicon (ASIC): Design services for custom AI accelerators of hyperscalers are Marvell's fastest-growing segment.
CEO Matt Murphy stated, "Our custom AI design activity is at an all-time high. The Marvell team is currently working on more than 50 new opportunities with over 10 clients."
2. Celestial AI Acquisition: A Quiet Revolution
The acquisition of Celestial AI, announced in the third quarter of fiscal year 2026, is described as a turning point in Marvell's scale-up strategy.
Technical implications: As AI models grow, on-chip connectivity speed becomes the most critical bottleneck determining performance. Celestial AI's optical connectivity technology could give Marvell a technical advantage over Broadcom in this area.
Critical point: The company achieved record design gains in fiscal year 2026. This provides "visibility" that guarantees revenue for the next 2-3 years. CEO Murphy stated that they achieved $5 billion in new design gains in FY2026, which provides a solid foundation for future growth.
3. Marvell vs Broadcom: The Course of the ASIC War
MRVL's biggest competitor is Broadcom (AVGO). Both produce custom AI chips (ASICs) for hyperscalers. Let's examine the differences between Marvell and Broadcom in four key categories:
Criteria - Marvell (MRVL)
• Main Focus: Portfolio spread across 5 AI engines
• Strength: Optical + ASIC + Switching integration
• Growth Target: Data center +50% by FY2027
Criteria - Broadcom (AVGO)
• Main Focus: Custom silicon leader, 3.5D XDSiP packaging
• Strength: More mature ASIC ecosystem
• Growth Target: AI revenue of $40 billion by FY2026
Marvell's "5-engine" strategy provides risk diversification while offering the potential to gain market share in every area against Broadcom's more concentrated structure.
4. India Move: $250 Million Investment
On July 29, 2026, Marvell announced it would invest $250 million to expand its Bangalore facility in India.
Strategic significance:
• India as a hub for the global AI talent pool
• Creating an engineering base outside of TSMC
• Geographic diversification against trade restrictions in China
• Leveraging growth potential in the Indian market
5. Risks and Challenges
Key risks identified by analysts:
1. Premium Valuation: The stock is priced at almost three times (14.40x) the sector's P/S multiple (5.06x). These levels indicate that future growth expectations are already priced in.
2. Customer Concentration: A large portion of revenue is tied to a few hyperscalers. This could lead to significant revenue declines in the event of customer loss.
3. Competition: Broadcom, AMD, and Astera Labs challenge Marvell in every area. Broadcom's mature ecosystem is a significant advantage, especially in the ASIC market.
4. Margin Pressure: Custom silicon ramp-ups may temporarily put pressure on margins. Production costs for new products can reduce margins in the initial stages.
Marvell is uniquely positioned in the "connectivity" layer of AI infrastructure. While Nvidia aims to lead in "computing," Marvell aims to lead in "moving data."
Critical indicators to watch in the coming period:
• Impact of the custom chip deal with Google on the income statement
• Technical and commercial results of Celestial AI integration
• Market share change in competition with Broadcom
• Trend in gross profit margins
Monitor the market reaction after the earnings report, especially the revenue forecast and margin guidance.
All assessments and comments here are purely personal and are absolutely not investment advice.
repost-content-media
$MRVL #GateStockInsightsChallenge
Marvell's "Trillion-Dollar" Secret: The Giant Leap with NVIDIA's Approval
At COMPUTEX 2026, NVIDIA CEO Jensen Huang took the stage and, pointing to Marvell CEO Matt Murphy, said, "Ladies and gentlemen, here is the next trillion-dollar company."
At that moment, MRVL surged 30%. This wasn't a compliment; it was a check from NVIDIA to Marvell. Jensen Huang's words were the most concrete indication of the reshaping of power dynamics in the AI ecosystem.
1. The $12.2 Billion Google Deal
The bombshell on August 19th: Google could purchase up to $12.2 billion worth
User_any
$MRVL #GateStockInsightsChallenge
Marvell's "Trillion-Dollar" Secret: The Giant Leap with NVIDIA's Approval
At COMPUTEX 2026, NVIDIA CEO Jensen Huang took the stage and, pointing to Marvell CEO Matt Murphy, said, "Ladies and gentlemen, here is the next trillion-dollar company."
At that moment, MRVL surged 30%. This wasn't a compliment; it was a check from NVIDIA to Marvell. Jensen Huang's words were the most concrete indication of the reshaping of power dynamics in the AI ecosystem.
1. The $12.2 Billion Google Deal
The bombshell on August 19th: Google could purchase up to $12.2 billion worth of shares in Marvell. The deal covers custom chips (AI inference accelerators, storage, and network controllers) connected to Google's TPU ecosystem. MRVL surged 10% on this news, while its competitor Broadcom fell 5%.
Strategic Significance: Google has been working with Broadcom for a decade. Now it's shifting to Marvell. This is one of the most significant developments strengthening Marvell's position in the specialized chip (ASIC) market. The structure of the agreement is also noteworthy: Google has been given a guarantee (warrant) giving it the right to purchase 58.97 million shares of MRVL at $206.58 each. The majority of the shares are earned based on Google's spending on Marvell products. A tranche of shares is opened for every $500 million in qualified revenue, and this process continues until fiscal year 2033. This structure provides Marvell with long-term revenue visibility while ensuring Google's supply of specialized chips.
2. Marvell's Hidden Growth Engine: Memory Revolution
On August 4th, Marvell announced a new generation of products in AI memory infrastructure. These products aim to solve memory bottlenecks in data centers:
Bravera SC6 SSD Controller: Offers 2x the performance of its predecessor with PCIe 6.0. It reduces GPU lag by moving AI's KV cache needs to SSDs. This is critical, especially for improving inference performance with large language models.
Structera X CXL Memory Expansion: Enables hyperscalers to scale memory independently of computing. This provides data center operators with more flexible resource management.
Photonic Fabric Optical Shared Memory: Promises 2-3 times higher token throughput in existing data centers by sharing up to 32TB of hot KV cache over up to 50 meters. This technology is a product of the optical connectivity capabilities Marvell acquired through its Celestial AI acquisition.
CEO Will Chu: "AI infrastructure is now moving from isolated servers to systems where computing, memory, and connectivity work seamlessly." This vision shapes Marvell's entire product portfolio.
3. $250 Million Investment in India
On July 29th, Marvell announced a $250 million investment to expand its Bangalore facility. This move has three strategic goals:
• Geographic diversification against trade restrictions in China
• Access to the global AI talent pool
• Establishing an engineering base outside of TSMC
As India becomes one of the hubs of global semiconductor design talent, Marvell is strengthening its presence in the region with this investment.
4. Price Target: What Do Analysts Say?
Criteria Value
Current Price ~$243
Average Target $269
Optimistic $400
Pessimistic $195
Annual Return +226% (last 1 year)
75% of analysts recommend "BUY". Market capitalization is $218 billion. Susquehanna maintains its "buy" recommendation with a raised target price of $265, while Rosenblatt Securities is even more optimistic with a raised target price of $300.
5. Earnings Expectations and Risks
MRVL is releasing its Q2 FY2027 earnings today (August 27). Expectations:
• Revenue: $2.72 billion (+35% year-over-year)
• Earnings Per Share: $0.93
• Data Center Growth: Expected to reach 55%
Key Risks:
Premium Valuation: The stock is priced at almost three times the sector's P/S multiple (14.40x). These levels indicate that future growth expectations are already priced in.
Customer Concentration: A large portion of revenue is tied to several hyperscalers. Significant revenue declines could occur in the event of customer loss.
Competition: Broadcom, AMD, and Astera Labs are challenging Marvell in every area. Broadcom's mature ecosystem is a significant advantage, especially in the ASIC market.
Margin Pressure: Custom silicon ramp-ups may temporarily put pressure on margins.
MRVL will show today whether it can meet these high expectations with its earnings report. Data center growth is expected to reach 55%. If these figures are achieved, the premium pricing will be justified. If not, there is a risk of a sharp correction in the stock, which has a 54x EV/EBITDA multiple.
NVIDIA CEO's "trillion-dollar company" description shows confidence in Marvell's long-term potential. However, in the short term, how much of this potential is priced in and whether the company's operational performance meets expectations will be decisive.
All assessments and comments here are purely personal and are absolutely not investment advice.
repost-content-media
MRVL+4.09%
NVDA-0.09%
AVGO+0.31%
AMD+2.54%
ALAB+2.37%
$MRVL#GateStockInsightsChallenge Marvell (MRVL) Post-Earnings Report: Not Today's Numbers, but Google's 240-Piece Warrant
MRVL is releasing its Q2 FY2027 earnings at market close today: Wall Street expects $2.71 billion in revenue and $0.93 in earnings per share.
The company's own guidance is $2.70 billion and $0.93 – a difference of only 0.3%. For the past four quarters, MRVL has exceeded EPS expectations by an average of 0.1%. The possibility of a "surprise" this quarter is almost nonexistent. The real story isn't in today's numbers, but in the filing with the SEC on August 19th.
Google
User_any
$MRVL#GateStockInsightsChallenge Marvell (MRVL) Post-Earnings Report: Not Today's Numbers, but Google's 240-Piece Warrant
MRVL is releasing its Q2 FY2027 earnings at market close today: Wall Street expects $2.71 billion in revenue and $0.93 in earnings per share.
The company's own guidance is $2.70 billion and $0.93 – a difference of only 0.3%. For the past four quarters, MRVL has exceeded EPS expectations by an average of 0.1%. The possibility of a "surprise" this quarter is almost nonexistent. The real story isn't in today's numbers, but in the filing with the SEC on August 19th.
Google Agreement: 240-Piece Warrant
Google acquired a warrant for 58,970,907 shares in MRVL. The exercise price is $206.58. The stock closed at $245.12 yesterday – meaning Google is up 19% even before a single tranche is vested.
The crucial part is the vesting terms:
• Almost all of the stock tranches (57.6 million units) will be vested in 240 installments.
• Each installment opens with Google purchasing $500 million worth of private chips from MRVL.
• 240 × $500 million = $120 billion
This is less of a customer contract and more of a "purchase route" that Google is writing to MRVL. And the first lights of this route will start flashing with the Q3 guidance to be given tonight. Because the purchase-based tranches are going into effect in the third quarter of FY2027.
Stock: Recovery from the Fall
MRVL had fallen as low as $163.39 on July 29th – the day the Google deal was signed. It recovered following the news of the deal and closed at $245.12 yesterday.
• Year-to-date return: 179%
• Sector average: 27.5%
• Forward P/S multiple: 14.40x – sector average 5.06x
• 75% of analysts recommend BUY
• Average target price: $269
• Most optimistic: $400
My 3 Scenarios
📈 Bullish Scenario:
Revenue $2.77 billion or more, Q3 guidance above $3.2 billion. The Google deal is clearly within the guidance and the first tranches are being activated. 77x trailing P/E is the only result justifying the stock's current position.
➡️ Base Scenario:
Revenue between $2.70-2.75 billion, Q3 guidance between $3.0-3.1 billion. Maintaining guidance for the fifth consecutive quarter. Nothing has been confirmed or refuted; the argument is being carried over to Investor Day on October 6th.
📉 Downward Scenario:
Revenue is at the lower end of the guidance range, Q3 guidance is below the $3.04 billion consensus. The Warrant is becoming a "story" rather than a "calendar" – and the 77x P/E ratio has very little ground to stand on.
3 Realities Behind the Numbers
1. Dependence on China
44% of last quarter's revenue came from China; it was 37% a year ago. The US share fell from 16% to 7%. A huge geographic shift in 12 months.
2. GAAP vs. Non-GAAP Gap
Last quarter's GAAP net income was $34.5 million, while Non-GAAP was $718 million – a 20x difference. The majority of this difference stems from $193 million in equity-based compensation and purchase amortization. The Google warrant will add a new item to this picture.
3. New CFO
Dan Durn was appointed CFO in June; today's guidance quarter is his first full term. Former CFO Willem Meintjes left after 10 years to spend time with his family.
The custom chip business is no longer a "design winning" game, but a "funding" game. NVIDIA mobilized $500 billion in third-party capital overnight. MRVL, meanwhile, traded 7% of its shares in exchange for a client's purchase schedule. Same move, different instrument.
The only indicator that would mislead me: Q3 guidance falling below $3.04 billion. The warrant only makes sense when the revenue behind it arrives. $3.04 billion is the threshold that tells Google's acquisitions have begun. Below that, those 240 squares are just a story, not a schedule.
All assessments and comments here are purely my personal opinions. DYOR 🔎 NFA ✔️
repost-content-media
MRVL+4.09%
NVDA-0.09%
Marvell's Share of the AI Storm: Behind the Scenes of the Growth Story $MRVL
Analysts expect 35% revenue growth in the second quarter; strong demand for custom chips and interconnection solutions is making Marvell a key player in the AI infrastructure game.
Marvell Technology continues to be one of the biggest winners of the AI data center boom. The company's second-quarter revenue is expected to reach $2.7 billion, up approximately 35% year-over-year. The main driver of this growth is the exceptional performance in the data center segment. In the first quarter, data center revenue reached
User_any
Marvell's Share of the AI Storm: Behind the Scenes of the Growth Story $MRVL
Analysts expect 35% revenue growth in the second quarter; strong demand for custom chips and interconnection solutions is making Marvell a key player in the AI infrastructure game.
Marvell Technology continues to be one of the biggest winners of the AI data center boom. The company's second-quarter revenue is expected to reach $2.7 billion, up approximately 35% year-over-year. The main driver of this growth is the exceptional performance in the data center segment. In the first quarter, data center revenue reached $1.83 billion, accounting for 76% of total revenue.
Growth Engines: XPU and Optical Interconnect
Marvell's growth strategy rests on two main pillars:
1. Custom AI Chips (XPU): CEO Matt Murphy notes that the company is experiencing an all-time high level of activity in custom AI chip designs. Marvell plays a critical role in the design of chips that hyperscalers develop specifically for their needs. Murphy predicts that growth in this area will exceed 20% in fiscal year 2027 and double in 2028. The company's target for private chip revenue in fiscal year 2029 is $100 billion.
2. Optical Interconnect Solutions: As AI clusters grow, data flow between chips and servers is becoming a critical bottleneck. Marvell's 800G and 1.6T optical interconnect solutions are designed to address this issue. Murphy notes that this business line is growing at an annual rate of over 70% and still has upside potential.
The Wind from NVIDIA
At COMPUTEX 2026, NVIDIA CEO Jensen Huang's statement, referring to Marvell CEO Matt Murphy, "Here's the next trillion-dollar company," fundamentally changed the market's perception of Marvell. This approval created an "NVIDIA effect," confirming Marvell's importance in the AI ecosystem.
Future Outlook
Marvell raised its revenue target to $115 billion for fiscal year 2027 and set a target of $165 billion for 2028. Murphy emphasized that the company's growth story is still in its early stages, stating, "AI-related orders are extraordinarily strong."
The critical question for investors is: How much of this growth is priced in? Marvell is trading at a valuation well above the industry average. The main focus in the coming period will be whether the company can meet these high expectations.
#GateStockInsightsChallenge #NVIDIAEarnings
DYOR 🔎 NFA ✔️
repost-content-media
MRVL+4.09%
NVDA-0.09%
#GateStockInsightsChallenge $MRVL ‌Two Faces of the Market: The Only Sector Carrying the S&P 500 Today
While the weighted index is rising, the equally weighted index is falling. The difference shows the burden carried solely by the technology sector and the real issue of today.
Today's Story Fits in One Box
The S&P 500 is up 0.83% at 7,739 points. But the Invesco S&P 500 Equal Weight ETF (RSP), which counts the same 500 companies with equal weighting, is down 0.04%. This means that the average S&P 500 company is worth less today; the index's gains are coming entirely from a handful of large t
User_any
#GateStockInsightsChallenge $MRVL ‌Two Faces of the Market: The Only Sector Carrying the S&P 500 Today
While the weighted index is rising, the equally weighted index is falling. The difference shows the burden carried solely by the technology sector and the real issue of today.
Today's Story Fits in One Box
The S&P 500 is up 0.83% at 7,739 points. But the Invesco S&P 500 Equal Weight ETF (RSP), which counts the same 500 companies with equal weighting, is down 0.04%. This means that the average S&P 500 company is worth less today; the index's gains are coming entirely from a handful of large technology stocks.
Ten out of eleven sector funds are in the red. The only green box: Technology (XLK), up 2.93%. Finance, energy, healthcare, retail... all are falling. And this picture hasn't changed since 9:30 AM.
Software Faster Than Chips
Within technology, leadership isn't in chips, but in software. Software development fund (IGV) rose 7%, while semiconductor development fund (SMH) remained at 2.9%. The volume difference is even more striking: IGV reached 138% of its normal daily trading volume; SMH at 38%.
The source of this movement is Salesforce's earnings report released last night: Revenue was $11.35 billion, EPS $5.90 (expected $3.27), and Agentforce annual recurring revenue (ARR) rose to $1.5 billion (+240% year-over-year). The real message, however, was in the order book: cRPO (signed but unbilled work) grew 14% to $33.5 billion, adjusted for currency effects. The thesis that vendor-led software will die in the age of AI has passed its purest test.
Marvell's Test: Not Today's Numbers, but Google's 240 Slices
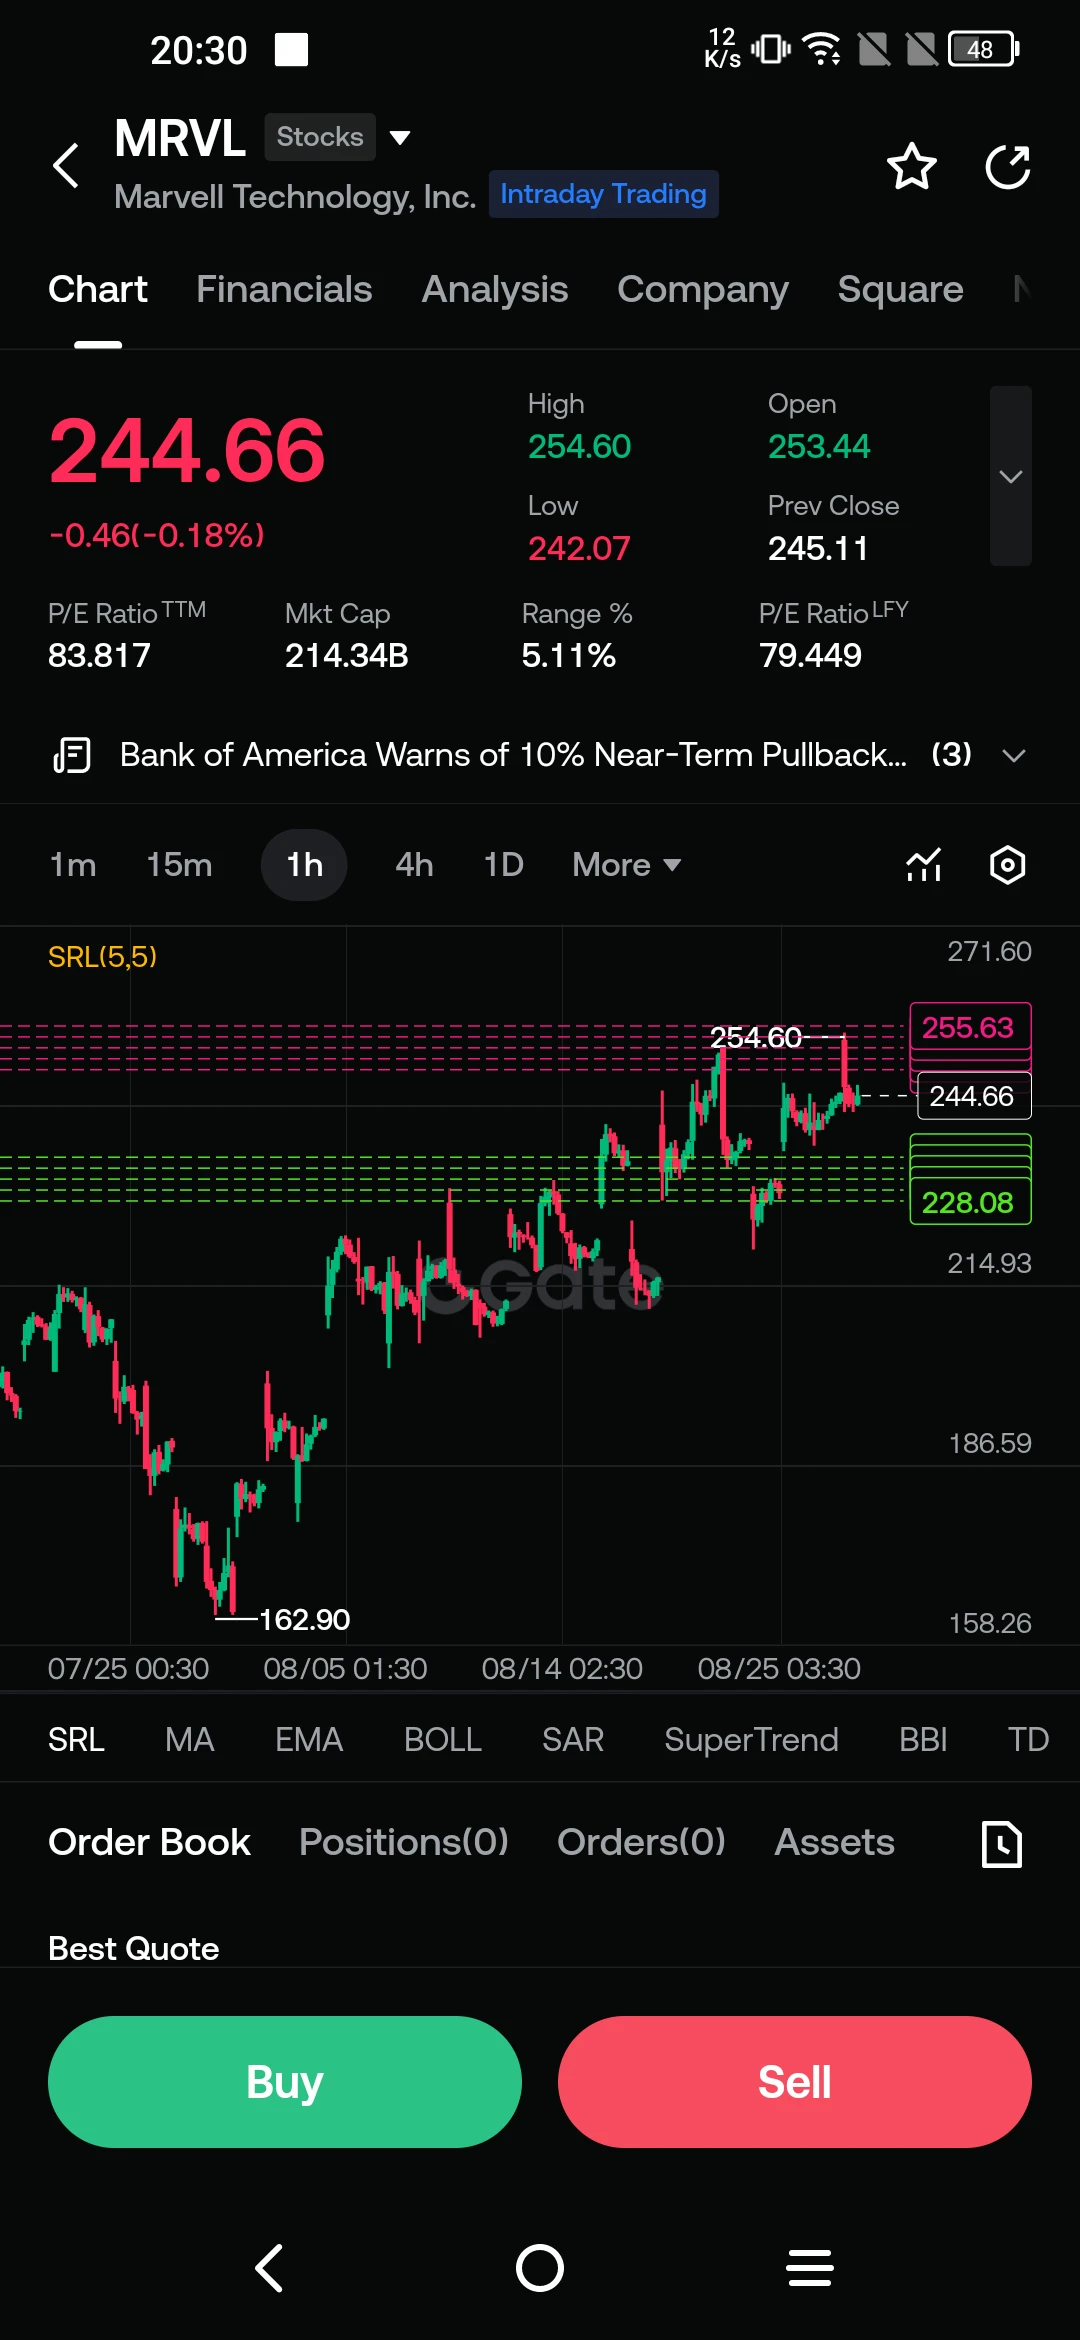
MRVL opened at $253 and fell to $242 before stabilizing at $245. Today's Q2 earnings report is expected to show $2.71 billion in revenue and $0.93 EPS. These figures, almost perfectly aligned with the company's own guidance, aren't the main point of interest.
The real story lies in the filing with the SEC on August 19th:
• Google acquired a warrant for 58.97 million shares of MRVL. The exercise price is $206.58. Each of the 240 shares, vested in Google, is backed by a $500 million private chip purchase from Marvell. 240 × 500 million = $120 billion.
This is an acquisition route. And the first glimpses of this path will be seen in today's Q3 guidance. Analysts are watching the $3.04 billion Q3 guidance as the threshold indicating the start of Google acquisitions.
The Only Indicator to Watch
MRVL is trading at a forward P/S multiple almost three times the industry average (5.06x) (14.40x). A drop below the $3.04 billion Q3 guidance would turn the warrant into a "story." A drop above it would trigger the 240-slice circuit.
All assessments and comments here are purely my personal opinions. This is not investment advice.
repost-content-media
MRVL+4.09%
US500-0.49%
XLK+1.35%
SMH+1.42%
CRM+1.87%
The Latest Outlook on AI and Semiconductors: The Production, Demand, and Price Triangle
The AI and semiconductor ecosystem continues to dominate the news agenda, with a flurry of activity from both the giant companies listed on the US stock exchange and the global supply chain. In this new era, shaped by production capacities, a surge in demand, and price pressures, it's possible to summarize the sector's pulse under three main headings:
1. Production and Roadmap: Capacity is Increasing, Costs are Being Questioned
NVIDIA announced its next-generation Rubin platform with a 2026 release date. Th
User_any
The Latest Outlook on AI and Semiconductors: The Production, Demand, and Price Triangle
The AI and semiconductor ecosystem continues to dominate the news agenda, with a flurry of activity from both the giant companies listed on the US stock exchange and the global supply chain. In this new era, shaped by production capacities, a surge in demand, and price pressures, it's possible to summarize the sector's pulse under three main headings:
1. Production and Roadmap: Capacity is Increasing, Costs are Being Questioned
NVIDIA announced its next-generation Rubin platform with a 2026 release date. This architecture, which combines GPUs, CPUs, and network chips in a single package, seems set to intensify competition, particularly in the inference field. NVIDIA also plans to ship a small volume of a dedicated chip to the Chinese market by the end of the year.
On the TSMC front, there are two significant developments. The company has decided not to transition to a high-performance NA EUV machine before 2029. Despite this, it revised its 2026 revenue growth forecast to over 30%. For 2027, an investment budget of between $80-85 billion is being discussed.
ASML also revised its annual forecast upwards, becoming another critical supplier confirming that AI spending remains strong.
2. Demand and Agreements: Growth Spreading Across All Areas
AMD exceeded expectations in the second quarter, reporting $11.54 billion in revenue with 50% growth. The company signed new agreements with Anthropic and Core Scientific. However, what is particularly noteworthy is that the increase in demand is not limited to accelerator chips. Intel and AMD are pursuing long-term CPU agreements with Chinese server customers. This shows that demand is also spreading to memory, networking, and server processors.
Broadcom increased its AI semiconductor revenue to $10.8 billion, registering 143% year-on-year growth. It has a plan to deliver 10 gigawatts of capacity next year, and a debt package of over $60 billion is on the agenda for customers like Anthropic.
3. Price and Market Reaction: Expectations Rise
While demand remains strong, market expectations are even higher. AMD saw its value drop by 6.6% in a single day, losing $59 billion, after its AI spending growth failed to meet expectations following record revenue. Broadcom experienced a decline in gross margins, while TSMC's rising costs are reportedly tightening margins on custom AI processors.
NVIDIA announced server price increases of over 15% due to rising memory costs. However, there is a strong indication that demand will continue: Alphabet, Microsoft, Amazon, and Meta are planning a total of $630 billion in AI infrastructure spending this year.
Current State of the Industry
In summary, production capacity and roadmap remain solid. Demand-side agreements are expanding, but pricing and margin pressure is increasing. The market is now questioning not only growth but also profitability. The most critical question for the coming period is whether the manufacturing side (TSMC, ASML) or the design side that best monetizes demand (NVIDIA, AMD, Broadcom) will win in this cycle.
This post is not investment advice; it is for informational purposes only. 👉 DYOR 🔎
#AI #Semiconductors #NVIDIA #TSMC #GateStockInsightsChallenge
$NVDA$MU$MRVL
NVDA-0.09%
TSM+1.13%
ASML+0.68%
AMD+2.54%
AVGO+0.31%
#GateStockInsightsChallenge $MSTR ‌MicroStrategy (MSTR) Transformation: From Bitcoin Treasury to Digital Credit Capitalism
MSTR reported a $8.2 billion GAAP loss in Q2 2026 and shifted towards a "Digital Credit Capitalism" strategy by halting Bitcoin purchases. The stock recently rose 37% to $137 but is down 60% year-to-date.
Balance Sheet and Strategic Transformation
Striking Loss: MSTR reported a $8.2 billion GAAP net loss in Q2 2026. Nearly all of the loss stemmed from an unrealized $8.32 billion impairment loss due to the decline in Bitcoin price. Revenue rose to $122.4 million, resultin
User_any
#GateStockInsightsChallenge $MSTR ‌MicroStrategy (MSTR) Transformation: From Bitcoin Treasury to Digital Credit Capitalism
MSTR reported a $8.2 billion GAAP loss in Q2 2026 and shifted towards a "Digital Credit Capitalism" strategy by halting Bitcoin purchases. The stock recently rose 37% to $137 but is down 60% year-to-date.
Balance Sheet and Strategic Transformation
Striking Loss: MSTR reported a $8.2 billion GAAP net loss in Q2 2026. Nearly all of the loss stemmed from an unrealized $8.32 billion impairment loss due to the decline in Bitcoin price. Revenue rose to $122.4 million, resulting in a loss per share of -$24.45.
Bitcoin Portfolio: The company holds approximately 4% of the entire Bitcoin supply with 840,447 BTC. The average cost is $75,385, resulting in approximately $2.84 billion in unrealized profit at current prices. When Bitcoin fell to $58,300 in June, the paper loss reached approximately $13 billion.
"Digital Credit Capitalism" Strategy
Saylor's New Direction: Michael Saylor has radically changed the company's strategy. The goal is no longer simply to accumulate Bitcoin, but to create a Bitcoin bank within the framework of "Digital Credit Capitalism." Preferred shares with 8-12% dividends, such as STRC, STRK, STRF, STRD, and STRE, are the cornerstone of this model.
First Bitcoin Sale: In May 2026, the company sold Bitcoin for the first time in its history: 32 BTC. Subsequently, a total of 6,916 BTC were sold; sales averaged between $60,000 and $64,000, well below the average cost of $75,385. Sales generated $432 million in revenue, while incurring a realized loss of $102 million.
Why Sell? The company faces approximately $1.76 billion in annual fixed liabilities (preferred share dividends and bond interest). In May, it spent $1.38 billion to early redeem its 2029 bonds, depleting its cash reserves. Therefore, a shift to a "cash flow" focused management approach was implemented starting in June.
New Financial Structure: Cash Warfare Fund
A $2.01 billion capital increase was conducted in August, but not a single Bitcoin was purchased. Use of these funds:
• $1.59 billion: Added to the new "USD Cash" liquidity pool.
• $300 million: Added to the USD Reserve.
• $136.4 million: Used to repurchase STRC preferred shares.
Strategic Significance: The company can now manage dividend payments, debts, and share buybacks with its cash reserves without being dependent on the Bitcoin price. A cash reserve of $6.69 billion provides approximately 3.9 years of buffer for its annual liabilities. CEO Michael Saylor no longer expects the stock to react to every move in the Bitcoin price.
Market Reaction and Valuation
Recent Rise: The stock has risen 37% in the last week, reaching $137. Canaccord analyst Joe Vafi raised his target price to $175. This optimism is attributed to the new cash strategy strengthening the balance sheet.
Risks and Critics: Peter Schiff recommends investors buy Bitcoin directly instead of MSTR. The decline in Bitcoin's return from 13.3% in May to 4.5% in July is the focus of criticism. The stock is still down 60% and 80% below its 2024 peak. The cash increase reduces the amount of Bitcoin per share.
Strategy (MicroStrategy) is radically changing its Bitcoin strategy. It's shifting from a "accumulate Bitcoin and hold" model to a "Digital Credit Capitalism" model backed by cash reserves and based on preferred shares. This shift provides the company with financial flexibility while raising new questions for investors. MSTR is no longer just a tool tied to the Bitcoin price, but a complex capital structure management game.
These assessments and comments are my personal opinions. They do not constitute investment advice.
MSTR+1.82%
BTC+0.51%
STRC+0.64%
👉👉👉 $NVDA ‌Nvidia's unique fiscal year calendar is creating this confusion.
Nvidia's fiscal year doesn't coincide with the calendar year; the company's fiscal year typically ends around January/February. So, right now, in August 2026, the company is releasing results for what it calls the "second quarter of fiscal year 2027," but which actually ends in July 2026. This is a standard naming convention Nvidia has used for years, referring to a quarter of the current calendar year while bearing the name of the following year.
Therefore, the phrase "fiscal year 2027" doesn't refer to a balance
Yuewen
👉👉👉 $NVDA ‌Nvidia's unique fiscal year calendar is creating this confusion.
Nvidia's fiscal year doesn't coincide with the calendar year; the company's fiscal year typically ends around January/February. So, right now, in August 2026, the company is releasing results for what it calls the "second quarter of fiscal year 2027," but which actually ends in July 2026. This is a standard naming convention Nvidia has used for years, referring to a quarter of the current calendar year while bearing the name of the following year.
Therefore, the phrase "fiscal year 2027" doesn't refer to a balance sheet for the yet-to-be-realized 2027 calendar year; it simply reflects the naming convention in Nvidia's internal accounting calendar. The figures released today cover a three-month period that has already occurred and been completed, ending in July 2026. This type of "shifted" fiscal year naming convention isn't unique to Nvidia; many technology and semiconductor companies use a similar approach, so it's important to remember that when you see phrases like "FY27 Q2" in the news, it doesn't exactly correspond to the calendar year.
DYOR 🔎
NVDA-0.09%
  • 1