
#SK海力士Q3营收创历史新高 SK Hynix surges nearly 11% in a single day: How long can the AI memory chip frenzy last?
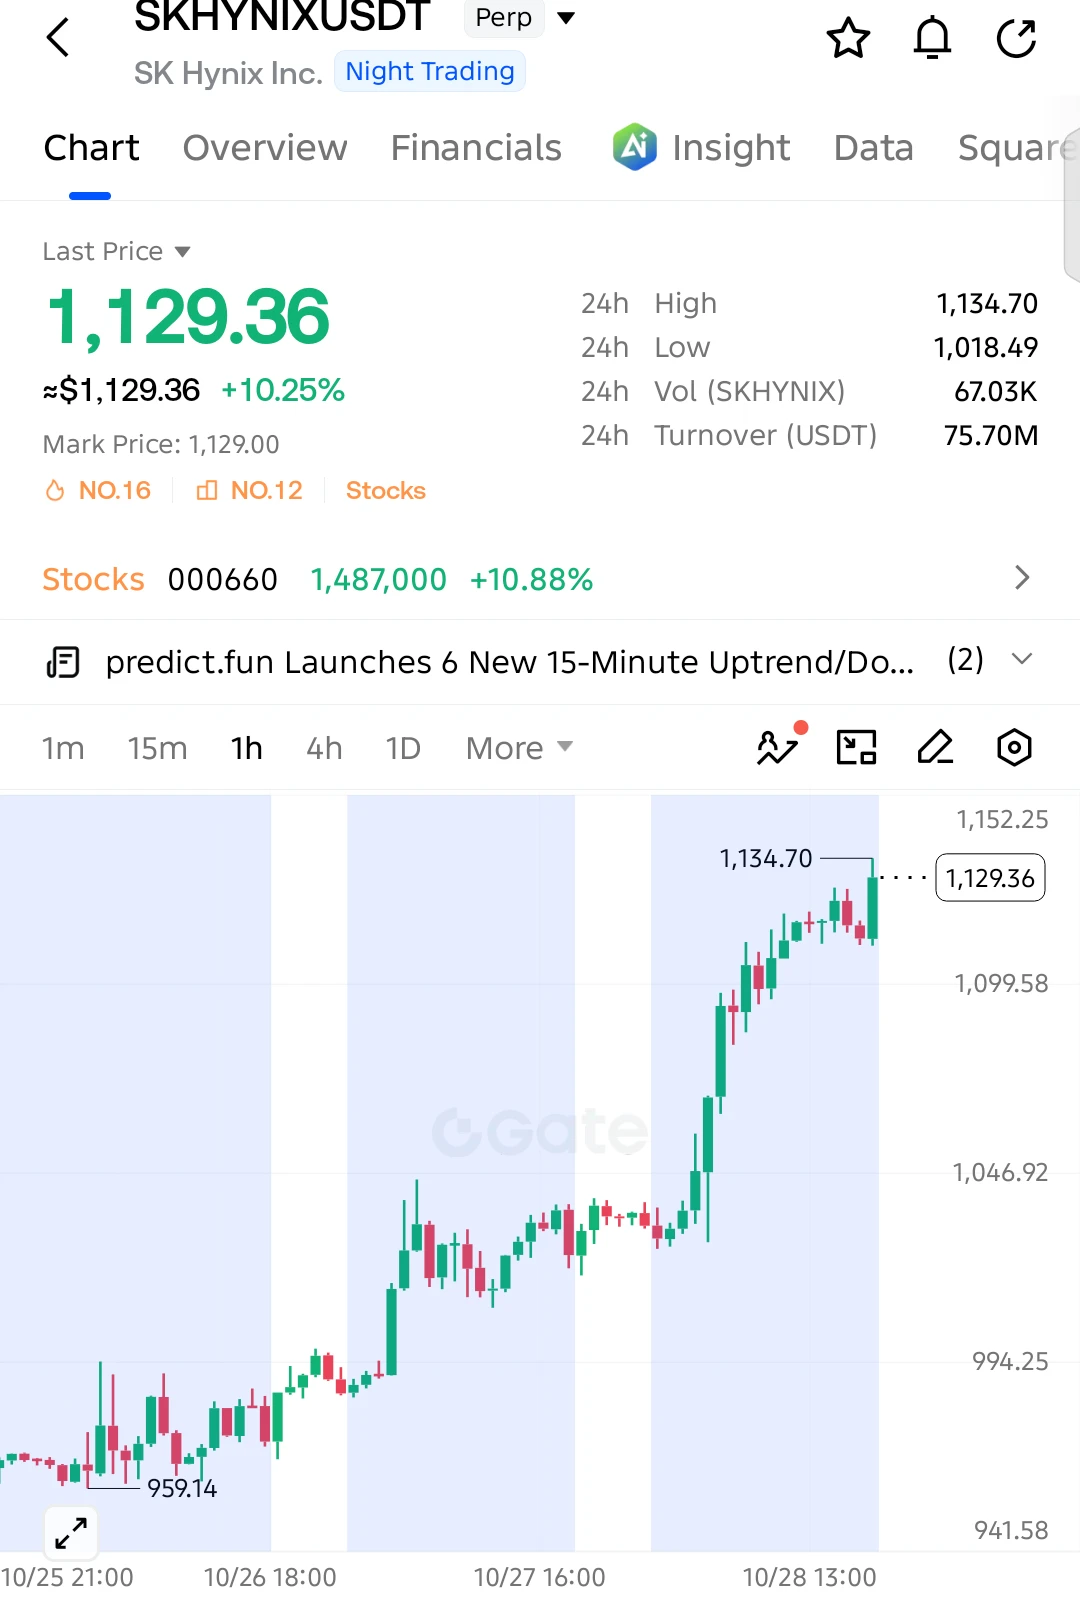
October 28, 2026 October 28, South Korea's semiconductor market saw a strong rally. SK Hynix closed up 10.89%, at 1.49 million won per share; Samsung Electronics rose 9.01%, and the Korea Composite Stock Price Index (KOSPI) gained 6.63%.
Behind the rally were better-than-expected earnings and a remarkably large shareholder return plan.
More importantly, demand for AI memory chips is still growing, and next-generation HBM4 is entering a critical phase. But does a nearly 11% gain in one day mean the memory chip rally will continue? Let's look at it from three angles.
I. Just how strong were these earnings?
SK Hynix has just announced its latest third-quarter results. The most astonishing figure was an operating margin of about 80%. This means that for every 100 won in revenue, about 80 won converts into operating profit. For a semiconductor manufacturer that needs to keep investing huge sums in factory construction and equipment, this represents extremely strong profitability.
The growth in results was mainly driven by demand for AI memory. As data centers expand, products such as HBM, high-end server DRAM, and enterprise SSDs are becoming increasingly important. SK Hynix has further boosted revenue and profit by focusing on high-value-added products. Reuters reported that the company's third-quarter operating profit exceeded market expectations. What the market sees is not just earnings growth, but AI demand translating into real profits.
II. HBM4 could determine the next phase of growth!
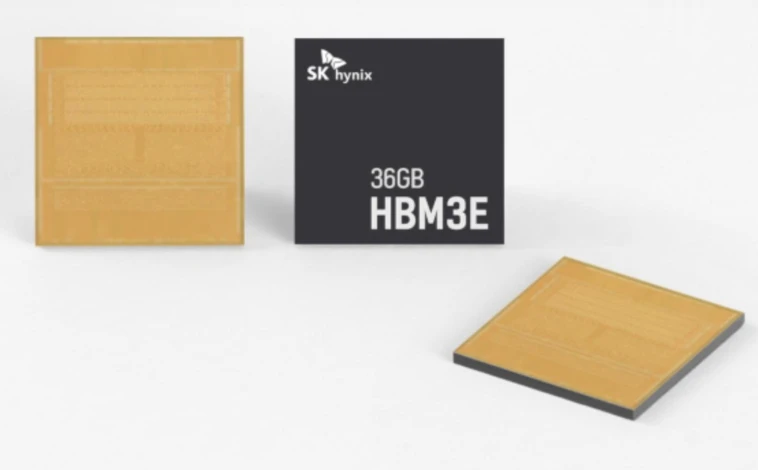
If HBM has been a hot keyword in the AI chip supply chain over the past few years, then HBM4 will gradually become the market's focus going forward.
Why is it so important? AI accelerators need to constantly read large volumes of model parameters and intermediate data. Ordinary memory struggles to meet bandwidth demands for high-performance computing in every scenario. By stacking multiple layers of DRAM and using a wide interface, HBM helps accelerators access data more efficiently. As models grow larger, AI systems' requirements for memory bandwidth, capacity, and power efficiency continue to rise. In its latest earnings report, SK Hynix said HBM4 will become a core product in the fourth quarter, with shipments and revenue expected to exceed those of HBM3E.
This means the next stage of competition will not be just about who can produce more memory chips, but also about who can complete next-generation product validation faster, achieve stable mass production, and meet customers' performance and reliability requirements.
Of course, ramping up HBM4 does not guarantee that profits will continue to rise. Manufacturing costs, yields, customer demand, and competitors' progress will all affect ultimate profitability.
III. Why is the company also making such large shareholder returns?
Another catalyst for the rally was SK Hynix's announcement that it would expand shareholder returns. The company said it plans to provide shareholder returns totaling about 100 trillion won in fiscal 2026, including cash dividends and share buybacks. In a board resolution on October 28, the company set the total third-quarter cash dividend at 14 trillion won, or 20,000 won per share; it also decided to buy back 20 trillion won worth of shares, with the portion intended for shareholder returns to be canceled and the rest used for employee performance awards. This sends two signals. First, the company's current cash-generating ability is strong. High profits can support R&D and capacity expansion while also enabling the company to return cash to shareholders. Second, the company wants to boost shareholders' confidence in future cash flows. For a semiconductor company that has already accumulated substantial profits, how to allocate funds among capacity expansion, R&D, and shareholder returns is itself an important decision. However, shareholder returns do not mean that the share price is certain to rise. Investors also need to watch the actual execution of buybacks, future capital expenditure, and whether the company can maintain the same level of profitability if the memory industry enters a downturn. IV. What risks remain after a nearly 11% rally? It's worth noting that SK Hynix was not the only stock to rise on October 28. Samsung Electronics also gained 9.01%, while the KOSPI rose 6.63% overall. This shows that the day's rally was driven both by company-specific catalysts—earnings and shareholder returns—and by improving market sentiment more broadly. The entire gain cannot be attributed to HBM demand. There are three main risks ahead.
First, market expectations may already be high. The share price reflects the market's view of the future. If results continue to grow but fail to meet even higher expectations, the share price could still pull back.
Second, the memory industry is cyclical. High profits may spur capacity expansion. If new capacity gradually comes online while investment in AI infrastructure slows, memory product prices and margins could come under pressure.
Third, competitors are also catching up. Manufacturers such as Samsung and Micron are advancing their high-bandwidth memory products. Whether SK Hynix can maintain its lead will depend on technology development, mass production capabilities, customer validation, and actual market share. So, to judge whether this rally is sustainable, don't just look at how much the stock rose today; pay closer attention to shipments, prices, and earnings over the next few quarters.
In short, SK Hynix's nearly 11% single-day gain resulted from the combined impact of strong conditions in the AI memory industry, better-than-expected earnings, and shareholder returns. The results also once again show that value in the AI supply chain is not concentrated in GPUs alone. As computing clusters expand, HBM, high-end DRAM, enterprise SSDs, and advanced packaging are all becoming more important. But remember: a good company is not necessarily worth buying at any price#Gate广场万圣节 $SPCX