
#BOJHikesTo1.25%31YearHigh
My analysis of the Bank of Japan's (BOJ) recent interest rate hike suggests we are witnessing a fundamental shift in market dynamics. The BOJ's move to raise interest rates to 0.25%—a level not seen in 15 years—has significant implications across various asset classes. Let us delve deeper into the interaction between the USD/JPY pair and Japanese equities in this new environment.
Feedback Loop: USD/JPY and Japanese Equities
Your observation regarding the tightly coupled feedback loop between the USD/JPY pair and Japanese equities (Nikkei 225 / TOPIX) is crucial. While an interest rate hike typically signals currency appreciation, the market's immediate reaction is often shaped by the distinction between the rate move itself and the central bank's forward guidance.
* USD/JPY as a Leading Indicator: Following a rate hike that has already been priced in, sudden volatility often manifests in the forex market. The key determinants here are the tone of the press conference and the resulting shifts in interest rate differentials.
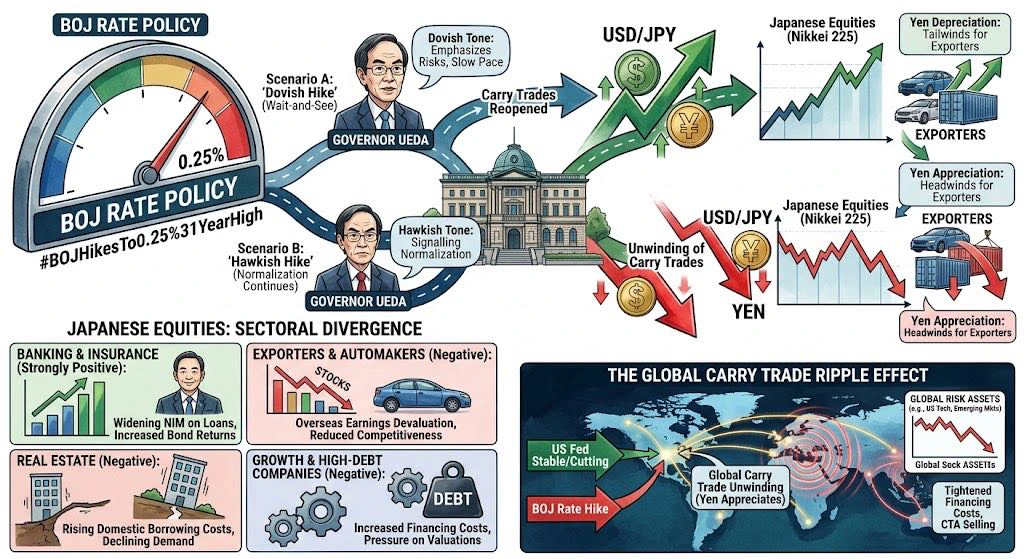
* Dovish" Stance ("Sell the Fact"): If Governor Ueda adopts a "dovish" tone—emphasizing risks and signaling a slow pace for future hikes—the market interprets this as a "sell the fact" event. "Carry trade" positions involving short Yen bets, which might have been closed in anticipation of a more "hawkish" (tightening) stance, could be rapidly reopened. This drives the USD/JPY pair higher.
* Hawkish" Stance: Conversely, a "hawkish" stance—signaling that the normalization process will continue—could cause a downward break in the USD/JPY pair. This scenario triggers a rapid unwinding of "carry trade" positions, exerting downward pressure on the currency pair.
In a "dovish" scenario, the depreciation of the Yen acts as an immediate tailwind for major Japanese exporters, supporting their stock prices. In a "hawkish" scenario, however, a rapid appreciation of the Yen can hurt the shares of exporting companies.
Japanese Equities: Sectoral Divergence
The impact of the BOJ's moves is not uniform across all sectors of the Japanese stock market. One key factor we observe is sectoral divergence.
Banking and Insurance. Strongly Positive Widening net interest margins (NIM) on loans and increased returns from bond portfolios directly support long-term profitability. This sector benefits from a high-interest-rate environment.
Exporters and Automakers Negative Yen appreciation (a decline in the USD/JPY pair) causes overseas earnings to lose value when converted into Yen. This reduces global price competitiveness and can squeeze profit margins.
Real Estate and Growth-Oriented Companies Negative Rising domestic borrowing costs exert pressure on these sectors. While real estate companies may face declining demand and valuation adjustments, growth-oriented companies with high debt levels confront rising financing costs that could negatively impact their valuations.
Consequently, the relationship between the Yen and Japanese equities is complex and depends largely on the specific sector involved.
The Global Carry Trade Ripple Effect
The impact of the Bank of Japan's (BOJ) policy shift extends far beyond Japan's borders, affecting global markets through the unwinding of "Yen carry trade" positions.
When the BOJ raises interest rates, the cost of borrowing in Yen increases. If this coincides with a period where the US Federal Reserve (Fed) is cutting or holding rates steady, the yield spread between US and Japanese short-term debt instruments narrows.
This tightening of financing costs compels macro funds and systematic CTA algorithms to close out their "carry trade" positions.
These positions involve borrowing Yen at low interest rates to invest in assets such as US technology stocks, emerging market bonds, and other high-yielding currencies.
A sudden appreciation of the Yen triggers a global sell-off of these risky assets, creating a ripple effect across financial markets.
In summary, the BOJ's move toward policy normalization—while a domestic decision—demonstrates the interconnectedness of modern markets and has profound implications for global financial stability. As the BOJ continues on its path of policy normalization... The interplay between the yen, Japanese equities, and global asset allocation will continue to be a key focus for investors.
My analysis of the Bank of Japan's (BOJ) recent interest rate hike suggests we are witnessing a fundamental shift in market dynamics. The BOJ's move to raise interest rates to 0.25%—a level not seen in 15 years—has significant implications across various asset classes. Let us delve deeper into the interaction between the USD/JPY pair and Japanese equities in this new environment.
Feedback Loop: USD/JPY and Japanese Equities
Your observation regarding the tightly coupled feedback loop between the USD/JPY pair and Japanese equities (Nikkei 225 / TOPIX) is crucial. While an interest rate hike typically signals currency appreciation, the market's immediate reaction is often shaped by the distinction between the rate move itself and the central bank's forward guidance.
* USD/JPY as a Leading Indicator: Following a rate hike that has already been priced in, sudden volatility often manifests in the forex market. The key determinants here are the tone of the press conference and the resulting shifts in interest rate differentials.
* Dovish" Stance ("Sell the Fact"): If Governor Ueda adopts a "dovish" tone—emphasizing risks and signaling a slow pace for future hikes—the market interprets this as a "sell the fact" event. "Carry trade" positions involving short Yen bets, which might have been closed in anticipation of a more "hawkish" (tightening) stance, could be rapidly reopened. This drives the USD/JPY pair higher.
* Hawkish" Stance: Conversely, a "hawkish" stance—signaling that the normalization process will continue—could cause a downward break in the USD/JPY pair. This scenario triggers a rapid unwinding of "carry trade" positions, exerting downward pressure on the currency pair.
In a "dovish" scenario, the depreciation of the Yen acts as an immediate tailwind for major Japanese exporters, supporting their stock prices. In a "hawkish" scenario, however, a rapid appreciation of the Yen can hurt the shares of exporting companies.
Japanese Equities: Sectoral Divergence
The impact of the BOJ's moves is not uniform across all sectors of the Japanese stock market. One key factor we observe is sectoral divergence.
Banking and Insurance. Strongly Positive Widening net interest margins (NIM) on loans and increased returns from bond portfolios directly support long-term profitability. This sector benefits from a high-interest-rate environment.
Exporters and Automakers Negative Yen appreciation (a decline in the USD/JPY pair) causes overseas earnings to lose value when converted into Yen. This reduces global price competitiveness and can squeeze profit margins.
Real Estate and Growth-Oriented Companies Negative Rising domestic borrowing costs exert pressure on these sectors. While real estate companies may face declining demand and valuation adjustments, growth-oriented companies with high debt levels confront rising financing costs that could negatively impact their valuations.
Consequently, the relationship between the Yen and Japanese equities is complex and depends largely on the specific sector involved.
The Global Carry Trade Ripple Effect
The impact of the Bank of Japan's (BOJ) policy shift extends far beyond Japan's borders, affecting global markets through the unwinding of "Yen carry trade" positions.
When the BOJ raises interest rates, the cost of borrowing in Yen increases. If this coincides with a period where the US Federal Reserve (Fed) is cutting or holding rates steady, the yield spread between US and Japanese short-term debt instruments narrows.
This tightening of financing costs compels macro funds and systematic CTA algorithms to close out their "carry trade" positions.
These positions involve borrowing Yen at low interest rates to invest in assets such as US technology stocks, emerging market bonds, and other high-yielding currencies.
A sudden appreciation of the Yen triggers a global sell-off of these risky assets, creating a ripple effect across financial markets.
In summary, the BOJ's move toward policy normalization—while a domestic decision—demonstrates the interconnectedness of modern markets and has profound implications for global financial stability. As the BOJ continues on its path of policy normalization... The interplay between the yen, Japanese equities, and global asset allocation will continue to be a key focus for investors.