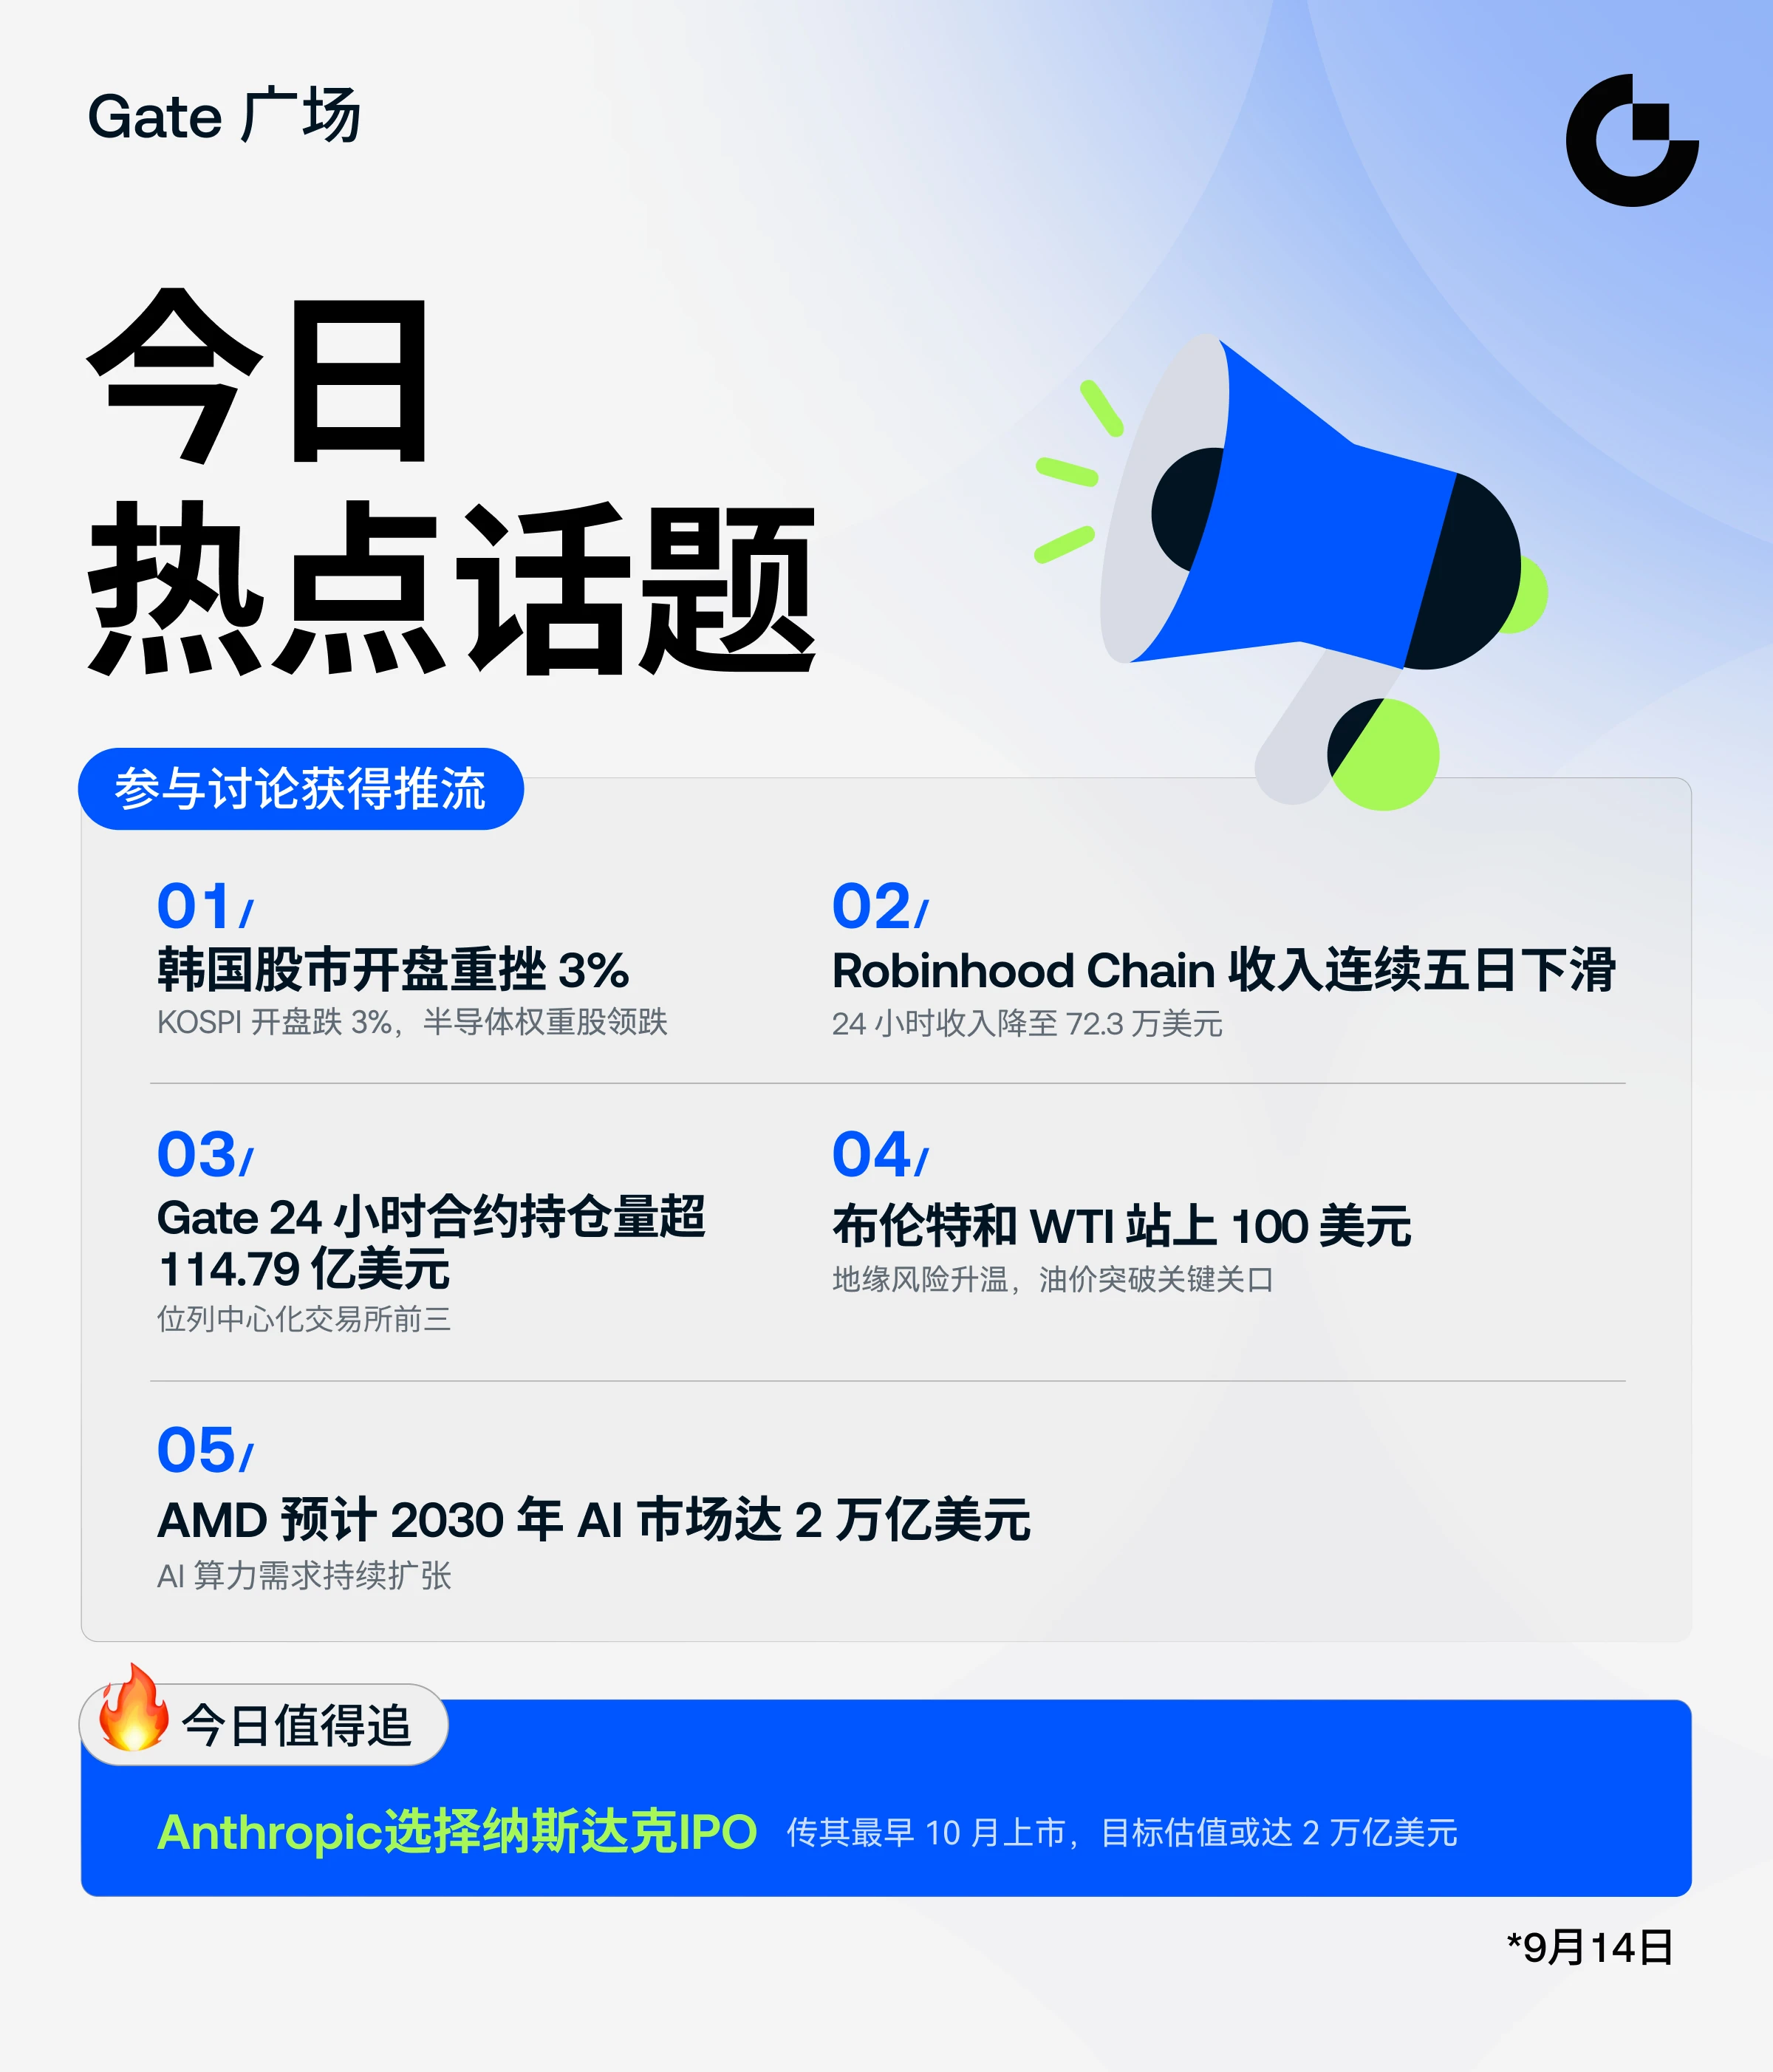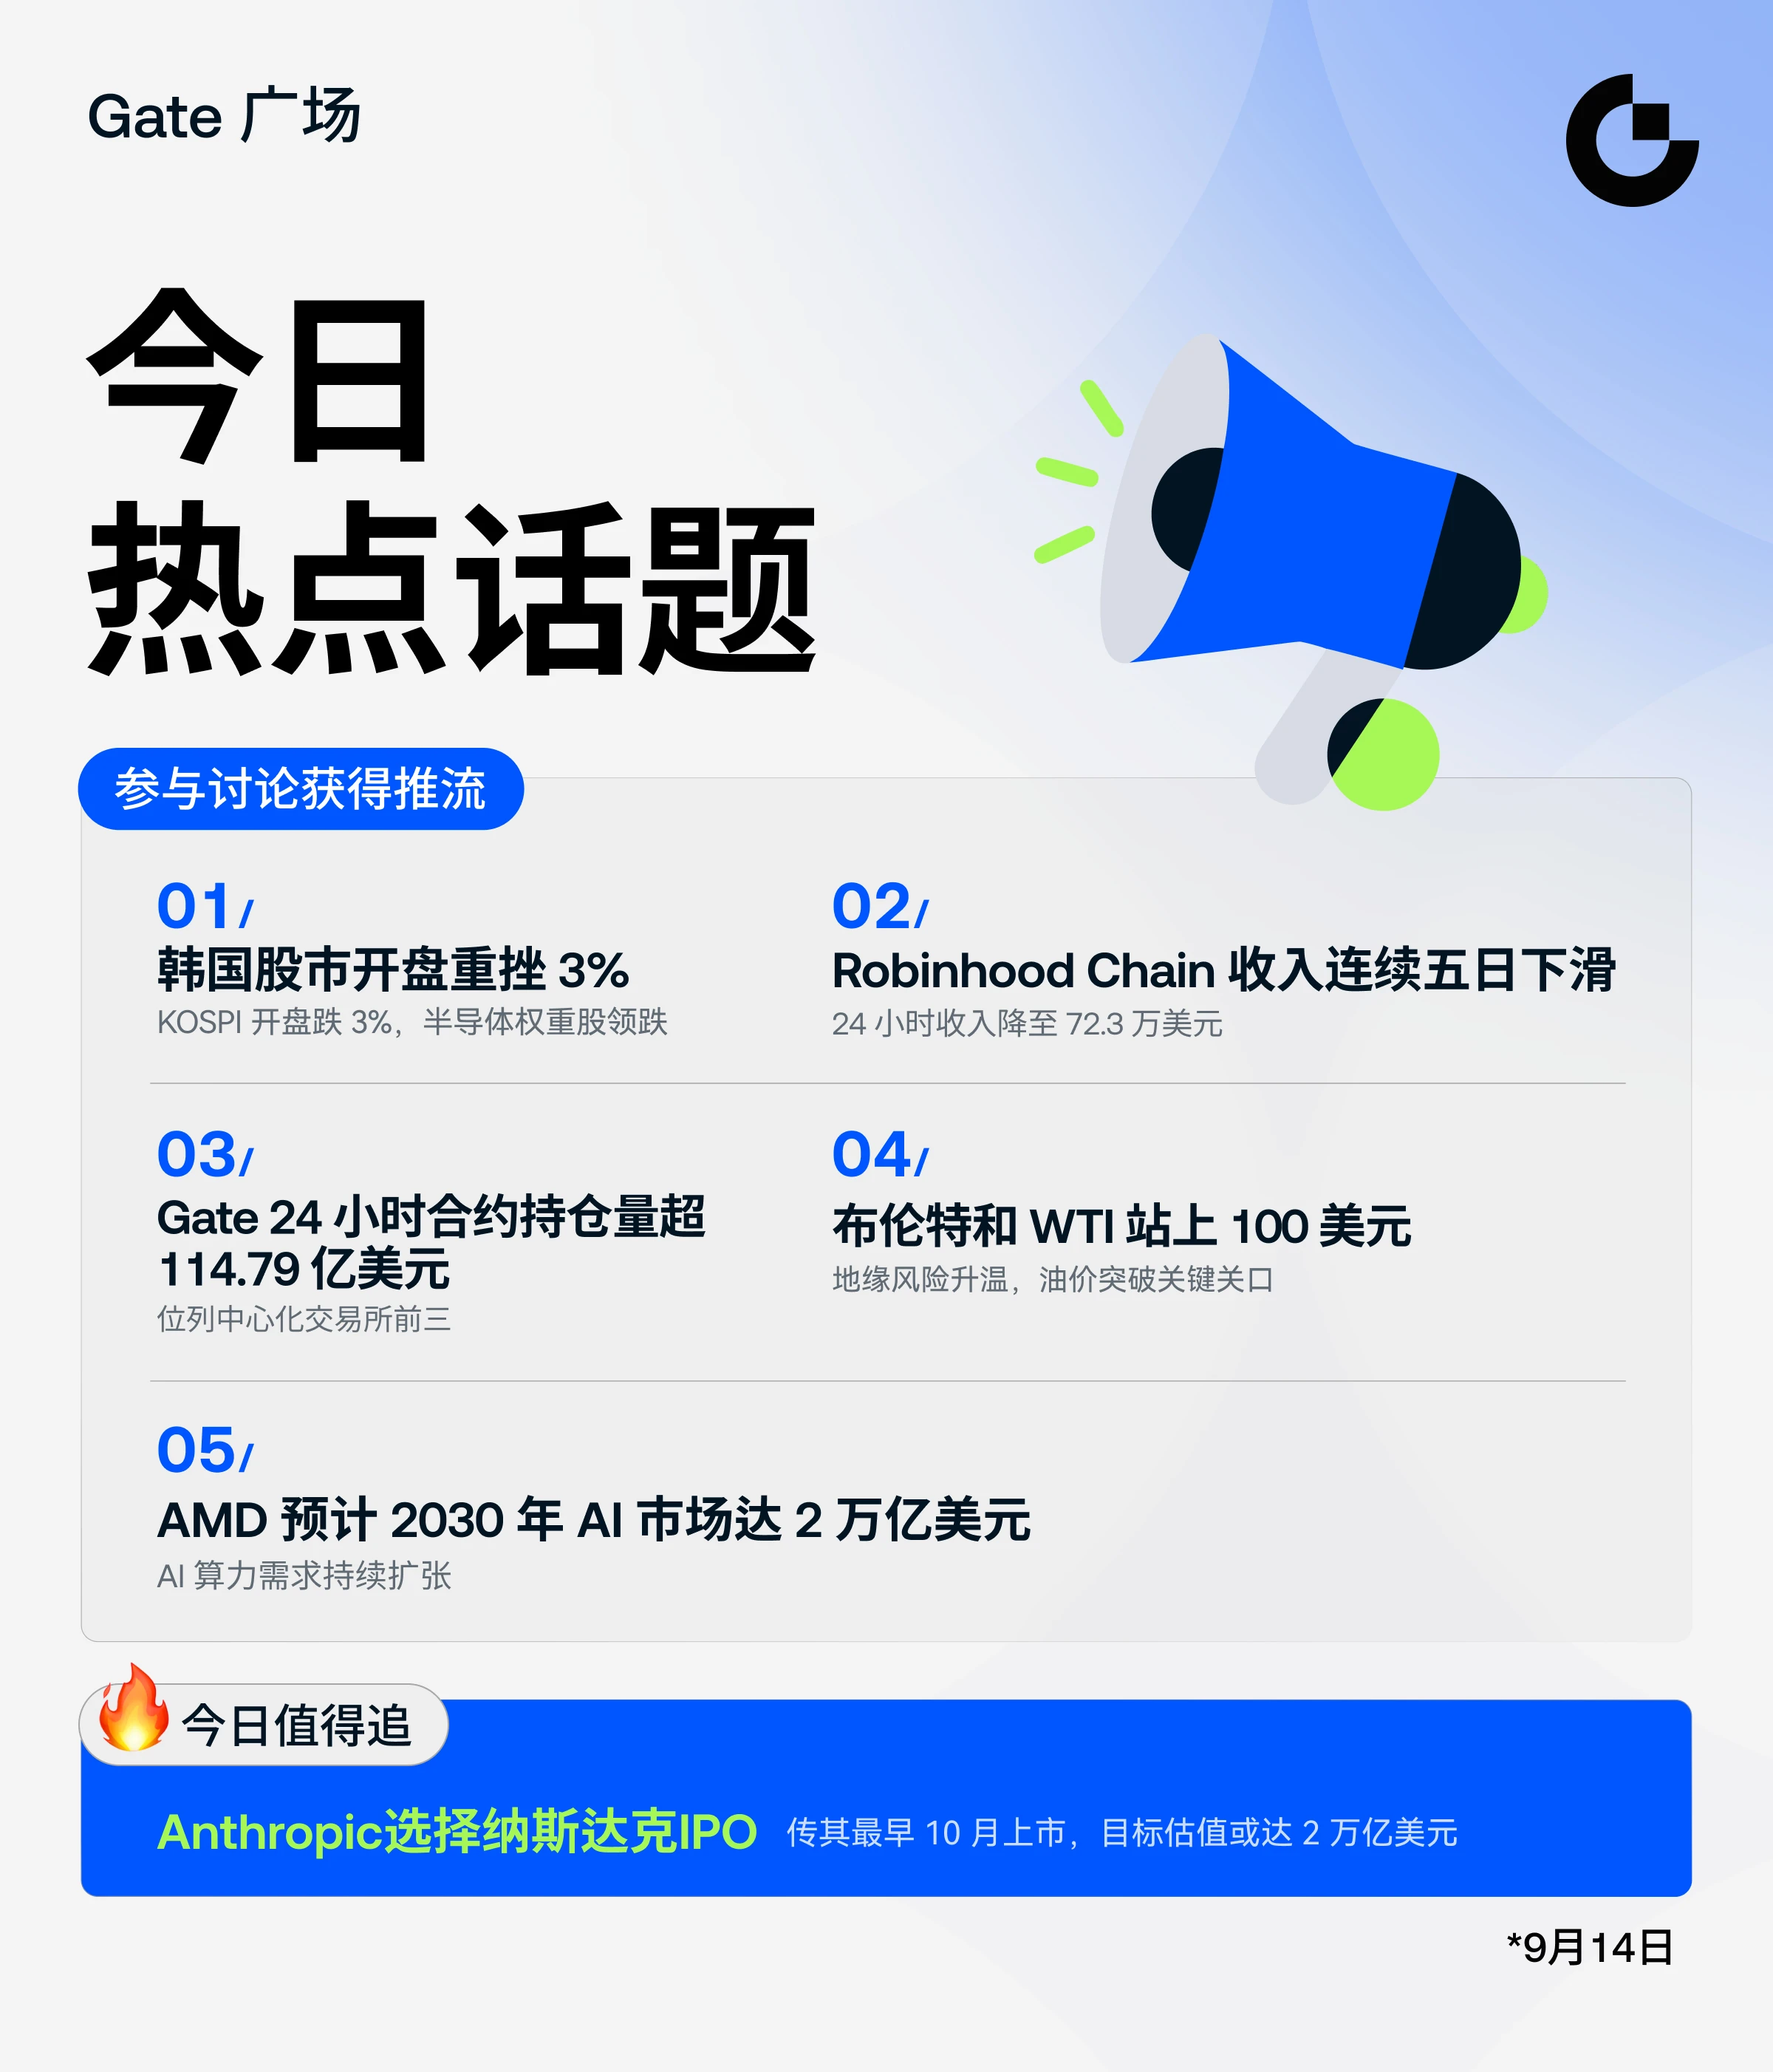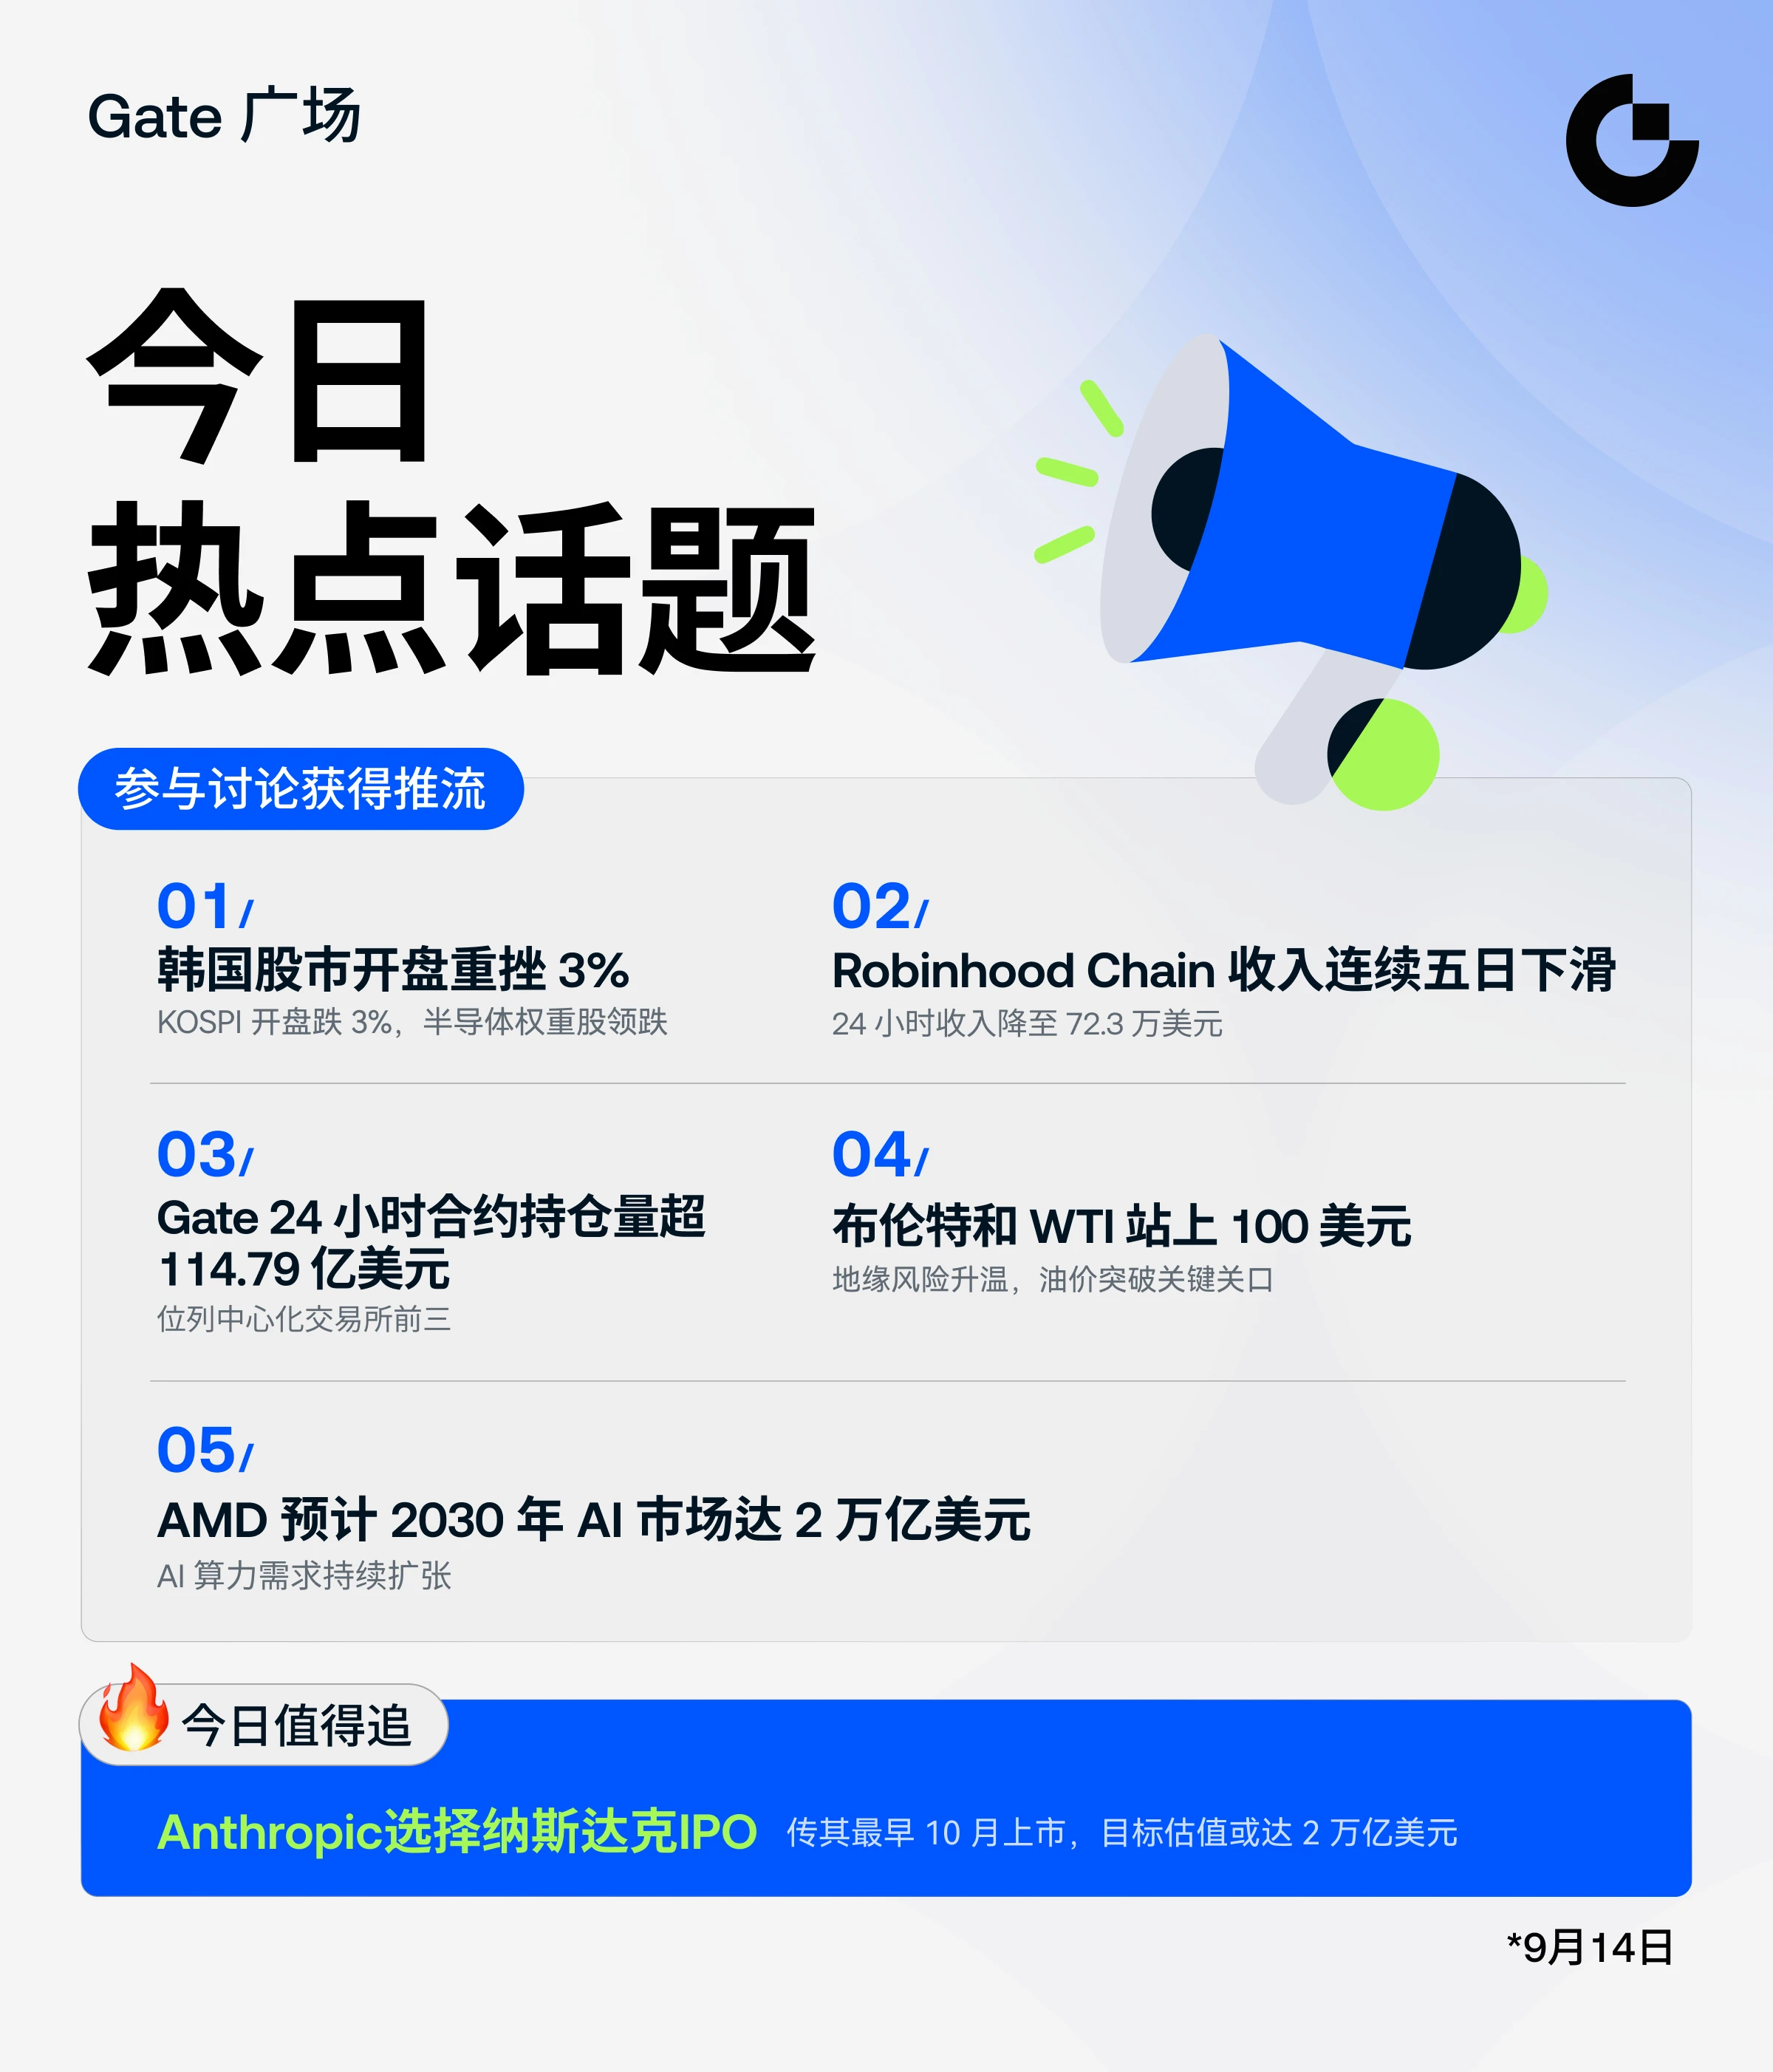



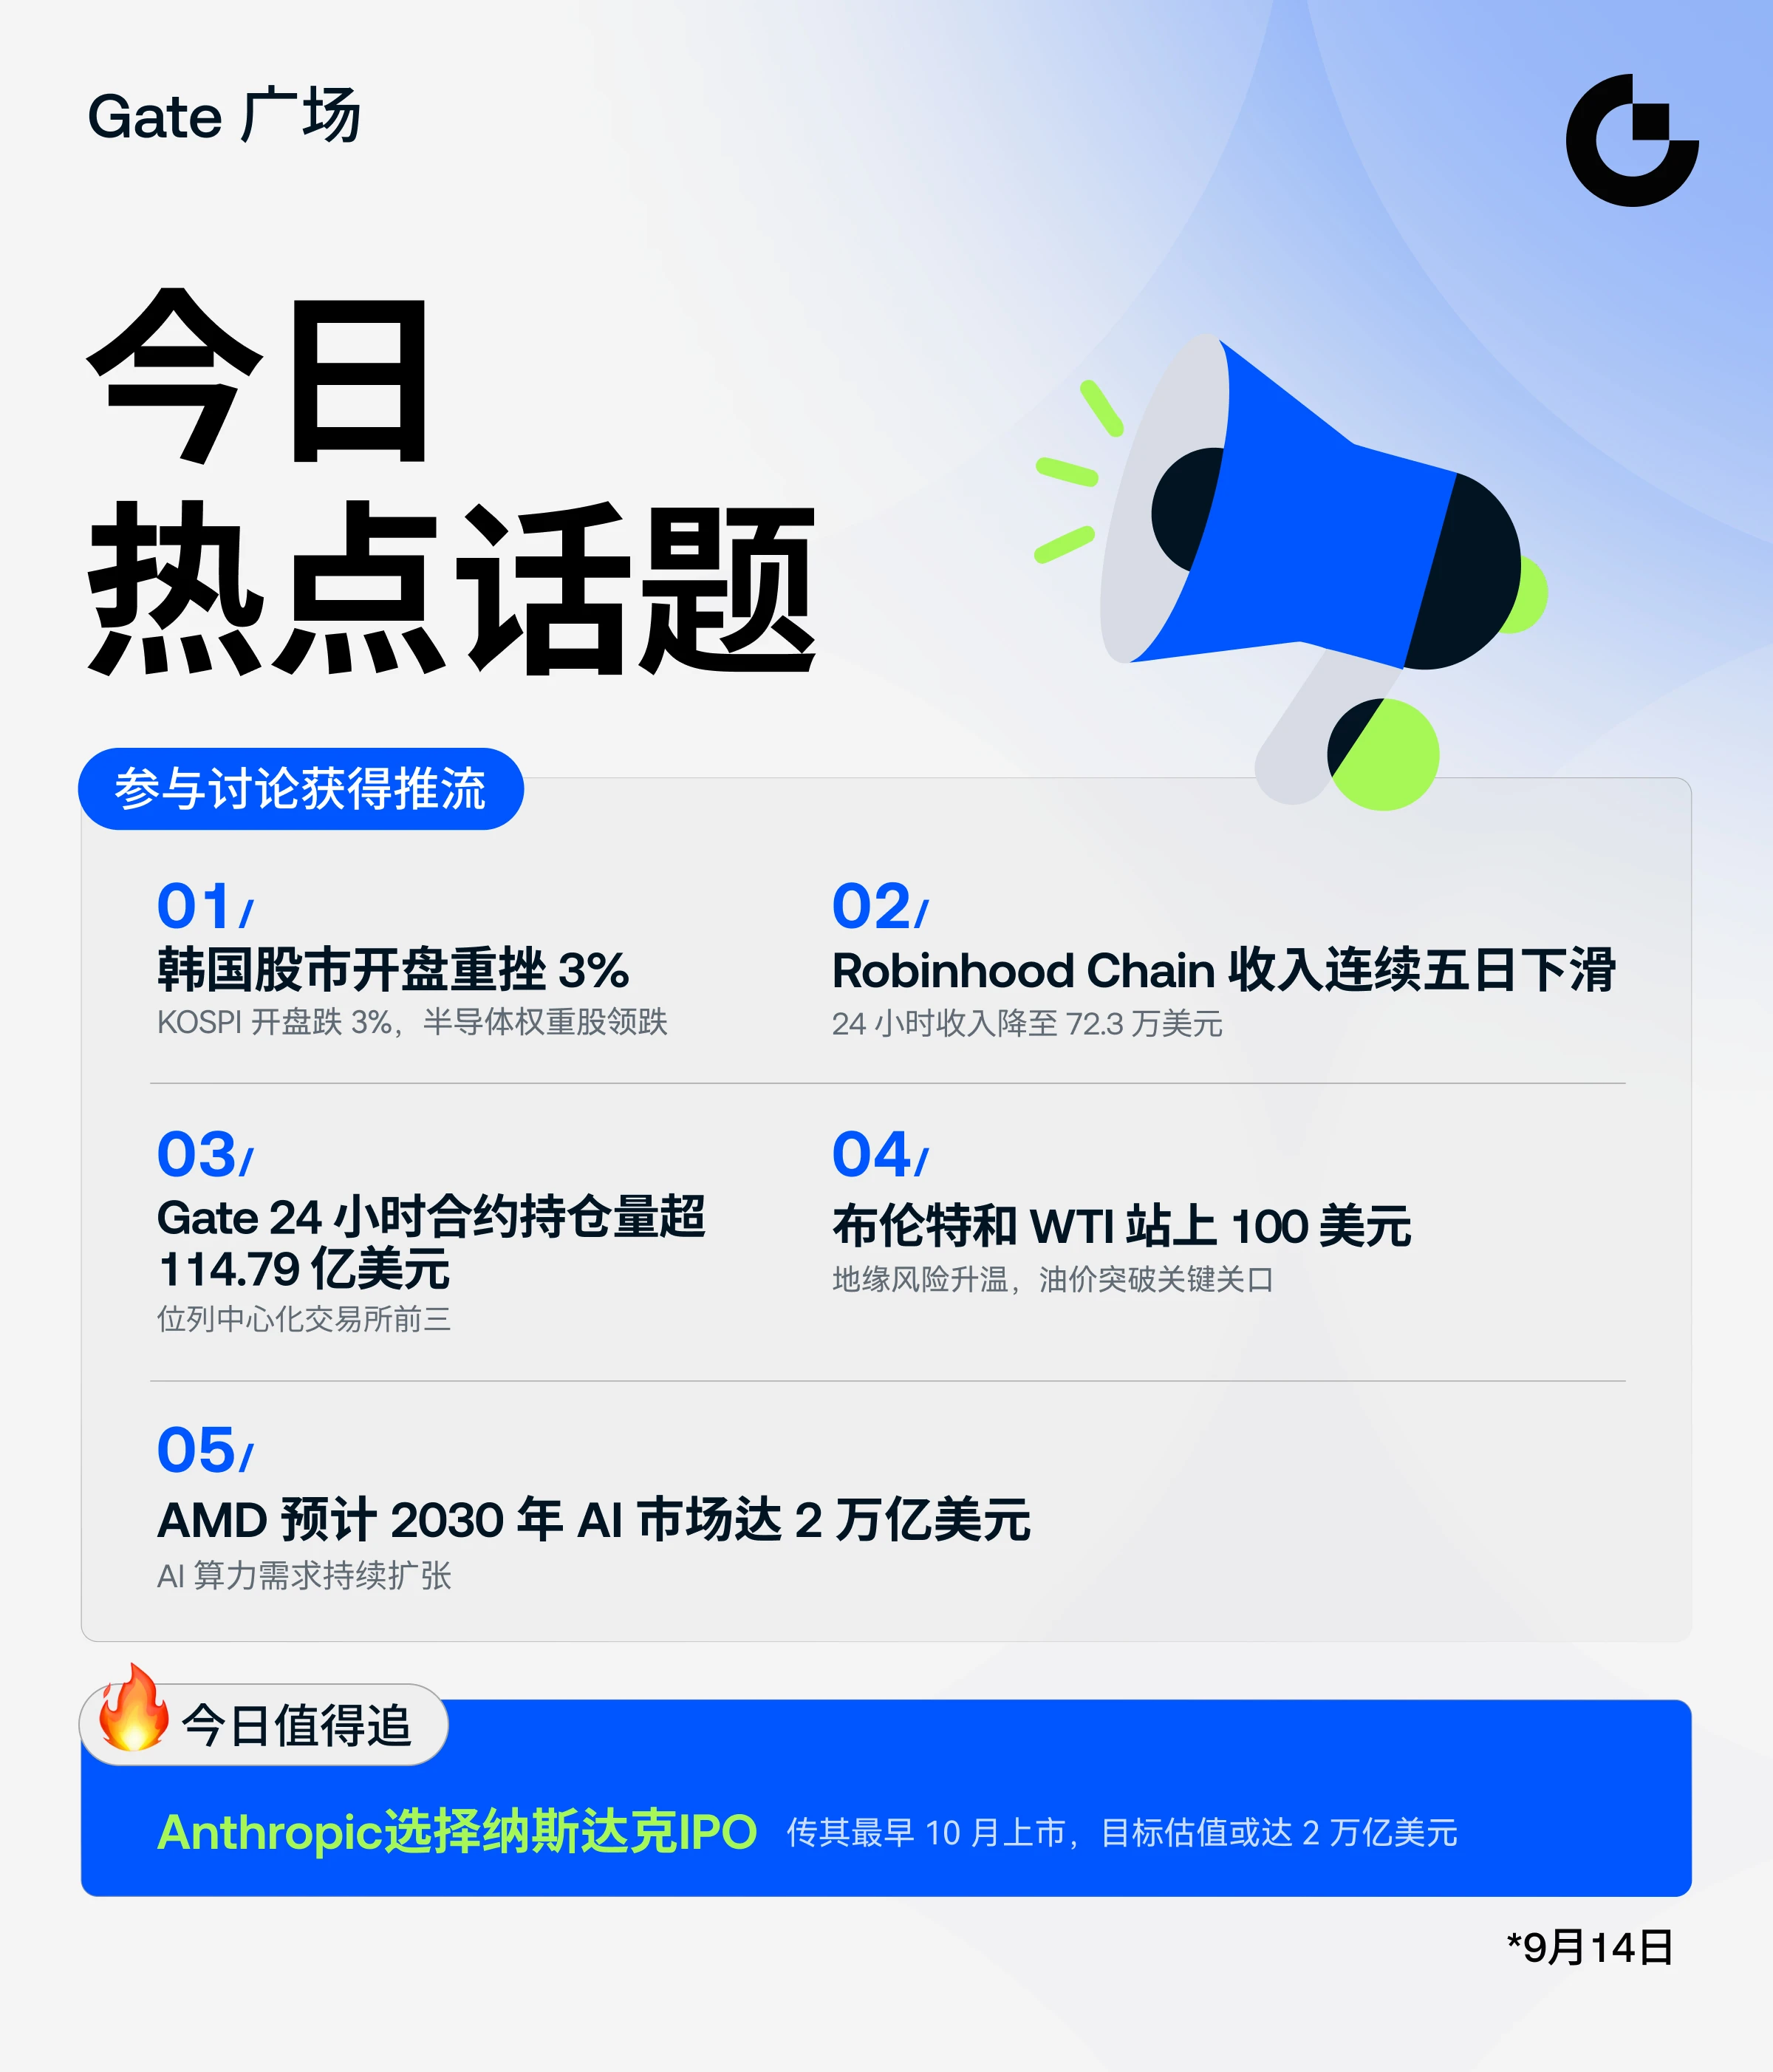
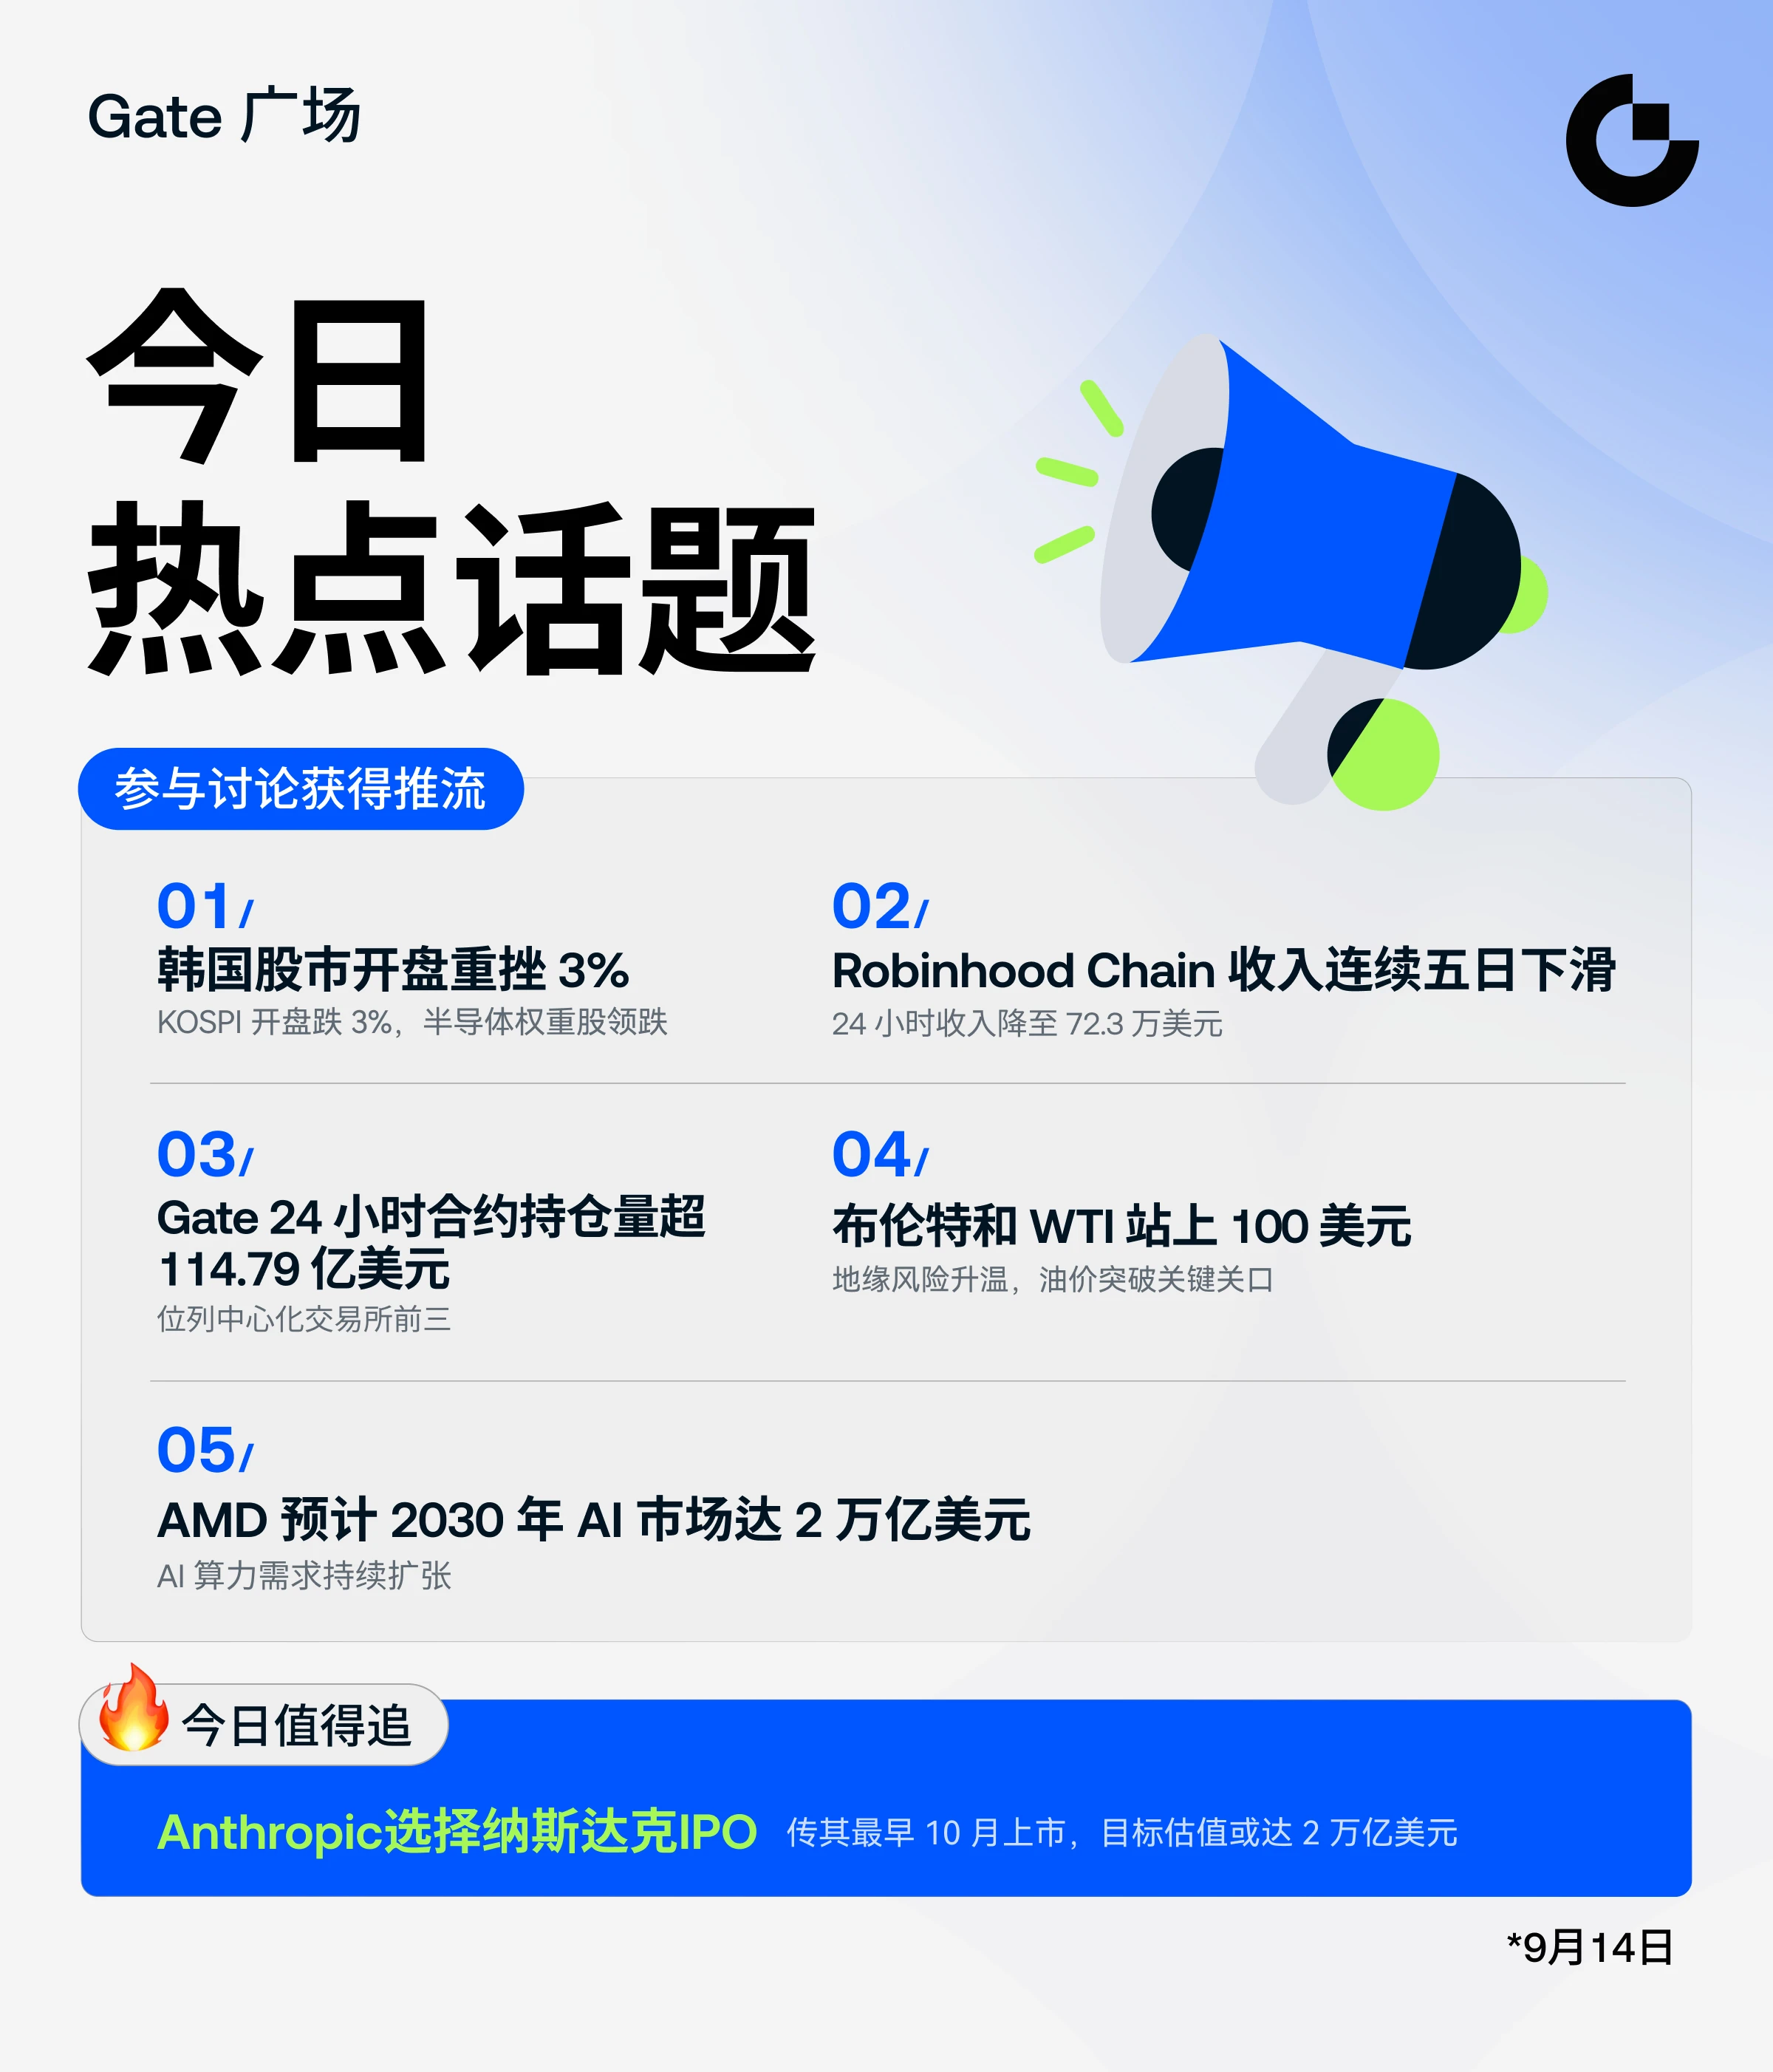
Robinhood Chain 收入连续五日下滑 - 24 小时收入降至 72.3 万美元
#RobinhoodChain #链上收入 #DeFi #收入下滑 #今日热点话题
Robinhood Chain Revenue Falls for Five Straight Days to $723K: The End of a Hype Cycle or a Healthy Normalization?
After a spectacular debut that made it one of the most talked-about chains in early September, Robinhood Chain is now showing the other side of rapid growth. Daily network revenue, which had peaked at around $6 million on September 4, has entered a five-day consecutive decline and has now compressed to the $723,000 to $950,000 range, representing an 83% to 85% drawdown from its all-time high.
On the surface, a drop of this magnitude looks like a collapse. The underlying data tells a far more nuanced and actually more interesting story about how new Layer-2 economies mature.
First, the numbers need to be placed in context. DeFiLlama data showed $5.54 million in daily revenue on September 4, followed by $841,178 on September 11, and $949,331 on September 10. Seven-day cumulative revenue settled around $18.34 million. That is still a figure that keeps Robinhood Chain ranked as the second-largest chain by daily revenue, just behind Canton, even during the correction. In other words, even at its low, it is earning more than most established Layer-1s.
Second, the decline in revenue has not been matched by a decline in usage. Blockscout data indicates the chain processed 13.6 million transactions on September 10, compared to 13.98 million on September 4, a drop of only about 3%. Decentralized exchange volume on the chain held firm near $1.7 to $2.5 billion in the same 24-hour window. Users did not leave. They simply started paying less.
That divergence between stable activity and falling fees is the key to understanding what happened. The initial revenue spike was not driven by organic, long-term transaction demand. It was driven by three temporary factors that all peaked at once. The public mainnet launch brought a wave of airdrop farmers executing high-frequency interactions to qualify for future rewards. The introduction of tokenized U.S. stocks for users in more than 120 countries created a novelty premium where traders were willing to pay elevated gas to be first. And an initial incentive program subsidized liquidity provision that inflated fee generation.
As those three factors normalized, the fee market did what fee markets always do. The average gas price fell back to a competitive level, and the protocol's take rate compressed. Gas revenue alone fell from $6.04 million on September 4 to $1.05 million on September 10, an 82.6% drop, perfectly mirroring total revenue.
For the parent company, this pattern is familiar. In its Q2 2026 report, Robinhood Markets reported that crypto transaction revenue fell 38% year-over-year to $100 million, even as equity trading volume hit $956 billion and options contracts reached 774 million. The company has consistently shown that it can grow its overall ecosystem while crypto-specific fees remain highly cyclical.
The strategic implication is actually positive. A chain that can maintain 13 million daily transactions and near-record DEX volume with sub-million-dollar daily revenue is demonstrating efficiency, not weakness. It suggests that the network is capable of supporting high throughput at low cost, which is precisely what is needed to compete for tokenized equities and retail DeFi flows in the long term. The $6 million day was an anomaly driven by speculation. The $723,000 day is likely much closer to its sustainable baseline.
What to watch next is not whether revenue rebounds to $6 million, because it should not without another artificial catalyst. What matters is whether transaction count and total value locked remain stable over the next two weeks and whether Robinhood Earn, its new decentralized lending product, can create a more durable, interest-based revenue stream to replace the volatile gas-based model.
#RobinhoodChain #链上收入 #DeFi #收入下滑 #今日热点话题
Robinhood Chain Revenue Falls for Five Straight Days to $723K: The End of a Hype Cycle or a Healthy Normalization?
After a spectacular debut that made it one of the most talked-about chains in early September, Robinhood Chain is now showing the other side of rapid growth. Daily network revenue, which had peaked at around $6 million on September 4, has entered a five-day consecutive decline and has now compressed to the $723,000 to $950,000 range, representing an 83% to 85% drawdown from its all-time high.
On the surface, a drop of this magnitude looks like a collapse. The underlying data tells a far more nuanced and actually more interesting story about how new Layer-2 economies mature.
First, the numbers need to be placed in context. DeFiLlama data showed $5.54 million in daily revenue on September 4, followed by $841,178 on September 11, and $949,331 on September 10. Seven-day cumulative revenue settled around $18.34 million. That is still a figure that keeps Robinhood Chain ranked as the second-largest chain by daily revenue, just behind Canton, even during the correction. In other words, even at its low, it is earning more than most established Layer-1s.
Second, the decline in revenue has not been matched by a decline in usage. Blockscout data indicates the chain processed 13.6 million transactions on September 10, compared to 13.98 million on September 4, a drop of only about 3%. Decentralized exchange volume on the chain held firm near $1.7 to $2.5 billion in the same 24-hour window. Users did not leave. They simply started paying less.
That divergence between stable activity and falling fees is the key to understanding what happened. The initial revenue spike was not driven by organic, long-term transaction demand. It was driven by three temporary factors that all peaked at once. The public mainnet launch brought a wave of airdrop farmers executing high-frequency interactions to qualify for future rewards. The introduction of tokenized U.S. stocks for users in more than 120 countries created a novelty premium where traders were willing to pay elevated gas to be first. And an initial incentive program subsidized liquidity provision that inflated fee generation.
As those three factors normalized, the fee market did what fee markets always do. The average gas price fell back to a competitive level, and the protocol's take rate compressed. Gas revenue alone fell from $6.04 million on September 4 to $1.05 million on September 10, an 82.6% drop, perfectly mirroring total revenue.
For the parent company, this pattern is familiar. In its Q2 2026 report, Robinhood Markets reported that crypto transaction revenue fell 38% year-over-year to $100 million, even as equity trading volume hit $956 billion and options contracts reached 774 million. The company has consistently shown that it can grow its overall ecosystem while crypto-specific fees remain highly cyclical.
The strategic implication is actually positive. A chain that can maintain 13 million daily transactions and near-record DEX volume with sub-million-dollar daily revenue is demonstrating efficiency, not weakness. It suggests that the network is capable of supporting high throughput at low cost, which is precisely what is needed to compete for tokenized equities and retail DeFi flows in the long term. The $6 million day was an anomaly driven by speculation. The $723,000 day is likely much closer to its sustainable baseline.
What to watch next is not whether revenue rebounds to $6 million, because it should not without another artificial catalyst. What matters is whether transaction count and total value locked remain stable over the next two weeks and whether Robinhood Earn, its new decentralized lending product, can create a more durable, interest-based revenue stream to replace the volatile gas-based model.