LittleQueen

vip
Active for: 1.4y
Peak Tier 5
Hello! I’m Littlequeen,here to guide you through the crypto market with smart signals and live insights. From trends to real-time updates, I break down data so you can trade with confidence. Got questions? I’ve got answers — don’t hesitate to ask! Join my live streams and let’s grow in this journey together!
#GateTop4MainstreamCEX
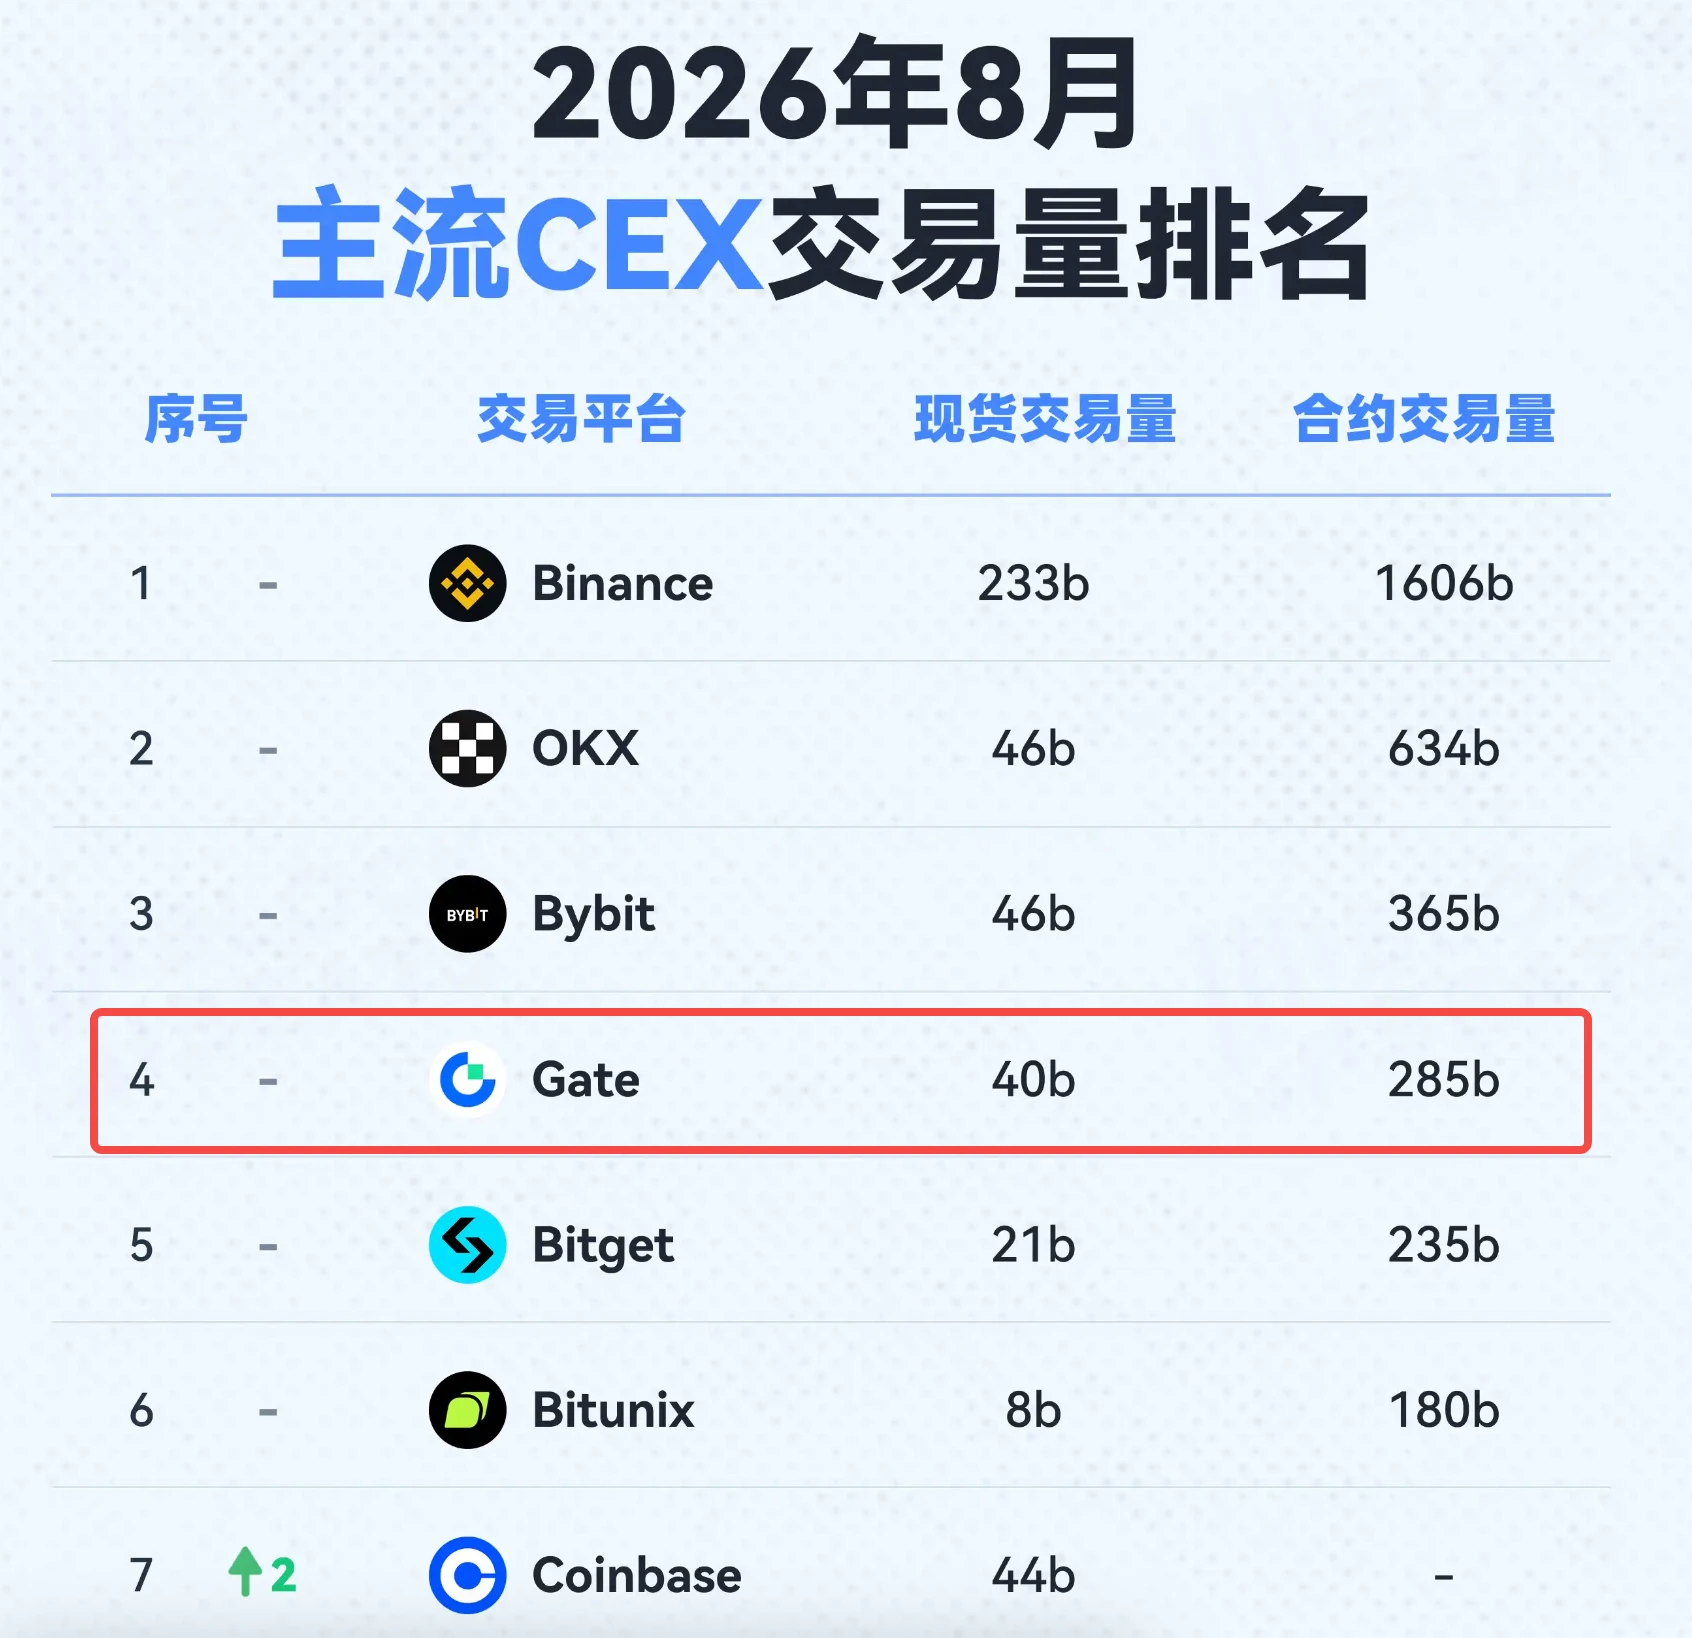
I keep seeing people focus on the “No. 4” part of Gate’s August ranking.
Personally, I’m more interested in what happened before Gate got there — and whether the numbers are strong enough to push it toward No. 3 next.
The August data shared by BlockBeats shows Gate doing roughly $40B in spot volume and $285B in derivatives volume. That is not a small number, especially when you consider how competitive the CEX market has become.
But volume by itself doesn’t convince me.
What I want to see is whether the activity is being supported by actual capital flows, users, liquidi
MrFlower_XingChen
#GateTop4MainstreamCEX
I keep seeing people focus on the “No. 4” part of Gate’s August ranking.
Personally, I’m more interested in what happened before Gate got there — and whether the numbers are strong enough to push it toward No. 3 next.
The August data shared by BlockBeats shows Gate doing roughly $40B in spot volume and $285B in derivatives volume. That is not a small number, especially when you consider how competitive the CEX market has become.
But volume by itself doesn’t convince me.
What I want to see is whether the activity is being supported by actual capital flows, users, liquidity and product growth.
And that’s where Gate’s recent numbers get interesting.
Gate’s August transparency report shows $8.215B in total reserves and a 127% overall reserve ratio as of August 19. It also reported around $308.1M in 30-day net inflows, which Gate said placed it second among major exchanges.
For me, that matters more than simply saying “Gate is No. 4.”
Then look at the user side.
Gate has now passed 60 million registered users, while its ecosystem has expanded to more than 5,000 digital assets and 12,800 stocks and ETFs. It is clearly moving beyond being just another crypto spot and futures platform and trying to build a much broader trading ecosystem.
But the part I’m watching most closely is derivatives.
Gate’s RWA perpetual volume reached approximately $64.7B in August, up 158% month over month. Its market share increased from 5.32% in July to 12.6%, putting Gate in the Top 3 for RWA perpetual trading.
That’s the kind of growth I pay attention to.
Because if Gate can keep gaining ground in newer markets while maintaining strong spot and derivatives activity, then the No. 4 ranking starts looking less like a ceiling and more like a stepping stone.
There’s another number I like even more from the transparency report: Gate’s Event Contract trading volume increased 286.09% month over month, while Perp DEX API trading volume increased 134%. Those are very different products, but together they show that the platform is trying to expand activity across multiple trading segments rather than relying on one market.
And this is where my personal view comes in.
I don’t think Gate needs to chase No. 3 just for the ranking.
If I’m using a platform for actual trading, I care about things like liquidity, execution, market depth, product choice, risk controls and whether the platform keeps improving when market conditions get difficult.
A ranking is the result.
The underlying infrastructure is what creates the ranking.
So where do I think Gate should be heading?
No. 4 → No. 3 → No. 2.
But I would rather see Gate take the slower route and make the growth sustainable than jump one position and lose momentum later.
The next test, in my opinion, is simple:
Can Gate continue attracting capital?
Can it keep growing derivatives volume without relying on temporary spikes?
Can it turn 60M+ users into deeper and more consistent trading activity?
And can its expansion into RWA, stocks and other asset classes create another source of long-term volume?
If the answer to those questions keeps being yes, then I don’t think No. 3 is an unrealistic target anymore.
In fact, the more interesting conversation might eventually become whether Gate can challenge the exchanges above No. 3.
But I’m not going to get ahead of the data.
Right now, I see a platform sitting at No. 4 with several growth indicators moving in the right direction.
So my target is straightforward:
No. 4 is where Gate is today.
No. 3 is where I want to see it next.
And after that, let the numbers decide how high it can go.
That’s the part I’ll be watching.
#GateMeme #GateTrenchesZeroGas #AppleEvent @GateSquare @Gate_Square
repost-content-media
#BrentWTITop$100
Brent crude is back above $100 — and this time, the move is not just about momentum.
As of September 14, Brent is trading around the $107 area, while WTI is around $103. Oil has moved sharply higher as traders price in a much bigger supply-risk premium across the Middle East. Reuters reported Brent near $107.81 and WTI near $102.94 today, while another live market feed showed Brent around $107.43.
The biggest catalyst right now is the growing threat to physical oil flows.
Saudi Arabia's East-West oil pipeline, which provides an important alternative route around the Strait o
MrFlower_XingChen
#BrentWTITop$100
Brent crude is back above $100 — and this time, the move is not just about momentum.
As of September 14, Brent is trading around the $107 area, while WTI is around $103. Oil has moved sharply higher as traders price in a much bigger supply-risk premium across the Middle East. Reuters reported Brent near $107.81 and WTI near $102.94 today, while another live market feed showed Brent around $107.43.
The biggest catalyst right now is the growing threat to physical oil flows.
Saudi Arabia's East-West oil pipeline, which provides an important alternative route around the Strait of Hormuz, was hit by drone attacks. At the same time, shipping risks around the Gulf and Bab el-Mandeb are increasing, while planned talks involving Iran and Gulf countries were postponed. That combination is making traders much more nervous about how quickly crude supplies can move through the region.
This is why I’m watching the $100 level very closely.
Brent already pushed above $100 earlier this month, and the latest move toward $108 shows that buyers are still willing to chase the market when new supply disruptions appear. Reuters reported that Brent jumped more than 6% on September 10 as tanker attacks deepened fears about future supply.
But I would not blindly chase every green candle here.
Oil above $100 creates a completely different macro environment. Higher crude prices can feed directly into fuel and transportation costs, keeping inflation elevated and potentially making central banks more cautious about cutting rates. Reuters noted that the current oil shock is already complicating the Federal Reserve's policy outlook.
My market view is simple: as long as geopolitical risks continue disrupting production, pipelines or shipping routes, Brent has a strong reason to remain elevated. A clean break and hold above the recent $108 area would keep the upside momentum alive.
But if diplomatic progress reduces the supply-risk premium, or disrupted flows begin returning to normal, this rally can unwind very quickly. The EIA also expects elevated prices while Middle East disruptions persist, but sees prices easing as production and exports recover.
So for me, the key story is no longer simply “Brent crossed $100.”
The real story is whether the market can stay above $100 without another major supply shock.
Right now, the fundamentals are still bullish — but volatility is extremely high, so I would rather wait for confirmation than chase the move.
#GateMeme #GateTrenchesZeroGas #GateLaunchesTrenchesWith0GasFee #AppleEvent @GateSquare @Gate_Square
$XTIUSD
repost-content-media
#AnthropicPicksNasdaqForIPO
This is one of those headlines where I think it is important to separate what is actually confirmed from what the market is already pricing in.
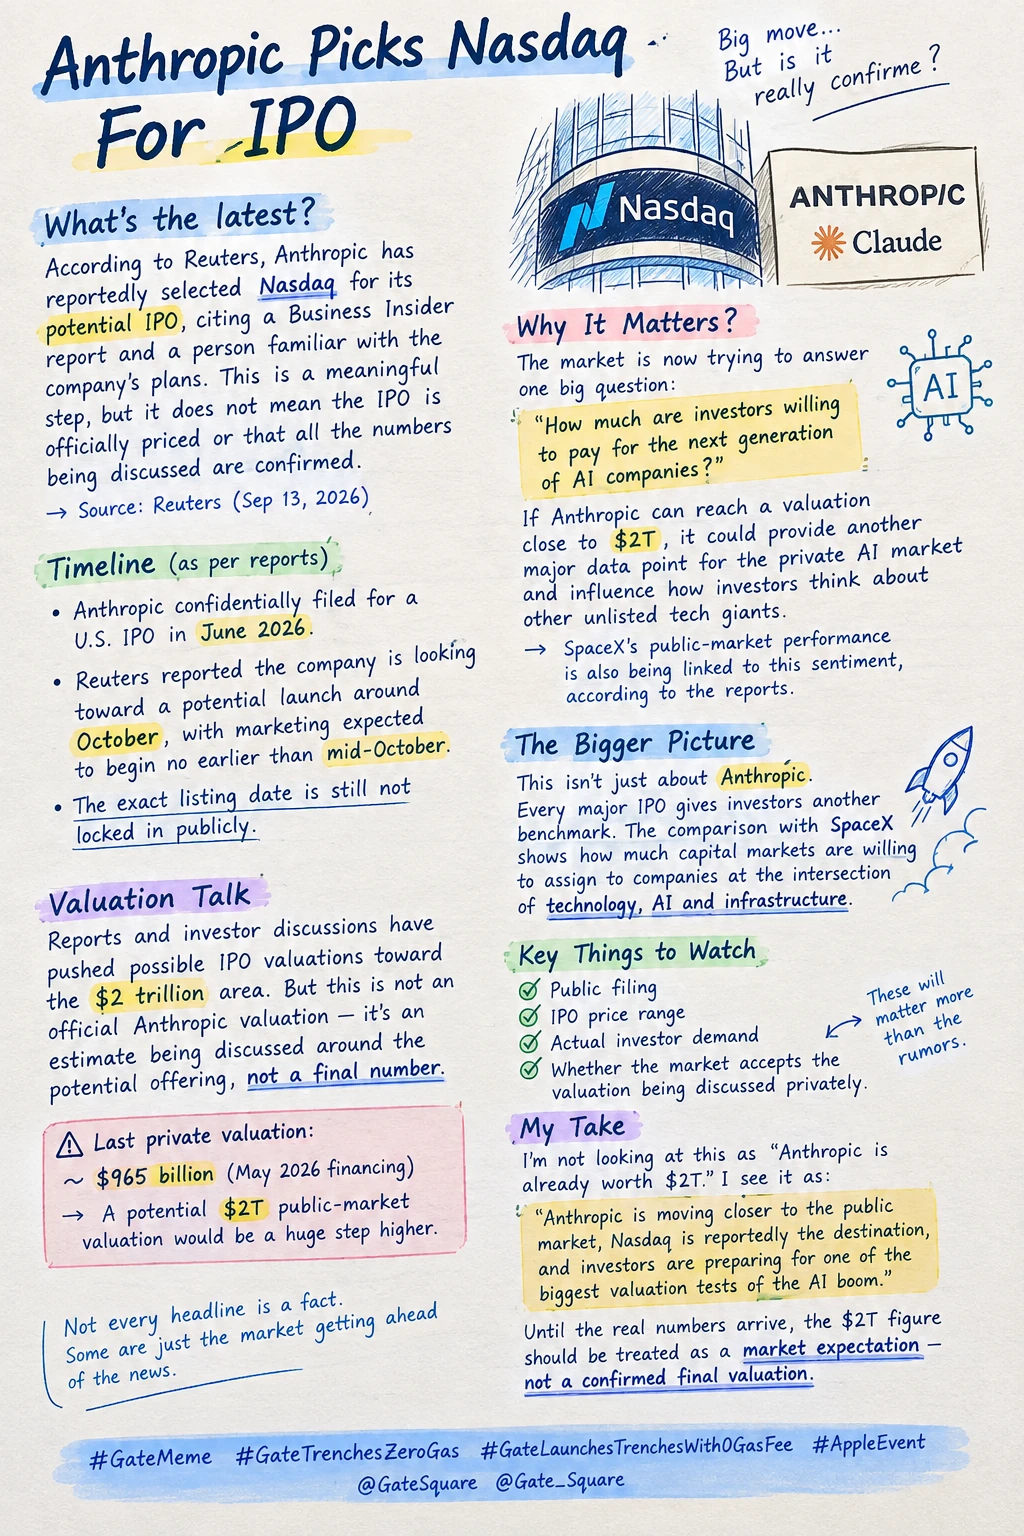
Anthropic has reportedly selected Nasdaq for its potential IPO, according to Reuters, citing a Business Insider report and a person familiar with the company's plans. That is a meaningful step because Anthropic is moving closer to becoming a public company, but it does not mean the IPO is officially priced or that every number circulating online is confirmed.
Anthropic, the company behind Claude, confidentially filed for a
MrFlower_XingChen
#AnthropicPicksNasdaqForIPO
This is one of those headlines where I think it is important to separate what is actually confirmed from what the market is already pricing in.
Anthropic has reportedly selected Nasdaq for its potential IPO, according to Reuters, citing a Business Insider report and a person familiar with the company's plans. That is a meaningful step because Anthropic is moving closer to becoming a public company, but it does not mean the IPO is officially priced or that every number circulating online is confirmed.
Anthropic, the company behind Claude, confidentially filed for a U.S. IPO in June. Reuters has since reported that the company is looking toward a potential launch around October, with marketing expected to begin no earlier than mid-October. The exact listing date is still not locked in publicly.
Now comes the part that has really caught the market's attention:
Valuation.
Reports and investor discussions have pushed possible IPO valuations toward the $2 trillion area. But I would not call $2T an official Anthropic valuation today. It is an estimate being discussed around the potential offering, not a final IPO price.
That distinction matters.
Anthropic's last major private valuation was reported around $965 billion following its May 2026 financing, meaning a potential $2T public-market valuation would represent a huge step higher.
And this is where the story becomes bigger than Anthropic itself.
The market is effectively trying to answer one question:
How much are investors actually willing to pay for the next generation of AI companies?
If Anthropic can successfully approach a valuation close to $2T, it would provide another major data point for the private AI market. It could also influence how investors think about other giant unlisted technology companies and the valuations attached to them.
SpaceX is an obvious comparison.
SpaceX's enormous public-market debut has already given investors another reference point for how much capital markets are willing to assign to companies sitting at the intersection of technology, AI and infrastructure. The comparison is not perfect because SpaceX and Anthropic have completely different businesses, but the psychological effect on the market is interesting.
Private-market valuations are no longer happening in isolation.
Every major IPO gives investors another benchmark.
And that is why I think the Nasdaq decision itself is less important than what comes next.
The real test will be Anthropic's public filing, its financial numbers, the actual IPO price range, investor demand and — most importantly — whether public-market investors accept the valuation being discussed privately.
There is also another risk that the market cannot ignore.
AI valuations have become extremely sensitive to expectations. If revenue growth, AI infrastructure spending or future profitability fail to justify the valuation investors are expecting, the same excitement that pushes a private company higher can work in reverse once the stock becomes publicly traded.
So I am not looking at this headline as:
“Anthropic is officially worth $2 trillion.”
I am looking at it as:
Anthropic is moving closer to the public market, Nasdaq is reportedly the destination, and investors are now preparing for one of the biggest valuation tests of the AI boom.
The next numbers that really matter are the public filing, IPO price range and actual investor demand.
Until those arrive, the $2T figure should be treated as a market expectation/reporting point — not a confirmed final valuation.
That distinction is where the real story is.
#GateMeme #GateTrenchesZeroGas #GateLaunchesTrenchesWith0GasFee #AppleEvent @GateSquare @Gate_Square
$NAS100
repost-content-media
NDAQ-0.64%
SPCX+1.95%
NAS100-0.73%
BTC MARKET PREDICTION
live-cover
LIVE34
#AMD$2TAI2030
AMD is no longer just trying to take a piece of the AI chip market.
It is positioning itself for what could become a much bigger computing cycle — and the numbers behind the latest customer wins are starting to make that story more interesting.
AMD’s CFO Jean Hu recently said the company’s total addressable market could reach $2 trillion by 2030, driven by growing demand across AI and computing. The important detail here: this is an estimate of AMD’s addressable market, not $2 trillion of expected AMD revenue.
And there is already real customer activity behind the thesis.
Meta h
MrFlower_XingChen
#AMD$2TAI2030
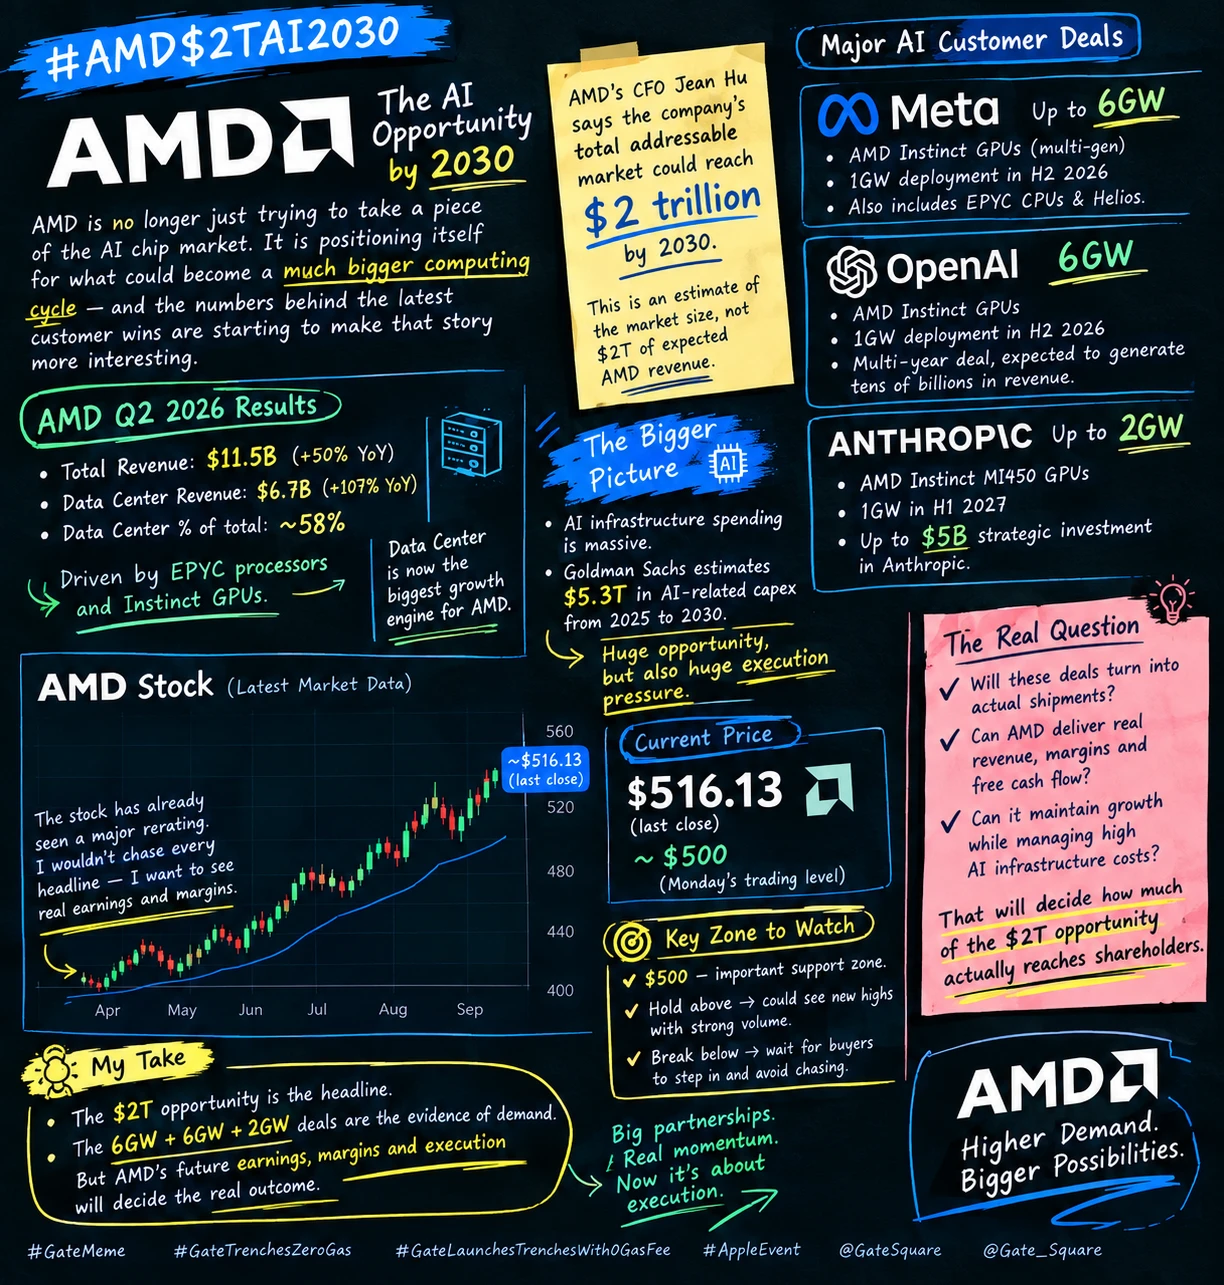
AMD is no longer just trying to take a piece of the AI chip market.
It is positioning itself for what could become a much bigger computing cycle — and the numbers behind the latest customer wins are starting to make that story more interesting.
AMD’s CFO Jean Hu recently said the company’s total addressable market could reach $2 trillion by 2030, driven by growing demand across AI and computing. The important detail here: this is an estimate of AMD’s addressable market, not $2 trillion of expected AMD revenue.
And there is already real customer activity behind the thesis.
Meta has agreed to deploy up to 6 gigawatts of AMD Instinct GPUs across multiple generations, with the first 1GW deployment scheduled to begin in the second half of 2026. The partnership also includes AMD EPYC CPUs and the Helios rack-scale architecture.
OpenAI has a separate 6-gigawatt agreement with AMD, with the first 1GW of MI450 GPU deployment also expected to begin in the second half of 2026. AMD says the multi-year agreement is expected to generate tens of billions of dollars in revenue over time.
Then came Anthropic.
Anthropic agreed to deploy up to 2GW of AMD Instinct MI450 GPUs in AMD Helios systems, with the first gigawatt planned for the first half of 2027. AMD is also committing up to $5 billion in strategic investment in Anthropic, tied to deployment milestones.
So the bigger story isn't simply “AMD has AI customers.”
It is that several major AI companies are committing to AMD hardware at gigawatt scale.
And AMD’s actual numbers are starting to reflect the demand.
In Q2 2026, AMD generated $11.5 billion in total revenue, up 50% year over year. Data Center revenue reached $6.7 billion, up an impressive 107% YoY, driven by EPYC processors and Instinct GPUs. Data Center now represents roughly 58% of AMD’s quarterly revenue.
That is the part I would watch more closely than the $2T headline.
The story is promising, but future AI contracts still have to become actual shipments, revenue, margins and free cash flow. Large capacity agreements sound huge, but investors ultimately need to see execution.
And there is another risk people shouldn't ignore: AI infrastructure is becoming extremely capital intensive. Goldman Sachs estimates the major technology companies could spend around $5.3 trillion from 2025 through 2030 on AI-related capital expenditure. That tells you how large the opportunity is — but also how much money is being committed to build it.
Now look at AMD itself.
The latest completed close was around $516.13, while Monday market data has shown the stock trading around the $500 area. AMD has already experienced a huge rerating, so at these levels I wouldn't chase every AI headline blindly.
For me, the key zone is around $500.
If AMD can hold that area and reclaim the recent highs with strong volume, the market can continue pricing in higher expectations for its AI business.
If $500 fails decisively, I would rather see where buyers step back in than assume every AI partnership automatically means the stock has to go higher.
My view is simple:
The $2T opportunity is the headline.
The 6GW + 6GW + 2GW customer commitments are the evidence of demand.
But AMD’s future earnings, margins and execution will decide how much of that opportunity actually reaches shareholders.
That is the part I’m watching.
#GateMeme #GateTrenchesZeroGas #GateLaunchesTrenchesWith0GasFee #AppleEvent @GateSquare @Gate_Square
$AMD
repost-content-media
AMD+2.54%
META+0.59%
GS+0.90%
#PumpFunHolderRewards
Pump.fun just changed one of the most important incentives around its token-launch economy — and I think the bigger story is what this could do to holder behavior.
The platform has introduced Holder Rewards and removed Cashback mode for standard token launches. Under the new system, eligible holders can receive a proportional share of the fees generated by their token, with rewards distributed multiple times per hour. The reward is paid in the quote asset of the trading pair — for example, a token paired with SOL can distribute rewards in SOL.
That is a meaningful chang
MrFlower_XingChen
#PumpFunHolderRewards
Pump.fun just changed one of the most important incentives around its token-launch economy — and I think the bigger story is what this could do to holder behavior.
The platform has introduced Holder Rewards and removed Cashback mode for standard token launches. Under the new system, eligible holders can receive a proportional share of the fees generated by their token, with rewards distributed multiple times per hour. The reward is paid in the quote asset of the trading pair — for example, a token paired with SOL can distribute rewards in SOL.
That is a meaningful change in the incentive structure.
Cashback was designed around rewarding trading activity. Holder Rewards puts more emphasis on actually staying in the position.
For new launches, creators can now choose between the traditional Creator Fee model and Holder Rewards. Existing Cashback and Creator Fee tokens can also apply to switch into Holder Rewards, but once the change is made, it cannot be reversed.
There is also an eligibility threshold: reports say holders need more than $20 worth of the token to qualify, while the reward amount is determined proportionally by their holdings. The longer-hold incentive is also built into the new system through higher reward caps for longer holding periods.
This is where I find the update interesting.
Pump.fun has always been heavily associated with extremely fast meme-coin rotations. A trader launches, attention arrives, liquidity moves in, and participants often move on to the next narrative just as quickly.
Holder Rewards tries to change that behavior.
If a token generates meaningful trading fees, simply holding it can now create an additional reason not to sell immediately. That could potentially help communities retain liquidity and reduce some of the “launch today, disappear tomorrow” behavior.
But there is an important catch:
Rewards are only as strong as the trading activity generating them.
Pump.fun's own terms make clear that rewards depend on fees generated by activity; there is no guaranteed minimum or permanent reward stream.
That means I would not treat Holder Rewards as automatic yield.
I would look at volume, liquidity, holder distribution and actual fee generation before deciding whether a token's reward model is meaningful.
And Pump.fun itself still has something to prove.
Current CoinGecko data shows roughly $1.38M in 24-hour platform fees and about $783K in project revenue, showing that the ecosystem still has substantial economic activity. At the same time, PUMP has been volatile, and the platform recently faced the temporary removal of its iOS app from the U.S. and India App Stores — another factor that could affect user growth if the situation persists.
So my takeaway is not simply “Holder Rewards is bullish.”
The real test is whether Pump.fun can turn this mechanism into better retention without sacrificing trading activity.
If users hold longer, communities become stronger and fee generation remains healthy, this could become a meaningful evolution of the launchpad model.
If trading volume falls because fewer users are actively rotating capital, the reward system could become much less attractive.
For me, the next numbers worth watching are simple:
Volume → fees → holder retention → liquidity.
That will tell us whether Holder Rewards is actually changing the behavior of Pump.fun users — or just changing the way the fees are distributed.
#PumpFunHolderRewards
#GateMeme #GateTrenchesZeroGas #AppleEvent @GateSquare @Gate_Square
@
repost-content-media
PUMP-3.31%
SOL+0.22%
#HBMShortageBoostsAlChipPrices
The AI trade has a new bottleneck — and it is sitting inside the chip, not outside the data center.
Everyone has been watching GPU demand, AI server orders and data-center spending. But the next constraint may be much simpler: there isn't enough high-bandwidth memory capacity to satisfy everything AI companies want to build.
HBM has become critical for modern AI accelerators because training and inference workloads need extremely fast access to large amounts of data. As AI infrastructure expands, memory suppliers are allocating more capacity toward HBM and other
MrFlower_XingChen
#HBMShortageBoostsAlChipPrices
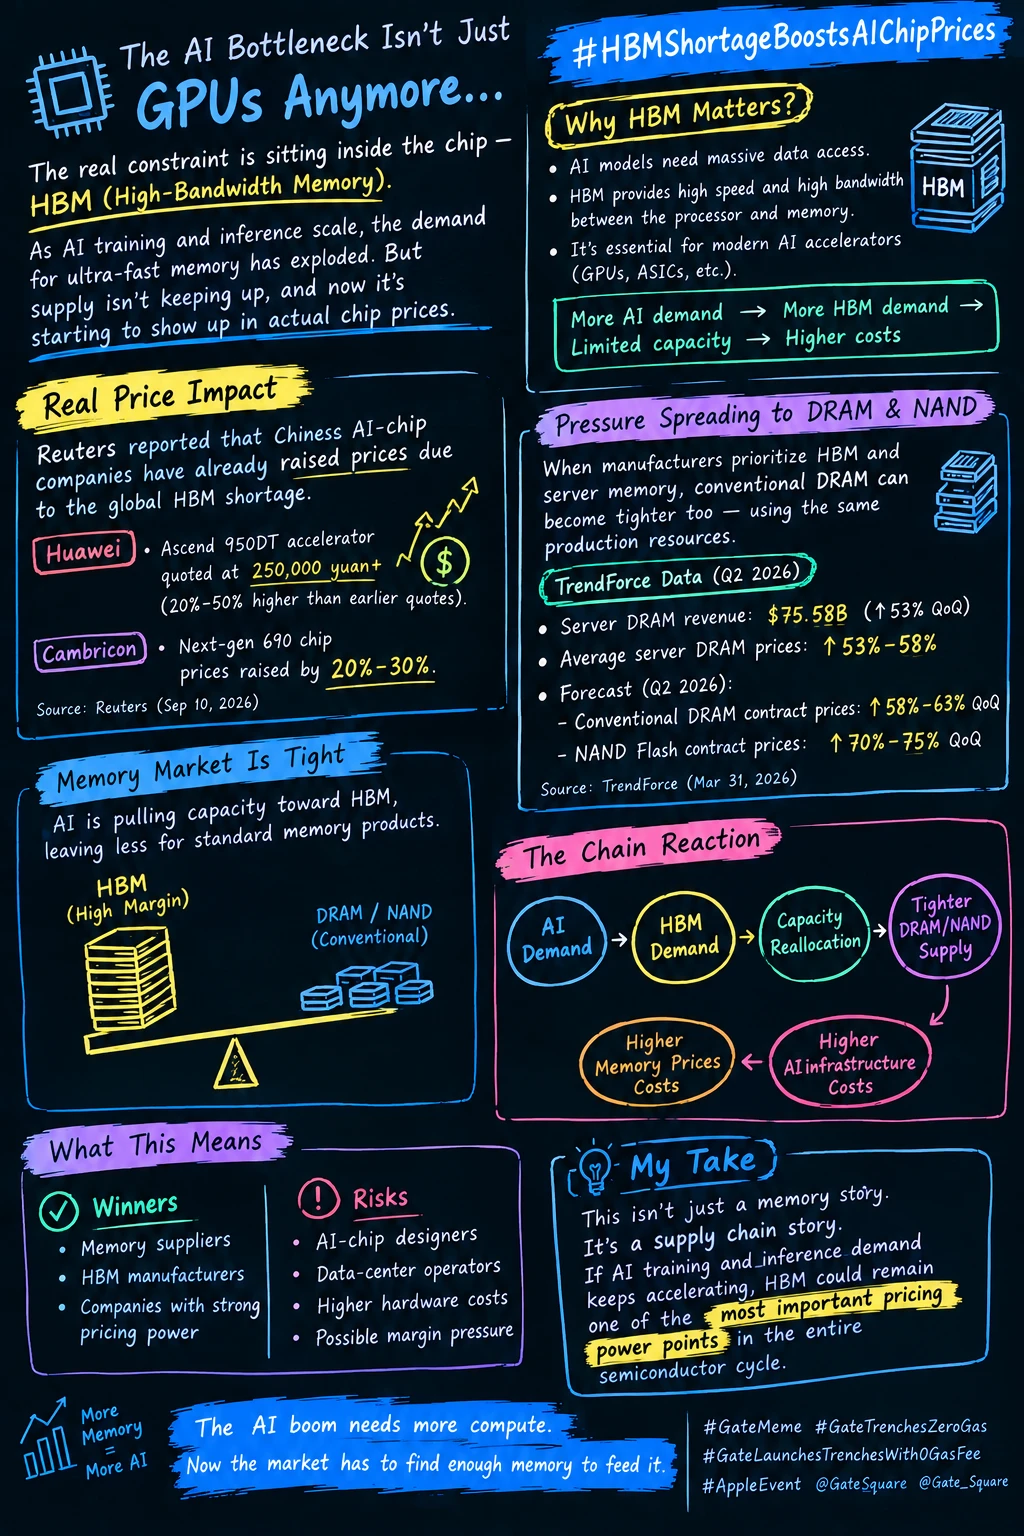
The AI trade has a new bottleneck — and it is sitting inside the chip, not outside the data center.
Everyone has been watching GPU demand, AI server orders and data-center spending. But the next constraint may be much simpler: there isn't enough high-bandwidth memory capacity to satisfy everything AI companies want to build.
HBM has become critical for modern AI accelerators because training and inference workloads need extremely fast access to large amounts of data. As AI infrastructure expands, memory suppliers are allocating more capacity toward HBM and other server-focused products.
And now we are seeing the effect in actual chip pricing.
Reuters reported that Chinese AI-chip companies have raised prices as the global HBM shortage increases production costs. Huawei reportedly raised the quoted price of its upcoming Ascend 950DT accelerator to more than 250,000 yuan, around 20%–50% above earlier quotes. Cambricon also raised prices for its next-generation 690 chip by roughly 20%–30%.
That is an important signal.
The shortage is no longer just a memory-company story.
It is beginning to affect the price of the AI computing hardware itself.
And there is another layer that I think the market should watch closely.
When manufacturers redirect capacity toward HBM and high-end server memory, conventional DRAM can become tighter because the same underlying production resources are competing for capacity.
TrendForce's latest data shows just how serious the pressure has become: in Q2 2026, server DRAM revenue jumped 53% QoQ to $75.58 billion, while average server DRAM prices increased 53%–58%. TrendForce says AI servers are driving demand for high-capacity RDIMMs and DDR5, while supplier inventories remain extremely low.
The pressure is not limited to DRAM either.
Earlier TrendForce forecasts already showed conventional DRAM contract prices expected to rise 58%–63% QoQ and NAND Flash contract prices 70%–75% QoQ in Q2 2026, with suppliers reallocating capacity toward server applications and enterprise SSDs.
So the chain I am watching is becoming very clear:
AI demand → HBM demand → capacity reallocation → tighter DRAM supply → higher memory prices → higher AI infrastructure costs.
That creates an interesting split across the semiconductor sector.
Memory manufacturers can benefit from stronger pricing power, while AI-chip designers and data-center operators may have to absorb higher component costs.
But I wouldn't call this purely bullish.
If memory prices continue climbing, hyperscalers may have to spend even more on infrastructure just to maintain the same expansion plans. That could eventually put pressure on margins or force companies to become more selective about where they deploy new AI capacity.
For me, the biggest takeaway is this:
The AI bottleneck is evolving.
It is no longer only about getting enough GPUs.
It is about getting enough GPUs with enough HBM, advanced packaging and supporting memory infrastructure at an acceptable cost.
If AI training and inference demand keeps accelerating, HBM could remain one of the most important pricing power points in the entire semiconductor supply chain.
And that makes memory pricing something I would watch just as closely as GPU shipments.
#HBMShortageBoostsAIChipPrices
#GateMeme #GateTrenchesZeroGas #AppleEvent @GateSquare @Gate_Square
$SKHYV$NVDA
repost-content-media
SKHYV-0.98%
NVDA-0.09%
DRAM+1.02%
🌕 Celebrate the Mid-Autumn Festival and reunite on Gate Live!
As the moon shines bright, the market is heating up. Come to Gate Live to watch livestreams and earn points, go live and compete on the leaderboard, and win USDT rewards and exclusive Mid-Autumn Festival gifts!
👀 Watch Livestreams
Watch livestreams and participate in interactions to earn points. The first 100 eligible users can randomly receive 1–5 USDT, with additional chances to win an exclusive Gate Mid-Autumn Festival gift box!
🎙️ Go Live
Start a livestream with a Mid-Autumn Festival theme. The TOP 20 will share 5,000 USDT po
MrFlower_XingChen
🌕 Celebrate the Mid-Autumn Festival and reunite on Gate Live!
As the moon shines bright, the market is heating up. Come to Gate Live to watch livestreams and earn points, go live and compete on the leaderboard, and win USDT rewards and exclusive Mid-Autumn Festival gifts!
👀 Watch Livestreams
Watch livestreams and participate in interactions to earn points. The first 100 eligible users can randomly receive 1–5 USDT, with additional chances to win an exclusive Gate Mid-Autumn Festival gift box!
🎙️ Go Live
Start a livestream with a Mid-Autumn Festival theme. The TOP 20 will share 5,000 USDT position experience vouchers, while the TOP 3 will additionally receive exclusive gift boxes. High-quality livestreams can also apply for official Red Packet Rain support!
⏰ Campaign Period: September 14 – September 27
Register now 👉 https://www.gate.com/zh/campaigns/6228
Campaign Announcement 👉 https://www.gate.com/announcements/article/101715
#GateLive #Gate中秋团圆局 #中秋节
repost-content-media
#BrentWTITop$100
WTI above $100 is not just another oil rally.
What caught my attention is why buyers are willing to pay this much for crude right now.
WTI is trading around $102.32 per barrel, up roughly 2.27% today, after gaining about 8% over the past week. The move came after crude had already broken back above $100 for the first time since May.
This time, the market is not waiting for demand to become stronger.
It is pricing the possibility that supply becomes harder to move.
Saudi Arabia temporarily shut its 1,200-kilometre East-West oil pipeline after a drone attack. That route is impo
MrFlower_XingChen
#BrentWTITop$100
WTI above $100 is not just another oil rally.
What caught my attention is why buyers are willing to pay this much for crude right now.
WTI is trading around $102.32 per barrel, up roughly 2.27% today, after gaining about 8% over the past week. The move came after crude had already broken back above $100 for the first time since May.
This time, the market is not waiting for demand to become stronger.
It is pricing the possibility that supply becomes harder to move.
Saudi Arabia temporarily shut its 1,200-kilometre East-West oil pipeline after a drone attack. That route is important because it allows Saudi crude to reach the Red Sea without depending entirely on the Strait of Hormuz. At the same time, fresh attacks on Saudi Arabia and reports of a vessel being hit around Hormuz have increased concerns about the safety of regional energy shipments.
That combination changes the oil equation.
When one transportation route is disrupted, traders can look for another route.
When multiple routes and chokepoints are under pressure at the same time, the market starts demanding a much higher risk premium.
That is exactly what we are seeing now.
And the impact is already reaching consumers.
U.S. diesel prices crossed $6 per gallon for the first time, according to Reuters. Diesel is critical for trucks, shipping, agriculture and heavy equipment, so a prolonged energy shock can spread far beyond the crude market.
This is where WTI becomes a macro story.
Oil above $100 doesn't automatically mean inflation will explode, but if elevated crude and fuel prices persist, the disinflation process becomes harder.
And the timing is not ideal.
U.S. August CPI increased 0.4% month over month, while core CPI rose 0.3%. Markets were already leaning toward a Federal Reserve rate hike, and the combination of hotter inflation and oil above $100 makes the policy decision even more complicated.
So I’m watching WTI differently here.
$100 is no longer just a round number. It is the market's psychological battlefield.
If WTI can stay above $100 while the Middle East supply disruptions continue, buyers could remain aggressive and the recent highs could come back into focus.
But I would not chase every green candle.
Oil is carrying a large geopolitical premium right now. If shipping conditions improve, the Saudi pipeline comes back online, or diplomatic efforts reduce the risk around Hormuz, some of that premium can disappear quickly.
That creates the real trade:
Supply disruption gets worse → WTI stays above $100 → inflation pressure increases.
Supply disruption improves → risk premium unwinds → WTI can correct sharply.
For me, the most important number isn't $110 or $120.
It is $100.
If buyers can turn $100 into genuine support, the bullish structure remains strong.
If WTI repeatedly loses $100, I would start questioning whether the geopolitical premium is fading.
The bigger story is no longer simply “oil is bullish.”
It is whether the world can keep moving enough oil through the routes that remain available.
That answer could influence not only crude prices, but also diesel, inflation, bond yields and central-bank policy.
#GateMeme #GateTrenchesZeroGas #AppleEvent @GateSquare @Gate_Square
repost-content-media
#AMD$2TAI2030
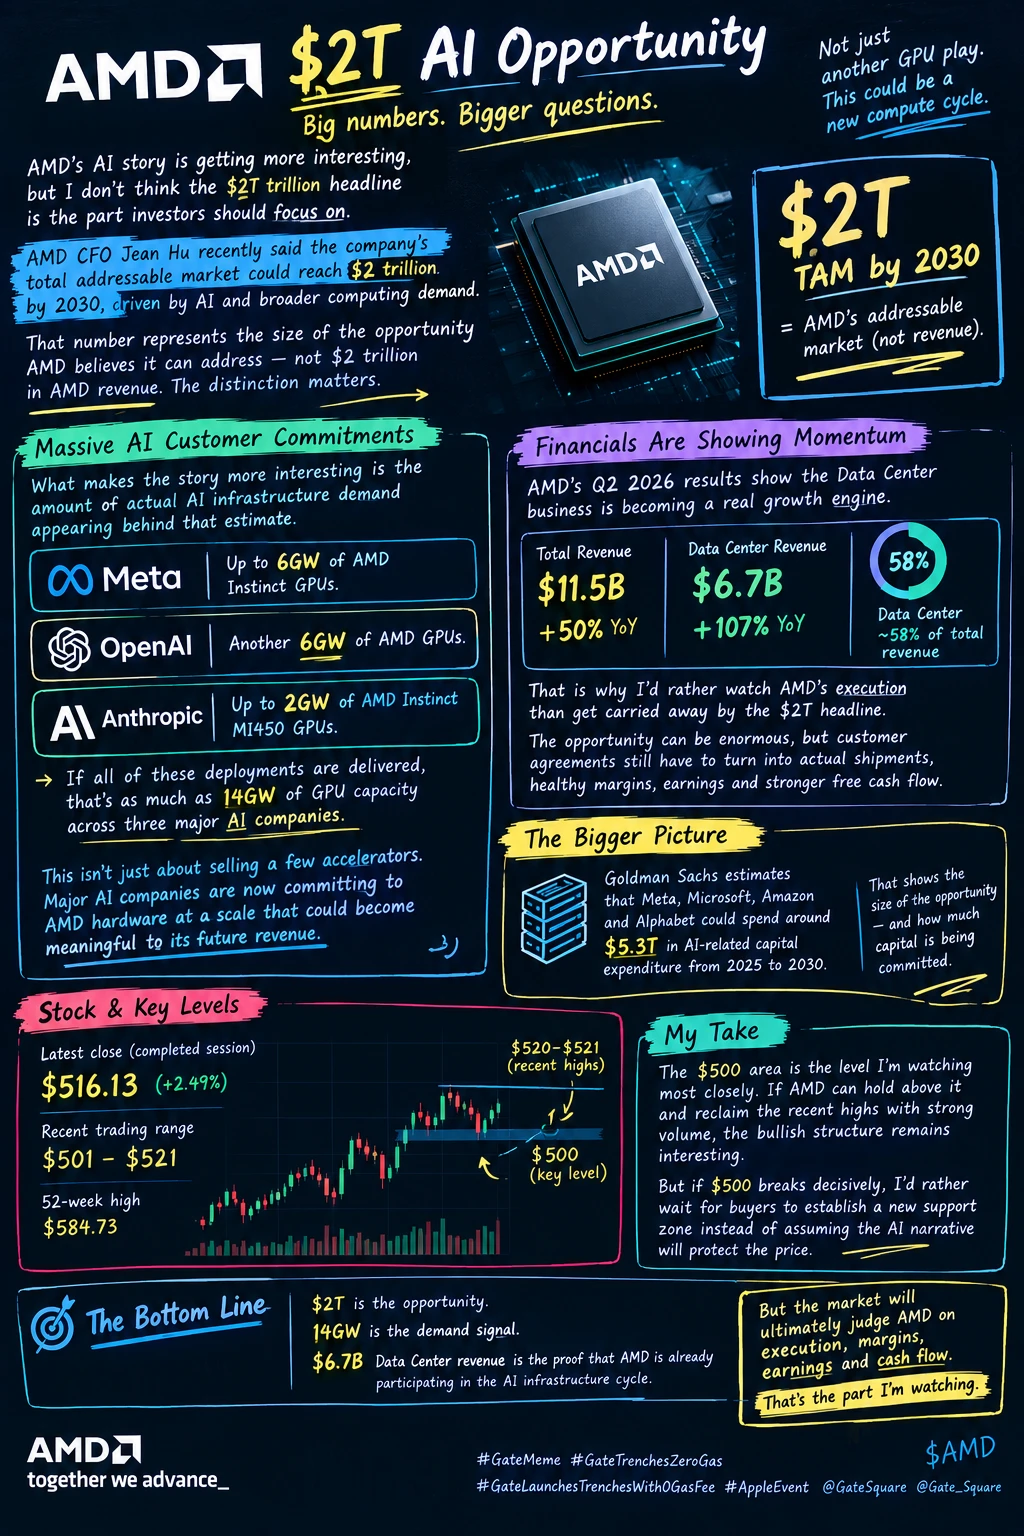
AMD’s AI story is getting more interesting, but I don’t think the $2 trillion headline is the part investors should focus on.
AMD CFO Jean Hu recently said the company’s total addressable market could reach $2 trillion by 2030, driven by AI and broader computing demand. That number represents the size of the opportunity AMD believes it can address — not $2 trillion in AMD revenue. The distinction matters.
What makes the story more interesting is the amount of actual AI infrastructure demand appearing behind that estimate. Meta has agreed to deploy up to 6GW of AMD Instinct GPUs,
MrFlower_XingChen
#AMD$2TAI2030
AMD’s AI story is getting more interesting, but I don’t think the $2 trillion headline is the part investors should focus on.
AMD CFO Jean Hu recently said the company’s total addressable market could reach $2 trillion by 2030, driven by AI and broader computing demand. That number represents the size of the opportunity AMD believes it can address — not $2 trillion in AMD revenue. The distinction matters.
What makes the story more interesting is the amount of actual AI infrastructure demand appearing behind that estimate. Meta has agreed to deploy up to 6GW of AMD Instinct GPUs, while OpenAI has a separate agreement for another 6GW. Anthropic has also agreed to deploy up to 2GW of AMD Instinct MI450 GPUs. If all of these announced deployments are delivered, that represents as much as 14GW of GPU capacity across three major AI companies.
For me, this is the bigger signal. AMD is not simply trying to sell a few AI accelerators into the market. Major AI companies are now committing to AMD hardware at a scale that can potentially become meaningful to the company’s future revenue.
And AMD’s existing numbers are already showing that the Data Center business is becoming much more important. In Q2 2026, AMD generated $11.5 billion in revenue, up 50% year over year, while Data Center revenue reached $6.7 billion, up 107% YoY. Data Center alone accounted for roughly 58% of quarterly revenue.
That is why I would rather watch AMD’s execution than get carried away by the $2T headline. The opportunity can be enormous, but customer agreements still have to turn into actual shipments. Those shipments then need to produce healthy margins, earnings and eventually stronger free cash flow.
There is another side to this AI boom that deserves attention. Goldman Sachs estimates that Meta, Microsoft, Amazon and Alphabet could collectively spend around $5.3 trillion on capital expenditure between 2025 and 2030. That shows how large the AI infrastructure cycle could become, but it also means companies are committing extraordinary amounts of capital. Eventually, investors will want to see strong returns from that spending.
Now I’m looking at the stock itself. AMD’s latest completed close was around $516.13, with the recent session trading roughly between $501 and $521. After such a major rerating, I wouldn’t chase the stock simply because another AI partnership gets announced.
The $500 area is the level I’m watching most closely. If AMD can continue holding above it and reclaim the recent highs with strong volume, the bullish structure remains interesting. But if $500 breaks decisively, I would rather wait for buyers to establish a new support zone instead of assuming the AI narrative will protect the price.
My view is simple: $2T is the opportunity, 14GW is the demand signal, and $6.7B of Data Center revenue is the proof that AMD is already participating in the AI infrastructure cycle.
But the market will ultimately judge AMD on something much harder to manufacture than headlines — execution, margins, earnings and cash flow.
That’s the part I’m watching.
#GateMeme #GateTrenchesZeroGas #AppleEvent @GateSquare @Gate_Square
$AMD
repost-content-media
AMD+2.54%
CRYPTO MARKET OVERVIEW
live-replay-cover
362 views09-14 04:35
01:21:54
BTC UPDATE
live-replay-cover
270 views09-14 03:31
00:52:23
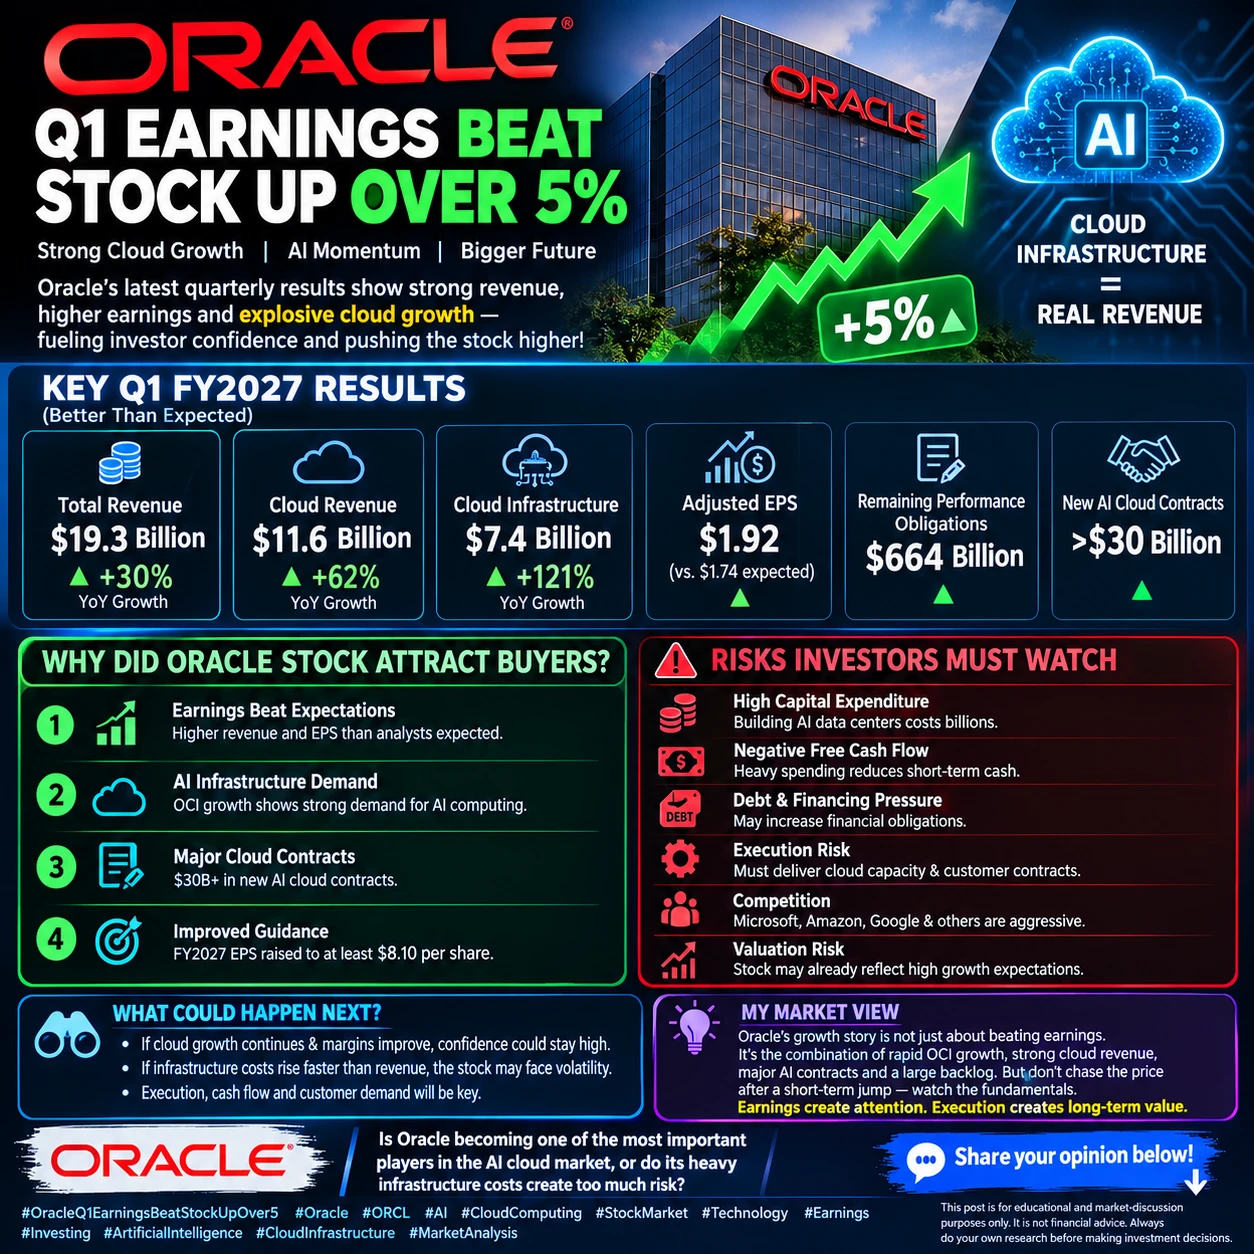
#OracleQ1EarningsBeatStockUpOver5 📈
Oracle’s AI Cloud Growth Sends a Strong Message to the Stock Market
The latest quarterly results from Oracle Corporation ($ORCL) have attracted significant attention from investors as the company continues to expand its position in cloud infrastructure and artificial intelligence. Strong earnings, higher revenue, and rapid growth in cloud services have helped improve market sentiment around Oracle’s long-term business strategy.
Oracle’s performance highlights an important trend in the technology sector: AI is no longer only a future opportunity. It is becom
post-image
MARKET OVERVIEW
live-replay-cover
181 views09-14 02:47
00:31:57
MARKET OVERVIEW
live-replay-cover
178 views09-14 01:28
00:49:37
BTC HPDATE
live-replay-cover
776 views09-13 20:21
02:29:26
CRYPTO MARKET
live-replay-cover
77 views09-13 17:07
00:30:28
BTC MARKET OVERVIEW
live-replay-cover
197 views09-13 16:22
00:32:50
btc market overview
live-replay-cover
391 views09-13 15:27
00:34:17
crypto market update
live-replay-cover
465 views09-13 14:41
00:34:50