Square
Following
Hot
News
Profile

YamahaBlue

vip
Active for: 2.9y
Peak Tier 5
"Welcome to the world of crypto! Here we will learn, grow and explore opportunities together. Let's get started!"
250
Following
267
Followers
19.2k
Liked
Hot Token Rotation Season Phase 4: New and Returning Friends Get a 1.5× Trading Volume Boost and Compete for 120,000 USDT https://www.gate.com/campaigns/6395?ref=AwBFBl5c&ref_type=132&utm_cmp=lDOVEArp
post-image
  • 4
I'm trading on Gate, a top-tier exchange with a 13-year track record. Come join me and dive into the hottest events right now! https://www.gate.com/campaigns/6518?ref=AwBFBl5c&ref_type=132
post-image
  • 3
#BTCBreaksThrough$86,000
🚀 Bitcoin Breaks Through $86,000!
BTC is back above the $86K level, showing strong momentum as buyers regain control. The next key test is the $87K area. 👀🔥
#Bitcoin #BTC #Crypto
$BTC $GT $ETH
FenerliBaba
#BTCBreaksThrough$86,000
🚀 Bitcoin Breaks Through $86,000!
BTC is back above the $86K level, showing strong momentum as buyers regain control. The next key test is the $87K area. 👀🔥
#Bitcoin #BTC #Crypto
$BTC $GT $ETH
repost-content-media
BTC+1.10%
GT-0.08%
ETH+0.84%
  • 1
📢 Reward Announcement | Gate Square New Creator Growth Plan
September weekly rewards (9.11–9.27) have been distributed. Congratulations to the winning creators! 🎉
Starting now, win up to 100 USDT every week 👉 https://www.gate.com/campaigns/6244
🎁 Generous rewards await
① Weekly Points Rewards: Earn points by posting, with up to 100 USDT
② Weekly TOP 10: Up to 300 USDT + VIP+1 trial card + creator benefits
③ Monthly TOP 3: Compete for the monthly leaderboard and enjoy 500 USDT + GT worth 30 USDT exclusively
🔥 Share your views with #每周来晒 and #市场回调如何布局 this week to win rewards!
👉 https://
GateSquare
📢 Reward Announcement | Gate Square New Creator Growth Plan
September weekly rewards (9.11–9.27) have been distributed. Congratulations to the winning creators! 🎉
Starting now, win up to 100 USDT every week 👉 https://www.gate.com/campaigns/6244
🎁 Generous rewards await
① Weekly Points Rewards: Earn points by posting, with up to 100 USDT
② Weekly TOP 10: Up to 300 USDT + VIP+1 trial card + creator benefits
③ Monthly TOP 3: Compete for the monthly leaderboard and enjoy 500 USDT + GT worth 30 USDT exclusively
Reward details:
https://docs.google.com/spreadsheets/d/1u4TWKlxBcKkeZGUvQXkMSMYifvYUdaCfON5oZE86q40/edit?hl=zh-CN&gid=0#gid=0
🔥 Share your views with #每周来晒 and #市场回调如何布局 this week to win rewards!
👉 https://www.gate.com/post
repost-content-media
GT-0.08%
  • 2
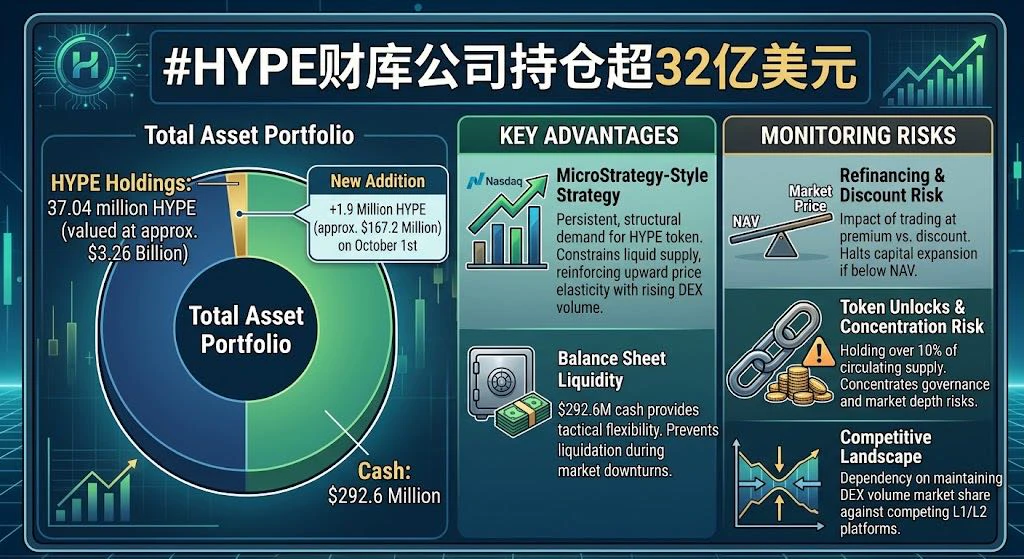
#HYPE财库公司持仓超32亿美元
The recent acquisition of 1.9 million HYPE tokens for approximately $167.2 million—bringing total assets to 37 million HYPE (valued at roughly $3.26 billion ) and $292.6 million in cash —serves as a textbook strategic move, yet it also introduces unique structural dynamics:
My take: While this signals strong conviction, it also entails a concentration risk.
The latest treasury update from Hyperliquid Strategies indicates total HYPE holdings of 37.04 million tokens—valued at approximately $3.26 billion—following the addition of roughly 1.95 million HYPE on October 1st.
1.
ybaser
#HYPE财库公司持仓超32亿美元
The recent acquisition of 1.9 million HYPE tokens for approximately $167.2 million—bringing total assets to 37 million HYPE (valued at roughly $3.26 billion ) and $292.6 million in cash —serves as a textbook strategic move, yet it also introduces unique structural dynamics:
My take: While this signals strong conviction, it also entails a concentration risk.
The latest treasury update from Hyperliquid Strategies indicates total HYPE holdings of 37.04 million tokens—valued at approximately $3.26 billion—following the addition of roughly 1.95 million HYPE on October 1st.
1. A MicroStrategy-Style Strategy for Perpetual DEXs
Hyperliquid Strategies operates as a dedicated treasury vehicle designed to accumulate the protocol's native token supply. By effectively converting public equity access (Nasdaq) into physical token purchases, they generate persistent, structural demand for HYPE. For a high-volume perpetual DEX like Hyperliquid, the permanent locking of approximately 37 million tokens effectively constrains the liquid circulating supply, thereby reinforcing upward price elasticity as trading volumes rise.
2. Balance Sheet Liquidity and Operational Scope
Holding $292.6 million in cash alongside the HYPE tokens provides tactical flexibility. They are not forced to fully liquidate tokens to fund operations or repay debt during market downturns; this prevents an uncontrolled sell-off in the event of high token price volatility.
3. Key Risks to Monitor
*Refinancing and Discount Risk: If the asset trades at a premium to its Net Asset Value (NAV), issuing shares to purchase additional HYPE is a value-accretive move. However, if market sentiment weakens and the asset trades below its NAV (at a discount), capital expansion halts, and this reflexive cycle reverses.
* Token Unlocks and Circulating Supply Concentration: While removing 1.9 million tokens from the market alleviates short-term selling pressure, holding more than 10% of the circulating market cap in a single treasury vehicle concentrates governance and market depth risks on one balance sheet.
This strengthens HYPE’s position as an institutional-grade asset; however, the asset's performance will remain heavily dependent on whether Hyperliquid can maintain its DEX volume market share against competing L1/L2 perpetual trading platforms.
$HYPE ‌
repost-content-media
HYPE+2.21%
  • 3
The most important number in global finance right now is not the Federal Reserve's policy rate or the yield on the U.S. 10-year Treasury. It is the yield on Japan's 30-year government bond, which climbed to a record 4.235% on Monday, the highest level since the country first sold that maturity in 1999. Japan is the world's largest creditor nation, the anchor of the global bond market, and the source of the cheapest funding that international investors have relied on for decades. When its long-end borrowing costs move this quickly, the effects do not stay in Tokyo.
To understand why this matter
User_any
The most important number in global finance right now is not the Federal Reserve's policy rate or the yield on the U.S. 10-year Treasury. It is the yield on Japan's 30-year government bond, which climbed to a record 4.235% on Monday, the highest level since the country first sold that maturity in 1999. Japan is the world's largest creditor nation, the anchor of the global bond market, and the source of the cheapest funding that international investors have relied on for decades. When its long-end borrowing costs move this quickly, the effects do not stay in Tokyo.
To understand why this matters to you, you have to start with the carry trade. For years, investors borrowed yen at near-zero interest rates and used those funds to buy higher-yielding assets in the United States, Europe, and emerging markets. This was not a niche strategy. It was a foundational structure of global finance, one that supported everything from U.S. corporate credit to emerging market debt to risk assets of every kind. Cross-border yen borrowing reached a record 360 trillion yen, or roughly $2.34 trillion, as of March. That is the scale of the funding channel that is now being tested.
The mechanism works until it doesn't. When Japanese yields rise, the cost of servicing yen-denominated loans increases, which squeezes the margin on every position funded with borrowed yen. If the yen also strengthens, the cost of repaying those loans rises further. The result is a mechanical unwind: investors sell their global holdings to repay yen debt, and that selling pressure spreads across bonds, equities, and currencies simultaneously. This is not hypothetical. In August 2024, a similar dynamic produced a one-day 12.4% drop in Japan's Nikkei index and cascading sell-offs in global markets.
The bond market is where this process becomes visible first. Japan's 30-year yield has risen from around 3.15% before Takaichi became the ruling party leader to 4.235% now, a move of more than a full percentage point. The 10-year yield is hovering near 2.8%, approaching the 3% level that some analysts see as a trigger for a new wave of selling. The Bank of Japan has explicitly linked part of this rise to bond issuance by AI-related companies, which it describes as a "big positive demand shock" that is pushing long-term rates higher. But the more important driver is fiscal. Prime Minister Sanae Takaichi's expansionary spending plans have raised concerns about the sustainability of Japan's debt burden, and the bond market is repricing that risk in real time.
The yen's role in all of this is counterintuitive. Normally, higher domestic yields would strengthen a currency because they attract capital. That is not happening in Japan. The yen remains weak, trading near 157 per dollar, even after the BOJ raised rates and the government intervened in the foreign exchange market at the end of July. The reason is that the fiscal risk premium is offsetting the yield advantage. When investors doubt a government's ability to service its debt, higher yields become a warning sign rather than an attraction. The yen is caught between two forces: higher rates that should support it, and fiscal concerns that undermine it.
The implications for global investment strategies are already visible in the flow data. Japanese institutions have been the largest foreign holders of U.S. Treasuries, and their portfolio investments abroad amount to roughly $4.8 trillion. As domestic yields rise, the incentive to hold that capital overseas diminishes. Japanese investors can now earn 4% or more on 30-year government bonds at home, a return that was unimaginable a few years ago. That reduces demand for U.S. and European debt, which pushes global yields higher. The first quarter of 2026 saw Japan sell $29.6 billion in U.S. Treasuries, a sign that this repatriation is already underway.
The BOJ's policy path is the other variable that matters. The market is pricing roughly 101 basis points of rate hikes from the BOJ by September 2027, compared with 64 basis points from the Federal Reserve. That gap is closing, and as it closes, the yen carry trade becomes less profitable. The "fast money" carry trade has already been unwound, according to analysts, but the slower institutional flows are still adjusting. The risk is that this adjustment does not stay orderly. If Japanese yields continue to climb and the yen strengthens sharply, the unwind could accelerate and spread beyond Japan's borders.
For anyone managing a portfolio, the lesson is that Japan is no longer a source of free funding. It is becoming a competitor for global capital. The era of permanently cheap Japanese money, which kept global bond yields lower than domestic fundamentals alone would have justified, is ending. That does not mean every asset will reprice overnight. It means the cost of capital for the entire system is rising, and the adjustment will show up in bond yields, equity valuations, and currency markets over the coming months. Watch the 10-year JGB yield and the yen. Those two numbers will tell you more about the direction of global liquidity than any single U.S. data release.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
#ShareWeekly #PlanYourTradesThisWeek

repost-content-media
  • 3
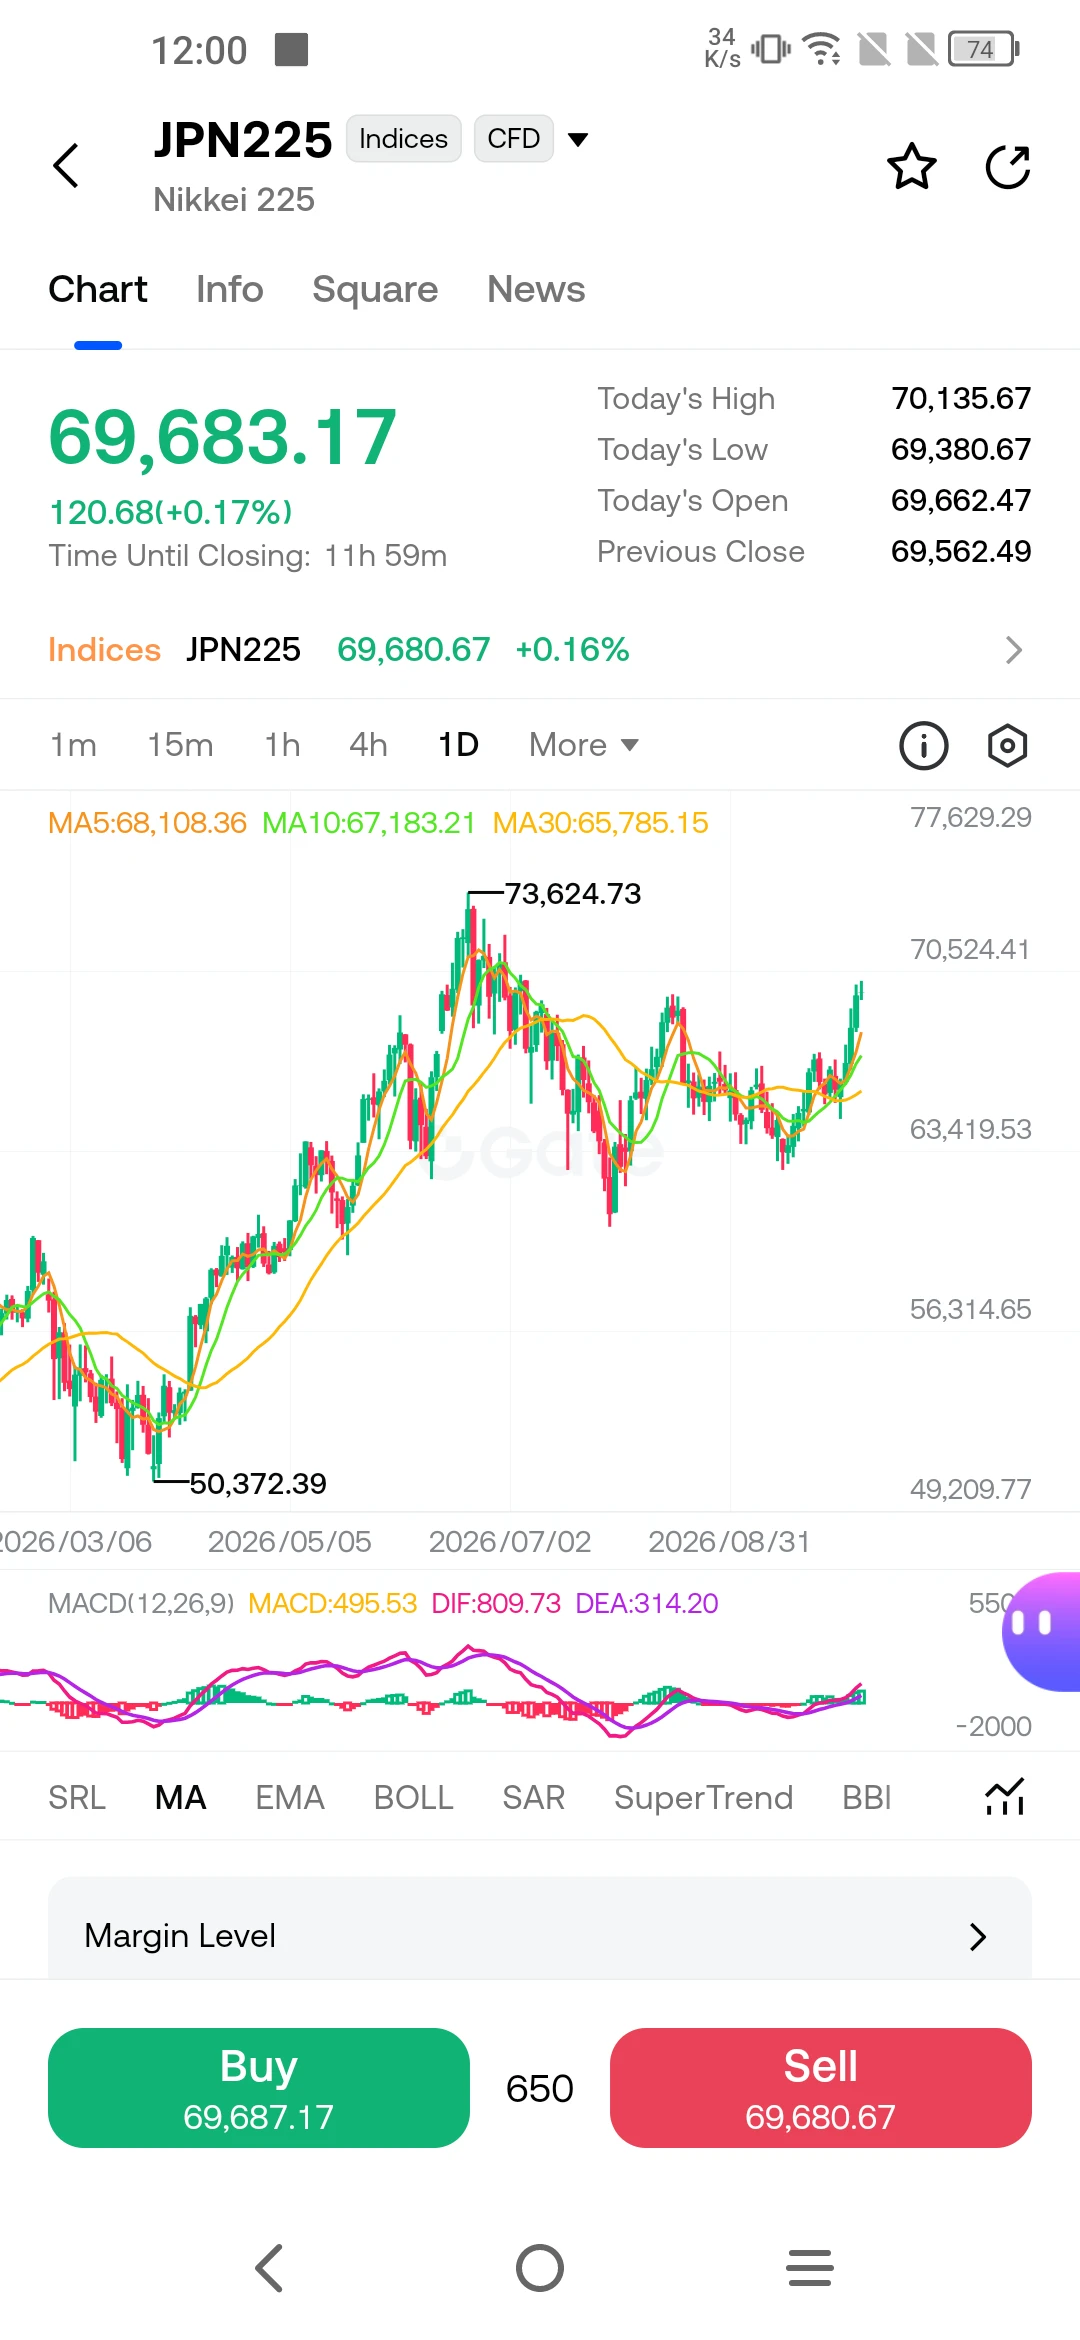
$JPN225 Japan's 30-year government bond yield climbed to a record 4.235% on Monday, the highest level since the country first sold 30-year debt in 1999. The yield broke above 4% for the first time in May and has not looked back since. The 10-year yield is hovering near 2.8%, a level last seen in 1996. This is not a gradual repricing. It is a structural shift in how the world's largest creditor nation finances itself, and it is happening while the Bank of Japan is still officially committed to a policy rate of just 1%.
The immediate trigger for Monday's move was anticipation. Prime Minister Sa
User_any
$JPN225 Japan's 30-year government bond yield climbed to a record 4.235% on Monday, the highest level since the country first sold 30-year debt in 1999. The yield broke above 4% for the first time in May and has not looked back since. The 10-year yield is hovering near 2.8%, a level last seen in 1996. This is not a gradual repricing. It is a structural shift in how the world's largest creditor nation finances itself, and it is happening while the Bank of Japan is still officially committed to a policy rate of just 1%.
The immediate trigger for Monday's move was anticipation. Prime Minister Sanae Takaichi was scheduled to deliver her policy speech to parliament, and the market was waiting to hear how she would reconcile two competing priorities: her signature "responsible, proactive fiscal policy" and the need to maintain fiscal sustainability. The record yield was the bond market's way of saying it had not yet been convinced. Takaichi's speech, delivered Monday afternoon, repeated her commitment to passing a consumption tax cut to address rising prices while insisting that she would not postpone necessary reforms. The market heard the first part clearly. The second part is what it is still waiting to see delivered.
What makes this moment different from previous episodes of Japanese bond stress is that the Bank of Japan has explicitly linked the rise in long-term yields to the global AI boom. Deputy Governor Shinichi Uchida said on Monday that while AI has boosted stock prices and made financial conditions easier, the massive wave of bond issuance by AI-related firms has put upward pressure on long-term interest rates. This is a significant admission. The BOJ is acknowledging that a force outside its control is driving domestic borrowing costs higher. Uchida also warned that if AI profits fail to materialise, the market could face a correction. He suggested that robust AI demand might alter Japan's natural interest rate, which is the theoretical rate at which the economy grows steadily without inflation accelerating.
The currency is where the tension between monetary policy and fiscal reality becomes most visible. USD/JPY is trading at 157.86, holding above the 157 level even after Japanese authorities intervened in the foreign exchange market at the end of July. The intervention was intended to support the yen, but it has not reversed the trend. The reason is the yield differential. Japan's policy rate is 1%, while the U.S. federal funds rate sits between 3.75% and 4%, leaving a gap of roughly 275 basis points. That gap is the primary driver of the yen's weakness, and intervention cannot close it. GBP/JPY is trading at 208.85, and EUR/JPY at 176.94, both reflecting the same dynamic. When the yield gap is this wide, capital flows toward higher-yielding currencies, and the yen remains under pressure regardless of official efforts.
The Nikkei 225 is trading at 69,683, holding above its key moving averages, which sit between 65,785 and 68,108. The index has been resilient despite the bond selloff, partly because the AI-related stocks that are driving global equity markets are also represented in the Japanese market. But the divergence between the equity market's optimism and the bond market's caution is worth noting. Equities are pricing in continued AI-driven growth. Bonds are pricing in the cost of financing that growth. When the two diverge this sharply, one of them has to adjust.
The BOJ's own projections illustrate the difficulty of the path ahead. In its April outlook, the central bank revised its core CPI forecast for fiscal 2026 sharply upward, from 1.9% to 2.8%, while cutting its real GDP growth forecast from 1.0% to 0.5%. That combination, higher inflation and slower growth, is the definition of stagflation. The BOJ's new inflation gauge, which excludes one-off factors like education and energy subsidies, hit 2.8% in April, well above the 2% target and faster than the government's benchmark measure. The central bank is caught between the need to normalize policy to control inflation and the risk that further rate hikes will choke off an already weak recovery.
What should you watch from here? The first variable is Takaichi's budget. If she delivers a credible fiscal consolidation plan alongside the tax cut, the long-end of the curve could stabilize. If the market perceives the fiscal path as unsustainable, the 30-year yield could push toward 4.5% or higher. The second variable is the AI bond issuance cycle. Uchida's warning about a correction is not theoretical. If AI-related companies continue to flood the bond market with new supply, long-term yields will remain under pressure regardless of what the BOJ does. The third variable is the yen. A sustained break above 160 would increase the pressure on the BOJ to hike again, but each hike risks further destabilizing the bond market. The central bank is in a difficult position, and the market knows it. The next few weeks will show whether Takaichi's fiscal promises can convince investors that Japan can grow its way out of its debt burden, or whether the bond market will force the issue first.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$EURJPY ‌ $USDJPY ‌#ShareWeekly #PlanYourTradesThisWeek
repost-content-media
JPN225+0.27%
USDJPY+0.27%
GBPJPY+0.05%
EURJPY-0.11%
  • 2
$BTC #BTCBreaksThrough$86,000 👀
Bitcoin is trading near $86,435, up 1.60% over the past 24 hours, and the reason it is holding this level has almost nothing to do with crypto itself. The move that carried it from $85,038 to an intraday high of $86,989 was driven by a single macro event: the September U.S. jobs report. The economy added just 29,000 jobs last month, far below the roughly 84,000 economists had expected, and the unemployment rate ticked up to 4.2%. That was enough to knock the implied probability of an October Fed rate hike from roughly 70% a week ago down to 18%, according to C
User_any
$BTC #BTCBreaksThrough$86,000 👀
Bitcoin is trading near $86,435, up 1.60% over the past 24 hours, and the reason it is holding this level has almost nothing to do with crypto itself. The move that carried it from $85,038 to an intraday high of $86,989 was driven by a single macro event: the September U.S. jobs report. The economy added just 29,000 jobs last month, far below the roughly 84,000 economists had expected, and the unemployment rate ticked up to 4.2%. That was enough to knock the implied probability of an October Fed rate hike from roughly 70% a week ago down to 18%, according to CME's FedWatch tool and prediction market Kalshi. When the odds of tighter policy fall, the opportunity cost of holding assets that do not pay a yield falls with them. That is the mechanism, and it explains why Bitcoin moved without any crypto-specific catalyst.
The geopolitical backdrop is reinforcing the same impulse, but through a different channel. At least three tankers have been struck by unidentified projectiles while passing through the Strait of Hormuz since October 1, even as the G7 released 100 million barrels from strategic reserves to calm the market. Brent crude is holding near $100, and the risk of a broader supply disruption keeps a bid under haven assets. Gold strengthened in tandem with Bitcoin after the jobs data, which tells you that both assets are being treated as hedges against the same set of risks: slower growth, sticky inflation, and an unresolved conflict that could push energy prices higher at any moment.
What makes this moment interesting is that the money is returning through two separate channels at once. On the traditional side, U.S. spot Bitcoin ETFs recorded a third consecutive week of net inflows, attracting $241.1 million last week and bringing cumulative net inflows to $57.8 billion. The funds added $102.7 million on the first trading day of October alone, following a $148.7 million outflow the day before. BlackRock's IBIT led the inflows with $196 million on that day. On the on-chain side, CryptoQuant analyst Darkfost noted that whale addresses moving more than $1 million in stablecoins to exchanges have increased their 30-day cumulative deposits from $21.7 billion to $30.5 billion, a rise of more than 40% in just over a month. Stablecoin deposits to exchanges are typically the precursor to buying, not selling. When both traditional and on-chain money are moving in the same direction, it provides medium-term bid support even if the near-term price action stays choppy.
The regulatory environment is also shifting in a way that broadens access. On October 2, the SEC approved a Cboe BZX rule change allowing six new futures-based ETPs that target three times the daily performance of Bitcoin, Ether, gold, silver, crude oil, and natural gas. The products come from Volatility Shares' VS Trust, and they will use regulated CME futures contracts rather than holding the underlying assets directly. Bloomberg ETF analyst Eric Balchunas called the approval a "big win" for the issuer, noting that less than three years ago the SEC was still fighting over a plain-vanilla spot Bitcoin ETF. Trading cannot begin until the separate S-1 registration statements take effect, so the near-term spot impact is limited. But the direction of travel is clear: the suite of compliant Bitcoin trading tools is expanding, and that expansion brings institutional access closer to parity with traditional assets.
The technical picture is a market compressing before a decision. Bitcoin has spent the past week pinned inside a range between roughly $84,924 and $86,999, and the short-term moving average stack is layered beneath the price: the 7-day at $84,877, the 20-day at $83,411, and the 50-day at $79,512. That structure is bullish, but the immediate resistance at $87,142 is a real wall, not a line drawn on a chart. The MACD histogram has flatlined at zero, which means bullish and bearish momentum are in exact equilibrium, and the RSI at 66.71 is climbing toward a zone where pullbacks become more common. The ATR of $1,986 tells you this market can move nearly two thousand dollars in a single session, so the compression will resolve, and it will resolve sharply. Above $87,142, the next target is $88,108. Below the range, the first support cluster sits at $82,865 to $84,200, with deeper support at $77,100 to $80,200.
The derivatives data adds a layer of nuance that is worth understanding. The global long/short ratio is nearly dead even at 0.9936, which means the crowd has no conviction. But the top trader cohort is 52.3% net long, and the taker buy/sell ratio has spiked to 1.4122, meaning aggressive market orders are hitting the ask at a ratio of nearly 1.4-to-1. Smart money is quietly positioning for upside while retail sits on the fence. That divergence does not guarantee a breakout, but it tells you who is doing the buying and who is waiting.
The risks deserve equal weight. The Fed's minutes from the September meeting are due this week, along with U.S. services data and consumer inflation expectations. A hawkish tone from policymakers would lift Treasury yields and the dollar, which would pressure risk assets including Bitcoin. The December FOMC meeting remains live, with FedWatch showing odds above 75% for a hike by year-end. And the inflation side of the mandate is not resolved: core PCE came in at 3.0% for August, which is cooler than expected but still well above the Fed's 2% target. If inflation data surprises to the upside in the coming weeks, the dovish repricing that has supported Bitcoin could reverse quickly.
The net read is that Bitcoin is being carried by macro forces rather than by its own narrative. The weak jobs report removed October from the hike calendar, the ETF inflows and whale deposits show that both institutional and on-chain money are returning, and the SEC's approval of leveraged products signals that the regulatory environment is broadening. But the price is still trapped below $87,000, and the data calendar over the next two weeks will determine whether that ceiling breaks or holds. Watch the Fed minutes and the inflation expectations data for the next directional signal. Bitcoin's ability to close above $87,142 would confirm the breakout; a failure to hold $84,000 would shift focus back to the $82,000 support zone.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC ‌#ShareWeekly #PlanYourTradesThisWeek
repost-content-media
  • 3
Crypto market volatility is picking up, and the data from the past week shows it clearly. Bitcoin started October with a spike above $87,200 after the softer-than-expected jobs report, then reversed sharply to below $84,000 within hours. In that window, crypto liquidations jumped past $570 million, with longs accounting for 99% of the losses in the final hour alone. By October 2, shorts lost another $110 million in a ten-minute burst. By October 5, bearish traders saw $113 million in short positions forcibly closed over a 24-hour period. Both sides of the trade are getting punished. That is wh
User_any
Crypto market volatility is picking up, and the data from the past week shows it clearly. Bitcoin started October with a spike above $87,200 after the softer-than-expected jobs report, then reversed sharply to below $84,000 within hours. In that window, crypto liquidations jumped past $570 million, with longs accounting for 99% of the losses in the final hour alone. By October 2, shorts lost another $110 million in a ten-minute burst. By October 5, bearish traders saw $113 million in short positions forcibly closed over a 24-hour period. Both sides of the trade are getting punished. That is what rising volatility looks like, and it is the environment you are currently operating in.
Bitcoin is trading near $86,000 after reclaiming that handle in Asian trade, but it has not managed to break $87,000, which remains the key test of momentum. The range that has defined the past two weeks sits between roughly $82,997 and $85,649, and the next move out of that band will set the tone for the rest of October. The $84,433 level is the near-term support that needs to hold for the constructive structure to remain intact, while $87,360 is the resistance that would confirm a breakout. Historical data shows Bitcoin has risen in 10 of the past 15 Octobers, with a median return of about 11.2%, but that statistic is a base rate, not a guarantee. Last year's October followed the same pattern until a flash crash erased the gains.
The ETF flow data adds another layer to the picture. US spot Bitcoin ETFs flipped back to net inflows on the first trading day of October, attracting $102.7 million after the prior session's $148.7 million outflow. Over the first two days of the month, the funds took in $134.4 million in net inflows. Cumulative net inflows now stand at $57.8 billion. That is a meaningful bid, but it is not enough on its own to push price through resistance. The institutional demand is steady, but the market is still waiting for a catalyst strong enough to absorb the selling pressure that appears every time Bitcoin approaches $87,000.
Tokenized US stocks are emerging as one of the more interesting developments in this environment. Trading volume in tokenized traditional equities crossed $54 billion in June 2026, up from $831 million in July 2025. SpaceX alone contributed $36 billion of that volume. Micron Technology saw its tokenized volume rise 17-fold from $736 million in April to $13.16 billion in May. On Solana, spot DEXs recorded $5.8 billion in tokenized stock volume in the second quarter, a 114% increase from the prior quarter. Through mid-September, Raydium processed about $2.3 billion in tokenized stock volume during the third quarter. This is a market that is growing quickly, and it is giving crypto traders access to traditional equity exposure without leaving the on-chain ecosystem. The appeal is straightforward: the same infrastructure that settles crypto trades can now settle exposure to Apple, Nvidia, or Tesla, and the liquidity is deepening as more platforms integrate these products.
The risk management implications of this environment are worth stating plainly. When both longs and shorts are getting liquidated in the same week, leverage is the common denominator. The $570 million in liquidations on October 2 and the $113 million in short squeezes on October 5 were not driven by changes in the fundamental outlook. They were driven by positioning. The market moved against the crowded trade in both directions, and the traders who got hurt were the ones holding size they could not afford to lose. Position sizing matters more than direction in a market like this. A correct call with too much leverage produces the same result as a wrong call.
Asset selection is the second variable. Bitcoin's dominance has held near 58% to 59% through the recent volatility, which tells you that capital is concentrating in the largest and most liquid asset rather than rotating into altcoins. That pattern is consistent with a risk-off posture inside the crypto market. When liquidity tightens and volatility rises, the largest assets tend to hold up better because they have deeper order books and more institutional participation. Altcoins, by contrast, face the heaviest pressure when capital is scarce. The rotation into tokenized equities is a variation on the same theme: traders are looking for exposure to assets outside the crypto-native universe, but they are doing it through platforms that settle on-chain.
The global data calendar is the third variable, and it is dense over the next two weeks. September CPI and PCE will both land before the October 28 FOMC meeting. The market has already priced a pause at that meeting, with the probability of a hike falling below 15% after the weak jobs report. But the inflation prints will determine whether that pause holds or whether the Fed feels compelled to act again. The October jobs report on November 6 will provide the next read on whether September's weakness was an anomaly or the start of a trend. Every one of these releases carries the potential to move crypto markets, because the entire asset class is currently trading on rate expectations rather than on its own fundamentals.
The net read is that the market is in a phase where patience and discipline matter more than conviction. The range between $82,997 and $87,360 is well defined, and the outcome of that range will determine the direction of the next move. ETF inflows are positive but not decisive. Tokenized equities are growing but not yet large enough to absorb macro-driven selling. The data calendar is heavy, and the Fed's next move is still uncertain. In this environment, staying on the sidelines is a legitimate position, and watching the majors alongside the tokenized equity market gives you two windows into where capital is flowing. The traders who survive volatile markets are not the ones who predict every move. They are the ones who manage their exposure so that a single move cannot take them out of the game.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
#ShareWeekly #PlanYourTradesThisWeek
$BTC $XRP $LINK
repost-content-media
  • 3
I'm trading on Gate, a top-tier exchange with a 13-year track record. Come join me and dive into the hottest events right now! https://www.gate.com/campaigns/6521?ch=8232&ref=AwBFBl5c&ref_type=132
post-image
  • 2
#USSeptemberJobs29K 🧐
The US economy added just 29,000 jobs in September, a fraction of the roughly 90,000 economists had expected and a sharp slowdown from the downwardly revised 133,000 gain in August. The unemployment rate ticked up to 4.2% from 4.1% the prior month, slightly above the 4.1% consensus. It is the weakest payrolls print since the labor market began its recovery from the pandemic shock, and it landed against a backdrop of elevated oil prices, a 5.6% 30-year Treasury yield, and a Federal Reserve that has already raised rates once this cycle.
The internals of the report offer li
User_any
#USSeptemberJobs29K 🧐
The US economy added just 29,000 jobs in September, a fraction of the roughly 90,000 economists had expected and a sharp slowdown from the downwardly revised 133,000 gain in August. The unemployment rate ticked up to 4.2% from 4.1% the prior month, slightly above the 4.1% consensus. It is the weakest payrolls print since the labor market began its recovery from the pandemic shock, and it landed against a backdrop of elevated oil prices, a 5.6% 30-year Treasury yield, and a Federal Reserve that has already raised rates once this cycle.
The internals of the report offer little comfort. July payrolls were revised down by 31,000 to a loss of 10,000, meaning the economy shed jobs that month. The household survey showed more people entering the labor force, which pushed the jobless rate higher even as hiring stalled. Wage growth data was mixed, and the participation rate held steady. The headline number alone tells you that employers have shifted from cautious hiring to outright hesitation.
The market's reaction was immediate and, at first glance, counterintuitive. Equity futures rallied, with S&P 500 futures up 0.9% and Nasdaq futures up 1%. Treasury yields slid as traders priced in a higher probability that the Fed will hold rates steady at its October meeting. Bitcoin and gold both jumped within minutes of the release, as investors interpreted the weak data as reducing the case for further tightening. The dollar softened against most major currencies.
That reaction tells you what the market was positioned for. The consensus expectation was for a resilient labor market that could absorb another rate hike. Instead, it got a report that suggests the economy is losing momentum fast. The Fed's dual mandate requires it to balance inflation control with maximum employment, and a 29,000 print makes the employment side of that equation harder to ignore. The probability of an October hike, which had already fallen to around 37% after the soft PCE reading earlier in the week, dropped further after the jobs data.
The context matters as much as the number itself. This report arrives in the middle of a broader macro storm. The 30-year Treasury yield hit 5.595%, its highest since 2002. Mortgage rates have climbed to 7.6%. Oil has surged above $100 on Middle East tensions. The Fed raised rates on September 16 for the first time in three years. Every one of those forces is a headwind for hiring, and the September payrolls report is the first hard data point that shows those headwinds are actually biting.
What should you watch from here? The revisions to the prior two months will be finalized in the next report, and if the August and September figures are revised lower again, the picture becomes even weaker. The Fed's next meeting on October 28 will be the key event, and the market is now pricing a pause as the base case. But the Fed has repeatedly said it is data-dependent, and one weak payrolls report does not automatically change the policy path. If inflation data continues to cool and the labor market stays soft, the case for a pause strengthens. If inflation surprises to the upside, the Fed could still hike despite the weak jobs number.
The honest reading is that the US labor market is cooling faster than expected, and the market is treating that as a reason to buy risk assets because it reduces the probability of further rate hikes. That is a coherent reaction, but it rests on the assumption that the Fed will prioritize employment over inflation. Whether that assumption holds depends on the next inflation print and the Fed's own communication. For now, the data has done what it needed to do: it has changed the conversation from "how many more hikes" to "is the tightening cycle over." That is a meaningful shift, and it will shape market behavior in the weeks ahead.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC $GT $SOL
repost-content-media
SPX500-0.14%
BTC+1.10%
GT-0.08%
SOL-0.65%
  • 4
The September jobs report has done more than disappoint expectations. It has clarified the Fed's dilemma in a way that the prior months of data did not. The U.S. economy added just 29,000 jobs last month, far below the roughly 90,000 economists had forecast and a sharp deceleration from the 133,000 gain in August. The unemployment rate ticked up to 4.2% from 4.1%, slightly above consensus, and average hourly earnings rose just 0.1% month-over-month against expectations of 0.3%. It is the weakest payrolls print of the post-pandemic recovery, and it arrives against a backdrop of 5.6% long-bond y
User_any
The September jobs report has done more than disappoint expectations. It has clarified the Fed's dilemma in a way that the prior months of data did not. The U.S. economy added just 29,000 jobs last month, far below the roughly 90,000 economists had forecast and a sharp deceleration from the 133,000 gain in August. The unemployment rate ticked up to 4.2% from 4.1%, slightly above consensus, and average hourly earnings rose just 0.1% month-over-month against expectations of 0.3%. It is the weakest payrolls print of the post-pandemic recovery, and it arrives against a backdrop of 5.6% long-bond yields, oil above $100, and a Federal Reserve that tightened rates on September 16 and signaled more could come before year-end.
The immediate market reaction was decisive. The probability of an October hike fell from roughly 34% to under 15% after the release, according to CME's FedWatch tool. The 2-year Treasury yield, the maturity most sensitive to Fed policy expectations, dropped 10 basis points to 4.787%, its largest one-day decline in eight months. The dollar softened, gold pushed from $4,178 to $4,227 an ounce, and Bitcoin climbed from around $86,450 to $87,230 within minutes. The bond market has effectively priced in a pause. It now treats October as a dead meeting, and the burden of proof has shifted to the inflation side of the Fed's mandate.
What makes this moment structurally different is the underlying composition of the labor market. The U.S. labor force has contracted by roughly 700,000 people through 2026, only the second time since 1948 that this has happened outside a recession. The BLS preliminary benchmark revision for March 2026 was negative 79,000. The unemployment rate has stayed relatively low at 4.2% not because hiring is strong, but because the supply of workers is shrinking. That distinction matters for the Fed because it means the labor market is cooling through a reduction in participation rather than through mass layoffs. It is a slow freeze rather than a sudden break, and it complicates the case for further tightening without providing a clear signal that the economy is in distress.
The Fed's dilemma is now explicit. Inflation remains above the 2% target, and the September PCE report showed core prices at 3.0% year-over-year, still well above where the central bank wants them. But the employment side of the dual mandate is no longer strong enough to absorb further tightening. J.P. Morgan still expects one more hike in December, but it does not see this as the start of a sustained cycle. State Street has flagged the divergence between the payrolls survey and the household survey, noting that the two are telling different stories about the same labor market. The data is not clean enough to declare the tightening cycle over, but it is weak enough to remove October from the table and to raise the bar for December.
The window between now and the October 28 FOMC meeting is short, and the data calendar is dense. September CPI and PCE will both land before the Fed decides, and those prints will determine whether the pause holds or whether the committee feels compelled to act again. The October jobs report on November 6 will then provide the next read on whether September was an anomaly or the start of a trend. For now, the market is treating the weak labor data as a reason to buy risk assets, because it reduces the probability of further rate hikes and lowers the opportunity cost of holding non-yielding assets. That is a coherent reaction, but it rests on the assumption that the Fed will prioritize employment over inflation. Whether that assumption holds depends on the inflation data and the Fed's own communication in the coming weeks.
The net read is that the labor market has delivered the first hard evidence that the Fed's tightening is biting, and the market has responded by removing October from the hike calendar. That is a meaningful shift for crypto and other risk assets, because it improves the liquidity environment and gives ETF inflows a better backdrop to operate in. But it is not a green light for an unlimited rally. The inflation side of the mandate is unresolved, the long end of the curve is still elevated, and the December meeting remains live. The next two inflation prints and the October jobs report will determine whether this is the beginning of a sustained easing in policy expectations or just another pause inside a longer tightening cycle.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
##USSeptemberJobs29K
#ShareWeekly
repost-content-media
CME-0.78%
BTC+1.10%
  • 4
I'm trading on Gate, a top-tier exchange with a 13-year track record. Come join me and dive into the hottest events right now! https://www.gate.com/campaigns/6520?ch=8224&ref=AwBFBl5c&ref_type=132
post-image
  • 3
$NEAR USDT - 5.367 +9.37%
NEAR is leading the altcoin run today.
Spot at 5.367 +9.37%, perp at 5.3652 +9.37%, 24h high 5.500, low 4.763, volume 8.00M NEAR, turnover 41.15M. This move is a continuation of what started mid-September.
From September 1 to 15, NEAR was grinding between 2.28 and 2.82. Then it broke. On September 15 it was 2.34, on September 18 it hit 3.45, a 45% move in three days. The full impulse was from 2.29 on September 16 to 4.8 on September 23, a 110% rally in less than 10 days, levels not seen since February. The driver is on-chain, not hype: NEAR Intents, its cross-chain
Sakura_3434
$NEAR USDT - 5.367 +9.37%
NEAR is leading the altcoin run today.
Spot at 5.367 +9.37%, perp at 5.3652 +9.37%, 24h high 5.500, low 4.763, volume 8.00M NEAR, turnover 41.15M. This move is a continuation of what started mid-September.
From September 1 to 15, NEAR was grinding between 2.28 and 2.82. Then it broke. On September 15 it was 2.34, on September 18 it hit 3.45, a 45% move in three days. The full impulse was from 2.29 on September 16 to 4.8 on September 23, a 110% rally in less than 10 days, levels not seen since February. The driver is on-chain, not hype: NEAR Intents, its cross-chain routing system, processed 29.3 billion dollars cumulatively, including 842 million in the past week alone, with a record day above 300 million on September 18 versus 406 million for all of July. Intents generated 5.01 million in fees over 30 days, retaining 1.58 million net revenue.
TVL is approaching 300 million fueled by Ondo partnership bringing tokenized stocks, and AI narrative around NEAR as AI-native blockchain hub. Bitwise even floated a long-term model of 155.85 if roadmap executes.
Your chart shows the second leg starting after a dip to 4.587.
What The 4H Chart Shows
Base at 2.298 on Sept 14, vertical to 5.579 around Sept 27, small pullback to 4.587, then immediate re-acceleration to 5.514 today, now 5.367.
EMA5 5.221 / EMA10 5.116 / EMA30 4.961 - perfect bullish stack, price above all three, EMAs rising. The 4.961 EMA30 is the trend backbone; it has not been broken since Sept 19.
MFI 66.542 - bullish, not yet overbought. On the previous top, MFI was above 95. Now at 66, there is room. The dip to 4.587 flushed MFI down to 12-20 area, which reset momentum.
Performance confirms strength: Today 7.84%, 7 days 22.28%, 30 days 185.63%, 90 days 177.51%, 180 days 340.82%, 1 year 102.76%. 30-day at 185% shows this is not a one-day pump.
Immediate support: 5.221 EMA5 and 5.116 EMA10. That 5.11-5.22 zone is first defense for intraday.
Second support: 4.961 EMA30 and 4.922 level on chart. Holding above 4.96 keeps the second leg intact.
Major support: 4.587 purple line, the low of the last pullback. Break below would mean a deeper reset toward 3.938.
Resistance: 5.514 and 5.579 recent highs, then 5.500 today's 24h high and 5.907 measured. A 4H close above 5.579 opens 5.907.
What To Watch
• Volume 8.00M NEAR with 41.15M turnover is strong but not blow-off. Previous top around 5.579 also had high volume. Current push is on similar volume, so buyers are real.
• NEAR is inching close to its 52-week high. Previous reports flagged 3.34 as 52-week high on Sept 19, now we are at 5.36, so that high is already broken and acting as support far below.
• MFI rising from 12 to 66 in three days shows money flow returning fast after the dip. If MFI pushes above 75 with price above 5.514, momentum could accelerate toward 5.90.
• Risk: NEAR is up 340% in 180 days. Any failure to hold 5.11 would trigger fast move to 4.96 then 4.58. Chasing at 5.36 without confirmation above 5.514 is risky.
Bias stays up while above 4.961. For new entries, waiting for hold above 5.221-5.116 or a retest of 4.961 offers better risk.
Snapshot:
NEAR/USDT 5.367 +9.37% / Perp 5.3652 +9.37%
High 5.500 / Low 4.763 / Vol 8.00M / Turnover 41.15M
EMA5 5.221 / EMA10 5.116 / EMA30 4.961 / MFI 66.542
Not Financial Advice.
ONDO+1.81%
  • 3
🤩 Happy National Day! Gate Social-exclusive gifts are being distributed, with up to 5,000 USDT!
Gate Social's 2️⃣4️⃣th Growth Points Lucky Draw is underway, with multiple great gifts awaiting you!
🎯 Growth Points Guide:
1️⃣ Plaza Tasks
Interact by posting, liking, commenting, and sharing daily to earn up to 600 Growth Points/day
2️⃣ Livestream Tasks
Watch livestreams, like, comment, share, and schedule livestreams to earn up to 300 Growth Points/day
3️⃣ Hot Chat Tasks
Participate in community discussions and share trading cards to earn up to 90 Growth Points/day
4️⃣ Creator-Exclusive Tasks
P
miss_1903
🤩 Happy National Day! Gate Social-exclusive gifts are being distributed, with up to 5,000 USDT!
Gate Social's 2️⃣4️⃣th Growth Points Lucky Draw is underway, with multiple great gifts awaiting you!
🎯 Growth Points Guide:
1️⃣ Plaza Tasks
Interact by posting, liking, commenting, and sharing daily to earn up to 600 Growth Points/day
2️⃣ Livestream Tasks
Watch livestreams, like, comment, share, and schedule livestreams to earn up to 300 Growth Points/day
3️⃣ Hot Chat Tasks
Participate in community discussions and share trading cards to earn up to 90 Growth Points/day
4️⃣ Creator-Exclusive Tasks
Publish content featuring designated tokens and trading cards to earn up to 300 Growth Points per task
Test your luck today 👉 https://www.gate.com/activities/pointprize?now_period=24
$BTC $ETH $ZEC
BTC+1.10%
ETH+0.84%
ZEC-0.04%
  • 1
#MarvellJumps4.5% #MU,
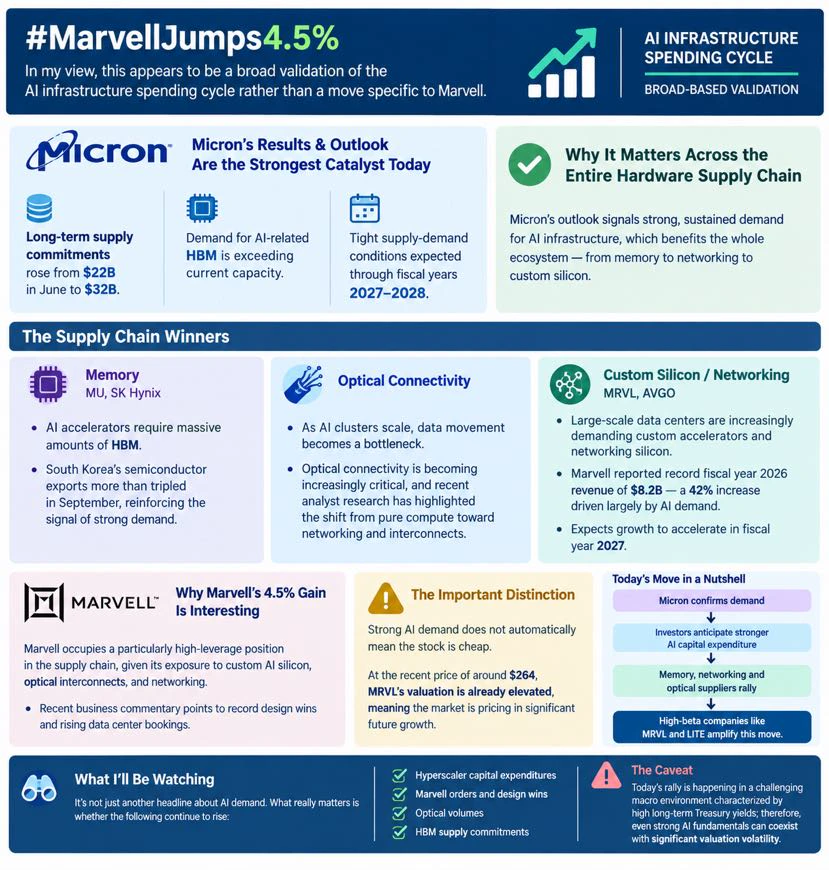
In my view, this appears to be a broad validation of the AI infrastructure spending cycle rather than a move specific to Marvell.
Micron's results and outlook seem to be the strongest catalyst today. Micron reported that long-term supply commitments rose from $22 billion in June to $32 billion, and that demand for AI-related high-bandwidth memory is pushing orders beyond current capacity. Furthermore, the company anticipates tight supply-demand conditions through fiscal years 2027–2028.
This is significant across the entire hardware supply chain:
* Memory — MU, SK Hyn
ybaser
#MarvellJumps4.5% #MU,
In my view, this appears to be a broad validation of the AI ​​infrastructure spending cycle rather than a move specific to Marvell.
Micron's results and outlook seem to be the strongest catalyst today. Micron reported that long-term supply commitments rose from $22 billion in June to $32 billion, and that demand for AI-related high-bandwidth memory is pushing orders beyond current capacity. Furthermore, the company anticipates tight supply-demand conditions through fiscal years 2027–2028.
This is significant across the entire hardware supply chain:
* Memory — MU, SK Hynix: AI accelerators require massive amounts of HBM. South Korea's semiconductor exports more than tripled in September, reinforcing the signal of strong demand.
* As AI clusters scale, data movement becomes a bottleneck. Optical connectivity is becoming increasingly critical, and recent analyst research has highlighted this shift from pure compute toward networking and interconnects.
* Custom silicon/networking — MRVL, AVGO: Large-scale data centers are increasingly demanding custom accelerators and networking silicon. Marvell reported record fiscal year 2026 revenue of $8.2 billion—a 42% increase driven largely by AI demand—and expects growth to accelerate in fiscal year 2027.
Why is Marvell's 4.5% gain interesting? Marvell occupies a particularly high-leverage position in the supply chain, given its exposure to custom AI silicon, optical interconnects, and networking. Recent business commentary points to record design wins and rising data center bookings.
However, there is a crucial distinction: strong AI demand does not automatically mean the stock is cheap. At the recent price of around $264, MRVL’s valuation is already elevated, meaning the market is pricing in significant future growth.
Thus, I would summarize today’s movement as follows:
Micron confirms demand → investors anticipate stronger AI capital expenditure → memory, networking, and optical suppliers rally → high-beta companies like MRVL and LITE amplify this move.
The most important thing I’ll be watching going forward isn't just another headline about AI demand; what really matters is whether hyperscaler capital expenditures, Marvell orders and design wins, optical volumes, and HBM supply commitments continue to rise enough to justify these valuations.
A caveat: Today’s rally is taking place in a challenging macro environment characterized by high long-term Treasury yields; consequently, even strong AI fundamentals can coexist with significant valuation volatility
$MU ‌
.$SKHYNIX ‌$MRVL ‌$LITE ‌
repost-content-media
MU-2.18%
MRVL+1.66%
SK Hynix+0.43%
LITE+3.77%
AVGO+3.30%
  • 3
Cash-In Thursday: Futures Event, Invite Friends for a 100% Chance to Win SOL Mystery Boxes https://www.gate.com/campaigns/6487?ch=8152&ref=AwBFBl5c&ref_type=132&utm_cmp=VmIxea8A
post-image
  • 3
$BTC ‌Bitcoin is trading at $84,283, down 0.12% over the past 24 hours, after a nine-day streak of ETF inflows came to an abrupt end. The price is caught between two competing forces: a major investment bank raising its long-term target, and a short-term flow reversal that has stalled momentum.
Citi raised its 12-month Bitcoin price target to $113,000 from $82,000 on Thursday, citing renewed demand for spot ETFs, the U.S. Treasury's bond buyback program, SEC rulemaking progress, and a softer dollar. The bank also lifted its Ether forecast to $3,028 from $2,240. The $113,000 target implies rou
User_any
$BTC ‌Bitcoin is trading at $84,283, down 0.12% over the past 24 hours, after a nine-day streak of ETF inflows came to an abrupt end. The price is caught between two competing forces: a major investment bank raising its long-term target, and a short-term flow reversal that has stalled momentum.
Citi raised its 12-month Bitcoin price target to $113,000 from $82,000 on Thursday, citing renewed demand for spot ETFs, the U.S. Treasury's bond buyback program, SEC rulemaking progress, and a softer dollar. The bank also lifted its Ether forecast to $3,028 from $2,240. The $113,000 target implies roughly 34% upside from current levels, though it remains below the record above $126,000 reached in October 2025. Citi specifically pointed to "debasement fears" returning to markets as a factor supporting the move.
That optimistic view contrasts with the immediate flow picture. U.S. spot Bitcoin ETFs snapped a nine-day inflow streak totaling $3.1 billion on Wednesday, swinging to $148.7 million in net outflows. Fidelity's FBTC led the retreat with $125.6 million leaving the fund, while BlackRock's IBIT also ended its own inflow streak with $9.5 million in outflows. Total ETF assets remain around $108 billion, but the funding backdrop has shifted from persistent buying to outflows, eroding the incremental demand that had supported prices through late September.
The macro environment is the primary reason Bitcoin keeps getting rejected near $84,000. The U.S. 10-year Treasury yield climbed to fresh highs, and France's 5-year credit default swap widened to 73.05 basis points, the highest since July 2013. Rising risk-free rates and sovereign-debt risk typically compress valuations for high-volatility assets. The Fed's preferred PCE inflation gauge came in below expectations, with core PCE at 0.2% month-on-month and 3.0% year-on-year, cutting the priced probability of another October hike to 37%. Bitcoin spiked quickly on the release but then slid back below $84,000, showing easier-policy expectations have yet to translate into sustained buying.
The technical picture is defined by a well-established resistance zone. Glassnode has flagged the $84,000 to $85,000 range as a key level, with long-term holders clustered there. A break above could target $96,700, while a drop below $84,000 may see support at $77,000. Bitcoin has now spent seven sessions oscillating around $84,000, and the $86,000 level that represents the average ETF cost basis creates a wall for the next rally. The 24-hour range of $83,183 to $84,617 shows the narrow band the price is confined to.
The honest takeaway is that Bitcoin is stuck between a bullish long-term thesis and a bearish short-term flow. Citi's target is a 12-month forecast, and the catalysts it cites are structural. The ETF outflow is a one-day event, and streaks end for many reasons. But the market is not trading on 12-month outlooks right now. It is trading on the cost of capital, and that cost is high. Until Treasury yields ease or ETF inflows resume, the $84,000 to $85,000 zone will remain the level that defines whether this consolidation resolves upward or downward.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
repost-content-media
BTC+1.10%
  • 3