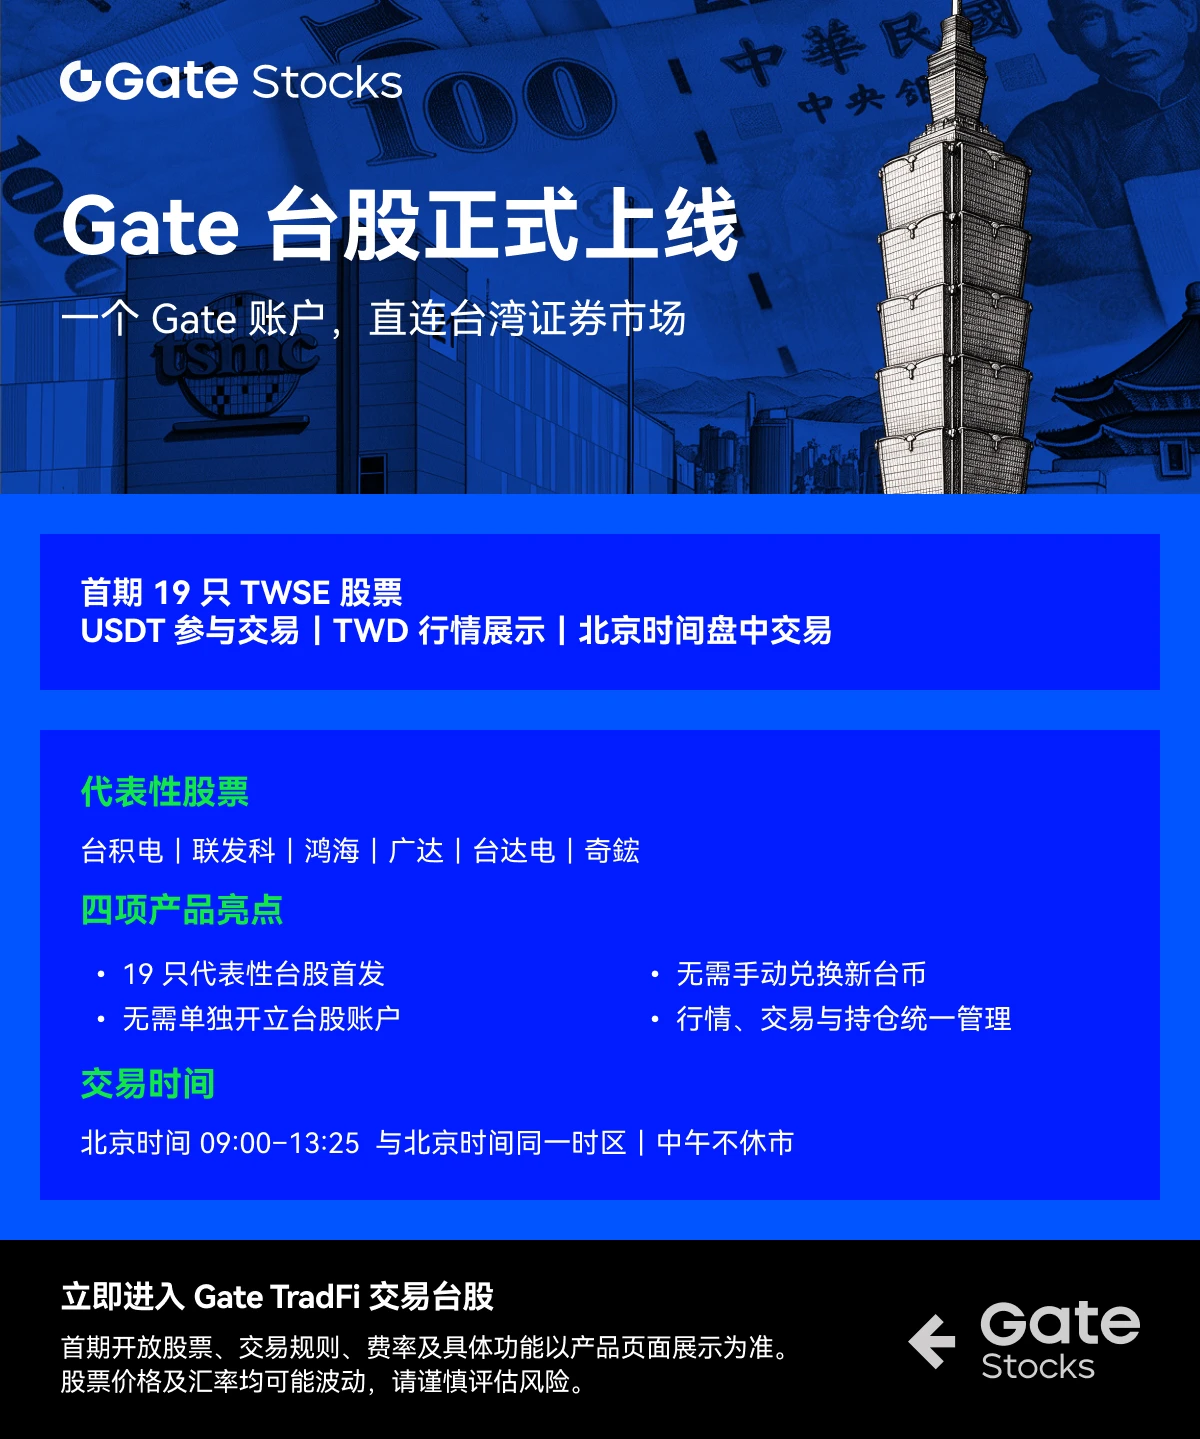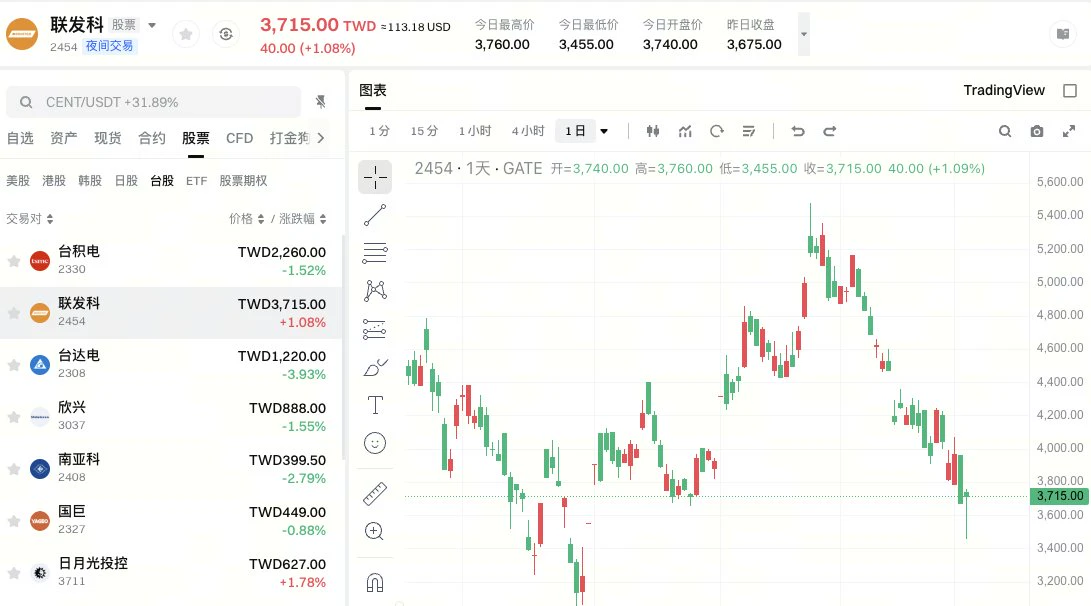

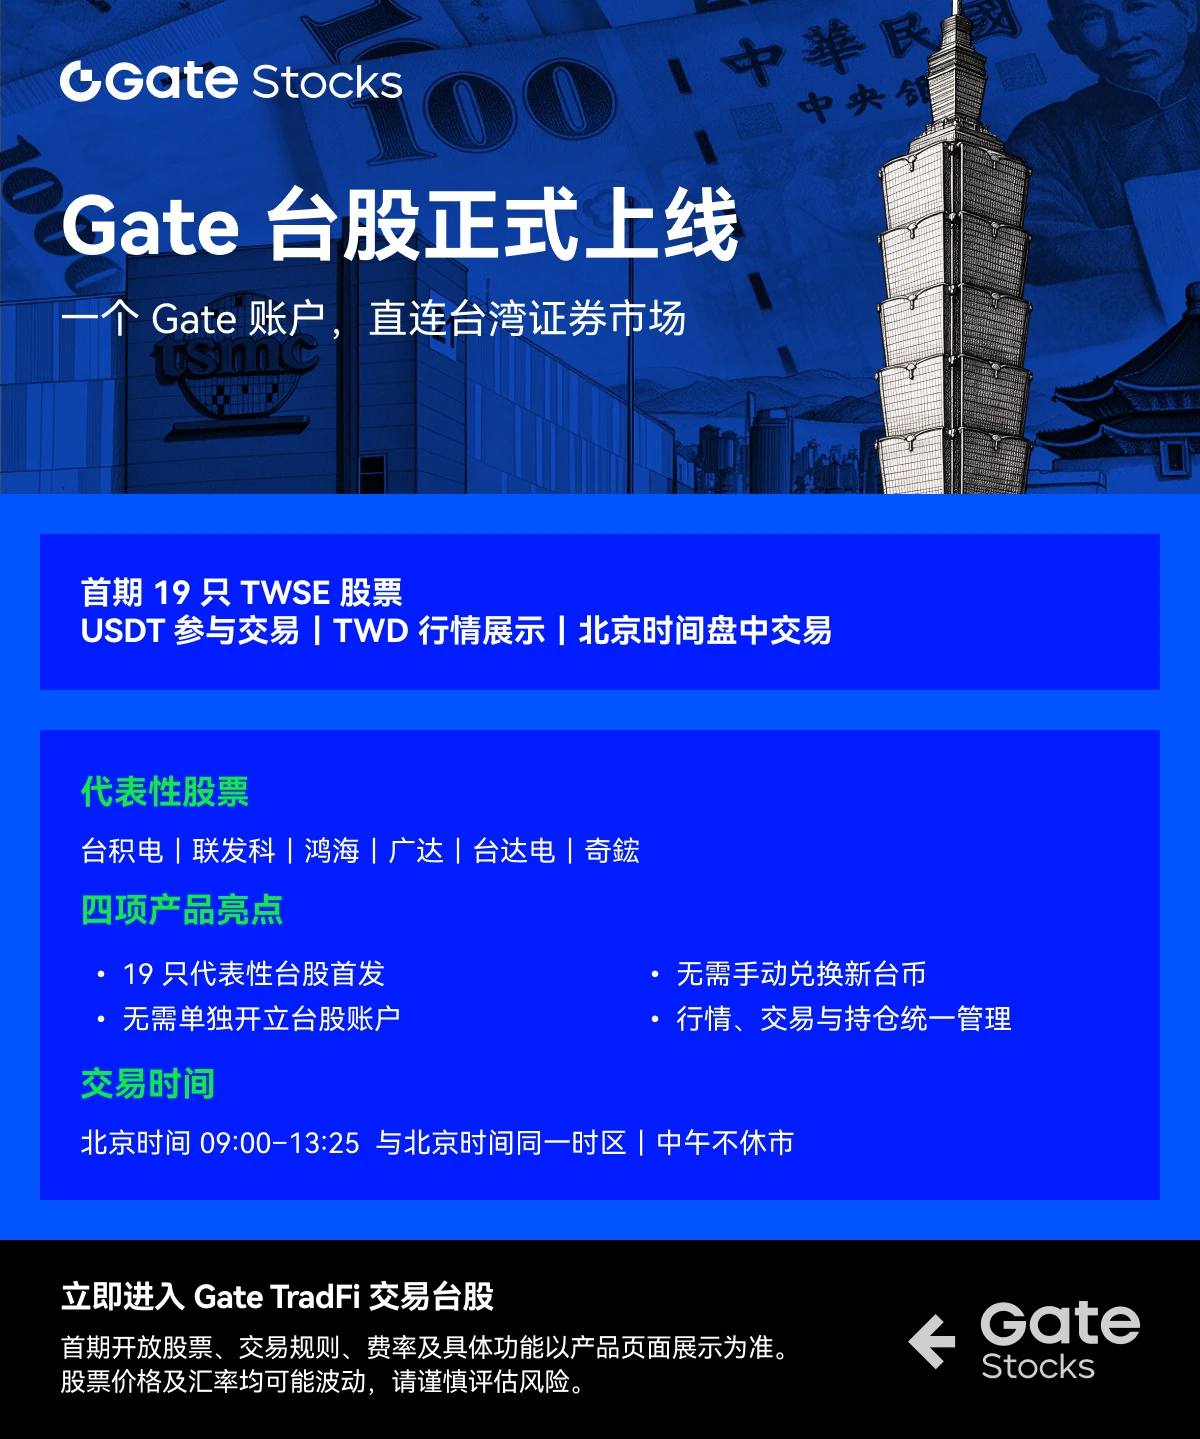
#Gate上线台股交易 For long-term AI potential, I favor TSMC most, followed by MediaTek, with Hon Hai in third place. The three companies are positioned at the manufacturing foundation, chip design, and system assembly stages, respectively.
TSMC Highest certainty
AI chips are increasingly concentrated in advanced process nodes and advanced packaging, giving TSMC pricing power and control over capacity allocation. Revenue grew 50.9% year over year in the third quarter of 2026, and its full-year USD revenue growth guidance was raised to around 44%; capital expenditure is expected to reach $60 billion to $64 billion.
Its advantage is its broad customer base, with performance not dependent on a single product. The main risks are overseas fab costs, pressure from ramping up advanced nodes, and the drag that continued high capital expenditure could have on margins.
MediaTek Greatest upside
MediaTek is shifting from smartphone chips to custom data center chips. Its first AI ASIC began shipping in small volumes in September 2026, with a fourth-quarter revenue target of $2.5 billion; management's target for 2027 is around $16 billion. This business is growing rapidly, but the payoff will come later. Yield on the first product, delivery pace, and the second customer's progress toward mass production will all have a significant impact on its valuation.
Hon Hai Strongest orders
Hon Hai's strength lies in AI server racks and system-level manufacturing. Net profit grew 35% year over year in the second quarter of 2026, and full-year AI server rack shipments are expected to double; management says capacity for the next year and a half is already largely booked. Its weak points are low operating margins and greater dependence on cloud service providers' capital expenditure. Even when demand is booming, the market pays closer attention to whether it can turn revenue growth into profit growth.
Assessment and approach
· Long-term core holding: TSMC. The more widespread AI infrastructure becomes, the more easily it can secure a stable share.
· Growth allocation: MediaTek, worth tracking for actual AI ASIC shipments and improving margins.
· Industry validation: Hon Hai. Order visibility is high, but it is better suited as an indicator to watch on the manufacturing side.
At this stage, I view TSMC as “the infrastructure of the AI wave,” MediaTek as “a high-growth variable,” and Hon Hai as “a demand validator.”$TSM
TSMC Highest certainty
AI chips are increasingly concentrated in advanced process nodes and advanced packaging, giving TSMC pricing power and control over capacity allocation. Revenue grew 50.9% year over year in the third quarter of 2026, and its full-year USD revenue growth guidance was raised to around 44%; capital expenditure is expected to reach $60 billion to $64 billion.
Its advantage is its broad customer base, with performance not dependent on a single product. The main risks are overseas fab costs, pressure from ramping up advanced nodes, and the drag that continued high capital expenditure could have on margins.
MediaTek Greatest upside
MediaTek is shifting from smartphone chips to custom data center chips. Its first AI ASIC began shipping in small volumes in September 2026, with a fourth-quarter revenue target of $2.5 billion; management's target for 2027 is around $16 billion. This business is growing rapidly, but the payoff will come later. Yield on the first product, delivery pace, and the second customer's progress toward mass production will all have a significant impact on its valuation.
Hon Hai Strongest orders
Hon Hai's strength lies in AI server racks and system-level manufacturing. Net profit grew 35% year over year in the second quarter of 2026, and full-year AI server rack shipments are expected to double; management says capacity for the next year and a half is already largely booked. Its weak points are low operating margins and greater dependence on cloud service providers' capital expenditure. Even when demand is booming, the market pays closer attention to whether it can turn revenue growth into profit growth.
Assessment and approach
· Long-term core holding: TSMC. The more widespread AI infrastructure becomes, the more easily it can secure a stable share.
· Growth allocation: MediaTek, worth tracking for actual AI ASIC shipments and improving margins.
· Industry validation: Hon Hai. Order visibility is high, but it is better suited as an indicator to watch on the manufacturing side.
At this stage, I view TSMC as “the infrastructure of the AI wave,” MediaTek as “a high-growth variable,” and Hon Hai as “a demand validator.”$TSM