




Nvidia Earnings Preview (Early Hours of November 18)
I. Earnings Schedule
• Time: After the market closes on November 17 in the U.S. (early hours of November 18 Beijing time); release of its Q3 FY2027 results.
• Background: The quarter ended before Jensen Huang's resignation on November 12, so the results mainly reflect orders and shipments during his tenure; interim CEO and CFO Colette Kress will host independently for the first time, with the real test being her outlook for the future.
II. Market Expectations: Nearly Double Year Over Year, with a High Bar to Beat
• Revenue: Consensus is about $109 billion, up about 91% year over year; management guidance is $108 billion ±2%.
• Adjusted EPS: Consensus is $2.47, versus $1.30 in the same period last year, nearly doubling.
• Data center revenue: Consensus is about $101.8 billion, up about 98% year over year, versus $89 billion last quarter.
• Gross margin: Guidance is about 74%, versus 75% last quarter.
• Major banks are generally optimistic: Goldman Sachs expects revenue of $110.08 billion and gross margin of 74.1%; Wedbush sees $113–115 billion.
III. Four Key Things to Watch
01 Q4 revenue guidance: The market expects about $124.3 billion, while Wedbush sees $124–130 billion; during the transition, management may issue cautious guidance. Even if Q3 beats expectations, cautious guidance could weigh on the stock.
02 Vera Rubin shipments: In August, it was expected to contribute about 20% of Q3 data center revenue. With HBM4 supply constraints, its 2026 shipment forecast has already been lowered. Confirm whether shipments will be delayed and whether they can ramp up in Q4.
03 Gross margin trajectory: Rising memory prices are squeezing margins, and the company has already forecast Q4 gross margin falling to 71%–72%. Guidance below 71% would raise concerns about cost pass-through.
04 Governance and succession: The permanent CEO position remains unsettled; internal candidate Ian Buck and Arm's CEO have reportedly been approached, while Huang is said to be considering a return. Alongside export compliance reviews, watch for comments on the earnings call about governance and customer partnerships.
IV. Other Areas to Watch
• Customer mix: Growth among hyperscalers and in AI cloud/enterprise business (ACIE); watch for large customers' in-house ASIC development and AMD taking market share.
• China market: Current guidance excludes China data center compute revenue; watch for any changes to assumptions for Q4.
• AI compute financing: Progress on the $500 billion third-party funding platform and guarantees related to OpenAI.
V. Stock Price and Volatility
• Current price is about $163, down about 32% over 30 days and about 35% from its October high.
• Options imply a one-day post-earnings move of about ±7%, and about ±8% through the weekend, corresponding to a range of about $150–176.
VI. Summary and Trading Approach
Strong results are likely, but amid a high base and management transition, the stock will depend more on Q4 guidance, Rubin shipments, and gross margin than on Q3 itself. After-hours liquidity is thin and volatility can increase, so consider limiting positions ahead of earnings and avoiding chasing orders. Focus on whether guidance beats expectations and governance risks ease before deciding whether to follow the move.
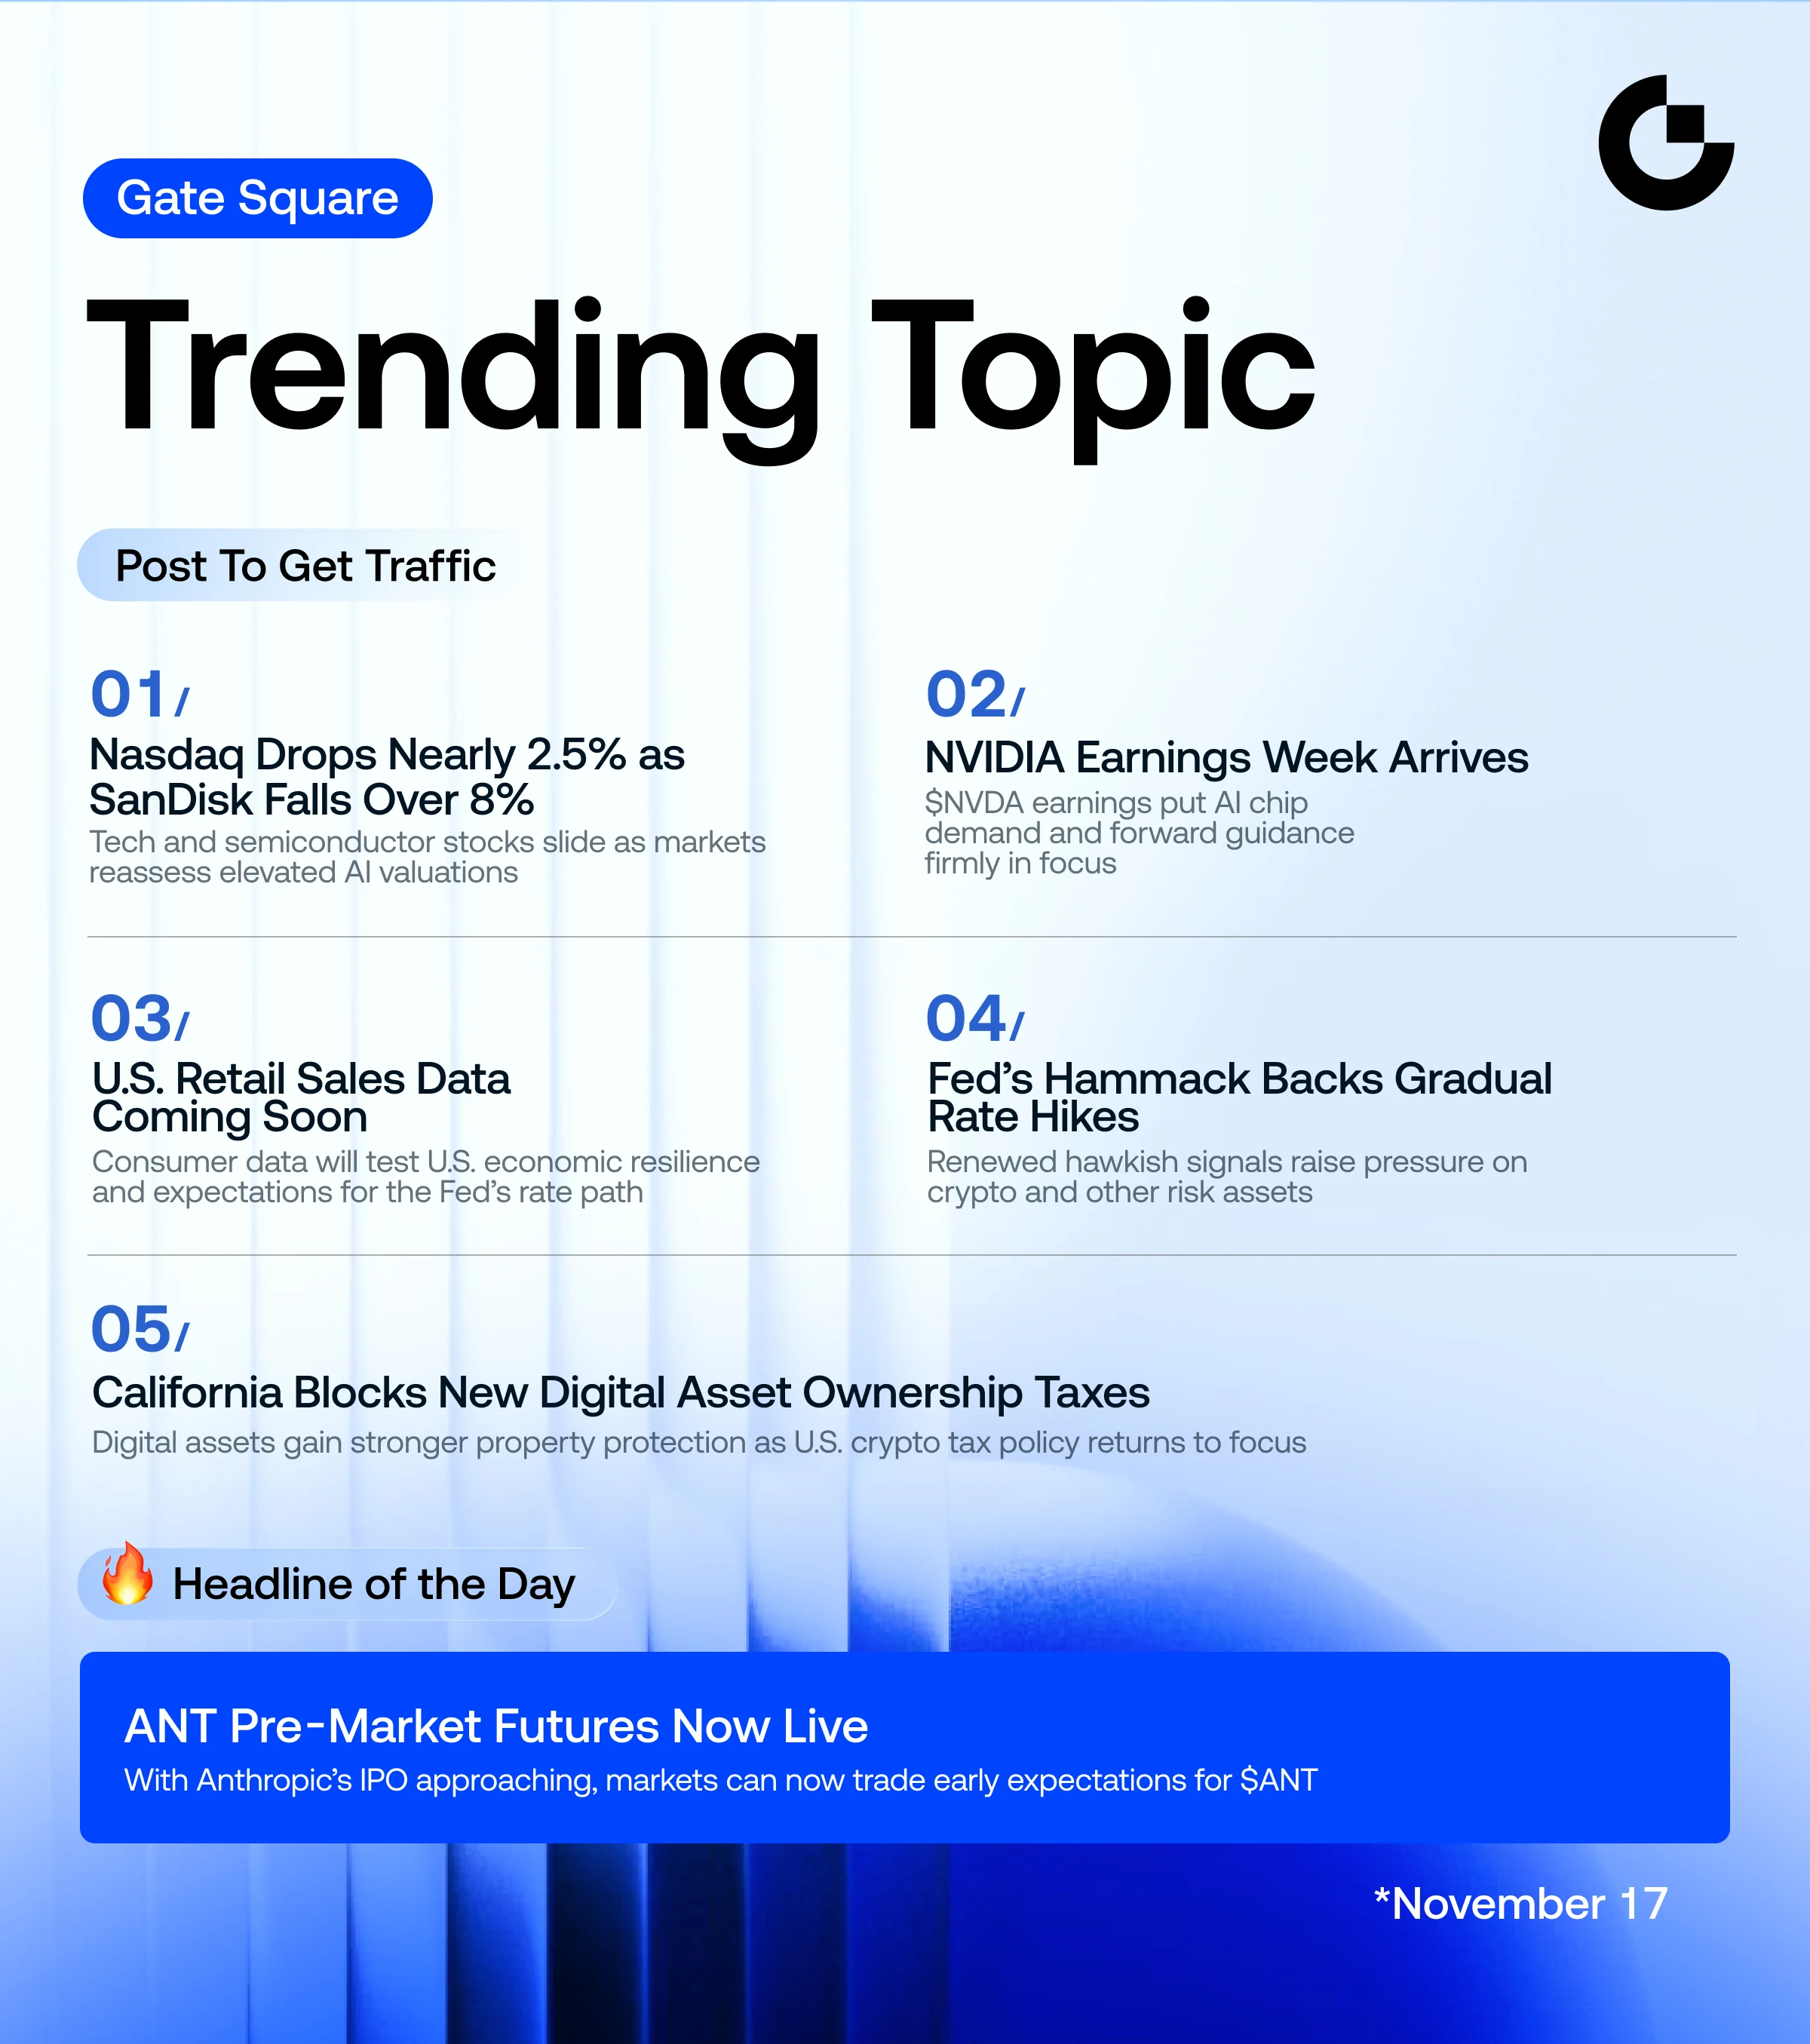
#英伟达财报周来袭
I. Earnings Schedule
• Time: After the market closes on November 17 in the U.S. (early hours of November 18 Beijing time); release of its Q3 FY2027 results.
• Background: The quarter ended before Jensen Huang's resignation on November 12, so the results mainly reflect orders and shipments during his tenure; interim CEO and CFO Colette Kress will host independently for the first time, with the real test being her outlook for the future.
II. Market Expectations: Nearly Double Year Over Year, with a High Bar to Beat
• Revenue: Consensus is about $109 billion, up about 91% year over year; management guidance is $108 billion ±2%.
• Adjusted EPS: Consensus is $2.47, versus $1.30 in the same period last year, nearly doubling.
• Data center revenue: Consensus is about $101.8 billion, up about 98% year over year, versus $89 billion last quarter.
• Gross margin: Guidance is about 74%, versus 75% last quarter.
• Major banks are generally optimistic: Goldman Sachs expects revenue of $110.08 billion and gross margin of 74.1%; Wedbush sees $113–115 billion.
III. Four Key Things to Watch
01 Q4 revenue guidance: The market expects about $124.3 billion, while Wedbush sees $124–130 billion; during the transition, management may issue cautious guidance. Even if Q3 beats expectations, cautious guidance could weigh on the stock.
02 Vera Rubin shipments: In August, it was expected to contribute about 20% of Q3 data center revenue. With HBM4 supply constraints, its 2026 shipment forecast has already been lowered. Confirm whether shipments will be delayed and whether they can ramp up in Q4.
03 Gross margin trajectory: Rising memory prices are squeezing margins, and the company has already forecast Q4 gross margin falling to 71%–72%. Guidance below 71% would raise concerns about cost pass-through.
04 Governance and succession: The permanent CEO position remains unsettled; internal candidate Ian Buck and Arm's CEO have reportedly been approached, while Huang is said to be considering a return. Alongside export compliance reviews, watch for comments on the earnings call about governance and customer partnerships.
IV. Other Areas to Watch
• Customer mix: Growth among hyperscalers and in AI cloud/enterprise business (ACIE); watch for large customers' in-house ASIC development and AMD taking market share.
• China market: Current guidance excludes China data center compute revenue; watch for any changes to assumptions for Q4.
• AI compute financing: Progress on the $500 billion third-party funding platform and guarantees related to OpenAI.
V. Stock Price and Volatility
• Current price is about $163, down about 32% over 30 days and about 35% from its October high.
• Options imply a one-day post-earnings move of about ±7%, and about ±8% through the weekend, corresponding to a range of about $150–176.
VI. Summary and Trading Approach
Strong results are likely, but amid a high base and management transition, the stock will depend more on Q4 guidance, Rubin shipments, and gross margin than on Q3 itself. After-hours liquidity is thin and volatility can increase, so consider limiting positions ahead of earnings and avoiding chasing orders. Focus on whether guidance beats expectations and governance risks ease before deciding whether to follow the move.
#英伟达财报周来袭