



Why Did Tech Rally While the Fed Raised Rates?
The Fed raised rates, and tech stocks still rallied.
Every textbook says the opposite should happen.
The explanation comes down to one thing: the gap between what the market had priced in and what it actually got.
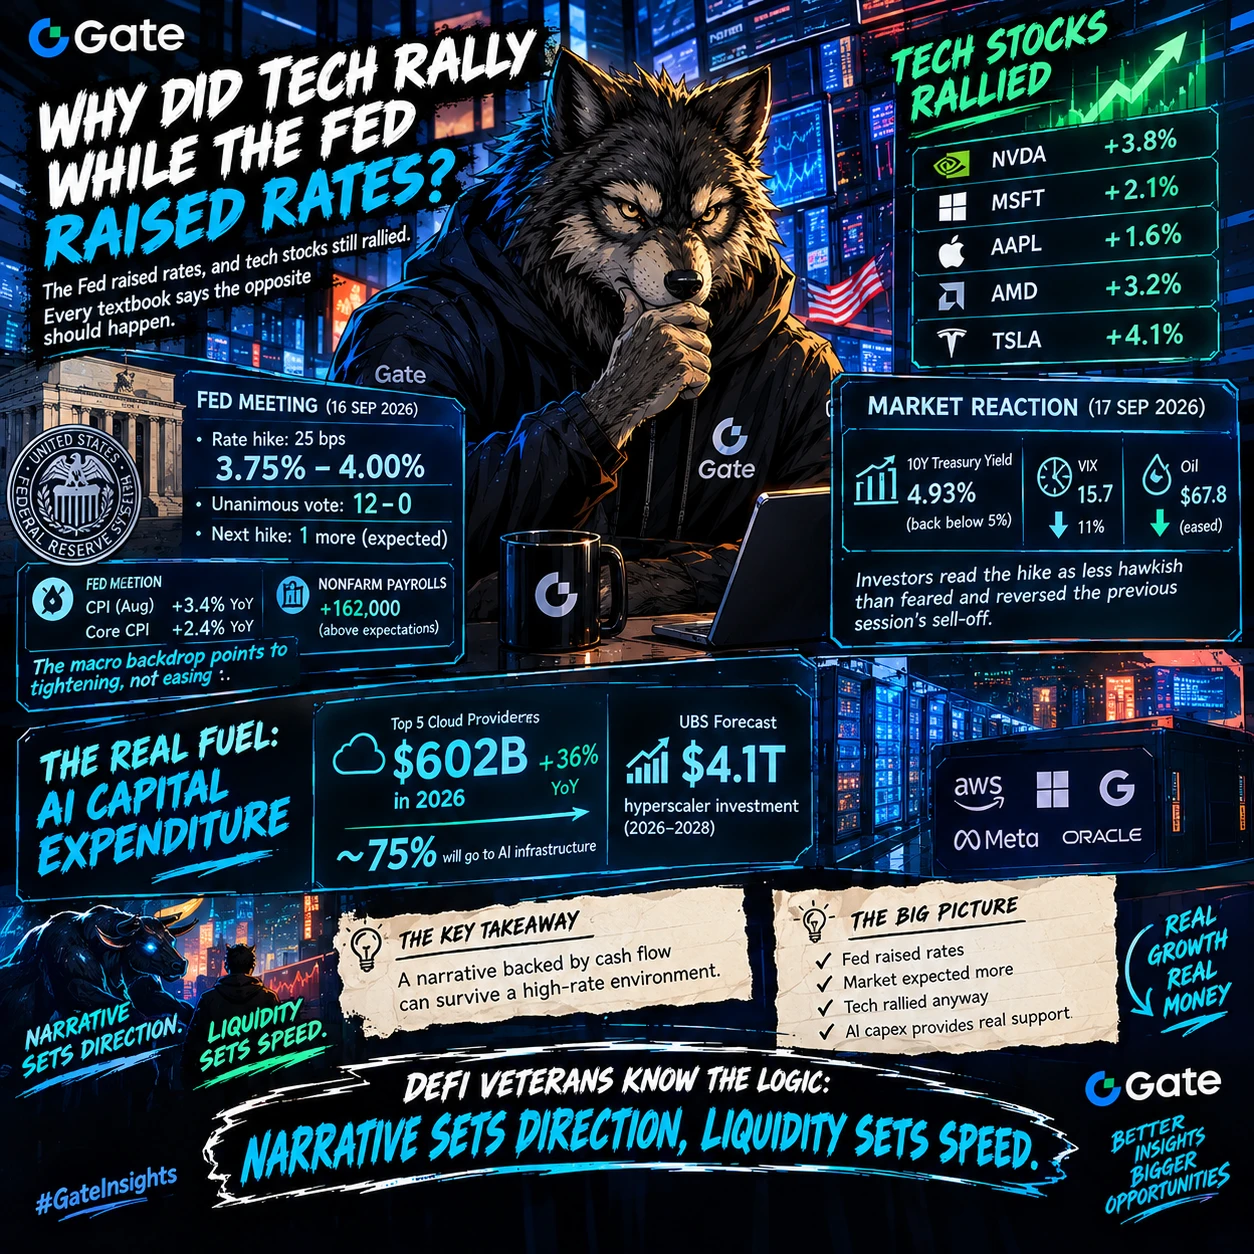
On 16 September, the Fed raised its policy rate by 25 basis points to 3.75–4.00%. The decision was unanimous at 12–0 and marked the first hike since 2023. Projections point to one more increase before year-end. August CPI came in at 3.4% year on year with core inflation at 2.4%, and nonfarm payrolls beat expectations at +162,000. The macro backdrop points to tightening, not easing.
Yet on 17 September risk appetite improved: the 10-year Treasury yield slipped to 4.93%, back below 5%; the VIX dropped 11% to 15.7; oil eased. Investors read the hike as less hawkish than feared and reversed the previous session's sell-off.
The real fuel, however, is AI capital expenditure. The top five cloud providers are set to spend roughly $602bn in 2026, up 36% year on year, with about three-quarters of that going into AI infrastructure. UBS models $4.1tn of hyperscaler investment across 2026–2028. A narrative backed by cash flow can survive a high-rate environment.
DeFi veterans will recognise the logic: narrative sets direction, liquidity sets speed.
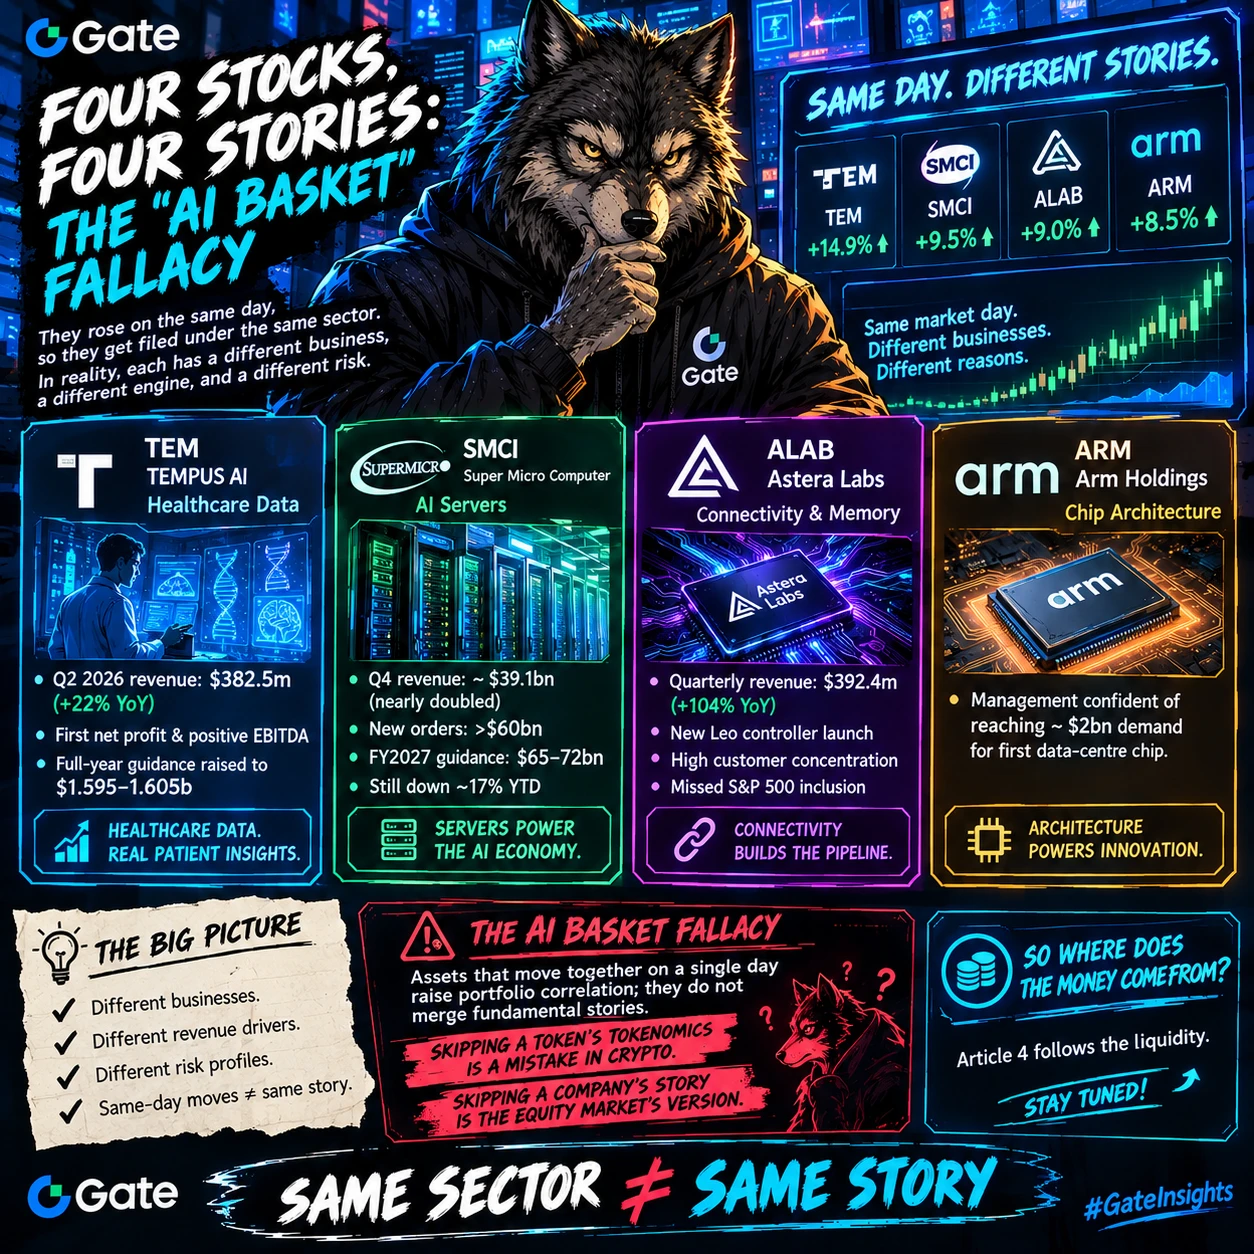
But are these four stocks really one "AI basket"? No — and that distinction changes your risk. Article 3 explains why.
This content is not investment advice. Always perform your own research before making financial decisions.
#Gate广场中秋团圆局 #美股AI概念股全线反弹 #GateMemeCarnival #WhereToParkStablecoinsWhileWaiting #GateSquareMidAutumnReunion
The Fed raised rates, and tech stocks still rallied.
Every textbook says the opposite should happen.
The explanation comes down to one thing: the gap between what the market had priced in and what it actually got.
On 16 September, the Fed raised its policy rate by 25 basis points to 3.75–4.00%. The decision was unanimous at 12–0 and marked the first hike since 2023. Projections point to one more increase before year-end. August CPI came in at 3.4% year on year with core inflation at 2.4%, and nonfarm payrolls beat expectations at +162,000. The macro backdrop points to tightening, not easing.
Yet on 17 September risk appetite improved: the 10-year Treasury yield slipped to 4.93%, back below 5%; the VIX dropped 11% to 15.7; oil eased. Investors read the hike as less hawkish than feared and reversed the previous session's sell-off.
The real fuel, however, is AI capital expenditure. The top five cloud providers are set to spend roughly $602bn in 2026, up 36% year on year, with about three-quarters of that going into AI infrastructure. UBS models $4.1tn of hyperscaler investment across 2026–2028. A narrative backed by cash flow can survive a high-rate environment.
DeFi veterans will recognise the logic: narrative sets direction, liquidity sets speed.
But are these four stocks really one "AI basket"? No — and that distinction changes your risk. Article 3 explains why.
This content is not investment advice. Always perform your own research before making financial decisions.
#Gate广场中秋团圆局 #美股AI概念股全线反弹 #GateMemeCarnival #WhereToParkStablecoinsWhileWaiting #GateSquareMidAutumnReunion