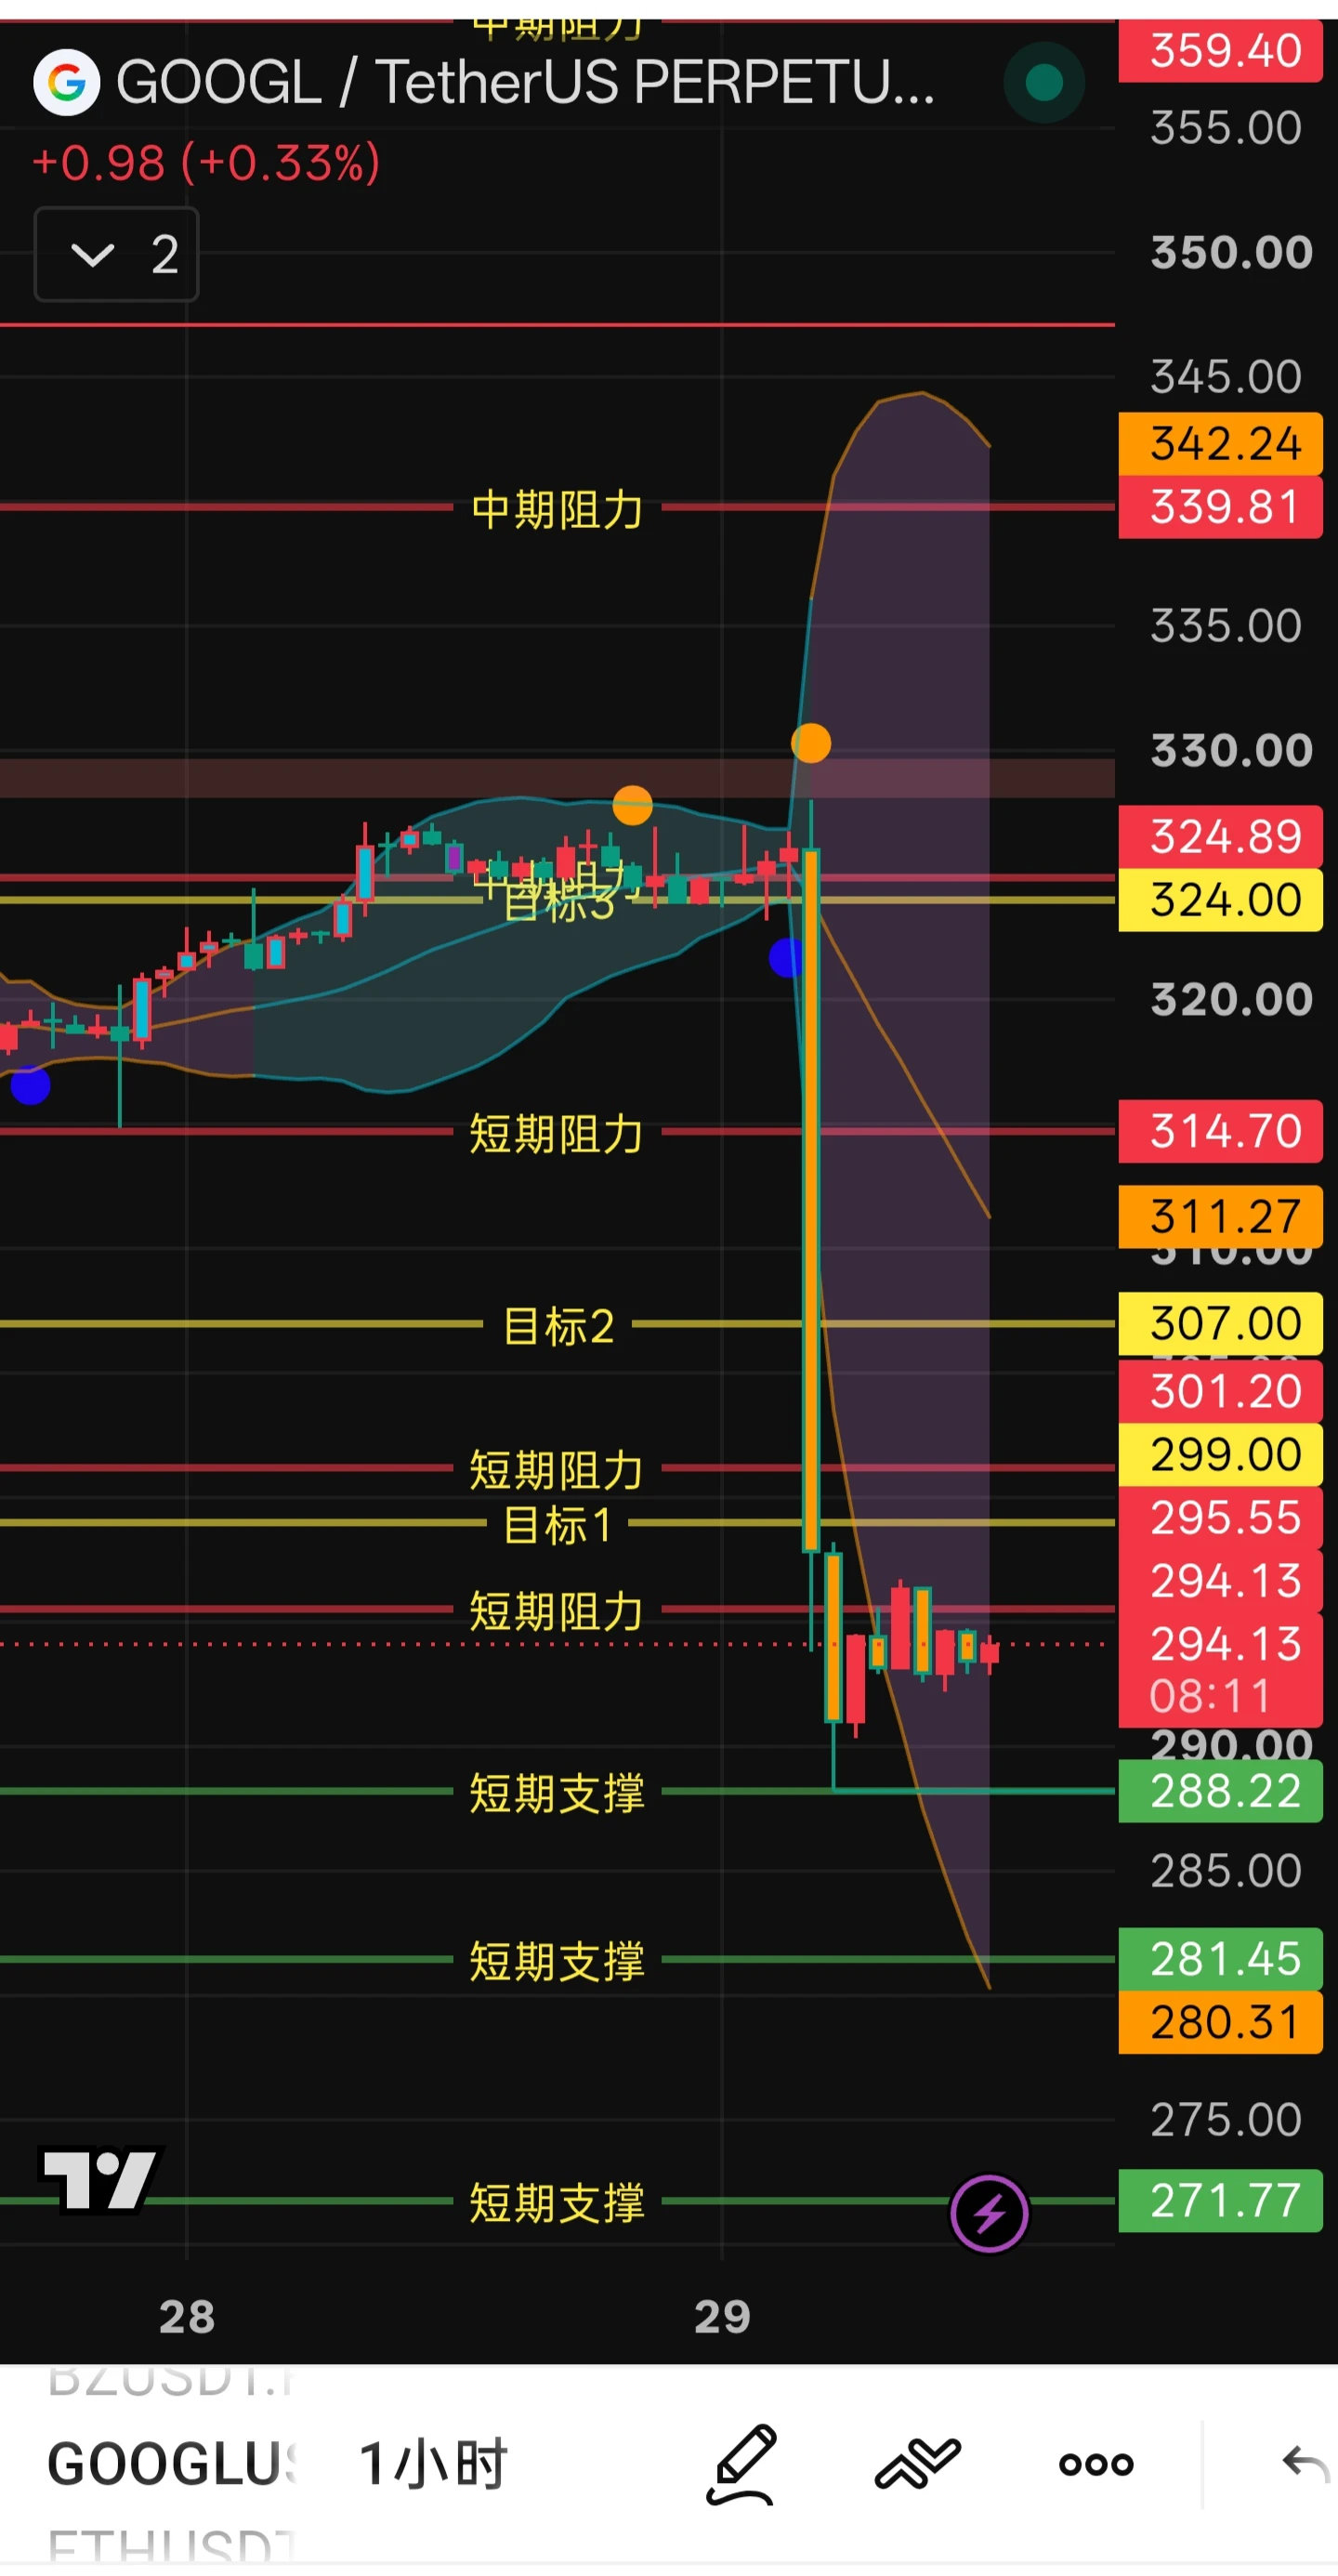
#谷歌云增长103%股价却跌近10% #每周来晒 Google's sharp after-hours drop this time shows that investors now demand stronger evidence that the “AI story” can continue to deliver. In the short term, the market is focused more on earnings and cash flow, while betting on AI growth over the long term.
Why cloud business surged while the stock fell
The cloud business is indeed very strong: Google Cloud revenue grew 103% year over year to $30.709 billion; operating profit was $11.121 billion, and its margin rose to 36.2%. AI infrastructure, solutions, and TPU sales are all driving growth.
Core advertising showed cracks: Search ad growth slowed to 12%, down from 17% in the previous quarter. AI-driven changes in traffic have the market worried about the monetization capability of traditional advertising.
Profit and cash flow are under pressure: Net profit fell 25% year over year, mainly dragged down by $8.66 billion in losses on equity investments; free cash flow was negative $9.07 billion, and capital expenditures reached $51.36 billion.
What the market is really calculating: Google Cloud's growth is impressive, but the market is asking: Can this revenue cover AI investment? Can the pace of cash outflows be reversed? Cloud backlog reached $561 billion, with more than half expected to be recognized over the next 24 months. This supports future revenue, but it takes time for orders to turn into actual recognized revenue.
So, in the short term, the market is using “earnings and cash flow” to set limits on AI valuations; over the medium to long term, the AI story still holds as long as the cloud business continues to grow rapidly and margins keep improving.
My view is that the market is now in a “verify first, revalue later” phase. Doubling cloud revenue is only the first proof point; next, the market will look at capital expenditure efficiency, the core advertising business, and a recovery in free cash flow. Only if all three improve in tandem will the stock have a chance to be repriced; cloud revenue growth alone is no longer enough to support a high valuation. $GOOGL