Share your thoughts
placeholder
Article
Golden September, Silver October Chapter 9: Why You Must Have an Awareness of Key Market Turning Points
A turning point is the dividing line in the battle between bulls and bears on the chart—in other words, a key support level, resistance level, or trend-reversal point. Having an awareness of turning points means planning all entries, stop-losses, and take-profits around key levels, rather than making impulsive decisions based on intraday sentiment.
$BTC
The root cause of many traders’ losses is not that they cannot read candlesticks, but that they lack an awareness of key levels: impulsivel
post-image
BTC+0.89%
ETH+0.31%
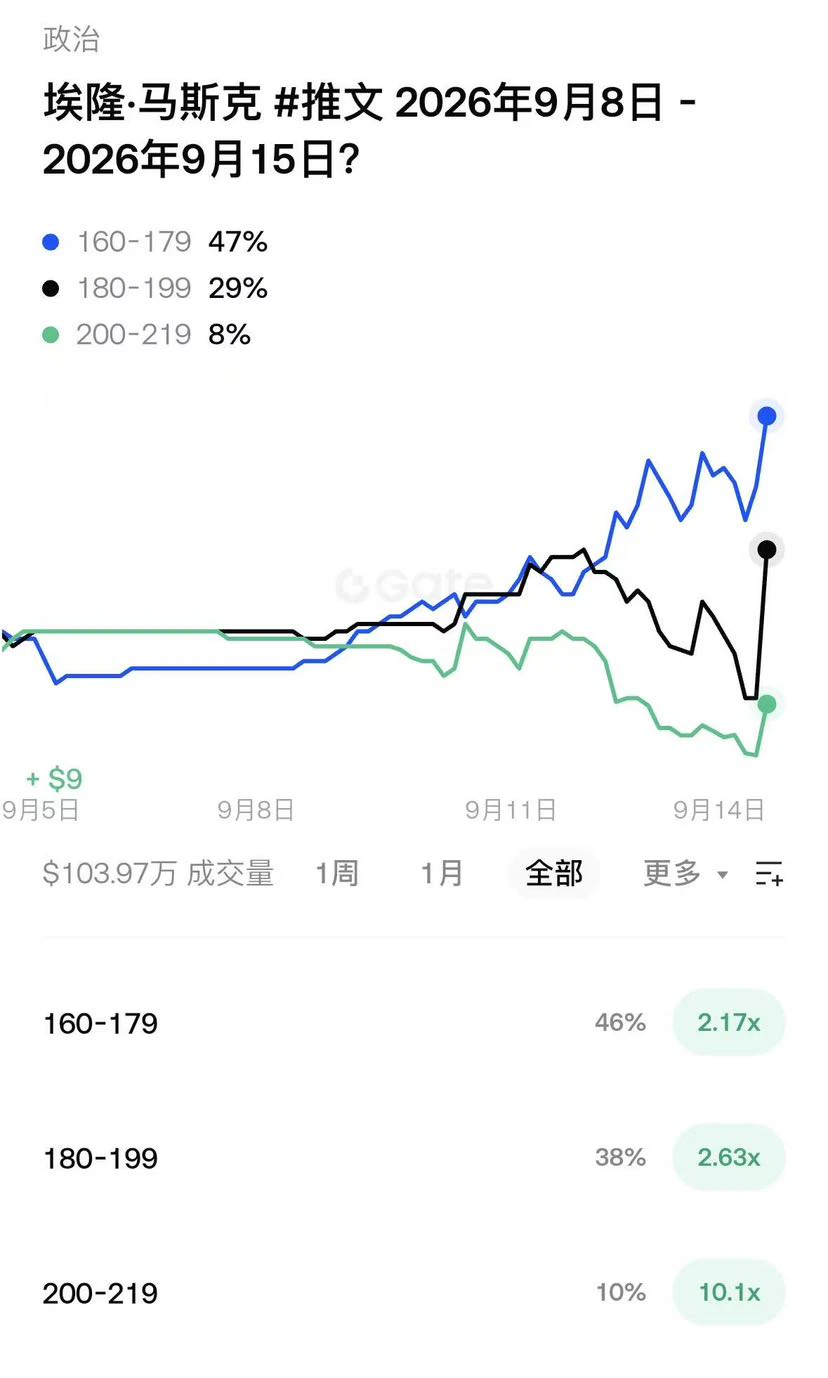
Mainstream market expectation: The probability that Musk’s tweet count this cycle will fall in the 160–179 range is highest, followed by 180–199; the market considers it highly unlikely that he will post 200 or more tweets in one week.
Overall, this week is expected to be a high-output cycle, but reaching the ultra-high posting volume of 200 or more tweets will be difficult.
post-image
Little Yellow Fish
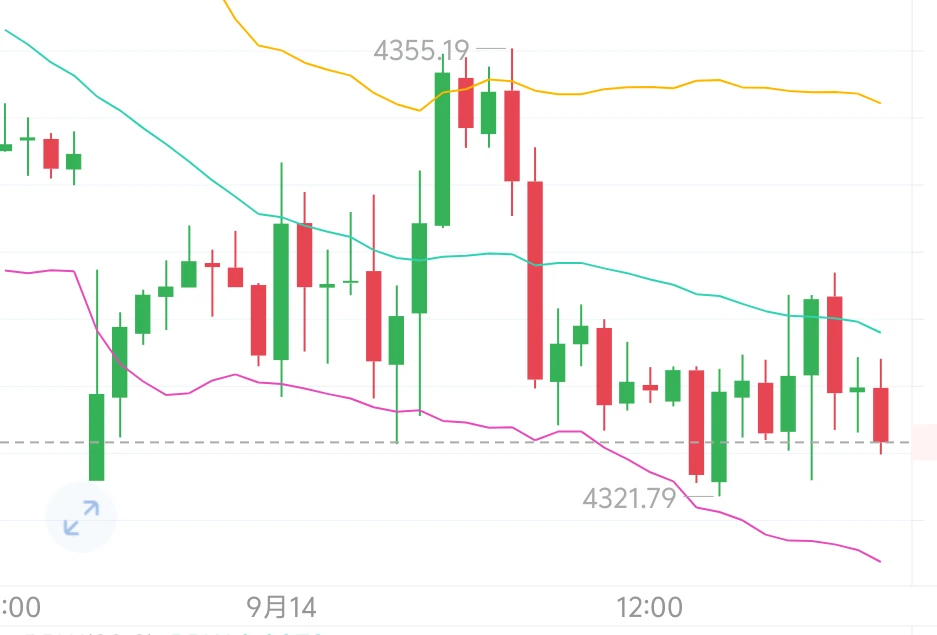
From a news perspective, the market is weighing expectations of a Federal Reserve rate hike. Geopolitical tensions have pushed up oil prices, further intensifying inflation concerns and thereby suppressing a rebound in gold prices. The current rally is merely a recovery following oversold conditions, not a trend reversal.
Resistance is around 4349–4388, while support is around 4310. In terms of trading, one can wait for prices to rebound to the 4350–4370 range before establishing short positions, with targets around 4310 and 4290.
$BTC $ETH $SOL #传Anthropic选择纳斯达克IPO #韩国股市开盘重
post-image
BTC+0.89%
ETH+0.31%
SOL+0.89%
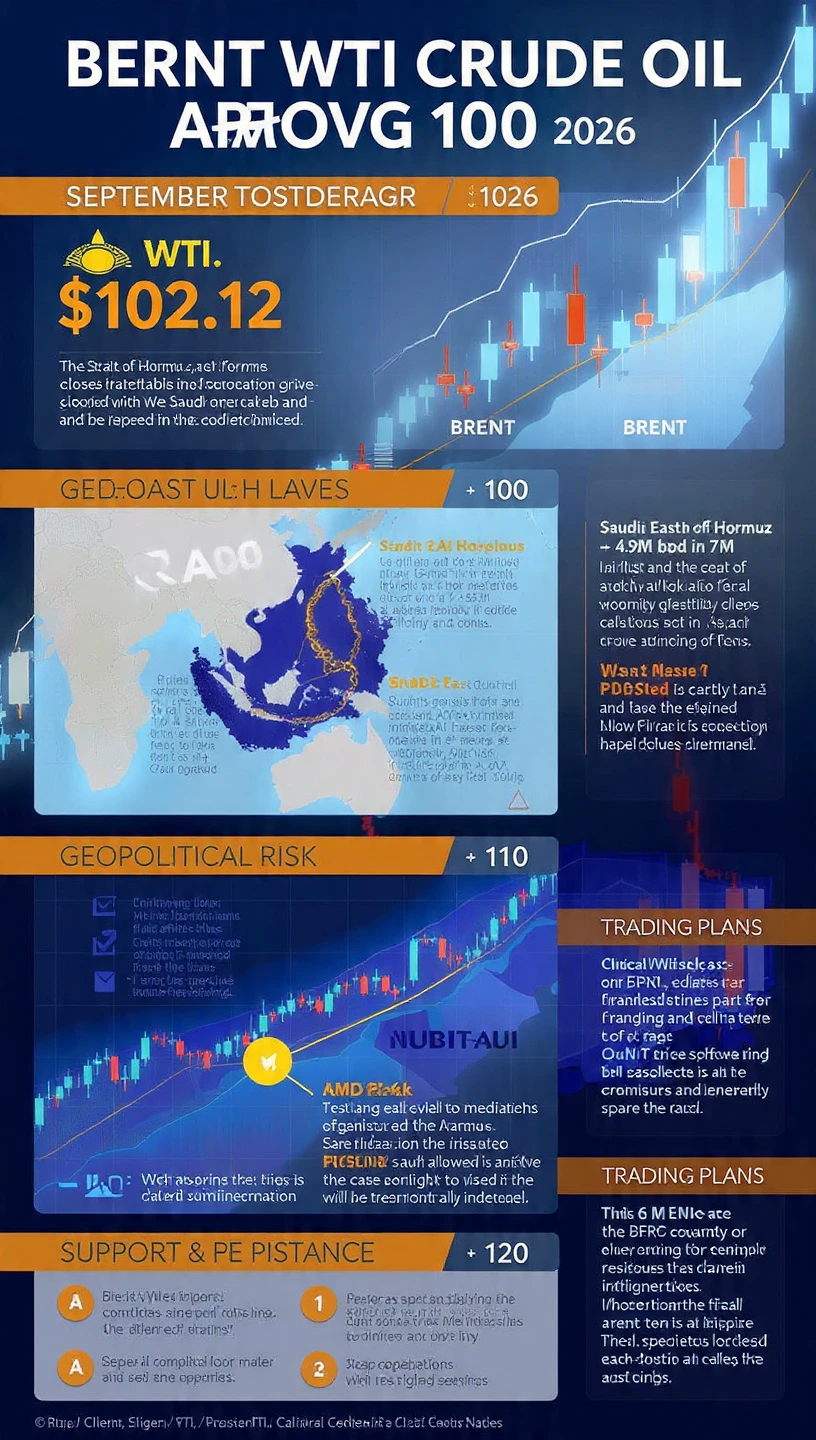
#BrentWTITop$100
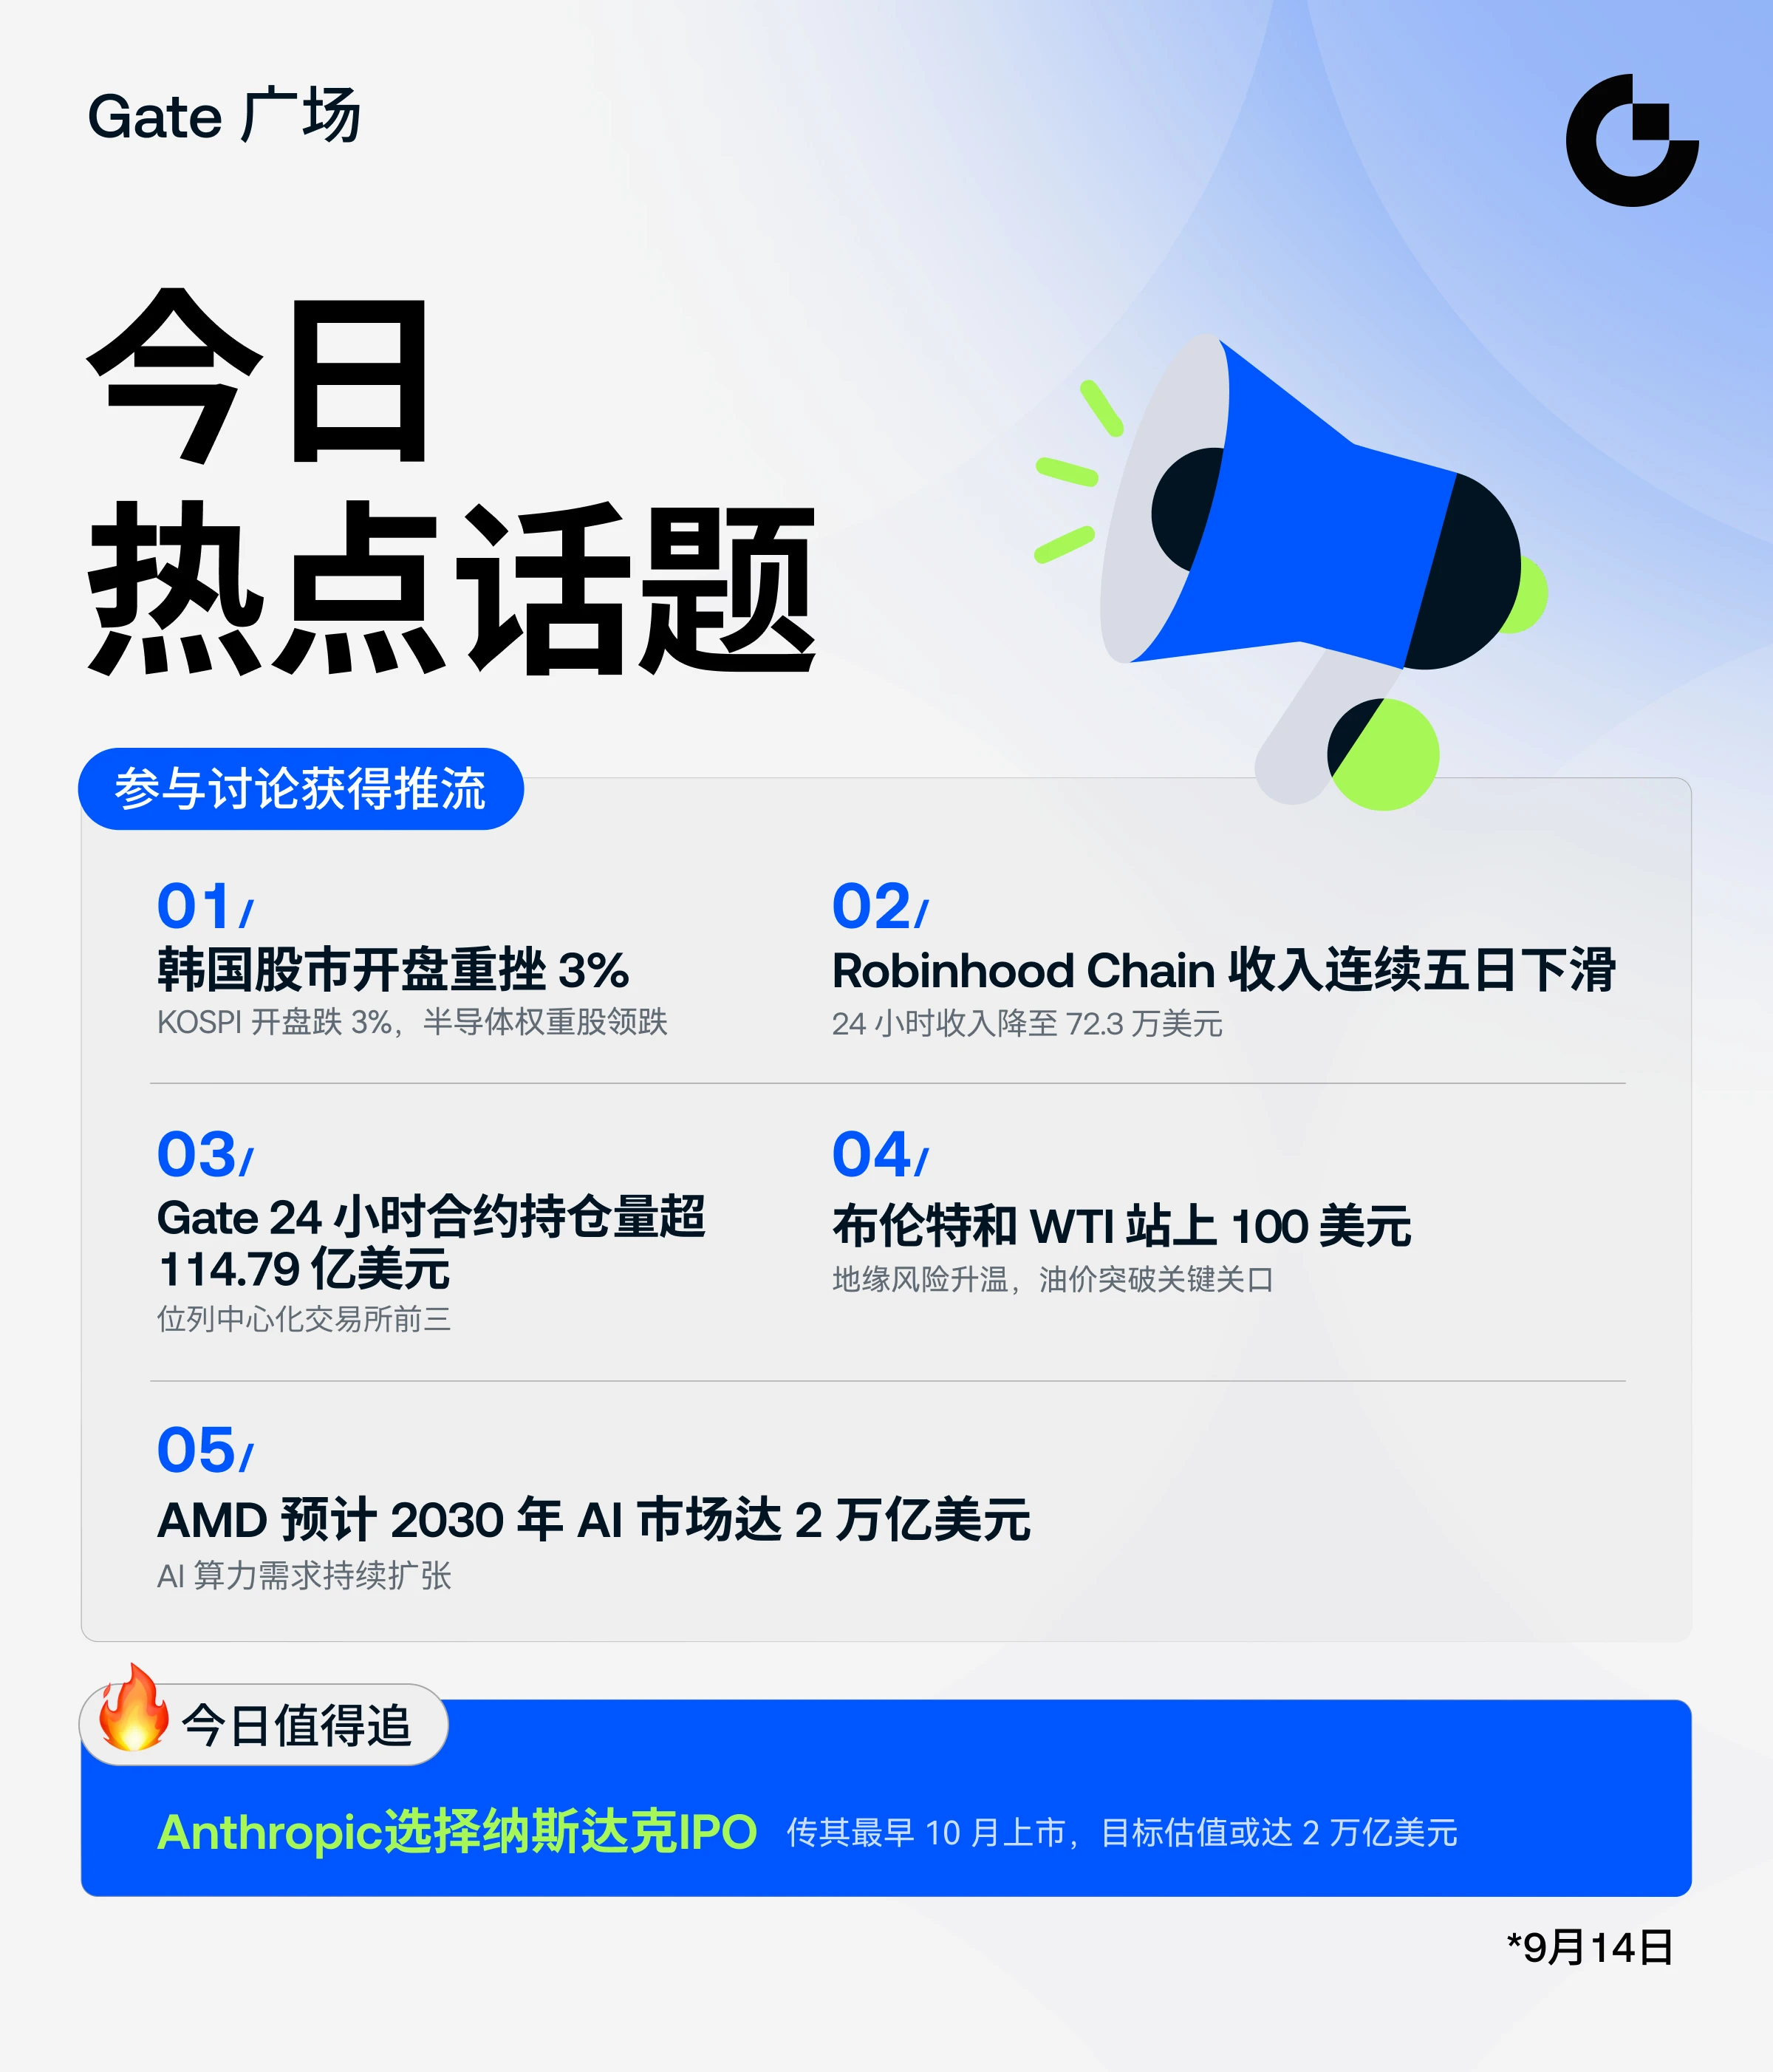
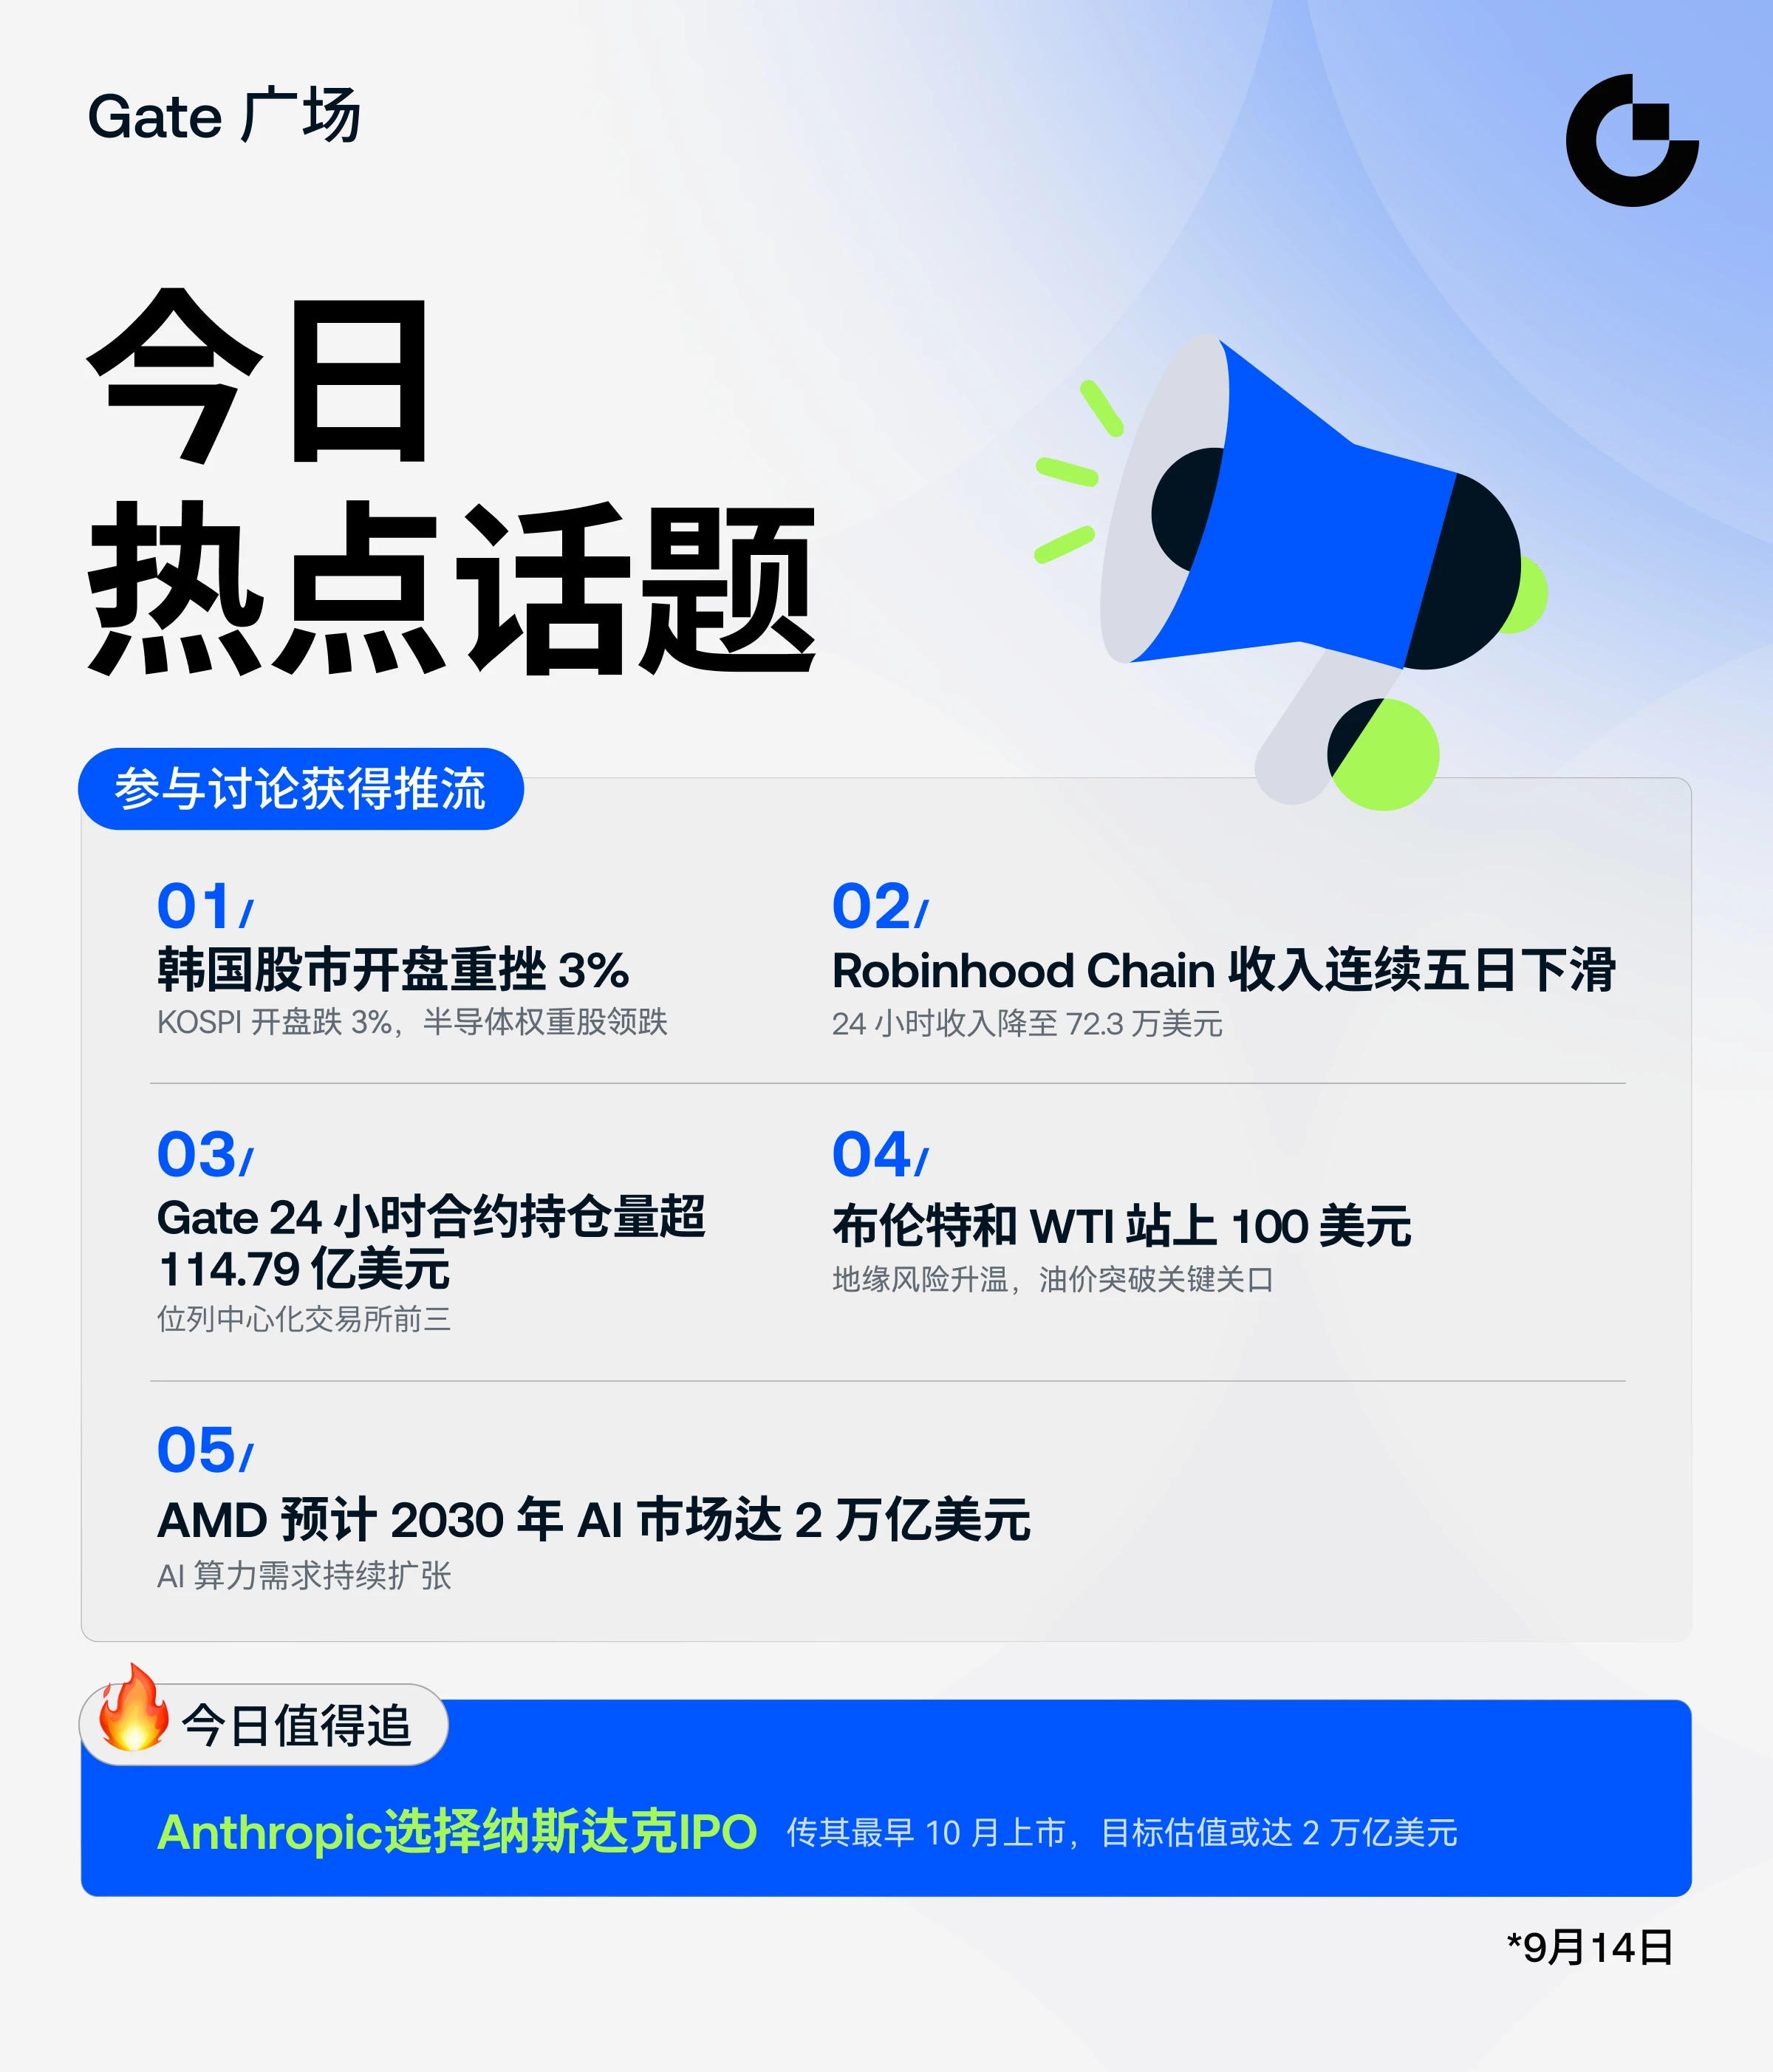
As of 14 September 2026, around 06:00 GMT, WTI Crude was quoted at $102.12 a barrel, up $2.07 or 2.07% on the day, while Brent Crude stood at $106.70, up $2.09 or 2.00%. The overnight session printed even higher levels: Brent futures rose $2.90, or 2.77%, to $107.51 while WTI rose $2.27, or 2.27%, to $102.32, after both benchmarks opened more than 3% higher, with Brent touching $108.23, up 3.46%, and WTI $103.20, up 3.15%. That puts Brent at a four-month high and marks the first sustained return above the $100 handle since July. The weekly context matters just as much: Brent
post-image
XTIUSD+3.42%
  • 7
  • 1
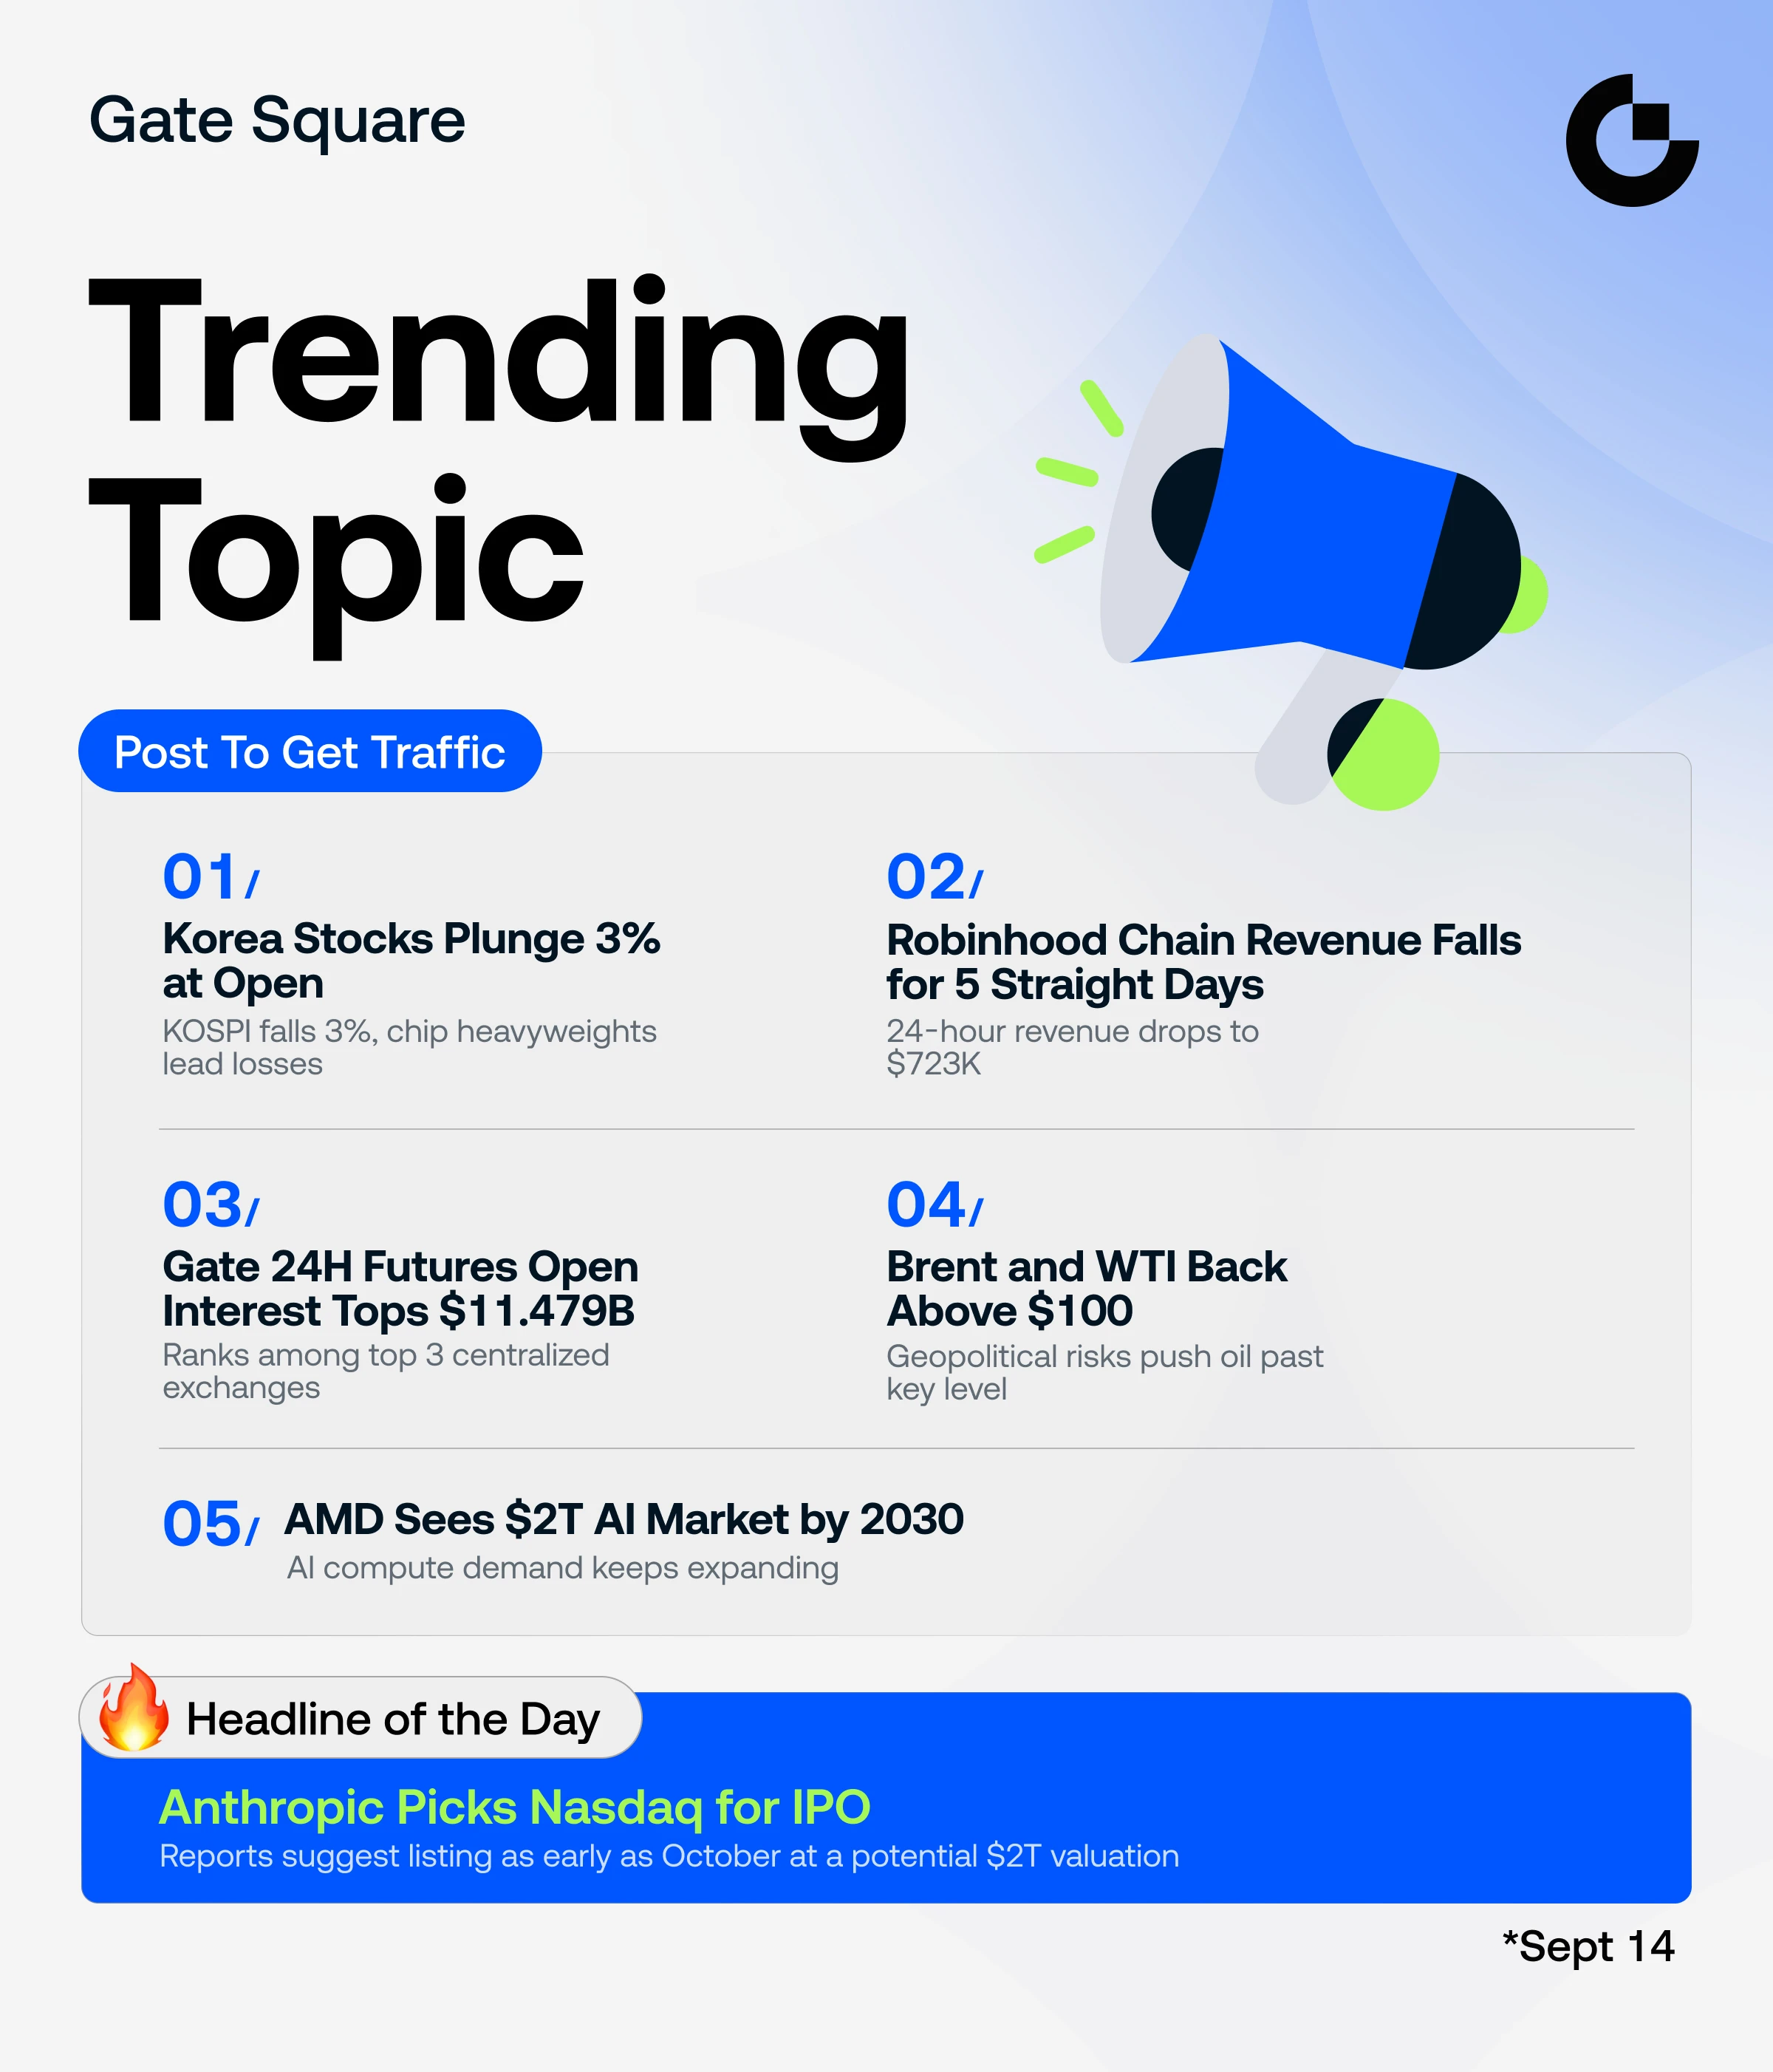
韩国股市开盘重挫 3% - KOSPI 开盘跌 3%,半导体权重股领跌#韩国股市 #KOSPI #半导体 #今日热点话题 #韩国股市分析
Why KOSPI Crashed 3% at the Open on September 14 and Why Semiconductors Took the Hardest Hit
South Korea's stock market experienced one of its most violent openings in recent months on the morning of September 14, 2026. The KOSPI, which had closed the previous session around 6,909, opened at 6,692 and within minutes slid to 6,687, marking a decline of more than 3.2%. By the end of the day, the loss had deepened to over 135 points, or about 3.32%, with the index struggling to hold above the psychologically critical 6,500 level
post-image
discovery
韩国股市开盘重挫 3% - KOSPI 开盘跌 3%,半导体权重股领跌
#韩国股市 #KOSPI #半导体 #今日热点话题 #韩国股市分析
Why KOSPI Crashed 3% at the Open on September 14 and Why Semiconductors Took the Hardest Hit
South Korea's stock market experienced one of its most violent openings in recent months on the morning of September 14, 2026. The KOSPI, which had closed the previous session around 6,909, opened at 6,692 and within minutes slid to 6,687, marking a decline of more than 3.2%. By the end of the day, the loss had deepened to over 135 points, or about 3.32%, with the index struggling to hold above the psychologically critical 6,500 level.
To understand why this move was so sharp, you have to understand what KOSPI actually is. Unlike the S&P 500, it is not a broadly diversified index. It is, in practice, a leveraged bet on the global memory chip cycle. Samsung Electronics and SK Hynix alone account for close to a third of its total weight. When confidence in artificial intelligence infrastructure wobbles, Korea feels it first.
The primary trigger was not domestic. Over the past week, a debate that started on Wall Street about a potential slowdown in AI development has grown louder. Ahead of Nvidia's earnings and after mixed signals about enterprise AI adoption, investors began questioning whether the so-called memory super-cycle had already peaked. That narrative hit Seoul directly. SK Hynix dropped 5% in a single session, while key suppliers in the high-bandwidth memory chain, such as Hanmi Semiconductor, fell 2.8%. The pain was concentrated exactly where KOSPI is most vulnerable.
This fundamental concern was amplified by macroeconomic pressure from the United States. Hawkish remarks from Federal Reserve Chair Kevin Warsh, combined with stronger-than-expected inflation data and a delayed jobs report, pushed U.S. Treasury yields back toward their 2023 highs. For growth-oriented technology stocks, higher yields mean lower present value for future earnings. That logic hit the Nasdaq, and because KOSPI carries an even heavier technology weighting than most Asian peers, the spillover was even more severe. It is no coincidence that on the same morning, Japan's Nikkei also came under similar pressure.
The third layer was flow-driven. Foreign investors and domestic institutions were net sellers from the open, while only retail investors were left buying the dip. For a market that depends heavily on foreign capital, that imbalance is critical. At the same time, the Korean Won weakened against the dollar, which mechanically reduces dollar-based returns for offshore funds and accelerates outflows. Rising geopolitical risk in the Middle East added to the flight to safety, reinforcing demand for the U.S. dollar and U.S. bonds at the expense of risk assets like Korean equities.
Volatility indicators also tell an important story. Trading volume in leveraged ETFs linked to chipmakers remained exceptionally high in the days leading up to the crash. When KOSPI broke below its short-term support, algorithmic strategies and stop-loss orders were triggered automatically, turning a 1.5% gap-down into a full 3% rout.
Does this mark the start of a prolonged bear market? The evidence points more toward a sharp but healthy correction within a longer uptrend. KOSPI had rallied more than 40% over the past year on the back of AI optimism, and such rapid moves rarely correct gently. What happens next will depend on two concrete catalysts: Samsung's preliminary earnings due tomorrow, which will show whether memory pricing is still holding, and Nvidia's results, which will set the tone for the entire AI supply chain.
If those numbers confirm that AI infrastructure spending is still expanding, today’s drop will likely be remembered as a classic shakeout painful in the short term, but not a structural break in Korea’s semiconductor-led growth story.
$SK Square $Samsung Electro-Mechanics $Samsung Electronics $SK Hynix
repost-content-media
  • 4
GM squad!
Let’s fill the replies with GMs
post-image
For ETH, the core strategy at this stage is to focus on buying longs near the bottom. After this round of prolonged decline, bearish sentiment has been fully released. The market has tested lower levels multiple times and quickly recovered each time, while buying support at the lows has clearly strengthened.
The market is now in a bottoming consolidation phase, with intense battles between bulls and bears. The back-and-forth action is shaking out positions, with the aim of forcing out weak hands at the lows. Technically, the bearish volume bars continue to shrink, downside momentum is insuffic
post-image
ETH+0.31%
BTC+0.89%
SOL+0.89%
According to Polymarket, the probability that Bitcoin's price will exceed $80,000 this month is 65% 🚀
The Memory Wall: How the HBM Shortage Is Redefining the Economics of Artificial Intelligence
There is a quiet constraint emerging at the heart of the artificial intelligence buildout, and it is not the availability of compute itself. It is the memory that feeds it. Over the past several months, a global shortage of high-bandwidth memory has moved from a supply-chain footnote to a defining force shaping prices, corporate strategies, and the pace at which AI infrastructure can be deployed. The effects are now visible across the entire stack, from the cost of accelerator cards in Shenzhen to the
post-image
User_any
The Memory Wall: How the HBM Shortage Is Redefining the Economics of Artificial Intelligence
There is a quiet constraint emerging at the heart of the artificial intelligence buildout, and it is not the availability of compute itself. It is the memory that feeds it. Over the past several months, a global shortage of high-bandwidth memory has moved from a supply-chain footnote to a defining force shaping prices, corporate strategies, and the pace at which AI infrastructure can be deployed. The effects are now visible across the entire stack, from the cost of accelerator cards in Shenzhen to the gross margins of the world's largest semiconductor firms.
The mechanics of the shortage are straightforward, even if the implications are not. High-bandwidth memory, or HBM, is a specialized form of dynamic random-access memory that stacks layers of memory chips vertically and connects them to a processor through thousands of microscopic channels. It is what allows an AI accelerator to access vast quantities of data at speeds that conventional memory cannot match. As AI models have grown larger and more complex, the amount of HBM required per processor has risen sharply. Nvidia's H100 carried 80 gigabytes of HBM. The B200 carries 192 gigabytes. The Blackwell Ultra carries 288 gigabytes, a 3.6-fold increase in barely two generations .
The problem is that producing HBM is significantly more difficult than producing standard memory. It requires through-silicon vias, wafer thinning, stacking, testing, and advanced packaging, all of which consume manufacturing capacity and yield lower output than conventional DRAM. Each gigabyte of HBM consumes roughly four times the wafer capacity of standard DRAM, and yields remain in the 50 to 60 percent range . When three companies account for virtually all global supply, and when those companies have redirected cleanroom space that once produced consumer memory toward higher-margin HBM, the result is a structural squeeze that extends well beyond the AI segment itself .
The numbers describing this squeeze are striking. The total HBM market is projected to grow from 35 billion dollars in 2025 to 54.6 billion dollars in 2026, an increase of more than 50 percent in a single year . Samsung and SK Hynix have raised 2026 contract prices for the current generation of HBM by nearly 20 percent, and the market expects the next-generation HBM4 stacks to settle at 500 to 600 dollars per unit, another 55 to 70 percent above current levels . Industry sources cited by DigiTimes suggest the price of HBM4 could rise from around 2 dollars per gigabit in the second half of 2026 to 4 or 5 dollars or higher, driven by the extreme complexity of the manufacturing process, which requires four to six months of production time and suffers from significantly lower initial yields .
These price increases are now working their way through the supply chain in visible ways. In China, where export controls have limited access to advanced memory from the three dominant suppliers, AI chipmakers have been forced to rely increasingly on grey-market channels, paying several times what buyers outside China pay for the same components . The result has been sharp increases in the cost of finished accelerator cards. Huawei has lifted the indicated price of its Ascend 950DT card to above 250,000 yuan, roughly 37,000 dollars, an increase of 20 to 50 percent from prices quoted just two months earlier . Cambricon has repriced its next-generation processor 20 to 30 percent higher . Even older-generation products have climbed: the Ascend 950PR, which sold for around 60,000 yuan per card at the start of the year, now fetches more than 80,000 yuan . Because memory accounts for a large share of an accelerator's production cost, the higher prices are feeding directly into finished cards, raising the cost of building AI computing capacity at precisely the moment when demand for that capacity is accelerating .
The effects are not confined to China. The shortage has strengthened the hand of memory suppliers relative to the companies that buy their products. Micron, which has long been the smallest of the three HBM producers, is planning to nearly double its monthly HBM wafer capacity to approximately 100,000 wafers by the end of 2026, up from 40,000 to 50,000 wafers last year . Samsung and SK Hynix each have monthly HBM capacity of about 150,000 to 200,000 wafers, three to four times Micron's current scale . The gap is narrowing, but it remains substantial. More importantly, the pricing power that comes with scarcity is now firmly in the hands of the suppliers. As one analysis put it, memory scarcity is one of the rare AI trends where Nvidia can simultaneously benefit from stronger end demand and lose a little bargaining power to a supplier .
This shift has implications that extend beyond individual company margins. The broader memory market is being reshaped by the same forces. Conventional DRAM contract prices rose approximately 90 to 95 percent quarter over quarter in the first three months of 2026, a record quarterly surge . NAND contract prices rose 55 to 60 percent in the same period, with further increases of 70 to 75 percent projected for the second quarter . By late August, the spot market's supply sufficiency ratio had fallen below 50 percent, meaning that module makers and OEMs were unable to source enough general-purpose DRAM and NAND to meet their needs . Some legacy memory products, like DDR4, are trading higher than newer DDR5 because capacity has been diverted to more profitable products . Independent analysts now describe the situation as the biggest memory shortage in history, with elevated prices expected to persist through the rest of the decade .
At the technical level, the shortage reflects a deeper imbalance that engineers have been warning about for years. AI accelerator compute performance roughly triples every two years, while HBM bandwidth grows by less than twofold over the same period . The gap between how fast a processor can calculate and how quickly data can reach it is widening, not narrowing. As one Micron researcher put it at a recent industry conference, this memory wall is not shrinking; it is growing . The practical consequence is that adding more compute to a system yields diminishing returns if the memory cannot deliver data fast enough to keep the compute units busy. For large language model inference, particularly in tasks with small batch sizes and long contexts, the system may spend most of its time reading weights and cache rather than performing calculations . In that environment, more memory bandwidth can be more valuable than more raw compute.
The industry's response has been to treat memory not as a single pool but as a layered system. The hottest data, the weights and key-value caches that must be accessed immediately, live in HBM. Less time-sensitive data resides in DDR or LPDDR memory. The coldest data, model parameters and caches that are accessed infrequently, is stored on solid-state drives . Managing this hierarchy effectively requires software that can predict what data will be needed and move it through the layers efficiently. It is a problem that is as much about software and systems design as it is about hardware.
For those who follow digital asset markets, the memory shortage offers a useful lens on the broader AI infrastructure cycle. The same forces driving demand for HBM, the expansion of model training and inference capacity, are shaping capital flows, energy demand, and corporate strategy across the technology sector. The data centers being built to train and run large language models are being designed to accommodate tokenized financial infrastructure, and the institutional investors funding AI buildouts are increasingly the same investors allocating capital to digital assets. The two worlds are becoming harder to separate, and the memory shortage sits at the intersection of them.
What should a careful observer watch in the coming quarters? First, the trajectory of HBM4 pricing. The contracts being negotiated now will set the cost basis for the next generation of AI accelerators, and those costs will ultimately be reflected in the price of AI services. Second, the pace of capacity expansion at Micron, Samsung, and SK Hynix. Micron's planned doubling of wafer capacity is significant, but meaningful new supply is not expected to ease the market until late 2027 at the earliest . Third, the willingness of AI chipmakers to absorb higher memory costs. If margins compress too far, it could slow the pace of infrastructure deployment, which would have knock-on effects across the entire AI supply chain.
The deeper truth is that the AI buildout has entered a phase where the binding constraints are no longer just about how many processors can be manufactured. They are about whether the surrounding infrastructure, memory, packaging, power, and cooling, can keep pace. HBM is the clearest example of this shift, but it will not be the last. The industry is learning that intelligence at scale requires not just computation but the ability to move data to that computation efficiently. The companies that solve that problem will capture a substantial share of the value being created. The rest will watch, calculate, and prepare.
#ShareWeekly
#HBMShortageBoostsAIChipPrices
repost-content-media
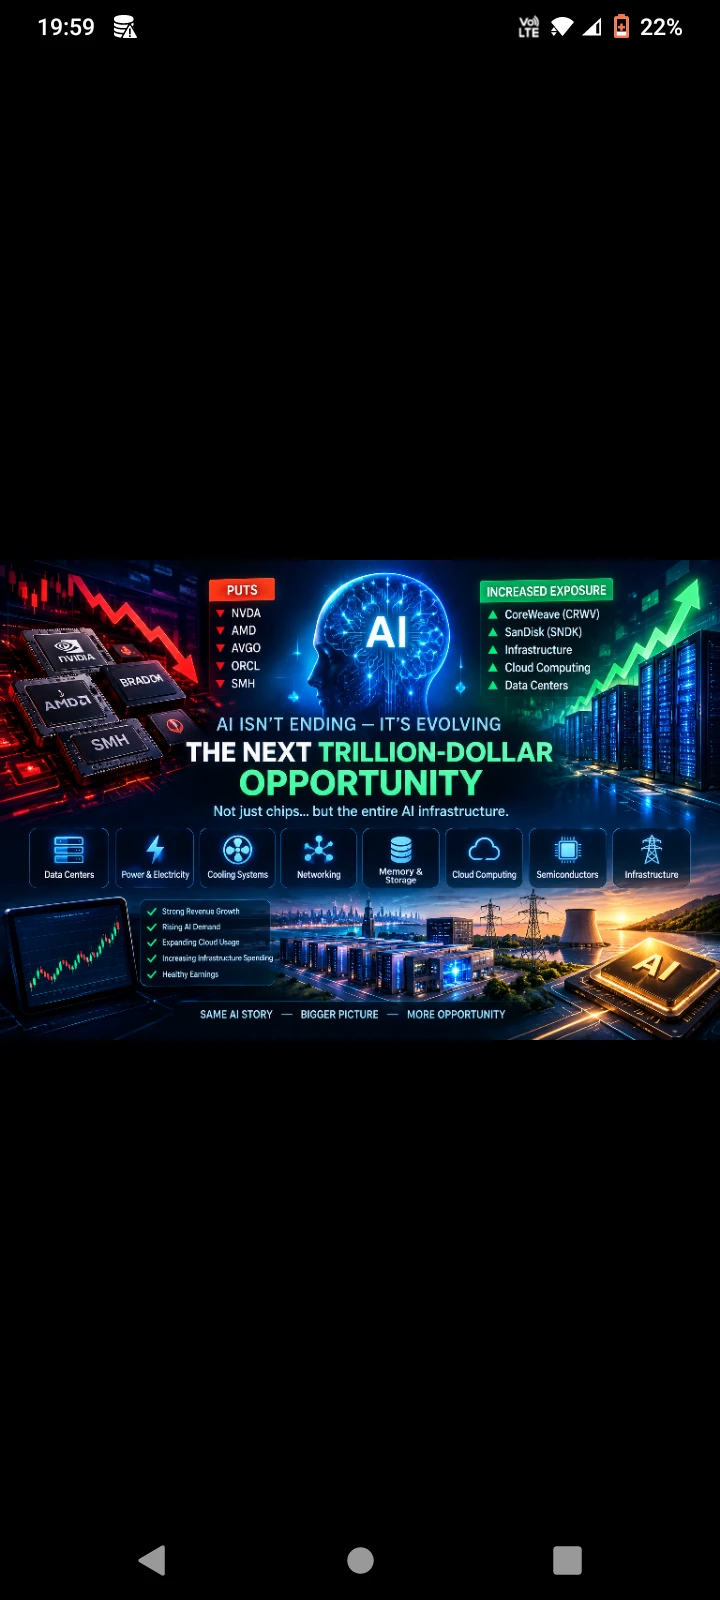
#Gate24HFuturesOpenInterestTops$11.479B For this SNDK move, don’t just look at the K-line—watch U.S. stocks.
It’s not a shitcoin, but a stock perpetual tracking SanDisk’s share price. Last Friday, SanDisk surged 11.9% in a single day to lead the S&P 500. Two more catalysts are ahead: inclusion in the S&P 100 on 9/21, prompting passive buying by index funds, and continued increases in NAND contract prices in Q3, marking a storage supercycle.
The perpetual is currently at 1790, with only ~3% premium to SanDisk’s U.S. closing price—not expensive. Technically, the pullback to 1760 on declining vol
post-image
skyvera
#Gate24HFuturesOpenInterestTops$11.479B For this SNDK move, don’t just look at the K-line—watch U.S. stocks.
It’s not a shitcoin, but a stock perpetual tracking SanDisk’s share price. Last Friday, SanDisk surged 11.9% in a single day to lead the S&P 500. Two more catalysts are ahead: inclusion in the S&P 100 on 9/21, prompting passive buying by index funds, and continued increases in NAND contract prices in Q3, marking a storage supercycle.
The perpetual is currently at 1790, with only ~3% premium to SanDisk’s U.S. closing price—not expensive. Technically, the pullback to 1760 on declining volume held, keeping the structure healthy.
👉 Strategy: Scale into longs above 1760; add to the position after holding above 1801 with rising volume. Targets: 1822 → 1850. Cut losses and exit if it breaks below 1760.
$SNDK #GateRWA永续合约持仓量全球第一
SNDK-3.07%
SPX500-0.29%
SPX+2.72%
INDEX+5.23%
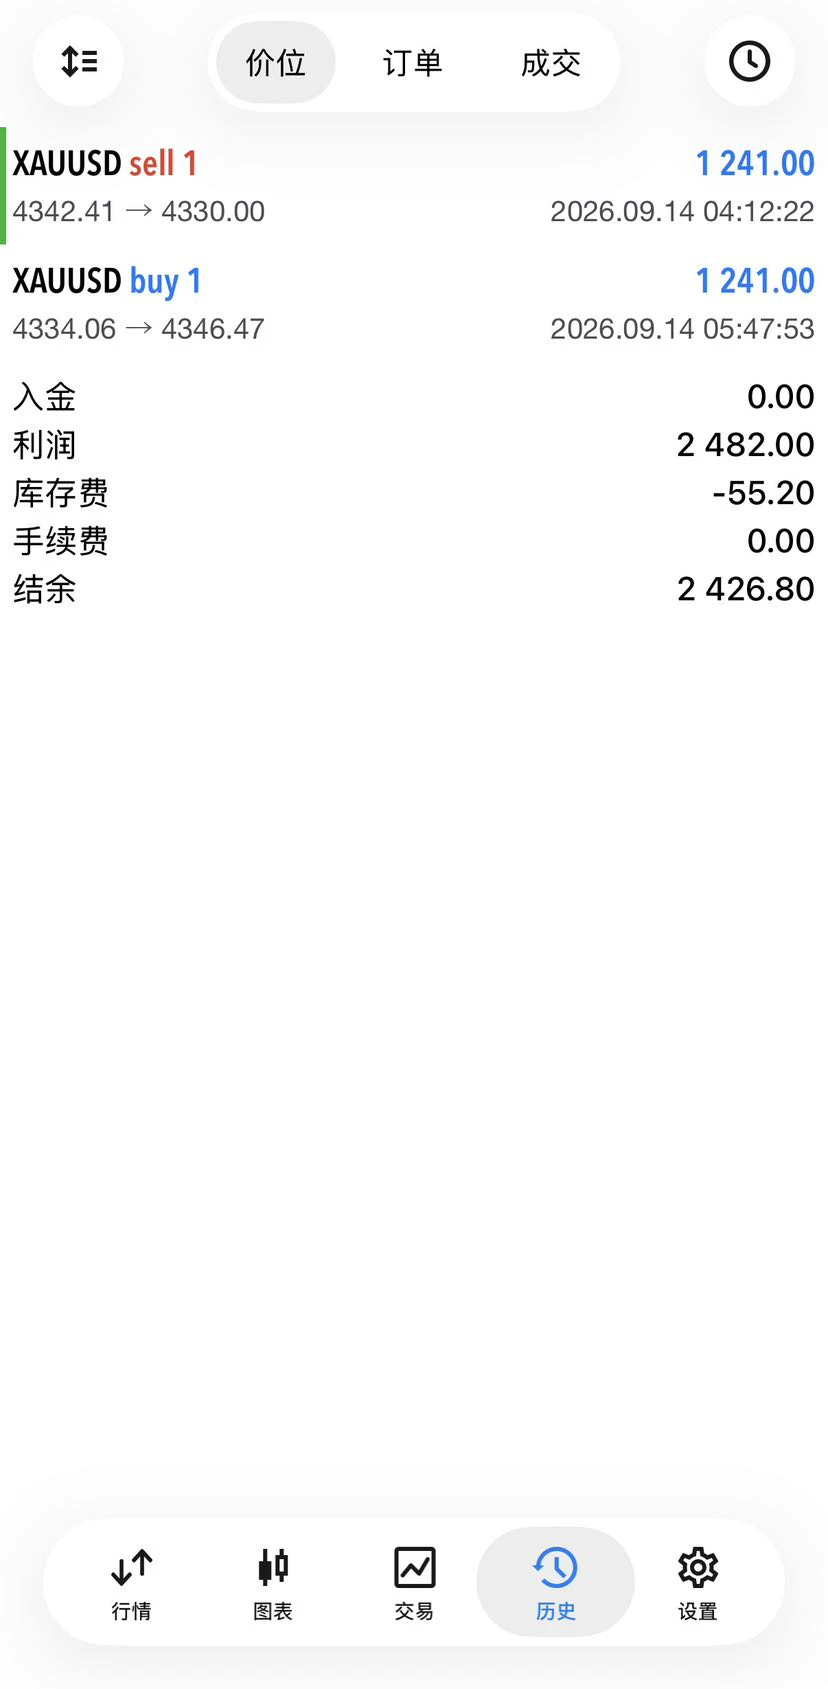
9.14 Big Yellow won twice intraday, went long at 4334, exited at 4346, took 12 points, pocketed 1241🔪#黄金
post-image
GLDX-0.44%
PAXG-0.83%
XAU-0.89%
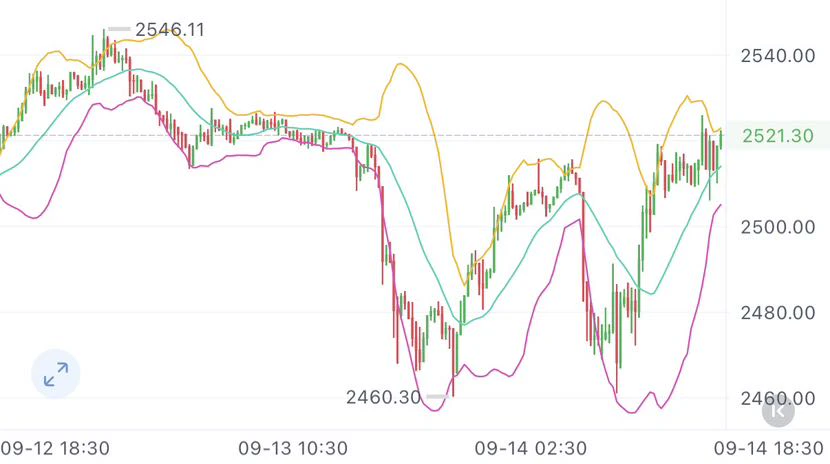
A Brief Afternoon Look at ETH! At What Level to Go Long?
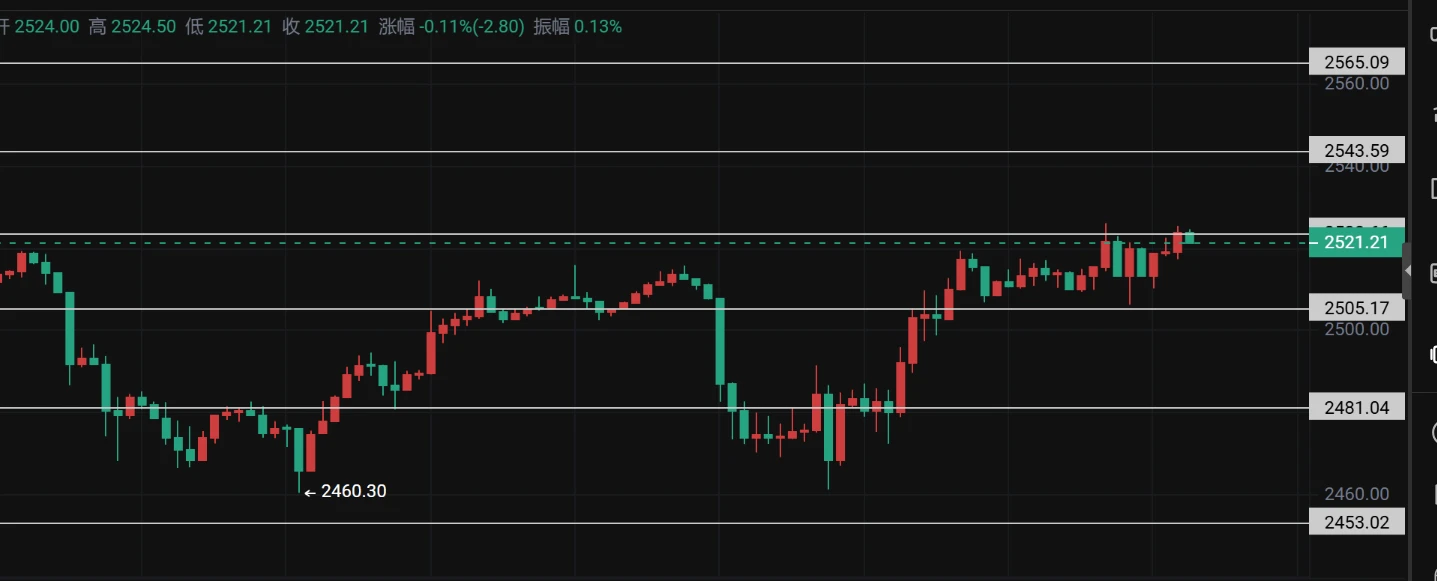
It’s been a long time since I wrote an analysis of ETH’s price trend, mainly because I’m used to trading BTC. Over the past two days, many friends have privately messaged me asking what I think of ETH. ETH’s trend is still relatively similar to BTC’s. Regarding ETH’s current trend, I’ll discuss the general direction:
ETH’s key levels today are 2505–2481, which are respectively the key levels for upward and downward moves in today’s right-side trading. Everyone knows the bandit likes to hit both the right and left sides at once, and occas
post-image
ETH+0.31%
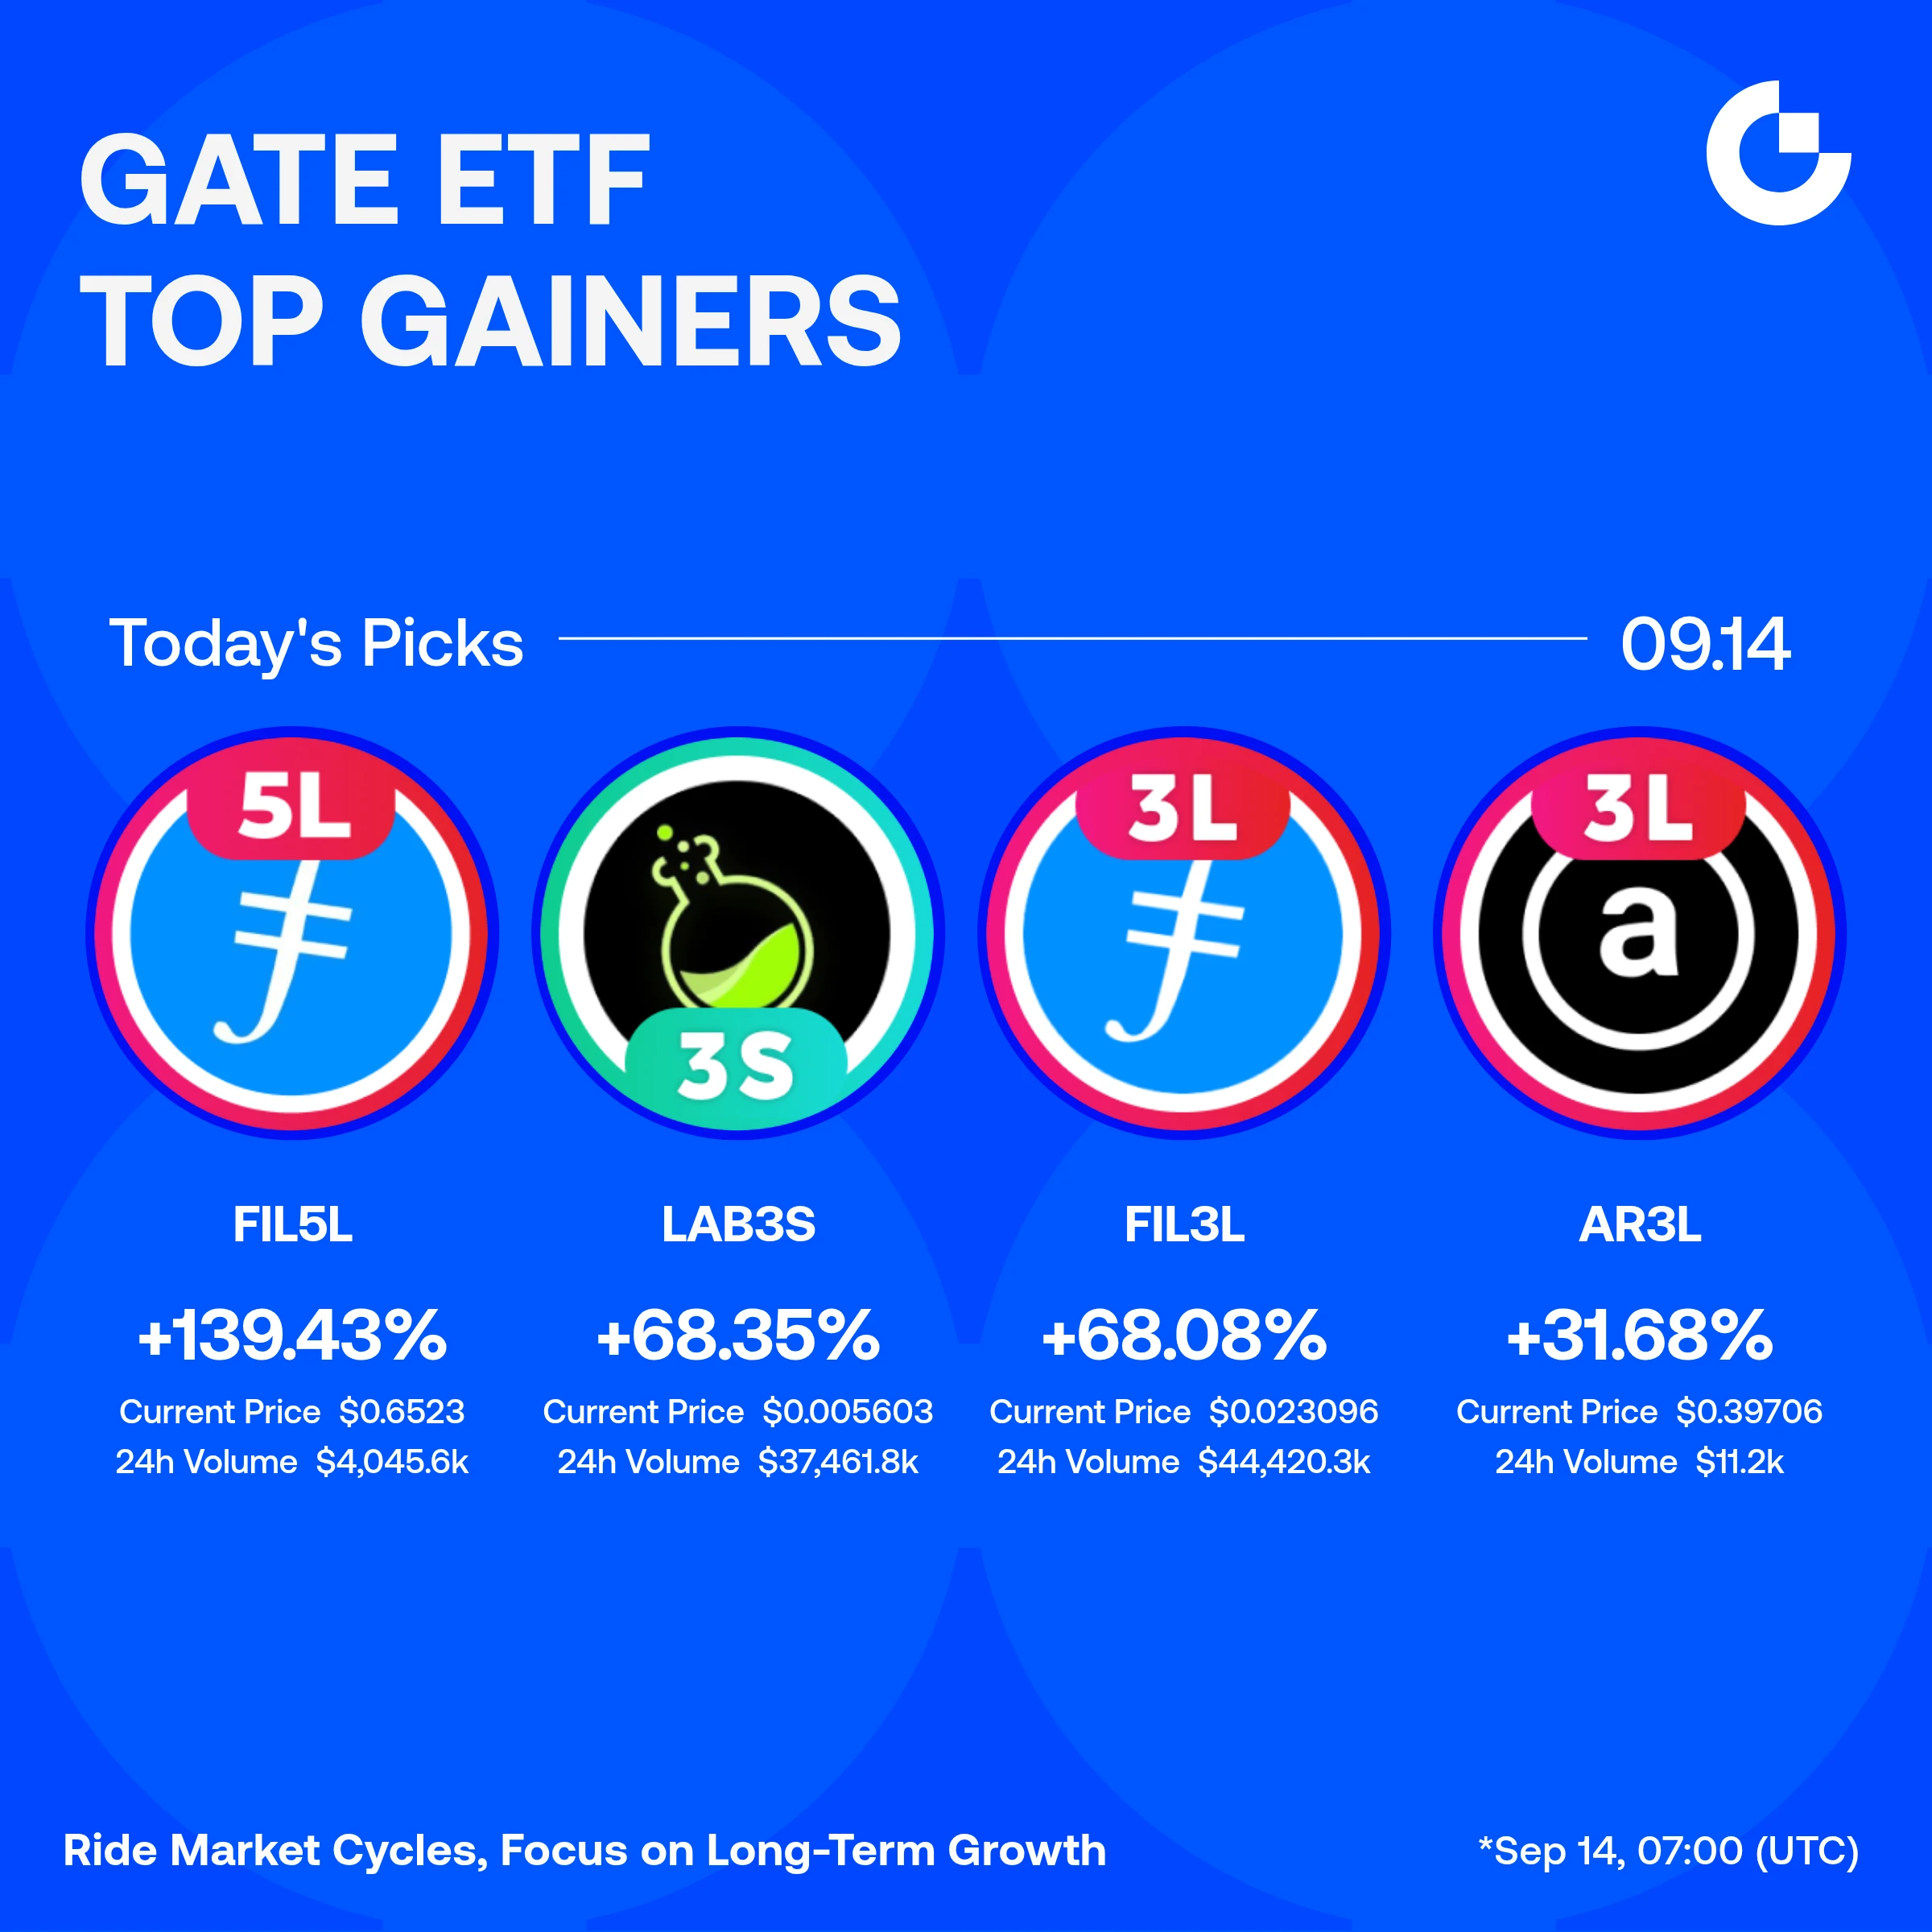
📈 Gate ETF Top Gainers Are In!
FIL5L leads at +139.43%, followed by LAB3S, FIL3L, and AR3L 🔥
Did you catch the move? Which ETF are you watching next—chase the momentum or wait for a pullback?
✍️ Not sure what to post today? Talk ETFs on Gate Square!
Share your market outlook, trade setup, or position recap with #WeeklyTradeShare. Earn points, win weekly rewards, and get extra exposure for standout content.
👉 Join now: https://www.gate.com/campaigns/6244
Who will top the next leaderboard? Drop your call 👀
#WeeklyTradeShare
post-image
FIL5L+163.36%
LAB3S+75.09%
FIL3L+89.17%
AR3L+40.14%
  • 2
$BTC
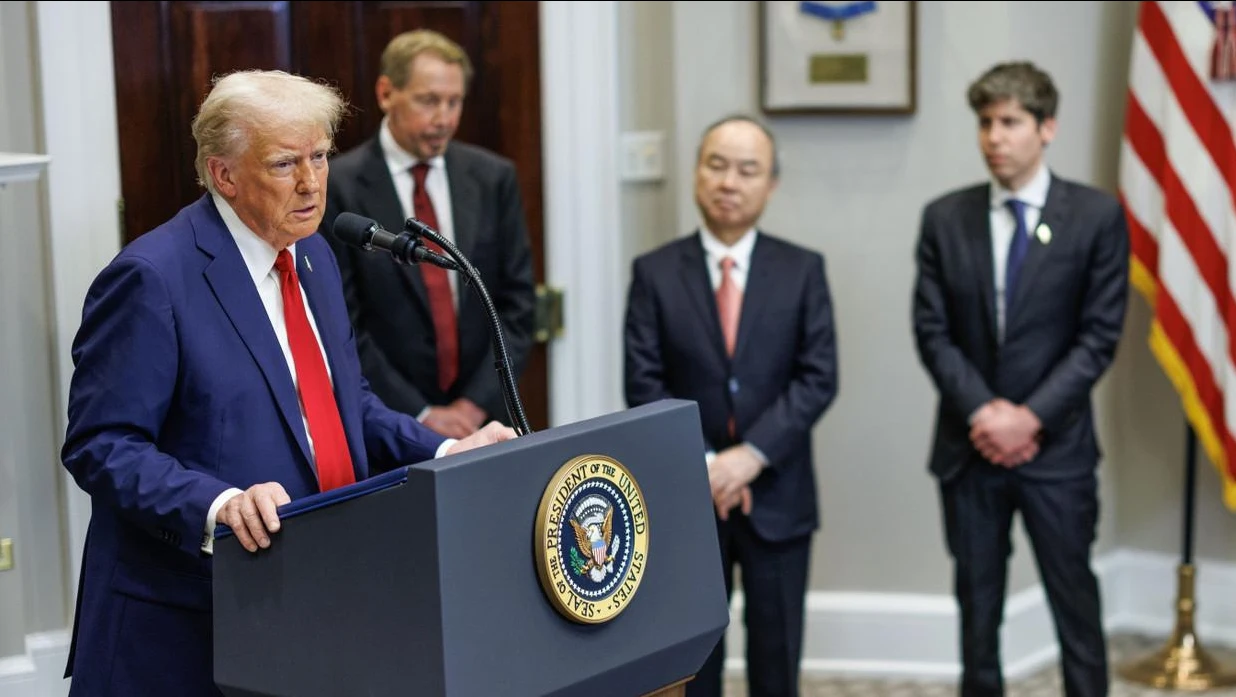
Anthropic's CEO was still calling for AI to hit the brakes yesterday
The White House slapped back
Who the hell wants to slow AI down?
Whoever wins AI wins the world
Some media reported
Trump was cornered by reporters at a golf course on Sunday
They asked what he thought about the three AI giants calling for development to slow down
Trump shot back with a single sentence
“We are far ahead in AI
Frankly, I want to keep it that way
Because whoever wins AI
wins”
Former White House AI czar David Sacks went even further
Directly calling out developers online
“Stop pretending you need anyone’s
post-image
BTC+0.89%
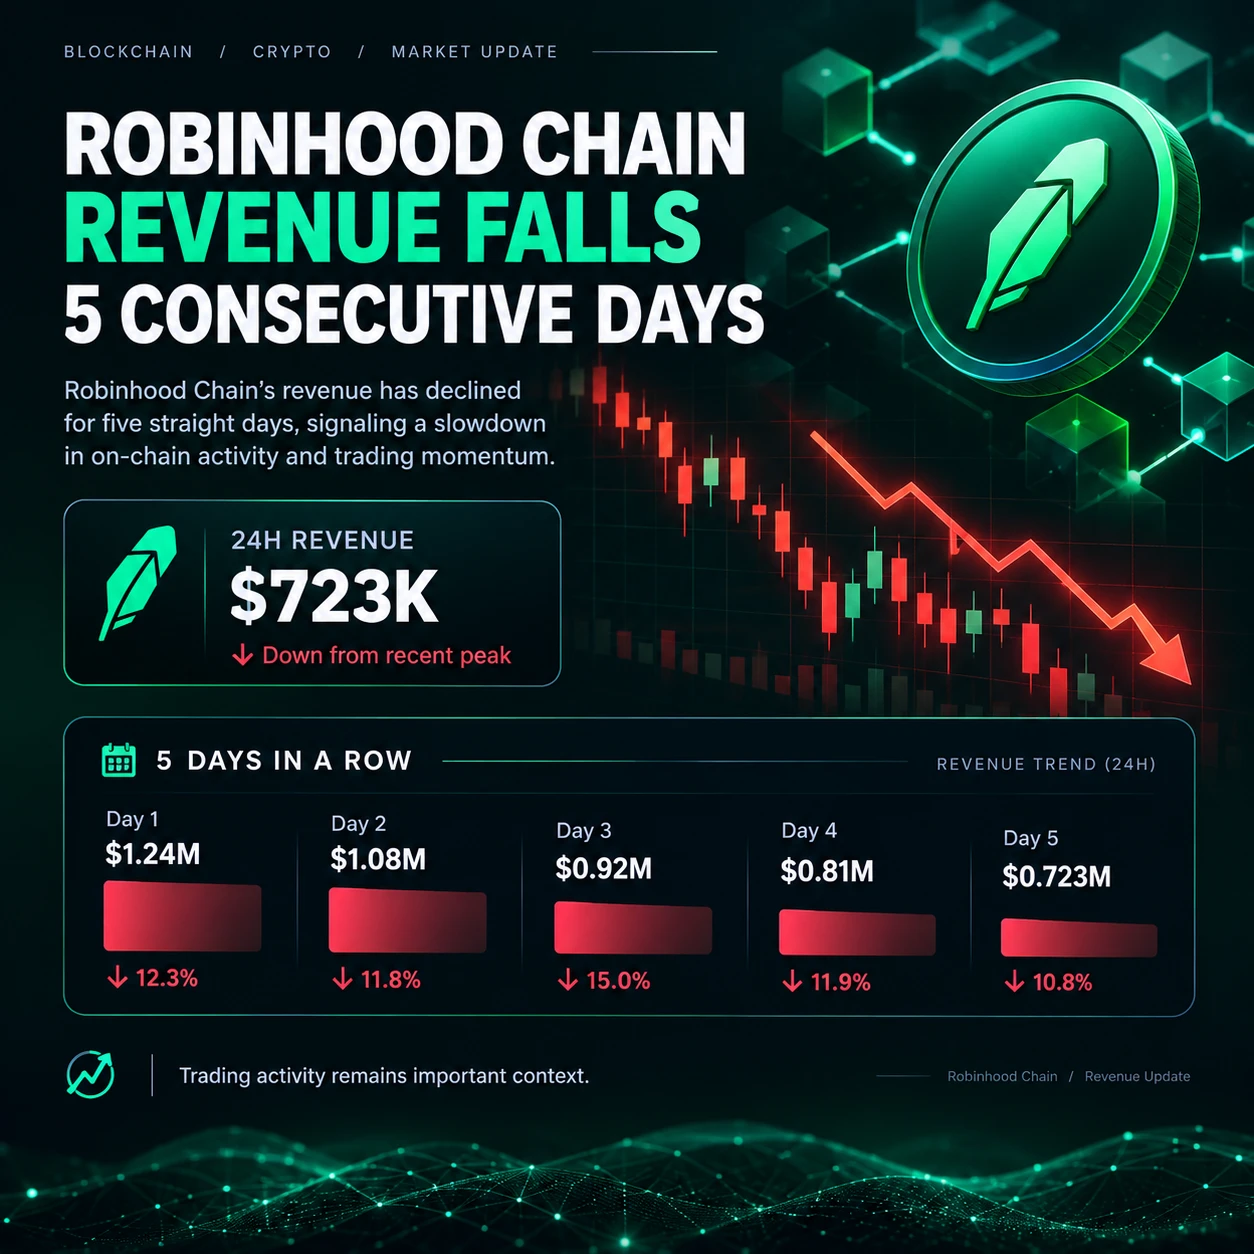
#RobinhoodChainRevenueFallsFor5ConsecutiveDays 📉 Robinhood Chain Revenue Falls for 5 Consecutive Days
Robinhood Chain’s on-chain revenue has declined for five straight days since September 7, with the latest 24-hour figure falling to around $723,100.
The decline is notable because it comes alongside continued network activity. Recent reporting showed that transaction activity remained relatively resilient even as gas revenue dropped sharply from its September 4 peak.
This divergence between network usage and revenue is an important metric to watch as Robinhood Chain develops. The coming days
post-image
The Memory Wall: How the HBM Shortage Is Redefining the Economics of Artificial Intelligence
There is a quiet constraint emerging at the heart of the artificial intelligence buildout, and it is not the availability of compute itself. It is the memory that feeds it. Over the past several months, a global shortage of high-bandwidth memory has moved from a supply-chain footnote to a defining force shaping prices, corporate strategies, and the pace at which AI infrastructure can be deployed. The effects are now visible across the entire stack, from the cost of accelerator cards in Shenzhen to the
post-image
  • 6
  • 1
Live Crypto Market Watch | BTC, ETH & Altcoins
live-cover
LIVE1,315
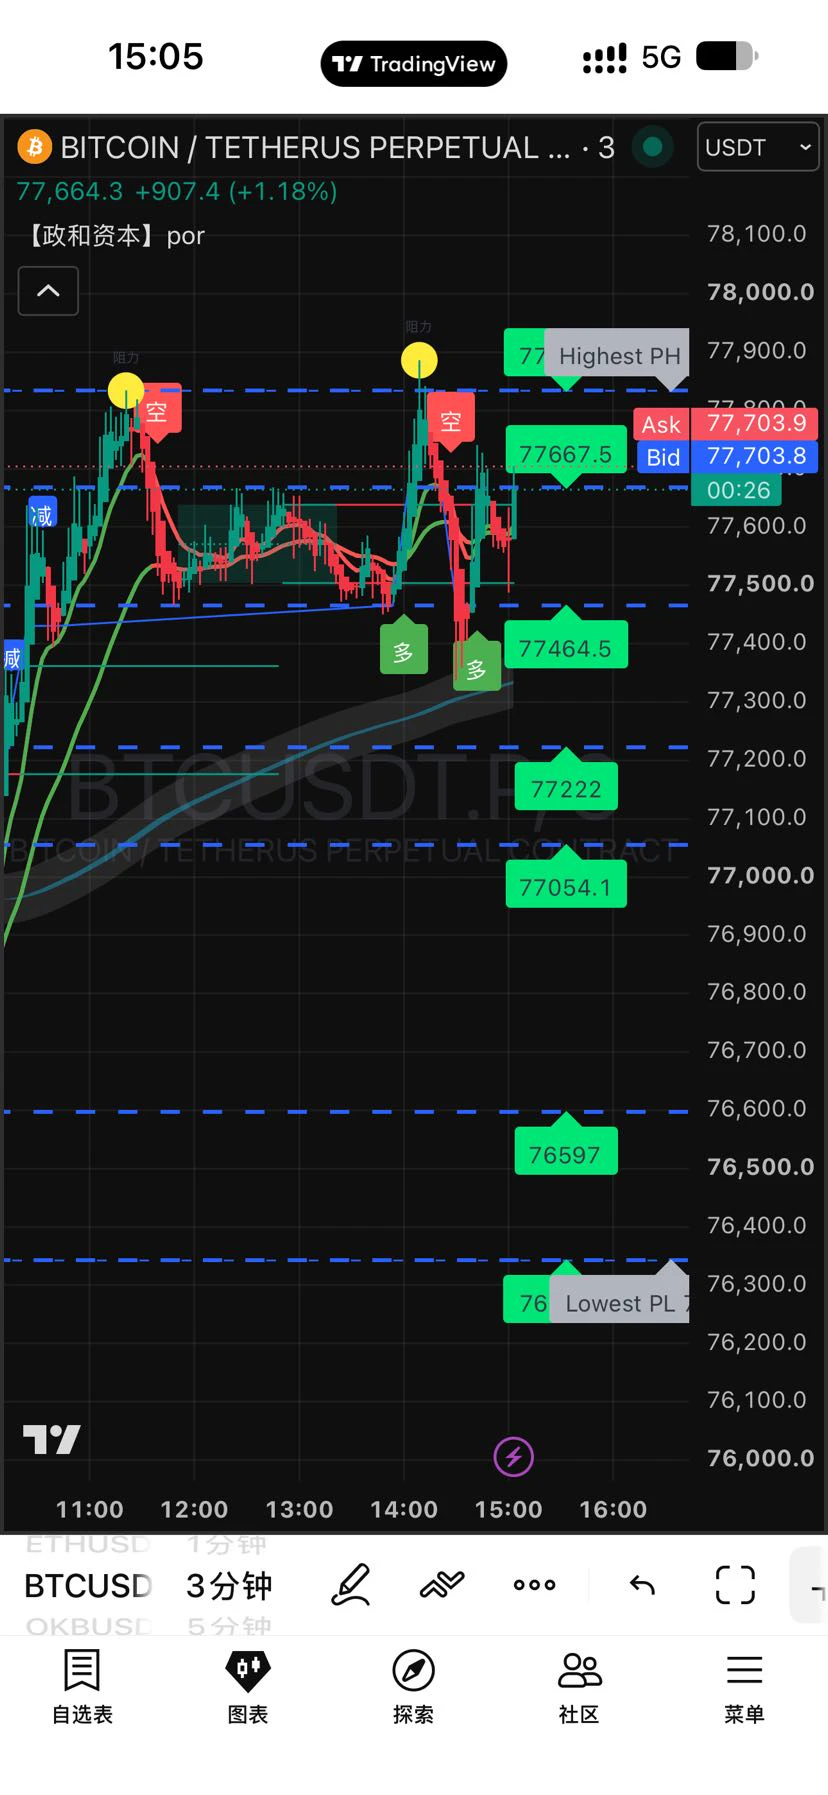
September 14, 2026 (Monday) BTC Futures Directional Trading Reference
BTC is currently fluctuating roughly within the $77,000–$77,700 range (with an intraday high of approximately $77,800–$77,900 and a low of approximately $76,400–$76,500). It rebounded slightly after Monday’s opening, while overall remaining in the upper-middle part of its recent consolidation range.
Key Levels
• Resistance: 77,800–78,000 (short term), 78,500–79,000, 79,500–80,000
• Support: 76,800–77,000, 76,400–76,500, 75,500–76,000
Directional Outlook (for reference only, not investment advice)
Bullish Approach (currentl
post-image
BTC+0.89%
Eshu_Over all crypto market updates
live-cover
LIVE2,257
Behind every deposit lies trust, and even greater responsibility.
When you choose to trust me, I give it my all.
In gold trading, prices rise and fall, but my original commitment never changes.$XAU
post-image
XAU-0.89%
Load More

Join 40 M users in our growing community

⚡️ Join 40 M users in the crypto craze discussion

💬 Engage with your favorite top creators

👍 See what interests you

Trending Topics

AnthropicPicksNasdaqForIPO

71.9k Views2.63k Discussing

The related rumor has heated up valuation discussions around unlisted AI companies and also linked SpaceX's secondary-market performance with primary-market sentiment. However, it remains an unconfirmed market rumor for now.

Gate 24H Futures Open Interest Tops $11.479B

4.04k Views118 Discussing

Korea Stocks Plunge 3.14% at Open

44.47k Views4.79k Discussing

View More