Square
Following
Hot
News
Notifications
Profile

contact

vip
Hello friends I'm new .
Market Analyst
70
Following
47
Followers
95
Liked
📣 November 6 Daily Top Posts: Good insights deserve to be seen
When will heavy AI investment deliver returns? Does an index rebound mean the market is strengthening? After making a bad trading call, how should you reassess your thinking?
These 8 posts cover everything from market analysis to trading reflections. Let’s take a look at what creators are observing👇
🔹 @赚钱吃肉肉: Ongoing AI investment: Can profits and cash flow keep up?
https://www.gate.com/zh/post/status/curated/25443255
🔹 @龙抄手: Rebound or reversal? A video anal
Sakura_3434
📣 November 6 Daily Top Posts: Good insights deserve to be seen
When will heavy AI investment deliver returns? Does an index rebound mean the market is strengthening? After making a bad trading call, how should you reassess your thinking?
These 8 posts cover everything from market analysis to trading reflections. Let’s take a look at what creators are observing👇
🔹 @赚钱吃肉肉: Ongoing AI investment: Can profits and cash flow keep up?
https://www.gate.com/zh/post/status/curated/25443255
🔹 @龙抄手: Rebound or reversal? A video analysis of BTC / ETH
https://www.gate.com/zh/post/status/25417274
🔹 @币靠普: Beyond the AI growth story, what else are investors watching?
https://www.gate.com/zh/post/status/curated/25443260
🔹 @云享财富讲堂: Tech stocks under pressure: What else needs to be confirmed before the Nasdaq rebound?
https://www.gate.com/zh/post/status/25442782
🔹 @山顶Ryak: Understanding PoSEC and asset verification from the user’s perspective
https://www.gate.com/zh/post/status/25427269
🔹 @阿炼CryptoView: BTC / ETH strength and key levels after the pullback
https://www.gate.com/zh/post/status/25443539
🔹 @初心实盘: After a trading mistake with SanDisk, reassessing mindset and judgment
https://www.gate.com/zh/post/status/25433936
🔹 @分析师Ansem: How do news events affect market sentiment and short-term volatility?
https://www.gate.com/zh/post/status/curated/25437719
🎁 Selected authors receive 3 days of traffic support + featured content
💬 Which post gave you a new perspective?
Visit the original post to share your questions, additions, or differing views. You’re also welcome to recommend yourself or others for great content in the comments.
The next top post might be yours.
The author’s views are for reference only and do not constitute investment advice or a promise of returns.
‍#每日神贴 #Gate Square
INDEX+0.00%
BTC-0.67%
ETH-1.26%
NDAQ-0.15%
#USCPIDataIncoming

On Tuesday, November 10, at 16:30, the Consumer Price Index for October will be released. The data in question will be decisive for the short-term direction of prices. Therefore, I prefer not to trade before the release and in the minutes when it is released.

The data is out on Tuesday, November 10, at 16:30 Turkey time, 08:30 US time. It is the consumer price index for October. Producer prices are also out in the same week. This is one of the most important pieces of data the central bank will see before its December 8-9 meeting.

Let us recall September. Headline had ri
discovery
#USCPIDataIncoming
On Tuesday, November 10, at 16:30, the Consumer Price Index for October will be released. The data in question will be decisive for the short-term direction of prices. Therefore, I prefer not to trade before the release and in the minutes when it is released.
The data is out on Tuesday, November 10, at 16:30 Turkey time, 08:30 US time. It is the consumer price index for October. Producer prices are also out in the same week. This is one of the most important pieces of data the central bank will see before its December 8-9 meeting.
Let us recall September. Headline had risen to 3.7% year over year, it was 3.4% in August. So the fall had stopped, it had turned up again. Now everyone is looking at what October will show.
What do forecasts say, let me say it clearly. The Cleveland side's live forecast sees October headline at +0.24% month over month, 3.74% year over year. Core at +0.21% month over month, 2.48% year over year. Another forecast sees headline at +0.30% month over month, core at +0.21%. One more sees +0.3% for both headline and core. So on a monthly basis we are hovering somewhere between 0.21% and 0.30%. On a yearly basis, around 3.7%.
What does this mean, let me say it simply. If monthly comes at 0.2%, the market will say "prices are still up, but not out of control." If monthly comes at 0.3% and above, it will say "sticky, not falling." If monthly comes cold like 0.1%, everyone will breathe a sigh. That is why a single digit after the comma moves billions of dollars in positions.
My view on this data is this. CPI alone does not set the rate decision. But with odds of a rate hike in December up in the 80s, CPI will either strengthen that view or weaken it. If it comes hot, the mood of "a hike in December is sure" grows, the dollar gets stronger, risk assets struggle. If it comes cold, the mood of "maybe there will be no hike" comes, the market breathes. So this data is not just a price data. It is like a rehearsal for the December decision.
So what will I do on Tuesday? Let me say it openly. I will not grow my position before the data. Because trading on a guess before the data is like tossing a coin. I will not trade in the first 10 minutes after the data either. In those first minutes, the price spikes to both sides, there are a lot of fake moves. I will read the data and look at headline and core together.
There are three places I will look at, but not like a list, just like I hold it in my mind. What did headline monthly come at, what did core monthly come at, and was the prior month revised. Core matters, because it looks without food and energy, it shows the more lasting part. If headline is hot and core is cold, the market will look at core. If both are hot together, it gets hard.
What if I am wrong? Data comes cold, price jumps, I will be late. I am okay with that. Data comes hot, price falls, I will not have been caught early. This week taught me that. The one who goes in early on data day usually ends up under the data.
What I feel inside is clear: On Tuesday at 16:30, October CPI is coming, forecast is in the 0.2-0.3% band monthly, around 3.7% yearly, September was 3.7%. This data will set the mood for the December decision. That is why I will not rush on Tuesday. Let the data come, let the first dust settle, let me put headline and core side by side and then decide.
#WCTCS9
#ShareWeekly
$AMD $NVDA $INTC $TSLA $MRVL
repost-content-media
AMD-8.76%
NVDA-1.92%
INTC-2.54%
TSLA-1.86%
MRVL-4.72%
Is the question "Are there funds in the vault?" still sufficient?

While the question of whether there are enough funds in the vault has been asked of cryptocurrency exchanges for years, the true critical point lies elsewhere: are those funds held in a wallet vulnerable to online attacks, or in a physically isolated vault?

A series of security breaches and losses amounting to millions of dollars across the industry has painfully demonstrated that the concept of "Proof of Reserves" is not enough on its own. This is because Proof of Reserves merely verifies the balance between the ledger and th
User_any
Is the question "Are there funds in the vault?" still sufficient?
While the question of whether there are enough funds in the vault has been asked of cryptocurrency exchanges for years, the true critical point lies elsewhere: are those funds held in a wallet vulnerable to online attacks, or in a physically isolated vault?
A series of security breaches and losses amounting to millions of dollars across the industry has painfully demonstrated that the concept of "Proof of Reserves" is not enough on its own. This is because Proof of Reserves merely verifies the balance between the ledger and the actual assets held. But what if, for instance, 11.74% of these assets are sitting in "hot wallets"—prime targets for cyberattackers? This is precisely where Gate has introduced a new, industry-disrupting standard: PoSEC, or "Proof of Security."
What does the transition from Proof of Reserves to Proof of Security entail?
Proof of Reserves—a practice Gate has championed since 2020—addresses the question: "Does the exchange hold enough funds to cover the assets it owes its users?" Proof of Security, however, focuses on a much harsher scenario: "If all your hot wallets were to be compromised and drained in a cyberattack tomorrow, would the assets held in your cold wallets be sufficient to cover all user funds?"
The latest data shared by Gate provides a clear answer: the cold wallet coverage ratio stands at 104.58%, with 88.26% of assets held in cold wallets and 11.74% in hot wallets, resulting in a total reserve ratio of 118.49%. The most critical detail here is that the 104.58% ratio does not merely represent cash on hand. This figure indicates that, even in the event of a total loss of all "hot" (online) wallets, the assets held in "cold" (offline) wallets would be sufficient to cover all user balances—with an additional 4.58% safety margin to spare. In other words, withdrawal channels remain open even during periods of high trading volume.
Where does the hidden risk lie?
Many exchanges in the market keep a significant portion of their assets in online hot wallets to maintain high transaction speeds. However, this creates a major "single point of failure" risk. Even if an exchange has a reserve ratio of 150%, if 40% of those assets are held in online wallets, a single smart contract vulnerability or server breach could instantly push the exchange to the brink of insolvency.
Gate’s reported 88.26% cold wallet ratio represents a level of isolation far above the industry average. Supported by multi-signature requirements and independent custody protocols, this structure ensures that private keys are not under the control of any single individual or server, and that multiple authorizations are required for any asset transfer.
Why is it important to interpret the 104.58% figure correctly?
As with any new standard, it is necessary to recognize the methodological limitations of "Proof of Security." The 104.58% coverage ratio is calculated based on a "snapshot" in time and can be influenced by sudden fluctuations in asset prices.
More importantly, the cold wallet coverage ratio only proves where assets are stored; it does not, by itself, demonstrate the robustness of internal controls, staff access privileges, or operational redundancy. Therefore, the ultimate assurance lies in the verification of disclosed data through independent third-party audits. Gate indicates that this process is currently underway and that audit reports will be shared soon.
What does the security paradigm of this new era change?
In the crypto market, trust is no longer measured solely by the total size of reserves. Standards such as "Proof of Security" emphasize the resilience aspect of trust. In other words, it is not enough for an exchange to simply hold a large amount of capital; it must also possess an architecture capable of safeguarding those funds, even in a worst-case scenario.
Whether the "cold wallet coverage ratio" will become a standard metric for all exchanges is set to be one of the most debated topics in the industry moving forward.
What should you look for when evaluating an exchange?
To determine whether an exchange is trustworthy—and to consider whether standards like "Proof of Security" should become mandatory alongside "Proof of Reserves"—one must examine two distinct layers.
First: Are the funds actually there? Second: Where are these funds held, and would they remain accessible in a worst-case scenario? The reserve ratio addresses the first question, while the cold wallet coverage ratio addresses the second. Without considering both, the picture remains incomplete.
Key factors to monitor include whether the cold wallet ratio remains stable over time, whether independent audits confirm the disclosed data, and how the share of assets held in "hot wallets" fluctuates in relation to trading volume.
This content is for informational purposes only and does not constitute investment advice.
#GateLaunchesPoSECProofOfSecurity
$BTC $GT $ETH $SOL $XRP
repost-content-media
BTC-0.67%
GT-2.41%
ETH-1.26%
SOL-0.77%
XRP-1.15%
Why did a week of risk aversion shake the stock markets so severely?

U.S. stocks ended the week with significant losses; the Nasdaq experienced its sharpest weekly decline in months, and the "fear index" (VIX) surged by as much as 70% on Thursday, climbing above the 28 level. Meanwhile, bond yields rose toward the end of the week, settling around 4.85%, and the U.S. dollar strengthened. Conversely, gold and silver saw their strongest weekly performance in months, closing with gains of approximately 4% and over 5%, respectively.

What does a "week of risk aversion" mean?

The events on Wall St
User_any
Why did a week of risk aversion shake the stock markets so severely?
U.S. stocks ended the week with significant losses; the Nasdaq experienced its sharpest weekly decline in months, and the "fear index" (VIX) surged by as much as 70% on Thursday, climbing above the 28 level. Meanwhile, bond yields rose toward the end of the week, settling around 4.85%, and the U.S. dollar strengthened. Conversely, gold and silver saw their strongest weekly performance in months, closing with gains of approximately 4% and over 5%, respectively.
What does a "week of risk aversion" mean?
The events on Wall Street this past week can be summarized in a single sentence: the market repriced risk. U.S. stocks closed the week with broad losses; the S&P 500 fell by approximately 2.7%, while the Nasdaq suffered its worst week in months, dropping 3.4%. The turning point arrived on Thursday, when a sell-off in artificial intelligence and semiconductor stocks triggered the sharpest single-day decline for the index since the spring of 2025, causing trillions of dollars in market capitalization to evaporate in a single day.
The reasons behind this are not merely technical—they are political. The shift in control of Congress following the midterm elections held earlier in the week led investors to question the future of spending on artificial intelligence infrastructure. As confidence in the growth narrative surrounding data centers wavered, stocks with the most inflated valuations faced the heaviest selling, while forced liquidations by leveraged funds turned the downturn into a full-blown panic. What you need to watch is whether this marks the end of a trend or is merely a correction. The attempt by AI-related stocks to recover on Friday suggests that the selling pressure is not entirely one-sided. It is too early to say whether the indices have bottomed out; however, the fact that panic selling did not shift into panic buying indicates that the market remains in a state of indecision.
Why did the "price of fear" surge?
The most striking development of the week occurred in the volatility index—often referred to as the "fear index." On Thursday, it spiked by approximately 70%, climbing above the 28 level—the highest reading seen in months. In simple terms, this means investors were willing to double the premiums they pay for instruments that act as insurance for their portfolios.
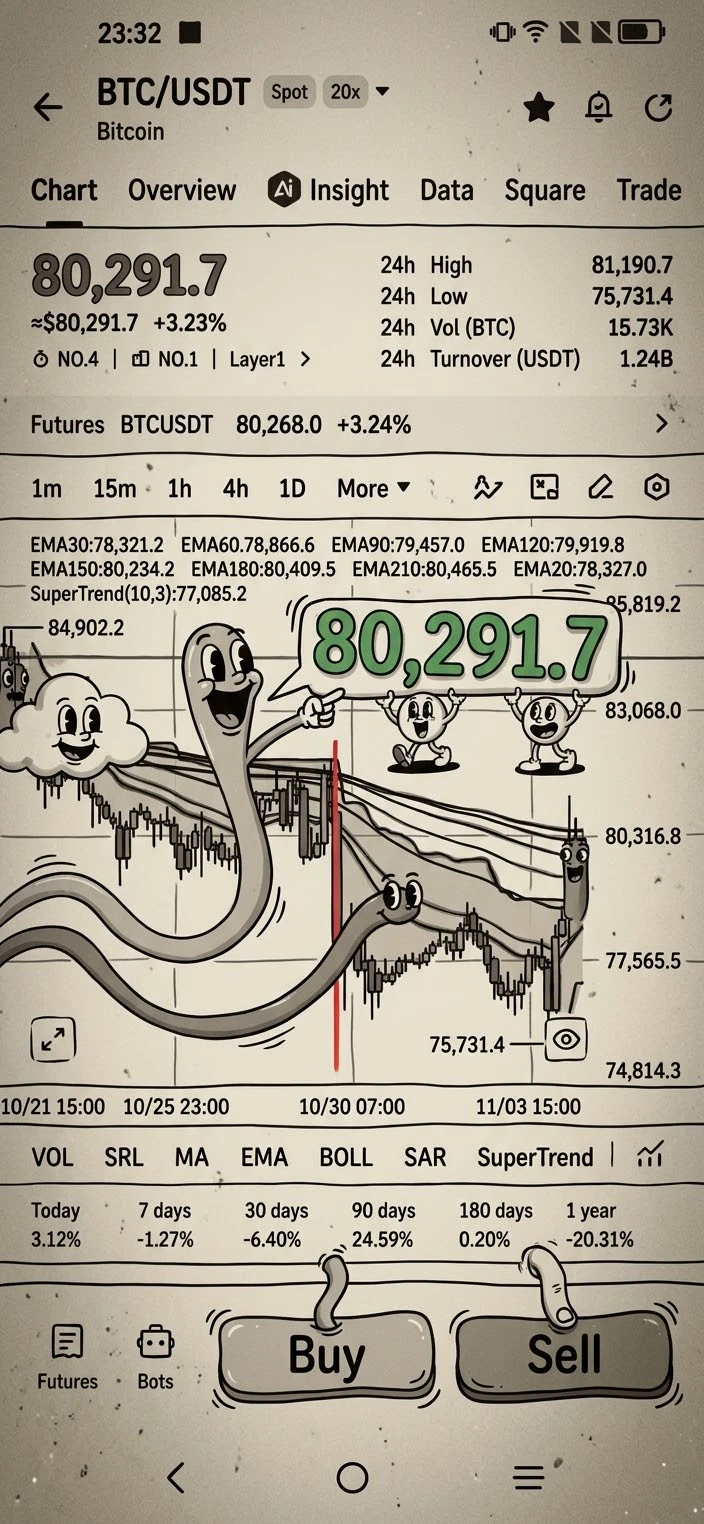
The impact of this surge in volatility is indirect yet profound. A high "fear premium" prompts market makers to trim their positions, leads funds to lower their risk limits, and results in an overall reduction in liquidity. We saw a clear manifestation of this in the crypto space: on that same day, hundreds of millions of dollars in leveraged long positions were liquidated, a wave that dragged Bitcoin down from above $80,000 to the $75,000 range.
The key indicator to monitor is the level at which the fear index eventually stabilizes. Sharp, single-day spikes are often reversed; however, if the index remains at elevated levels, it suggests that the market environment has not yet cleared, and any rally in risk assets will be met with skepticism.
How did the interplay between interest rates and the dollar unfold?
Throughout the week, the bond market told two distinct stories. Mid-week, a flight to safety—triggered by a sell-off in equities—pushed interest rates lower; however, a strong employment report released on Friday reversed this dynamic. The addition of 165,000 new jobs drove bond yields back up, with the 10-year benchmark yield settling around 4.85%, while the dollar also ended the week on a strong note.
For crypto investors, this shift is significant: both interest rates and the dollar serve as inverse indicators of risk appetite. When interest rates rise and the dollar strengthens, the appeal of non-yielding assets diminishes, the cost of leverage increases, and institutional capital tends to migrate toward safer havens. Indeed, Bitcoin spot funds saw outflows exceeding a billion dollars last week—a clear, tangible sign of weakening institutional demand.
All eyes are now on Tuesday’s CPI data. Economists anticipate that annual inflation will climb from 3.7% to approximately 3.9%. Should this figure materialize, a December interest rate hike would become all but certain, keeping pressure on both bond yields and the dollar. Conversely, if inflation comes in surprisingly low, this pressure could ease, providing some breathing room for risk assets.
Why did gold and silver rise simultaneously?
The surprise stars of the week were, without a doubt, precious metals. Gold closed the week with a gain of approximately 4%, settling above the $4,000 threshold, while silver topped the performance list with an increase of over 5%. This marked their strongest week in months. The rise in gold—occurring alongside falling stocks, a surging "fear index" (volatility index), and rising interest rates—defies conventional wisdom; typically, high interest rates are the arch-nemesis of gold, an asset that yields no interest.
So, why the rally? The answer lies in a shift in capital flows. Investors moved funds pulled from equities not into other stocks, but into tangible assets. This was bolstered by central banks, which, as revealed in data released this week, continued to purchase gold at record levels during the third quarter. A broad spectrum of investors—from family offices to massive institutional funds—simultaneously sought a "safe haven," pushing prices higher despite the headwinds from rising interest rates. The sharper rally in silver, meanwhile, reflects both safe-haven demand and industrial demand.
The key question now is whether the $4,000 level will serve as a pivotal turning point for gold. If this level holds, the thesis of a rotation into safe-haven assets gains weight; however, should interest rates climb even further, maintaining this resistance level will become increasingly difficult. The takeaway here is that the rise in precious metals should be viewed not as mere "hype," but as a defensive reflex aimed at portfolio protection.
What about Bitcoin?
This week, crypto failed to fit into either the "safe-haven" category or the role of a bellwether for risk appetite. Bitcoin fell in tandem with the sell-off in equities, and unlike gold, it failed to rally. The wave of billion-dollar outflows from institutional funds has once again put the "digital gold" narrative to the test this week—and the results were not encouraging. During this week of fear, institutional capital flowed into commodities and bonds rather than the blockchain.
To understand why, one must view Bitcoin as a liquidity-sensitive asset. As the likelihood of the Federal Reserve tightening policy increases, the supply of borrowed capital in the market shrinks; consequently, speculative, long-horizon assets are the first to be sold off. Bitcoin is currently defending the $75,000 support level. If this threshold holds, the bearish scenario is deferred; if it is lost, the $73,000 level—followed by the $70,000–$72,000 range—emerges as the next potential destination.
In the crypto space, there are two key factors to watch: first, whether the direction of institutional fund flows shifts this week; and second, whether Tuesday’s inflation data can revive risk appetite. The debate over whether Bitcoin acts as a "safe haven" or a "risk asset" cannot be settled in a single week—but this week’s outcome clearly leans toward the latter.
What is the lesson for the individual investor?
Looking at the week as a whole, the picture is clear: we are witnessing a global "flight to safety." Equities are being sold, metals are being bought, the dollar and interest rates are strengthening, and crypto finds itself caught in the crossfire. In weeks like this, the costliest mistake is to gauge the entire market based on the movement of a single asset. Assuming a "safe-haven" rush simply because gold is rising, predicting a market collapse because stocks are falling, or declaring a final verdict because Bitcoin is being sold—these are all hasty reactions, and they all stem from the same error: losing sight of the broader context.
The lesson for you is this: build your portfolio based on its inherent resilience, not on the direction of the wind. Periods of "risk-off" sentiment are times when the correlations between all assets approach one—meaning everything falls in tandem; it is precisely during such weeks that the true value of diversification becomes clear. Furthermore, keep a close eye on the economic calendar; the CPI data on Tuesday, followed by the Federal Reserve’s December decision, will be the defining moments that set the market's direction. During these periods, leverage is the first thing to evaporate in the face of volatility—manage your margin accordingly.
Finally, bear in mind this reality: risk-off phases do not last forever, and the most aggressive rallies often follow the darkest weeks. However, do not mistake "often" for "always." Your task today is not to predict the future, but to accurately interpret the current landscape and ensure that, regardless of which scenario unfolds, your positions remain resilient.
This content is for informational purposes only and does not constitute investment advice.
$BTC $XAU $XAG $US500 $US30
#USCPIDataIncoming
#USAIStocksHitHard
#USNonfarmPayrolls
#StockTalkSeason
#ShareWeekly
repost-content-media
What happened in the markets this week, and what do the numbers tell us?

The S&P 500 closed the week with a loss of approximately 2.7%, with the Nasdaq at the epicenter of the decline, while the "fear index" (VIX) settled at 25.6 by the week's end. Yields on two-year Treasury notes climbed to 4.53%, and ten-year yields rose to 4.87%, as the dollar index strengthened to around 102.3. Meanwhile, gold gained nearly 5% for the week, reaching approximately $4,065, and silver also saw gains, approaching $52. Bitcoin finished the week slightly lower, remaining above $75,000. Looking ahead, Tuesday’s
User_any
What happened in the markets this week, and what do the numbers tell us?
The S&P 500 closed the week with a loss of approximately 2.7%, with the Nasdaq at the epicenter of the decline, while the "fear index" (VIX) settled at 25.6 by the week's end. Yields on two-year Treasury notes climbed to 4.53%, and ten-year yields rose to 4.87%, as the dollar index strengthened to around 102.3. Meanwhile, gold gained nearly 5% for the week, reaching approximately $4,065, and silver also saw gains, approaching $52. Bitcoin finished the week slightly lower, remaining above $75,000. Looking ahead, Tuesday’s CPI (Consumer Price Index) data stands as the next critical milestone on the calendar.
What picture do these numbers paint?
Sometimes, the summary of a week can be captured in a single word: sell-off. U.S. equities ended the week with broad losses; the S&P 500 fell by about 2.7% to around 7,377, while the Dow saw a more modest decline of nearly 1%. The tech sector, however, took the hardest hit. The Nasdaq dropped nearly 5% for the week, driven by a sell-off centered on artificial intelligence and semiconductor stocks. The fear index closed at 25.6, providing a numerical testament to just how frayed investors' nerves have become.
The answer to why this sell-off occurred has two layers. The first factor is political: the shift in control of Congress has increased uncertainty regarding the future of AI infrastructure spending, triggering an initial sell-off in stocks with inflated valuations, followed by a chain reaction of liquidations. The second factor is macroeconomic: Friday’s robust employment report—showing 165,000 new jobs—reinforced expectations that interest rates could climb even higher, dampening the appetite for buying stocks.
The key point to watch is this: while technology stocks attempted a recovery over the weekend, the weekly picture remains in the red. It is not yet clear whether this sell-off is merely a wave of panic or the first step toward a broader reversal; the coming week should provide the answer.
Why is every step on the interest rate ladder becoming more expensive?
The bond market sent a clear, two-pronged message this week: rates are heading higher. The two-year Treasury yield rose to 4.53%, the ten-year reached 4.87%, and long-term yields remained above 5.2%. Taken together, these figures suggest the market believes the Federal Reserve will continue on its path of monetary tightening. The two-year yield, in particular, serves as the most accurate reflection of short-term monetary policy expectations—and right now, that reflection points toward further tightening.
While the impact varies across different asset classes, there is a common underlying mechanism: interest rates shift the center of gravity for capital. In a world where a "risk-free" return of 4.5%–5% is available, the risk premium that investors—who otherwise seek profit—demand for holding growth stocks or non-yielding assets (like certain coins) increases. This factor played at least as significant a role in this week’s stock sell-off as the political developments did.
The specific milestone to keep an eye on is clear: Tuesday’s CPI (Consumer Price Index) data. Economists expect annual inflation to rise from 3.7% to approximately 3.9%; if this expectation materializes, interest rates will likely climb another step higher. Conversely, should there be a positive surprise—a shift toward better-than-expected data—the upward trajectory of rates may pause for a while.
What does the dollar’s position above 102 signify?
The dollar index closed the week on a strong note, hovering around 102.3 and recovering from an interim pullback experienced earlier in the week. This figure is also technically significant, as the index is trading at its highest level in a year. Robust employment data and expectations of further interest rate hikes have provided the dollar with a dual boost—bolstering its appeal both in terms of yield and as a "safe-haven" asset.
The strengthening of the dollar hits the crypto market particularly hard, as coin prices are denominated in dollars, and investors with dollar-denominated debt are often forced to trim their positions during periods of dollar strength. Bitcoin’s losses this week are a direct result of this mechanism; outflows from institutional funds, exceeding a billion dollars, have pushed the leading cryptocurrency down from the $80,000 range toward the $75,000 level.
Looking ahead, the key threshold to watch is the resistance zone between 102.5 and 104 on the dollar index. If the dollar breaks through this range, the liquidity headwinds for risk assets will intensify; if, however, the index turns back from this level, it could spark a debate about whether the dollar has peaked, potentially easing some of the pressure. This week, the direction of the dollar cannot be viewed independently from the direction of crypto assets.
Why did metals diverge?
The top performer of the week came from an unexpected quarter: gold rose by nearly 5% to reach $4,065, while silver climbed by approximately 6%, nearing the $52 mark. Both assets posted strong weekly gains—a level of performance not seen in months. It is worth highlighting a contradiction here: the rise in metals alongside climbing interest rates and a stronger dollar defies conventional financial wisdom, as high interest rates are traditionally the nemesis of gold, which yields no interest.
The explanation lies in the behavior of capital; funds exiting equities did not return to the stock market but instead flowed into tangible assets. Amidst a week defined by fear, investors sought a form of insurance—and they found it in precious metals. Furthermore, record-level purchases by central banks have expanded demand beyond just institutional investors. As for silver, its sharper ascent is bolstered by expectations of industrial demand.
For gold, the $4,000 threshold is the key level to watch. If this zone holds, the role of metals as a "safe haven" will be reinforced; however, should interest rates climb further, the resilience of this rally will be put to the test. It is more prudent to view the movement in metals not as the beginning of a new trend, but rather as a reflection of a week driven by fear.
Is Bitcoin a liquidity asset or a safe haven?
Bitcoin ended the week with a loss of approximately 2%, closing near $75,750. While a 2% decline may seem modest compared to the losses seen in equity indices, the context is significant: while gold rallied this week, Bitcoin—often dubbed "digital gold"—fell. This divergence serves as the crypto market’s definitive answer to the "safe-haven" debate: in moments of fear, capital fled toward commodities and bonds rather than the blockchain.
The reason for this lies in the very nature of Bitcoin. In the short term, it functions as a liquidity-driven asset; it shines when money is abundant and interest rates are low, but it is sold off alongside equities when liquidity tightens. With the market pricing in a potential Federal Reserve rate hike in December, combined with an outflow from institutional funds and a strengthening dollar, the $75,000 level has emerged as this week’s primary line of defense.
Moving forward, two critical factors bear watching: whether Bitcoin can hold onto its $75,000 support level, and whether the direction of institutional fund flows will shift. If the support level is lost, the next targets to consider are $73,000 and the $70,000–$72,000 range. Conversely, if it holds—and if Tuesday’s data manages to revive risk appetite—then this week’s losses might simply be viewed as a temporary pause. The answer to the question of what Bitcoin "is" can change from week to week; this week, it proved to be a risk asset.
What is the lesson here for the individual investor?
All the data from this week boils down to a single reality: liquidity is tightening, and capital is seeking safety. Equities fell, interest rates and the dollar rose, metals gained value, and cryptocurrencies remained under pressure. A common mistake among individual investors is to interpret each data point as an isolated piece of news, when in fact, they are all different scenes from the same story. Interest rates rise, the dollar strengthens, risk assets are sold off, and safe-haven assets are bought. This is the chain of events—don’t just watch the individual scenes; read the entire chain. As for the practical lesson: Tuesday’s CPI data will determine the next link in this chain. A high reading implies continued pressure from yields and the dollar, while a low reading could open the door to some relief. On days when such data is released, volatility tends to be intense, and leveraged positions are the first to incur losses. Adjust your margin accordingly, and review the balance between risk assets and defensive assets in your portfolio to ensure it can withstand either scenario. Consumption data due in mid-November—such as retail sales figures—will provide a clear picture of the pressure inflation is exerting on consumers.
The final takeaway is this: weekly figures provide guidance, but they do not define the overall trend. Next week, the market could just as easily sell everything or buy everything; your task is not to predict which will happen, but to be prepared for either outcome.
This content is for informational purposes only and does not constitute investment advice.
$BTC $XAG $XAU $NAS100 $US500
#USCPIDataIncoming #USAIStocksHitHard #USNonfarmPayrolls #StockTalkSeason
#ShareWeekly
repost-content-media
Gate Launchpool will launch the #386: ValueX (VLX) project. Stake BTC, ETH, or VLX to earn a share of 454,546 VLX tokens at no cost. Airdrop rewards are distributed every hour.

Learn more 👉 https://www.gate.com/en/announcements/article/102656

👉https://www.gate.com/share/act/2441e7f5

#StakeOnLaunchpoolToShare450KVLX

Do your own research 🔎 Not financial advice ✔️

$BTC $ETH $VLX
User_any
Gate Launchpool will launch the #386: ValueX (VLX) project. Stake BTC, ETH, or VLX to earn a share of 454,546 VLX tokens at no cost. Airdrop rewards are distributed every hour.
Learn more 👉 https://www.gate.com/en/announcements/article/102656
👉https://www.gate.com/share/act/2441e7f5
#StakeOnLaunchpoolToShare450KVLX
Do your own research 🔎 Not financial advice ✔️
$BTC $ETH $VLX
repost-content-media
VLX+0.00%
BTC-0.67%
ETH-1.26%
#BTCETFOutflowsContinue

During the week of November 2–6, U.S. spot Bitcoin ETFs recorded a total net outflow of $1.28 billion—the worst weekly performance since the end of June. Fidelity’s fund was the only major fund to end the week in positive territory, with a net inflow of approximately $93 million, while BlackRock’s fund alone accounted for $1.21 billion in outflows. The aggregate of all funds excluding IBIT also finished the week in the red, pushing cumulative year-to-date fund flows into slightly negative territory. This shift occurred alongside Bitcoin’s price action hovering around
User_any
#BTCETFOutflowsContinue
During the week of November 2–6, U.S. spot Bitcoin ETFs recorded a total net outflow of $1.28 billion—the worst weekly performance since the end of June. Fidelity’s fund was the only major fund to end the week in positive territory, with a net inflow of approximately $93 million, while BlackRock’s fund alone accounted for $1.21 billion in outflows. The aggregate of all funds excluding IBIT also finished the week in the red, pushing cumulative year-to-date fund flows into slightly negative territory. This shift occurred alongside Bitcoin’s price action hovering around the $75,000 mark.
The week’s tally: Where did institutional capital flow?
In the crypto market, the sentiment of retail investors can be gauged via social media, while that of institutional capital is reflected in ETF flow data. The figures for the week of November 2–6 are stark: U.S. spot Bitcoin ETFs saw a net outflow of $1.28 billion—a weekly loss unseen in nearly five months. The fact that outflows occurred on four out of the five days suggests this was not merely a one-day reaction, but rather a risk-reduction decision that played out over the entire week.
An interesting aspect of this data lies in its distribution; Fidelity’s fund ended the week in the green—even including Wednesday, the only day of the week that saw positive inflows. Conversely, BlackRock’s massive fund recorded outflows every single day, accounting for nearly the entire weekly total. While it is accurate to say that institutional capital is exiting, that statement is incomplete. In reality, institutional capital is undergoing a repositioning—a process that varies depending on the specific fund manager. The value of monitoring this data lies in the fact that ETF flows represent the cleanest indicator of institutional demand for crypto; unlike sentiment-driven commentary, these figures reflect the aggregate of actual, multi-million-dollar investment decisions. And right now, that aggregate suggests a cautious stance.
Why is this major fund bleeding capital?
IBIT is more than just a fund—it is an industry icon. With over $60 billion in total assets and cumulative inflows exceeding $65 billion, this product alone accounts for more than half of the U.S. spot Bitcoin ETF market. Consequently, a $1.21 billion weekly outflow from IBIT is, in numerical terms, the movement of a single fund, but in psychological terms, it represents a shift across the entire market.
As for why this outflow is occurring, there are several layers. First, there is the macro perspective: a sharp sell-off in tech stocks throughout the week, combined with uncertainty following the mid-term elections, has pushed portfolio managers into a "risk-off" mode. The reduction of positions by leveraged investment funds directly accounts for a portion of these outflows. Second, there is the structural aspect: while large funds generally act to dampen rather than accelerate losses, this only goes so far. The outflows recorded today are merely a dent—not a collapse—when viewed against the roughly $97 billion in total ETF assets.
The key metric to watch here is clear: the pace of outflows from IBIT. If outflows from a single fund persist for a week, it suggests a fund-specific decision; however, if the trend spreads across multiple funds and continues for several weeks, it points toward a broader, sector-wide trend. Currently, the situation leans toward the former, but the overall direction will likely become clear over the next two weeks.
What does Fidelity’s counter-move signify?
Perhaps the most significant—yet least discussed—data point of the week is that while everyone else was selling, Fidelity’s fund was buying. The fund served as the primary driver for positive inflows into the category on Wednesday; despite a sharp outflow on Thursday, it swung back to positive territory on Friday, closing the week with a net inflow of approximately $93 million. This indicates that there remains a segment of institutional buyers in the market willing to purchase Bitcoin at its current price.
There are two ways to interpret this divergence, and both must be considered. The optimistic view suggests that the decline stems from liquidity conditions rather than a lack of demand—implying that buyers return once the price reaches an attractive level, and that market bottoms are forming even before institutional inflows accelerate. The pessimistic view posits that this fund-specific activity might merely reflect the unique positioning of a single asset management firm relative to its own client base, lacking the power to shift broader industry trends; as long as IBIT continues to see inflows, the activity from this other fund is little more than a drop in the ocean.
The lesson here is that the flow of a single fund is a data point, not a trend. However, data points accumulate; if the positive momentum seen with Fidelity persists into a second or third week, it would serve as the most concrete evidence for the thesis that "smart money" is accumulating near the market bottom. If it does not persist, it will remain nothing more than an isolated, one-off event.
Why did the stock rise while funds were flowing out?
Even as the Bitcoin fund saw outflows, the stock of the firm managing it closed the day in the green, trading around $1,170–$1,180. While this might appear contradictory at first glance, it is not; the stock of an asset manager depends not only on the performance of a single crypto fund but also on the firm’s total assets under management, management fees, and overall corporate outlook. The sheer scale of a multi-billion-dollar traditional fund portfolio is enough to render the outflows from a single crypto fund negligible in terms of the firm’s stock price.
Nevertheless, this dual picture offers an important lesson for individual investors: "institutional" investors do not act as a monolithic block. Within the same firm, one team might be liquidating a fund while the company as a whole continues to grow. Outflows from a specific fund do not necessarily mean that institutions are fleeing crypto—just as a rise in a firm’s stock price does not necessarily mean that institutions are bullish on crypto. Furthermore, analysts’ technical interpretations of an asset management firm’s stock performance add another layer; while such insights can be informative, they are by no means a guarantee.
Moving forward, it is worth tracking two indicators: ETF flow data on one hand, and the stock performance of the management firms on the other. The moment both move in the same direction, it will serve as a strong signal of a genuine turning point in institutional sentiment.
What about these two market realities?
Despite the fund outflows, Bitcoin held its ground, remaining within the $75,000–$76,000 range. This demonstrates remarkable resilience; the fact that the price did not lose the $75,000 support level—even in the face of $1.28 billion in institutional outflows—suggests that these exits were part of a planned repositioning rather than a panic-driven sell-off. However, the tone of the conversation on social media—revolving around "bull traps" and downward-sloping channels—reveals that confidence among retail investors remains fragile. In technical terms, the price is still trapped within a downward channel, and a recent attempt to rally toward the 87,000 level was rejected.
The next major turning point is clear: the U.S. Consumer Price Index (CPI) data for October, due on Tuesday. Economists expect the annual inflation rate to rise from 3.7% to approximately 3.9%. A "hot" (higher-than-expected) reading would all but guarantee a Federal Reserve interest rate hike in December; in such a scenario, bond yields and the U.S. dollar would likely climb, ETF outflows could accelerate, and the 75,000 level might be tested once again. Conversely, a favorable (lower-than-expected) reading would improve liquidity expectations and potentially open the door for the return of institutional capital that has been fleeing for weeks—Fidelity’s client base, for instance, might be waiting for precisely such a moment.
In short, ETF flows next week will serve as a response to this data. If outflows remain limited, the argument that this was merely a "test of the bottom" gains strength; if outflows deepen, it suggests the beginning of a broader institutional exodus. Be prepared for either scenario—the market will inevitably choose one, and your job is to observe it unfold, not to guess the outcome.
What is the lesson for the individual investor?
When you synthesize the week’s entire narrative, a clear framework emerges: institutional flows have turned negative, yet the bulk of these outflows is concentrated in a single fund, while other institutions are buying elsewhere. Meanwhile, the price is holding its critical support level, and Tuesday’s data could rewrite the entire picture. In this context, the biggest mistake one could make is to oversimplify the entire market based on a single headline—such as "institutions are selling" or "Fidelity is buying." Every facet of the institutional mirror reflects a different angle; your job is to examine the mirror in its entirety.
For your practical approach, monitor ETF flows on a daily—rather than weekly—basis, and take special note of the share held by any major fund; outflows originating from a single fund are not the same as broad-based outflows. Track the consistency of purchases from entities like Fidelity; a trend spanning two or three weeks is far more significant than a single day’s movement. Furthermore, review your positions ahead of Tuesday’s CPI data; the sharpest declines often occur when the liquidation of leveraged positions coincides with institutional outflows during periods of high volatility—adjust your margin accordingly.
Ultimately, while institutional flows serve as a compass, you are the one holding it. The mirror does not dictate what you should buy; it merely reveals the direction of the wind. Read the wind, structure your plan accordingly, and never mistake a single data point—whether it concerns a specific fund, a particular stock, or a single day’s activity—for the entire story.
This content is for informational purposes only and does not constitute investment advice.
$BTC $ETH $BLK
#Gate股票畅聊季 #GateStockTalkSeason #ShareWeekly
repost-content-media
Why did the world raise interest rates simultaneously during the same week?

The weekly summary has been verified point by point: employment in the United States increased by 165,000, the unemployment rate fell to 4.1%, and wages rose by 0.4%. The Bank of England raised interest rates to 4.00%—its first such move in over three years—while Australia pushed its rates to 4.85%, an 18-year high. Inflation climbed to 4.0% in the Eurozone and 1.5% in Switzerland, and Sweden raised its interest rate to 2.00%. Norway kept its rate steady at 4.50% but left the door open for future adjustments; meanwhil
User_any
Why did the world raise interest rates simultaneously during the same week?
The weekly summary has been verified point by point: employment in the United States increased by 165,000, the unemployment rate fell to 4.1%, and wages rose by 0.4%. The Bank of England raised interest rates to 4.00%—its first such move in over three years—while Australia pushed its rates to 4.85%, an 18-year high. Inflation climbed to 4.0% in the Eurozone and 1.5% in Switzerland, and Sweden raised its interest rate to 2.00%. Norway kept its rate steady at 4.50% but left the door open for future adjustments; meanwhile, unemployment in Canada rose to 6.7%, and China’s manufacturing index slipped to 49.3, signaling a contraction.
Market data confirms this picture: the euro is trading against the dollar at 1.12295—well below its early-September peak of 1.17114 and hovering near a low of 1.11047. Brent crude oil is trading around $108.81, having retreated after reaching an intraday high of $111.07.
The global landscape for the week of November 2–6 can be summed up in a single sentence: monetary policy is tightening worldwide, driven by a common factor—energy-related inflation. The Bank of England has implemented its first interest rate hike in over three years, bringing the rate to 4.00%; Australia has reached an 18-year high of 4.85% with its fifth hike of the year; and Sweden has raised its rate to 2.00%—its first increase since 2023—while signaling further hikes to come. In the United States, although the Federal Reserve has kept rates unchanged, strong employment data has significantly bolstered the likelihood of a rate hike in December.
This synchronized movement is no coincidence; there is a common trigger. The conflict in the Middle East has constrained energy supplies, driving up the costs of everything from fuel to electricity bills and compelling central banks to move in the same direction. The rise in UK inflation to 3.5% in September and the surge in energy prices—which have climbed by more than 20% year-on-year in the Eurozone—are all links in the same chain. In the U.S., an employment gain of 165,000 in October, coupled with a decline in the unemployment rate, has given the Fed confidence that this monetary tightening can be carried out without damaging the broader economy.
The key question now is: where does this upward trajectory peak? The tension between the Bank of England’s warning—that this is merely the first in a long series of rate hikes—and the market’s expectation that the Fed will raise rates in December will define the primary economic narrative for the coming months.
This week’s inflation data demonstrates that the world is not experiencing a uniform inflationary trend. In the Eurozone, annual inflation has climbed from 3.8% to 4.0%—reaching a three-year high—driven by a 20.8% surge in energy costs, while core inflation has remained at 2.5%. This distinction is critical: we are witnessing a shock stemming from fuel bills, with core inflation currently showing no signs of broad-based expansion. However, analysts warn that energy costs could spill over into other sectors—from food to services—in the coming months, suggesting that "second-round effects" may be on the horizon.
Switzerland is experiencing a milder version of the same shock, with inflation rising from 1.0% to 1.5%, led by increases in transport and housing energy costs. While this level remains modest by global standards, it represents an unusually rapid pace for Switzerland—the highest reading in three years. The situation in Japan presents a different, intriguing picture: real wages have been rising for months, and the Bank of Japan has officially declared that its 2% inflation target—a goal not seen in 13 years—has been reached. While interest rate hikes are anticipated, they have yet to be implemented. We are looking at an economy on the verge of a regime shift following three decades of deflation.
The takeaway here is that rising inflation is not a monolithic story. The question of whether this fuel-driven shock will evolve into persistent, entrenched inflation will dictate the Eurozone’s policy decisions in December, the limits of Switzerland’s tolerance, and the potential onset of monetary tightening in Japan.
The dynamics of the EUR/USD exchange rate further confirm this divergence. The Euro has retreated from the 1.17 level toward 1.11 and is currently attempting to stabilize around 1.12. This reflects both the strengthening of the dollar and the expectation that, despite inflation in the eurozone, the European Central Bank will not be able to tighten policy as aggressively as the Federal Reserve. The currency pair should be interpreted not merely as a movement in exchange rates, but as a reflection of the divergence in the pace of policy tightening between the two central banks.
Two employment stories in the same week, two contrasting worlds. In the United States, employment growth tripled expectations, the unemployment rate fell, and wages accelerated—a picture of economic resilience that provides the Federal Reserve with the room to continue its tightening cycle. In Canada, meanwhile, the unemployment rate rose from 6.5% to 6.7%, employment declined for the third consecutive month, and the private sector shed tens of thousands of jobs; public sector hiring attempted, but failed, to salvage the situation. The pressure from U.S. tariffs is slowing the Canadian economy, creating a scenario that complicates the Bank of Canada’s resolve to raise interest rates at the end of October.
Norway stands somewhere in between; its central bank held interest rates steady at 4.50% while reiterating that it remains prepared to hike further if necessary. It is a cautious "wait-and-see" approach—inflation remains above the target, but a strengthening krone is doing some of the heavy lifting. This patience in Northern Europe—displayed in a country neighboring Sweden, which has opted for rate hikes—demonstrates that even within a regional wave of monetary tightening, the pace of individual nations can diverge.
The key takeaway here is that currency strength is now shaped less by inflation and more by the balance within the labor market. The U.S. dollar is gaining ground, backed by a robust labor market, while the Canadian dollar remains under pressure as unemployment rises. There is no universal rule stating that interest rate hikes automatically strengthen a currency; rather, every economy operates according to its own unique internal balance.
Data emerging from the "eastern front" this week may well represent the most significant blow to global risk appetite. China’s official manufacturing purchasing managers' index (PMI) has fallen from 50.1 in September to 49.3, slipping back into contraction territory; the component for new export orders has also dipped below 50. This is not merely a one-month fluctuation, but a broader signal: the "world’s factory" is experiencing a sharp slowdown.
The cause-and-effect chain here is global. A contraction in Chinese manufacturing weakens demand for commodities; the resulting strain spreads through Asian supply chains, putting downward pressure on the currencies of commodity-exporting nations. For the crypto market, there is an indirect yet tangible link: a growth shock originating in China dampens global risk appetite and drags down the performance of leveraged assets. The way Asian stock markets closely mirrored the sell-off in the U.S. earlier this week serves as clear evidence of this contagion.
The oil market represents the most concrete link in this chain. On the weekly chart, Brent crude is trading around $108.81, following a major rally from a low of $58.70 to a peak of $120.57. In other words, the energy shock has not ended; it has merely retreated slightly from its peak. As long as oil prices remain at these levels, inflationary pressures—and the rationale for central banks to pursue monetary tightening—will persist.
Key developments to watch include high-level diplomatic or economic engagements expected in the coming week, as well as the November data for export orders. If the index recovers to 50, the October dip could be viewed as a temporary setback; however, if it remains consistently below 49, it would signal the onset of a period marked by downward revisions to global growth forecasts.
So, what does this entire landscape mean for a crypto investor? In short: the headwinds are intensifying. Rising interest rates across three continents, a strengthening dollar, and climbing bond yields all point to a tightening of liquidity—a negative for crypto. The week’s market data bore this out: stocks were sold off, the "fear index" spiked, Bitcoin retreated from the $80,000 level toward the $75,000 range, and U.S. spot Bitcoin ETFs saw $1.28 billion in outflows—the worst weekly fund flow since June.
It is now possible to map out the financial transmission of an energy shock originating in the Middle East: oil prices rise, inflation climbs, central banks tighten policy, bond yields increase, a flight to safety begins, and—as the final link in this chain—cryptocurrencies are sold off. This week, the world watched this sequence unfold, step by step. However, there is a counter-possibility to keep in mind: if the recent decline in oil prices continues, inflation expectations could fall, potentially reversing the entire chain of events. In fact, the Bank of England’s recent, more encouraging remarks over the last 48 hours point precisely to this possibility.
Your watchlist should be shaped by this macro landscape: U.S. CPI data on Tuesday, the trajectory of energy prices in the Eurozone and the UK, Japan’s interest rate decision in December, and the Federal Reserve’s meeting on December 9th. Every major move in the crypto market will likely trace back to these events.
What is the lesson for the individual investor? Let’s synthesize the narrative of the week: we are in a period of synchronized monetary tightening—a rarity in the history of global monetary policy—triggered by an energy shock stemming from war, underpinned by a robust U.S. economy, and contrasted by weakening manufacturing in China. In this landscape, the greatest risk for an individual investor is to focus on a single wave rather than the entire sea—mistaking the decision of one central bank or a single inflation figure for the whole picture. The reality is a complex, interconnected whole playing out across dozens of economies simultaneously, and this week, that whole signaled a shift toward tightening.
Your practical strategy should consist of three layers. First, the calendar: Tuesday’s CPI release and the Federal Reserve’s decision on December 9th are the two key pillars for the coming month. Volatility tends to spike around these dates, making leveraged positions particularly vulnerable. Second, diversification: as interest rates rise, the correlation between various risk assets tends to approach one. Defensive assets—as evidenced by gold’s 5% gain this week—proved to be the only front that decoupled from the broader trend. Third, patience: throughout history, tightening cycles have always come to an end. The first signs of such an end appear in statements like the one from the Bank of England this week, suggesting that if energy prices fall, further rate hikes may not be necessary.
In short: as an individual investor—a small boat in a global tide of interest rate shifts—you cannot stop the waves, but you can adjust your vessel to navigate them. Reduce your position sizes, abandon leverage, mark your calendar, and keep liquidity on the sidelines so that, during moments of panic, you are in a position to acquire assets from those who lacked a plan.
$NAS100 $GBPUSD $EURUSD $USDJPY $BTC
#USCPIDataIncoming #USAIStocksHitHard #USNonfarmPayrolls #StockTalkSeason
#ShareWeekly
repost-content-media
The U.S. Consumer Price Index (CPI) data for October will be released on Tuesday—with economists expecting annual inflation to rise from 3.7% to approximately 3.9%—followed by the Producer Price Index (PPI) data on Friday. The Federal Reserve’s next interest rate decision is scheduled for December 9, and the market is currently pricing in a high probability of a quarter-percentage-point hike. It is also worth noting that the commentary provided by Fed officials following these data releases will be closely monitored.

Why will these two key events drive the market?

The calendar for the coming
User_any
The U.S. Consumer Price Index (CPI) data for October will be released on Tuesday—with economists expecting annual inflation to rise from 3.7% to approximately 3.9%—followed by the Producer Price Index (PPI) data on Friday. The Federal Reserve’s next interest rate decision is scheduled for December 9, and the market is currently pricing in a high probability of a quarter-percentage-point hike. It is also worth noting that the commentary provided by Fed officials following these data releases will be closely monitored.
Why will these two key events drive the market?
The calendar for the coming week revolves around two data points: the CPI on Tuesday and the PPI on Friday. Their significance stems from the current context; the Fed will seriously deliberate on an interest rate hike at its December meeting, and it will derive its final, comprehensive picture of inflation from these two reports. Market pricing is already sensitive, with a quarter-percentage-point increase heavily factored in. Such a clearly defined expectation amplifies the potential for a surprise—the market reacts not to the direction of the data itself, but to any deviation from those expectations.
Why is this so critical? Because the 165,000-job increase reported for October, combined with accelerating wage growth, has provided the Fed with assurance that the economy can withstand further tightening. Now, the focus shifts to inflation: if inflation comes in high while employment remains strong, a December rate hike becomes all but certain; conversely, if inflation proves surprisingly low, the Fed’s position weakens. In short, Tuesday’s figures represent the first half of the equation for the December decision, while Friday’s data constitutes the second half.
Your task is to review your positions in the hours leading up to these data releases. The market movement in the immediate seconds following the release of a figure is often misleading; a true assessment of the market’s direction only emerges once the details of the data—such as core inflation and service-sector components—have been fully digested.
What figures will be in play for Tuesday’s CPI (Consumer Price Index) report?
Economists generally expect annual consumer inflation to rise from 3.7% to approximately 3.9%. This remains far from the Federal Reserve’s 2% target—a level that reinforces the narrative that inflation has remained stubbornly persistent for the past three years. However, the headline figure does not tell the whole story; the real distinction lies in core inflation. The trajectory of prices, excluding food and energy, serves as the primary indicator of whether energy-related shocks have become embedded in consumer costs. As seen in this week’s data from the Eurozone, energy price hikes—stemming from developments in the Middle East—tend to ripple through utility bills, eventually spilling over into food and services. In the U.S., the key question is how far this "spillover" has progressed.
The mechanism of impact is clear: if inflation comes in higher than expected, bond yields and the U.S. dollar will likely rise, risk appetite will wane, and liquidity pressure on the crypto market will intensify—potentially exacerbating the strain already evidenced by last week’s $1.28 billion in fund outflows. Conversely, a figure below expectations would reverse this chain reaction: the probability of further interest rate hikes would diminish, the dollar would retreat, and pent-up demand—suppressed for weeks—would likely surface.
There is also a second layer to monitor: the immediate reaction from Federal Reserve officials following the data release. The direction of the market is shaped not only by the figure itself but also by how policymakers interpret that number. A hawkish tone keeps the door open for further hikes, even when data is positive; a dovish tone, meanwhile, frames poor data as merely temporary, helping to put the market at ease.
Why is the PPI, due on Friday, as significant as the CPI?
The Producer Price Index (PPI), to be released on Friday, is a data point often overlooked by most investors but closely monitored by professionals. The logic is straightforward: producers' costs are eventually passed on to consumers. Increases in the costs of raw materials, transportation, and energy first drive up prices at the factory gate; these costs then filter through to retail prices—and subsequently to the Consumer Price Index (CPI)—over the following months. In essence, the PPI serves as a precursor to inflation, offering a preview of consumer inflation in the months ahead.
The context this week is unique. With geopolitical pressures continuing to weigh on energy prices, cost-push inflation is rising more sharply on the producer side than on the consumer side; the uptick in transportation and storage costs suggests that this pass-through process is already underway. If this trend is confirmed on Friday, the thesis that "inflation has peaked and is now easing" will be significantly undermined—because today’s producer figures are tomorrow’s consumer figures.
The takeaway for you is this: while Tuesday’s CPI represents the heartbeat of the market, Friday’s PPI acts as its compass. If the CPI comes in favorable but the PPI looks poor, any optimism might be premature; however, if both come in strong (i.e., lower than expected), expectations for a December rate hike could genuinely soften, opening a window of relief for risk assets.
What will the week hold in terms of Fed officials' commentary?
Beyond the data calendar, the series of speeches scheduled throughout the week will also be instrumental in setting the market's direction. Every statement from policymakers following the CPI release should be evaluated with two questions in mind: Does the Federal Reserve perceive a lasting shift in inflation, and do they consider the conditions sufficient to justify a rate hike in December? Following this week’s employment data, it is known that several Fed members have signaled that inflation remains a concern; the data arriving on Tuesday will either sharpen or soften this tone.
The nuance here is that Fed members speak, in part, to manage market expectations. If the market has priced in a rate hike for December too aggressively, members might deliberately choose to temper that sentiment—because an overly aggressive expectation sets the stage for a sharp, counter-directional reaction once the actual data is released. Therefore, view their statements alongside the hard data as a form of "calibration" mechanism: if the market has run too far ahead, Fed members pull it back; if the market is hesitant, they nudge it forward.
Keep your monitoring process simple: after every significant statement, observe the two-way movement in bond yields. Regardless of the actual words spoken, the reaction of the bond market serves as the most honest interpretation of how the market has understood those remarks.
On the crypto front, will the $75,000 level take center stage once again?
The outlook for the crypto sector next week remains an extension of the last: Bitcoin is defending the $75,000 support zone, institutional fund flows are fragile, the "fear index" is elevated, and the vast majority of the market is awaiting an answer to a single question: will liquidity continue to tighten, or will there be a signal of easing? The data arriving on Tuesday and Friday will provide the answer.
Let’s lay both scenarios out on the table. In a "hot" inflation scenario, a rate hike in December becomes certain, the dollar and bond yields rise, the $75,000 level for Bitcoin is tested once again—and more aggressively—altcoins suffer steeper-than-average losses, and the crowded long positions in the futures market are liquidated. In a "moderate" inflation scenario, however, interest rate expectations soften, some of the risk appetite lost last week returns, and prices attempt a recovery from support zones. Neither scenario constitutes a price prediction; both serve as a map of the thresholds to watch.
Your compass consists of three key thresholds: Bitcoin’s weekly closes relative to the $75,000 level, the direction of U.S. spot fund flows between Tuesday and Friday, and the trajectory of bond yields following the data releases. If all three shift in the same direction, the trend is likely genuine; if only one shifts, it is merely "noise."
In short, the week ahead features two major data releases, five days of intense commentary, and a market braced for each event. During such weeks, the individual investor’s greatest enemy is the emotional reaction to the data release. A figure is announced, the chart spikes in a split second, and everyone suddenly feels like they’ve "missed the boat"—yet, treating data that has been on the calendar for weeks as a "surprise" is simply a sign of being unprepared. Your advantage lies in the fact that you already have the calendar in your hands.
Let your plan be defined by three points. First, keep leverage near zero on data-release days; during periods of high volatility, even the slightest adverse move can knock you out of the game. Secondly, do not focus on a single data point; instead, look at the combination of Tuesday and Friday. If the CPI (Consumer Price Index) comes in strong while the PPI (Producer Price Index) weakens—or vice versa—it sends a contradictory signal to the market, requiring patience rather than a hasty interpretation. Thirdly, everyone you encounter will have a forecast—whether on social media, television, or within the stock market—but rather than focusing on the number of forecasts, you should focus on clearly defining your own risk limits.
Ultimately, while "inflation weeks" may dictate the direction of the markets, it is an investor’s own discipline that determines their fate. The figures released on Tuesday and Friday will come and go; if your positions are structured to withstand these numbers in either direction, then regardless of the outcome, this week will work in your favor.
This content is for informational purposes only and does not constitute investment advice.
$BTC $ETH $NVDA $SPCX $NAS100
#USCPIDataIncoming #USAIStocksHitHard #USNonfarmPayrolls #StockTalkSeason
#ShareWeekly
repost-content-media
#QualcommAndArmEarningsInFocus
- Qualcomm and Arm Earnings Today: Why $QCOM and $ARM Will Decide The Next Chip Rebound
All eyes are on two names today. $QCOM and $ARM.
Qualcomm shares are in focus on Wall Street on Wednesday, November 4, as the semiconductor manufacturer prepares to announce its fourth-quarter fiscal 2026 financial results after the US stock market closes.
This is not a normal earnings day. This is the day that decides if the chip stocks rebound we saw yesterday continues, or fails.
Verified Earnings Setup:
$QCOM Qualcomm:
• Q3 FY2026 Recap: Qualcomm reported revenue of $9.9
discovery
#QualcommAndArmEarningsInFocus
- Qualcomm and Arm Earnings Today: Why $QCOM and $ARM Will Decide The Next Chip Rebound
All eyes are on two names today. $QCOM and $ARM.
Qualcomm shares are in focus on Wall Street on Wednesday, November 4, as the semiconductor manufacturer prepares to announce its fourth-quarter fiscal 2026 financial results after the US stock market closes.
This is not a normal earnings day. This is the day that decides if the chip stocks rebound we saw yesterday continues, or fails.
Verified Earnings Setup:
$QCOM Qualcomm:
• Q3 FY2026 Recap: Qualcomm reported revenue of $9.95 billion for Q3 FY2026, down 4% year over year but above analysts’ estimates of $9.66 billion. Non-GAAP earnings per share declined 20.2% to $2.21, marginally below the market expectation of $2.22. • On July 29, Qualcomm reported mixed financial results for Q3 FY2026. Revenue came in at $9.95 billion, down 4% year-over-year, but ahead of the Street's estimate of $9.66 billion.
• Q4 Schedule: Qualcomm scheduled its fiscal 2026 results for November 4, 2026, after the market close. Qualcomm announced on October 22, 2026, that it will publish its fourth-quarter and fiscal 2026 results on November 4, 2026, after the market close.
• Guidance for Q4: Revenue between $9.7 billion and $10.5 billion and non-GAAP EPS $2.05 to $2.25.
• Current Price: $QCOM 165.86 USD, up 0.86% today, 52-week range 121.99 - 259.92. Down -10.28% in last month.
$ARM Arm Holdings:
• Current Price: 192.165 USD, down -5.099% today, open 201.98, high 209.49, low 190.06. 52-week range 100.02 - 452.7. 5-day return -13.96%, 1-month -37.51%.
• ARM is the architecture behind every smartphone chip. Qualcomm, Apple, MediaTek, Nvidia all pay license fees to ARM. When ARM sneezes, mobile industry catches cold.
Why Qualcomm and Arm Earnings Are In Focus Together?
1. They Are The Same Ecosystem: Qualcomm's fiscal third-quarter revenue was 4.00 percent below the year-earlier level, while non-GAAP EPS came in at $2.21. Qualcomm's next earnings date is November 4, 2026. ARM licenses its CPU architecture to Qualcomm. Every Snapdragon chip sold means royalty to ARM. If Qualcomm's handset revenue falls 20% year over year, ARM's royalty growth also slows. They move together.
2. The AI Cost Concern: Qualcomm shares are in top focus today with quarterly earnings, growth outlook amid AI costs concerns. Wall Street is asking: Is AI spending in handsets and edge devices monetizing fast enough to cover R&D cost? Qualcomm reported revenue of $9.95 billion, down 4%, but still beat estimates. That tells you cost control is working, but growth is not yet back.
3. The Verdict Overhang: Qualcomm cites Arm verdict as Qualcomm stock sits 31.00 percent below its high. The legal dispute between Qualcomm and Arm over custom CPU license has been a dark cloud. A verdict in Qualcomm's favor would unlock its custom Oryon CPU roadmap for PCs and smartphones. A verdict for Arm would increase licensing costs for everyone.
What Will Decide The Rebound?
Chipmaker stocks rallied Tuesday as investors returned to AI-related shares. The Philadelphia Semiconductor Index advanced 3%. Broadcom and Nvidia jumped 3.1% and 2.3%. AMD jumped 6.2% premarket today on strong forecast.
For that rebound to hold, Qualcomm and Arm must deliver two things tonight:
A. QCOM: Must beat $9.7-10.5B revenue guidance and show handset inventory bottoming. If QCOM says Q1 2027 will grow, $QCOM goes to $180+ and drags $ARM up.
B. ARM: Must show royalty growth from AI smartphones and data center. ARM down -37.51% in one month means expectations are washed out. A small beat could trigger 10% short squeeze.
My Academic View:
This earnings is not about past quarter $2.21 EPS. It is about future architecture.
• If Qualcomm says its new AI PC chips with Arm architecture are ramping, both $ QCOM and $ARM win.
• If Qualcomm guides Q4 revenue above $10.1B midpoint, it confirms handset market bottomed after -20% decline.
• If Arm guides royalty growth back to double digits, $ARM recovers from 100 low toward 250.
For traders trading Taiwan stocks on Gate: $2454 MediaTek and $2330 TSMC are directly linked. MediaTek pays Arm royalty, TSMC fabricates Qualcomm chips. Gate launching 19 Taiwan stocks with USDT means you can trade this entire Qualcomm-Arm-TSMC triangle in Asian hours.
Tonight at 4 PM ET, after market close, $QCOM reports. $ARM reports close to same window.
Will Qualcomm and Arm confirm chip stocks rebound or kill it?
I am watching funding rates and $ QCOM $ARM premarket volume on Gate for clues.
#QualcommAndArmEarningsInFocus
repost-content-media
QCOM-2.69%
ARM-4.70%
AAPL+0.41%
NVDA-1.92%
AVGO-4.86%
#BTCBreaksPastMidtermBearishPattern
Bitcoin Just Broke Its 12-Year Midterm Bearish Pattern: This Time Is Different
For 12 years, Bitcoin followed the same midterm script. Fall before the vote, crash in Q4, then rally a year later.
This time, Bitcoin broke the pattern.
Verified Historical Pattern:
Bitcoin fell in the fourth quarter of each of the last three U.S. midterm election years, yet traded higher one year after every vote, according to an analysis by Joe Consorti.
Bitcoin's fourth-quarter losses were 17.3% in 2014, 43.5% in 2018 and 14.8% in 2022.
Over the longer historical comparis
discovery
#BTCBreaksPastMidtermBearishPattern
Bitcoin Just Broke Its 12-Year Midterm Bearish Pattern: This Time Is Different
For 12 years, Bitcoin followed the same midterm script. Fall before the vote, crash in Q4, then rally a year later.
This time, Bitcoin broke the pattern.
Verified Historical Pattern:
Bitcoin fell in the fourth quarter of each of the last three U.S. midterm election years, yet traded higher one year after every vote, according to an analysis by Joe Consorti.
Bitcoin's fourth-quarter losses were 17.3% in 2014, 43.5% in 2018 and 14.8% in 2022.
Over the longer historical comparison, Consorti reported Bitcoin gains of 24.5%, 44.9% and 92.3% one year after the election-day closes in 2014, 2018 and 2022, respectively.
Deepest midterm drops: -49.7% in 2018, -39.8% in 2014, -18.5% in 2022 FTX week — all recovered positive by day 365. 2018 cycle, the worst drawdown of the three, ended +45.8% one year after the midterm low.
This was the bearish midterm pattern everyone feared.
What Happened in 2026? Pattern Broken:
The US midterm elections took place on November 3, 2026. Around election day, Bitcoin was trading near $77,000, approximately 5.2% above its 200-day moving average of $73,169.
Bitcoin reached a low near $57,850 on July 1, approximately 125 days before the November election. By October 22, it had recovered to around $81,455, representing an increase of roughly 40% from that July low.
According to CoinDesk data, Bitcoin was trading near $76,990 on November 3, approximately 5.2% above its 200-day moving average of $73,169.
In 2014, 2018 and 2022, the situation on the midterm election day was the opposite, as bitcoin traded below the average, by about 35%, 9% and 22% respectively. These three years were bear markets.
Bitcoin BTC $78,299.12 has gone into each of the last three U.S. midterm elections licking its wounds. This time is different.
Bitcoin entered the November 3, 2026 U.S. midterm elections 5.2% above its 200-day moving average, breaking a pattern observed in 2014, 2018 and 2022.
The Election Day Selloff And Immediate Rebound:
Bitcoin price has reclaimed $78,000 after falling to a seven-week low near $75,600 as the U.S. midterm election results initially unsettled cryptocurrency markets. According to market data, BTC recovered to approximately $78,300 on November 4, trading nearly 1% higher after erasing its earlier losses.
The cryptocurrency dropped toward $75,600, its lowest level since September 17, after failing to maintain support around $77,000. Bitcoin trades at $77,786 (+1.64% 24h).
This is critical: Even the selloff was shallow compared to history. -49.7% in 2018 vs -7% drop to $75,600 in 2026. And it recovered within 24 hours to $78,300.
Why This Break Matters - Academic View:
1. 200-Day Average Position: In past midterms, Bitcoin was in bear market, below 200-day. Now it is 5.2% above $73,169. This means institutional cost basis is profitable, not underwater. Bearish pattern requires bearish positioning. We are not in it. 2. Q3 Strength: CoinGlass quarterly data shows Bitcoin closed the third quarter of 2026 up 42.7%, its second-best third quarter on record. In 2014, 2018, 2022, Q3 was weak. In 2026, Q3 was strong. Momentum is opposite. 3. One Year After Effect Still Valid: Even though Q4 bearish pattern broke, the one-year bullish pattern after midterms is still intact. Historical gains of 24.5%, 44.9% and 92.3% one year after election-day closes suggest that if history repeats, $77,000 today could be $95,000 - $148,000 one year after.
My Conclusion:
Bitcoin has declined during the August–September window before all three U.S. midterms in its trading history, then fallen further in the fourth quarter each time. Bitcoin fell into each of the last three U.S. midterms, yet rallied hard in late summer 2026, a break the halving clock explains better than the ballot box.
The midterm bearish pattern is broken because this cycle is driven by halving and ETF inflows, not just by election uncertainty.
Bitcoin did not bottom before those elections in past cycles, which he says is not the case now. We bottomed at $57,850 on July 1, 125 days before election, and rallied 40% to $81,455 before vote.
This is the first midterm where Bitcoin went into vote day strong, not weak.
If pattern holds, the next 12 months are historically the strongest period post-midterm. The bearish Q4 pattern is dead. The bullish one-year pattern is alive.
Are you positioned for the post-midterm rally?
#BTCBreaksPastMidtermBearishPattern
#ShareWeekly
$BTC
repost-content-media
BTC-0.67%
XRP Technical Outlook: XRP Consolidates Near $1.30 as Bulls Attempt to Defend Support
XRP is currently trading around $1.3049–$1.3051, consolidating after its recovery from the $1.00 region. The recent rally pushed price toward the $1.37 area, but XRP faced rejection and has since moved into a corrective phase.
The broader recovery has lost some momentum, with price trading below the 50, 100, and 200 EMAs. However, XRP is holding near the 20 EMA and attempting to stabilize around $1.30.
The immediate focus is whether buyers can defend the $1.30 area and reclaim the $1.3243–$1.3362 resistance z
asiftahsin
XRP Technical Outlook: XRP Consolidates Near $1.30 as Bulls Attempt to Defend Support
XRP is currently trading around $1.3049–$1.3051, consolidating after its recovery from the $1.00 region. The recent rally pushed price toward the $1.37 area, but XRP faced rejection and has since moved into a corrective phase.
The broader recovery has lost some momentum, with price trading below the 50, 100, and 200 EMAs. However, XRP is holding near the 20 EMA and attempting to stabilize around $1.30.
The immediate focus is whether buyers can defend the $1.30 area and reclaim the $1.3243–$1.3362 resistance zone. A sustained move above this zone would improve the recovery outlook, while a breakdown below support could expose XRP to further downside.
EMA Structure
* 20 EMA: $1.3030
* 50 EMA: $1.3362
* 100 EMA: $1.3243
* 200 EMA: $1.3634
XRP is trading slightly above the 20 EMA but remains below the 50, 100, and 200 EMAs. This indicates that short-term price action is attempting to stabilize, while the broader trend still faces significant overhead resistance.
The $1.3243–$1.3362 region is the first important resistance zone. Reclaiming the 50 EMA at $1.3362 would strengthen the short-term recovery, while the 200 EMA near $1.3634 remains a major barrier.
Fibonacci Levels
Based on the visible chart levels:
* 0.236: Around $1.3459
* 0.382: Around $2.00
* 0.5: Around $2.32
* 0.618: Around $2.64
* 0.786: Around $3.08
XRP is trading below the visible 0.236 Fibonacci resistance area. A sustained recovery above $1.3459 would be an early sign of improving momentum. The higher Fibonacci levels represent broader recovery objectives rather than immediate targets.
Bullish Scenario
If XRP holds the $1.30 support area and buyers manage to reclaim the nearby EMA resistance zone, the price could attempt a recovery toward:
* $1.3243
* $1.3362
* $1.3459
* $1.3634
* $1.3773
* $1.4475
* $1.5204
A decisive move above $1.3459 would improve the bullish outlook. Reclaiming $1.3634–$1.3773 could open the way toward the $1.4475 resistance area.
Pullback Scenario
If XRP fails to hold above $1.30 and selling pressure increases, the following support areas deserve attention:
* $1.3030 — 20 EMA
* $1.30 — Immediate psychological support
* $1.27–$1.25 — Potential lower support area
* $1.00 — Major historical support region
A sustained breakdown below $1.30 would weaken the current consolidation structure and increase the possibility of a deeper correction. The $1.00 region remains an important broader support reference on the chart.
RSI Momentum
* RSI: 47.82
* RSI Signal Average: 40.26
RSI is below the neutral 50 level, showing that bullish momentum remains limited. However, the RSI is above its signal average, suggesting a modest improvement in short-term momentum.
A move above 50–55 would provide stronger confirmation of a recovery attempt. If RSI turns lower and falls below 40, downside pressure could increase.
Market Structure & Liquidity
XRP has experienced a prolonged decline from its previous highs before finding support around the $1.00 region. The subsequent recovery pushed price toward the $1.37 area, but buyers have struggled to maintain that upward momentum.
The latest price action shows lower highs and consolidation around $1.30–$1.34. The market is currently testing whether the $1.30 region can hold as support.
The broader structure remains under pressure while XRP trades below the 50, 100, and 200 EMAs. A confirmed reclaim of the $1.3459–$1.3773 zone would be needed to establish a stronger bullish recovery.
Key Levels
Resistance
* $1.3243
* $1.3362
* $1.3459
* $1.3634
* $1.3773
* $1.4475
* $1.5204
Support
* $1.3030
* $1.30
* $1.27–$1.25
* $1.00
Final Outlook
XRP remains neutral-to-bearish while trading below the $1.3362–$1.3634 resistance zone. The price is attempting to stabilize around $1.30, but the broader recovery still needs confirmation.
A sustained breakout above $1.3459 could open the path toward $1.3773, followed by $1.4475. On the downside, losing $1.30 would increase the risk of a deeper correction.
Bias: Neutral-to-bearish below $1.3459 | Breakout above $1.3773 could strengthen recovery toward $1.4475–$1.5204.
Analysis based on the provided XRP/USDT 1D chart dated November 4, 2026. These levels represent technical scenarios, not guaranteed outcomes.
$XRP ‌
repost-content-media
XRP-1.15%
The market caught its breath just ahead of the U.S. midterm elections. Riskier tech stocks, which had been sold off for days, saw renewed buying interest. The Philadelphia Semiconductor Index rose 2.6%, snapping a three-day losing streak.
There was a rotation at play within this movement. While Apple—often viewed as a "safe" tech play—fell 1.9% following a warning that memory costs would squeeze margins during the holiday quarter, chipmakers took center stage. Nvidia climbed 2.3% after a four-day slide, moving back toward the $5 trillion market cap threshold. Ahead of its earnings report, AMD
User_any
The market caught its breath just ahead of the U.S. midterm elections. Riskier tech stocks, which had been sold off for days, saw renewed buying interest. The Philadelphia Semiconductor Index rose 2.6%, snapping a three-day losing streak.
There was a rotation at play within this movement. While Apple—often viewed as a "safe" tech play—fell 1.9% following a warning that memory costs would squeeze margins during the holiday quarter, chipmakers took center stage. Nvidia climbed 2.3% after a four-day slide, moving back toward the $5 trillion market cap threshold. Ahead of its earnings report, AMD shares rose between 3.7% and 5.5% during the day, while Micron gained 2.6% and Broadcom added 3.1%.
Analysts interpret this as a rebound—a "buy-the-dip" response—following the Nasdaq 100’s decline of more than 10% from its peak, which pushed the index into correction territory. In other words, the decline itself became the catalyst for buying.
Why was AMD’s earnings report such a major talking point?
Because it presented a strong picture right in the midst of widespread market anxiety. Total revenue surged 45% to $13.4 billion, exceeding the upper end of the company’s own guidance.
The real story lay in the data center segment. Revenue hit a record $8.5 billion—up 97% year-over-year and 27% quarter-over-quarter—accounting for 64% of total revenue. This growth was driven by EPYC processors and the launch of the new Instinct MI450 series GPUs. Earnings per share jumped 74% to $2.09, and the operating margin climbed to 29%.
Why is there such ambitious talk regarding 2027?
The company has revised its outlook upward—not just for the present, but for the future as well. For the fourth quarter, revenue is projected at approximately $17 billion—a 66% year-over-year increase. Looking ahead to 2027, expectations point to revenue growth exceeding 80%.
This projection implies that the demand for artificial intelligence hardware is expected to remain robust through 2027. In other words, the investment cycle is not over; it is simply shifting gears.
How should one interpret the difference between Nvidia and AMD?
While both operate in the same sector, they possess distinct characteristics.
Nvidia is the dominant leader, with a valuation exceeding $5 trillion, whereas AMD sits in the $850–900 billion range. Over the last four quarters, Nvidia has grown by 83.4% and AMD by 39.5%; however, AMD is gaining momentum, driven by a 97% surge in its data center segment.
In terms of valuation, the picture shifts. Nvidia trades at approximately 14 times its projected earnings for the next 12 months, while AMD trades at around 37 times. Essentially, Nvidia—with its higher profit margins and cash flow—trades at a lower multiple, whereas AMD’s valuation already reflects a significant portion of its anticipated growth.
Is this a temporary reaction, or the start of a new trend?
Two questions will determine the answer.
First, what will be the return on AI investments? Will the infrastructure spending by major cloud companies—projected to reach roughly $800 billion in 2026 and $1.2 trillion by 2027—actually translate into profit?
Second, how resilient are these valuations? For stocks trading at high multiples, there is always a risk of a market correction if expectations are not met. In short, the underlying dynamics appear strong, but the critical question is to what extent the current price has already "priced in" this strength.
What should you take away from this?
Nvidia, with its proven scale and profitability, represents a search for stability at a lower valuation multiple. AMD, on the other hand, carries a higher risk premium, driven by its potential to expand market share and the promise of aggressive growth.
This recovery—arriving ahead of the earnings season—shows that the sector remains vibrant, while also serving as a reminder of its inherent fragility. As long as infrastructure spending continues, the narrative will persist; however, each earnings report will serve as a new test of how much of this story is already reflected in the stock price.
This content is for informational purposes only and does not constitute investment advice.
$AAPL ‌ $MU ‌$NVDA ‌$AMD ‌
#ChipStocksRebound #GateSquareTradingChallenge #ShareWeekly #QualcommAndArmEarningsInFocus #DemocratsWinBothChambers
‌
repost-content-media
AAPL+0.41%
NVDA-1.92%
AMD-8.76%
MU-2.56%
AVGO-4.86%
Gate has launched the "Gate Security Guardian" program—a new initiative designed to elevate account security—making it available for free to users who meet specific security criteria. This is more than just a security setting; it serves as an additional layer of protection for your account.

Perhaps the most notable feature is that, under certain conditions, users can file a compensation claim in the event of an unauthorized asset transfer. In other words, it doesn’t just alert you—it’s also designed to have your back in specific situations.

What exactly does it protect against?

There are th
User_any
Gate has launched the "Gate Security Guardian" program—a new initiative designed to elevate account security—making it available for free to users who meet specific security criteria. This is more than just a security setting; it serves as an additional layer of protection for your account.
Perhaps the most notable feature is that, under certain conditions, users can file a compensation claim in the event of an unauthorized asset transfer. In other words, it doesn’t just alert you—it’s also designed to have your back in specific situations.
What exactly does it protect against?
There are three main scenarios, all of which could potentially happen to anyone:
First: Phishing and malware. This includes scenarios such as clicking on a fraudulent link, entering your credentials on a fake website, or having your account compromised via malicious software installed on your device.
Second: Device control and remote access. This occurs when a tool infiltrates your phone, allowing transactions to be carried out without your knowledge.
Third: SIM card theft or fraudulent SIM swapping. This happens if your phone is lost, or your SIM card is stolen or reissued in your name, granting unauthorized access to your account.
For an approved incident, you may file a compensation claim for up to $200,000 in a single instance. However, there are clear exclusions: transactions initiated by you personally, transfers authorized by you under the direction of a third party, erroneous transactions, and losses resulting from market fluctuations are not covered.
How do you qualify for this protection?
There are three primary requirements:
Your account security score must be at least 80 out of 100. You must have completed KYC Level 2 identity verification. Additionally, you are expected to have fulfilled the necessary security steps, and your account must be in good standing. If you meet these requirements, you can activate the feature for free via the Gate app—by navigating to Profile > Security Center > Gate Security Guardian—or through the web interface.
Why doesn’t it become active immediately? What is the significance of the 30-day period?
Protection does not begin the moment you enable the program; instead, a 30-day security-strengthening phase commences. Throughout these 30 days, your score must remain at or above 80 without interruption.
Once this period concludes, your account status shifts to "Protection Active," and you become eligible to submit a claim. If your score drops below 80 during this phase, the protection is suspended. If you manage to raise your score back to 80 within 48 hours, the process restarts from day one. If, after 48 hours, your score remains below 80, the program is terminated; should you choose to reapply, the 30-day process will begin anew.
This detail conveys an important message: security is not a simple "on/off" button—it is a habit.
How does the compensation process work in the event of an incident?
For a claim to be considered, the incident must have occurred while your account was in the "Protection Active" status, and your score must have remained above 80 for the 30 days leading up to the incident.
Following an incident, you are required to contact the security team via the "My Protection" section within 45 days. You must also provide documentation of a formal report filed with law enforcement, as well as records of the asset transfers in question.
Should you view this as insurance?
No. Gate explicitly states that this is not an insurance product. Each claim is evaluated according to the platform’s rules, and there is no guarantee of compensation for every submission.
Therefore, you should view this not as your primary line of defense, but rather as a supplementary layer of protection. A strong password, two-factor authentication, and device security remain your first line of defense. This shield serves as an additional safety net that kicks in once you have done your part.
This content is for informational purposes only and does not constitute investment or financial advice.
#GateGuardNowAvailableForFree
repost-content-media
Bitcoin After the Election 👀
Following the November 3rd midterm elections, Bitcoin’s technical position stands outside the cycle we have come to expect. While we typically see a weaker market structure during election periods, the picture is different this time.
The price remains above the 200-day simple moving average (SMA). This indicates that the long-term trend has not yet been disrupted, despite the uncertainty surrounding the election. In other words, while there is some short-term "noise," the broader directional trend remains intact.
What does the 200-day moving average tell us?
A his
User_any
Bitcoin After the Election 👀
Following the November 3rd midterm elections, Bitcoin’s technical position stands outside the cycle we have come to expect. While we typically see a weaker market structure during election periods, the picture is different this time.
The price remains above the 200-day simple moving average (SMA). This indicates that the long-term trend has not yet been disrupted, despite the uncertainty surrounding the election. In other words, while there is some short-term "noise," the broader directional trend remains intact.
What does the 200-day moving average tell us?
A historical comparison is useful here. During the midterm elections of 2014, 2018, and 2022, Bitcoin was trading below its 200-day moving average; however, in 2026, this trend has reversed.
Currently, the price is hovering approximately 5% above this average. While this divergence is not a definitive bullish signal on its own, it confirms that the long-term structure has not weakened. The uncertainty brought on by the elections has not dragged the trend downward as it did in the past. Consequently, this level serves as a compass—a reference point indicating the current state of the trend.
Why are we seeing outflows from ETFs?
Although the technical outlook appears strong, there has been a short-term "tapping of the brakes" on the institutional side. On November 2nd, spot Bitcoin ETFs in the United States experienced net outflows of nearly $400 million, with the bulk of these outflows coming from the fund of the largest issuer.
What does this mean? Institutional investors are remaining cautious amid post-election uncertainty. Their appetite for buying hasn't vanished, but they have chosen to wait before taking on further risk. In short, while the broader price trend remains intact, institutional capital is opting to stay on the sidelines for the short term.
Why are geopolitical risks creating pressure? A second factor is the situation around the Strait of Hormuz. Reports of tankers striking mines and vessels being intercepted in the region are fueling concerns regarding the global oil supply. While the tension surrounding oil does not directly impact Bitcoin, it generally dampens risk appetite.
Risky assets tend to move in tandem. When oil prices climb, or when there is significant movement in the dollar and bond markets, caution also rises within the crypto space. This is not a weakness specific to Bitcoin, but rather a reflection of the broader risk sentiment.
What do the miners say?
On the other side of the picture, we have data from the network itself. Miners' revenue for October reached its highest level in the last 11 months, indicating that network activity and demand for transactions remain robust.
While ETF outflows and geopolitical risks exert short-term downward pressure on prices, on-chain data—such as mining revenue—suggests that the underlying infrastructure remains healthy. One reflects the current state of the price, while the other reflects the current state of the network; they do not always move in sync.
There are two opposing forces at play. While the asset's position relative to its long-term average suggests a strong underlying structure, ETF outflows and geopolitical headlines keep the potential for short-term volatility alive.
What you should watch here is whether the 200-day moving average holds as support, and whether the ETF outflows represent a one-off event or the beginning of a trend spanning several days. On the geopolitical front, the duration of the correlation between oil prices and risk appetite will be a key deciding factor.
This content is for informational purposes only and does not constitute investment advice.
$BTC ‌ ‌
#BTCBreaksPastMidtermBearishPattern
#DemocratsWinBothChambers
#GateSquareTradingChallenge
#ShareWeekly
BTC-0.67%
Perpetual futures open the door
Perpetual futures—an indispensable instrument in crypto markets—have opened the door to traditional finance. Yet, beyond this door lies more than just a new product; there is a complex legal battle, shaped by disputes over jurisdictional authority among regulatory bodies and objections from market participants.
Approval has been granted, and the products are being prepared for listing. However, the permanence of this approval hinges on decisions yet to be reached in the courtroom.
What does the approval signify, and what is "dual oversight"?
In the United States
User_any
Perpetual futures open the door
Perpetual futures—an indispensable instrument in crypto markets—have opened the door to traditional finance. Yet, beyond this door lies more than just a new product; there is a complex legal battle, shaped by disputes over jurisdictional authority among regulatory bodies and objections from market participants.
Approval has been granted, and the products are being prepared for listing. However, the permanence of this approval hinges on decisions yet to be reached in the courtroom.
What does the approval signify, and what is "dual oversight"?
In the United States, the agency that oversees commodity futures has, for the first time, authorized the trading of perpetual futures contracts based on individual stocks on regulated platforms. Under the Modernization Act—which came into effect in 2000—these products have been classified as "security futures contracts."
This classification is critical: it dictates that these products can only be listed on exchanges registered with both regulatory bodies, and they will be subject to joint oversight by authorities covering both commodities and securities. In other words, they fall under the regulatory frameworks of two separate agencies rather than just one.
Why is the traditional sector objecting?
Immediately following the approval, an alliance of traditional financial institutions initiated legal action. They have requested the revocation of the approval, arguing that these products are not "security futures," but rather security-based swaps—a category that falls under the exclusive jurisdiction of the securities regulator.
The core of this objection goes beyond mere financial risk; the fundamental question concerns where the boundaries of regulatory authority should be drawn. Whether a product is classified as a "futures contract" or a "swap" determines which agency holds the authority to oversee it. The first ruling from the court has arrived—but isn’t the message clear?
The initial decision from the U.S. District Court for the Southern District of New York denied the alliance’s request to temporarily halt the trading of these products. The court reasoned that it had not been sufficiently demonstrated that the failure to grant an injunction would result in irreparable harm. In other words, for the time being, the products may continue to be traded.
However, the second part of the ruling is more significant. While denying the request for an injunction, the court indicated that the alliance has a strong likelihood of succeeding on the merits of the case. The court suggested that classifying perpetual futures as "security futures contracts" might constitute an overreach of authority, noting that, in terms of structure, these contracts align more closely with swap agreements.
How is the crypto model being applied to stocks?
Perpetual futures are instruments with no fixed expiration date; they offer flexible leverage and potentially extended trading hours. Adapting this model—which has been used in crypto markets for years—to equities represents a major structural shift in traditional derivatives markets.
Yet, the pace and scope of this transformation are not merely technical matters. It is a process that necessitates the redrawing of jurisdictional boundaries between regulatory bodies. Until it is clarified which agency holds oversight authority, the precise mechanics of how these products will function remain uncertain.
For individual investors, the situation requires weighing the flexibility offered by this new instrument against the legal and operational uncertainties that accompany it.
The fact that a product is traded on a regulated platform does not mean its legal status is definitively settled. While the legal proceedings are ongoing, the final shape of the regulatory framework remains uncertain.
During such periods, rather than being swayed by the allure of new products, it is more prudent to seek an understanding of the legal foundation upon which a product rests, as well as the associated regulatory risks. Monitoring how funding payments operate, understanding collateral requirements, and considering how a potential change in classification might affect trading hours or access becomes more significant than focusing solely on price.
This content is for informational purposes only and does not constitute investment advice.
$NAS100 $MU $AAPL $NVDA $MSFT
#Gate股票畅聊季 #GateStockTalkSeason #GateSquareTradingChallenge #ShareWeekly
#USEquityPerpetualFuturesGoLive
repost-content-media
NAS100-0.07%
MU-0.63%
AAPL-0.05%
NVDA-0.35%
MSFT+0.59%
Cryptocurrencies after the election 🔎
Following the midterm elections in the United States, the new political landscape has shifted how markets price the balance between regulatory oversight and fiscal policy. With the Democrats securing a majority in both the House of Representatives and the Senate, major digital assets initially experienced a sharp pullback, followed by a notable recovery.
This movement is best interpreted as a rapid repricing of political risk rather than a fundamental shift in demand.
What happened to prices?
After dipping toward $75,600 during the overnight session, Bitc
User_any
Cryptocurrencies after the election 🔎
Following the midterm elections in the United States, the new political landscape has shifted how markets price the balance between regulatory oversight and fiscal policy. With the Democrats securing a majority in both the House of Representatives and the Senate, major digital assets initially experienced a sharp pullback, followed by a notable recovery.
This movement is best interpreted as a rapid repricing of political risk rather than a fundamental shift in demand.
What happened to prices?
After dipping toward $75,600 during the overnight session, Bitcoin climbed above $78,000, eventually reaching approximately $80,290. Ethereum showed similar momentum, rising by about 7% to approach $2,434 before stabilizing around $2,421.
During this recovery, the total market capitalization increased by approximately $87 billion, reaching $2.63 trillion. The Fear & Greed Index rose from 26 to 34; while still in the "fear" zone, the trend has shifted upward.
This V-shaped movement appears to be a reaction to the resolution of uncertainty rather than a response to any single piece of news.
What happened with leverage?
Activity in the derivatives market was intense. Total liquidations over the last 24 hours reached $468.66 million, with $266.24 million coming from long positions. In other words, long positions were wiped out during the decline, followed by a swift rebound.
There was also significant activity in the options market on election day. Approximately $660 million worth of Bitcoin options changed hands in block trades, with about $420 million of this volume consisting of call option purchases. This points to positioning geared toward a recovery; the market was shaken initially, but those betting on a rebound subsequently stepped forward.
Why is this recovery not surprising?
From a long-term and dialectical perspective, the initial decline followed by a recovery suggests that a "Democratic sweep" had already been largely priced in. Prediction markets had assigned a high probability to this outcome, meaning the scope for a shock was limited.
The structural implication concerns the legislative front. A divided government creates additional friction for the market structure bill—a piece of legislation already facing gridlock in the Senate. With existing regulatory guidance from the SEC and the CFTC remaining in place, the likelihood that new, comprehensive legislation will be delayed until 2027 has increased.
Where did the macro tailwind come from?
The recovery is not merely an intra-crypto story; macro factors also provided support. Political gridlock reduced the prospect of significant fiscal expansion, which pushed down Treasury yields and the dollar. A weaker dollar, combined with expectations for a pause in interest rate hikes, created a supportive environment for risk assets, including crypto.
In short, the resolution of political uncertainty, coupled with easing in the dollar and bond yields, opened a short-term window for risk appetite.
Is this rally sustainable?
The real question here is whether this recovery is simply a "relief rally" triggered by the removal of uncertainty, or if it can be sustained by actual spot demand. The divergence between short-term optimism and long-term structural challenges remains at the core. Until security concerns, the need for regulatory clarity, and liquidity conditions are addressed, the sustainability of the post-election rally will depend on the extent to which spot demand enters the market.
Key indicators to watch include whether the rise in total market capitalization is confirmed by spot trading volume, whether the "fear index" has moved out of the "fear zone," and whether the easing in bond yields and the US dollar continues.
This content is for informational purposes only and does not constitute investment advice.
$BTC ‌$ETH ‌#DemocratsWinBothChambers #BTCBreaksPastMidtermBearishPattern
#GateSquareTradingChallenge #WCTCS9 #ShareWeekly
repost-content-media
BTC-0.67%
ETH-1.26%
Why are prices falling even as crude oil inventories have been shrinking for five weeks?
Official energy data released on November 4 showed that commercial crude oil inventories fell by 865,000 barrels for the week ending October 30, dropping to 409.8 million barrels—the fifth consecutive weekly decline. Analysts had expected a draw of 1.7 million barrels, so the actual figure was smaller than anticipated.
Typically, when supply tightens, prices find support. This time, the opposite occurred: while physical barrels dwindled, the price of "paper" (financial/futures) barrels fell.
Is the physica
User_any
Why are prices falling even as crude oil inventories have been shrinking for five weeks?
Official energy data released on November 4 showed that commercial crude oil inventories fell by 865,000 barrels for the week ending October 30, dropping to 409.8 million barrels—the fifth consecutive weekly decline. Analysts had expected a draw of 1.7 million barrels, so the actual figure was smaller than anticipated.
Typically, when supply tightens, prices find support. This time, the opposite occurred: while physical barrels dwindled, the price of "paper" (financial/futures) barrels fell.
Is the physical market truly tight?
Yes. Commercial inventories are currently 4% below their five-year average. Total product supply—a proxy for demand—has averaged 21.2 million barrels per day over the last four weeks, up 4.2% compared to last year. The refinery utilization rate rose from 92.8% to 94.5%, with the volume of crude oil processed increasing by 199,000 barrels per day to reach 16.7 million.
In short, demand is not falling, refineries are operating at higher intensity, and inventories are shrinking nonetheless. The physical side of the market points to tightness.
Where does the real squeeze lie?
Not in crude oil, but in diesel. Distillate inventories—which include diesel and heating oil—fell by 3.6 million barrels to 99.3 million. This is the lowest level since May 2003 and sits 13% below the five-year average.
Coming just before the winter season in the Northern Hemisphere, this data highlights growing vulnerability within the refined products sector. The availability of crude oil does not guarantee an abundance of diesel.
Why did prices fail to react to this data? Another leading industry indicator had pointed to a more significant drawdown, but official figures and geopolitical developments overshadowed it. WTI fell by more than 2.9% to around $93.30, while Brent saw a brief dip below $100 before staging a modest recovery.
On that day, the market focused more on politics than on inventory levels. The results of the midterm elections and signals of potential diplomatic engagement with Iran led to a repricing of the likelihood of disruptions in the Strait of Hormuz. The geopolitical risk premium—which had previously supported prices—was rapidly pared back.
How should this divergence be interpreted in the long term?
From a long-term, dialectical perspective, the picture is multi-layered: the physical market remains tight, while the "paper" (financial) market is shedding its risk premium.
The short-term trigger is political, but the structural bottleneck lies within the refining sector. Even with record-breaking production in the United States, refineries are unable to increase diesel output due to efficiency constraints and limitations on operational capacity. Distillate inventories are expected to remain below their five-year average for the better part of 2027.
This implies that while headline crude oil prices may fluctuate based on macroeconomic headlines, refined products—such as diesel and heating oil—will remain highly sensitive to any potential supply shocks.
One must choose between these two indicators: physical inventories or the risk premium embedded in the financial markets?
In the short term, the risk premium is driving prices; the post-election landscape and diplomatic signals have eased concerns regarding the Strait of Hormuz. In the medium term, however, physical realities will be the deciding factor: inventories are below average, diesel stocks are at historic lows, and winter is just around the corner. What you need to monitor is whether refinery utilization can remain at this high level, whether distillate stocks can recover ahead of winter, and to what extent the geopolitical premium has been permanently erased. "Paper" barrels move quickly, while physical barrels recover slowly.
This content is for informational purposes only and does not constitute investment advice.
$XTIUSD ‌$XBRUSD ‌#GateSquareTradingChallenge #WCTCS9
#𝐎𝐈𝐋
repost-content-media
XTIUSD+0.00%
XBRUSD+0.00%
In the U.S., stock index futures have recovered from an election-related dip seen during the overnight session, as traders shift their focus back to the broader macroeconomic landscape. Stronger-than-expected labor market data and rising oil prices have brought the debate over the Federal Reserve’s policy path to the forefront, while digital assets remain under pressure from institutional outflows.
In the short term, the resilience of the labor market is acting as a headwind for risk assets; meanwhile, long-term infrastructure integration continues to progress quietly. In other words, while pr
User_any
In the U.S., stock index futures have recovered from an election-related dip seen during the overnight session, as traders shift their focus back to the broader macroeconomic landscape. Stronger-than-expected labor market data and rising oil prices have brought the debate over the Federal Reserve’s policy path to the forefront, while digital assets remain under pressure from institutional outflows.
In the short term, the resilience of the labor market is acting as a headwind for risk assets; meanwhile, long-term infrastructure integration continues to progress quietly. In other words, while prices remain under pressure, the underlying infrastructure is maturing.
How resilient is the U.S. labor market?
Private-sector employment for October came in at 86,000—surpassing the 67,000 expected—and job openings climbed to a four-month high. This complicates the Federal Reserve’s task. Although the 10-year Treasury yield has eased to around 4.93% and the dollar index has retreated to a one-month low of 101.4, the possibility of an interest rate hike remains on the table.
Markets continue to price in the chance of a rate hike at the December 9 meeting. Friday’s non-farm payrolls data will be a key indicator; a strong reading would likely lead to tighter rate expectations—putting pressure on crypto—while a weak reading could alleviate pressure from the dollar, offering a temporary reprieve.
Why are energy and inflation back on the agenda?
Geopolitical tensions have escalated following reports of an attack on an island near the Strait of Hormuz, pushing Brent crude above $100 and bringing WTI close to $97. Simultaneously, inflation in the Eurozone has reached a three-year high, reinforcing expectations for an interest rate hike in December. On one hand, there is inflationary pressure stemming from oil; on the other, an inflation surprise originating from Europe. Both factors complicate the position of central banks and dampen risk appetite.
Why is capital flowing out of the crypto space?
Spot Bitcoin ETFs in the U.S. have recorded a net outflow of approximately $1.16 billion over the last three sessions; the $643 million outflow on October 30th marked the largest single-day withdrawal since the end of June. The Fear & Greed Index remains in the 30s—firmly within the "fear" zone.
Bitcoin is trading around $80,100, but sustained momentum requires consistent daily inflows exceeding $200 million. Without this, price action above $80,000 remains vulnerable to selling pressure. Current price movements are driven more by derivatives and macro sentiment than by spot accumulation.
What is happening on the infrastructure front?
Beneath the surface of ETF outflows and price consolidation, traditional financial infrastructure continues to integrate with digital assets. Developments such as an exchange operator’s plan to bring perpetual futures to the U.S., a clearinghouse launching tokenization services, and a payments company securing approval for a trust bank represent structural milestones—independent of daily price volatility.
These developments signal the maturation of institutional plumbing; even if capital flows remain hesitant, the underlying infrastructure continues to advance.
What is the real threshold to watch?
In the near term, the key variable is whether the $80,000 level can hold as a structural support. Without robust spot ETF inflows, any recovery remains fragile.
There are three signals you should keep an eye on. How will Friday’s employment data shape interest rate expectations? Is the geopolitical premium in oil prices permanent or transitory? And will ETF inflows turn positive again and surpass the $200 million threshold? Macro pressures are defining the short term, while infrastructure integration is shaping the long term.
This content is for informational purposes only and does not constitute investment advice.
#DemocratsWinBothChambers
#CRYPTO #MARKET
#GateSquareTradingChallenge #Gate股票畅聊季
$BTC $GT $ETH $SOL $NAS100
repost-content-media
INDEX+0.00%
BTC-0.67%
GT-2.41%
ETH-1.26%
SOL-0.77%
$TRUMP ‌$MELANIA ‌$WLFI ‌
The Democrats securing a majority in Congress has triggered a sharp divergence in the digital asset market. While tokens associated with political figures faced intense selling pressure, mainstream crypto assets saw a recovery.

This divergence highlights that political sentiment—much like liquidity—can serve as a primary driver for certain assets.

What happened to politically-linked tokens?

Over the last 24 hours, the trend has been distinctly negative.

The official Trump-related token fell 17% to $1.33. World Liberty Financial dropped more than 7% to $0.047. A
User_any
$TRUMP ‌$MELANIA ‌$WLFI ‌
The Democrats securing a majority in Congress has triggered a sharp divergence in the digital asset market. While tokens associated with political figures faced intense selling pressure, mainstream crypto assets saw a recovery.
This divergence highlights that political sentiment—much like liquidity—can serve as a primary driver for certain assets.
What happened to politically-linked tokens?
Over the last 24 hours, the trend has been distinctly negative.
The official Trump-related token fell 17% to $1.33. World Liberty Financial dropped more than 7% to $0.047. A token associated with the First Lady declined by approximately 13% to around $0.066. The total market capitalization of the political memecoin sector shrank by over 16% to $477 million, while trading volume surged by 123% to $437 million.
A decline in value accompanied by an increase in volume points to a sell-side trend.
Why did the broader market move in the opposite direction?
During the same period, mainstream assets rallied. Bitcoin rose by approximately 4% to $80,500, and Ethereum climbed 6% to $2,433. The total crypto market capitalization increased by 3.4% to $2.69 trillion.
In short, while politically-linked tokens reacted to the shift in the balance of power in Washington, Bitcoin and Ethereum responded to macroeconomic factors and institutional capital flows. It was a day marked by a breakdown in correlation.
What are the implications regarding financial exposure and regulation? One of the topics that has emerged following the election concerns financial exposure and congressional oversight.
According to research by a news agency, it is alleged that approximately $2.3 billion in earnings had been generated from family-linked crypto ventures as of the end of April. Reports indicate that a 2025 financial disclosure lists over $1 billion in crypto-related income, alongside roughly $635 million in royalties from "memecoins."
It is reported that the incoming chair of the House Oversight Committee has signaled a potential investigation, advising relevant parties to "retain counsel." The scope of inquiry may include matters such as a $500 million investment from the Emirates into "World Liberty Financial" and the potential pardon of a cryptocurrency exchange founder. These remain in the realm of allegations and proposed actions; the specific trajectory of any investigative process is not yet clear.
What does this signify?
From a long-term, dialectical perspective, the inherent fragility of assets that derive their value from political proximity becomes apparent. Investors in such tokens are not betting on a specific technology or a business capable of generating cash flow; rather, they are betting on the continued popularity and influence of a political figure. Should the political landscape shift, the demand structure can collapse rapidly.
This is why structural differentiation is significant. As core assets mature, the correlation between political narratives and their valuation may weaken; conversely, for narrative-driven tokens, the political narrative may remain the sole driver of value.
What should be monitored moving forward?
The subpoena power held by Congress allows for the formal request of documents and testimony from private entities. This could lead to greater scrutiny of the financial structures underpinning these ventures. The focus may extend beyond the tokens themselves to a broader network of business and political relationships.
The key variable here is whether this regulatory and legal pressure will have a lasting impact on the sustainability of these ventures, or whether it will remain a cyclical phenomenon tied to the current political configuration. For the broader crypto market, the outcome will serve as a test of how effectively the industry can decouple its core technological and financial infrastructure from assets driven by politically charged narratives.
This content is for informational purposes only and does not constitute investment advice.
#DemocratsWinBothChambers
#WCTCS9
#GateSquareTradingChallenge
repost-content-media
TRUMP-0.95%
MELANIA-2.90%
WLFI-0.16%
MEME-0.94%
BTC-0.67%
Load More