Multiplying the first 1,000 USDT by 3.6% and the remainder by 3%, then dividing by the total balance, produces an estimate rather than a separately published rate: about 3.3% at 2,000 USDT and about 3.06% at 10,000 USDT. Idle Earn on the Spot Account and the Futures Account pays up to 3% APR, and both the balance location and the payout location differ, so that rate cannot be applied to Earn inside Gate Money. Sending funds to a bank is a fiat cash-out.
Key Takeaways
- Flexible USDT example: 3.6% APR on the first 1,000 USDT, 3% APR above that, deposits and withdrawals at any time, no lock-up.
- 3.6% is not the rate on the whole balance. Applying both tiers to a balance produces an estimate, not a separately published rate.
- The entry is Earn on the Money home screen. It is not Idle Earn on the Spot Account and the Futures Account; the balance location and the payout location both differ.
- Any minimum balance and any subscription cap follow the Earn product page. The APR can change with market conditions. Money is not a bank.
What Kind of Yield Does Earn Credit Inside Gate Money?
Earn is the yield entry on the Gate Money home screen. Flexible USDT allows deposits and withdrawals at any time: 3.6% APR on the first 1,000 USDT and 3% APR on the amount above 1,000 USDT. The annualized rate can change with market conditions, so the product page and terms govern (Gate Money FAQ, 2026-10-19). The product page describes the same capability as 3.6% APR with no lock-up.
The 3.6% applies only to the first tranche, and the amount above 1,000 USDT accrues at 3% APR. Any minimum balance and any subscription cap follow the Earn product page and cannot be inferred from 3.6%.
Money is not a bank. It provides fintech services such as account management, payments, cards, and asset management, and the provider and terms vary by region. 3.6% is not a bank deposit rate.
How Much of a Balance Does 3.6% Actually Cover?
The tier split cuts the balance into two parts, each with its own APR. 3.6% covers only the first 1,000 USDT, and the amount above 1,000 USDT accrues at 3%. The larger the balance, the closer an estimate built from the two tiers sits to 3%, not to 3.6%.
| Balance |
Accrual split |
Blended APR (approx.) |
| 500 USDT |
500 × 3.6% |
3.6% |
| 1,000 USDT |
1,000 × 3.6% |
3.6% |
| 2,000 USDT |
1,000 × 3.6% + 1,000 × 3% |
3.3% |
| 10,000 USDT |
1,000 × 3.6% + 9,000 × 3% |
3.06% |
The blended figures apply the two published APR tiers to a fixed balance and assume the rates stay unchanged through the accrual period. They are not a settlement quote and not a yield promise. Accrual frequency, payout frequency, and whether interest compounds follow the product terms. The product page states APR.
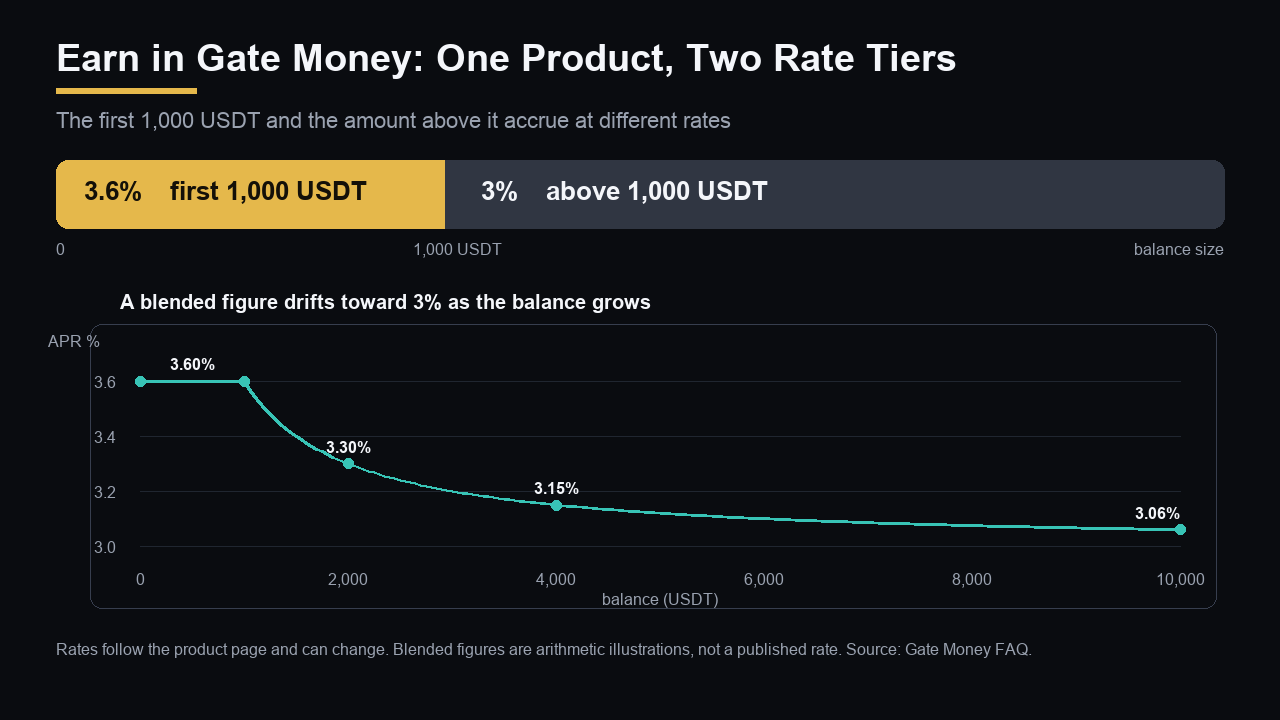
Figure 1. Flexible USDT is split into two tiers: 3.6% APR on the first 1,000 USDT and 3% APR above that. A blended estimate moves toward 3% as the balance grows.
Why Does the 3.6% on the Page Differ from the Account?
3.6% is the marginal rate on the first tier. What the account earns overall is the weighted average of both tiers. At or below 1,000 USDT the two numbers match; once the balance crosses 1,000 USDT, the 3% tier pulls the average down.
Two judgments follow. First, multiplying 3.6% by the entire balance overstates interest above 1,000 USDT. Second, the same product stays closer to the headline number on a small balance and closer to 3% on a large one. Before comparing, substitute the actual balance into the table, then check whether the product page still shows these two tiers that day.
The annualized rate can change with market conditions. An estimate built on 3.6% and 3% may later be running on a different pair of rates. Recalculate from the APR shown on the Earn product page that day.
How Does Gate Money Earn Differ from Idle Earn?
Both can generate yield on stablecoin balances, but the account that holds the balance, the accrual method, and the payout location differ. A rate shown on the Spot Account cannot be applied to Money.
| Item |
Gate Money Earn (flexible USDT example) |
Idle Earn |
| Where the balance sits |
Earn inside Gate Money |
Stablecoins in the Spot Account and Futures Account |
| Rate as stated |
3.6% APR on the first 1,000 USDT, 3% APR above |
Up to 3% APR, adjusted with the market |
| How to join |
Open Earn on the home screen and follow the product page |
After it is enabled, accrual uses a daily average balance snapshot, with no daily manual subscription |
| Payout |
Follows the Earn product terms |
Credited to the Spot Account on T+1 |
| Lock-up |
The flexible USDT example allows deposits and withdrawals at any time |
Funds stay in the original account and can still be traded |
Idle Earn snapshots the daily average balance of eligible USDT, USDC, and other stablecoins in the trading account, and corporate or institutional users are not eligible; see the Idle Earn guide. The flexible USDT tier inside Gate Money splits at 1,000 USDT. A figure near 3% first requires checking whether the balance is in Earn inside Money or in Idle Earn on the Spot or Futures Account.
What Boundaries Should You Check Before Using It?
Four boundaries can be checked: where the tier splits, whether deposits and withdrawals stay open, the APR on the product page that day, and whether the entry is visible in the user's region. Any minimum balance and any subscription cap follow the Earn product page.
- Tiers: Confirm whether the first tranche is still 1,000 USDT and whether the amount above it is still 3%.
- Withdrawal: Flexible USDT allows deposits and withdrawals at any time, with no lock-up. That is not the same as funds already arriving at a bank. A USD fiat cash-out to an own-name account is a transfer, not a withdrawal inside Earn.
- APR that day: Use the figure shown on the Earn product page when it is opened. Both 3.6% and 3% can change with market conditions.
- Entry: Earn sits in the quick actions on the Money home screen. If the entry is missing, the App prompt governs. Verification-level account limits are a separate cap from this Earn balance.
The named example inside Earn is flexible USDT. Lock-up, withdrawal rules, and the rate on any other product in the list follow that product's own page, and the flexible rule does not carry over.
What Risks Apply to This Yield?
Four risks decide whether 3.6% can be read literally: rate resets, the stablecoin price, platform exposure, and the protection boundary. Redeeming at any time addresses liquidity only, not the other three.
- Rate reset: Both 3.6% and 3% are variable annualized rates, not a locked rate.
- Stablecoin price: The market price of USDT can move away from 1 US dollar. When it does, the dollar value of principal and accrued yield moves together. Reserve disclosure from the issuer is on Tether Transparency.
- Platform exposure: A balance that is accruing sits in a platform yield product and follows the product terms. It is not a bank deposit.
- Product boundary: Money is not a bank. 3.6% is not a bank deposit rate.
Summary
Flexible USDT in Gate Money Earn accrues in two tiers: 3.6% APR on the first 1,000 USDT and 3% APR on the amount above 1,000 USDT, with deposits and withdrawals at any time and no lock-up. The 3.6% figure is not the rate on the whole balance. An estimate built from the two tiers is not a separately published rate. The balance does not sit in the same place as Idle Earn, and Money is not a bank. Check the tiers on the product page that day before using it.
FAQ
Does 3.6% apply to the entire USDT balance?
No. The first 1,000 USDT accrues at 3.6% APR, and the amount above 1,000 USDT accrues at 3% APR. The whole balance equals 3.6% only when it does not exceed 1,000 USDT.
Are Gate Money Earn and Idle Earn the same feature?
No. Gate Money Earn sits inside Money, and flexible USDT splits at 1,000 USDT. Idle Earn snapshots stablecoin balances in the Spot Account and the Futures Account at up to 3% APR, with yield credited to the Spot Account on T+1.
Can flexible USDT be withdrawn at any time?
Flexible USDT allows deposits and withdrawals at any time, with no lock-up. That is not the same as funds already arriving at a bank. Sending them to a bank or using them for payment still follows the corresponding transfer or payment steps.
Is there a minimum balance or a subscription cap?
The stated boundary is 1,000 USDT. Any minimum balance, any subscription cap, and whether accrual still uses 3.6% and 3% follow the Earn product page.
Is this a bank deposit?
No. Money is not a bank. It provides fintech services such as account management, payments, cards, and asset management. 3.6% is not a bank deposit rate.