
#日本央行加息至1.25%创31年新高 #Gate广场中秋团圆局 Japan Raises Interest Rates by 25 Basis Points to 1%, a 31-Year High—Why Did the Yen Fall Instead of Rise?
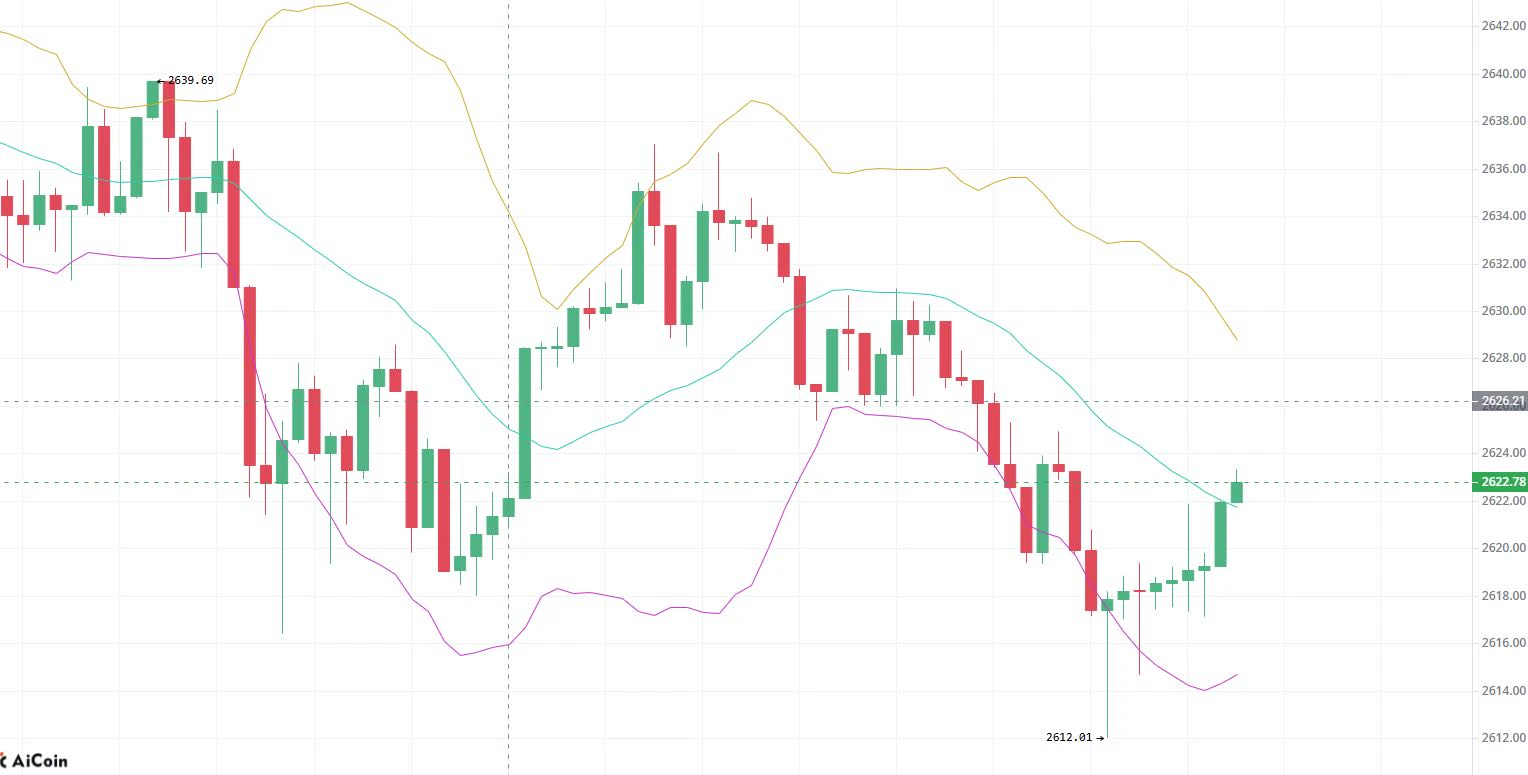
On September 18, the Bank of Japan raised its policy rate by 25 basis points to 1.25%, the highest level since April 1995. This was another rate hike after the Bank of Japan raised rates from 0.75% to 1% in June this year, and marked another important step in Japan’s move away from its long-standing ultra-loose monetary policy. But the market produced a seemingly “counterintuitive” result: Japan raised interest rates, yet the yen did not rise and instead continued to fall. As of the afternoon of September 18, the yen briefly fell to around 157.76 against the US dollar, down more than 1% intraday; its cumulative decline against the US dollar this week also reached approximately 2.6%.
So why did the yen fall despite the Bank of Japan raising interest rates? The answer is not complicated. What truly determines exchange rates has never been a single rate hike itself, but rather how interest rates will evolve in the future and whether the interest-rate gap between Japan and the United States will genuinely narrow.
I. The yen rate hike failed to drive the yen higher, with the yen falling more than 1% against the US dollar after the hike.
According to conventional logic, when a country’s central bank raises interest rates, domestic asset yields increase, potentially attracting capital inflows and supporting the local currency. But the yen’s problem is precisely this: Japan raised rates, but the market believes the pace of future rate hikes may not be as fast as expected.
On September 18, the Bank of Japan voted 7–2 to approve a 25-basis-point rate hike to 1.25%. This was the highest level in 31 years, but two members voted against it, calling for the rate to remain at 1%. The market subsequently interpreted the result as indicating that the Bank of Japan was not internally united in supporting faster tightening. At the same time, the Federal Reserve also raised its policy rate by 25 basis points this week to 3.75%–4%.
In other words, although Japan raised rates, the United States raised rates by the same amount, so the Japan-US interest-rate gap remained substantial.
More importantly, the market trades not on “whether rates will be raised today,” but on “how much further they can rise in the future.” If Japan’s rate rises from 1% to 1.25% while US rates remain far above Japan’s, the change in the interest-rate gap caused by a single hike is actually limited.
Therefore, the market did not buy large amounts of yen simply because Japan raised rates. Instead, after confirming that the Bank of Japan had not signaled a stronger series of rate hikes, it increased demand for the US dollar again. This is why the seemingly contradictory scene emerged: the Bank of Japan raised rates, yet the yen fell. In reality, this does not mean the rate hike failed; rather, the market repriced the “pace of future rate hikes.”
II. Whether the yen will see another rate hike this year, with market expectations failing to increase.
This may be the question the market cares about most after the Bank of Japan’s rate hike on September 18. The Bank of Japan did raise rates, but it did not clearly tell the market: When will the next hike come? The 7–2 vote at the September 18 meeting itself showed that divisions remain within the Bank of Japan over the pace of rate hikes. If all nine voting members had supported a hike, the market might have found it easier to conclude that Japanese monetary policy was entering a clearer tightening cycle. But two members publicly opposed the hike. Therefore, market bets on whether Japan will continue raising rates this year did not increase significantly because of this hike.
Bank of Japan Governor Kazuo Ueda also emphasized after the meeting that there is no pre-set fixed pace for future rate adjustments, and no mechanical arrangement to “raise rates once every three months.” The central bank will reassess the situation at each meeting based on changes in prices, wages, the economy, and financial markets.
Of course, Ueda did not close the door on further rate hikes. He said that if inflation risks rise significantly, the Bank of Japan would not rule out raising rates by 50 basis points at once, or even implementing consecutive hikes at subsequent meetings. This statement is highly important. It means that the Bank of Japan has gradually shifted the discussion from “whether to raise rates” to “how quickly to raise them.” For now, however, the Bank of Japan still wants to avoid tightening financial conditions too quickly. The reason is practical: Japan’s economy still needs time to adjust to higher interest rates, while corporate financing costs, real estate, financial assets, and household loans will all be affected. Therefore, whether the yen can truly strengthen in the future depends not only on how high Japanese interest rates reach, but also on whether the market believes the Bank of Japan will continue raising rates. If expectations of future hikes continue to intensify, the yen may regain support; if rate hikes enter a slow, gradual phase, the Japan-US interest-rate gap may continue to weigh on the yen for a long time.
III. Japan’s inflation in August 2026 was already close to the Bank of Japan’s target.
Why must the Bank of Japan continue considering rate hikes now?
One answer is inflation. Data released by Japan’s Ministry of Internal Affairs and Communications on September 18 showed that Japan’s nationwide CPI rose 1.9% year-on-year in August 2026; excluding fresh food and energy, CPI also rose 1.9% year-on-year. In other words, Japan’s inflation has moved increasingly close to the Bank of Japan’s 2% target. More importantly, the Bank of Japan is concerned not only with the current CPI figure, but also with whether rising costs can continue to be passed on to businesses and consumers. Rising energy prices, yen depreciation, and higher prices for semiconductors and other goods could all increase corporate costs. If companies can pass higher costs on to consumers, the initial shock from energy and import prices could gradually evolve into broader domestic inflation. This is the biggest difference between the Bank of Japan today and in the past.
Over the past several decades, Japan’s biggest concern was deflation. Companies were reluctant to raise prices, households were reluctant to spend, wage growth was weak, and the central bank could only stimulate the economy through extremely low or even negative interest rates. Now, however, the Bank of Japan is beginning to worry about another problem: could inflation shift from being “too low” to exceeding its target? The Bank of Japan’s July outlook report forecast that core CPI excluding fresh food would rise by an average of 2.5% in fiscal 2026, while real GDP would grow 0.6%. The report also noted that oil prices, yen depreciation, and higher semiconductor prices driven by AI demand could all push prices higher.
Therefore, the Bank of Japan’s policy logic is changing: previously, it sought ways to push inflation higher; now, it must prevent inflation from rising too quickly. This is also an important signal that Japan has entered the monetary-policy normalization phase.
IV. Japan’s negative-interest-rate era has come to a complete end.
Viewed over a longer period, the significance of the September 18 rate hike goes far beyond 25 basis points. It means that Japan’s decades-long ultra-loose monetary policy is truly approaching its end.
In March 2024, the Bank of Japan ended its negative-interest-rate policy and simultaneously exited its yield-curve-control policy. Since then, Japanese interest rates have gradually begun returning to normal levels.
In June 2026, the Bank of Japan raised its rate to 1%; in September, it raised it further to 1.25%. Moving from negative rates to 1.25% may look like merely a change in a few numbers, but it actually represents a major turning point in Japan’s financial environment.
In the past, Japan relied on extremely low interest rates to stimulate the economy for an extended period. The defining feature of this policy was cheap borrowing. Corporate financing costs were low, household borrowing costs were low, and Japan was also one of the world’s largest sources of low-cost financing. As a result, large amounts of capital flowed overseas, forming the famous “yen carry trade.”
Now, as Japanese interest rates continue to rise, this logic is changing. Japanese companies and households will face higher borrowing costs in the future, but savers and banks will also begin receiving higher interest income.
More importantly, the yields on Japanese assets themselves are rising. If Japan continues to raise rates and the yen gradually strengthens, the past model of “borrowing cheap yen and investing in high-yield overseas assets” will face increasing constraints. This does not mean the yen carry trade will suddenly disappear, but it does mean that the environment on which it depends is changing.
In the past, Japan’s biggest advantage was cheap yen. In the future, Japan may develop a different kind of advantage: higher domestic yields, a stronger yen, and domestic capital flowing back.
Therefore, what is truly worth watching about Japan’s rate hikes is not why the yen fell 1% today. It is that Japan is gradually changing from an economy that has long exported low-cost funds into one where domestic interest rates and asset yields are both beginning to rise. This may mean that the contraction of the yen carry trade is not necessarily the end of Japan’s investment story. On the contrary, it may be the starting point for renewed changes in Japan’s financial markets and capital-flow dynamics.$USDJPY
On September 18, the Bank of Japan raised its policy rate by 25 basis points to 1.25%, the highest level since April 1995. This was another rate hike after the Bank of Japan raised rates from 0.75% to 1% in June this year, and marked another important step in Japan’s move away from its long-standing ultra-loose monetary policy. But the market produced a seemingly “counterintuitive” result: Japan raised interest rates, yet the yen did not rise and instead continued to fall. As of the afternoon of September 18, the yen briefly fell to around 157.76 against the US dollar, down more than 1% intraday; its cumulative decline against the US dollar this week also reached approximately 2.6%.
So why did the yen fall despite the Bank of Japan raising interest rates? The answer is not complicated. What truly determines exchange rates has never been a single rate hike itself, but rather how interest rates will evolve in the future and whether the interest-rate gap between Japan and the United States will genuinely narrow.
I. The yen rate hike failed to drive the yen higher, with the yen falling more than 1% against the US dollar after the hike.
According to conventional logic, when a country’s central bank raises interest rates, domestic asset yields increase, potentially attracting capital inflows and supporting the local currency. But the yen’s problem is precisely this: Japan raised rates, but the market believes the pace of future rate hikes may not be as fast as expected.
On September 18, the Bank of Japan voted 7–2 to approve a 25-basis-point rate hike to 1.25%. This was the highest level in 31 years, but two members voted against it, calling for the rate to remain at 1%. The market subsequently interpreted the result as indicating that the Bank of Japan was not internally united in supporting faster tightening. At the same time, the Federal Reserve also raised its policy rate by 25 basis points this week to 3.75%–4%.
In other words, although Japan raised rates, the United States raised rates by the same amount, so the Japan-US interest-rate gap remained substantial.
More importantly, the market trades not on “whether rates will be raised today,” but on “how much further they can rise in the future.” If Japan’s rate rises from 1% to 1.25% while US rates remain far above Japan’s, the change in the interest-rate gap caused by a single hike is actually limited.
Therefore, the market did not buy large amounts of yen simply because Japan raised rates. Instead, after confirming that the Bank of Japan had not signaled a stronger series of rate hikes, it increased demand for the US dollar again. This is why the seemingly contradictory scene emerged: the Bank of Japan raised rates, yet the yen fell. In reality, this does not mean the rate hike failed; rather, the market repriced the “pace of future rate hikes.”
II. Whether the yen will see another rate hike this year, with market expectations failing to increase.
This may be the question the market cares about most after the Bank of Japan’s rate hike on September 18. The Bank of Japan did raise rates, but it did not clearly tell the market: When will the next hike come? The 7–2 vote at the September 18 meeting itself showed that divisions remain within the Bank of Japan over the pace of rate hikes. If all nine voting members had supported a hike, the market might have found it easier to conclude that Japanese monetary policy was entering a clearer tightening cycle. But two members publicly opposed the hike. Therefore, market bets on whether Japan will continue raising rates this year did not increase significantly because of this hike.
Bank of Japan Governor Kazuo Ueda also emphasized after the meeting that there is no pre-set fixed pace for future rate adjustments, and no mechanical arrangement to “raise rates once every three months.” The central bank will reassess the situation at each meeting based on changes in prices, wages, the economy, and financial markets.
Of course, Ueda did not close the door on further rate hikes. He said that if inflation risks rise significantly, the Bank of Japan would not rule out raising rates by 50 basis points at once, or even implementing consecutive hikes at subsequent meetings. This statement is highly important. It means that the Bank of Japan has gradually shifted the discussion from “whether to raise rates” to “how quickly to raise them.” For now, however, the Bank of Japan still wants to avoid tightening financial conditions too quickly. The reason is practical: Japan’s economy still needs time to adjust to higher interest rates, while corporate financing costs, real estate, financial assets, and household loans will all be affected. Therefore, whether the yen can truly strengthen in the future depends not only on how high Japanese interest rates reach, but also on whether the market believes the Bank of Japan will continue raising rates. If expectations of future hikes continue to intensify, the yen may regain support; if rate hikes enter a slow, gradual phase, the Japan-US interest-rate gap may continue to weigh on the yen for a long time.
III. Japan’s inflation in August 2026 was already close to the Bank of Japan’s target.
Why must the Bank of Japan continue considering rate hikes now?
One answer is inflation. Data released by Japan’s Ministry of Internal Affairs and Communications on September 18 showed that Japan’s nationwide CPI rose 1.9% year-on-year in August 2026; excluding fresh food and energy, CPI also rose 1.9% year-on-year. In other words, Japan’s inflation has moved increasingly close to the Bank of Japan’s 2% target. More importantly, the Bank of Japan is concerned not only with the current CPI figure, but also with whether rising costs can continue to be passed on to businesses and consumers. Rising energy prices, yen depreciation, and higher prices for semiconductors and other goods could all increase corporate costs. If companies can pass higher costs on to consumers, the initial shock from energy and import prices could gradually evolve into broader domestic inflation. This is the biggest difference between the Bank of Japan today and in the past.
Over the past several decades, Japan’s biggest concern was deflation. Companies were reluctant to raise prices, households were reluctant to spend, wage growth was weak, and the central bank could only stimulate the economy through extremely low or even negative interest rates. Now, however, the Bank of Japan is beginning to worry about another problem: could inflation shift from being “too low” to exceeding its target? The Bank of Japan’s July outlook report forecast that core CPI excluding fresh food would rise by an average of 2.5% in fiscal 2026, while real GDP would grow 0.6%. The report also noted that oil prices, yen depreciation, and higher semiconductor prices driven by AI demand could all push prices higher.
Therefore, the Bank of Japan’s policy logic is changing: previously, it sought ways to push inflation higher; now, it must prevent inflation from rising too quickly. This is also an important signal that Japan has entered the monetary-policy normalization phase.
IV. Japan’s negative-interest-rate era has come to a complete end.
Viewed over a longer period, the significance of the September 18 rate hike goes far beyond 25 basis points. It means that Japan’s decades-long ultra-loose monetary policy is truly approaching its end.
In March 2024, the Bank of Japan ended its negative-interest-rate policy and simultaneously exited its yield-curve-control policy. Since then, Japanese interest rates have gradually begun returning to normal levels.
In June 2026, the Bank of Japan raised its rate to 1%; in September, it raised it further to 1.25%. Moving from negative rates to 1.25% may look like merely a change in a few numbers, but it actually represents a major turning point in Japan’s financial environment.
In the past, Japan relied on extremely low interest rates to stimulate the economy for an extended period. The defining feature of this policy was cheap borrowing. Corporate financing costs were low, household borrowing costs were low, and Japan was also one of the world’s largest sources of low-cost financing. As a result, large amounts of capital flowed overseas, forming the famous “yen carry trade.”
Now, as Japanese interest rates continue to rise, this logic is changing. Japanese companies and households will face higher borrowing costs in the future, but savers and banks will also begin receiving higher interest income.
More importantly, the yields on Japanese assets themselves are rising. If Japan continues to raise rates and the yen gradually strengthens, the past model of “borrowing cheap yen and investing in high-yield overseas assets” will face increasing constraints. This does not mean the yen carry trade will suddenly disappear, but it does mean that the environment on which it depends is changing.
In the past, Japan’s biggest advantage was cheap yen. In the future, Japan may develop a different kind of advantage: higher domestic yields, a stronger yen, and domestic capital flowing back.
Therefore, what is truly worth watching about Japan’s rate hikes is not why the yen fell 1% today. It is that Japan is gradually changing from an economy that has long exported low-cost funds into one where domestic interest rates and asset yields are both beginning to rise. This may mean that the contraction of the yen carry trade is not necessarily the end of Japan’s investment story. On the contrary, it may be the starting point for renewed changes in Japan’s financial markets and capital-flow dynamics.$USDJPY