






#美股AI和加密概念上涨 With expectations for AI demand recovering and tech giants’ earnings reports coming one after another, risk appetite is back in the market. This rally is backed by volume, but how far can it fly? Put simply, it still depends on whether earnings can withstand expectations—the mood can light the fire, but earnings are what keep it alive.
I’m still mainly watching Nvidia (NVDA), for a very direct reason:
1. Its results haven’t disappointed. Next quarter’s revenue guidance is $108 billion (±2%), with a 74% gross margin. Data centers remain its biggest pillar—data center revenue last quarter was $51.2 billion, up 66% year over year, and AI demand is still surging.
2. Don’t panic about “capex peaking” just yet. Goldman Sachs has set a $300 price target, saying physical AI revenue has already surpassed the full-year figure; Jensen Huang said at GTC Berlin, “Build an AI factory in 14 days,” and Google Cloud plans to deploy 960k Rubin GPUs all at once—the demand story is still being written, not finished.
3. Remember two pitfalls before getting in. Earnings guidance excludes data center revenue from mainland China, so don’t be misled by the headline figures; the valuation isn’t cheap, with a $5.35 trillion market cap and a TTM P/E of 27.7x. The next earnings report will be a major test.
In short, AI chips are still the hottest thing on the street, but whether they can stay that way depends on how earnings meet expectations.
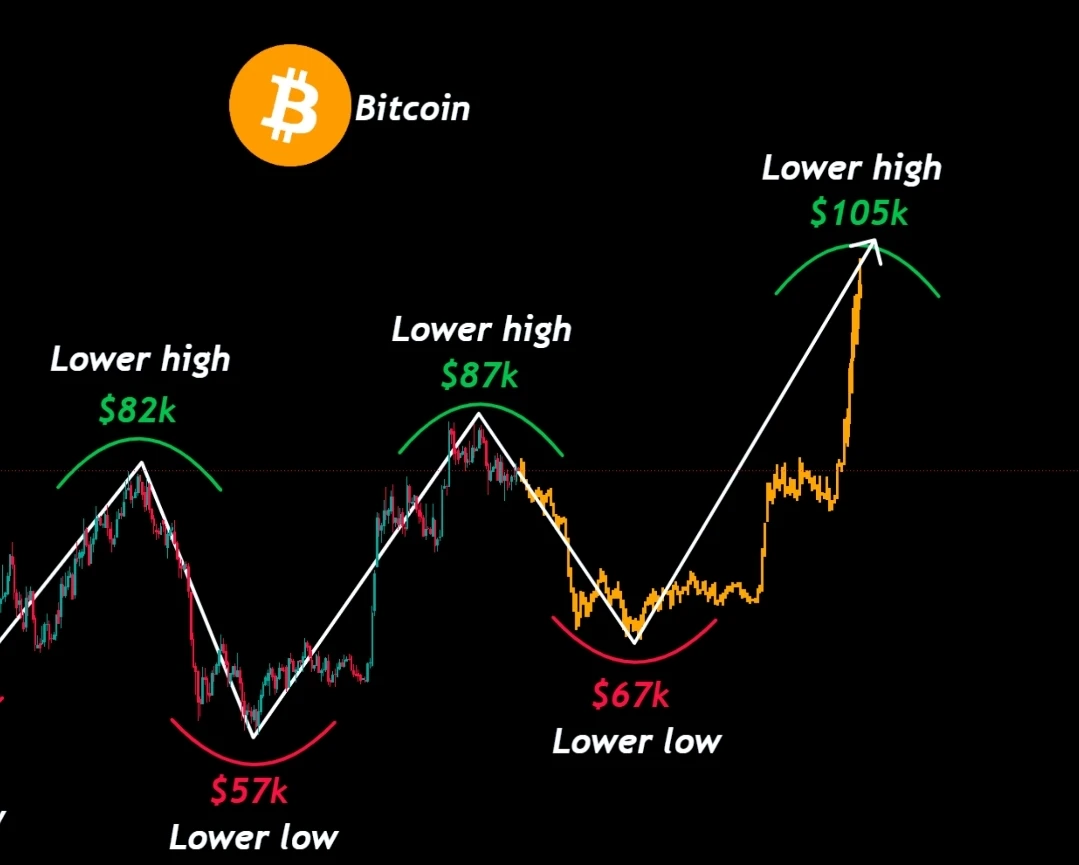
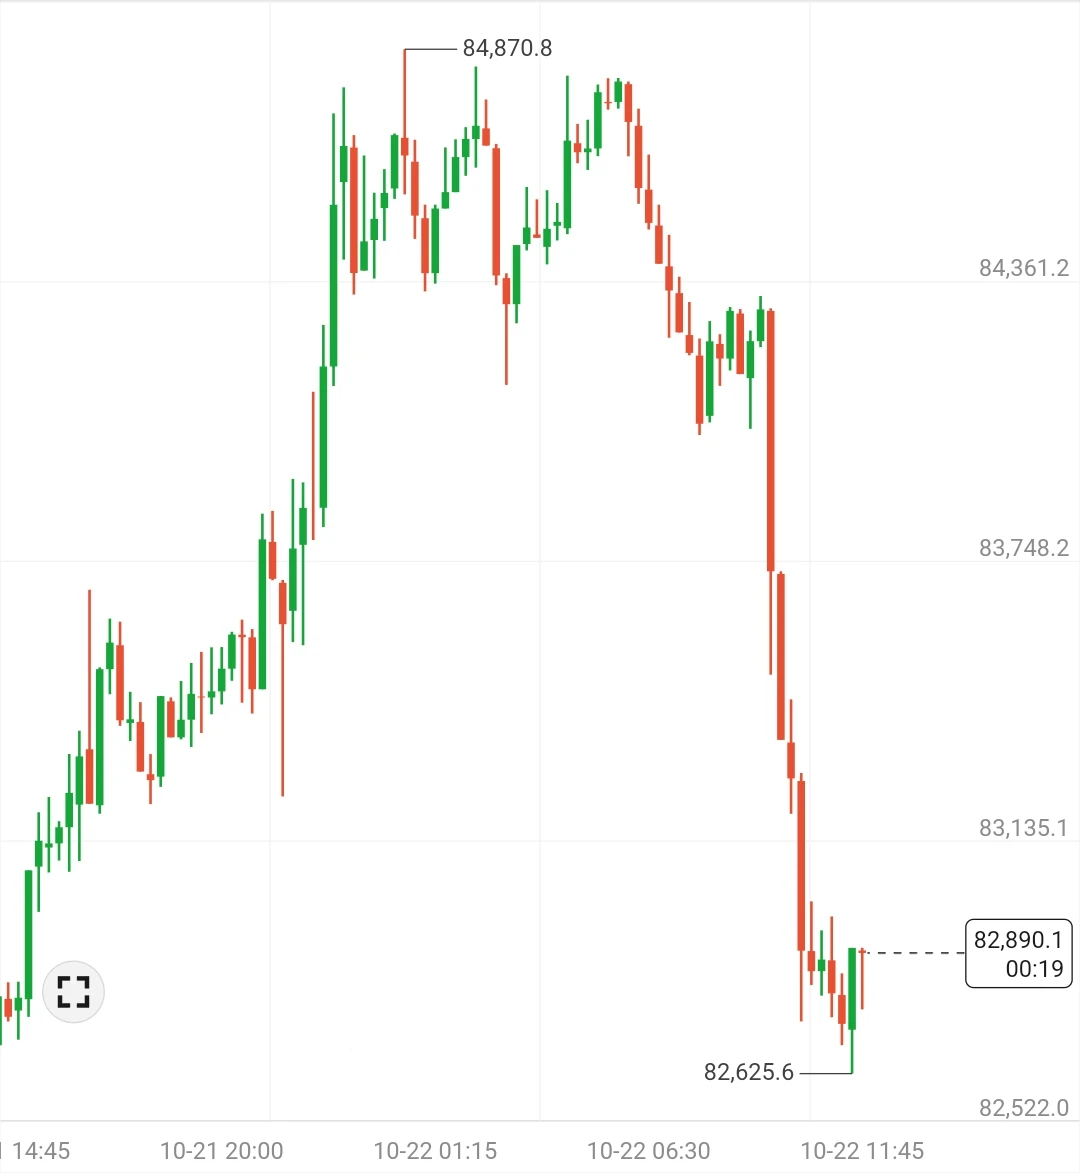
Meanwhile, BTC has broken $83k, and MSTR, COIN, and MARA have all taken off, with their high-beta moves in full swing—but that’s a different playbook: token prices, regulation, and capital flows are a different story from AI chips.
Which side are you on this time? Will AI chips keep leading, or will crypto-related stocks take over? Pick one in the comments and tell us which assets you’re watching. #GateWCTCS9全球交易赛 $NVDA