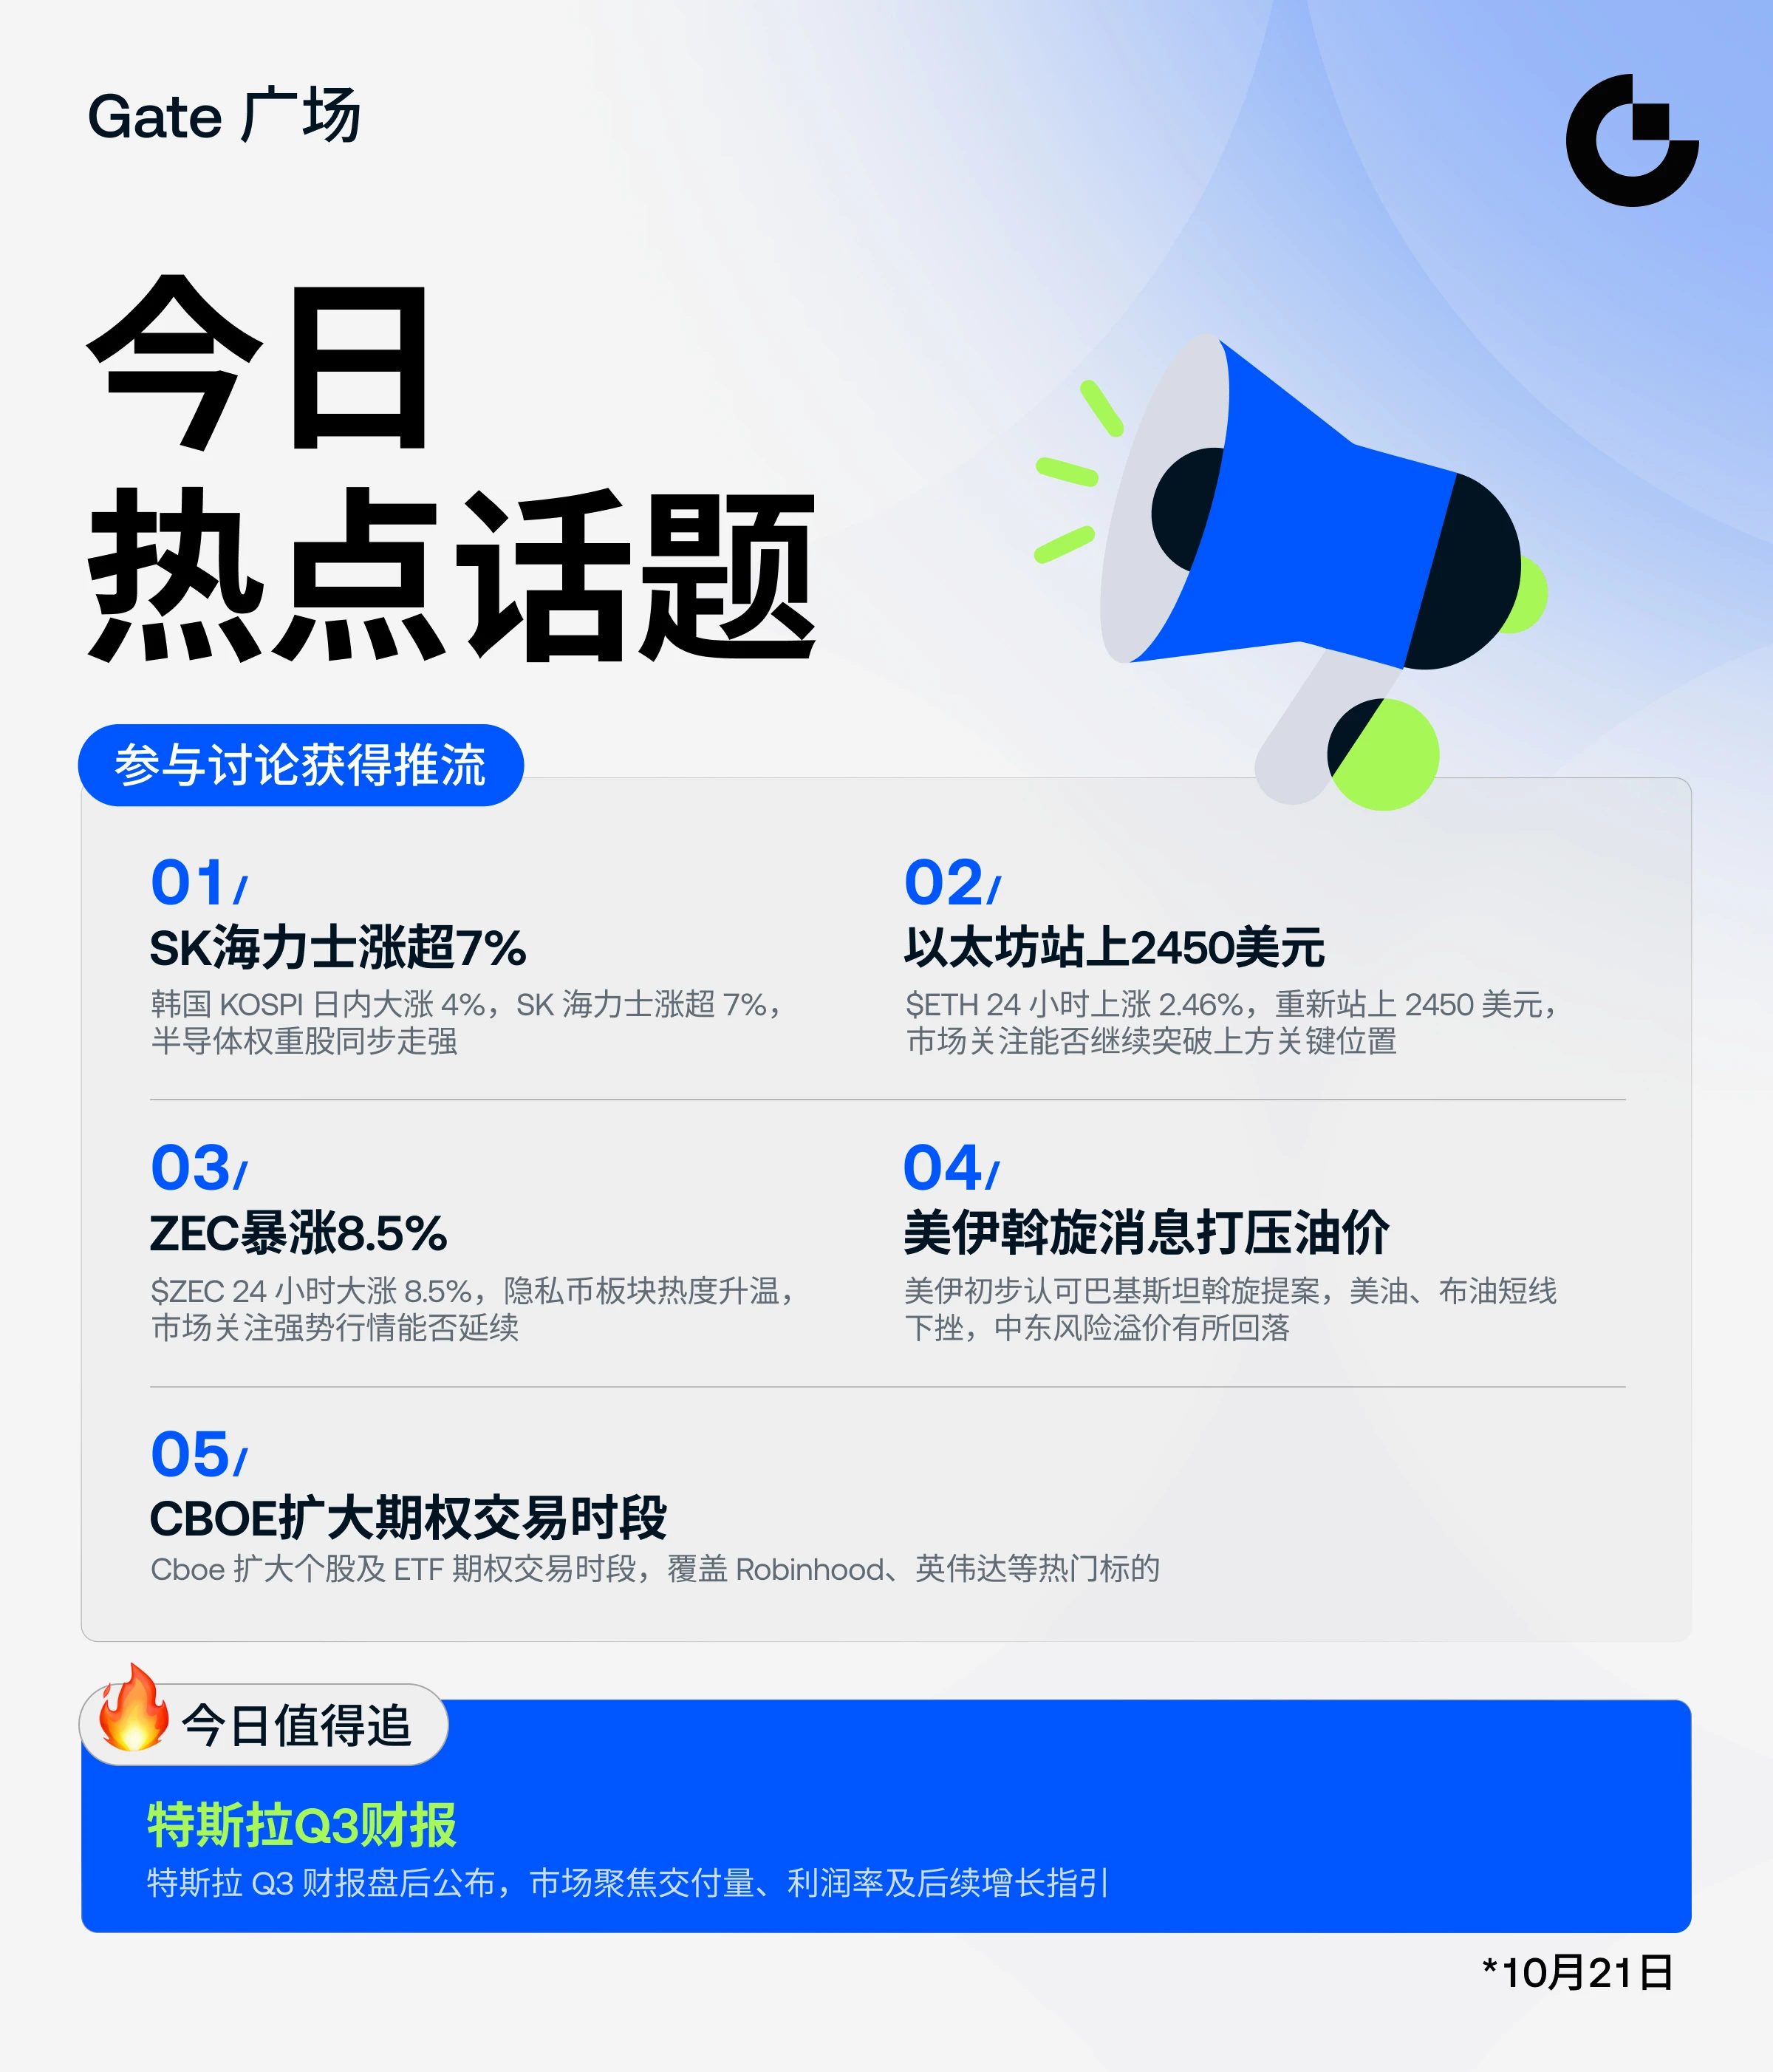







#美伊斡旋消息打压油价 A Single Headline Triggered a Deep V-Shaped Rebound: Three Scenarios for Crude Oil
During the overnight session on October 20, international crude oil saw a sharp, classic “headline-driven” swing. Brent crude briefly surged to a five-month high of $111.95/barrel, while WTI crude rose to $101.37/barrel. Then a geopolitical headline hit, sending prices plunging: Brent touched a low of $105.95/barrel, and WTI fell to $95.35/barrel, with the intraday decline briefly widening to around 3%. But the sell-off did not continue; prices quickly rebounded from their lows. At settlement on October 21, WTI closed at $101.79/barrel and Brent at $108.79/barrel. SC fell 4.47% in the overnight session.
The session left behind not a one-way trend, but a huge star candle—and a more pressing question: what exactly was the crude oil market trading that night?
The immediate trigger for the decline was a rumor about US-Iran talks.
Media reports said Qatar and Pakistan had submitted a compromise proposal to the US and Iran, which had received “preliminary approval.”
The market’s first reaction was direct: if the talks made a breakthrough, shipping restrictions in the Strait of Hormuz could gradually be lifted, marginally improving the global crude supply outlook. The key factor that had been driving oil prices higher was the risk premium stemming from geopolitical conflict in the Middle East; once a “sign of easing” emerged in the source of that premium, long positions were closed en masse during the thinly traded overnight session, rapidly amplifying the decline. Meanwhile, the resumption of Russian diesel exports was an overlooked marginal headwind. As the US suspended some sanctions and moved to lift export restrictions, at least two tankers carrying around 300,000 barrels of diesel had set sail for Turkey and Brazil, respectively. The marginal recovery in refined-product supply weakened the upward support that the diesel market had previously provided to crude valuations. This signal and the US-Iran news resonated, together providing the fundamental backdrop for the decline.
However, the rebound was almost as rapid as the drop.
The first force behind the rebound was the swift reversal of the news itself. Diplomats involved in US-Iran contacts promptly denied that an “agreement was imminent,” stressing that talks were ongoing but that claims an agreement was close to being finalized were inaccurate. Expectations shifted in the space of a few hours from “peace is within reach” to “it is too early to say.”
The deeper force behind the rebound was renewed recognition that tail risks had not disappeared because of diplomatic rumors.
On the same day, another maritime security incident was reported near the Strait of Hormuz. Iran’s Revolutionary Guard claimed that two oil tankers passing without authorization had struck mines and caught fire; the Houthi threat to attack Saudi oil facilities also remained.
Iran’s conditions for reopening the strait include lifting the naval blockade, unfreezing assets, removing sanctions on oil exports, and withdrawing US forces from the border, among seven key demands. This means that even if a negotiating track exists, there is still a considerable distance to go before any meaningful easing.
After the decline, the market recognized anew that the “source” of the risk premium could contract temporarily on a single headline, but its “foundation”—the tail risk of an actual supply disruption—had not fallen by a corresponding amount.
In addition, API inventory data provided fundamental support: for the week ended October 16, US API crude inventories fell by 4.931 million barrels, while gasoline and distillate inventories also declined, by more than expected. The Strategic Petroleum Reserve, already at an extremely low level, fell to 282.7 million barrels, its lowest since 1982, further magnifying the marginal impact of any supply disruption on prices.
Looking ahead, the core tension in the crude oil market can be summed up as a tug-of-war between downward pressure from the directional unwinding of the geopolitical risk premium and the fundamental support of tail risks to supply disruption.
In the base-case scenario, oil prices are more likely to remain high and trade in a wide range than to continue rising in one direction or fall in a sustained trend. If verifiable progress in talks emerges, the roughly $10 to $15/barrel geopolitical premium currently priced in will face concentrated unwinding, and the average Brent price for the fourth quarter could fall to the $103 to $108/barrel range. But the complexity of Iran’s seven conditions means the premium is more likely to unwind in “steps” than in a “waterfall.”
If talks remain deadlocked and tail risks materialize intermittently, a wide-ranging oscillation between $105 and $112/barrel for Brent is the most probable path. Actual supply vulnerabilities and extremely low inventories would provide a floor, while downward revisions to demand expectations would cap prices; around $120/barrel could be a potential ceiling for a short-term, sentiment-driven spike.
If shipping through the Strait of Hormuz is substantially disrupted, or key Saudi facilities suffer quantifiable production capacity damage, oil prices will see a sharp upward spike. But if this scenario is triggered, it will also activate demand destruction, strategic reserve releases, and stronger incentives for diplomatic intervention, potentially making the spike shorter-lived than a linear extrapolation would suggest.
For crude-related assets, the defining features of the current environment are not a clear trend, but persistently high volatility and the unpredictability of event-driven pricing. The October 20 “sell-off and rebound” is a concentrated example of this dynamic: an unverified headline can trigger a 3% decline within hours, and its refutation can reverse the move just as quickly.
In this environment, the risk-reward profile of one-way directional bets is asymmetric. A more sensible allocation approach should prioritize risk hedging over return enhancement. The rationale for higher valuations in upstream oil and gas assets remains intact, but investors should leave a safety buffer for the potential stepwise unwinding of the geopolitical premium. Downstream chemicals, meanwhile, face pressure from both high cost-side volatility and downward revisions to demand, and are less able than crude itself to keep pace with rising prices.
The signals to monitor most closely, in order of priority, are verifiable changes in actual traffic through the Strait of Hormuz; verifiable progress on specific terms in US-Iran talks; actual OPEC+ production and export data; and marginal trends in US inventories and refinery margins.