#比特币跌破7万美元 BTC Falls Below $70,000 | Traditional Finance Is Slowly Dismantling Web3
The crypto market plunged this past weekend. Weekend sell-offs are nothing new, but the explanations have usually been the same old refrain: oversold, support, next level to watch. Those factors were present this weekend too. But beyond them, I observed traditional finance gradually dismantling Web3’s old narrative, taking what it can use—including pricing power.
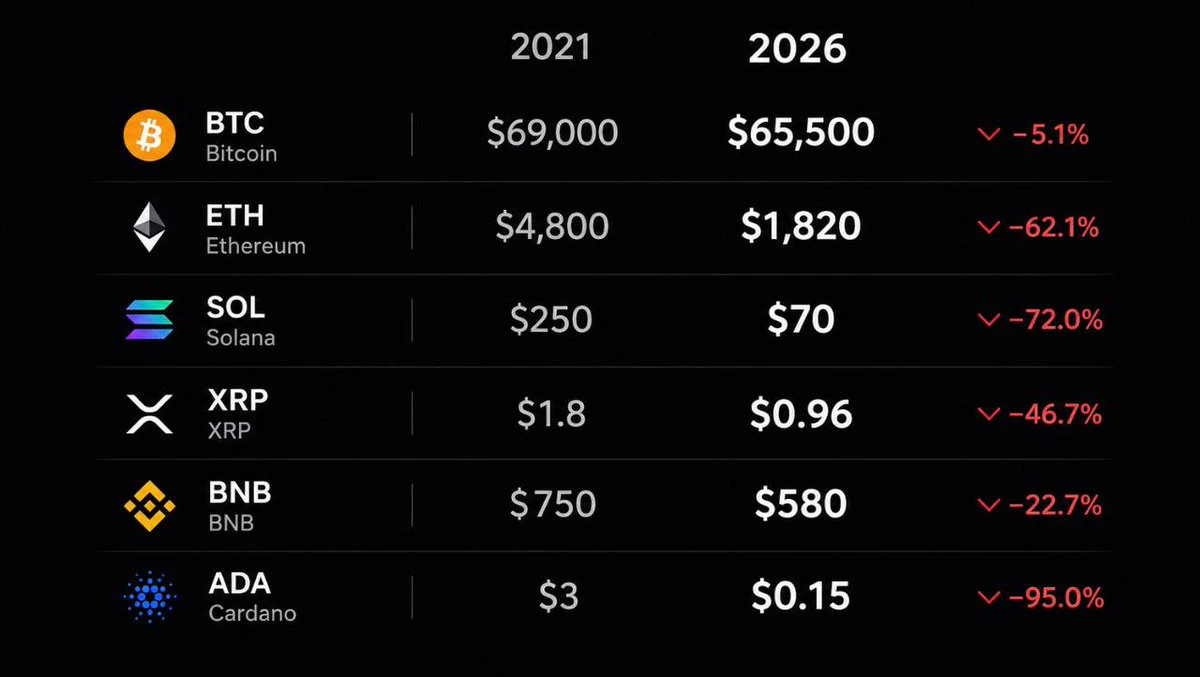
Let’s first lay out what happened in the market. During the Asian session on November 15, An'an's BTCUSDT hit a low of $62,006, a price not seen since July 14. The previous day wasn’t pretty either: it fell to $63,320 intraday on the 14th and closed at $64,150. From the October 21 close of $84,093, that’s a drop of roughly 26%.
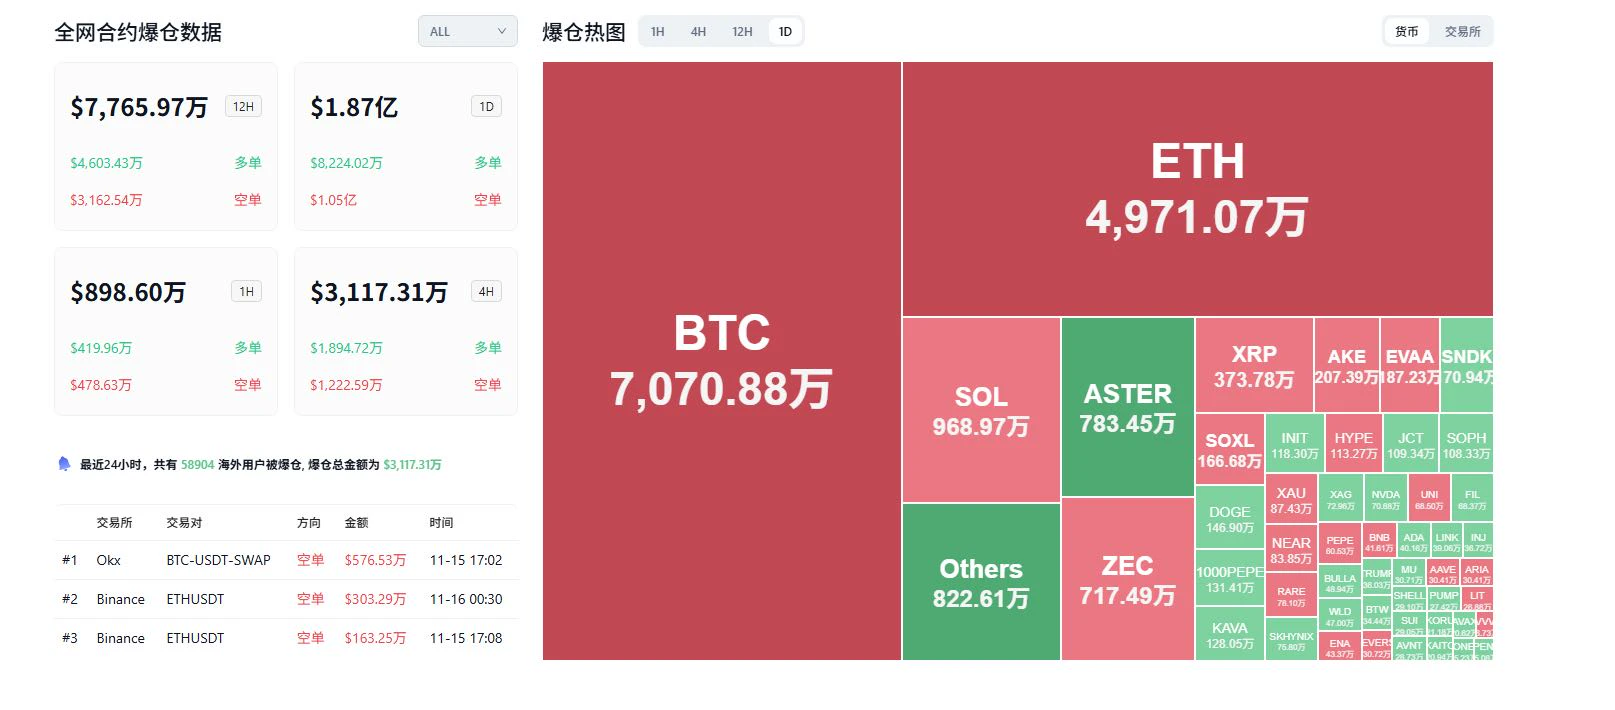
Ethereum also briefly dipped to $1,711 on November 15, likewise a new low since July. By this morning, Bitcoin had recovered to around $65,000—but compared with the steep sell-off over the weekend, this rebound was clearly negligible. Liquidation figures were even more unforgiving than the candlesticks. In the 24 hours leading up to Sunday daytime, around $2 billion in positions across the market were forcibly liquidated, according to Coinglass, with Bitcoin accounting for $750 million to $770 million, all of them longs. Looking further back, there had already been a round of roughly $1.3 billion in liquidations on the 13th. For U.S. spot Bitcoin ETFs, Farside Investors’ figures show net outflows for seven consecutive trading days from November 5 to 13, totaling around $1.91 billion. During this period, as the decline continued, Bitcoin had already fallen below its 200-day moving average of around $73,000, after which concentrated liquidations followed. New shorts also piled in after the break.
In the past, a decline like this would have been explained as a technical breakdown, with calls to watch the next support level. What was different this time was that the four words shouted loudest over the past two years—“institutions are coming”—didn’t play out this weekend. The market was falling, but institutions didn’t show up to support it.
Which funds were flushed out this weekend
First, let’s clarify what exactly was flushed out.
It wasn’t that some blockchain broke in the middle of the night. Blocks kept being produced, wallets kept making transfers, and every announcement that was supposed to go out did. What collapsed was something else: the leveraged positions of traders treating Bitcoin as a high-volatility risk asset.
Spot ETFs were once the most convincing evidence that “institutions had arrived.” The logic was simple: they put Bitcoin into brokerage accounts, letting traditional investors trade it in the familiar way. But when the same money heads for the exit for seven consecutive trading days, it is no longer a hand reaching out to provide support. It looks more like a gate that opens and closes to the rhythm of traditional markets. The anchor for prices has shifted too: they are increasingly driven by interest rate expectations, the dollar, and risk appetite, rather than by the stories the crypto industry tells itself.
The narrative that “institutions will provide support” didn’t even survive a single real-market test this weekend.
Traditional finance didn’t stop working, but what it took was the components.
That said, traditional finance didn’t stop working this weekend; announcements came one after another. On November 12, the Depository Trust & Clearing Corporation (DTCC) announced plans to connect its already-launched tokenization services to Solana. To be clear: the service launched on October 28, while the Solana integration is planned for the second half of 2027 and covers only eligible assets held in DTC custody—so don’t frame this as “U.S. stocks are already on Solana.” On the same day, Anchorage Digital announced a partnership with Visa: some stablecoins issued by its federally chartered bank can serve as settlement assets on the Visa network, with Western Union’s USDPT first up. In Singapore, three tranches of tokenized MAS bills have already been issued, starting at 1 million and 10 million Singapore dollars and reaching 100 million Singapore dollars in the issuance on November 6. But consultation on stablecoin legislation only closed on October 16, and there is still no clear timeline for the formal bill or its effective date. The MAS itself still calls these bills trials; they are issued only to institutions, settled using wholesale central bank digital currency, and excluded from official statistics.
These are real things, not PowerPoint slides. But they move slowly, are mostly wholesale products aimed at institutions, and many are still at the trial stage. They can’t catch the weekend’s price action. Look one layer deeper: traditional finance isn’t taking all of Web3. It wants clearing efficiency, payment rails, and the parts of tokenized assets that can fit into existing legal and custody frameworks. It doesn’t want unlicensed yield stories, nor the idea that “on-chain will replace clearinghouses and exchanges.” So the components are taken apart one by one. The outer shell can still be called blockchain, but the power to define it no longer belongs to the protocols and communities that once held it.
RWA is what most clearly exposes the cracks in the narrative
Over the past two years, ETF, RWA, and tokenized Treasuries have often been mentioned together, with the unspoken message: this time is different; institutions will provide support, and on-chain yields will be backed by Treasuries. On November 14, the stUSDT team posted a wind-down notice on Medium. The product once marketed itself as offering “tokenized Treasury yields” and reached a peak of around $2.3 billion on DefiLlama in November 2023. By Sunday, only about $8.6 million remained on its books. The official position is that the underlying assets remain fully redeemable, but no explanation was given for why it was closing.
Automatic interest accrual stopped on November 14. The redemption portal will remain open until 23:59 (UTC) on May 14, 2027, with processing to continue monthly through August 2027.
Even so, this episode is enough to expose a corner of the RWA narrative. A product hailed as an RWA star can quietly stop accruing interest and open redemptions after its scale has evaporated by 99%, without necessarily going out with a bang.
The term RWA has never automatically meant asset quality. By contrast, what is still growing is the MAS’s trial bills, tokenized assets in the custody of clearinghouses, and stablecoin settlement by licensed banks and card networks. The more they grow, the more they resemble traditional financial products of their own, just wrapped in a layer of blockchain.
ETFs follow the same logic: first invite Bitcoin into brokerage accounts, then price it according to the rules governing traditional capital flows.
What’s really being taken away is pricing power
What is being dismantled on the surface is the product; what is being quietly shifted is something else: who gets to decide, who sets the prices, and who gets to define it.
In the past, crypto largely priced itself: watching halving cycles, leverage and sentiment on exchanges, and whatever new story the on-chain world could come up with at the time.
Now things have changed. Bitcoin is increasingly priced according to interest rates, the dollar, ETF flows, and risk appetite. Tokenization, meanwhile, is governed by licensing, custody, and clearinghouse rules. Who gets to decide “whether this counts as being on-chain” or “whether this counts as RWA”? The answer increasingly points to clearinghouses, card networks, regulators, and licensed issuers—not the people behind protocols and communities.
Once the power to shape the narrative moves elsewhere, there’s no need to pretend the two paths are the same.
The two paths will diverge further
One will continue as a high-volatility risk asset; the other will turn to become the pipes and packaging of traditional finance. A crash on the first path doesn’t mean the second has stopped working; more announcements on the second won’t save the market on the first. At this crossroads for Web3, I can’t predict whether Bitcoin’s price has bottomed, but I think the more important question has become: once the parts that can be taken are removed, what will the rest of Web3 rely on for pricing? As for AI drawing risk capital over to its side—that will only make the pricing narrative that “crypto is just another high-beta asset” even harder to sustain, but it’s background, not today’s main story.
Traditional finance is dismantling Web3, taking the components it can use; along with them, it is taking pricing power and the power to shape the narrative. The two paths will diverge further. #WCTCS9 $BTC
The crypto market plunged this past weekend. Weekend sell-offs are nothing new, but the explanations have usually been the same old refrain: oversold, support, next level to watch. Those factors were present this weekend too. But beyond them, I observed traditional finance gradually dismantling Web3’s old narrative, taking what it can use—including pricing power.
Let’s first lay out what happened in the market. During the Asian session on November 15, An'an's BTCUSDT hit a low of $62,006, a price not seen since July 14. The previous day wasn’t pretty either: it fell to $63,320 intraday on the 14th and closed at $64,150. From the October 21 close of $84,093, that’s a drop of roughly 26%.
Ethereum also briefly dipped to $1,711 on November 15, likewise a new low since July. By this morning, Bitcoin had recovered to around $65,000—but compared with the steep sell-off over the weekend, this rebound was clearly negligible. Liquidation figures were even more unforgiving than the candlesticks. In the 24 hours leading up to Sunday daytime, around $2 billion in positions across the market were forcibly liquidated, according to Coinglass, with Bitcoin accounting for $750 million to $770 million, all of them longs. Looking further back, there had already been a round of roughly $1.3 billion in liquidations on the 13th. For U.S. spot Bitcoin ETFs, Farside Investors’ figures show net outflows for seven consecutive trading days from November 5 to 13, totaling around $1.91 billion. During this period, as the decline continued, Bitcoin had already fallen below its 200-day moving average of around $73,000, after which concentrated liquidations followed. New shorts also piled in after the break.
In the past, a decline like this would have been explained as a technical breakdown, with calls to watch the next support level. What was different this time was that the four words shouted loudest over the past two years—“institutions are coming”—didn’t play out this weekend. The market was falling, but institutions didn’t show up to support it.
Which funds were flushed out this weekend
First, let’s clarify what exactly was flushed out.
It wasn’t that some blockchain broke in the middle of the night. Blocks kept being produced, wallets kept making transfers, and every announcement that was supposed to go out did. What collapsed was something else: the leveraged positions of traders treating Bitcoin as a high-volatility risk asset.
Spot ETFs were once the most convincing evidence that “institutions had arrived.” The logic was simple: they put Bitcoin into brokerage accounts, letting traditional investors trade it in the familiar way. But when the same money heads for the exit for seven consecutive trading days, it is no longer a hand reaching out to provide support. It looks more like a gate that opens and closes to the rhythm of traditional markets. The anchor for prices has shifted too: they are increasingly driven by interest rate expectations, the dollar, and risk appetite, rather than by the stories the crypto industry tells itself.
The narrative that “institutions will provide support” didn’t even survive a single real-market test this weekend.
Traditional finance didn’t stop working, but what it took was the components.
That said, traditional finance didn’t stop working this weekend; announcements came one after another. On November 12, the Depository Trust & Clearing Corporation (DTCC) announced plans to connect its already-launched tokenization services to Solana. To be clear: the service launched on October 28, while the Solana integration is planned for the second half of 2027 and covers only eligible assets held in DTC custody—so don’t frame this as “U.S. stocks are already on Solana.” On the same day, Anchorage Digital announced a partnership with Visa: some stablecoins issued by its federally chartered bank can serve as settlement assets on the Visa network, with Western Union’s USDPT first up. In Singapore, three tranches of tokenized MAS bills have already been issued, starting at 1 million and 10 million Singapore dollars and reaching 100 million Singapore dollars in the issuance on November 6. But consultation on stablecoin legislation only closed on October 16, and there is still no clear timeline for the formal bill or its effective date. The MAS itself still calls these bills trials; they are issued only to institutions, settled using wholesale central bank digital currency, and excluded from official statistics.
These are real things, not PowerPoint slides. But they move slowly, are mostly wholesale products aimed at institutions, and many are still at the trial stage. They can’t catch the weekend’s price action. Look one layer deeper: traditional finance isn’t taking all of Web3. It wants clearing efficiency, payment rails, and the parts of tokenized assets that can fit into existing legal and custody frameworks. It doesn’t want unlicensed yield stories, nor the idea that “on-chain will replace clearinghouses and exchanges.” So the components are taken apart one by one. The outer shell can still be called blockchain, but the power to define it no longer belongs to the protocols and communities that once held it.
RWA is what most clearly exposes the cracks in the narrative
Over the past two years, ETF, RWA, and tokenized Treasuries have often been mentioned together, with the unspoken message: this time is different; institutions will provide support, and on-chain yields will be backed by Treasuries. On November 14, the stUSDT team posted a wind-down notice on Medium. The product once marketed itself as offering “tokenized Treasury yields” and reached a peak of around $2.3 billion on DefiLlama in November 2023. By Sunday, only about $8.6 million remained on its books. The official position is that the underlying assets remain fully redeemable, but no explanation was given for why it was closing.
Automatic interest accrual stopped on November 14. The redemption portal will remain open until 23:59 (UTC) on May 14, 2027, with processing to continue monthly through August 2027.
Even so, this episode is enough to expose a corner of the RWA narrative. A product hailed as an RWA star can quietly stop accruing interest and open redemptions after its scale has evaporated by 99%, without necessarily going out with a bang.
The term RWA has never automatically meant asset quality. By contrast, what is still growing is the MAS’s trial bills, tokenized assets in the custody of clearinghouses, and stablecoin settlement by licensed banks and card networks. The more they grow, the more they resemble traditional financial products of their own, just wrapped in a layer of blockchain.
ETFs follow the same logic: first invite Bitcoin into brokerage accounts, then price it according to the rules governing traditional capital flows.
What’s really being taken away is pricing power
What is being dismantled on the surface is the product; what is being quietly shifted is something else: who gets to decide, who sets the prices, and who gets to define it.
In the past, crypto largely priced itself: watching halving cycles, leverage and sentiment on exchanges, and whatever new story the on-chain world could come up with at the time.
Now things have changed. Bitcoin is increasingly priced according to interest rates, the dollar, ETF flows, and risk appetite. Tokenization, meanwhile, is governed by licensing, custody, and clearinghouse rules. Who gets to decide “whether this counts as being on-chain” or “whether this counts as RWA”? The answer increasingly points to clearinghouses, card networks, regulators, and licensed issuers—not the people behind protocols and communities.
Once the power to shape the narrative moves elsewhere, there’s no need to pretend the two paths are the same.
The two paths will diverge further
One will continue as a high-volatility risk asset; the other will turn to become the pipes and packaging of traditional finance. A crash on the first path doesn’t mean the second has stopped working; more announcements on the second won’t save the market on the first. At this crossroads for Web3, I can’t predict whether Bitcoin’s price has bottomed, but I think the more important question has become: once the parts that can be taken are removed, what will the rest of Web3 rely on for pricing? As for AI drawing risk capital over to its side—that will only make the pricing narrative that “crypto is just another high-beta asset” even harder to sustain, but it’s background, not today’s main story.
Traditional finance is dismantling Web3, taking the components it can use; along with them, it is taking pricing power and the power to shape the narrative. The two paths will diverge further. #WCTCS9 $BTC