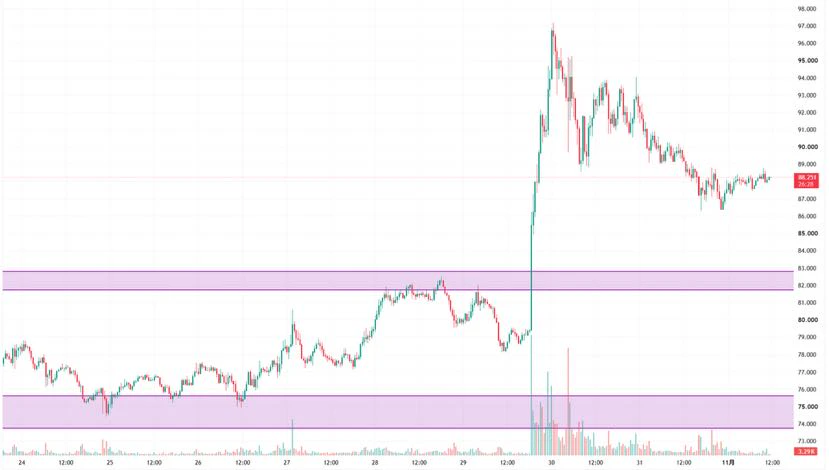
#HYPE逆市大涨 #Gate广场万圣节 The next BN? No, HYPE wants all of Wall Street
In 2006, AWS ushered in the era of cloud computing. Twenty years later, Hyperliquid is trying to bring the same infrastructure revolution to Wall Street.
Over the next decade, HYPE’s greatest potential is no longer becoming the next bn, but becoming the AWS capable of holding all of Wall Street.
1. Hyperliquid’s market position in 2026
According to blockchain data monitoring platform Defiliama, overall on-chain perpetual contract trading volume shrank 2.5% in the third quarter of 2026, while Hyperliquid bucked the trend with 9.2% growth. With a 38.6% share of trading volume, it captured 58% of the entire network’s open interest, demonstrating its outstanding ability to attract and retain capital.
Two points here merit closer examination.
One is open interest, because it represents the accumulation of long-term capital, making it a very difficult metric to fake. By contrast, trading volume can be manipulated in the short term. Volume can pile up rapidly over a short period, but maintaining a massive amount of open positions requires genuine margin, ample liquidity, and traders’ long-term trust in the platform.
The other is its ability to grow against the trend. Growth in favorable conditions is nothing unusual; what truly tests a platform’s strength is whether it can continue growing amid a sluggish market, shrinking liquidity, and intensifying competition. This is remarkable. If trading volume reflects a platform’s popularity, open interest reflects its heft, while growth against the trend reflects Hyperliquid’s true vitality.
Liquidation data in August had already begun to reveal the signs. Public research estimates that in May 2026, Hyperliquid’s total perpetual trading volume was equivalent to about 14.4% of Bn’s and about 6.6% of all centralized platforms’ volume. On the surface, this suggests huge room for growth. But how could a 14.4% share have such a high liquidation volume? It suggests Hype has many whale-type customers—high-quality whales or institutional traders. This is where Hype is truly impressive, and worth savoring. Institutions and whales arrive first, then retail investors pour in—that’s another story.
2. Growth in a bull market is nothing special; resilience in a bear market is what shows true strength
From November 2025 to September 2026, trading volume across the entire on-chain perpetual contract market nearly halved. Aster fell 74%, while Lighter plunged 81%. But what about Hyperliquid? It fell by only 2.4%, almost maintaining its previous level. What does that mean? As the entire industry receded and competitors’ trading volumes shrank sharply, Hyperliquid almost entirely defended its core business. One can imagine just how strong its product competitiveness, liquidity depth, and user stickiness must be to maintain such astonishing resilience in these market conditions.
3. Of every $100 in perpetual contract fees, about $89 ultimately flows into the Assistance Fund
In the third quarter of 2026, Hyperliquid generated about $165 million in perpetual contract fees, of which about $147 million flowed into the Assistance Fund to buy back HYPE. This means that for every $100 in fees users pay, about $89 goes to the HYPE buyback mechanism.
What does that mean? Hyperliquid is not only a trading platform capable of generating sustained revenue; more importantly, it is converting the platform’s business revenue into sustained demand for the HYPE token. Trading volume generates fees, fees support buybacks, and buybacks in turn link the platform’s economic value to the token. What is truly worth imagining is: if Hyperliquid eventually supports not just cryptocurrency trading, but a broader range of global financial assets, how large could this mechanism become?
4. Infrastructure is coming into its own
In July 2026, tradexyz, built on Hyperliquid, at one point accounted for half of Hyperliquid’s total perpetual contract trading volume. What does this mean? Hyperliquid is proving that it can not only match Bitcoin and Ethereum trades, but also provide underlying trading infrastructure for a broader range of financial assets, such as stocks and indices. Although tradexyz’s share of trading volume fell back to 23.9% by September, a trend has emerged: Hyperliquid’s future may not depend on how many markets it can list itself, but on how many developers are willing to build financial products on its infrastructure. An’an’s core is an exchange, while AWS’s core is an ecosystem. Hyperliquid is trying to move toward the latter.
In the third quarter of 2026, Hyperliquid’s HIP-4 event contracts recorded a cumulative trading volume of $231.4 million, slightly below the $282 million recorded shortly after launch in May and June. However, compared with the two giants of prediction markets, HIP-4 is still at an early stage. Currently, the sector is led primarily by regulated centralized platform Kalshi and Web3 leader Polymarket. In September alone, Kalshi’s trading volume reached $60.3 billion, while Polymarket reached $13.1 billion.
By comparison, HIP-4 recorded only $81.8 million during the same period, about 0.14% of Kalshi’s volume. But HIP-4’s ambitions go beyond prediction markets. When it proposed HIP-4 in February 2026, Hyperliquid positioned it as an underlying primitive enabling on-chain options and prediction markets. This means prediction markets are only the first step for HIP-4. As options-based derivatives gradually launch in the future, Hyperliquid may further expand its range of products, evolving from a cryptocurrency perpetual contract platform into underlying infrastructure covering more financial derivatives.
On September 16, Payward, the parent company of Krak, announced plans to open a HIP-3 trading market for U.S. customers through Hyperliquid, bringing a massive influx of new trading volume and builder revenue to the ecosystem. Bitnomial, a CFTC-licensed exchange acquired by Payward in May, will lead the initiative. If AWS redefined how computing resources are allocated, Hyperliquid wants to redefine how global financial assets are traded and how they flow. Hyperliquid is trying to replicate a similar story. It is not content to be an on-chain exchange, but is trying to build the underlying operating system for the next generation of global finance. When trading, assets, and liquidity all move on-chain, HYPE may be Wall Street’s AWS for the next decade.
5. Valuation scenario analysis
From a valuation perspective, HYPE is not cheap at its current price. Based on a fully diluted valuation (FDV) of about $91 billion as of September 30, 2026, applying Aster’s 124x revenue multiple implies an FDV of about $99.4 billion for Hyperliquid at its average fee rate in the third quarter; applying Lighter’s 134.3x multiple yields $108 billion. But using edgeX’s 65.2x multiple, even at the higher fee rate in September, the implied FDV is only $56 billion. This means whether HYPE’s current valuation is justified depends not only on Hyperliquid’s future revenue growth, but also on how high a valuation multiple the market is willing to assign it.
In other words, the market is already paying a premium for Hyperliquid’s growth potential, and future performance must be strong enough to support these expectations. If HYPE is assessed solely through the valuation framework for exchanges, that framework cannot capture its true ambition.
Trading is only the starting point; financial infrastructure is the endgame. From perpetual contracts to on-chain asset issuance, Hyperliquid is building an open financial ecosystem. Over the next decade, it is not competing for the market share of a particular exchange, but for the foundational gateway to all of Wall Street.
History does not simply repeat itself, but it always rhymes.
Whether Hyperliquid can become Wall Street’s AWS is too early to say. Whether its technological advantages can translate into lasting competitive barriers, whether its open ecosystem can attract enough developers and financial institutions, and whether traditional financial assets can truly migrate on-chain at scale are all questions that will take time to answer. What’s more, the capital markets have already assigned a hefty price to this potential. But one point is worth considering: in 2006, when Amazon launched AWS, few realized that an e-commerce company was quietly building the infrastructure of the future internet.
Twenty years later, when we look at Hyperliquid, perhaps we should not focus only on how many trades it matches today or how much in fees it earns. Because the value of truly great infrastructure often lies not in how much business it conducts itself, but in how much future business cannot function without it.$HYPE