
#黄仁勋辞职 #每周来晒 Is Jensen Huang’s departure the beginning of the AI bubble bursting?
On November 12, 2026, Nvidia announced that Jensen Huang had resigned as president, CEO, and director, effective immediately. Longtime CFO Colette Kress was appointed interim CEO, while the board simultaneously began searching for a permanent successor.
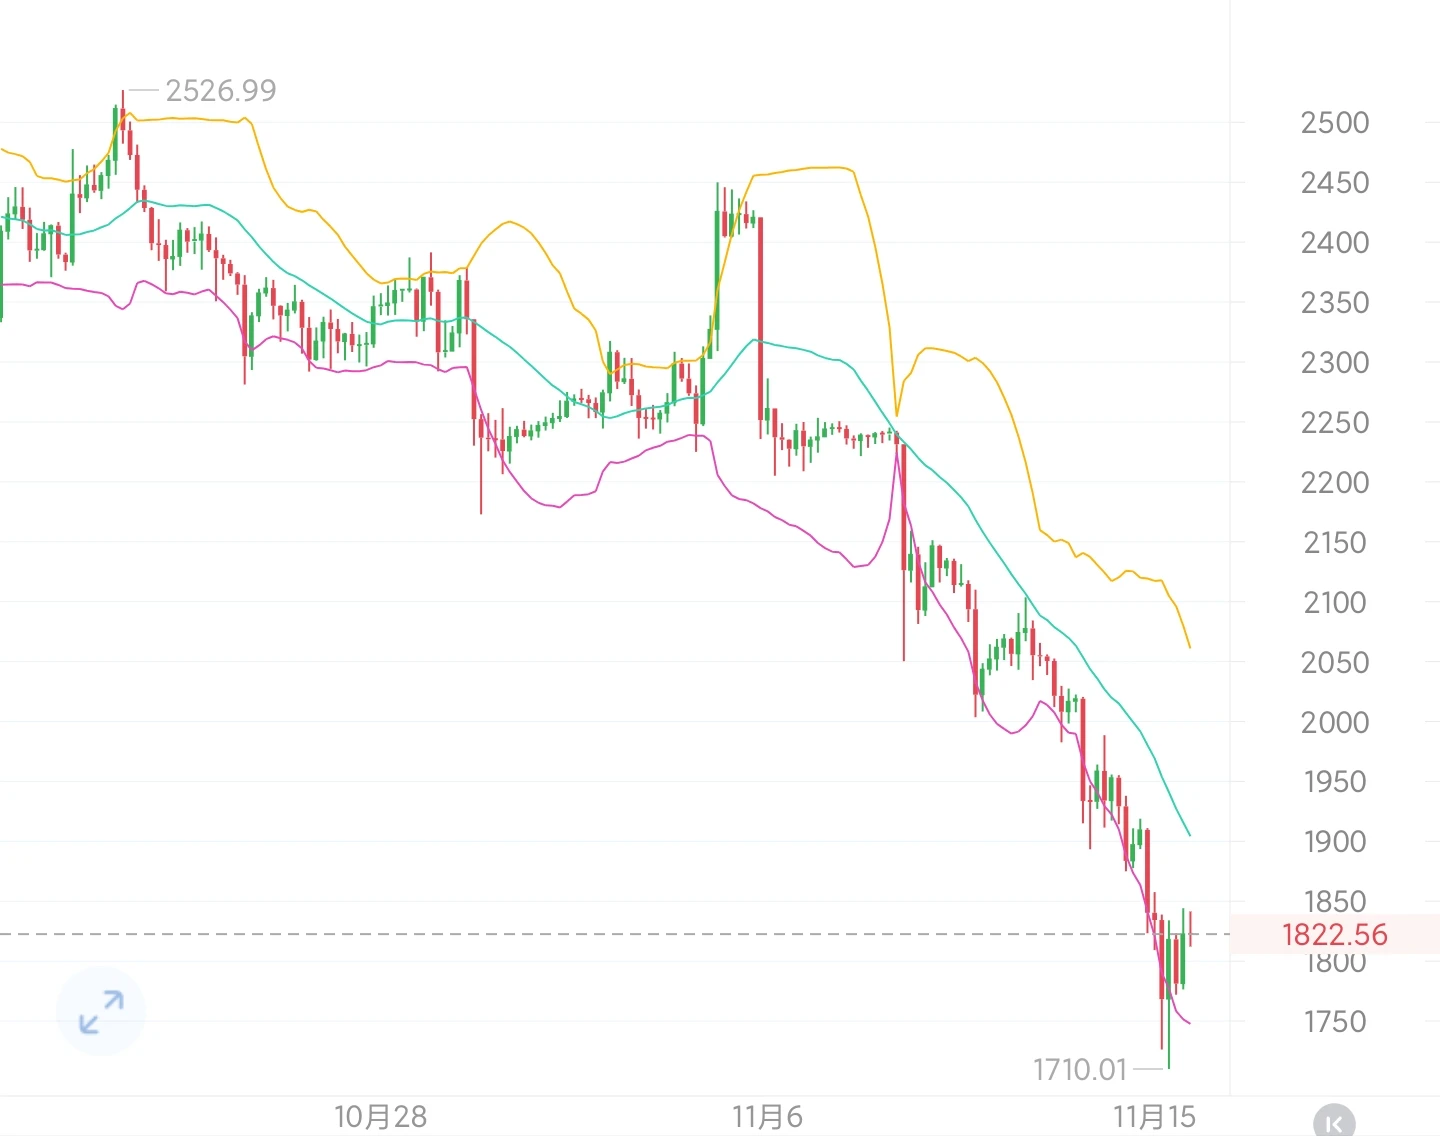
After the news broke, Nvidia shares plunged nearly 14% at one point during intraday trading, before paring their losses to about 4.3% by the close. The market instantly interpreted the move as a landmark turning point in the AI boom: “The king of AI is stepping down; the bubble is about to burst.”
But looking at the timeline more closely, this seems more like a fuse than the explosion itself.
The immediate trigger for Huang’s departure was issues concerning his personal ethics and an independent investigation by the board, not a sudden collapse in industry demand. The sharp stock decline reflects the market repricing the “founder halo”; it does not mean the fundamentals of the entire AI industry chain have failed.
What truly determines whether the AI bubble will burst has never been any one person’s departure or staying on. It comes down to four key factors: capital expenditure, returns from real-world applications, the competitive landscape, and policy constraints.
For Nvidia, Huang is far more than just a CEO. During his 33 years at the helm, he led three make-or-break transformations: from gaming graphics cards to the general-purpose computing CUDA ecosystem, and then to today’s role as a core supplier of global AI computing infrastructure. He did more than set the product roadmap: he also connected TSMC, cloud providers, model companies, and regulators around the world, using his immense personal influence to take the narrative that “AI needs more computing power” global. The CUDA ecosystem, hardware-software integration, supply chain cadence, and negotiations with major customers all bear the imprint of his decisions.
Investors have been willing to give Nvidia a high valuation partly because they are buying its chips, and partly because they believe in Huang’s ability to keep betting on the right direction. So when he suddenly leaves, the market’s first reaction is: the linchpin that “kept delivering miracles” is gone, and the risk premium must rise.
But there is a key distinction here: the founder halo can disappear, but the barriers already built will not vanish overnight. The CUDA developer ecosystem, servers already delivered, mature foundry chain, and cloud provider orders already secured are network effects built up over many years.
In the short term, the business will continue at its existing pace. Hard metrics like earnings, shipments, and gross margins are what will determine the valuation. The divergence in the market that day also confirms this: Nvidia plunged, while competitors such as AMD and Broadcom actually gained. Investors were selling the “Jensen Huang premium,” not rejecting demand for AI computing power across the board.
In other words, this is a company-level confidence shock, not a systemic collapse across the entire industry.
The so-called AI bubble was already being debated repeatedly long before Huang’s departure.
The current contradiction is clear: global AI capital expenditure has already reached the trillion-dollar level, but commercial returns downstream are lagging far behind the pace of investment. Several institutions estimate that AI infrastructure investment will be enormous in the coming years, while the directly monetizable market for generative AI remains relatively limited. After deploying AI, many companies have not seen an increase in net profits; many pilots remain at the demonstration stage and have not generated stable cash flow.
High market valuations are fundamentally a bet on the future: spending money today to build computing capacity, then realizing returns through AI agents, industry applications, and automation. If this payoff takes longer, or the return on investment continues to deteriorate, the bubble will come under pressure to contract. During Huang’s tenure, his speeches, product upgrades, and orders from major customers continually backed this long-term narrative. Without that backing, the market will shift from “believing the story” to “demanding evidence,” and valuations will be judged more rigorously.
In the post-Huang era, Nvidia will shift from a founder-driven “offensive mode” to an institutionally governed “verification mode.” Kress, the interim leader, comes from a finance background and is familiar with the company’s cash flow, cost controls, and capital allocation. This suggests that future strategy may lean toward prudence: controlling the pace of capital expenditure, improving earnings quality, and balancing growth with risk, rather than continuing to make aggressive bets on high-risk paths.
This is a normal transition for a mature corporation, but for the AI sector it means two things.
First, Nvidia will no longer be the “engine” pushing computing capacity expansion at any cost, and the expansion pace of the entire industry chain may slow;
Second, competitors, domestic computing power providers, and software companies will have a greater window of opportunity. In the past, the market assumed Nvidia’s roadmap was the industry’s roadmap. Now that the roadmap is more uncertain, capital will be reallocated, spreading from the single leading player to alternatives, and shifting from pure hardware speculation toward companies with real-world use cases.
Across A-shares and the global tech supply chain, this change will bring clear structural divergence.
If Huang is leaving for personal reasons alone, with no material deterioration in the company’s operations or orders, then the short-term impact will be mainly emotional: volatility will increase for computing power, optical modules, high-speed interconnects, and other assets that have already risen sharply, but companies with genuine orders and cash flow will not be abandoned all at once. If the successor later changes strategy, cuts expansion, or US export controls tighten further, expectations for demand across the entire computing power chain will be revised downward, and theme stocks whose earlier gains were driven by valuation will be the first to see their bubbles deflate.
Conversely, AI will not simply disappear: embodied intelligence, robotics, industrial automation, and corporate cost-cutting applications will continue to advance. Capital will simply shift from “betting on distant possibilities” to “looking at current returns.”
A bubble bursting does not mean AI is dead. It means valuations return to earth, pushing out speculation unsupported by performance and leaving the parts that truly create value.
There is another easily overlooked risk: geopolitics.
Nvidia’s business is at the center of great-power technological rivalry, and export controls, chip tiers, and supply chain relocation continue to constrain its room to expand. Huang’s personal communication skills once helped buffer the company as it balanced regulators in different countries and maintained customer relationships; a successor will find it difficult to replicate his network and influence. If tighter policies coincide with management turmoil, Nvidia’s deliveries, pricing, and market share will all face greater uncertainty, which will in turn affect the entire global computing power supply chain. This is the risk that deserves more attention than a personnel change.
Of course, the bubble could also “land softly.”
If Nvidia completes the transition smoothly, with no major interruptions to product upgrades, ecosystem support, or deliveries to major customers, while downstream AI applications begin generating real revenue and capital expenditure shifts from blind expansion to growth with returns, then this adjustment will simply mark AI’s transition from a period of frenzy to one of maturity.
Many technological revolutions have gone through similar phases: the internet and mobile internet both saw bubbles burst, but the technologies ultimately transformed industries. AI’s core proposition is to reduce the cost of production, research and development, and services. That underlying demand has not disappeared; it is simply taking longer to deliver than the market expected.
From an investor’s perspective, three layers of signals should be monitored to determine whether this is an emotional pullback or the start of a bubble.
The first layer is Nvidia itself: have its earnings guidance, data center revenue, gross margins, or customer orders materially declined?
The second layer is the industry chain: are cloud providers cutting capital expenditure? Are computing capacity utilization and downstream customers’ willingness to pay for applications improving?
The third layer is governance and competition: what is the new management’s strategic direction, how are US chip controls evolving, and how much traction are alternatives gaining?
Only if all three layers of signals deteriorate simultaneously can we say that the AI bubble has entered an accelerated bursting phase. A founder’s departure alone is not enough to trigger a systemic collapse.
Ultimately, Huang’s departure marks the end of an era, not the end of the technology. His personal charisma and strategic vision accelerated AI’s boom and amplified the market’s optimistic expectations for the sector. With this “anchor” gone, the market will return to the simplest business principles: revenue, profit, and cash flow. A bubble is when prices run ahead of delivery; when the market is no longer willing to pay a hefty premium for long-term stories, the bubble begins to contract. This will not happen in a single day of steep declines, but through a prolonged period of divergence: pure-play theme stocks with no ability to deliver will continue to be flushed out, while infrastructure and application companies that genuinely create efficiencies will find their footing amid volatility.
The AI wave will not come to an abrupt halt just because one person has left, but the market’s party has lost its most influential drummer. The market ahead will no longer be a game of believing in dreams, but a contest of the ability to deliver. $NVDA
On November 12, 2026, Nvidia announced that Jensen Huang had resigned as president, CEO, and director, effective immediately. Longtime CFO Colette Kress was appointed interim CEO, while the board simultaneously began searching for a permanent successor.
After the news broke, Nvidia shares plunged nearly 14% at one point during intraday trading, before paring their losses to about 4.3% by the close. The market instantly interpreted the move as a landmark turning point in the AI boom: “The king of AI is stepping down; the bubble is about to burst.”
But looking at the timeline more closely, this seems more like a fuse than the explosion itself.
The immediate trigger for Huang’s departure was issues concerning his personal ethics and an independent investigation by the board, not a sudden collapse in industry demand. The sharp stock decline reflects the market repricing the “founder halo”; it does not mean the fundamentals of the entire AI industry chain have failed.
What truly determines whether the AI bubble will burst has never been any one person’s departure or staying on. It comes down to four key factors: capital expenditure, returns from real-world applications, the competitive landscape, and policy constraints.
For Nvidia, Huang is far more than just a CEO. During his 33 years at the helm, he led three make-or-break transformations: from gaming graphics cards to the general-purpose computing CUDA ecosystem, and then to today’s role as a core supplier of global AI computing infrastructure. He did more than set the product roadmap: he also connected TSMC, cloud providers, model companies, and regulators around the world, using his immense personal influence to take the narrative that “AI needs more computing power” global. The CUDA ecosystem, hardware-software integration, supply chain cadence, and negotiations with major customers all bear the imprint of his decisions.
Investors have been willing to give Nvidia a high valuation partly because they are buying its chips, and partly because they believe in Huang’s ability to keep betting on the right direction. So when he suddenly leaves, the market’s first reaction is: the linchpin that “kept delivering miracles” is gone, and the risk premium must rise.
But there is a key distinction here: the founder halo can disappear, but the barriers already built will not vanish overnight. The CUDA developer ecosystem, servers already delivered, mature foundry chain, and cloud provider orders already secured are network effects built up over many years.
In the short term, the business will continue at its existing pace. Hard metrics like earnings, shipments, and gross margins are what will determine the valuation. The divergence in the market that day also confirms this: Nvidia plunged, while competitors such as AMD and Broadcom actually gained. Investors were selling the “Jensen Huang premium,” not rejecting demand for AI computing power across the board.
In other words, this is a company-level confidence shock, not a systemic collapse across the entire industry.
The so-called AI bubble was already being debated repeatedly long before Huang’s departure.
The current contradiction is clear: global AI capital expenditure has already reached the trillion-dollar level, but commercial returns downstream are lagging far behind the pace of investment. Several institutions estimate that AI infrastructure investment will be enormous in the coming years, while the directly monetizable market for generative AI remains relatively limited. After deploying AI, many companies have not seen an increase in net profits; many pilots remain at the demonstration stage and have not generated stable cash flow.
High market valuations are fundamentally a bet on the future: spending money today to build computing capacity, then realizing returns through AI agents, industry applications, and automation. If this payoff takes longer, or the return on investment continues to deteriorate, the bubble will come under pressure to contract. During Huang’s tenure, his speeches, product upgrades, and orders from major customers continually backed this long-term narrative. Without that backing, the market will shift from “believing the story” to “demanding evidence,” and valuations will be judged more rigorously.
In the post-Huang era, Nvidia will shift from a founder-driven “offensive mode” to an institutionally governed “verification mode.” Kress, the interim leader, comes from a finance background and is familiar with the company’s cash flow, cost controls, and capital allocation. This suggests that future strategy may lean toward prudence: controlling the pace of capital expenditure, improving earnings quality, and balancing growth with risk, rather than continuing to make aggressive bets on high-risk paths.
This is a normal transition for a mature corporation, but for the AI sector it means two things.
First, Nvidia will no longer be the “engine” pushing computing capacity expansion at any cost, and the expansion pace of the entire industry chain may slow;
Second, competitors, domestic computing power providers, and software companies will have a greater window of opportunity. In the past, the market assumed Nvidia’s roadmap was the industry’s roadmap. Now that the roadmap is more uncertain, capital will be reallocated, spreading from the single leading player to alternatives, and shifting from pure hardware speculation toward companies with real-world use cases.
Across A-shares and the global tech supply chain, this change will bring clear structural divergence.
If Huang is leaving for personal reasons alone, with no material deterioration in the company’s operations or orders, then the short-term impact will be mainly emotional: volatility will increase for computing power, optical modules, high-speed interconnects, and other assets that have already risen sharply, but companies with genuine orders and cash flow will not be abandoned all at once. If the successor later changes strategy, cuts expansion, or US export controls tighten further, expectations for demand across the entire computing power chain will be revised downward, and theme stocks whose earlier gains were driven by valuation will be the first to see their bubbles deflate.
Conversely, AI will not simply disappear: embodied intelligence, robotics, industrial automation, and corporate cost-cutting applications will continue to advance. Capital will simply shift from “betting on distant possibilities” to “looking at current returns.”
A bubble bursting does not mean AI is dead. It means valuations return to earth, pushing out speculation unsupported by performance and leaving the parts that truly create value.
There is another easily overlooked risk: geopolitics.
Nvidia’s business is at the center of great-power technological rivalry, and export controls, chip tiers, and supply chain relocation continue to constrain its room to expand. Huang’s personal communication skills once helped buffer the company as it balanced regulators in different countries and maintained customer relationships; a successor will find it difficult to replicate his network and influence. If tighter policies coincide with management turmoil, Nvidia’s deliveries, pricing, and market share will all face greater uncertainty, which will in turn affect the entire global computing power supply chain. This is the risk that deserves more attention than a personnel change.
Of course, the bubble could also “land softly.”
If Nvidia completes the transition smoothly, with no major interruptions to product upgrades, ecosystem support, or deliveries to major customers, while downstream AI applications begin generating real revenue and capital expenditure shifts from blind expansion to growth with returns, then this adjustment will simply mark AI’s transition from a period of frenzy to one of maturity.
Many technological revolutions have gone through similar phases: the internet and mobile internet both saw bubbles burst, but the technologies ultimately transformed industries. AI’s core proposition is to reduce the cost of production, research and development, and services. That underlying demand has not disappeared; it is simply taking longer to deliver than the market expected.
From an investor’s perspective, three layers of signals should be monitored to determine whether this is an emotional pullback or the start of a bubble.
The first layer is Nvidia itself: have its earnings guidance, data center revenue, gross margins, or customer orders materially declined?
The second layer is the industry chain: are cloud providers cutting capital expenditure? Are computing capacity utilization and downstream customers’ willingness to pay for applications improving?
The third layer is governance and competition: what is the new management’s strategic direction, how are US chip controls evolving, and how much traction are alternatives gaining?
Only if all three layers of signals deteriorate simultaneously can we say that the AI bubble has entered an accelerated bursting phase. A founder’s departure alone is not enough to trigger a systemic collapse.
Ultimately, Huang’s departure marks the end of an era, not the end of the technology. His personal charisma and strategic vision accelerated AI’s boom and amplified the market’s optimistic expectations for the sector. With this “anchor” gone, the market will return to the simplest business principles: revenue, profit, and cash flow. A bubble is when prices run ahead of delivery; when the market is no longer willing to pay a hefty premium for long-term stories, the bubble begins to contract. This will not happen in a single day of steep declines, but through a prolonged period of divergence: pure-play theme stocks with no ability to deliver will continue to be flushed out, while infrastructure and application companies that genuinely create efficiencies will find their footing amid volatility.
The AI wave will not come to an abrupt halt just because one person has left, but the market’s party has lost its most influential drummer. The market ahead will no longer be a game of believing in dreams, but a contest of the ability to deliver. $NVDA