#Gate24小时净流入Top2 The Next Crypto Opportunity: Protocol Oligopolies and the Migration of Old Money
The next major opportunity in the crypto market may no longer depend on a broad bull market.
For more than a decade, crypto wealth creation has mainly come from incremental capital. BTC rises, ETH follows, and then capital spreads to various small- and mid-cap tokens, creating periodic alt seasons. Almost every project has relied on a constantly expanding market to drive its valuation higher.
But as the industry matures, this model may not continue. The crypto market could enter a prolonged period of competition for existing capital, with overall market capitalization even remaining depressed. Yet a handful of projects could still deliver enormous outsize returns.
Two trends are worth watching: first, security risks in the post-AI era are accelerating protocol oligopolization; second, early BTC and ETH holders are gradually reallocating their wealth. The former means industry profits are concentrating in a few leading protocols, while the latter could provide long-term capital support to some competitors with distinctive value.
I. Assuming Protocols Will Fail Is the Reasonable Post-AI Era Outlook
The crypto industry has long treated security as a technical issue. Projects continually emphasize code audits, multisignatures, smart contract security, and decentralization, while investors are accustomed to seeking protocols that claim to be technologically advanced enough to avoid major vulnerabilities. But AI may be changing this logic. AI is reducing the cost of code review, vulnerability discovery, social engineering, and automated attacks. Defenders can also use AI, but attackers only need to find one weak point, while a financial system must continuously maintain large amounts of complex software, permissions, and operating procedures.
As AI capabilities improve, even mature protocols may struggle to guarantee that they will never suffer a major security incident. Investors may therefore need to change their valuation assumptions: instead of assuming protocols will not fail, assume that all complex protocols could fail given enough time. This does not mean that every protocol will inevitably be hacked; it means that long-term security risks need to be priced in.
Under this assumption, what matters is not just whether the technology is secure, but whether a protocol can compensate users, repair its systems, and continue operating after an incident. The security incidents involving ZEC and NEAR in 2026 have already provided two noteworthy examples.
A serious vulnerability was discovered in Zcash’s Orchard privacy transaction system, involving the potential risk of token counterfeiting. The development team quickly organized a fix, preventing any known real-world exploitation. NEAR Intents, meanwhile, suffered an actual cross-chain asset theft. The team subsequently fixed the vulnerability, coordinated the recovery of assets, and resumed operations. The incidents were different in nature, but both demonstrated the disaster recovery capabilities of mature projects. Zcash’s community funding system has accumulated assets worth hundreds of millions of dollars, although a substantial portion is denominated in ZEC and subject to governance constraints, so it cannot simply be treated as unrestricted cash. The NEAR ecosystem, meanwhile, has real business activity that generates ongoing fee revenue. These projects have not only developers, but also the funding and organizational capacity to maintain their systems over the long term.
This raises a metric that has been undervalued in the past: Can a protocol survive a major security incident?
For small projects without stable revenue or reserves, a single serious vulnerability could mean permanent market exit. Projects with ample funding and mature development teams are better positioned to fix issues and restore trust, even after a major crisis. If security incidents become a risk the crypto industry must routinely contend with, financial strength could become not only an operational advantage, but also a security advantage.
II. HYPE’s Core Advantage Is Being Better Positioned Than Most Competitors to Pay for Losses
Hyperliquid is a project worth studying under this new valuation logic. In the past, the market primarily evaluated DEXs based on trading speed, fees, slippage, volume, and liquidity.
But if we assume that any trading protocol could suffer a major incident in the future, competition gains a new dimension: who is better able to absorb the losses? Hyperliquid is already one of the highest-revenue protocols in the on-chain derivatives sector, with real trading demand and substantial recurring revenue. Compared with the many smaller DEXs that depend on token subsidies, fundraising, and market hype to stay operational, this profitability has particular significance.
Suppose two DEXs each suffer a security incident resulting in $30 million in losses. One generates hundreds of millions of dollars in annual revenue and has ample reserves and a mature operations team; the other generates only a few million dollars in annual revenue, or even operates at a persistent loss. The same loss could be a manageable business incident for the first, but leave the second insolvent, facing a user run and the end of the project.
What users ultimately care about is not just whether an exchange can avoid an attack, but also whether someone can take responsibility if their assets are lost.
This means that the profitability of trading protocols could carry new significance in their valuations.
The more HYPE earns, the better positioned it is in theory to invest in security, build reserves, handle incidents, and keep operating when competitors cannot survive.
Of course, protocol revenue is not the same as cash reserves. Hyperliquid uses some of its fee revenue to buy HYPE, and its Assistance Fund cannot be equated directly with an insurance fund for user assets.
Actual capacity to compensate users still depends on available assets, risk mechanisms, and clear compensation arrangements. But compared with the many small protocols without stable revenue, Hyperliquid is clearly on a stronger financial footing to establish these safeguards. More importantly, HYPE is not just competing for market share from other DEXs. Hyperliquid is taking derivatives trading business from centralized exchanges such as Binance and OKX. It does not need to replace CEXs entirely; capturing just a stable share of the overall market could drive substantial growth.
This gives it two potential sources of upside: gaining business from CEXs, and widening its lead over weaker competitors within the DEX sector through scale and profitability.
III. Major Security Incidents Could Actually Strengthen Industry Oligopolies
Binance’s recent major security incident can also be understood within the same framework. In the face of massive asset losses, leading exchanges have reserves, capital accumulated through years of operations, and strong external coordination capabilities. If Binance ultimately manages to compensate users and resume normal operations, it will have shown that it can withstand extreme losses. But an incident of the same scale at a mid-sized or small exchange could have a very different outcome. Many platforms may simply lack sufficient assets to make users whole, and could end up ceasing operations. Security incidents therefore do not necessarily weaken industry oligopolies; they may instead strengthen their competitive advantage. Because they may be able to afford to pay when something goes wrong. Large platforms that continue operating normally after major losses will lead users to place greater importance on solvency; smaller platforms without sufficient financial strength may lose all credibility after a single incident. This bears some resemblance to the evolution of the banking industry. Customers care not only about whether financial institutions can make money, but also whether they can absorb losses under extreme circumstances.
In the post-AI era, the crypto industry may also gradually develop a similar capital barrier. This shift could even occur in both the CEX and DEX markets.
Leading exchanges such as Binance and Gate may further consolidate their positions in the centralized exchange sector, while highly profitable protocols such as Hyperliquid may continue to expand their share of decentralized trading. The two types of platforms will continue to compete, but concentration within each sector could increase. AI may make it increasingly easy to create new protocols, while making it increasingly difficult to maintain a safe, trusted financial protocol capable of absorbing losses.
There may be more and more new projects in the future, but fewer truly new giants capable of surviving long term. This concentration trend may continue even if the crypto market as a whole enters a downturn. As weaker projects exit due to falling revenue, leading protocols could gain even more market share. So an industry downturn and rising profits for a handful of protocols are not contradictory. Oligopolization is coming to the crypto industry: only the leaders in each sector are worth investing in; the rest may never get their chance because they cannot afford to pay if something goes wrong.
IV. Old Money in BTC and ETH May Be Looking for a New Home
Besides protocol oligopolization, another important potential source of capital in the crypto market is the reallocation of wealth by early BTC and ETH holders.
After more than a decade of development, the crypto industry has created a large class of wealthy people. Some OGs have accumulated wealth worth tens of millions, hundreds of millions, or even billions of dollars by holding BTC and ETH over the long term. But past investment success does not mean they will keep the same asset allocation forever.
BTC is already a highly mature, giant asset, and its long-term upside, technological evolution, and security budget are all worth reassessing.
ETH, meanwhile, faces competition from high-performance public blockchains, as well as usage risks arising from complex wallet, authorization, and custody systems.
The major Bybit theft in 2025 took place during the ETH cold wallet signing process, with attackers exploiting infrastructure associated with Safe wallets that had been compromised. This does not mean Ethereum’s underlying consensus was breached, but it is enough to make some large asset holders reconsider the complexity of managing on-chain assets. (Binance still had an ETH wallet this time.) For OGs who have lived through more than a decade of market cycles, BTC and ETH may no longer offer the same growth potential they did in their early days, and may no longer be the only crypto assets worth holding for the long term. But even if they sell BTC and ETH, they may not leave the crypto market. These people are already accustomed to wallets, exchanges, on-chain assets, and extreme volatility. They have accumulated long-term knowledge, experience, and social connections in the crypto industry. This path dependence means that losing patience with BTC and ETH is more likely to first trigger asset reallocation within the crypto industry than a complete exit.
Jin, associated with the so-called “10·11 insider whale,” is one case worth watching.
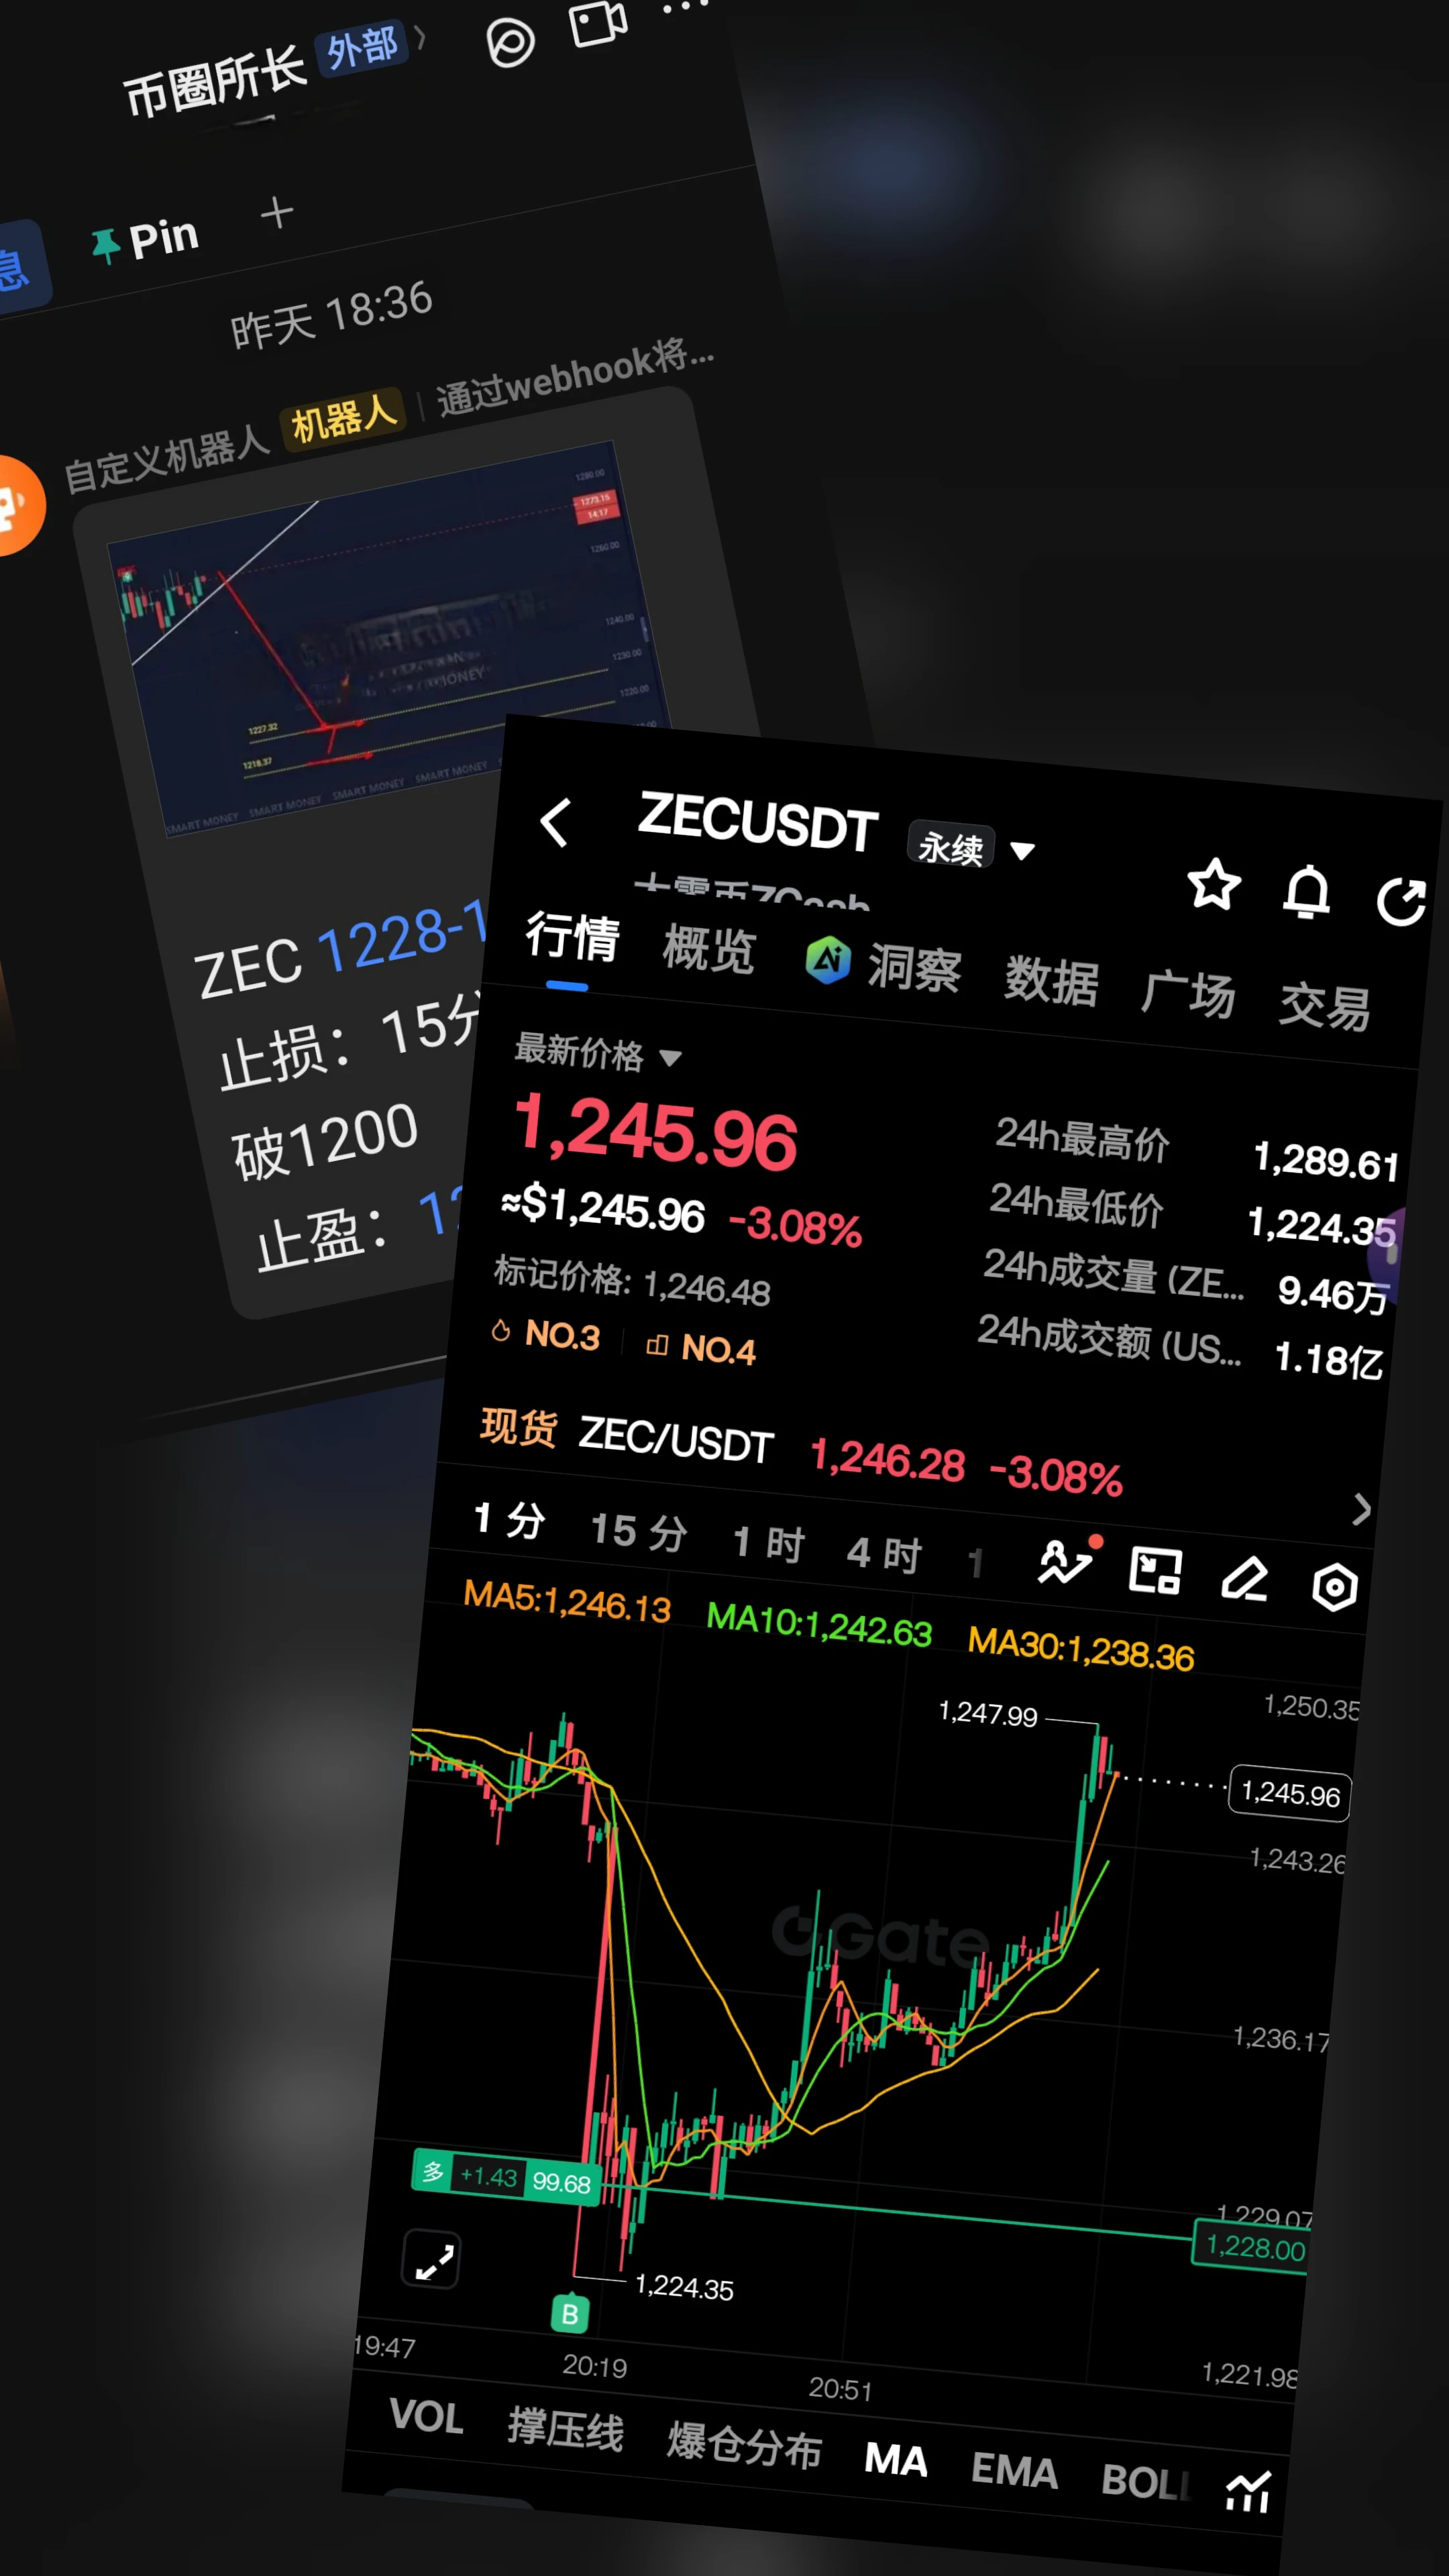
Based on publicly displayed withdrawal records and on-chain monitoring, accounts associated with him once withdrew around 200,000 ZEC, representing a very substantial amount of assets. The transactions also involved hedging and leverage, so they do not directly prove that he intends to hold for the long term, but the scale of the funds is already significant. For early investors who have accumulated enormous BTC wealth, allocating 1% of their total wealth could mean an investment worth tens of millions or even hundreds of millions of dollars.
For BTC, this could be only a small portion of the funds; for relatively smaller-cap assets such as ZEC, it could create enormous marginal demand.
More importantly, OGs may have different investment horizons from ordinary altcoin speculators. They have accumulated wealth by holding for more than a decade. If they find another asset they believe in, they could continue allocating capital over a five- or ten-year horizon, rather than merely participating in one short-term rally.
Of course, transfers from old wallets do not necessarily indicate a sale, and selling BTC or ETH does not prove that the funds will inevitably flow into competing coins. But even if only a small portion of early wealth is reallocated within crypto, it could have a significant long-term impact on small- and mid-cap assets.
V. The Winners of the Future Won’t All Need to Make Money!
If protocol oligopolization and the migration of OG wealth are considered together, two very different types of winners could emerge in the future crypto market.
The first type is profitable protocols like HYPE. They rely on real business activity, recurring revenue, and scale advantages to continually strengthen their security investment and disaster recovery capabilities in the post-AI era, gradually eating into competitors’ market share.
The second type may not rely on traditional business profits, but instead have a distinctive narrative and asset properties that resonate with some OGs. Examples include ZEC’s financial privacy, LTC’s long operating history and different mining economics, as well as other monetary assets that could regain recognition. These projects do not necessarily need to prove they can keep making money like businesses. The value of monetary assets does not come entirely from operating profits; it comes from scarcity, credibility, long-term consensus, and the store-of-value function holders are willing to assign to them.
For competitor coins with market capitalizations far below those of BTC and ETH, attracting long-term allocations from just a handful of wealthy OGs could lead to a significant valuation re-rating. What these two types of assets have in common is not that they share the same business model, but that both could benefit from the reallocation of existing capital. The former attract capital through increasingly strong business performance; the latter could regain recognition from long-term investors because of an attribute that has been overlooked in the past. Of course, an appealing narrative is no guarantee of success, and capital migration does not guarantee sustained price increases.
What is truly worth looking for are assets that are distinctive, have sufficient staying power, and are not yet fully priced in by the market.
Past alt seasons relied on incremental capital spreading broadly, but the structural market trends of the future may be the opposite: capital will be highly concentrated, and only a handful of projects will continue to attract new demand.
The next crypto wealth effect may not come from the entire industry expanding again, but from profits concentrating within the industry and old BTC and ETH money migrating over the long term to a handful of competing assets. Even without a broad bull market, these two shifts could be enough to create new winners.
The boom period is not just about expansion during an upswing; redistribution is also an important opportunity!