Share your thoughts
placeholder
Article
What activities are included in Gate VIP’s Golden Autumn Festival? A full breakdown of trading rebates, level acceleration, and consecutive check-ins
GateBlog
What activities are included in Gate VIP’s Golden Autumn Festival? A full breakdown of trading rebates, level acceleration, and consecutive check-ins
In digital asset trading, cost control and access to benefits are two variables that professional users focus on over the long term. In the golden autumn of 2026, Gate launched a VIP-exclusive campaign series covering multiple dimensions, including trading rebates, net deposit incentives, tier upgrades, and consecutive trading check-ins. Based on Gate’s official campaign page and Gate market data as of September 20, 2026, this article systematically outlines the structure of the golden autumn campaign and the VIP tier system, providing a comprehensive reference for users focused on optimizing trading costs.
The Core Logic of Gate’s VIP Tier System
Gate has built a multidimensional VIP tier evaluation mechanism that does not rely on a single trading volume metric. Users can reach the corresponding threshold through any one of three paths: account asset holdings, average GT holdings over 14 days, or 30-day trading volume. The system automatically
  • 3
I don't believe it; it's my last bit of stubbornness.
post-image
$1000 to $100,000 Crypto Trade Challenge Today
live-cover
LIVE534
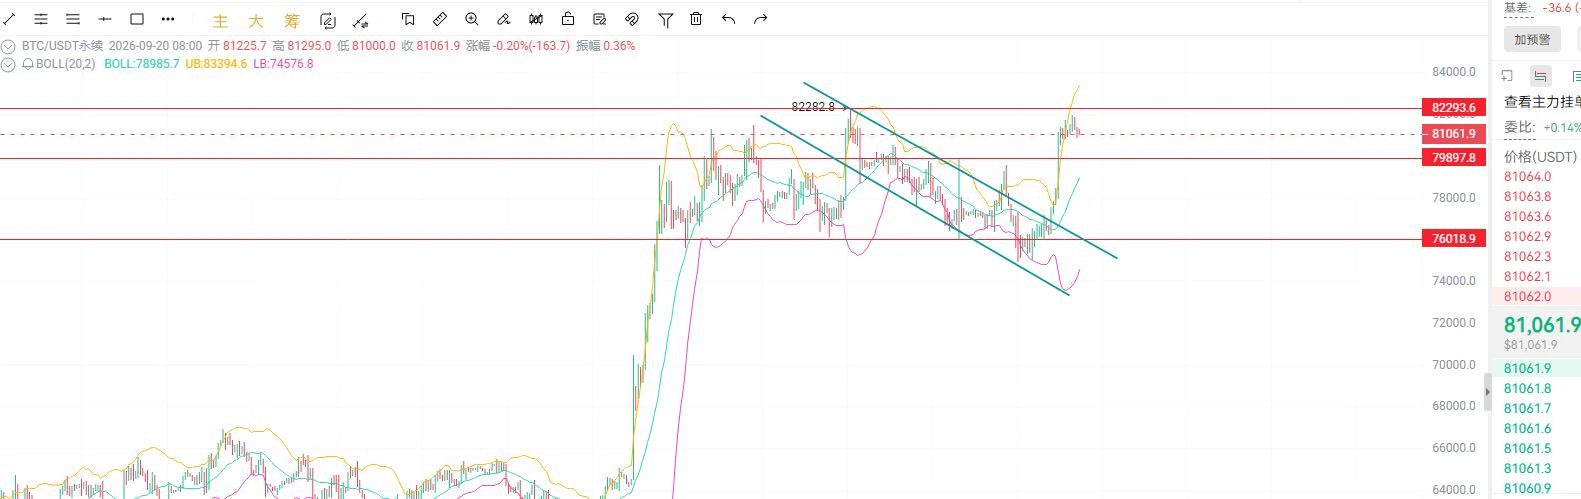
☀️ GM! Ding—BTC has reached 81K. 🛗
$80K has regained a firm footing, will the market continue upward?
👇 How high do you see the next stop?
🔥 Today's recommended topic: #BTCBackTo81K
Come post on Gate Square and share your take:
📈 Will it continue breaking out, or consolidate at high levels?
🎯 How high do you see the next target?
💡 Which signals are worth paying close attention to?
Quality insights may receive featured recommendations + Square traffic support.
💬 Go post on Gate Square:
https://www.gate.com/post
post-image
BTC-0.59%
  • 6
  • 2
$33 million in unrealized losses, yet he keeps adding to his position—the “doomsday bet” by ZEC’s largest short seller. ZEC broke through $1,584, setting a new all-time high. Behind this market rally lies an extreme countertrend battle between major players.
The market’s top ZEC short holder is suffering massive unrealized losses, yet has chosen to keep adding to the position and holding against the trend. The whale holds approximately 38,000 ZEC short, with a total position value of nearly 59 million and an average entry price of 665.8. As the price continues to rise, unrealized losses have k
post-image
ZEC-6.06%
ETH-0.56%
Weekend Summary
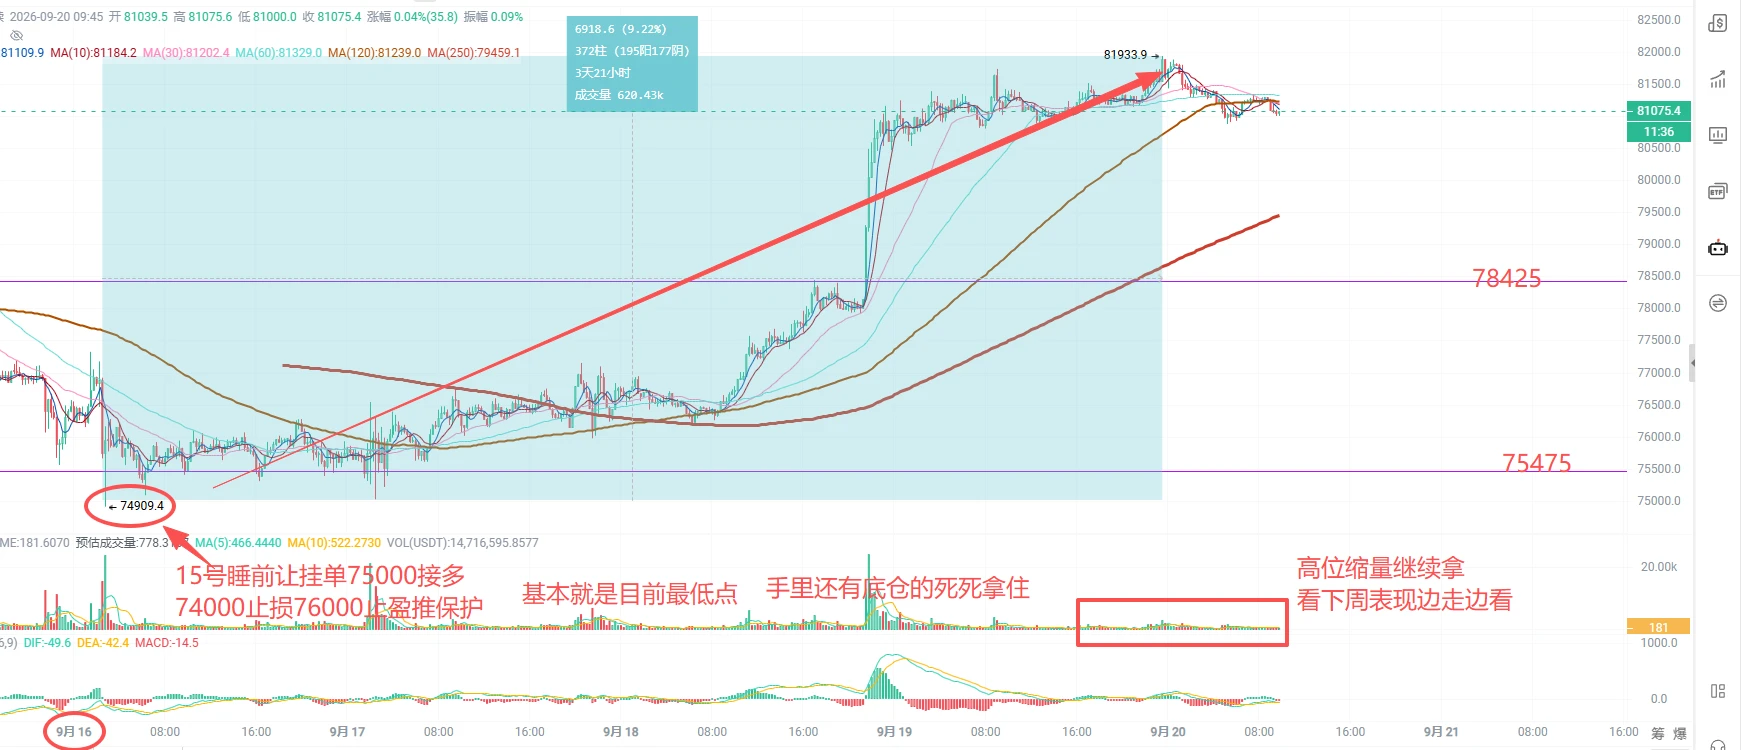
Yesterday’s summary already covered it. This week, all 10 pre-emptive strategy calls were spot-on and profitable—10 out of 10, making me the real Sao-ge himself this week;
I accurately anticipated the US Senate, Kevin Warsh and the Fed, among many other setups. Since the data landed, the market has rallied continuously from early Thursday until now, and we basically captured all the gains!
For those who missed it: give yourselves a few hard slaps to wake up!
BTC support/resistance levels: 78425/75475/71300/67135
This week’s 75000 long: hold the core position firmly with the sto
post-image
BTC-0.59%
ETH-0.56%
SNDK+11.05%
  • 4
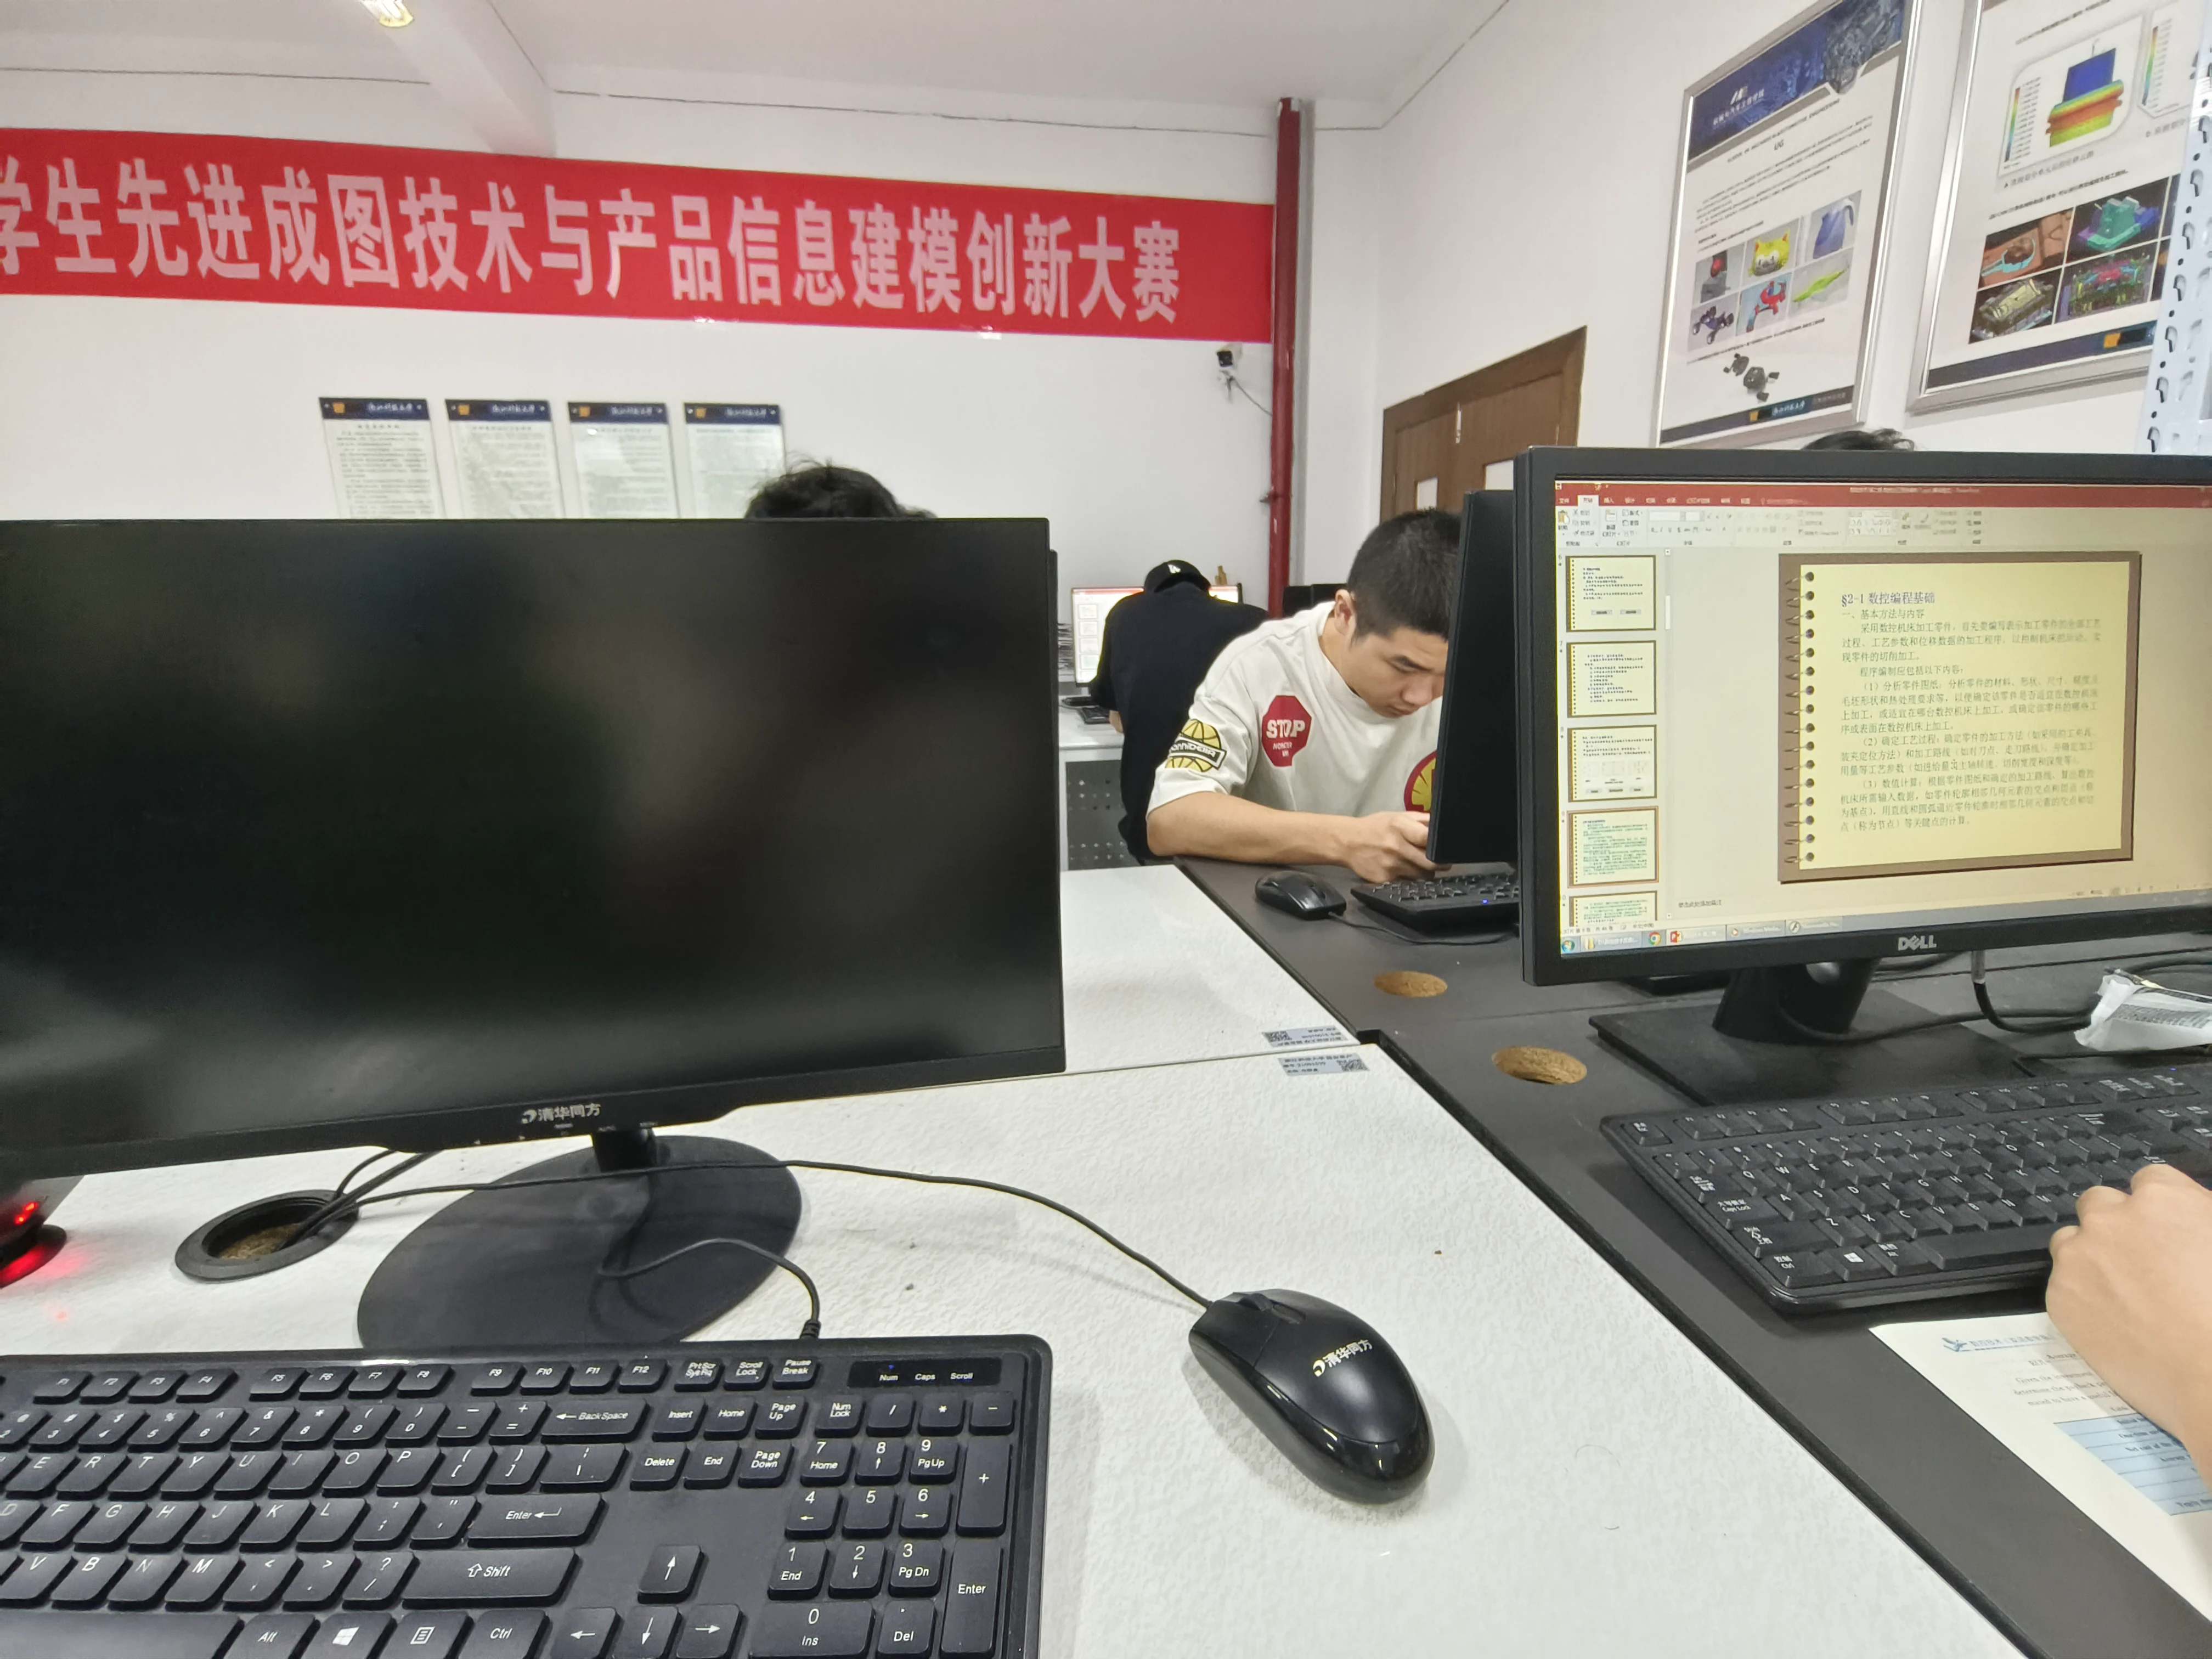
I was already a little late when I got up, then I bought breakfast. When I got to the classroom, all the computers in the last row were broken, and this one is broken too. Could the school provide more working computers? How are we supposed to attend class without computers?$ETH #Gate股票永续合约覆盖数量行业第一
post-image
ETH-0.56%
Watching the market nonstop got annoying; once I turned it off, I could see things more clearly, and with my eyes off the screen, my heart stopped panicking too.
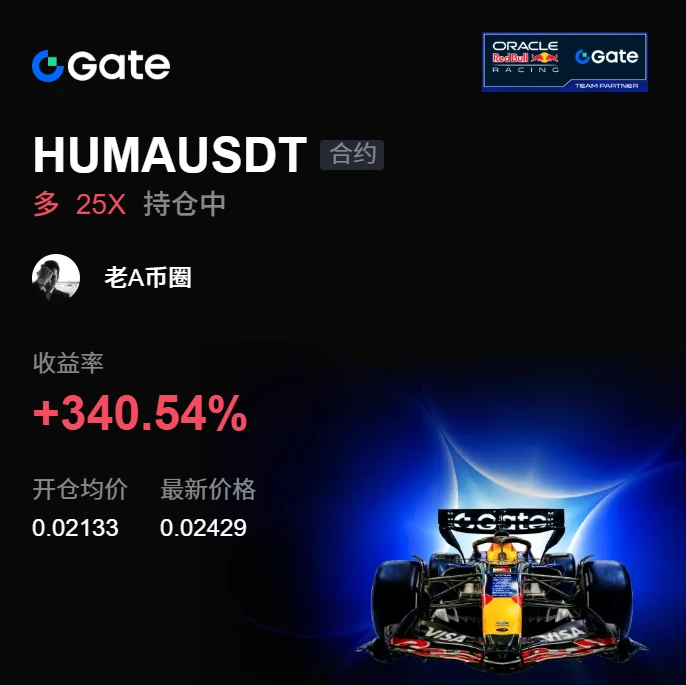
A few days ago, the last thing I saw before bed was a pullback holding on $HUMA , with buying pressure strengthening. At the time, I only said: Stay bullish, don’t panic—the structure is still intact.
Now from 0.02133 to 0.02419, +331.34% locked in. This profit feels great—staying up late wasn’t for nothing.
Putting risk controls first is called rationality; cutting losses only after losing is called making a brave sacrifice. Staying
post-image
HUMA-4.77%
DOGE-2.20%
SNDK+0.24%
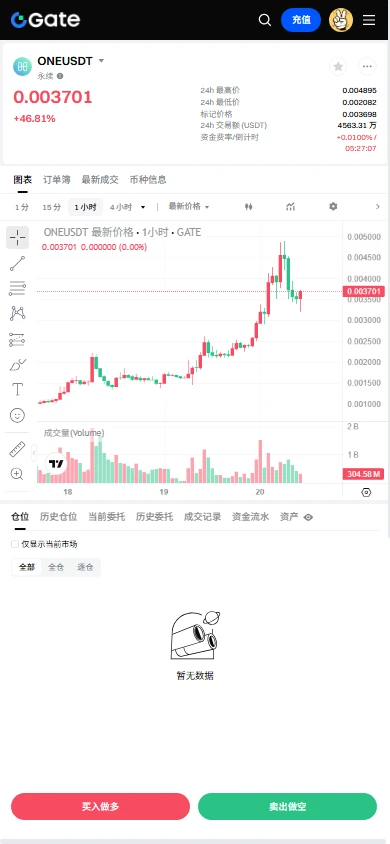
🛑 Everyone, $ONE looks very weak right now, and the sellers seem to be in complete control. Selling pressure is intensifying, so I’m preparing for a major sell-off that could occur from here.
I will short $ONE with 30x leverage, targeting a drop below $0.0020. The key level to watch is $0.0020. If sellers continue to dominate and support breaks, we could see another strong downward move. I’m closely monitoring the price action and managing risk carefully, as 30x leverage can be extremely dangerous. Will you short $ONE with me, or choose to stay on the sidelines? Click below to trade with m
post-image
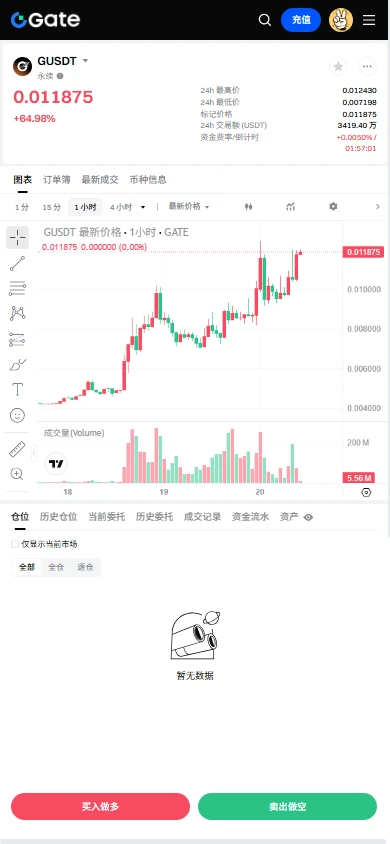
【$G Signal】Long, 1H MACD expansion, lie in wait for a pullback to the range
$G RSI 82.79, 1H Bollinger upper band at 0.0114 is nearby, 1H MACD bullish bars continue to expand, and short-term strength persists.
🎯Direction: Long
⚡Entry/Pending order: 0.01119033 - 0.01122400
🛑Stop-loss: 0.01111176
🚀Target 1: 0.01139236
🚀Target 2: 0.01147654
🛡️Trade management:
- Execution strategy: After reaching Target 1, reduce the position by 50% and move the stop-loss up to breakeven. If the price falls back to the entry level, exit automatically to protect the principal.
In-depth logic: The 1H Bollinger
post-image
BTC-0.59%
ETH-0.56%
SOL-3.79%
Market Alert

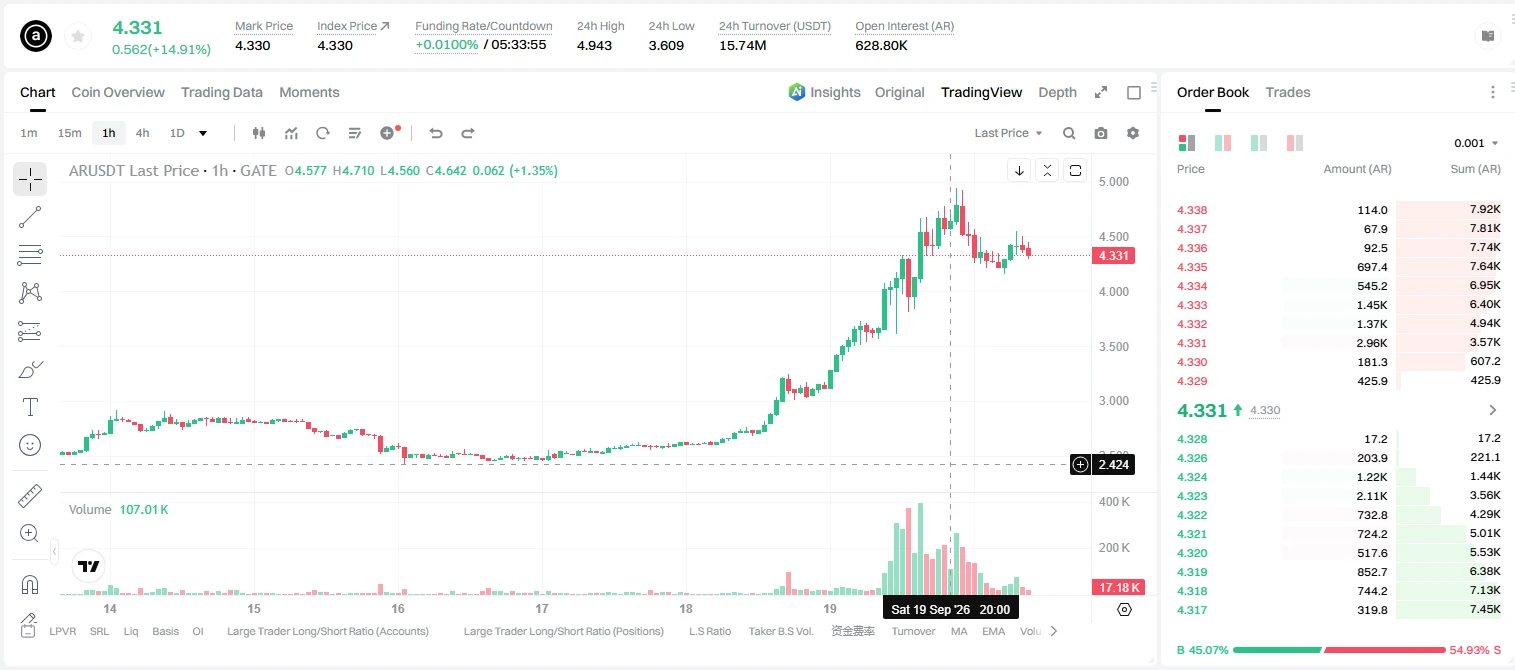
$AR /USDT - LONG

Trade Plan:
Entry: 4.257 – 4.367
SL: 3.779
TP1: 4.711
TP2: 4.978
TP3: 5.377

Why this setup?
Technical setup found.

Debate:
Thoughts?

⚠️ Personal market analysis only. NFA — manage risk and DYOR.
Educational content, not investment advice or a recommendation to buy, sell, deposit, or withdraw any asset. No paid promotion or referral/affiliate links.
post-image
AR+12.47%
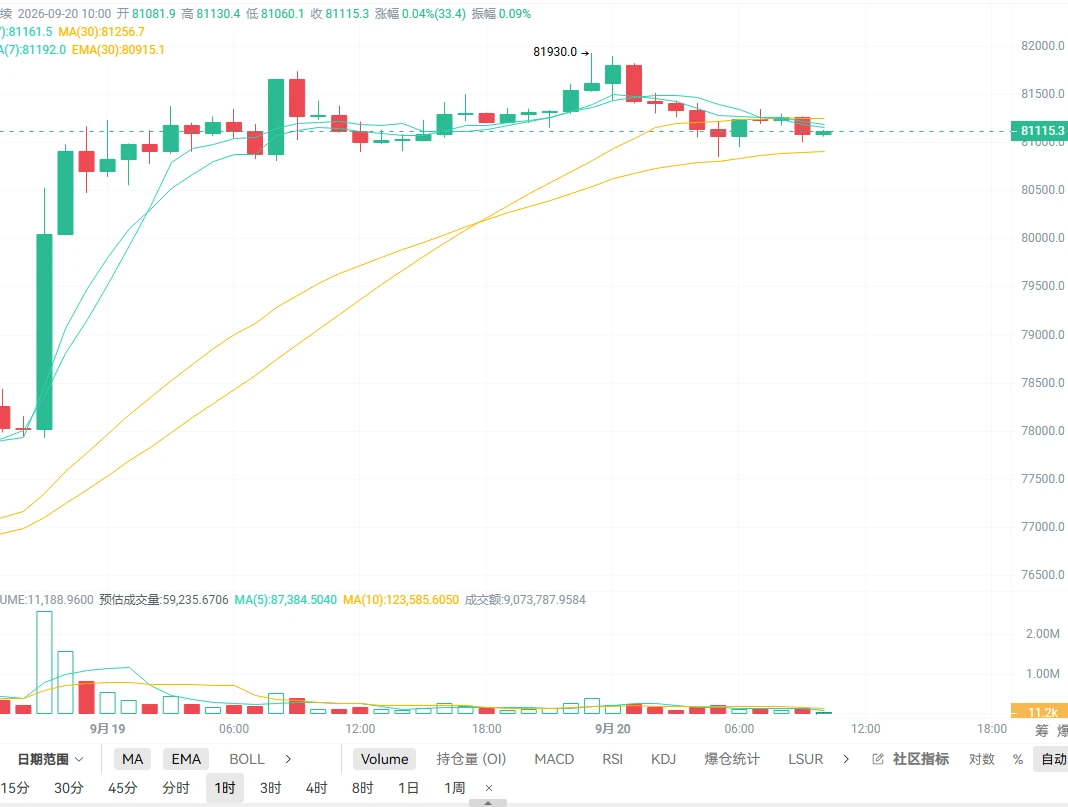
Yang Guang bit | September 20 $BTC ETF large inflows continue to fuel the short squeeze, buy longs at 81000 support, lightly test shorts at 82000
[Today's Strategy]
Longs (primary strategy)
Entry: Buy on a pullback to the 80850—81050 support zone
Stop-loss: Below 80550
Take-profit targets: First target 81700—81800; second target 81900—82000
Shorts (lightly test shorts at 82000)
Entry: Lightly test shorts on a rebound to 81900—82100
Stop-loss: Above 82400
Take-profit targets: First target 81300—81500; second target 80900—81000
Key Conclusion
Geopolitically, the US-Iran conflict has continued fo
post-image
BTC-0.51%
【$ONE Signal】Long 1H pullback support + negative funding rate short squeeze
$ONE 1H pullback support, 4H RSI at a high 78.34, order book bid depth imbalance +15.47%, with thick buy orders below 0.003865.
🎯 Direction: Long
⚡ Entry/limit orders: 0.003896774 - 0.003908500
🛑 Stop-loss: 0.003865553
🚀 Target 1: 0.003972920
🚀 Target 2: 0.004005130
🛡️Trade management:
- Execution strategy: Reduce the position by 50% after reaching Target 1, and move the stop-loss up to the breakeven level. If the price falls back to the entry level, exit automatically to protect the principal.
The 4H MACD histo
post-image
Good morning, fam!
Embrace the morning light and welcome a new day.
Like a seashell,
remain radiant despite weathering the storms.
May we keep moving upward,
slowly building up our own light. ✨
post-image
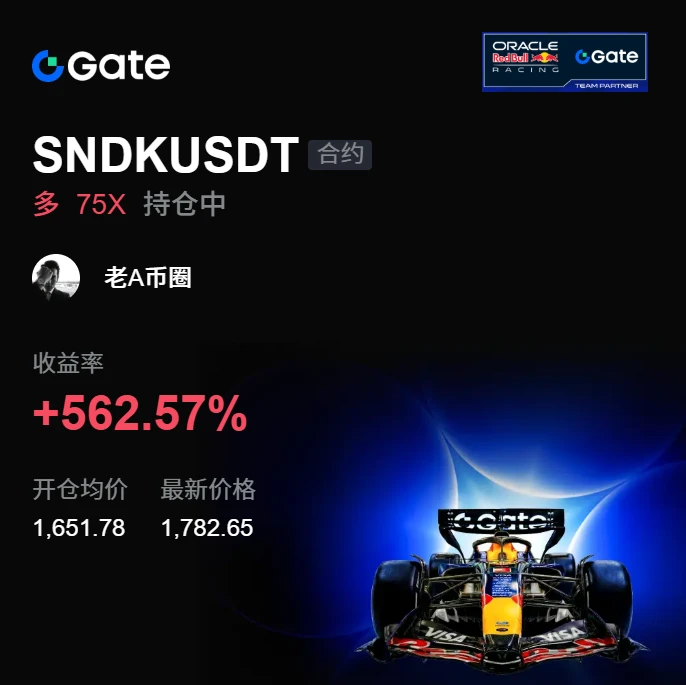
I didn’t make any judgment—it just stayed open a little longer, and I didn’t expect it to reward me so generously. When it was bottoming out intraday, $SNDK the key level held, buying pressure strengthened, and I told everyone at the time not to touch their long positions.

From 1651.78 to 1783.16, +562.96%—the wait was worth it. Take most of the profit off the table first, lock in 80%, and protect the remaining 20% at breakeven by moving the stop-loss closer to the entry price.

Hold as long as the trend remains intact; get out if it breaks down. Don’t fall in love with a stock. The premise
post-image
SNDK+0.24%
SOL-3.64%
DOGE-2.20%
JUST IN: Zhipu AI faces pushback from Taiyuan Chengming Technology over alleged automatic uploading of full project data via ZCode, with demands to delete, disclose and prove data removal. $AI?
post-image
ZHIPU AI+5.40%
I just opened a quick short-term trade on $AVAX
. Enter now: sell at 10.450 or 10.650. First target: 10.200. Second: 10.00. Third: 9.800. Final target: 9.600++. Set the stop-loss above 11.200.
post-image
AVAX+11.96%
#日本央行加息至1.25%创31年新高 #Gate广场中秋团圆局 Japan raises rates by 25 basis points to 1%, a 31-year high—why did the yen fall instead of rise?
On September 18, the Bank of Japan raised its policy rate by 25 basis points to 1.25%, the highest level since April 1995. This was another rate hike after the BOJ raised rates from 0.75% to 1% in June this year, and was an important step in Japan’s move away from its long-standing ultra-loose monetary policy. But the market saw an apparently “unreasonable” result: Japan raised rates, yet the yen did not rise and instead continued to fall. As of the afternoon of Se
post-image
ThisIsTranslateContent:
#日本央行加息至1.25%创31年新高 #Gate广场中秋团圆局 Japan Raises Interest Rates by 25 Basis Points to 1%, a 31-Year High—Why Did the Yen Fall Instead of Rise?
On September 18, the Bank of Japan raised its policy rate by 25 basis points to 1.25%, the highest level since April 1995. This was another rate hike after the Bank of Japan raised rates from 0.75% to 1% in June this year, and marked another important step in Japan’s move away from its long-standing ultra-loose monetary policy. But the market produced a seemingly “counterintuitive” result: Japan raised interest rates, yet the yen did not rise and instead continued to fall. As of the afternoon of September 18, the yen briefly fell to around 157.76 against the US dollar, down more than 1% intraday; its cumulative decline against the US dollar this week also reached approximately 2.6%.
So why did the yen fall despite the Bank of Japan raising interest rates? The answer is not complicated. What truly determines exchange rates has never been a single rate hike itself, but rather how interest rates will evolve in the future and whether the interest-rate gap between Japan and the United States will genuinely narrow.
I. The yen rate hike failed to drive the yen higher, with the yen falling more than 1% against the US dollar after the hike.
According to conventional logic, when a country’s central bank raises interest rates, domestic asset yields increase, potentially attracting capital inflows and supporting the local currency. But the yen’s problem is precisely this: Japan raised rates, but the market believes the pace of future rate hikes may not be as fast as expected.
On September 18, the Bank of Japan voted 7–2 to approve a 25-basis-point rate hike to 1.25%. This was the highest level in 31 years, but two members voted against it, calling for the rate to remain at 1%. The market subsequently interpreted the result as indicating that the Bank of Japan was not internally united in supporting faster tightening. At the same time, the Federal Reserve also raised its policy rate by 25 basis points this week to 3.75%–4%.
In other words, although Japan raised rates, the United States raised rates by the same amount, so the Japan-US interest-rate gap remained substantial.
More importantly, the market trades not on “whether rates will be raised today,” but on “how much further they can rise in the future.” If Japan’s rate rises from 1% to 1.25% while US rates remain far above Japan’s, the change in the interest-rate gap caused by a single hike is actually limited.
Therefore, the market did not buy large amounts of yen simply because Japan raised rates. Instead, after confirming that the Bank of Japan had not signaled a stronger series of rate hikes, it increased demand for the US dollar again. This is why the seemingly contradictory scene emerged: the Bank of Japan raised rates, yet the yen fell. In reality, this does not mean the rate hike failed; rather, the market repriced the “pace of future rate hikes.”
II. Whether the yen will see another rate hike this year, with market expectations failing to increase.
This may be the question the market cares about most after the Bank of Japan’s rate hike on September 18. The Bank of Japan did raise rates, but it did not clearly tell the market: When will the next hike come? The 7–2 vote at the September 18 meeting itself showed that divisions remain within the Bank of Japan over the pace of rate hikes. If all nine voting members had supported a hike, the market might have found it easier to conclude that Japanese monetary policy was entering a clearer tightening cycle. But two members publicly opposed the hike. Therefore, market bets on whether Japan will continue raising rates this year did not increase significantly because of this hike.
Bank of Japan Governor Kazuo Ueda also emphasized after the meeting that there is no pre-set fixed pace for future rate adjustments, and no mechanical arrangement to “raise rates once every three months.” The central bank will reassess the situation at each meeting based on changes in prices, wages, the economy, and financial markets.
Of course, Ueda did not close the door on further rate hikes. He said that if inflation risks rise significantly, the Bank of Japan would not rule out raising rates by 50 basis points at once, or even implementing consecutive hikes at subsequent meetings. This statement is highly important. It means that the Bank of Japan has gradually shifted the discussion from “whether to raise rates” to “how quickly to raise them.” For now, however, the Bank of Japan still wants to avoid tightening financial conditions too quickly. The reason is practical: Japan’s economy still needs time to adjust to higher interest rates, while corporate financing costs, real estate, financial assets, and household loans will all be affected. Therefore, whether the yen can truly strengthen in the future depends not only on how high Japanese interest rates reach, but also on whether the market believes the Bank of Japan will continue raising rates. If expectations of future hikes continue to intensify, the yen may regain support; if rate hikes enter a slow, gradual phase, the Japan-US interest-rate gap may continue to weigh on the yen for a long time.
III. Japan’s inflation in August 2026 was already close to the Bank of Japan’s target.
Why must the Bank of Japan continue considering rate hikes now?
One answer is inflation. Data released by Japan’s Ministry of Internal Affairs and Communications on September 18 showed that Japan’s nationwide CPI rose 1.9% year-on-year in August 2026; excluding fresh food and energy, CPI also rose 1.9% year-on-year. In other words, Japan’s inflation has moved increasingly close to the Bank of Japan’s 2% target. More importantly, the Bank of Japan is concerned not only with the current CPI figure, but also with whether rising costs can continue to be passed on to businesses and consumers. Rising energy prices, yen depreciation, and higher prices for semiconductors and other goods could all increase corporate costs. If companies can pass higher costs on to consumers, the initial shock from energy and import prices could gradually evolve into broader domestic inflation. This is the biggest difference between the Bank of Japan today and in the past.
Over the past several decades, Japan’s biggest concern was deflation. Companies were reluctant to raise prices, households were reluctant to spend, wage growth was weak, and the central bank could only stimulate the economy through extremely low or even negative interest rates. Now, however, the Bank of Japan is beginning to worry about another problem: could inflation shift from being “too low” to exceeding its target? The Bank of Japan’s July outlook report forecast that core CPI excluding fresh food would rise by an average of 2.5% in fiscal 2026, while real GDP would grow 0.6%. The report also noted that oil prices, yen depreciation, and higher semiconductor prices driven by AI demand could all push prices higher.
Therefore, the Bank of Japan’s policy logic is changing: previously, it sought ways to push inflation higher; now, it must prevent inflation from rising too quickly. This is also an important signal that Japan has entered the monetary-policy normalization phase.
IV. Japan’s negative-interest-rate era has come to a complete end.
Viewed over a longer period, the significance of the September 18 rate hike goes far beyond 25 basis points. It means that Japan’s decades-long ultra-loose monetary policy is truly approaching its end.
In March 2024, the Bank of Japan ended its negative-interest-rate policy and simultaneously exited its yield-curve-control policy. Since then, Japanese interest rates have gradually begun returning to normal levels.
In June 2026, the Bank of Japan raised its rate to 1%; in September, it raised it further to 1.25%. Moving from negative rates to 1.25% may look like merely a change in a few numbers, but it actually represents a major turning point in Japan’s financial environment.
In the past, Japan relied on extremely low interest rates to stimulate the economy for an extended period. The defining feature of this policy was cheap borrowing. Corporate financing costs were low, household borrowing costs were low, and Japan was also one of the world’s largest sources of low-cost financing. As a result, large amounts of capital flowed overseas, forming the famous “yen carry trade.”
Now, as Japanese interest rates continue to rise, this logic is changing. Japanese companies and households will face higher borrowing costs in the future, but savers and banks will also begin receiving higher interest income.
More importantly, the yields on Japanese assets themselves are rising. If Japan continues to raise rates and the yen gradually strengthens, the past model of “borrowing cheap yen and investing in high-yield overseas assets” will face increasing constraints. This does not mean the yen carry trade will suddenly disappear, but it does mean that the environment on which it depends is changing.
In the past, Japan’s biggest advantage was cheap yen. In the future, Japan may develop a different kind of advantage: higher domestic yields, a stronger yen, and domestic capital flowing back.
Therefore, what is truly worth watching about Japan’s rate hikes is not why the yen fell 1% today. It is that Japan is gradually changing from an economy that has long exported low-cost funds into one where domestic interest rates and asset yields are both beginning to rise. This may mean that the contraction of the yen carry trade is not necessarily the end of Japan’s investment story. On the contrary, it may be the starting point for renewed changes in Japan’s financial markets and capital-flow dynamics.$USDJPY
repost-content-media
USDJPY+0.58%
9.20 BTC
BTC is currently oscillating around 81000. Yesterday’s intraday high was 81900, failing to break the previous high. It is normal for the market to move sideways during the current day off.
The 1-hour chart is in a short-term correction phase, while the bullish structure on the 4-hour chart remains intact, with MACD showing a bullish alignment. However, directly chasing longs is not recommended at present to avoid getting trapped. The intraday strategy is the same as yesterday: short at highs and long at lows.
Intraday strategy: Short at 81200, stop-loss at 81800, target 80000$BTC .
post-image
BTC-0.51%
Layout for Bitcoin, Ethereum, and Dogecoin
live-cover
LIVE1,402
Load More

Join 40 M users in our growing community

⚡️ Join 40 M users in the crypto craze discussion

💬 Engage with your favorite top creators

👍 See what interests you

Trending Topics

BTCRetakes81K

56.13k Views59.73k Discussing

BTC has reclaimed the $81,000 level and is consolidating near 81K. The $79,800-$80,500 zone serves as near-term support, while $82,000-$82,900 remains key resistance. Funding rates are back to neutral, and spot ETF inflows have resumed. Breakout or pullback?

GarrettJinHolds320MInZEC

37.14k Views1.39k Discussing

MSTRTopsNasdaq100

72.33k Views2.59k Discussing

View More