







#黄仁勋辞职 #每周来晒 Is now a good time to buy the dip in Nvidia?
For investors, does Jensen Huang's departure present a good opportunity to buy the dip in Nvidia, or is it a value trap that means Nvidia should be removed from their long-term holdings?
Wall Street is deeply divided on this question, but there is relatively broad agreement that Nvidia's share price will remain under pressure in the short term.
Christopher Davis, founding partner of Hudson Value Partners, said he thinks Nvidia may have to sit on the sidelines for a while until the situation becomes clearer. “For now, I’m inclined to sit tight. This is not an opportunity to buy.”
Stephanie Link believes that although Nvidia's share price has fallen considerably, it is not a value trap because the company is still growing. The classic definition of a value trap is a company that isn’t growing, always looks cheap, and keeps getting cheaper. “Nvidia certainly still has growth potential, but it needs time to find its footing.”
Stephanie Link also stressed that Nvidia is a stock that almost everyone is likely to be overweight in, but this shock is very difficult to price in. Although Nvidia's fundamentals are very strong, at least in the short to medium term, fundamentals have been completely cast aside. “I like buying quality companies at low prices, but the headwind this time is just too great, especially because it’s simply impossible to foresee.” Stephanie Link said.
Stephanie Link first bought Nvidia in July this year, when its share price had already risen above $200. “At the time, I thought Nvidia's valuation was very attractive—it was trading at 18 times projected future earnings, and the company was expected to post very high annual revenue growth over the next two years. In my view, the disconnect between valuation and fundamentals was just too large. And it has underperformed the S&P year to date. Those were all reasons I bought.”
Nvidia's second-quarter earnings were also impressive.
In its second-quarter report, Nvidia said the shortage of AI computing capacity was likely to persist at least through the end of fiscal 2028. The report showed that Nvidia's second-quarter revenue doubled to $96.22 billion, with data center revenue up 117% year over year to $89 billion. It forecast third-quarter revenue of $108 billion, above analysts’ average estimate of $104.1 billion, and unusually provided a revenue growth forecast for fiscal 2028, projecting growth of 80%. Nvidia will report its third-quarter results on November 17.
Where will the money flowing out of Nvidia go?
One question to watch is where the money flowing out of Nvidia will go: will it continue flowing into other AI names or move into other sectors?
On this, Stephanie Link said that holding a bunch of names within the AI sector does not reduce AI concentration or theme risk. Selling some Nvidia to buy AMD does not change AI exposure; beta to sentiment around the theme will remain high.
So how should investors decide which stocks to sell? Stephanie Link advised investors to weigh the positions of their AI stocks in their portfolios one by one. If a stock already accounts for more than 6% or 7% of a portfolio, it may be time to consider trimming the position and locking in gains, “because if you don’t, history tells us the market will often take those gains away from you.” Stephanie Link also advised investors to start looking for companies that “AI will make better”—beneficiaries that can improve what they do, rather than companies that must keep pouring huge sums into capital expenditures.
Fortunately, so far the problem has been confined to Nvidia and has not spread across the entire AI sector.
But Stephanie Link believes that if Nvidia continues to weaken, and the AI revolution really does rely on Nvidia for power, the current difficulties could drag the entire AI trade down with it.
The AI sector is facing several tests. In addition to the Nvidia turmoil, there are rising interest rates and Anthropic's IPO.
Market expectations of a Fed rate hike in December are increasingly aligned. Some investors even believe the Fed will raise rates by 50 basis points in December. However, Stephanie Link believes the Fed has consistently signaled a 25-basis-point hike. Even if it raises rates by 25 basis points in December, the market can still move higher because that is already the baseline expectation for most people; anything beyond it would cause a problem. Meanwhile, this earnings season has shown that companies are performing strongly, and there is no reason to think that will not continue in the fourth quarter and next year.
Another key factor shaping the AI sector's outlook is bonds.
Goldman Sachs data shows that global debt issuance related to artificial intelligence has totaled nearly $600 billion so far this year, including debt issued by hyperscalers, data centers, project financings, and other AI-related borrowers. About $400 billion of that is in the US investment-grade debt market, accounting for more than a fifth of total investment-grade bond supply and bringing AI-related bonds to around 12% of the Bloomberg US Corporate Bond Index.
Howard Marks, co-founder and co-chairman of Oaktree Capital, said that AI-related debt issuance is clearly one of the major developments in capital markets this year. Artificial intelligence may require an average of $1 trillion in new capital annually for some time, with hundreds of billions of dollars potentially continuing to be raised through debt issuance each year. Since expanding capacity and developing new products are urgent priorities for AI companies, they may not slow their AI investments simply because interest rates could be higher than expected. This means they must become “takers” of financing, even when financing is scarce and costs more.
In the past, the high-margin, non-AI businesses of big tech companies generated substantial free cash flow, leaving them debt-free, cash-rich, and highly rated. That is now changing: these companies are drawing down their cash reserves and current cash flow, and borrowing more.
For now, their strong investment-grade ratings allow them to finance AI expansion easily. But as this process unfolds, it is worth considering whether their credit ratings will change. Meanwhile, the market often sees loans and related purchases between chipmakers, major AI companies, data center builders, and others. It remains unclear whether these transactions are conducted at arm’s length or whether suppliers are subsidizing buyers to support demand and protect market share for their products.
Howard Marks therefore said that AI lending is entering a new era, characterized by debt concentrated in one industry, rapidly changing industry fundamentals, and heavy reliance on future sales to calculate revenue. Lenders must remain vigilant about the creditworthiness of the borrowers they support and the structures and terms under which they do so.
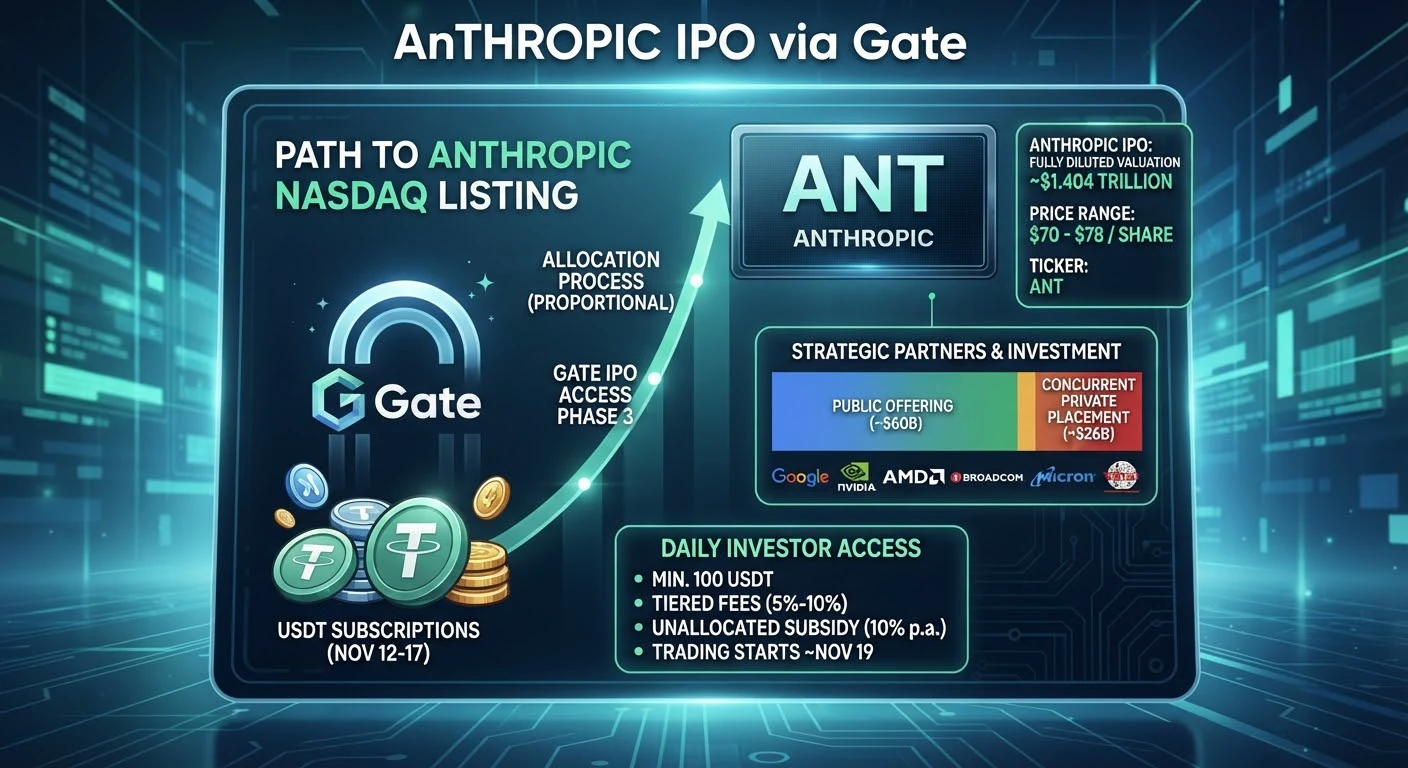
Meanwhile, the anticipated IPO of AI leader Anthropic is also expected to divert some market funds. According to the announcement, Anthropic will hold its IPO around November 19. The company announced plans to offer 825 million shares in the upcoming IPO, priced at $70 to $78 per share. The offering is expected to raise up to $64.4 billion for Anthropic.$NVDA
For investors, does Jensen Huang's departure present a good opportunity to buy the dip in Nvidia, or is it a value trap that means Nvidia should be removed from their long-term holdings?
Wall Street is deeply divided on this question, but there is relatively broad agreement that Nvidia's share price will remain under pressure in the short term.
Christopher Davis, founding partner of Hudson Value Partners, said he thinks Nvidia may have to sit on the sidelines for a while until the situation becomes clearer. “For now, I’m inclined to sit tight. This is not an opportunity to buy.”
Stephanie Link believes that although Nvidia's share price has fallen considerably, it is not a value trap because the company is still growing. The classic definition of a value trap is a company that isn’t growing, always looks cheap, and keeps getting cheaper. “Nvidia certainly still has growth potential, but it needs time to find its footing.”
Stephanie Link also stressed that Nvidia is a stock that almost everyone is likely to be overweight in, but this shock is very difficult to price in. Although Nvidia's fundamentals are very strong, at least in the short to medium term, fundamentals have been completely cast aside. “I like buying quality companies at low prices, but the headwind this time is just too great, especially because it’s simply impossible to foresee.” Stephanie Link said.
Stephanie Link first bought Nvidia in July this year, when its share price had already risen above $200. “At the time, I thought Nvidia's valuation was very attractive—it was trading at 18 times projected future earnings, and the company was expected to post very high annual revenue growth over the next two years. In my view, the disconnect between valuation and fundamentals was just too large. And it has underperformed the S&P year to date. Those were all reasons I bought.”
Nvidia's second-quarter earnings were also impressive.
In its second-quarter report, Nvidia said the shortage of AI computing capacity was likely to persist at least through the end of fiscal 2028. The report showed that Nvidia's second-quarter revenue doubled to $96.22 billion, with data center revenue up 117% year over year to $89 billion. It forecast third-quarter revenue of $108 billion, above analysts’ average estimate of $104.1 billion, and unusually provided a revenue growth forecast for fiscal 2028, projecting growth of 80%. Nvidia will report its third-quarter results on November 17.
Where will the money flowing out of Nvidia go?
One question to watch is where the money flowing out of Nvidia will go: will it continue flowing into other AI names or move into other sectors?
On this, Stephanie Link said that holding a bunch of names within the AI sector does not reduce AI concentration or theme risk. Selling some Nvidia to buy AMD does not change AI exposure; beta to sentiment around the theme will remain high.
So how should investors decide which stocks to sell? Stephanie Link advised investors to weigh the positions of their AI stocks in their portfolios one by one. If a stock already accounts for more than 6% or 7% of a portfolio, it may be time to consider trimming the position and locking in gains, “because if you don’t, history tells us the market will often take those gains away from you.” Stephanie Link also advised investors to start looking for companies that “AI will make better”—beneficiaries that can improve what they do, rather than companies that must keep pouring huge sums into capital expenditures.
Fortunately, so far the problem has been confined to Nvidia and has not spread across the entire AI sector.
But Stephanie Link believes that if Nvidia continues to weaken, and the AI revolution really does rely on Nvidia for power, the current difficulties could drag the entire AI trade down with it.
The AI sector is facing several tests. In addition to the Nvidia turmoil, there are rising interest rates and Anthropic's IPO.
Market expectations of a Fed rate hike in December are increasingly aligned. Some investors even believe the Fed will raise rates by 50 basis points in December. However, Stephanie Link believes the Fed has consistently signaled a 25-basis-point hike. Even if it raises rates by 25 basis points in December, the market can still move higher because that is already the baseline expectation for most people; anything beyond it would cause a problem. Meanwhile, this earnings season has shown that companies are performing strongly, and there is no reason to think that will not continue in the fourth quarter and next year.
Another key factor shaping the AI sector's outlook is bonds.
Goldman Sachs data shows that global debt issuance related to artificial intelligence has totaled nearly $600 billion so far this year, including debt issued by hyperscalers, data centers, project financings, and other AI-related borrowers. About $400 billion of that is in the US investment-grade debt market, accounting for more than a fifth of total investment-grade bond supply and bringing AI-related bonds to around 12% of the Bloomberg US Corporate Bond Index.
Howard Marks, co-founder and co-chairman of Oaktree Capital, said that AI-related debt issuance is clearly one of the major developments in capital markets this year. Artificial intelligence may require an average of $1 trillion in new capital annually for some time, with hundreds of billions of dollars potentially continuing to be raised through debt issuance each year. Since expanding capacity and developing new products are urgent priorities for AI companies, they may not slow their AI investments simply because interest rates could be higher than expected. This means they must become “takers” of financing, even when financing is scarce and costs more.
In the past, the high-margin, non-AI businesses of big tech companies generated substantial free cash flow, leaving them debt-free, cash-rich, and highly rated. That is now changing: these companies are drawing down their cash reserves and current cash flow, and borrowing more.
For now, their strong investment-grade ratings allow them to finance AI expansion easily. But as this process unfolds, it is worth considering whether their credit ratings will change. Meanwhile, the market often sees loans and related purchases between chipmakers, major AI companies, data center builders, and others. It remains unclear whether these transactions are conducted at arm’s length or whether suppliers are subsidizing buyers to support demand and protect market share for their products.
Howard Marks therefore said that AI lending is entering a new era, characterized by debt concentrated in one industry, rapidly changing industry fundamentals, and heavy reliance on future sales to calculate revenue. Lenders must remain vigilant about the creditworthiness of the borrowers they support and the structures and terms under which they do so.
Meanwhile, the anticipated IPO of AI leader Anthropic is also expected to divert some market funds. According to the announcement, Anthropic will hold its IPO around November 19. The company announced plans to offer 825 million shares in the upcoming IPO, priced at $70 to $78 per share. The offering is expected to raise up to $64.4 billion for Anthropic.$NVDA