Square
Following
Hot
News
Notifications
Profile

ToTheYUE

vip
Officer com.
Market AnalystMemecoin Hunter
114
Following
34
Followers
974
Liked
#BTCETFOutflowsContinue 🔎

Outflows from Bitcoin ETFs have raised the question: is institutional capital losing confidence in Bitcoin? U.S. spot Bitcoin ETFs saw a net outflow of approximately $870 million over the course of the week, as weak institutional demand and macroeconomic uncertainty intensified selling pressure.

This development is particularly noteworthy because spot Bitcoin ETFs have become one of the primary channels through which traditional financial institutions, asset managers, and professional investors gain exposure to Bitcoin. However, a crucial distinction must be made:
User_any
#BTCETFOutflowsContinue 🔎

Outflows from Bitcoin ETFs have raised the question: is institutional capital losing confidence in Bitcoin? U.S. spot Bitcoin ETFs saw a net outflow of approximately $870 million over the course of the week, as weak institutional demand and macroeconomic uncertainty intensified selling pressure.

This development is particularly noteworthy because spot Bitcoin ETFs have become one of the primary channels through which traditional financial institutions, asset managers, and professional investors gain exposure to Bitcoin. However, a crucial distinction must be made: an ETF outflow does not automatically mean that institutions are abandoning Bitcoin; rather, it indicates a net exit of capital from these specific investment vehicles during the period in question.

What is the answer to the $870 million question?

Between November 2 and November 5, U.S. spot Bitcoin ETFs experienced a cumulative net outflow of approximately $869.8 million. The daily breakdown is as follows: -$398.6 million on November 2, -$115.6 million on November 3, +$74.6 million on November 4, and -$430.2 million on November 5.

The most significant detail is that the market saw substantial outflows on both November 2 and November 5, with only one positive day in between—a clear sign that institutional demand is under significant pressure.

There is an update, however. Data from November 6 points to another major outflow; one tracker reported an exit of approximately $411.9 million, with reports from some funds still pending. Other summaries place the total weekly outflow at around $1.28 billion. In other words, the $870 million figure represents the situation from November 2–5, not the final weekly total.

Why are investors withdrawing their funds?

There is no single explanation; at least five factors stand out.

The first is the outlook for Federal Reserve interest rates. The October employment report, which came in above expectations—with 165,000 new jobs added against a forecast of 65,000, and the unemployment rate falling to 4.1%—has altered the outlook for monetary policy. This has dampened expectations for near-term easing. If interest rates remain higher for longer, financing costs rise, risk appetite diminishes, dollar-denominated assets become more attractive, speculative investments face pressure, and portfolio managers may reduce their exposure to volatile assets. While this relationship is not strictly mechanical, the direction is significant.

Secondly, institutional investors are becoming more selective. While ETFs provide traditional investors with easy access, institutions are under no obligation to hold Bitcoin indefinitely. They make adjustments based on portfolio risk limits, volatility, macroeconomic expectations, investment mandates, liquidity requirements, and relative performance compared to stocks, bonds, and commodities. Even if their long-term outlook remains positive, they may trim their positions when volatility spikes.

Thirdly, technology stocks and crypto are being sold off in tandem. On November 5, as Bitcoin fell by approximately 5.6%, the Nasdaq dropped 5.5%, with the semiconductor index experiencing an even sharper decline. Institutions increasingly view Bitcoin as part of a broader portfolio of risky assets; consequently, when a sell-off hits tech stocks, both leveraged investors and portfolio managers may also reduce their crypto holdings.

Fourthly, leveraged positions exacerbate volatility. During the sell-off on November 5–6, approximately $880 million worth of leveraged crypto positions were liquidated within 24 hours—the vast majority of which were long positions. As the price falls, long positions approach liquidation; the exchange triggers an automatic closure, the resulting forced sale increases downward pressure, and the lower price, in turn, sparks further liquidations. This "liquidation spiral" can cause Bitcoin’s price to drop much more rapidly than it would through spot market selling alone.

A fifth factor is political and regulatory uncertainty. Ambiguity surrounding cryptocurrency regulation, taxation, exchange oversight, and the future treatment of digital assets weighs on investor confidence—though this is not the sole explanation.

Does the most critical piece of the puzzle lie with BlackRock?

Data from November 6 revealed a significant outflow from one major fund in particular: BlackRock’s fund saw an outflow of $403 million, while Fidelity’s fund recorded an inflow of $42.8 million; meanwhile, Bitwise, ARK, and Grayscale saw outflows of $20.5 million, $20.1 million, and $11.1 million, respectively. These figures were initially based on incomplete fund reports and remained subject to further revision.

A key observation is the divergence among the largest funds—while one experienced a substantial outflow, another recorded an inflow. This suggests that investors are not abandoning all Bitcoin-related products simultaneously; rather, they may be reallocating capital between funds or adjusting their holdings to meet specific portfolio requirements.

Since its launch in January 2024, BlackRock’s fund has attracted significant cumulative net inflows, making a sustained outflow from it far more noteworthy than a one-off withdrawal from a smaller fund. However, a single session—or even two—does not constitute proof of a structural shift. What truly matters is whether this trend persists over several weeks and whether total assets under management decline in tandem with these net outflows.

Does an ETF outflow actually mean a sale of Bitcoin?

This is one of the most critical technical questions. Spot Bitcoin ETFs generally hold Bitcoin directly. When investors redeem their ETF shares—resulting in a net outflow from the fund—the fund’s creation and redemption mechanism can lead to the sale of Bitcoin or a reduction in its underlying holdings, depending on the product's settlement structure. Consequently, sustained net outflows can become a source of selling pressure in the Bitcoin market.

However, ETF flow data does not capture all institutional activity. Institutions may purchase Bitcoin directly from exchanges, corporations might acquire it for their treasuries, investors may hold it through private funds, positions can be taken via derivatives, and capital may shift between different types of products. While an ETF outflow is a significant indicator of demand, it does not provide a complete measure of institutional Bitcoin ownership.

What does the price tell us, and what do the three scenarios suggest?

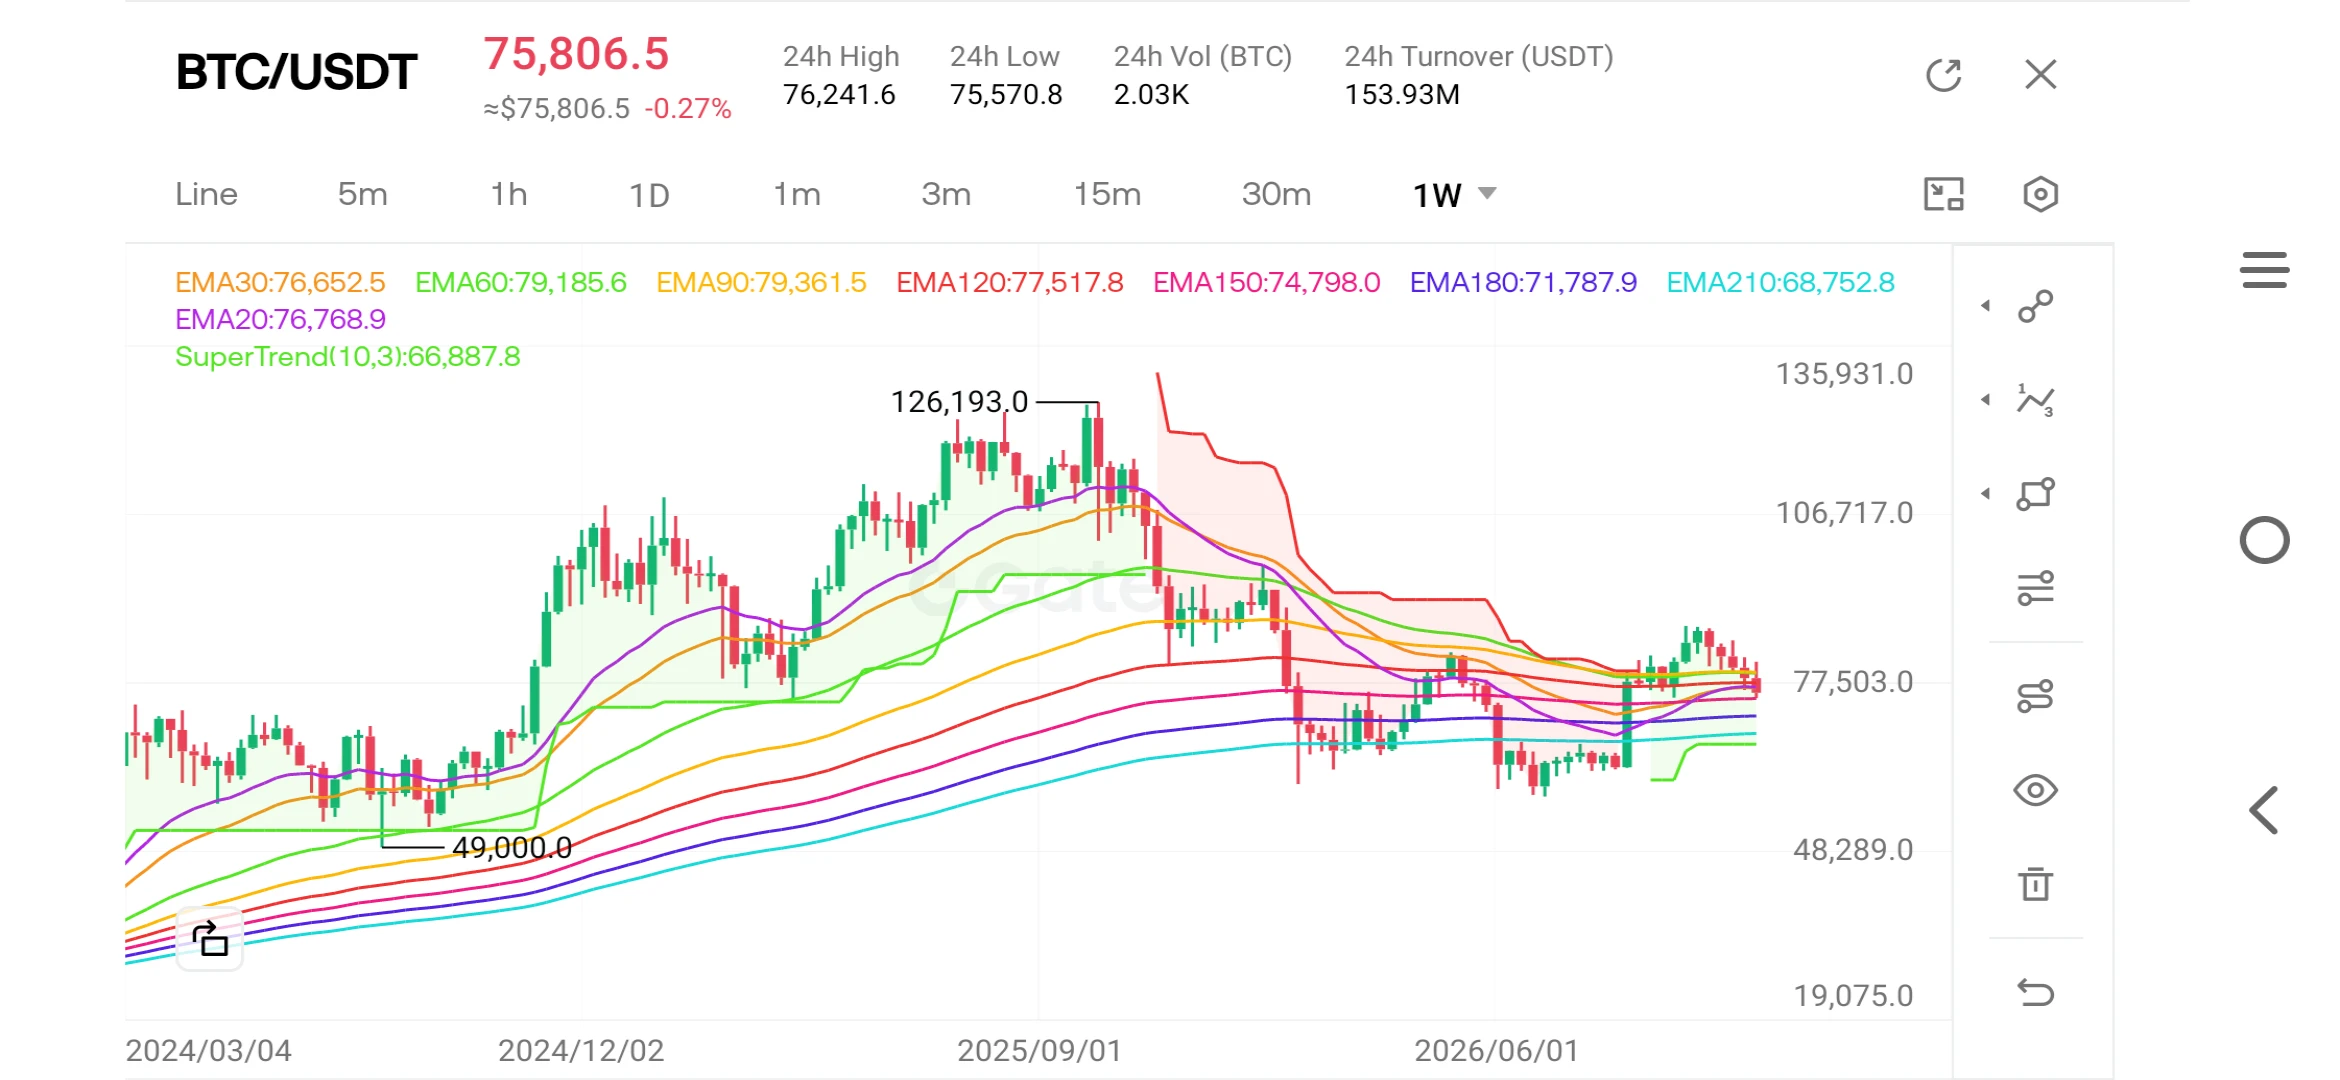
ETF outflows have coincided with a deterioration in the price structure. On November 5, Bitcoin fell sharply toward $76,000; on November 6, it briefly dipped below $75,000 before recovering to approximately $75,800. This represents a notable decline from the level of around $80,700 seen earlier this week.

Key reference levels are as follows: $80,000–$81,000 as immediate resistance; $77,000–$78,000 as recovery resistance; $75,000–$76,000 as significant near-term support; $73,000, which aligns roughly with the 200-day moving average; and $71,000–$72,000 as a potential zone to watch on the downside. These are not guaranteed support or resistance levels, but rather reference points. A sustainable recovery requires four developments: Bitcoin reclaiming the $78,000–$80,000 range; consistent positive net ETF inflows over several sessions; a reduction in derivatives leverage and forced liquidations; and an improvement in global liquidity alongside a more supportive interest rate outlook. If Bitcoin rises while ETF outflows persist, the recovery would be less convincing, as it would imply that institutional demand in the spot market remains weak. Conversely, if ETF inflows return while the price trades sideways, it could signal an improvement in underlying demand.

Ethereum is also under pressure, with ETF outflows totaling approximately $271.9 million between November 2 and 5. Combined, Bitcoin and Ethereum have seen outflows approaching $1.14 billion. This suggests that the pressure may reflect a broader decline in demand for digital assets, rather than being isolated to a single product. However, Bitcoin and Ethereum possess distinct market structures and investment narratives: Bitcoin is primarily viewed as a scarce digital monetary asset, whereas Ethereum derives value from network activity, decentralized finance (DeFi), the staking economy, and its smart contract infrastructure.

Three scenarios emerge. In the first, institutional demand returns, ETFs see sustained net inflows, Federal Reserve expectations become supportive, bond yields stabilize, and Bitcoin reclaims key resistance levels—potentially paving the way for a recovery toward the $80,000–$85,000 range. In the second scenario—a prolonged consolidation—outflows gradually taper off but do not reverse; Bitcoin holds the $73,000–$76,000 range, institutions remain cautious, and macro uncertainty persists, likely resulting in volatile, sideways price action between support and resistance levels. In the third scenario, institutional selling intensifies, outflows persist for several weeks, Bitcoin breaks through major support levels, liquidations accelerate, the US dollar strengthens further, yields remain high, and the $70,000 level becomes a significant psychological benchmark.

For now, it is prudent to lean toward a more cautious stance. ETF outflows, declining prices, liquidations in the derivatives market, and uncertainty surrounding the Federal Reserve are creating a negative environment in the short term. However, a single week of negative ETF flows does not invalidate the long-term thesis for Bitcoin.

Key indicators to monitor include Federal Reserve interest rates, the US Dollar Index (DXY), 2-year and 10-year Treasury yields, core inflation, and the multi-week trend in ETF flows. Price alone does not tell the whole story; it must be interpreted alongside the underlying institutional flows and liquidity.

This content is for informational purposes only and does not constitute investment advice.

#GateSquareTradingChallenge #WCTCS9 #ShareWeekly

$BTC ‌$ETH ‌
repost-content-media
Why has the Ahr999 dropped below 0.45, and what does this signify?

As Bitcoin trades within the $75,000–$76,000 range, the Ahr999 indicator has fallen below the 0.45 threshold to approximately 0.43—a level historically identified as a "buy-the-dip" zone. It has been confirmed that previous instances where the indicator dipped below 0.45 coincided with the market bottoms seen in late 2018, early 2020, and the 2022 bear market. Furthermore, it is noted that Bitcoin is currently attempting to defend the $75,000 support level, with the market’s focus fixed on the U.S. Consumer Price Index (CPI) d
User_any
Why has the Ahr999 dropped below 0.45, and what does this signify?

As Bitcoin trades within the $75,000–$76,000 range, the Ahr999 indicator has fallen below the 0.45 threshold to approximately 0.43—a level historically identified as a "buy-the-dip" zone. It has been confirmed that previous instances where the indicator dipped below 0.45 coincided with the market bottoms seen in late 2018, early 2020, and the 2022 bear market. Furthermore, it is noted that Bitcoin is currently attempting to defend the $75,000 support level, with the market’s focus fixed on the U.S. Consumer Price Index (CPI) data due this Tuesday.

What does this "silent alarm" tell us?

In the crypto world, every price movement is discussed, but some indicators only make a real impact when they cross specific thresholds. The Ahr999 is currently at such a juncture: as Bitcoin struggles to hold the $75,000–$76,000 range, the indicator has slipped below the 0.45 mark to roughly 0.43. So, what does this figure measure? The Ahr999 is a valuation tool that combines Bitcoin’s current price, its 200-day moving average cost, and a long-term growth valuation model to answer the question: is Bitcoin currently cheap or expensive from a historical perspective?

To simplify the logic: when the indicator is above 1, Bitcoin is considered to be trading above its long-term average cost and growth trend—placing it in a "normal" or "expensive" zone. A reading below 1 signals that the asset is "cheap," while a level below 0.45 represents a statistical range where, historically, those who made purchases have fared well over the long term. At the current juncture, the price has fallen significantly below both the average cost and the valuation model.

What one should monitor is how long the indicator remains in this zone. A one-day dip could merely be "noise"; however, sustained presence in this area serves as a stronger statistical signal that the market has entered a bottoming-out process.

What do the three "red circles" in history tell us?

The most revealing aspect of this indicator lies in its history. There have been only a few instances where it dropped below the 0.45 line: late 2018, early 2020, and the bear market bottom of 2022. In each of those periods, the market sentiment was identical—perceived as a bottomless pit, an endless decline, accompanied by a pervasive pessimism that "this time is different." Yet, looking back from today, all these instances proved to be long-term buying opportunities.

The cause-and-effect relationship here is crucial; this indicator is not a magical prophecy—it is an average. A price can only fall this far below its long-term cost during a severe wave of selling—in other words, a reading below 0.45 captures moments when panic selling has driven prices down to bargain levels. This is precisely where the historical advantage arises: the moments of peak fear have historically been the moments when disciplined investors could breathe most easily.

However, one must remain balanced; past performance is no guarantee of future results. While the outcome was favorable in those three instances, it does not prove that this fourth instance will conclude the same way. Statistics offer probabilities, not guarantees. One must also consider the counter-scenario: if macroeconomic conditions deteriorate, what is currently a "cheap" zone could become even cheaper.

The indicator says it’s cheap—so why is the market still on edge?

Here lies the core contradiction: while the valuation tool points to a historical low, the market itself remains in a state of fear. The reason for this is hidden in a layer the indicator cannot see. The Ahr999 metric compares current prices to the past, but it fails to account for interest rates, the dollar, or liquidity conditions. Yet, these are precisely the variables dominating the agenda right now: there is a strong probability of a Federal Reserve rate hike in December, bond yields are high, the dollar index is hovering near its annual peak, and institutional Bitcoin funds saw outflows exceeding a billion dollars last week.

This duality should be interpreted as follows: the price is "cheap" from a valuation standpoint, but it is facing headwinds in terms of liquidity. The signal of "cheapness" reflects a long-term perspective, while liquidity pressure is a short-term reality. When these two forces clash, it is not at all surprising for the price to remain in the "cheap" zone for an extended period—or even to test lower levels within that range. Indeed, the $75,000 support level has been tested several times this week and is currently holding; if it fails, the next potential levels to watch are $73,000 and the $70,000–$72,000 range.

The goal isn't to predict which of these two worlds will "win," but rather to remain aware of both. Long-term valuation and short-term liquidity can point in opposite directions during the same week; what distinguishes a professional investor is the ability to hold both perspectives simultaneously.

Will Tuesday’s CPI data determine the fate of this range?

The Ahr999 metric currently sits at 0.43—but what could push this figure higher or lower? In the short term, the answer is clear: the U.S. Consumer Price Index (CPI) data for October, set to be released on Tuesday. Economists expect annual inflation to rise from 3.7% to approximately 3.9%. If the data confirms this expectation, a Federal Reserve interest rate hike in December would become all but certain; bond yields and the dollar would likely climb, while risk appetite would decline. In such a scenario, Bitcoin—already in an "inexpensive" zone—could potentially become even cheaper.

Conversely, if inflation figures come in surprisingly favorable, the outlook shifts: expectations for a rate hike weaken, concerns regarding liquidity subside, and suppressed risk appetite resurfaces. The fact that the "fear index" is at an extreme level suggests that market sentiment is currently priced in a one-sided manner; in such periods, a positive surprise can trigger a sharp, counter-trend reaction. In other words, a return to a level above 0.45 for the indicator is most likely to be triggered by this specific data release.

The resulting watchlist is clear: the CPI data; subsequent inflation and employment figures leading up to the Fed’s December decision; Bitcoin’s behavior as it approaches the $75,000 range; and the direction of institutional fund flows. Together, these four factors will gradually reveal whether the current reading of 0.43 on the indicator represents a definitive bottom or merely a temporary pause.

What do the two sides of the "buy-the-dip" argument have to say?

Let’s be honest: the term "buy-the-dip" is used in two distinct ways on social media. For some, it serves as a call to action—a claim that a historic opportunity has arrived. For others, it serves as a cautionary note—a reminder that indicators are backward-looking and cannot predict the future. Both perspectives hold some truth, which is why it is worth considering both sides of the debate. The bull camp’s trump card is statistics: historically, readings below 0.45 have marked bottom reversals three times. The indicator currently sits well below the 200-day cost basis, and the prevailing climate of fear suggests that capitulation has set in—which, in turn, strengthens the position of long-term buyers. The bear camp, meanwhile, points to the broader context: the interest-rate-hike cycle is ongoing, institutional capital is flowing out, and—crucially—past bottoms did not result in immediate rebounds; rather, markets lingered in these zones for weeks or even months. In short, while an indicator may signal that an asset is "cheap," it cannot predict the timing of a turnaround.

The sound conclusion is this: this zone is not a signal to buy, but an invitation to conduct further research. The indicator suggests that the current price is historically low, but it makes no promise that the price will rise tomorrow. Confusing the two is the costliest conceptual error one can make in this market.

What is the lesson for the individual investor?

Taking the full picture into account, a long-term valuation indicator has reached a level of "cheapness" not seen in years, while short-term macroeconomic conditions continue to present a stiff headwind. Navigating the tension between these two realities is the true test for the individual investor. In such periods, the two most common mistakes are two sides of the same coin: either ignoring the indicator and exiting in a panic, or treating the indicator as gospel and committing all one’s capital at once in hopes of catching the bottom. Both represent instances where emotion takes precedence over data.

A sound approach lies somewhere in between—and should be part of a well-defined plan. An investor with a long-term perspective views such zones not as a single moment for entry, but as a time frame; they divide their capital, adjust their position size according to liquidity conditions, and incorporate the data calendar—such as Tuesday’s CPI release and the Fed’s December decision—into their roadmap. Furthermore, they do not base decisions on a single indicator; rather, they analyze valuation tools, on-chain data, fund flows, and the macro calendar in tandem, which helps keep their "compass" accurate.

Most importantly, when a given indicator sits at, say, 0.43, any quick, off-the-cuff commentary circulating in the market is not more valuable than your own well-laid plan. By definition, "bottom" zones are areas where few find it easy to buy; maintaining discipline while in these zones is far more profitable than making the most accurate prediction.

This content is for informational purposes only and does not constitute investment advice.

$BTC ‌#Ahr999EntersBottomBuyingZone
#GateSquareTradingChallenge #WCTCS9 #ShareWeekly #BTCETFOutflowsContinue
repost-content-media
Gate Launchpool will launch the #386: ValueX (VLX) project. Stake BTC, ETH, or VLX to earn a share of 454,546 VLX tokens at no cost. Airdrop rewards are distributed every hour.

Learn more 👉 https://www.gate.com/en/announcements/article/102656

👉https://www.gate.com/share/act/2441e7f5

#StakeOnLaunchpoolToShare450KVLX

Do your own research 🔎 Not financial advice ✔️

$BTC $ETH $VLX
User_any
Gate Launchpool will launch the #386: ValueX (VLX) project. Stake BTC, ETH, or VLX to earn a share of 454,546 VLX tokens at no cost. Airdrop rewards are distributed every hour.

Learn more 👉 https://www.gate.com/en/announcements/article/102656

👉https://www.gate.com/share/act/2441e7f5

#StakeOnLaunchpoolToShare450KVLX

Do your own research 🔎 Not financial advice ✔️

$BTC $ETH $VLX
repost-content-media
VLX+0.00%
BTC-0.67%
ETH-1.26%
#BTCETFOutflowsContinue

During the week of November 2–6, U.S. spot Bitcoin ETFs recorded a total net outflow of $1.28 billion—the worst weekly performance since the end of June. Fidelity’s fund was the only major fund to end the week in positive territory, with a net inflow of approximately $93 million, while BlackRock’s fund alone accounted for $1.21 billion in outflows. The aggregate of all funds excluding IBIT also finished the week in the red, pushing cumulative year-to-date fund flows into slightly negative territory. This shift occurred alongside Bitcoin’s price action hovering around
User_any
#BTCETFOutflowsContinue

During the week of November 2–6, U.S. spot Bitcoin ETFs recorded a total net outflow of $1.28 billion—the worst weekly performance since the end of June. Fidelity’s fund was the only major fund to end the week in positive territory, with a net inflow of approximately $93 million, while BlackRock’s fund alone accounted for $1.21 billion in outflows. The aggregate of all funds excluding IBIT also finished the week in the red, pushing cumulative year-to-date fund flows into slightly negative territory. This shift occurred alongside Bitcoin’s price action hovering around the $75,000 mark.

The week’s tally: Where did institutional capital flow?

In the crypto market, the sentiment of retail investors can be gauged via social media, while that of institutional capital is reflected in ETF flow data. The figures for the week of November 2–6 are stark: U.S. spot Bitcoin ETFs saw a net outflow of $1.28 billion—a weekly loss unseen in nearly five months. The fact that outflows occurred on four out of the five days suggests this was not merely a one-day reaction, but rather a risk-reduction decision that played out over the entire week.

An interesting aspect of this data lies in its distribution; Fidelity’s fund ended the week in the green—even including Wednesday, the only day of the week that saw positive inflows. Conversely, BlackRock’s massive fund recorded outflows every single day, accounting for nearly the entire weekly total. While it is accurate to say that institutional capital is exiting, that statement is incomplete. In reality, institutional capital is undergoing a repositioning—a process that varies depending on the specific fund manager. The value of monitoring this data lies in the fact that ETF flows represent the cleanest indicator of institutional demand for crypto; unlike sentiment-driven commentary, these figures reflect the aggregate of actual, multi-million-dollar investment decisions. And right now, that aggregate suggests a cautious stance.

Why is this major fund bleeding capital?

IBIT is more than just a fund—it is an industry icon. With over $60 billion in total assets and cumulative inflows exceeding $65 billion, this product alone accounts for more than half of the U.S. spot Bitcoin ETF market. Consequently, a $1.21 billion weekly outflow from IBIT is, in numerical terms, the movement of a single fund, but in psychological terms, it represents a shift across the entire market.

As for why this outflow is occurring, there are several layers. First, there is the macro perspective: a sharp sell-off in tech stocks throughout the week, combined with uncertainty following the mid-term elections, has pushed portfolio managers into a "risk-off" mode. The reduction of positions by leveraged investment funds directly accounts for a portion of these outflows. Second, there is the structural aspect: while large funds generally act to dampen rather than accelerate losses, this only goes so far. The outflows recorded today are merely a dent—not a collapse—when viewed against the roughly $97 billion in total ETF assets.

The key metric to watch here is clear: the pace of outflows from IBIT. If outflows from a single fund persist for a week, it suggests a fund-specific decision; however, if the trend spreads across multiple funds and continues for several weeks, it points toward a broader, sector-wide trend. Currently, the situation leans toward the former, but the overall direction will likely become clear over the next two weeks.

What does Fidelity’s counter-move signify?

Perhaps the most significant—yet least discussed—data point of the week is that while everyone else was selling, Fidelity’s fund was buying. The fund served as the primary driver for positive inflows into the category on Wednesday; despite a sharp outflow on Thursday, it swung back to positive territory on Friday, closing the week with a net inflow of approximately $93 million. This indicates that there remains a segment of institutional buyers in the market willing to purchase Bitcoin at its current price.

There are two ways to interpret this divergence, and both must be considered. The optimistic view suggests that the decline stems from liquidity conditions rather than a lack of demand—implying that buyers return once the price reaches an attractive level, and that market bottoms are forming even before institutional inflows accelerate. The pessimistic view posits that this fund-specific activity might merely reflect the unique positioning of a single asset management firm relative to its own client base, lacking the power to shift broader industry trends; as long as IBIT continues to see inflows, the activity from this other fund is little more than a drop in the ocean.

The lesson here is that the flow of a single fund is a data point, not a trend. However, data points accumulate; if the positive momentum seen with Fidelity persists into a second or third week, it would serve as the most concrete evidence for the thesis that "smart money" is accumulating near the market bottom. If it does not persist, it will remain nothing more than an isolated, one-off event.

Why did the stock rise while funds were flowing out?

Even as the Bitcoin fund saw outflows, the stock of the firm managing it closed the day in the green, trading around $1,170–$1,180. While this might appear contradictory at first glance, it is not; the stock of an asset manager depends not only on the performance of a single crypto fund but also on the firm’s total assets under management, management fees, and overall corporate outlook. The sheer scale of a multi-billion-dollar traditional fund portfolio is enough to render the outflows from a single crypto fund negligible in terms of the firm’s stock price.

Nevertheless, this dual picture offers an important lesson for individual investors: "institutional" investors do not act as a monolithic block. Within the same firm, one team might be liquidating a fund while the company as a whole continues to grow. Outflows from a specific fund do not necessarily mean that institutions are fleeing crypto—just as a rise in a firm’s stock price does not necessarily mean that institutions are bullish on crypto. Furthermore, analysts’ technical interpretations of an asset management firm’s stock performance add another layer; while such insights can be informative, they are by no means a guarantee.

Moving forward, it is worth tracking two indicators: ETF flow data on one hand, and the stock performance of the management firms on the other. The moment both move in the same direction, it will serve as a strong signal of a genuine turning point in institutional sentiment.

What about these two market realities?

Despite the fund outflows, Bitcoin held its ground, remaining within the $75,000–$76,000 range. This demonstrates remarkable resilience; the fact that the price did not lose the $75,000 support level—even in the face of $1.28 billion in institutional outflows—suggests that these exits were part of a planned repositioning rather than a panic-driven sell-off. However, the tone of the conversation on social media—revolving around "bull traps" and downward-sloping channels—reveals that confidence among retail investors remains fragile. In technical terms, the price is still trapped within a downward channel, and a recent attempt to rally toward the 87,000 level was rejected.

The next major turning point is clear: the U.S. Consumer Price Index (CPI) data for October, due on Tuesday. Economists expect the annual inflation rate to rise from 3.7% to approximately 3.9%. A "hot" (higher-than-expected) reading would all but guarantee a Federal Reserve interest rate hike in December; in such a scenario, bond yields and the U.S. dollar would likely climb, ETF outflows could accelerate, and the 75,000 level might be tested once again. Conversely, a favorable (lower-than-expected) reading would improve liquidity expectations and potentially open the door for the return of institutional capital that has been fleeing for weeks—Fidelity’s client base, for instance, might be waiting for precisely such a moment.

In short, ETF flows next week will serve as a response to this data. If outflows remain limited, the argument that this was merely a "test of the bottom" gains strength; if outflows deepen, it suggests the beginning of a broader institutional exodus. Be prepared for either scenario—the market will inevitably choose one, and your job is to observe it unfold, not to guess the outcome.

What is the lesson for the individual investor?

When you synthesize the week’s entire narrative, a clear framework emerges: institutional flows have turned negative, yet the bulk of these outflows is concentrated in a single fund, while other institutions are buying elsewhere. Meanwhile, the price is holding its critical support level, and Tuesday’s data could rewrite the entire picture. In this context, the biggest mistake one could make is to oversimplify the entire market based on a single headline—such as "institutions are selling" or "Fidelity is buying." Every facet of the institutional mirror reflects a different angle; your job is to examine the mirror in its entirety.

For your practical approach, monitor ETF flows on a daily—rather than weekly—basis, and take special note of the share held by any major fund; outflows originating from a single fund are not the same as broad-based outflows. Track the consistency of purchases from entities like Fidelity; a trend spanning two or three weeks is far more significant than a single day’s movement. Furthermore, review your positions ahead of Tuesday’s CPI data; the sharpest declines often occur when the liquidation of leveraged positions coincides with institutional outflows during periods of high volatility—adjust your margin accordingly.

Ultimately, while institutional flows serve as a compass, you are the one holding it. The mirror does not dictate what you should buy; it merely reveals the direction of the wind. Read the wind, structure your plan accordingly, and never mistake a single data point—whether it concerns a specific fund, a particular stock, or a single day’s activity—for the entire story.

This content is for informational purposes only and does not constitute investment advice.

$BTC $ETH $BLK

#Gate股票畅聊季 #GateStockTalkSeason #ShareWeekly
repost-content-media
Why did the world raise interest rates simultaneously during the same week?

The weekly summary has been verified point by point: employment in the United States increased by 165,000, the unemployment rate fell to 4.1%, and wages rose by 0.4%. The Bank of England raised interest rates to 4.00%—its first such move in over three years—while Australia pushed its rates to 4.85%, an 18-year high. Inflation climbed to 4.0% in the Eurozone and 1.5% in Switzerland, and Sweden raised its interest rate to 2.00%. Norway kept its rate steady at 4.50% but left the door open for future adjustments; meanwhil
User_any
Why did the world raise interest rates simultaneously during the same week?

The weekly summary has been verified point by point: employment in the United States increased by 165,000, the unemployment rate fell to 4.1%, and wages rose by 0.4%. The Bank of England raised interest rates to 4.00%—its first such move in over three years—while Australia pushed its rates to 4.85%, an 18-year high. Inflation climbed to 4.0% in the Eurozone and 1.5% in Switzerland, and Sweden raised its interest rate to 2.00%. Norway kept its rate steady at 4.50% but left the door open for future adjustments; meanwhile, unemployment in Canada rose to 6.7%, and China’s manufacturing index slipped to 49.3, signaling a contraction.

Market data confirms this picture: the euro is trading against the dollar at 1.12295—well below its early-September peak of 1.17114 and hovering near a low of 1.11047. Brent crude oil is trading around $108.81, having retreated after reaching an intraday high of $111.07.

The global landscape for the week of November 2–6 can be summed up in a single sentence: monetary policy is tightening worldwide, driven by a common factor—energy-related inflation. The Bank of England has implemented its first interest rate hike in over three years, bringing the rate to 4.00%; Australia has reached an 18-year high of 4.85% with its fifth hike of the year; and Sweden has raised its rate to 2.00%—its first increase since 2023—while signaling further hikes to come. In the United States, although the Federal Reserve has kept rates unchanged, strong employment data has significantly bolstered the likelihood of a rate hike in December.

This synchronized movement is no coincidence; there is a common trigger. The conflict in the Middle East has constrained energy supplies, driving up the costs of everything from fuel to electricity bills and compelling central banks to move in the same direction. The rise in UK inflation to 3.5% in September and the surge in energy prices—which have climbed by more than 20% year-on-year in the Eurozone—are all links in the same chain. In the U.S., an employment gain of 165,000 in October, coupled with a decline in the unemployment rate, has given the Fed confidence that this monetary tightening can be carried out without damaging the broader economy.

The key question now is: where does this upward trajectory peak? The tension between the Bank of England’s warning—that this is merely the first in a long series of rate hikes—and the market’s expectation that the Fed will raise rates in December will define the primary economic narrative for the coming months.

This week’s inflation data demonstrates that the world is not experiencing a uniform inflationary trend. In the Eurozone, annual inflation has climbed from 3.8% to 4.0%—reaching a three-year high—driven by a 20.8% surge in energy costs, while core inflation has remained at 2.5%. This distinction is critical: we are witnessing a shock stemming from fuel bills, with core inflation currently showing no signs of broad-based expansion. However, analysts warn that energy costs could spill over into other sectors—from food to services—in the coming months, suggesting that "second-round effects" may be on the horizon.

Switzerland is experiencing a milder version of the same shock, with inflation rising from 1.0% to 1.5%, led by increases in transport and housing energy costs. While this level remains modest by global standards, it represents an unusually rapid pace for Switzerland—the highest reading in three years. The situation in Japan presents a different, intriguing picture: real wages have been rising for months, and the Bank of Japan has officially declared that its 2% inflation target—a goal not seen in 13 years—has been reached. While interest rate hikes are anticipated, they have yet to be implemented. We are looking at an economy on the verge of a regime shift following three decades of deflation.

The takeaway here is that rising inflation is not a monolithic story. The question of whether this fuel-driven shock will evolve into persistent, entrenched inflation will dictate the Eurozone’s policy decisions in December, the limits of Switzerland’s tolerance, and the potential onset of monetary tightening in Japan.

The dynamics of the EUR/USD exchange rate further confirm this divergence. The Euro has retreated from the 1.17 level toward 1.11 and is currently attempting to stabilize around 1.12. This reflects both the strengthening of the dollar and the expectation that, despite inflation in the eurozone, the European Central Bank will not be able to tighten policy as aggressively as the Federal Reserve. The currency pair should be interpreted not merely as a movement in exchange rates, but as a reflection of the divergence in the pace of policy tightening between the two central banks.

Two employment stories in the same week, two contrasting worlds. In the United States, employment growth tripled expectations, the unemployment rate fell, and wages accelerated—a picture of economic resilience that provides the Federal Reserve with the room to continue its tightening cycle. In Canada, meanwhile, the unemployment rate rose from 6.5% to 6.7%, employment declined for the third consecutive month, and the private sector shed tens of thousands of jobs; public sector hiring attempted, but failed, to salvage the situation. The pressure from U.S. tariffs is slowing the Canadian economy, creating a scenario that complicates the Bank of Canada’s resolve to raise interest rates at the end of October.

Norway stands somewhere in between; its central bank held interest rates steady at 4.50% while reiterating that it remains prepared to hike further if necessary. It is a cautious "wait-and-see" approach—inflation remains above the target, but a strengthening krone is doing some of the heavy lifting. This patience in Northern Europe—displayed in a country neighboring Sweden, which has opted for rate hikes—demonstrates that even within a regional wave of monetary tightening, the pace of individual nations can diverge.

The key takeaway here is that currency strength is now shaped less by inflation and more by the balance within the labor market. The U.S. dollar is gaining ground, backed by a robust labor market, while the Canadian dollar remains under pressure as unemployment rises. There is no universal rule stating that interest rate hikes automatically strengthen a currency; rather, every economy operates according to its own unique internal balance.

Data emerging from the "eastern front" this week may well represent the most significant blow to global risk appetite. China’s official manufacturing purchasing managers' index (PMI) has fallen from 50.1 in September to 49.3, slipping back into contraction territory; the component for new export orders has also dipped below 50. This is not merely a one-month fluctuation, but a broader signal: the "world’s factory" is experiencing a sharp slowdown.

The cause-and-effect chain here is global. A contraction in Chinese manufacturing weakens demand for commodities; the resulting strain spreads through Asian supply chains, putting downward pressure on the currencies of commodity-exporting nations. For the crypto market, there is an indirect yet tangible link: a growth shock originating in China dampens global risk appetite and drags down the performance of leveraged assets. The way Asian stock markets closely mirrored the sell-off in the U.S. earlier this week serves as clear evidence of this contagion.

The oil market represents the most concrete link in this chain. On the weekly chart, Brent crude is trading around $108.81, following a major rally from a low of $58.70 to a peak of $120.57. In other words, the energy shock has not ended; it has merely retreated slightly from its peak. As long as oil prices remain at these levels, inflationary pressures—and the rationale for central banks to pursue monetary tightening—will persist.

Key developments to watch include high-level diplomatic or economic engagements expected in the coming week, as well as the November data for export orders. If the index recovers to 50, the October dip could be viewed as a temporary setback; however, if it remains consistently below 49, it would signal the onset of a period marked by downward revisions to global growth forecasts.

So, what does this entire landscape mean for a crypto investor? In short: the headwinds are intensifying. Rising interest rates across three continents, a strengthening dollar, and climbing bond yields all point to a tightening of liquidity—a negative for crypto. The week’s market data bore this out: stocks were sold off, the "fear index" spiked, Bitcoin retreated from the $80,000 level toward the $75,000 range, and U.S. spot Bitcoin ETFs saw $1.28 billion in outflows—the worst weekly fund flow since June.

It is now possible to map out the financial transmission of an energy shock originating in the Middle East: oil prices rise, inflation climbs, central banks tighten policy, bond yields increase, a flight to safety begins, and—as the final link in this chain—cryptocurrencies are sold off. This week, the world watched this sequence unfold, step by step. However, there is a counter-possibility to keep in mind: if the recent decline in oil prices continues, inflation expectations could fall, potentially reversing the entire chain of events. In fact, the Bank of England’s recent, more encouraging remarks over the last 48 hours point precisely to this possibility.

Your watchlist should be shaped by this macro landscape: U.S. CPI data on Tuesday, the trajectory of energy prices in the Eurozone and the UK, Japan’s interest rate decision in December, and the Federal Reserve’s meeting on December 9th. Every major move in the crypto market will likely trace back to these events.

What is the lesson for the individual investor? Let’s synthesize the narrative of the week: we are in a period of synchronized monetary tightening—a rarity in the history of global monetary policy—triggered by an energy shock stemming from war, underpinned by a robust U.S. economy, and contrasted by weakening manufacturing in China. In this landscape, the greatest risk for an individual investor is to focus on a single wave rather than the entire sea—mistaking the decision of one central bank or a single inflation figure for the whole picture. The reality is a complex, interconnected whole playing out across dozens of economies simultaneously, and this week, that whole signaled a shift toward tightening.

Your practical strategy should consist of three layers. First, the calendar: Tuesday’s CPI release and the Federal Reserve’s decision on December 9th are the two key pillars for the coming month. Volatility tends to spike around these dates, making leveraged positions particularly vulnerable. Second, diversification: as interest rates rise, the correlation between various risk assets tends to approach one. Defensive assets—as evidenced by gold’s 5% gain this week—proved to be the only front that decoupled from the broader trend. Third, patience: throughout history, tightening cycles have always come to an end. The first signs of such an end appear in statements like the one from the Bank of England this week, suggesting that if energy prices fall, further rate hikes may not be necessary.

In short: as an individual investor—a small boat in a global tide of interest rate shifts—you cannot stop the waves, but you can adjust your vessel to navigate them. Reduce your position sizes, abandon leverage, mark your calendar, and keep liquidity on the sidelines so that, during moments of panic, you are in a position to acquire assets from those who lacked a plan.

$NAS100 $GBPUSD $EURUSD $USDJPY $BTC
#USCPIDataIncoming #USAIStocksHitHard #USNonfarmPayrolls #StockTalkSeason
#ShareWeekly
repost-content-media
The U.S. Consumer Price Index (CPI) data for October will be released on Tuesday—with economists expecting annual inflation to rise from 3.7% to approximately 3.9%—followed by the Producer Price Index (PPI) data on Friday. The Federal Reserve’s next interest rate decision is scheduled for December 9, and the market is currently pricing in a high probability of a quarter-percentage-point hike. It is also worth noting that the commentary provided by Fed officials following these data releases will be closely monitored.

Why will these two key events drive the market?

The calendar for the coming
User_any
The U.S. Consumer Price Index (CPI) data for October will be released on Tuesday—with economists expecting annual inflation to rise from 3.7% to approximately 3.9%—followed by the Producer Price Index (PPI) data on Friday. The Federal Reserve’s next interest rate decision is scheduled for December 9, and the market is currently pricing in a high probability of a quarter-percentage-point hike. It is also worth noting that the commentary provided by Fed officials following these data releases will be closely monitored.

Why will these two key events drive the market?

The calendar for the coming week revolves around two data points: the CPI on Tuesday and the PPI on Friday. Their significance stems from the current context; the Fed will seriously deliberate on an interest rate hike at its December meeting, and it will derive its final, comprehensive picture of inflation from these two reports. Market pricing is already sensitive, with a quarter-percentage-point increase heavily factored in. Such a clearly defined expectation amplifies the potential for a surprise—the market reacts not to the direction of the data itself, but to any deviation from those expectations.

Why is this so critical? Because the 165,000-job increase reported for October, combined with accelerating wage growth, has provided the Fed with assurance that the economy can withstand further tightening. Now, the focus shifts to inflation: if inflation comes in high while employment remains strong, a December rate hike becomes all but certain; conversely, if inflation proves surprisingly low, the Fed’s position weakens. In short, Tuesday’s figures represent the first half of the equation for the December decision, while Friday’s data constitutes the second half.

Your task is to review your positions in the hours leading up to these data releases. The market movement in the immediate seconds following the release of a figure is often misleading; a true assessment of the market’s direction only emerges once the details of the data—such as core inflation and service-sector components—have been fully digested.

What figures will be in play for Tuesday’s CPI (Consumer Price Index) report?

Economists generally expect annual consumer inflation to rise from 3.7% to approximately 3.9%. This remains far from the Federal Reserve’s 2% target—a level that reinforces the narrative that inflation has remained stubbornly persistent for the past three years. However, the headline figure does not tell the whole story; the real distinction lies in core inflation. The trajectory of prices, excluding food and energy, serves as the primary indicator of whether energy-related shocks have become embedded in consumer costs. As seen in this week’s data from the Eurozone, energy price hikes—stemming from developments in the Middle East—tend to ripple through utility bills, eventually spilling over into food and services. In the U.S., the key question is how far this "spillover" has progressed.

The mechanism of impact is clear: if inflation comes in higher than expected, bond yields and the U.S. dollar will likely rise, risk appetite will wane, and liquidity pressure on the crypto market will intensify—potentially exacerbating the strain already evidenced by last week’s $1.28 billion in fund outflows. Conversely, a figure below expectations would reverse this chain reaction: the probability of further interest rate hikes would diminish, the dollar would retreat, and pent-up demand—suppressed for weeks—would likely surface.

There is also a second layer to monitor: the immediate reaction from Federal Reserve officials following the data release. The direction of the market is shaped not only by the figure itself but also by how policymakers interpret that number. A hawkish tone keeps the door open for further hikes, even when data is positive; a dovish tone, meanwhile, frames poor data as merely temporary, helping to put the market at ease.

Why is the PPI, due on Friday, as significant as the CPI?

The Producer Price Index (PPI), to be released on Friday, is a data point often overlooked by most investors but closely monitored by professionals. The logic is straightforward: producers' costs are eventually passed on to consumers. Increases in the costs of raw materials, transportation, and energy first drive up prices at the factory gate; these costs then filter through to retail prices—and subsequently to the Consumer Price Index (CPI)—over the following months. In essence, the PPI serves as a precursor to inflation, offering a preview of consumer inflation in the months ahead.

The context this week is unique. With geopolitical pressures continuing to weigh on energy prices, cost-push inflation is rising more sharply on the producer side than on the consumer side; the uptick in transportation and storage costs suggests that this pass-through process is already underway. If this trend is confirmed on Friday, the thesis that "inflation has peaked and is now easing" will be significantly undermined—because today’s producer figures are tomorrow’s consumer figures.

The takeaway for you is this: while Tuesday’s CPI represents the heartbeat of the market, Friday’s PPI acts as its compass. If the CPI comes in favorable but the PPI looks poor, any optimism might be premature; however, if both come in strong (i.e., lower than expected), expectations for a December rate hike could genuinely soften, opening a window of relief for risk assets.

What will the week hold in terms of Fed officials' commentary?

Beyond the data calendar, the series of speeches scheduled throughout the week will also be instrumental in setting the market's direction. Every statement from policymakers following the CPI release should be evaluated with two questions in mind: Does the Federal Reserve perceive a lasting shift in inflation, and do they consider the conditions sufficient to justify a rate hike in December? Following this week’s employment data, it is known that several Fed members have signaled that inflation remains a concern; the data arriving on Tuesday will either sharpen or soften this tone.

The nuance here is that Fed members speak, in part, to manage market expectations. If the market has priced in a rate hike for December too aggressively, members might deliberately choose to temper that sentiment—because an overly aggressive expectation sets the stage for a sharp, counter-directional reaction once the actual data is released. Therefore, view their statements alongside the hard data as a form of "calibration" mechanism: if the market has run too far ahead, Fed members pull it back; if the market is hesitant, they nudge it forward.

Keep your monitoring process simple: after every significant statement, observe the two-way movement in bond yields. Regardless of the actual words spoken, the reaction of the bond market serves as the most honest interpretation of how the market has understood those remarks.

On the crypto front, will the $75,000 level take center stage once again?

The outlook for the crypto sector next week remains an extension of the last: Bitcoin is defending the $75,000 support zone, institutional fund flows are fragile, the "fear index" is elevated, and the vast majority of the market is awaiting an answer to a single question: will liquidity continue to tighten, or will there be a signal of easing? The data arriving on Tuesday and Friday will provide the answer.

Let’s lay both scenarios out on the table. In a "hot" inflation scenario, a rate hike in December becomes certain, the dollar and bond yields rise, the $75,000 level for Bitcoin is tested once again—and more aggressively—altcoins suffer steeper-than-average losses, and the crowded long positions in the futures market are liquidated. In a "moderate" inflation scenario, however, interest rate expectations soften, some of the risk appetite lost last week returns, and prices attempt a recovery from support zones. Neither scenario constitutes a price prediction; both serve as a map of the thresholds to watch.

Your compass consists of three key thresholds: Bitcoin’s weekly closes relative to the $75,000 level, the direction of U.S. spot fund flows between Tuesday and Friday, and the trajectory of bond yields following the data releases. If all three shift in the same direction, the trend is likely genuine; if only one shifts, it is merely "noise."

In short, the week ahead features two major data releases, five days of intense commentary, and a market braced for each event. During such weeks, the individual investor’s greatest enemy is the emotional reaction to the data release. A figure is announced, the chart spikes in a split second, and everyone suddenly feels like they’ve "missed the boat"—yet, treating data that has been on the calendar for weeks as a "surprise" is simply a sign of being unprepared. Your advantage lies in the fact that you already have the calendar in your hands.

Let your plan be defined by three points. First, keep leverage near zero on data-release days; during periods of high volatility, even the slightest adverse move can knock you out of the game. Secondly, do not focus on a single data point; instead, look at the combination of Tuesday and Friday. If the CPI (Consumer Price Index) comes in strong while the PPI (Producer Price Index) weakens—or vice versa—it sends a contradictory signal to the market, requiring patience rather than a hasty interpretation. Thirdly, everyone you encounter will have a forecast—whether on social media, television, or within the stock market—but rather than focusing on the number of forecasts, you should focus on clearly defining your own risk limits.

Ultimately, while "inflation weeks" may dictate the direction of the markets, it is an investor’s own discipline that determines their fate. The figures released on Tuesday and Friday will come and go; if your positions are structured to withstand these numbers in either direction, then regardless of the outcome, this week will work in your favor.

This content is for informational purposes only and does not constitute investment advice.

$BTC $ETH $NVDA $SPCX $NAS100
#USCPIDataIncoming #USAIStocksHitHard #USNonfarmPayrolls #StockTalkSeason
#ShareWeekly
repost-content-media
Gate has launched the "Gate Security Guardian" program—a new initiative designed to elevate account security—making it available for free to users who meet specific security criteria. This is more than just a security setting; it serves as an additional layer of protection for your account.
Perhaps the most notable feature is that, under certain conditions, users can file a compensation claim in the event of an unauthorized asset transfer. In other words, it doesn’t just alert you—it’s also designed to have your back in specific situations.
What exactly does it protect against?
There are three
User_any
Gate has launched the "Gate Security Guardian" program—a new initiative designed to elevate account security—making it available for free to users who meet specific security criteria. This is more than just a security setting; it serves as an additional layer of protection for your account.

Perhaps the most notable feature is that, under certain conditions, users can file a compensation claim in the event of an unauthorized asset transfer. In other words, it doesn’t just alert you—it’s also designed to have your back in specific situations.

What exactly does it protect against?

There are three main scenarios, all of which could potentially happen to anyone:

First: Phishing and malware. This includes scenarios such as clicking on a fraudulent link, entering your credentials on a fake website, or having your account compromised via malicious software installed on your device.

Second: Device control and remote access. This occurs when a tool infiltrates your phone, allowing transactions to be carried out without your knowledge.

Third: SIM card theft or fraudulent SIM swapping. This happens if your phone is lost, or your SIM card is stolen or reissued in your name, granting unauthorized access to your account.

For an approved incident, you may file a compensation claim for up to $200,000 in a single instance. However, there are clear exclusions: transactions initiated by you personally, transfers authorized by you under the direction of a third party, erroneous transactions, and losses resulting from market fluctuations are not covered.

How do you qualify for this protection?

There are three primary requirements:

Your account security score must be at least 80 out of 100. You must have completed KYC Level 2 identity verification. Additionally, you are expected to have fulfilled the necessary security steps, and your account must be in good standing. If you meet these requirements, you can activate the feature for free via the Gate app—by navigating to Profile > Security Center > Gate Security Guardian—or through the web interface.

Why doesn’t it become active immediately? What is the significance of the 30-day period?

Protection does not begin the moment you enable the program; instead, a 30-day security-strengthening phase commences. Throughout these 30 days, your score must remain at or above 80 without interruption.

Once this period concludes, your account status shifts to "Protection Active," and you become eligible to submit a claim. If your score drops below 80 during this phase, the protection is suspended. If you manage to raise your score back to 80 within 48 hours, the process restarts from day one. If, after 48 hours, your score remains below 80, the program is terminated; should you choose to reapply, the 30-day process will begin anew.

This detail conveys an important message: security is not a simple "on/off" button—it is a habit.

How does the compensation process work in the event of an incident?

For a claim to be considered, the incident must have occurred while your account was in the "Protection Active" status, and your score must have remained above 80 for the 30 days leading up to the incident.

Following an incident, you are required to contact the security team via the "My Protection" section within 45 days. You must also provide documentation of a formal report filed with law enforcement, as well as records of the asset transfers in question.

Should you view this as insurance?

No. Gate explicitly states that this is not an insurance product. Each claim is evaluated according to the platform’s rules, and there is no guarantee of compensation for every submission.

Therefore, you should view this not as your primary line of defense, but rather as a supplementary layer of protection. A strong password, two-factor authentication, and device security remain your first line of defense. This shield serves as an additional safety net that kicks in once you have done your part.

This content is for informational purposes only and does not constitute investment or financial advice.
#GateGuardNowAvailableForFree
repost-content-media
Could Tesla and SpaceX—two companies I follow closely—end up under the same corporate umbrella?
This has been the most discussed topic in the market in recent weeks: the possibility of a merger between these two major companies. As stock prices fluctuate, investors are focused on both potential merger scenarios and the companies' operational performance.
An announcement on October 20 brought this rumor into the realm of official consideration. It was disclosed that special committees, composed of independent board members, have been formed at both companies to evaluate a potential merger. Whil
User_any
Could Tesla and SpaceX—two companies I follow closely—end up under the same corporate umbrella?

This has been the most discussed topic in the market in recent weeks: the possibility of a merger between these two major companies. As stock prices fluctuate, investors are focused on both potential merger scenarios and the companies' operational performance.

An announcement on October 20 brought this rumor into the realm of official consideration. It was disclosed that special committees, composed of independent board members, have been formed at both companies to evaluate a potential merger. While it was suggested that a merger could be a sound idea, it was also explicitly emphasized that no terms have been agreed upon and that a deal is by no means guaranteed.

How might such a merger take place?

Market expectations suggest that a merger could be structured as a stock-for-stock exchange, with a significant portion of the voting control in the combined entity remaining with the same individual.

However, the process is complex. A merger requires shareholder approval—necessitating a specific majority—and is also subject to the consent of regulatory bodies. In other words, it is not enough for the two companies alone to desire the merger; the shareholder structure and the regulatory framework are also decisive factors.

Therefore, it is more prudent to view the merger as an option currently under evaluation, rather than as a foregone conclusion.

What do operations at Tesla indicate?

Regardless of the merger discussions, there are notable developments at Tesla. As of November 2, the company’s autonomous ride-hailing service, "Robotaxi," has launched in Fort Worth, Texas—marking its fourth city in the state, following Austin, Dallas, and Houston.

It is reported that the company plans to introduce its purpose-built "Cybercab" vehicle in Dallas later this month. Meanwhile, in Nevada, it has been disclosed that authorization has been granted for up to 5,000 vehicles to operate in Las Vegas during the first year. The key detail to monitor here is cost. Management has set a target of approximately $0.30 per kilometer, a goal that has reportedly not yet been met. This target is critical to the long-term profitability of the service.

What is the situation with SpaceX?

For SpaceX, the focus is on valuation and strategic partnerships. One firm has significantly revised its revenue forecasts for 2027 and 2028 upward and brought forward the projected break-even point for free cash flow from 2035 to 2031. It is important to note that these projections are based on model assumptions and would need to be validated by actual earnings reports.

Meanwhile, there are efforts to expand Starlink into the mobile operator space. The CEO of a major mobile carrier reiterated that there are no plans for a virtual operator agreement with the satellite company, arguing that satellite connectivity does not represent an incremental market. The fact that none of the three major U.S. carriers appear receptive to such an agreement poses a hurdle to the goal of becoming a mobile operator. There are also reports suggesting that the company is seeking alternative partnerships to pursue this objective.

Both companies saw a decline in the most recent trading session. Some have suggested that this drop may be linked to the election results following high levels of political spending during the midterm elections. However, rather than attributing it to a single factor, it would be more prudent to view it as part of broader fluctuations in market sentiment, especially since neither company has disclosed any quantitative impact on their operational results.

There is a clear divergence of opinion among analysts. While one firm raised its price target, it maintained a "neutral" stance, whereas another adopted a more constructive outlook. Another institution considers a merger by 2027 highly probable, projecting that the combined entity could reach a valuation exceeding $3 trillion. These projections represent expectations for the future and do not constitute certainties.

There are two distinct dynamics at play. The first is operational: the Robotaxi and Cybercab initiatives hold the potential to strengthen Tesla’s position in autonomous driving, while Starlink’s mobile strategy sits at the core of SpaceX’s growth narrative.

The second is structural: a potential merger would directly impact the portfolio composition and risk profile, and it remains contingent upon a multi-stage process—including regulatory approvals and shareholder votes.

Key developments to monitor include official announcements from merger committees, progress regarding the urban expansion of the Robotaxi and its cost-per-mile targets, and the partnership model Starlink adopts for its mobile operations. While rumors may spread quickly, true value is built through operations.

This content is for informational purposes only and does not constitute investment advice.

$TSLA ‌$SPCX ‌#Gate股票畅聊季 #GateStockTalkSeason
repost-content-media
TSLA+5.45%
SPCX+5.34%
  • 1
Following the midterm elections in the United States, the new political landscape triggered a rapid repricing of regulatory risk within the technology sector. As Democrats secured majorities in both the House of Representatives and the Senate, index futures plummeted during the overnight session—with the Nasdaq-100 falling by as much as 2.4% and the S&P 500 by 1.4%—driven by expectations of stricter oversight regarding artificial intelligence and data center expansion.

However, the situation reversed by morning. The Nasdaq-100 rose by approximately 1%, the S&P 500 climbed 1.8%, and the Dow re
User_any
Following the midterm elections in the United States, the new political landscape triggered a rapid repricing of regulatory risk within the technology sector. As Democrats secured majorities in both the House of Representatives and the Senate, index futures plummeted during the overnight session—with the Nasdaq-100 falling by as much as 2.4% and the S&P 500 by 1.4%—driven by expectations of stricter oversight regarding artificial intelligence and data center expansion.

However, the situation reversed by morning. The Nasdaq-100 rose by approximately 1%, the S&P 500 climbed 1.8%, and the Dow recovered by nearly 1,500 points. Rather than focusing on political uncertainty, the market shifted its attention to the structural implications of a divided government.

Why did the "AI trade" diverge?

A clear bifurcation emerged within the recovery.

Major hyperscalers rallied: Amazon, Apple, and Microsoft surged by over 6%, while Alphabet gained 4% and Meta rose 2.7%. In contrast, companies directly tied to infrastructure deployment faced pressure; Nvidia fell by approximately 2%, and next-generation cloud-sector players saw declines of up to 3.2% in futures trading, with firms like Applied Digital and Nebius experiencing similar headwinds.

In short, the market did not price AI as a monolithic package. While the platform side found support, the segment linked to infrastructure and construction faced increased scrutiny.

What does the 45% capacity risk signify?

According to an institutional assessment, Democratic victories at the state level could potentially impact approximately 45% of the planned data center capacity in the United States. Newly elected governors who support a full or conditional moratorium now hold sway over approximately 47 GW of planned capacity.

In the second quarter alone, at least 45 data center projects—with a combined value of $68 billion—faced setbacks due to local opposition. Two legislative proposals are already on the table: one that would require data centers to shoulder a larger share of grid-connection costs, and another that calls for a moratorium on data centers dedicated to artificial intelligence.

Will these laws be enacted anytime soon?

From a long-term, dialectical perspective, the initial sell-off followed by a recovery suggests a fine-tuned calibration rather than a uniform repricing of risk.

A new Congress implies increased oversight, investigations, hearings, and subpoenas. Democratic lawmakers have already signaled their intent to summon AI executives to provide sworn testimony and to scrutinize the industry’s energy consumption and its impact on consumer costs.

However, there is a structural check on sweeping legislative change. The President retains veto power, and a divided government significantly reduces the likelihood of major new legislation that could severely undermine data center development. The more immediate impact is likely to manifest through oversight and investigation rather than through statutory restrictions.

Will states actually halt these projects?

A candidate might campaign against data centers, but once in office, the realities of job creation, payroll, and property tax revenue come into play. As one analyst noted, a pause or a list of conditions often marks the beginning of negotiations, not the end of a project.

The landscape is fragmented. Texas and Georgia account for roughly one-third of all AI data center spending—and both states saw Democratic gubernatorial candidates win—yet alternative locations remain viable elsewhere. In other words, a decision in a single state does not halt the entire rollout; it merely shifts its trajectory.

What is the real variable here?

The question is not whether regulation will stop the AI rollout, but rather how the pace and cost structure of that deployment will be adjusted.

A slower and more costly expansion would weigh on growth and valuations, particularly for companies heavily reliant on infrastructure. Meanwhile, the resolution of the election itself has provided a sense of relief to the market; bonds rallied on the expectation that a divided government would limit fiscal expansion.

The key factor to watch is whether the risk of oversight from the new Congress—or the structural resilience of the AI investment cycle—will prove more decisive. In the short term, headlines regarding oversight drive price volatility, while in the medium term, costs and speed will dictate the true economic reality of the narrative.

This content is for informational purposes only and does not constitute investment advice.

#TechStocks #AIRegulation #USPolitics #Gate股票畅聊季 #GateStockTalkSeason
repost-content-media
INDEX+0.00%
SPX500+0.19%
AMZN+4.14%
AAPL+2.44%
MSFT+2.02%
$TRUMP ‌$MELANIA ‌$WLFI ‌
The Democrats securing a majority in Congress has triggered a sharp divergence in the digital asset market. While tokens associated with political figures faced intense selling pressure, mainstream crypto assets saw a recovery.

This divergence highlights that political sentiment—much like liquidity—can serve as a primary driver for certain assets.

What happened to politically-linked tokens?

Over the last 24 hours, the trend has been distinctly negative.

The official Trump-related token fell 17% to $1.33. World Liberty Financial dropped more than 7% to $0.047. A
User_any
$TRUMP ‌$MELANIA ‌$WLFI ‌
The Democrats securing a majority in Congress has triggered a sharp divergence in the digital asset market. While tokens associated with political figures faced intense selling pressure, mainstream crypto assets saw a recovery.

This divergence highlights that political sentiment—much like liquidity—can serve as a primary driver for certain assets.

What happened to politically-linked tokens?

Over the last 24 hours, the trend has been distinctly negative.

The official Trump-related token fell 17% to $1.33. World Liberty Financial dropped more than 7% to $0.047. A token associated with the First Lady declined by approximately 13% to around $0.066. The total market capitalization of the political memecoin sector shrank by over 16% to $477 million, while trading volume surged by 123% to $437 million.

A decline in value accompanied by an increase in volume points to a sell-side trend.

Why did the broader market move in the opposite direction?

During the same period, mainstream assets rallied. Bitcoin rose by approximately 4% to $80,500, and Ethereum climbed 6% to $2,433. The total crypto market capitalization increased by 3.4% to $2.69 trillion.

In short, while politically-linked tokens reacted to the shift in the balance of power in Washington, Bitcoin and Ethereum responded to macroeconomic factors and institutional capital flows. It was a day marked by a breakdown in correlation.

What are the implications regarding financial exposure and regulation? One of the topics that has emerged following the election concerns financial exposure and congressional oversight.

According to research by a news agency, it is alleged that approximately $2.3 billion in earnings had been generated from family-linked crypto ventures as of the end of April. Reports indicate that a 2025 financial disclosure lists over $1 billion in crypto-related income, alongside roughly $635 million in royalties from "memecoins."

It is reported that the incoming chair of the House Oversight Committee has signaled a potential investigation, advising relevant parties to "retain counsel." The scope of inquiry may include matters such as a $500 million investment from the Emirates into "World Liberty Financial" and the potential pardon of a cryptocurrency exchange founder. These remain in the realm of allegations and proposed actions; the specific trajectory of any investigative process is not yet clear.

What does this signify?

From a long-term, dialectical perspective, the inherent fragility of assets that derive their value from political proximity becomes apparent. Investors in such tokens are not betting on a specific technology or a business capable of generating cash flow; rather, they are betting on the continued popularity and influence of a political figure. Should the political landscape shift, the demand structure can collapse rapidly.

This is why structural differentiation is significant. As core assets mature, the correlation between political narratives and their valuation may weaken; conversely, for narrative-driven tokens, the political narrative may remain the sole driver of value.

What should be monitored moving forward?

The subpoena power held by Congress allows for the formal request of documents and testimony from private entities. This could lead to greater scrutiny of the financial structures underpinning these ventures. The focus may extend beyond the tokens themselves to a broader network of business and political relationships.

The key variable here is whether this regulatory and legal pressure will have a lasting impact on the sustainability of these ventures, or whether it will remain a cyclical phenomenon tied to the current political configuration. For the broader crypto market, the outcome will serve as a test of how effectively the industry can decouple its core technological and financial infrastructure from assets driven by politically charged narratives.

This content is for informational purposes only and does not constitute investment advice.

#DemocratsWinBothChambers
#WCTCS9
#GateSquareTradingChallenge
repost-content-media
TRUMP-0.95%
MELANIA-2.90%
WLFI-0.16%
BTC-0.67%
ETH-1.26%
#IntelBeatsEarningsButStockPlunges
Intel Beats Earnings But Stock Plunges - Why Beat Was Not Enough
Intel posted a clean beat in Q3, yet the stock collapsed right after, a classic case of strong report versus stretched price.
The Beat
Q3 revenue came at 13.7 billion USD, up 3% year over year, ahead of Street view near 13.17 billion USD. Adjusted EPS was 0.23 USD, well above consensus near 0.02 USD, and far above Zacks view of 22 cents. GAAP net income swung to 4.1 billion USD profit versus a 16.6 billion USD loss a year ago.
On the print, shares first jumped 6% to 10% in after hours, trading
discovery
#IntelBeatsEarningsButStockPlunges
Intel Beats Earnings But Stock Plunges - Why Beat Was Not Enough

Intel posted a clean beat in Q3, yet the stock collapsed right after, a classic case of strong report versus stretched price.

The Beat

Q3 revenue came at 13.7 billion USD, up 3% year over year, ahead of Street view near 13.17 billion USD. Adjusted EPS was 0.23 USD, well above consensus near 0.02 USD, and far above Zacks view of 22 cents. GAAP net income swung to 4.1 billion USD profit versus a 16.6 billion USD loss a year ago.

On the print, shares first jumped 6% to 10% in after hours, trading in a 37 to 41.38 USD band, near a two year high. The year to date move before the drop was 85% to 90%, far ahead of broad market and ahead of many chip peers. Bernstein lifted target to 35 USD from 21 USD while keeping Market Perform, a sign that even bulls saw upside as limited.

The Plunge

Current board shows a sharp reversal. Price as of Oct 30 regular close is 65.76 USD, open 68.36 USD, high 68.77 USD, low 63.20 USD, prior close 92.07 USD, daily change -26.31 USD, -28.57%. Five day return is -24.38%, one month -44.89%, six month -33.99%, year to date still +78.21% but well off top.

Live spot prints earlier in the run were 90.64 USD +1.18%, 90.72 USD -0.08%, 90.51 USD +0.46%, 90.45 USD +0.4%, 97.71 USD +0.17%, showing how crowded the top became before the wash.

Why did a beat turn into a plunge?
1. Quality of beat. Growth of 3% is thin. The beat came from lower restructuring cost and tight cost control, not from AI chip demand surge. For a sector where Cloud grew over 100% in same quarter for peers, 3% feels light. 2. Valuation. After a 90% year to date rally, market needed more than a cost driven beat. When prior close hit 92.07 USD, many holders chose to lock profit. The drop to 63.20 USD low shows forced exit of late longs. 3. Cash flow and spend. Foundry build requires heavy capex. Free cash flow pressure and low margin in foundry unit kept fear alive. Trailing EPS still near -0.0589, so profit is not yet stable. 4. Peer mood. When a Cloud unit posted 103% growth yet parent stock fell near 10% and lost over 480 billion USD in market cap in one day, risk off spread. Intel, with slower top line, was hit harder.
What to Watch Now

For traders, levels are clear. Support: 63.20 USD low, then 65.76 USD current, then 68.36 USD open. Break of 63.20 USD with high volume opens path toward 58 to 60 USD. Resistance: 68.77 USD high, then 90.51 to 90.72 USD prior spot cluster, then 92.07 USD prior close. To reclaim bullish trend, price must close above 90.64 USD with strong volume.

Long term story is still alive - return to profit, foundry orders, US government backing, AI deals worth 15 billion USD cited in recent reports. But market wants proof of core growth above single digits and margin lift in foundry before paying a 90% rally again.

Until then, this stays a beat and fade market. Buyers need daily close above prior high cluster, sellers control while price stays below 68.77 USD.

#IntelBeatsEarningsButStockPlunges #ShareWeekly
repost-content-media
INTC+3.56%
  • 1
SOL Technical Outlook: Solana Drops Below Major EMAs as Selling Pressure Pushes Price Toward $92 Support
Solana is currently trading around $95.07, facing renewed selling pressure after failing to sustain its recovery toward the $98.50–$100 resistance zone. SOL has pulled back from its recent highs and is now trading below all four major EMAs, indicating that short-term momentum has shifted in favor of sellers.
The immediate support area is around $92.94, while RSI has dropped to 29.64, showing that SOL is approaching oversold territory. Buyers need to reclaim the $97.06–$100.06 resistance reg
asiftahsin
SOL Technical Outlook: Solana Drops Below Major EMAs as Selling Pressure Pushes Price Toward $92 Support

Solana is currently trading around $95.07, facing renewed selling pressure after failing to sustain its recovery toward the $98.50–$100 resistance zone. SOL has pulled back from its recent highs and is now trading below all four major EMAs, indicating that short-term momentum has shifted in favor of sellers.

The immediate support area is around $92.94, while RSI has dropped to 29.64, showing that SOL is approaching oversold territory. Buyers need to reclaim the $97.06–$100.06 resistance region to improve the outlook, while losing $92.94 could expose lower support zones.

EMA Structure

* 20 EMA: $102.11
* 50 EMA: $104.18
* 100 EMA: $100.06
* 200 EMA: $98.23

SOL is trading below all four EMAs, indicating a bearish short-term structure.

The 200 EMA near $98.23 is the first important moving-average resistance. Above that, the $100.06–$102.11 region represents another major barrier, followed by the 50 EMA near $104.18.

A sustained recovery above the $100–$104 EMA cluster would be needed to restore stronger bullish momentum.

Fibonacci Levels

Based on your chart:

* 0: $61.72
* 0.236: $106.02
* 0.382: $134.88
* 0.5: $157.48
* 0.618: $180.09
* 0.786: $212.26
* 1.0: $253.25

SOL is trading below the 0.236 Fibonacci region near $106.02, showing that the broader recovery still faces significant resistance.

The first objective for buyers is to reclaim the nearby EMA cluster. A sustained move above $106.02 would provide a stronger recovery signal and potentially open the path toward higher Fibonacci levels.

Bullish Scenario

If SOL holds the $92.94 support area and buyers regain momentum, a recovery could develop toward:

- $97.06–$98.23
- $100.06–$102.11
- $104.18–$106.02
- $108.62–$109.84
- $112.58–$114.35
- $117.68–$121.96

A sustained move above $98.23 would be the first sign of short-term recovery. Reclaiming the $100.06–$104.18 EMA region would strengthen the bullish outlook, while a breakout above $106.02 could open the path toward $112.58–$117.68.

Pullback Scenario

If SOL fails to reclaim the $97.06–$100.06 resistance region and selling pressure continues, watch these support areas:

* $92.94
* $86.69
* $82.23
* $81.70
* $80.51–$79.06
* $61.72 — broader Fibonacci base

A decisive breakdown below $92.94 could expose the $86.69 area first. If selling pressure accelerates and this support fails, the $82.23–$80.51 region could become the next important downside area.

The $61.72 level represents the broader Fibonacci base, not an immediate downside target.

RSI Momentum

* RSI: 29.64
* RSI Signal Average: 36.74

RSI has dropped below 30, indicating that SOL is approaching oversold territory. It is also trading below its signal average, confirming that bearish momentum remains dominant.

A recovery above 30–35 could be an early indication that selling pressure is easing. A sustained move above 40–50 would provide stronger evidence of improving momentum.

However, oversold conditions alone do not guarantee an immediate reversal.

Market Structure & Liquidity

SOL previously recovered from the June low near $61.72 and gradually moved higher, eventually reaching the $98.52–$100 region in October.

However, the latest rejection has pushed price below the major EMA cluster and weakened the recovery structure. The market is now testing whether the $92.94 area can attract buyers and prevent another leg down.

The $97.06–$100.06 region is an important resistance zone that buyers need to reclaim. Until SOL recovers above this area, sellers retain the short-term advantage.

A confirmed breakdown below $92.94 would increase the risk of a deeper correction toward $86.69 and potentially $82.23.

Key Levels

Resistance

* $97.06–$98.23
* $100.06–$102.11
* $104.18–$106.02
* $108.62–$109.84
* $112.58–$114.35
* $117.68–$121.96

Support

* $92.94
* $86.69
* $82.23–$81.70
* $80.51–$79.06
* $61.72

Final Outlook

SOL remains bearish in the short term while trading below the $98.23–$100.06 resistance region. Price is approaching an important support area near $92.94, while RSI indicates that selling pressure is elevated.

A sustained recovery above $100.06 could open the path toward $102.11–$104.18, followed by $106.02. On the downside, losing $92.94 would increase the risk of a deeper correction toward $86.69 and $82.23.

Bias: Bearish below $100.06 | Recovery above $104.18 → $106.02 → $112.58

Analysis based on the SOL/USDT 1D chart dated November 1, 2026. These are technical scenarios, not guaranteed outcomes or financial advice.
$SOL ‌
repost-content-media
SOL-0.77%
🎃 WEEKEND CRYPTO UPDATE: THE BEARS TOOK EVERYTHING EXCEPT OUR PATIENCE! 🐻📉
What a week! 😱 More than 400,000 traders reportedly got liquidated, and over $2.5 billion went up in smoke! 💸🔥
The bears didn't just visit the market this week. They moved in, changed the locks, and started charging rent! 🐻🏠😂
Meanwhile, a major theft incident involving more than $5 billion added to market anxiety, while AI stocks suffered a serious sell-off on Thursday and Friday. 📉💥 Risk appetite weakened, uncertainty increased, and both crypto and traditional markets felt the pressure.
❤️ But life is bigger
Repanzal
🎃 WEEKEND CRYPTO UPDATE: THE BEARS TOOK EVERYTHING EXCEPT OUR PATIENCE! 🐻📉

What a week! 😱 More than 400,000 traders reportedly got liquidated, and over $2.5 billion went up in smoke! 💸🔥

The bears didn't just visit the market this week. They moved in, changed the locks, and started charging rent! 🐻🏠😂

Meanwhile, a major theft incident involving more than $5 billion added to market anxiety, while AI stocks suffered a serious sell-off on Thursday and Friday. 📉💥 Risk appetite weakened, uncertainty increased, and both crypto and traditional markets felt the pressure.

❤️ But life is bigger than charts!

Behind every market candle is a real person dealing with real-life challenges. One trader shared that campaigning left them with back pain, while their child's month-long cough developed into pneumonia. After spending several days at the hospital, they finally found a little time to pay the team before heading back to care for their child. 🏥❤️

Wishing the little one a speedy recovery! 🙏👶 Sometimes the market isn't the only thing testing our patience.

₿ BTC: THE BATTLE ZONE ⚔️

Bitcoin has dropped into the $75,475–$78,425 range.

🔹 If BTC holds above this zone, buyers may attempt a recovery.
🔹 If it breaks below the range, further downside remains possible.
🔹 Watch price action and trading volume to assess whether buyers are returning.

⚠️ Don't assume every dip is the bottom. Sometimes the market offers a discount, and sometimes it offers another discount on the discount! 😂📉

◆ ETH: PATIENCE OVER PANIC 💎

Ethereum has multiple trading zones below the current price, making risk management essential.

📍 One proposed strategy is to accumulate ETH spot gradually around $2,300 or below, with additional purchases considered after each further $200 decline.

But remember: these are potential entry levels, not guaranteed support.

💡 Keep enough capital available in case the correction deepens. Don't turn your entire portfolio into a rescue mission for falling candles! 🕯️🆘

🟡 GOLD: IS THE BOTTOM HIDING? 🏆

Gold has reportedly reached a new low for 2026. Will it stabilize or continue falling?

👀 Keep an eye on Monday's opening session and next week's key developments:

📊 ADP employment data
📊 U.S. nonfarm payrolls
🗳️ U.S. midterm elections on November 3
🌍 Developments around the Strait of Hormuz

These macro events could influence gold, equities, and crypto sentiment.

⚠️ In uncertain markets, technical indicators can produce misleading signals. Stay flexible and don't marry a price target!

📈 U.S. STOCKS: WAIT FOR THE NEXT MOVE 🇺🇸

AI-related stocks suffered a sharp sell-off on Thursday and Friday. Monday's reaction may provide more clues about market direction.

For now, let's give the market a little time to breathe. Even charts deserve a recovery day! 😂☕

🧠 MY WEEKEND SURVIVAL GUIDE

✅ Accumulate BTC and ETH spot gradually according to a predefined plan.

✅ Keep emergency funds separate from trading capital.

✅ Avoid excessive leverage during extreme volatility.

✅ If trading futures, use a clear stop-loss and appropriate position sizing.

✅ If you cannot control the risk, staying out is also a valid trading decision.

🚨 Nobody knows the exact bottom. The market might recover tomorrow, next month, or much later. No asset is guaranteed to recover on our preferred schedule.

❤️ ONE LAST THING

Let's hope the little one gets discharged soon, life returns to normal, and the market gives everyone a break.

The bears have had their feast. 🐻🍽️

The bulls are missing in action. 🐂🔍

The liquidated traders are looking for their money. 💸😭

And the rest of us? We're just staring at the chart, drinking coffee, and pretending everything is under control! ☕😂

Stay patient. Protect your capital. And remember: surviving the market is also a win. 💪💎

⚠️ Personal market commentary only. Not financial advice. DYOR and manage risk careful.
#USStocks #MarketVolatility #BTC大跌 #ETHPullsBack
BTC-0.67%
ETH-1.26%
XAU+0.38%
ADP-0.79%
$ZRO is setting up for an exciting move!
After weeks of downward pressure, the chart is finally showing signs of strength.
A clean escape from the falling trendline has opened the door for a fresh upward expansion.
The recent surge toward $1.88 suggests buyers are becoming more aggressive.
The $1.75–$1.80 area is now an important zone to watch for continued strength.
If demand stays strong, price could challenge $1.95 before attempting the $2.10 region.
Momentum is building, and the next few 4H candles could be crucial.
$ZRO might be entering a new bullish phase. Watch closely!
MarcusCorvinus
$ZRO is setting up for an exciting move!

After weeks of downward pressure, the chart is finally showing signs of strength.

A clean escape from the falling trendline has opened the door for a fresh upward expansion.

The recent surge toward $1.88 suggests buyers are becoming more aggressive.

The $1.75–$1.80 area is now an important zone to watch for continued strength.

If demand stays strong, price could challenge $1.95 before attempting the $2.10 region.

Momentum is building, and the next few 4H candles could be crucial.

$ZRO might be entering a new bullish phase. Watch closely!
repost-content-media
ZRO-2.59%
$XRP MARKET CAP JUST FACED A BRUTAL REJECTION!
On the 15-minute chart, XRP’s market cap surged toward $79.7B before sellers crushed the momentum, sending it below $79B!
Now sitting at $79.14B (-0.05%), buyers are fighting back from the $78.85B–$78.95B demand zone.
Hold $79B: Recovery toward $79.4B–$79.5B.
Lose $78.85B: Another selloff could follow.
Bulls are defending the floor, but can they take back control?
LedgerBull
$XRP MARKET CAP JUST FACED A BRUTAL REJECTION!

On the 15-minute chart, XRP’s market cap surged toward $79.7B before sellers crushed the momentum, sending it below $79B!

Now sitting at $79.14B (-0.05%), buyers are fighting back from the $78.85B–$78.95B demand zone.

Hold $79B: Recovery toward $79.4B–$79.5B.

Lose $78.85B: Another selloff could follow.

Bulls are defending the floor, but can they take back control?
repost-content-media
XRP-1.15%
The Organization of the Petroleum Exporting Countries and its allies, known as OPEC+, have reached a preliminary agreement to keep production targets unchanged for December. Three sources familiar with the matter confirmed the principle to Reuters. The decision follows a virtual meeting of seven key members, including Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan, and Oman. The group had already maintained September 2026 production levels for November during its October 4 meeting.
This approach reflects the group's focus on market stability. Several members are producing below their
User_any
The Organization of the Petroleum Exporting Countries and its allies, known as OPEC+, have reached a preliminary agreement to keep production targets unchanged for December. Three sources familiar with the matter confirmed the principle to Reuters. The decision follows a virtual meeting of seven key members, including Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan, and Oman. The group had already maintained September 2026 production levels for November during its October 4 meeting.

This approach reflects the group's focus on market stability. Several members are producing below their assigned quotas due to disruptions in the Middle East. Shipping through the Strait of Hormuz and the Red Sea has faced repeated attacks, affecting export volumes. Meanwhile, a separate voluntary cut of about 2 million barrels per day remains in place through the end of 2026. Analysts note that OPEC+ is shifting its attention toward negotiating production policy for 2027. The group aims to complete a review of each member's production capacity before setting new quotas.

For you, stable production targets can influence fuel costs and inflation expectations. If supply remains constrained by geopolitical risks, energy prices may stay elevated. If disruptions ease, pressure could soften. Both directions remain possible. Markets are watching the 2027 policy discussions and the security situation in key shipping routes. I am holding my positions and watching the market. This is not financial advice.
#Petrol #𝐎𝐈𝐋 #GateSquareHalloween
#ShareWeekly
repost-content-media
The decline in US technology stocks in recent months signals not just a price correction, but a deep unraveling in the market structure. The TMT momentum factor, an indicator tracking the fastest-rising technology, media, and telecommunications stocks in recent times, has fallen 62% from its peak. This decline is even sharper than the losses seen during the bursting of the Dot-Com bubble in 2000 and the 2008 Global Financial Crisis.

What's behind this decline?

There's no single reason behind this picture. Over the past two years, investors have approached growth in the artificial intelligenc
User_any
The decline in US technology stocks in recent months signals not just a price correction, but a deep unraveling in the market structure. The TMT momentum factor, an indicator tracking the fastest-rising technology, media, and telecommunications stocks in recent times, has fallen 62% from its peak. This decline is even sharper than the losses seen during the bursting of the Dot-Com bubble in 2000 and the 2008 Global Financial Crisis.

What's behind this decline?

There's no single reason behind this picture. Over the past two years, investors have approached growth in the artificial intelligence field with great faith. However, this optimism has brought with it intense borrowing. Margin debt on US stock exchanges has reached record levels. Investors often bought AI stocks on credit. When prices began to fall, brokerage firms demanded additional collateral. Investors who couldn't find cash were forced to sell other assets. This further deepened the sell-off.

What Does This Mean for Individual Investors?

For you, the most important part of this process is not only understanding what is happening, but also discerning what isn't. This decline doesn't mean AI is a hoax. However, the market is now questioning when companies' spending on this technology will translate into profit. While growth in core business lines is slowing for giants like Alphabet, Amazon, and Meta, spending on AI infrastructure continues to rise. This imbalance is testing investors' patience.

In the coming period, markets will want to see tangible returns on these company expenditures. If companies can maintain their profitability, confidence can be restored. However, if spending continues to rise faster than revenue growth, the pressure may persist. At this point, it will be important for you to review your own risk tolerance and portfolio allocation. Such market shifts generally require a long-term perspective.

Do you think this decline is an opportunity for technology stocks, or the beginning of a longer repricing process?

This is not investment advice.
#TechStocks #Momentum #AI

$NAS100 $EURUSD $US30
repost-content-media
AMZN+4.14%
NAS100+2.72%
EURUSD+0.51%
US30+1.70%
  • 1
1. Stocks falling below their offering price: A familiar, bitter feeling

Based on intraday lows from October 30, Alphabet’s Class C shares fell approximately 32.5% below their offering price, while Class A shares dropped 21.5% below. Intel shares fell 21.1% below, and Meta shares dipped 2.4% below. While this might appear as nothing more than a shifting number on a screen, it can trigger an internal questioning—a gap between the narrative you envisioned when you first bought the stock and where the price stands today.

After all, you rarely buy a stock solely for its price chart; you buy it b
User_any
1. Stocks falling below their offering price: A familiar, bitter feeling

Based on intraday lows from October 30, Alphabet’s Class C shares fell approximately 32.5% below their offering price, while Class A shares dropped 21.5% below. Intel shares fell 21.1% below, and Meta shares dipped 2.4% below. While this might appear as nothing more than a shifting number on a screen, it can trigger an internal questioning—a gap between the narrative you envisioned when you first bought the stock and where the price stands today.

After all, you rarely buy a stock solely for its price chart; you buy it because of the confidence you have in the company’s future. When the price falls below the offering price, the question arises: "Why did I believe in this story?" This question resonates more within yourself than it does on your portfolio screen.

2. The fine line between a "good company" and a "good stock"

The sell-off appears to have been ignited by Alphabet’s search advertising revenue falling short of expectations, and Intel’s disclosure of supply chain issues regarding its data center components. As for Meta, concerns emerged that the pace at which its AI investments translate into revenue might lag behind the spending itself; compounded by the company’s plan to sell up to $60 billion in additional shares, an invisible weight has settled upon the stock.

For the individual investor, this serves as a reminder: a company’s size or its standing within an industry offers no guarantee as to how its stock will perform in the short term. It is precisely on days like these that the fine line between being a "good company" and a "good stock" becomes starkly apparent.

3. Is growth now having to sustain itself? In the first nine months of 2026, five major technology companies spent a total of $556.9 billion on AI infrastructure; during the same period, their combined operational cash flow stood at $542.9 billion. In other words, their expenditures have exceeded the cash generated from their own business operations. In the third quarter, Alphabet’s capital expenditures surpassed its operational cash flow, pushing its free cash flow into negative territory; similarly, Meta experienced such significant pressure on its cash flow for the first time.

For investors, this may imply that growth is no longer self-sustaining. There is now a need for external capital—whether through borrowing or the issuance of new shares. This does not necessarily mean a company is “bad,” but it does signal a shift in how its growth is financed. And when the method of financing changes, the nature of the associated risk changes as well.

4. Share dilution: Smaller slices of the same pie

When a company announces a new share issuance, the immediate takeaway is often simply that it is “raising capital.” However, the flip side is the dilution of existing shareholders' stakes. As a company issues new shares, each share you hold represents a smaller slice of the company’s total “pie.” In this context, share offerings—such as Alphabet’s $85 billion, Intel’s $23 billion, and Meta’s $25 billion—are not merely news of “fundraising”; they also represent a reconfiguration of the value attributable to each individual share.

Meta’s plan for an additional $60 billion in potential share offerings—which have not yet been sold—can also be viewed as part of this “invisible burden.” For the individual investor, the question here is: “Am I a partner in this company, or am I merely tracking its price movements?” Being a partner serves as a reminder that dilution is also part of your own investment story.

5. Meta’s cash flow: The feeling that “there’s no cash left in the till”

Over the last quarter, Meta spent approximately $34 billion on buildings and equipment, while its operations generated about $33 billion in cash. This equation pushed the company’s free cash flow into negative territory for the first time since 2012. Meanwhile, share buybacks have all but ceased, and the issuance of new shares has come into play.

This does not mean that “Meta is going under.” However, it does create the impression that the company—which once fueled its growth through its own cash generation—is now increasingly reliant on external capital. This shift leaves investors wondering when the race between the “rate of spending” and the “rate of earning” will finally reach a balance.

6. The question beyond the numbers: Is it a case of being “too late,” or simply a matter of cost?

The experience of investors in companies like Alphabet, Meta, and Intel evokes a familiar sentiment: the feeling of being “too late.” Yet, this sensation isn’t always tied to the direction of the stock price; sometimes, it stems from the lack of an answer to the question: “When will there be a return on such massive expenditure?”

The notion that “share dilution is becoming yet another cost of the AI frenzy” is not investment advice—it is an observation of the current reality. And perhaps what the individual investor needs most is precisely this: a sober accounting where costs are transparent, rather than narratives driven by enthusiasm.

NFA ✔️ DYOR 🔎
repost-content-media
$XTIUSD ‌$XBRUSD ‌
1. The quiet slowdown in the Strait of Hormuz
In the final week of October, the daily flow of crude oil passing through the Strait of Hormuz dropped to 7.3 million barrels—more than 40% below pre-war levels. While the average for the entire month hovered around 11.1 million barrels per day, the decline in that last week raises a question: Is this a temporary fluctuation, or the first whisper of a more permanent shift in direction? For the individual investor, the answer to this question has less to do with lines on a chart and more to do with one’s own perception of risk.
User_any
$XTIUSD ‌$XBRUSD ‌

1. The quiet slowdown in the Strait of Hormuz

In the final week of October, the daily flow of crude oil passing through the Strait of Hormuz dropped to 7.3 million barrels—more than 40% below pre-war levels. While the average for the entire month hovered around 11.1 million barrels per day, the decline in that last week raises a question: Is this a temporary fluctuation, or the first whisper of a more permanent shift in direction? For the individual investor, the answer to this question has less to do with lines on a chart and more to do with one’s own perception of risk.

2. Brent reaching $118: “Expensive, compared to what?”

At the end of October, Brent crude hit $118—its highest level since April—while WTI traded in the $103 range. These figures alone are not enough to label something as “expensive” or “cheap.” The real issue is this: Has the price reached this level because of an actual contraction in supply, or because future concerns are being priced in today? The distinction between the two determines how long you might be able to hold your position.

3. The gap between “war risk” and “actual supply”

Tanker traffic through the Strait of Hormuz did not come to a complete halt throughout the month; in fact, it reached 10.3 million barrels per day as late as mid-month. In other words, beyond any actual “disruption,” there are invisible frictions at play, such as rising insurance costs and altered shipping routes. For the individual investor, this distinction is crucial: a physical cutoff in supply is not the same thing as supply simply becoming more costly to deliver. The second scenario pushes the price upward, but it changes the nature of the narrative.

4. Green candles on the chart and the question behind them

When the candles on your screen turn green, you might get the feeling that you are “missing out.” Yet, behind that green lies the reality that the flow through the Strait of Hormuz dropped to 7.3 million barrels in the final week—a figure that highlights the gap compared to pre-war levels. In other words, what is driving the price higher is not the sentiment that “everything is fine,” but rather the concern that “something is not right.” Recognizing this distinction can shift how you view the chart.

5. The “short-term volatility” trap

The fact that the flow dropped from 10.3 million barrels per day in the middle of the month to 7.3 million by the end illustrates just how volatile such data can be. For an individual investor, this volatility presents two types of risks: first, attempting to discern a general trend based on a single week’s data; and second, conversely, overlooking a structural shift by assuming that “things will bounce back eventually.” Striking a balance between these two requires far more patience than technical analysis alone.

6. Beyond the numbers: “Where do I fit into this story?”

With Brent crude reaching $118, WTI hovering around the $103 mark, and the flow through the Strait of Hormuz falling 40% below pre-war levels—when all these figures appear side-by-side on your screen as an investor, they boil down to a single question: What is your role in this story? Are you someone trying to predict the direction of the price, or are you someone seeking to understand where the supply—and the risk—truly stand? The second is a path that is always less exciting, but longer-lasting.

DYOR 🔎 NFA ✔️
repost-content-media
XTIUSD-2.46%
XBRUSD-3.35%
#BTC大跌 An Expected Decision, an Unexpected Breath

The last Wednesday of October marked yet another significant moment for the crypto market. The Federal Reserve held its policy interest rate steady within the 3.75%–4% range—an outcome most of us had already anticipated. Yet, the truly interesting aspect wasn't the decision itself, but rather the events immediately preceding and following it. Sitting before our screens for hours, waiting for a single sentence... In truth, what we were waiting for wasn't just an interest rate figure; it was a sense of certainty—a piece of news that would allow
User_any
#BTC大跌 An Expected Decision, an Unexpected Breath

The last Wednesday of October marked yet another significant moment for the crypto market. The Federal Reserve held its policy interest rate steady within the 3.75%–4% range—an outcome most of us had already anticipated. Yet, the truly interesting aspect wasn't the decision itself, but rather the events immediately preceding and following it. Sitting before our screens for hours, waiting for a single sentence... In truth, what we were waiting for wasn't just an interest rate figure; it was a sense of certainty—a piece of news that would allow us to catch our breath. The market felt this, too. Bitcoin saw a brief recovery following the announcement before settling down. This state of numerical equilibrium mirrors the current internal state of many of us: we aren't necessarily looking for a major move; we simply crave clarity.

Two Different Voices at the Same Table: The Debate Within the Fed

The headline "Rates Kept Steady" is what everyone saw. But there is a story unfolding in the background: while 10 members opted to wait, two members argued for an immediate hike. The presence of these two dissenting voices—even during a period when stability is the primary goal—reveals just how diverse the range of perspectives is within the economic leadership. Isn't this a dynamic you and I experience every single day? One voice urges, "Stay calm, just wait," while another insists, "Don't fall behind." Markets, much like people, try to maintain their footing while listening to these two competing internal voices. The committee chose to prioritize data over speculation—much as a mature investor would.

The Weight Behind the Phrase "Inflation Remains High"

Perhaps the most thought-provoking sentence in the Fed’s policy statement was also the simplest: inflation remains high. This statement was made in a meeting room in Washington, yet its impact reaches all the way to wallets across the globe. As long as interest rates remain high, the cost of keeping one’s money in "safe" assets rises, while the appetite for riskier assets is constrained. In essence, this isn't just about a specific rate; it’s a dilemma regarding where capital should flow. It is worth noting, however, that the market had already priced this in. Sometimes, the biggest surprise is the absence of one. All eyes are now turned toward the December meeting and upcoming inflation data.

Looking Toward December: The Market’s Real Agenda Lies Beyond October

The October decision has been priced in—so what comes next? Expectations for an interest rate hike at the December meeting have risen significantly within the futures markets. This means that in the coming weeks, the most critical data points to watch will emerge well before the actual decision date. Inflation figures, employment numbers, bond yields, the dollar index—these are no longer mere background noise; each one serves as a finger on the pulse of the market. This brings us to a classic yet valuable reminder: the core issue isn't a single decision day, but rather the series of data points that pave the way for that decision. For the individual investor, the most prudent approach is to stay informed without becoming overly fixated on any single piece of data.

Bitcoin’s Stance: A Price That Says Little but Commands Much Attention

Following the decision, Bitcoin climbed above $81,000, though it couldn't sustain that level and subsequently drifted back toward that threshold. It neither soared nor collapsed; it simply paused to reflect. My takeaway from this is that the market—much like us—is currently in a "wait-and-see" mode. There was selling pressure leading up to the decision; the announcement brought a temporary sense of relief, followed by a period of introspection. Neutral price action is, in essence, a reflection of a neutral state of sentiment. During such times, rather than reacting with impulsive, knee-jerk trades, it is far more valuable to ask: "What is this picture telling me?" Observing the market’s calm yet cautious stance—until greater clarity emerges—means there is no need to rush.

When Interest Rates Speak, the Market Listens: The Secret Language of Global Capital

Consider this scenario: 12 individuals enter a room in the U.S., and upon their exit, millions of investment portfolios across the globe shift in the same direction. At the October meeting, interest rates remained unchanged—with two members dissenting—and Fed Chair Warsh emphasized that they bear the responsibility of combating inflation, asserting that politics has no place at their table. In the long run, this is a reassuring message; after all, what every investor desires most is for those who set the rules to remain committed to them. The crypto market interpreted this message in two ways: a sense of immediate relief, coupled with a forward-looking sense of caution. Our task is to try and understand this language; the market is always shouting, but the key lies in hearing its whispers.

This content is for informational purposes only and does not constitute investment advice.

$EURUSD $US30 $NAS100 $BTC $XAU
#FedKeepsRatesSteady #USEarningsSeason #ETHPullsBack
repost-content-media
BTC-0.67%
EURUSD+0.06%
US30+0.38%
NAS100-0.07%
XAU+0.38%
Load More