#MetaSwingsFromSurgeToSelloff
META'S EARNINGS PARADOX: RECORD REVENUE, RISING AI COSTS, AND A WALL STREET REALITY CHECK
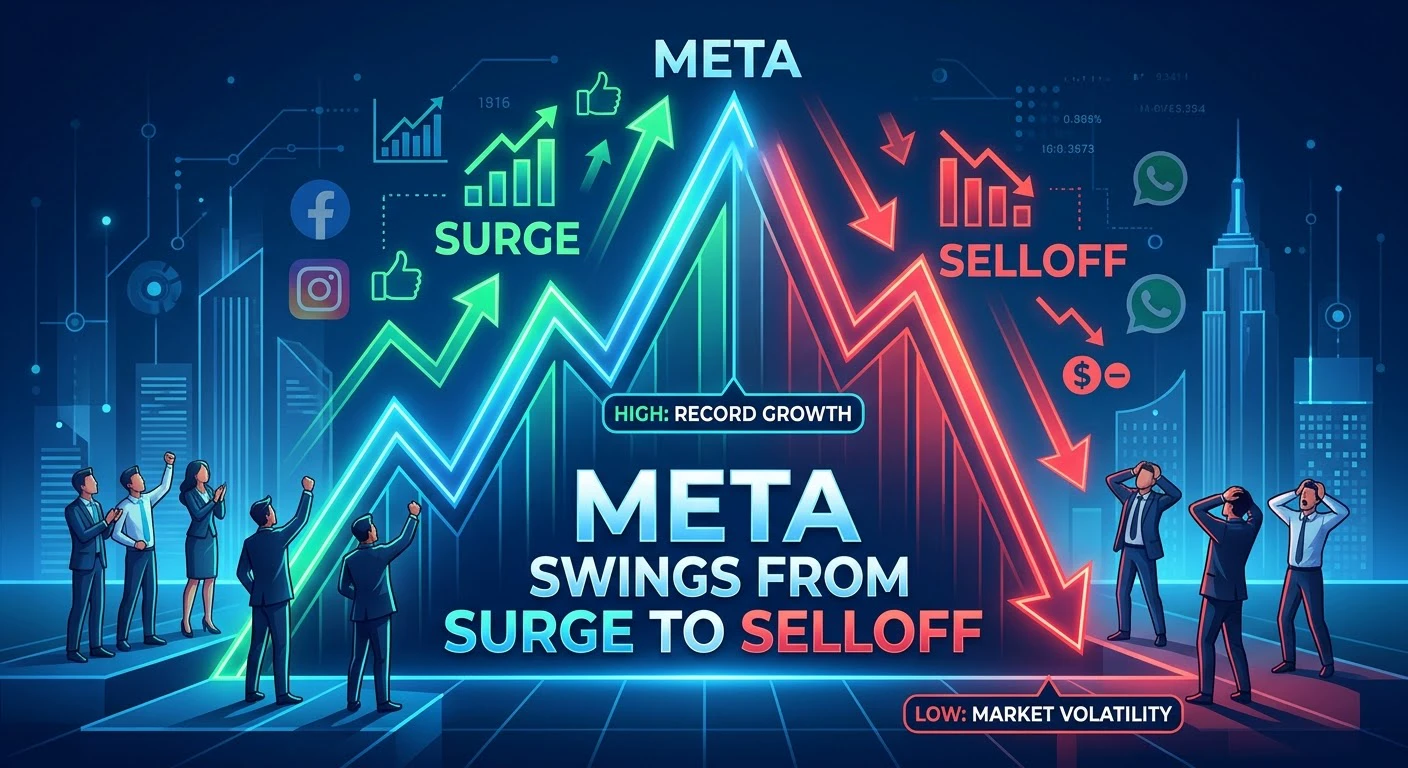
The stock market has delivered a powerful reminder that strong earnings do not always guarantee a rising share price. Meta Platforms, the parent company of Facebook, Instagram, and WhatsApp, reported impressive third-quarter revenue growth, yet its shares suffered a sharp selloff as investors focused on the enormous cost of its artificial intelligence ambitions.
On October 22, 2026, Meta shares fell approximately 7% following the company's latest earnings announcement. The reaction highlighted a growing debate across Wall Street: how much should investors pay today for AI growth that may take years to deliver its full financial return?
📊 Meta's Q3 2026 Financial Performance
Meta reported revenue of $64.60 billion, representing a substantial 26% increase compared with the same quarter last year. Advertising remained a major growth engine, supported by higher ad impressions, stronger pricing, and improvements in AI-powered recommendations.
The company also reported the following results:
• Revenue: $64.60 billion, up 26% year over year.
• Net income: $9.86 billion, compared with $2.71 billion a year earlier.
• Reported diluted EPS: $3.83, compared with $1.05 in Q3 2025.
• Capital expenditures: $34.91 billion during the quarter.
• Free cash flow: Negative $2.12 billion.
These figures require context. Meta recorded a substantial legal-related charge of approximately $9.89 billion. Excluding that charge, diluted earnings per share would have been approximately $7.40. Therefore, the reported decline in operating income and the increase in expenses should not be interpreted without considering the legal expense.
Source: Meta's official third-quarter earnings release.
🤖 Why Did Meta Shares Fall Despite Strong Revenue?
The primary concern is the rising price of the AI race.
Meta is investing aggressively in data centers, computing infrastructure, advanced AI models, and new products. These investments are intended to improve advertising efficiency, increase engagement across its platforms, and develop new AI services.
However, investors want clear evidence that the spending will generate sufficient returns.
Meta raised the lower end of its 2026 capital expenditure outlook, with the company now expecting spending of $135 billion to $145 billion. This enormous commitment has intensified concerns about future cash flow, infrastructure costs, and the time required to monetize AI investments.
The company also announced plans to establish a new class of non-voting Class C shares, creating another potential funding mechanism for future investments and other corporate priorities.
For shareholders, the central question is whether AI-driven revenue growth can eventually outpace the associated expenses.
📱 AI Remains Meta's Biggest Growth Opportunity
Despite the market reaction, Meta's underlying business continues to show considerable strength.
Its advertising ecosystem reaches billions of people worldwide. Better recommendation systems can increase engagement, while AI tools can help advertisers target audiences and improve campaign performance.
Meta is also expanding its AI product ecosystem, including its Muse AI initiatives. If these products attract users and generate sustainable revenue, today's infrastructure investments could support significant long-term growth.
The challenge is timing. Investors must distinguish between promising technology and measurable financial returns.
📉 What Does the Selloff Mean for the Broader Market?
Meta's decline also affected sentiment across technology and semiconductor stocks. On October 22, the Nasdaq Composite fell approximately 2.60%, while the S&P 500 declined around 1.21%. The Dow Jones Industrial Average finished almost unchanged.
This reaction suggests that the market is becoming more selective about AI-related investments. Strong demand for artificial intelligence is no longer enough by itself; investors increasingly want evidence of profitability, disciplined spending, and sustainable cash generation.
🔮 Market Outlook: Bullish Potential or Further Downside?
Meta's short-term outlook remains uncertain.
A bullish scenario could emerge if advertising growth remains strong, AI products gain traction, and management demonstrates that capital expenditures are translating into higher long-term returns. Under these conditions, the selloff could eventually attract investors looking for opportunities in a fundamentally strong business.
A bearish scenario becomes more likely if spending continues to rise faster than revenue, free cash flow remains under pressure, or investors lose confidence in the profitability of AI infrastructure.
The next important signals will be advertising growth, operating margins, capital expenditure guidance, free cash flow, and management's explanation of AI monetization.
My conclusion: Meta's selloff is not necessarily evidence that its business is weakening. Instead, it reflects a market reassessing the cost, timing, and profitability of the company's AI strategy.
For investors, patience and disciplined risk management matter more than reacting emotionally to a single trading session. Strong revenue is encouraging, but sustainable cash flow and profitable growth will ultimately determine whether Meta can regain its upward momentum.
#MetaSwingsFromSurgeToSelloff