BlockRider

vip
Active for: 1.6y
Peak Tier 0
No content yet
#GateStockInsightsChallenge +#NVIDIA
NVDA EARNINGS WEEK: THE AI KING DELIVERED AGAIN, AND THE BEST IS STILL AHEAD

The moment we have been waiting for finally arrived. On August 26, 2026, Nvidia reported its fiscal second quarter results, and the numbers did not just meet the sky-high expectations, they smashed right through them. This report is another masterclass in execution, scale, and pure technological dominance.

THE NUMBERS SPEAK FOR THEMSELVES

The headline that matters most: Nvidia generated $96.2 billion in revenue for the quarter, a stunning 106% increase year over year and an
#NVIDIAEarnings
NVIDIA Earnings: Is $221 the Start of the Next Major Move?
NVIDIA has delivered another extraordinary report card, showing why the AI infrastructure boom remains one of the biggest themes in global markets. The company reported $96.22 billion in quarterly revenue, up 106% year over year and 18% from the previous quarter. Net income reached about $59.69 billion, while adjusted EPS came in at $2.22, beating expectations near $2.09. The biggest headline was Data Center revenue at $89 billion, up 117% year over year. Both revenue and profit beat expectations, making this another p
HighAmbition
#NVIDIAEarnings
NVIDIA Earnings: Is $221 the Start of the Next Major Move?
NVIDIA has delivered another extraordinary report card, showing why the AI infrastructure boom remains one of the biggest themes in global markets. The company reported $96.22 billion in quarterly revenue, up 106% year over year and 18% from the previous quarter. Net income reached about $59.69 billion, while adjusted EPS came in at $2.22, beating expectations near $2.09. The biggest headline was Data Center revenue at $89 billion, up 117% year over year. Both revenue and profit beat expectations, making this another powerful quarter for NVIDIA.
If I had to grade the report, I would give NVIDIA an A+. But for traders, strong earnings are only the beginning. The real question is whether NVIDIA can turn this financial performance into another major stock move from the current reference price of $221.
The $96.2 billion revenue figure is remarkable because NVIDIA is no longer growing from a small base. It is approaching $100 billion in quarterly revenue while still producing triple-digit year-over-year growth. That shows how aggressively technology companies are investing in AI computing, data centers and accelerated infrastructure.
The $89 billion Data Center figure is even more important. Data Center now represents roughly 92% of total revenue, proving that AI infrastructure is driving the business. The segment grew 117% year over year and 18% sequentially, beating expectations of roughly $86.3 billion.
NVIDIA is no longer simply a GPU company. Its ecosystem covers computing, networking, systems and software. That broader platform is a major competitive advantage because customers building AI infrastructure can rely on NVIDIA across multiple parts of the stack.
Profitability is another major strength. NVIDIA generated roughly $59.7 billion in net income and maintained a gross margin around 75%.
That means the company is not only increasing sales but converting an enormous amount of revenue into profit. Strong profitability gives NVIDIA the ability to invest heavily in research, manufacturing, new architectures and future AI platforms while continuing to generate significant cash.
Trading Strategy
The current reference price is $221. I remain fundamentally bullish, but I would not blindly chase the stock. Strong fundamentals create the foundation; price action determines timing.
The first important support is $218–$220. If NVDA holds this area, the short-term bullish structure remains attractive. The first major breakout confirmation is $225.
Above $225, I would watch:
$228 → $232 → $236 → $240 → $245 → $250
If $225 breaks with strong volume, $228 becomes the first target. A move through $228 can open $232–$236. If $236 breaks decisively, $240–$245 becomes the next major zone.
Above $245, the psychological $250 level comes into focus.
Pullback Plan
Instead of chasing at $221, a more conservative trader can wait for $214–$218. If price reaches that area, stabilizes and buyers return, a bullish reversal could offer a better risk-to-reward entry.
If NVDA loses $214–$215 with strong selling pressure, the short-term setup weakens. The next major zone is $210–$211. A decisive break below $210–$211 would be a serious warning and could signal a deeper correction.
For risk management, position size should remain controlled. A strong company can still experience a sharp decline. Profit-taking can be considered around $225–$228, then $232–$236, and again around $240–$245. If $250 breaks with strong momentum, a smaller remaining position can be managed with a trailing approach.
What Matters Next
Investors are watching AI infrastructure spending, hyperscaler capital expenditure, Data Center demand, Blackwell adoption, Rubin demand, margins, memory and component costs, supply availability, China and competition from alternative AI accelerators.
NVIDIA’s next-quarter outlook is especially important. The company expects approximately $108 billion in revenue, while management has indicated around 70% revenue growth into fiscal 2028.
The main risks are equally clear: expectations are extremely high, memory and component costs can pressure margins, and any slowdown in AI capital spending could affect future growth. NVIDIA’s current outlook also does not depend on Data Center compute revenue from China, making that market another important variable.
Final Forecast
From $221, my base-case target is $232–$245, with $250 possible if $236 and $245 break with strong volume.
Support: $218–$220
Defensive support: $214–$215
Major warning: $210–$211
Breakout: $225
Targets: $228 → $232 → $236 → $240 → $245 → $250
NVIDIA deserves an A+ for this earnings report.
Revenue, profit and Data Center growth all show that AI demand remains powerful, while the $108 billion next-quarter outlook keeps the future story strong.
At $221, I remain bullish but disciplined. I would not chase blindly. I would watch $218–$220 for support and $225 for confirmation. Above $225, the path toward $228, $232–$236 and then $240–$245 becomes increasingly interesting. A strong break above $245 puts $250 directly in focus.
The real question is no longer whether NVIDIA is benefiting from AI. It clearly is. The question is whether AI infrastructure spending can remain strong enough for NVIDIA to keep producing extraordinary growth from an already massive revenue base.
If that happens, $221 could eventually look like another step in a much larger move. If expectations become too high, margins weaken or AI spending slows, volatility could increase sharply.
My plan is simple: respect support, confirm breakouts, take partial profits and control downside risk.
Will NVDA reach $230 first, $240 first, or go directly for $250?That is the core bullish argument here.
#GateStockInsightsChallenge +#NVIDIA
repost-content-media
NVDA+0.69%
  • 1
#GateStockInsightsChallenge +#SPCX
Can SPCX Rebound After the Unlock and Return to $150?
The big question for SpaceX stock is whether SPCX can reclaim the psychological $150 level after surviving the recent lockup unlocks, or whether the current rebound is simply a temporary relief rally before another decline. The setup is unusually balanced because technical momentum, valuation, and future share supply are sending mixed signals.
SPCX listed on Nasdaq on June 12, 2026 at an IPO price of $135. It surged to an all-time high of $225.64 on June 16, gaining more than 67% in only four trading days
HighAmbition
#GateStockInsightsChallenge +#SPCX
Can SPCX Rebound After the Unlock and Return to $150?
The big question for SpaceX stock is whether SPCX can reclaim the psychological $150 level after surviving the recent lockup unlocks, or whether the current rebound is simply a temporary relief rally before another decline. The setup is unusually balanced because technical momentum, valuation, and future share supply are sending mixed signals.
SPCX listed on Nasdaq on June 12, 2026 at an IPO price of $135. It surged to an all-time high of $225.64 on June 16, gaining more than 67% in only four trading days. The rally then reversed sharply, with the stock falling to $104.83 on August 3, representing a peak-to-trough decline of roughly 53.5%. By the August 25 close, SPCX had recovered to $137.95, up 31.6% from the August low and only slightly above its IPO price. However, it remains about 38.8% below its record high.
The biggest catalyst has been the staggered lockup schedule. On August 6, around 911 million shares worth approximately $100 billion became eligible to trade, more than doubling the tradable float. Many traders expected heavy insider selling and a major collapse, but the opposite happened: SPCX gained more than 6% on the unlock day and nearly 16% in the following session. A second tranche of around 319 million shares unlocked on August 20 and again failed to trigger the feared collapse, although the stock fell roughly 2.6% that day.
However, the supply problem is not finished.
Around 700 million additional shares are expected to unlock in September, with a similar amount in October. Ultimately, approximately 88% of SpaceX's roughly 13 billion shares are expected to become eligible through 2027.
September could therefore bring a potential $116 billion unlock event. This means the market has successfully absorbed two unlocks, but the larger future tranches still represent a significant risk.
Volume is another important warning sign. SPCX traded roughly 53 million shares on August 25 compared with an average daily volume of about 118 million. That means recent trading activity is running at less than half the average.
A rally toward $150 on declining volume is less convincing than a breakout supported by strong institutional participation. For a sustainable move above $150, I would want to see volume expand significantly, ideally above the 118 million-share average.
The stock's volatility also makes the setup particularly interesting. With a beta near 6.5, SPCX can move dramatically more than the broader market. This creates opportunities for traders but also makes risk management extremely important. A single major headline can potentially produce a double-digit percentage move in either direction.
Short interest was another major source of the recent rebound. Short interest reportedly reached around 34% of the public float, representing approximately 206–208 million shares, before the first unlock. By mid-August, it had fallen toward 11% as the float expanded and short sellers covered positions. This covering created additional buying pressure and helped accelerate the rebound. However, much of that fuel has now disappeared. Future gains therefore need to come increasingly from genuine new buyers rather than forced short covering.
Analyst sentiment remains broadly bullish, although the enormous range of price targets highlights the uncertainty surrounding SPCX.
Around 33 analysts are reported to cover the stock, with the majority maintaining Buy or Strong Buy ratings. Average targets are roughly $216–$232, while the most aggressive target reaches $450. Morgan Stanley has maintained a $300 target, with a bull case around $600 based heavily on the potential AI opportunity.
JPMorgan recently reiterated an Overweight rating with a $240 target, while Bernstein has a $248 target.
On the bearish side, Phillip Securities has a $75 target, DZ Bank has a $100 sell rating, and Morningstar's fair-value estimate is around $62.
The enormous difference between $62 and $450 demonstrates how divided the market is about SpaceX's future valuation.
The fundamental debate is straightforward. Bears argue that SPCX's approximately $1.8 trillion market capitalization is extremely aggressive relative to projected 2026 revenue of around $18.7 billion. The company is also expected to remain unprofitable in 2026, with forecasts pointing toward a loss before a potential return to profitability in 2027. From this perspective, the stock already prices in extraordinary future growth.
Bulls are looking beyond today's earnings. They believe the market is undervaluing SpaceX's AI ambitions, Starlink expansion, launch dominance, Grok-related opportunities, and orbital data-centre plans. The reported partnership with Nvidia and the acceleration of AI-powered orbital data-centre launches toward late 2027 have strengthened the long-term bull narrative. Institutional interest also provides support, with Harvard and the University of California reportedly holding substantial positions, while ARK Invest has also been buying.
So, can SPCX return to $150?
At $137.95, the stock needs only about an 8.7% gain to reach $150. Given its extreme volatility, that move is absolutely achievable, potentially within a single strong session. SPCX has already traded into the $146–$148 area during previous recovery attempts, showing that the $150 zone is within reach.
The problem is that $150 is not just another price level. It is a significant psychological and technical resistance zone. Previous attempts toward the high $140s have failed, and the current rebound is losing some momentum because volume remains weak. A temporary move above $150 would therefore not automatically mean a confirmed breakout.
My view is that the post-unlock rebound is genuine and stronger than many traders expected. The fact that SPCX survived two major unlock events without collapsing is an encouraging sign that insider selling may be more controlled than feared. However, the September and October unlocks remain unresolved, and the current rally lacks the volume confirmation needed for a powerful sustained breakout.
The most likely near-term scenario, in my view, is continued volatility and consolidation between roughly the low $130s and the $150–$152 resistance area. A clean breakout above $152 could open the door toward $160 and potentially higher. On the other hand, rejection around $150 could send SPCX back toward $135, with deeper support potentially appearing in the low $130s.
For a stronger bullish setup, I would watch three things closely: first, whether upside volume expands above the roughly 118 million-share average; second, whether SPCX successfully survives the September unlock while remaining above the $135 IPO price; and third, whether SpaceX produces tangible progress on AI, Starlink, and orbital data-centre monetisation rather than relying solely on announcements.
Short-term traders willing to accept extreme volatility could consider strength above $140, targeting $150–$152 and then potentially $160, while maintaining strict risk controls. Long-term investors may prefer waiting for the September unlock to pass cleanly or for clearer evidence that the AI and orbital data-centre opportunity can translate into meaningful revenue.
In conclusion, SPCX's rebound is real, and the market appears to have been too pessimistic about the immediate impact of the unlocks. A return to $150 is certainly possible from $137.95, but reclaiming $150 convincingly will require stronger volume and continued fundamental catalysts. The September and October unlocks remain the biggest obstacles.
SPCX is therefore an attractive but extremely high-risk setup. The bullish case has enormous potential, but the valuation and share-supply risks cannot be ignored. For now, $150–$152 is the key battlefield: a rejection could bring another pullback, while a high-volume breakout could signal the beginning of a much larger recovery toward $160 and beyond.
repost-content-media
SPCX+1.91%
#CandyDrop1BTCForOldUsers
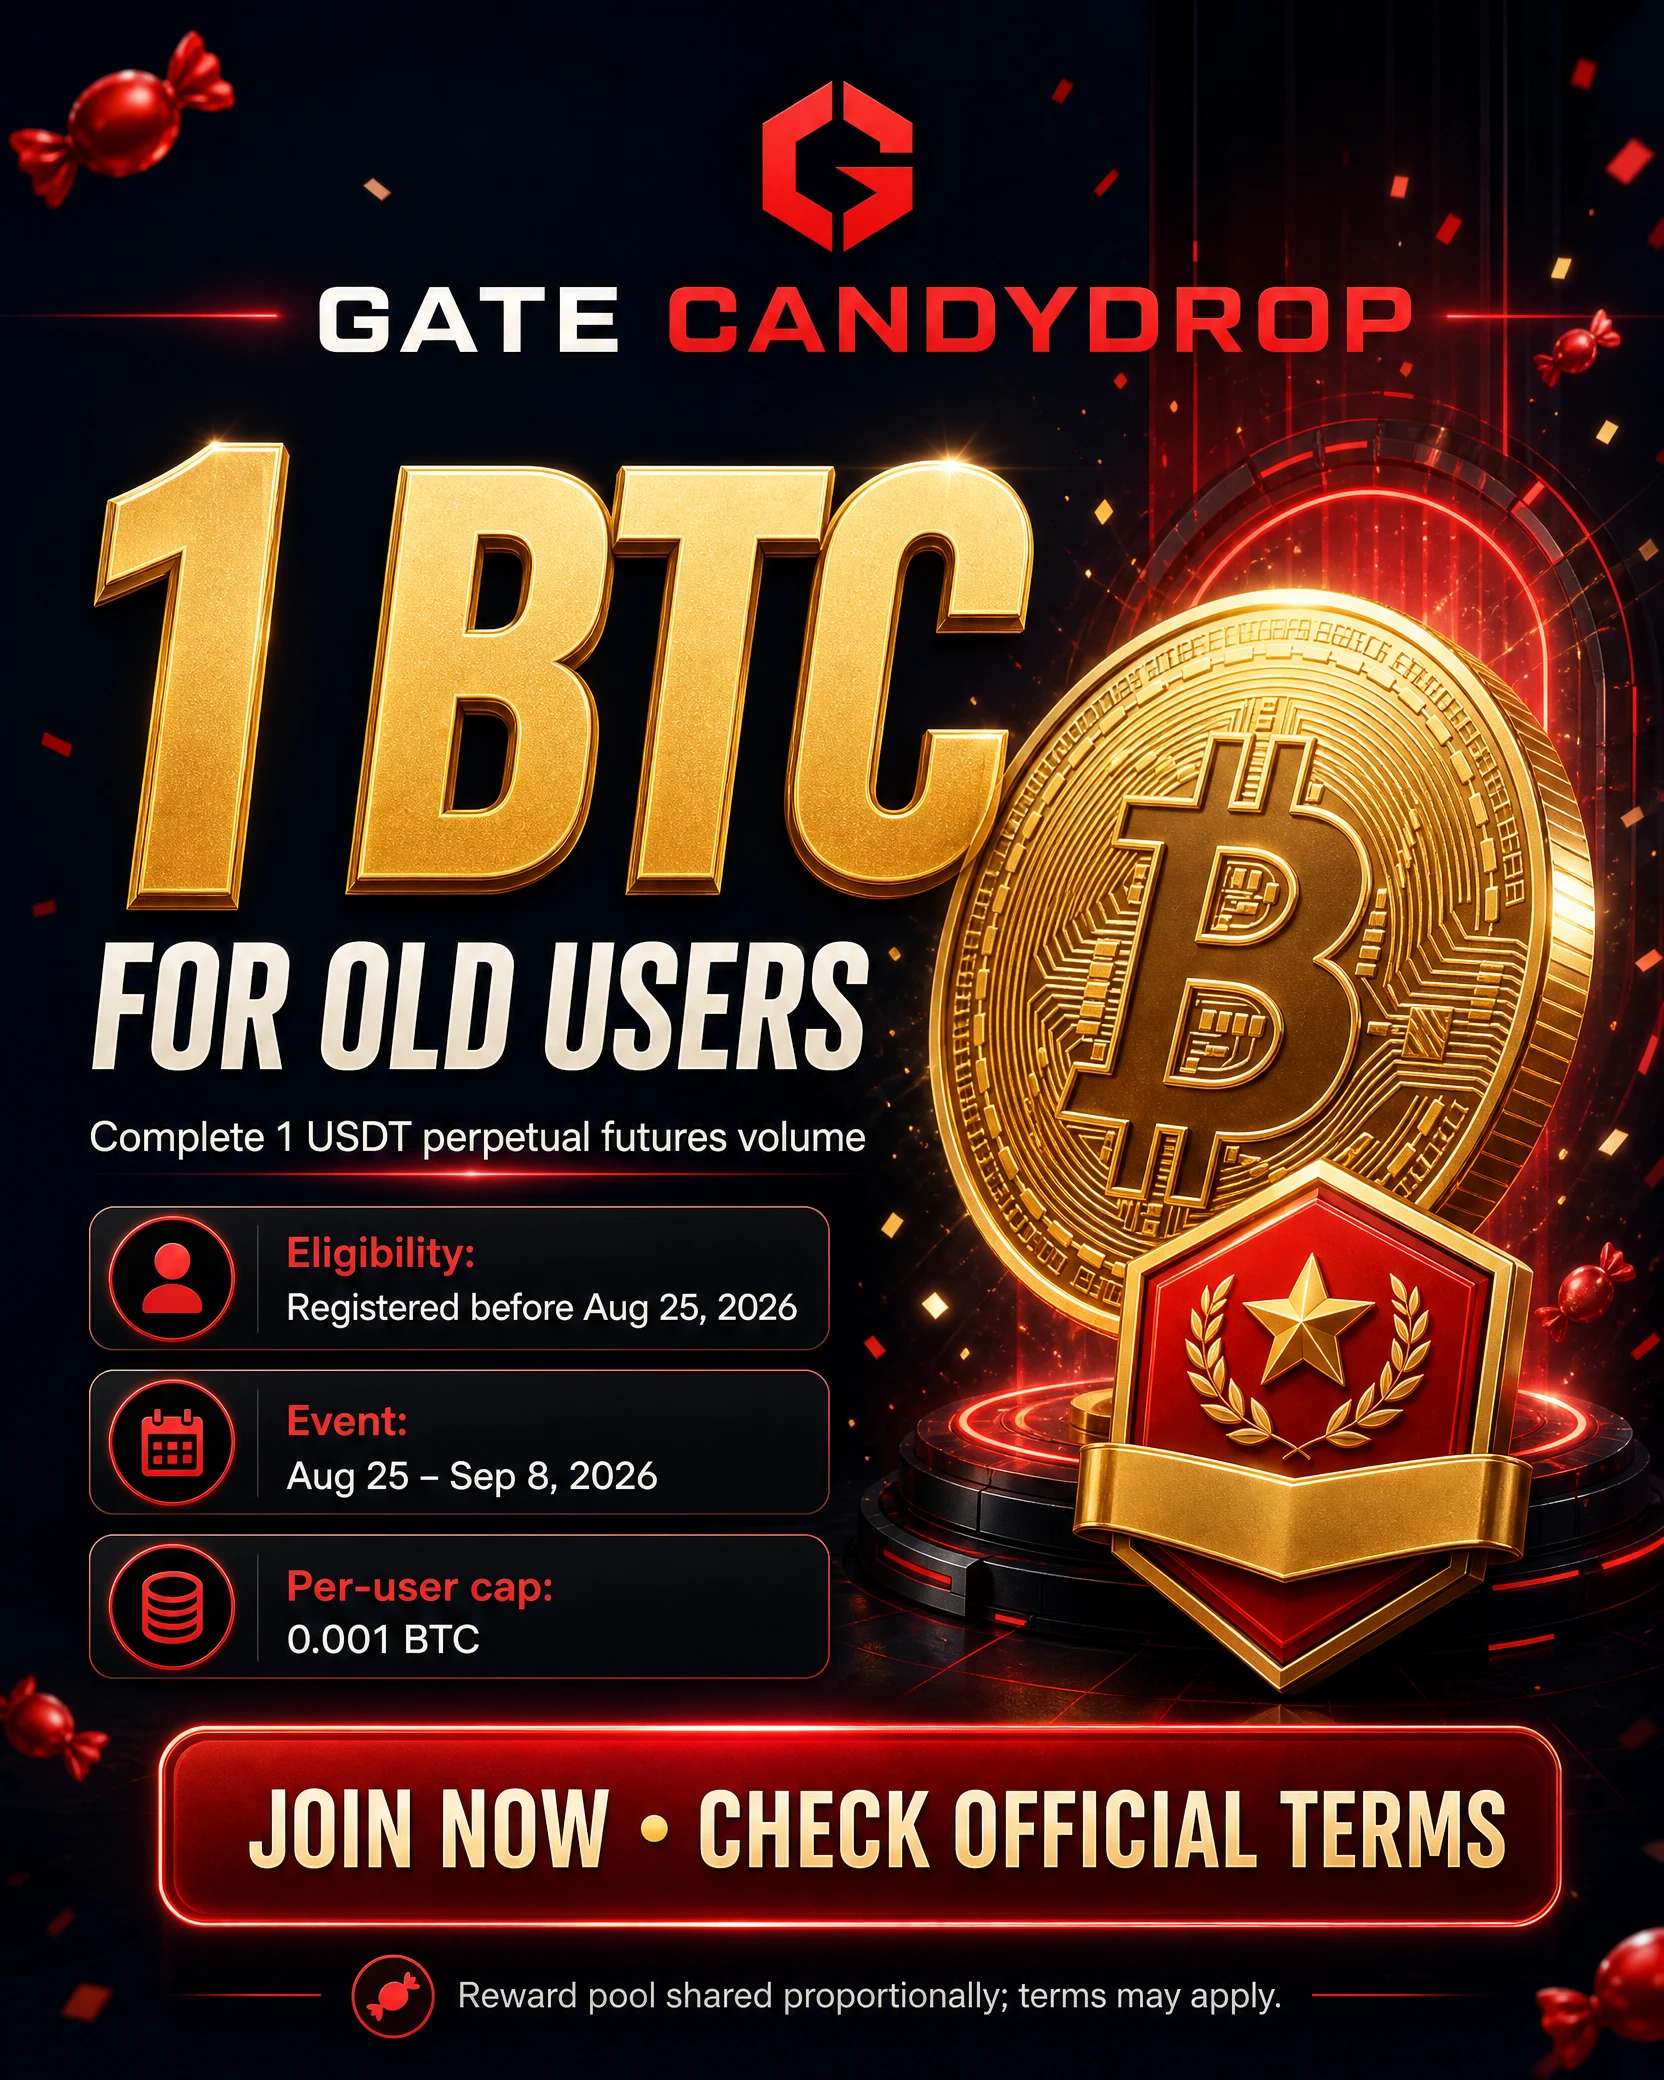
Gate has launched a special CandyDrop campaign for existing users, offering a total reward pool of 1 BTC. The campaign is attracting attention because the qualification requirement is extremely small compared with the size of the reward pool. Eligible users only need to complete a minimum perpetual futures trading requirement during the campaign period. In my view, this is an interesting opportunity for old Gate users, but the actual value depends on participation and the final distribution of the 1 BTC pool.
CandyDrop is Gate’s task-based reward system where users c
HighAmbition
#CandyDrop1BTCForOldUsers
Gate has launched a special CandyDrop campaign for existing users, offering a total reward pool of 1 BTC. The campaign is attracting attention because the qualification requirement is extremely small compared with the size of the reward pool. Eligible users only need to complete a minimum perpetual futures trading requirement during the campaign period. In my view, this is an interesting opportunity for old Gate users, but the actual value depends on participation and the final distribution of the 1 BTC pool.
CandyDrop is Gate’s task-based reward system where users complete specific activities and receive candies that can qualify them for promotional rewards. Depending on the campaign, tasks may involve trading, deposits or other platform activities. Every campaign has its own eligibility rules, time period and reward mechanism, so users should always check the official terms before participating.
For the “1 BTC for Old Users” campaign, the key requirement is that the Gate account must have been registered before 2026-08-25 00:00 UTC+8. This means the promotion is specifically targeting users who already had an account before the stated cutoff. Users who registered after this time are not eligible for this particular campaign. Only the main account qualifies, while sub-account activity does not simply combine with the main account. Multiple-account farming or reward abuse can also lead to disqualification.
The event runs from 2026-08-25 18:00 until 2026-09-08 18:00 UTC+8, giving eligible users roughly two weeks to complete the requirement. One of the most important details is that users should join the campaign before completing the qualifying trade. If you trade first and click “Join Now” afterward, that activity may not count. The safest sequence is simple: open the CandyDrop campaign, join the event, and then complete the qualifying perpetual futures activity within the official event period.
The minimum qualifying requirement is only 1 USDT of perpetual futures trading volume. Compared with many trading promotions that require hundreds or thousands of dollars in volume, this is extremely small. However, the requirement refers to trading volume rather than simply depositing 1 USDT. Users should still check the minimum order size and exact campaign conditions before placing any trade.
Now comes the most important part: the 1 BTC reward pool does not mean every participant receives 1 BTC. It is the total prize pool shared among eligible users according to the campaign’s candy allocation mechanism. If Bitcoin is around $78,700, the entire 1 BTC pool is worth approximately $78,700. There is also a maximum reward of 0.001 BTC per user, which at $78,700 BTC would equal approximately $78.70.
However, the maximum $78.70 equivalent is not guaranteed. Your final allocation depends on the campaign’s distribution mechanism and the number of qualifying participants. If participation becomes very large, the average reward can be much smaller. Therefore, users should look at the 1 BTC figure as a total promotional pool, not as an individual guaranteed payout.
Reward timing is another important point. After completing the qualifying activity, candies may take around 1–3 hours to appear. The final BTC reward is expected to be distributed within 14 working days after the campaign ends. So, completing the trade does not mean BTC will arrive immediately. Users should wait for the final calculation and official distribution.
The market environment also makes this campaign interesting. Bitcoin has recently been trading around the $78,700 area, while overall crypto sentiment has moved toward strong risk-on conditions. The Fear & Greed Index has been around 80, showing strong Greed, while total crypto market capitalization has been around $2.75 trillion. Bitcoin has also gained approximately 13.6% over the previous seven days in the referenced market snapshot.
Bitcoin dominance around 59.6% indicates that a large amount of market capital remains concentrated in BTC. Ethereum has been trading near $2,490, while Solana has been around $101. These prices can change quickly because crypto markets operate continuously, but the broader picture suggests improving risk appetite and renewed trader participation.
From Gate’s perspective, the campaign makes strategic sense. When market activity increases, exchanges want inactive users to return, trading volume to grow and liquidity to improve. By offering a 1 BTC reward pool specifically for older users, Gate is giving existing users a reason to return and interact with the platform.
For eligible users, it creates a chance to earn BTC while meeting a very small qualifying requirement.
My personal view is positive, but realistic. I consider this an interesting low-requirement promotion for eligible Gate users. The biggest attraction is not that everyone will receive a large amount of BTC, because that is clearly not guaranteed. The attraction is the extremely low qualifying threshold. If you already understand perpetual futures and can complete the requirement responsibly, there is little reason to ignore the opportunity simply because the individual reward may be modest.
At the same time, I would not call the campaign completely risk-free. Perpetual futures involve market risk, and leverage can turn even a small trade into a meaningful loss. Users should never increase their position size simply because a promotional reward is available. If the requirement is only 1 USDT of qualifying volume, there is no sensible reason to create unnecessary exposure or use excessive leverage just to chase a bonus.
Another important consideration is participation.
The 1 BTC pool is fixed. If relatively few eligible users participate, the potential allocation could be more attractive. But if thousands or more users qualify, the same 1 BTC must be distributed among a much larger participant base. This means the final reward could be considerably lower than the headline number might initially suggest.
My approach would be straightforward. First, confirm that your Gate account was registered before the 2026-08-25 00:00 UTC+8 cutoff. Second, enter the CandyDrop campaign and click “Join Now” before trading. Third, complete only the required qualifying perpetual futures volume. Fourth, check whether the candies have appeared after the qualifying activity. Finally, wait for the official BTC distribution instead of expecting an immediate payout.
I would also strongly avoid generating large trading volumes just because you believe higher volume will automatically produce a much larger reward. The campaign has a defined reward mechanism and a maximum allocation of 0.001 BTC per user. Excessive trading can create additional fees, market exposure and potential losses without providing a proportional benefit.
The safest mindset is to treat this as a bonus opportunity rather than a trading strategy. Do not take a position you would not normally take just because a CandyDrop campaign exists. Do not use aggressive leverage, and do not manufacture unnecessary volume. Meeting the minimum requirement responsibly is far more sensible than taking additional risk for an uncertain incremental reward.
At approximately $78,700 BTC, the entire 1 BTC prize pool represents around $78,700, while the maximum theoretical individual allocation of 0.001 BTC is about $78.70. This puts the promotion into perspective. The objective should be to collect a potential bonus, not to expect a life-changing payout.
The campaign is particularly interesting for older Gate users who already have an account but have been inactive. Instead of requiring a large deposit or significant trading commitment, Gate is giving these users a relatively simple reason to return. At the same time, Gate benefits through increased engagement, trading activity and liquidity. In that sense, the campaign can be beneficial for both sides when approached responsibly.
My final opinion is positive, but I would keep expectations under control. If you are eligible, I think the campaign is worth checking because the minimum qualifying requirement is extremely small compared with the 1 BTC total reward pool. But I would not chase the reward aggressively. Join first, complete the minimum qualifying activity carefully, avoid unnecessary leverage and volume, and then wait for the final allocation.
In short, Gate’s “1 BTC for Old Users” CandyDrop is a low-barrier promotional opportunity, not a guaranteed large payout. The headline reward is attractive, the qualification requirement is very small, and the current bullish crypto environment makes the promotion more interesting. But the actual reward depends on participation and the campaign’s distribution mechanism, with an individual maximum of 0.001 BTC.
If you registered on Gate before the eligibility cutoff, this is certainly an event worth checking. Complete the required activity responsibly, take whatever BTC allocation you qualify for, and treat it as a bonus rather than a reason to take unnecessary trading risk. In my view, that is the smartest way to approach this campaign.
repost-content-media
#EventContracts1%Reward
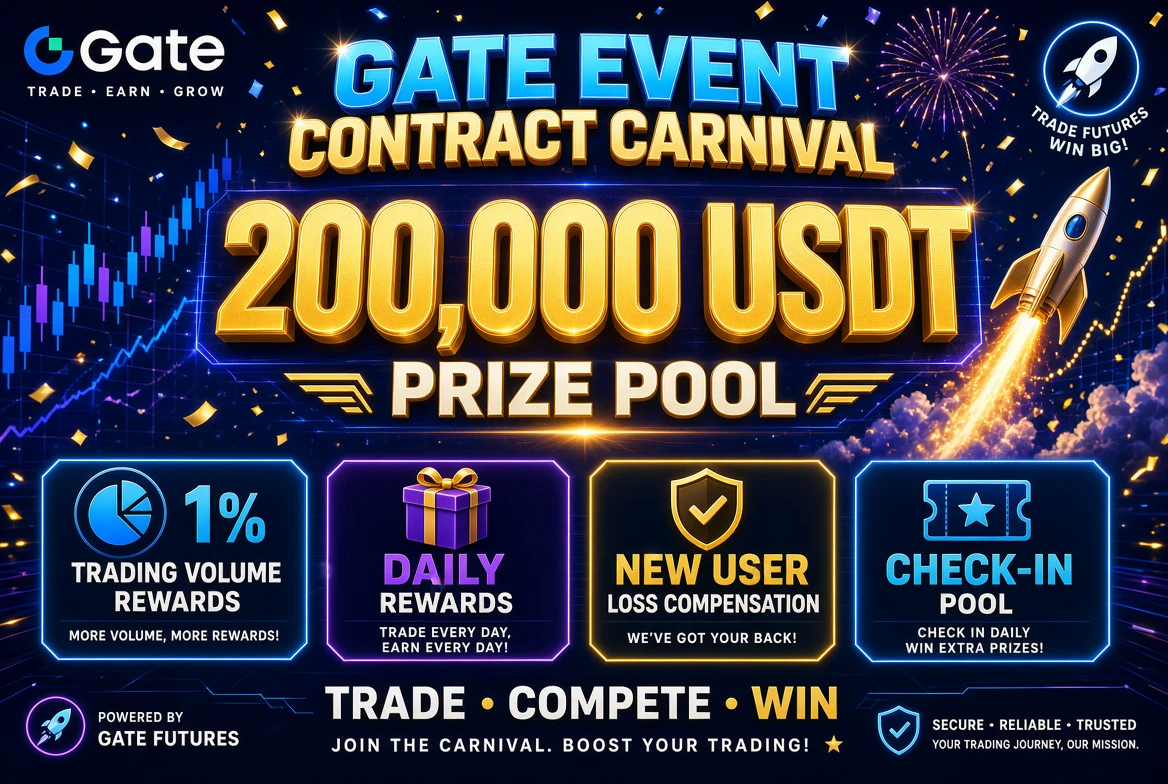
🔥 Gate Event Contract Carnival Is LIVE — 200,000 USDT Prize Pool Up for Grabs! 🚀
Gate has officially launched its Event Contract Carnival Competition, and this campaign gives traders several different ways to earn rewards instead of relying on just one leaderboard. From first-order loss compensation for new users to 1% trading-volume rewards, daily trading incentives, and check-in rewards, there are multiple opportunities available during the event period.
📅 Event Period: August 26, 14:00 – September 2, 08:00 (UTC+8)
The campaign is built around one simple idea: the
HighAmbition
#EventContracts1%Reward
🔥 Gate Event Contract Carnival Is LIVE — 200,000 USDT Prize Pool Up for Grabs! 🚀
Gate has officially launched its Event Contract Carnival Competition, and this campaign gives traders several different ways to earn rewards instead of relying on just one leaderboard. From first-order loss compensation for new users to 1% trading-volume rewards, daily trading incentives, and check-in rewards, there are multiple opportunities available during the event period.
📅 Event Period: August 26, 14:00 – September 2, 08:00 (UTC+8)
The campaign is built around one simple idea: the more consistently you participate and meet the required conditions, the more opportunities you have to claim a share of the rewards. However, traders should always remember that rewards should never be the reason to take unnecessary trading risk.
🌟 Incentive 1 — New Users Get First-Order Loss Compensation
For new users, Gate is offering a special first-order protection incentive. The first 2,000 eligible new users whose first order results in a loss can receive compensation based on their actual loss, with a maximum payout of 5 USDT per person.
This can be a useful opportunity for newcomers who are trying Event Contracts for the first time.
Instead of immediately focusing on large trading volume, new users can start by understanding how Event Contracts work, place their first trade carefully, and potentially receive compensation if that first order ends in a qualifying loss.
🏆 Incentive 2 — 1% Trading Volume Rewards
The biggest attraction of the campaign is the Peak Trading Competition, which offers a massive 100,000 USDT prize pool. Rewards are distributed through different trading-volume tiers, meaning traders with higher eligible volume can compete for larger rewards.
One particularly important target is the 1,000,000 USDT trading-volume level. According to the campaign rules, users who reach at least 1 million USDT in eligible trading volume are guaranteed a 1% reward.
There is also a separate 50,000 USDT trading-volume share pool. Eligible users who do not receive leaderboard rewards can still participate in this pool, with their reward determined by their proportion of eligible trading volume. The maximum reward is 500 USDT per person.
💰 Incentive 3 — Daily Trading Volume Rewards
Gate is also rewarding traders who maintain consistent daily activity.
Tier A requires at least 500 USDT in daily trading volume and offers a 2.5 USDT daily reward.
Tier B requires at least 1,000 USDT in daily trading volume and offers a much larger 10 USDT daily reward.
The important point is that users must meet the requirements on at least 3 days to claim the applicable rewards. If you manage to meet the Tier B requirement every day throughout the campaign, the potential reward can reach up to 70 USDT.
This makes consistency more important than simply having one extremely high-volume trading day. Traders who already plan to participate regularly may find it easier to structure their activity around these daily thresholds.
🎁 Incentive 4 — Daily Check-In Rewards
There is also a lower-volume participation option through daily check-ins.
To complete a qualifying check-in, you need to make at least 3 trades and reach a minimum daily trading volume of 20 USDT. If you complete qualifying check-ins on at least 3 cumulative days, you can participate in sharing a 10,000 USDT prize pool.
This is particularly interesting for traders who may not be able or willing to compete for the large-volume leaderboard. Instead of chasing millions in trading volume, participants can focus on meeting the relatively smaller daily activity requirements and staying consistent throughout the event.
🔥 My Take on the Campaign
In my view, the strongest part of this promotion is that Gate has created several reward paths for different types of users. High-volume traders can target the 100,000 USDT leaderboard pool and the 1% trading-volume reward, while other participants can focus on the 50,000 USDT volume-share pool, daily trading rewards, or the 10,000 USDT check-in pool.
If I were participating, I would focus first on meeting the requirements consistently rather than increasing volume just for the sake of chasing rewards. For example, a trader targeting Tier B could plan around the 1,000 USDT daily requirement, while a smaller participant could focus on the 20 USDT plus 3-trade check-in requirement.
The important thing is to understand the campaign terms, eligible trading activity, reward calculations, and claim requirements before participating. Trading more simply to qualify for a reward can expose you to unnecessary losses, so risk management should remain the priority.
🚀 Quick Breakdown
💰 Total Prize Pool: 200,000 USDT
🏆 Peak Competition Pool: 100,000 USDT
🔥 Volume Share Pool: 50,000 USDT
🎁 Check-In Pool: 10,000 USDT
💵 New User First-Order Compensation: Up to 5 USDT
📈 Tier A: 500 USDT daily volume → 2.5 USDT reward
🚀 Tier B: 1,000 USDT daily volume → 10 USDT reward
💎 Tier B Every Day: Up to 70 USDT
🎯 Check-In: 3 trades + 20 USDT daily volume
🏅 1M USDT volume: 1% reward guarantee under the campaign rules
⏰ Event Ends: September 2, 08:00 (UTC+8)
👉 Sign up and participate here: https://
gate.onelink.me/7pdk/830fdf479a8a6a77
This is definitely an event worth watching for Gate users who already trade Event Contracts.
Multiple reward mechanisms mean you don't necessarily need to be the biggest trader on the leaderboard to have an opportunity to earn something from the campaign.
Trade strategically, keep your risk under control, and make every trade with a clear plan. 🚀
repost-content-media
#TopFiveLeaguesPreMatchPredictor
⚽ PRE-MATCH PREDICTION · ISSUE 09 | BARCELONA vs ATHLETIC BILBAO
🔥 Barcelona vs Athletic Bilbao — Can Barça Continue Their Perfect Start?
One of the most interesting La Liga fixtures is here, and this is not just another league match. Barcelona are preparing for their first home league game of the new campaign, while Athletic Bilbao arrive looking to recover from a disappointing opening-day defeat. The match is scheduled for August 28 at 03:00 (UTC+8), and in my opinion, Barcelona enter this contest with a clear advantage — but Athletic Bilbao have enough qua
HighAmbition
#TopFiveLeaguesPreMatchPredictor
⚽ PRE-MATCH PREDICTION · ISSUE 09 | BARCELONA vs ATHLETIC BILBAO
🔥 Barcelona vs Athletic Bilbao — Can Barça Continue Their Perfect Start?
One of the most interesting La Liga fixtures is here, and this is not just another league match. Barcelona are preparing for their first home league game of the new campaign, while Athletic Bilbao arrive looking to recover from a disappointing opening-day defeat. The match is scheduled for August 28 at 03:00 (UTC+8), and in my opinion, Barcelona enter this contest with a clear advantage — but Athletic Bilbao have enough quality to make certain periods of the match difficult for the defending champions.
My prediction is Barcelona to WIN, and I believe a 3-1 or 3-0 victory is the most realistic range. However, I would not completely underestimate Athletic, especially if Barcelona allow the visitors to find space behind the defensive line.
🔵🔴 BARCELONA — A VERY STRONG START
Barcelona could hardly have asked for a better opening to their title defence. Hansi Flick’s side travelled to Elche and produced a dominant 5-0 victory, immediately showing that their attacking strength remains a major weapon.
The result was impressive not only because of the five goals, but also because of the way Barcelona controlled the match. They created pressure, moved the ball quickly, attacked from multiple areas and showed that they have several players capable of deciding a game.
Raphinha was one of the biggest stars of the opening game, scoring twice, while Fermín López also found the net twice and Karim Adeyemi scored on his debut. Anthony Gordon also made an immediate impact with two assists.
That gives Flick an extremely interesting attacking situation — but it is a good problem to have.
Barcelona now have pace, creativity and multiple attacking combinations. Lamine Yamal can create danger from the right, Raphinha can move centrally or operate from the left, Fermín can attack spaces between midfield and defence, while the new additions provide additional speed and unpredictability.
And the biggest question is whether Athletic can stop Barcelona’s attacking movement for 90 minutes.
I personally think that will be extremely difficult.
🏟️ HOME ADVANTAGE COULD BE HUGE
This is Barcelona’s first home league match of the new campaign, and the home atmosphere should provide another important advantage.
Barcelona have historically enjoyed a very strong record against Athletic at home. Their recent head-to-head record is heavily in their favour, and that psychological advantage cannot be ignored.
Barcelona also enter this match after a 5-0 away victory, while Athletic suffered a 3-1 defeat against Sevilla.
So Barcelona arrive with confidence and attacking momentum, while Athletic have to face one of the strongest teams in Spain immediately after losing their opening fixture.
From my point of view, that puts enormous pressure on Athletic from the first whistle.
🔴⚪ ATHLETIC BILBAO — DANGEROUS, BUT FACING A MAJOR TEST
Athletic Bilbao should not be judged only by their 3-1 defeat to Sevilla.
Their opening match was heavily influenced by Yuri Berchiche’s early red card, which left Athletic playing with ten men from the 11th minute. That completely changed the tactical situation and made it extremely difficult for Athletic to compete normally.
So I don't think the 3-1 scoreline tells the complete story.
Athletic have talented players who can cause Barcelona problems, particularly when they attack quickly.
Nico Williams is the obvious danger. His pace can be extremely valuable against a Barcelona team that often pushes its defensive line high. Iñaki Williams also offers speed and direct running, while Oihan Sancet can provide creativity between the lines.
The return of important players could also give Athletic more balance and confidence.
That means Barcelona cannot simply assume this will be an easy match.
If Athletic survive Barcelona’s initial pressure and find opportunities on the counter, they can absolutely score.
⚔️ THE BIGGEST BATTLE — BARCELONA'S ATTACK vs ATHLETIC'S DEFENCE
For me, this is where the match will probably be decided.
Barcelona are likely to dominate possession and try to move Athletic’s defensive block from side to side. The objective will be to create gaps and then exploit them with quick combinations.
Lamine Yamal will be one of the most important players in this respect.
If Yamal receives the ball one-on-one against a defender, Barcelona can immediately create danger. His ability to cut inside, combine with midfielders and deliver the final pass means Athletic cannot concentrate only on Raphinha.
And that is exactly why Barcelona are difficult to defend.
If Athletic focus too much on Yamal, Raphinha can attack the opposite side.
If they concentrate on Raphinha, Yamal gets more space.
If they push their defensive line higher, Barcelona can attack the space behind them.
If they sit deep, Barcelona have enough technical quality to patiently move the ball around the penalty area.
This is the tactical puzzle Athletic must solve.
⚡ RAPHINHA COULD BE THE KEY MAN
My personal player to watch is Raphinha.
He already scored twice in Barcelona’s opening 5-0 victory, and his movement into central areas makes him particularly dangerous.
With Barcelona operating with considerable flexibility in attack, Raphinha’s ability to move centrally could become a major part of Flick’s attacking system.
He does not have to remain fixed on the wing.
He can drop, combine, attack the box and appear in scoring positions.
That makes it harder for Athletic’s centre-backs to decide whether to follow him or maintain their defensive shape.
If Raphinha gets the same freedom he enjoyed against Elche, I would not be surprised if he gets another goal or assist.
🧠 PEDRI AND THE MIDFIELD BATTLE
Another major factor will be Barcelona’s midfield.
Pedri remains one of the most important players in Flick’s system because Barcelona need someone capable of controlling the tempo rather than simply playing fast all the time.
Against Athletic, patience will be important.
Barcelona do not need to attack every possession immediately.
They can control the game, move Athletic around, wait for the right opening and then accelerate.
Marc Bernal is also expected to have an important role in midfield, while the potential involvement of Rodri adds another fascinating dimension to the match.
If Rodri enters the game, even for a limited period, his experience and ability to control possession could help Barcelona dominate the final stages.
🚨 BARCELONA'S BIGGEST RISK
Despite my confidence in Barcelona, there is one major danger that I would not ignore: the space behind their defensive line.
Barcelona often play with a high line, and that can become dangerous against Athletic’s fast forwards.
Nico Williams and Iñaki Williams have the pace to punish even a small defensive mistake.
If Barcelona lose the ball in midfield while their full-backs are advanced, Athletic could immediately launch a counter-attack.
That is the main route I see toward an Athletic goal.
Therefore, Barcelona need to maintain defensive concentration even if they dominate possession.
🎯 HOW I EXPECT THE MATCH TO DEVELOP
I expect Barcelona to start aggressively.
The first 15–20 minutes could be extremely important.
Barcelona will probably try to pin Athletic back, maintain possession and create early chances. If they score early, I think the match could become very difficult for Athletic.
My biggest concern for Athletic is what happens if Barcelona score before halftime.
If Athletic are forced to open up, Barcelona can exploit the spaces.
That could turn a 1-0 match into 2-0 or 3-0 very quickly.
On the other hand, if Athletic manage to keep Barcelona at 0-0 for a long period, their confidence will increase. Barcelona may then become slightly more impatient, and that could create opportunities for Nico Williams and Iñaki Williams on the counter.
So the first goal is extremely important.
If Barcelona score first, I strongly favour Barcelona.
If Athletic score first, the entire prediction changes because Barcelona would have to chase the game.
📊 MY WIN PROBABILITY
After considering form, home advantage, squad quality, attacking strength and recent head-to-head results, my personal probability estimate is:
Barcelona Win — 72%
Draw — 17%
Athletic Bilbao Win — 11%
These are my own probability estimates, not guaranteed outcomes.
For goals, I expect Barcelona to have the stronger attacking output. A total of three or more goals is definitely possible if the match opens up after the first goal.
⭐ PLAYER TO WATCH: RAPHINHA
If I have to choose one player who could make the biggest difference, I am going with Raphinha.
He already started the season with two goals and looks ready to continue his strong attacking form. If Athletic cannot prevent him from finding central positions, he could once again appear on the scoresheet.
But Lamine Yamal is the other player I would watch very closely.
His one-on-one ability could be decisive, especially against a defence that may struggle to cover the entire width of the pitch.
🚨 CAN ATHLETIC PULL OFF THE UPSET?
Yes, football always gives the underdog a chance.
If Athletic defend compactly, frustrate Barcelona, win the physical battles and exploit Barcelona’s high defensive line through Nico and Iñaki Williams, they can create a serious problem.
But looking at the complete picture, I don't think the probability is high enough for me to make Athletic the favourite.
Barcelona have too many attacking weapons, they are playing at home, they started the season with a 5-0 victory, and their recent record against Athletic is extremely strong.
So my confidence remains with the defending champions.
🏁 FINAL CALL
Barcelona to WIN.
My main prediction: Barcelona 3-1 Athletic Bilbao.
Alternative prediction: Barcelona 3-0 Athletic Bilbao.
Expected match pattern: Barcelona possession + sustained pressure + Athletic counter-attacks.
Key Barcelona players: Raphinha, Lamine Yamal, Pedri and Fermín López.
Key Athletic threats: Nico Williams, Iñaki Williams and Oihan Sancet.
My biggest expectation is that Barcelona will eventually break Athletic’s defensive resistance, and once the first goal arrives, the home side should have enough quality to control the match.
⚽ My final call is Barcelona WIN — but I would respect Athletic Bilbao’s counter-attacking threat and would not call this a completely risk-free game.
#SKHynixSurgesOver5%
SK Hynix is currently trading around 1,262 USDT on Gate, with the latest price action showing a bullish medium-term structure but short-term consolidation after a strong recovery. Price recently moved from approximately 1,201 to 1,281 USDT, creating an intraday range of nearly 6.7%. The asset is around +1.3% over 24 hours and roughly +3.2% over seven days based on the reference data. This volatility is important: buyers remain active, but price is now approaching a major resistance zone where profit-taking can increase. The immediate question is whether SK Hynix can break
HighAmbition
#SKHynixSurgesOver5%
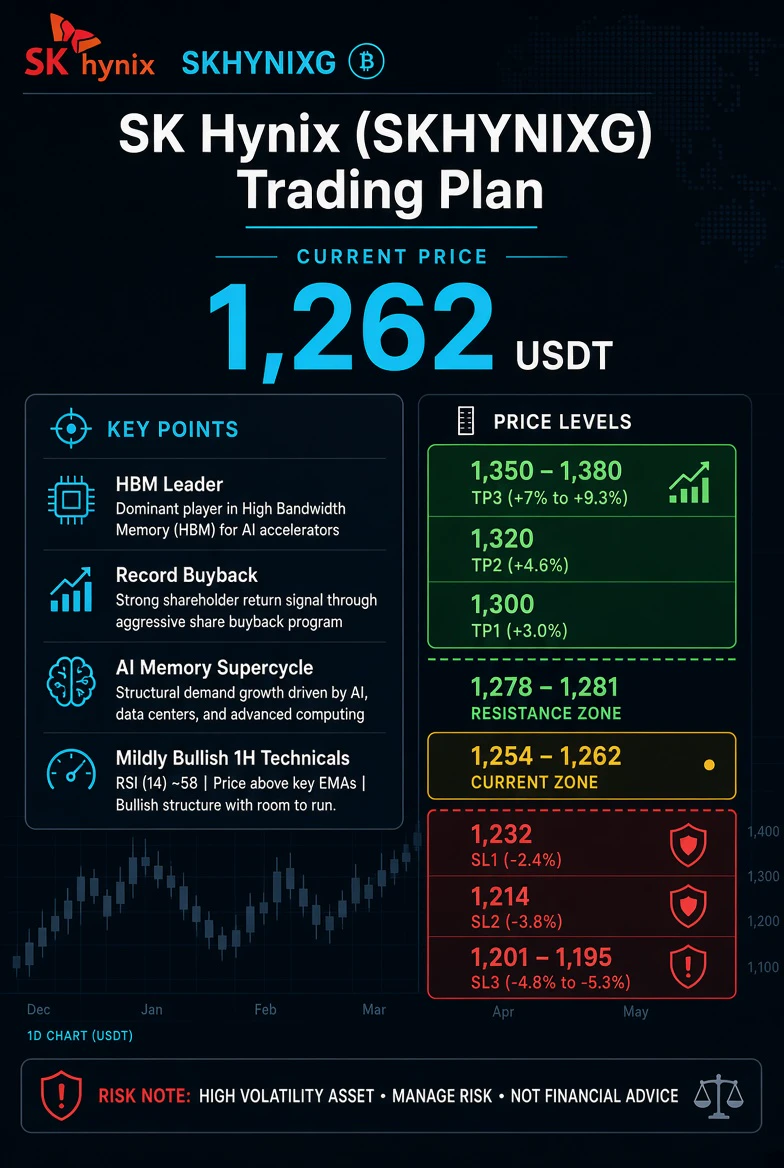
SK Hynix is currently trading around 1,262 USDT on Gate, with the latest price action showing a bullish medium-term structure but short-term consolidation after a strong recovery. Price recently moved from approximately 1,201 to 1,281 USDT, creating an intraday range of nearly 6.7%. The asset is around +1.3% over 24 hours and roughly +3.2% over seven days based on the reference data. This volatility is important: buyers remain active, but price is now approaching a major resistance zone where profit-taking can increase. The immediate question is whether SK Hynix can break 1,280–1,281 and continue toward 1,300 and beyond, or whether it will first pull back toward 1,230–1,240.
The fundamental story remains strongly bullish. SK Hynix has announced a massive 40 trillion Korean won, roughly $28–29 billion, shareholder-return program involving share buybacks and cancellation, while also targeting more than 50% of cumulative free cash flow from 2025–2027 for shareholder returns. The market reacted strongly, with the Korean-listed shares gaining roughly 12% following the announcement. Such a large buyback can support earnings per share, reduce outstanding shares and improve investor confidence. More importantly, it comes while SK Hynix is benefiting from strong demand for AI-related memory.
The biggest structural catalyst is high-bandwidth memory, or HBM. SK Hynix remains one of the world's leading HBM suppliers, with its share estimated around 56–60% depending on the segment and measurement period. HBM is essential for advanced AI accelerators, making SK Hynix a major beneficiary of continued AI data-center expansion. Nvidia and other AI-chip companies require increasing quantities of high-performance memory, and larger AI models are creating greater demand for bandwidth and energy-efficient memory.
This gives SK Hynix direct exposure to one of the strongest growth areas in the semiconductor industry.
The memory-cycle outlook also remains favorable. Bank of America has described the current environment as a potential memory supercycle and identified SK Hynix as a preferred company in the sector. Forecasts have pointed toward roughly 51% year-over-year DRAM revenue growth and around 45% NAND revenue growth, alongside significant increases in average selling prices. If these expectations are achieved, SK Hynix could benefit from higher volumes, stronger pricing, improved margins and greater cash generation. The company is also investing heavily in future capacity, including approximately 54 trillion won of planned memory investment, while continuing development of advanced NAND technology such as 375-layer products.
However, traders should not ignore the risks. SK Hynix has already gained approximately 200–235% year to date depending on the reference listing. After such a massive rally, sharp corrections are normal. Profit-taking, valuation concerns, changes in memory pricing, increased competitor supply, weaker AI spending or a broader technology selloff could trigger significant downside even if the long-term fundamentals remain strong. The biggest danger is assuming that strong fundamentals mean the price can only move higher. At current valuation levels, expectations are already elevated, so the company may need to continue exceeding expectations to maintain strong momentum.
Technically, the 1-hour chart remains constructive. Price is above the major short-term moving averages, with the 7-period average around 1,254–1,262, the 30-period average near 1,232, the 120-period average around 1,219 and the 200-period average near 1,214. This alignment favors the bulls because shorter averages remain above longer averages.
As long as price holds above the 1,214–1,220 area, the medium-term structure remains healthy.
RSI is around 58, showing positive momentum without extreme overbought conditions. This means there is still room for another upside move. A move toward 60–65 combined with a breakout above 1,280 would strengthen the bullish setup. MACD is slightly positive, consistent with consolidation rather than a confirmed reversal. The Bollinger upper band is around 1,278–1,280, while the middle band is near 1,231. Price is therefore near the upper part of its recent range, which makes chasing the market less attractive than waiting for either a confirmed breakout or a controlled pullback. ADX around 19 also suggests that a stronger directional trend has not yet fully developed.
The first major resistance is 1,278–1,281. From 1,262, a move to 1,281 represents approximately +1.5%. A confirmed breakout above this zone could open the way toward the psychological 1,300 level. From 1,262 to 1,300 is approximately +3.0%. If buyers establish 1,300 as support, the next target becomes 1,320, representing approximately +4.6%. A stronger continuation could then target 1,350, around +7.0%, while an extended move toward 1,380 would represent approximately +9.3%.
On the downside, 1,254–1,262 is the immediate pivot. The first important support is 1,231–1,232, around -2.4% from 1,262. This level combines the 30-period moving average and the Bollinger middle band, making it an important area for buyers. Below that, 1,214–1,220 is the critical structural support zone. A decline to 1,214 represents approximately -3.8%. If this area holds and buyers return, the bullish structure remains intact. If 1,214 breaks decisively, the probability of a deeper correction increases.
The next downside zone is 1,201–1,185. A move to 1,201 would represent approximately -4.8%, while 1,185 would be around -6.1% from the 1,262 reference. Losing 1,185 would seriously weaken the current short-term bullish thesis and could indicate that the recent recovery has failed.
For the trading strategy, I would avoid blindly chasing price near the upper resistance. The preferred breakout setup is a confirmed move above 1,280–1,281 with strong momentum and a successful hold. In that scenario, TP1 is 1,300 (+3.0%), TP2 is 1,320 (+4.6%), and TP3 is 1,350–1,380 (+7.0% to +9.3%). Profit should be taken progressively rather than waiting for the final target. If price instead pulls back, the 1,231–1,240 area is the first zone to watch for a bullish reversal. A deeper test of 1,214–1,220 can also become an opportunity if buyers clearly defend the level.
For risk management, SL1 is 1,232, approximately -2.4% from the 1,262 reference.
This is suitable for aggressive short-term trades but may be vulnerable to normal volatility. SL2 is 1,214, approximately -3.8%, and is more suitable for a swing setup because it sits below the major moving-average cluster. SL3 is 1,201–1,195, approximately -4.8% to -5.3%. Because this stop is wider, position size should be smaller. The trader should select one appropriate stop rather than treating all three as simultaneous exits.
The risk-to-reward picture explains why entry timing matters. Entering at 1,262 with SL2 at 1,214 risks roughly 3.8%, while TP1 at 1,300 provides only around 3.0% upside. TP2 improves the reward to approximately 4.6%, and TP3 at 1,350 provides around 7.0%. Therefore, the setup becomes more attractive if the trader waits for a better pullback entry or confirms a breakout before entering. A smaller position with a structurally meaningful stop is preferable to a large position with an extremely tight stop because SK Hynix can easily move several percentage points during normal volatility.
There are three likely scenarios from here. The bullish scenario is a breakout above 1,280–1,281, followed by 1,300 and then 1,320–1,350.
If momentum remains strong, 1,380 becomes possible. The neutral scenario is consolidation between roughly 1,230 and 1,280 while the market digests the recent rally. This would not necessarily be bearish; sideways consolidation can create a stronger base for a later breakout.
The bearish scenario begins with a sustained break below 1,214, opening the possibility of 1,201 and 1,185. Below 1,185, the short-term recovery structure would be seriously damaged.
Over the next 6–12 months, I remain constructive because of SK Hynix's HBM leadership, AI infrastructure exposure, Nvidia-related demand, advanced memory development, large investment plans and aggressive shareholder returns. If AI spending continues expanding and HBM supply remains relatively tight, earnings and margins could remain strong. The main long-term risks are weaker AI capital expenditure, falling memory prices, excess supply, stronger competition and valuation compression.
My overall bias is bullish, but disciplined rather than aggressive. Above 1,280–1,281, the breakout case becomes much stronger, with 1,300, 1,320 and 1,350–1,380 as the main upside roadmap. A pullback toward 1,231–1,240 followed by a strong reversal could provide an even better entry. The most important support is 1,214–1,220. As long as 1,214 holds, I would continue to view weakness primarily as a correction within a broader bullish structure. A decisive break below 1,214 would force a more defensive approach.
Final roadmap: TP1 1,300 (+3.0%), TP2 1,320 (+4.6%), TP3 1,350–1,380 (+7.0% to +9.3%). SL1 1,232 (-2.4%), SL2 1,214 (-3.8%), SL3 1,201–1,195 (-4.8% to -5.3%). My preferred strategy is to wait for either a confirmed breakout above 1,280 or a controlled pullback into strong support. Do not chase every green candle, especially after a 200%+ year-to-date rally. Let the market confirm the direction, keep position size under control and take profits in stages.
Final verdict: SK Hynix remains structurally bullish and is still one of the strongest AI-memory plays, but the market is currently at a critical technical decision point. The fundamentals support higher prices, while the chart demands patience. A successful breakout above 1,280–1,281 could start the next leg toward 1,300, 1,320 and potentially 1,350–1,380.
A healthy pullback toward 1,231–1,240 could offer a better risk-adjusted entry, while 1,214 remains the key level that bulls must defend.
The trend remains favorable, but risk management should come first because this asset can move 5–7% very quickly.
This is a market-analysis framework, not a guaranteed prediction. The 1,262 USDT reference is used for the percentage calculations, while live prices can change rapidly. Unexpected company news, earnings, semiconductor sentiment, AI spending, macroeconomic developments and liquidity conditions can invalidate any technical setup.
repost-content-media
Gate Social | Recruiting Streamers and Creators
One insightful post, one livestream—get your expertise noticed and your creativity rewarded.
🎁 Growth Rewards for New Creators
New streamers can unlock VIP5 trial benefits by going live, while outstanding streamers can earn up to $100 worth of GT in rewards. Content creators can also earn up to 60% in commission through Content Mining.
🔥 Trending Topics, Bonus Rewards
Create posts and host livestreams about NVIDIA’s earnings for the chance to earn NVDA Creator Rewards and the Lucky Copy Trader Prize. Join the Gate Event Contracts Creator Challe
HighAmbition
Gate Social | Recruiting Streamers and Creators
One insightful post, one livestream—get your expertise noticed and your creativity rewarded.
🎁 Growth Rewards for New Creators
New streamers can unlock VIP5 trial benefits by going live, while outstanding streamers can earn up to $100 worth of GT in rewards. Content creators can also earn up to 60% in commission through Content Mining.
🔥 Trending Topics, Bonus Rewards
Create posts and host livestreams about NVIDIA’s earnings for the chance to earn NVDA Creator Rewards and the Lucky Copy Trader Prize. Join the Gate Event Contracts Creator Challenge to win up to 80 USDT in cash, with more themed campaigns and creator rewards launching regularly.
Turn your insights into influence and your creativity into lasting value.
👉 Go live now: https://www.gate.com/zh/live
👉 Create a post: https://www.gate.com/post
repost-content-media
GT-0.71%
NVDA+0.69%
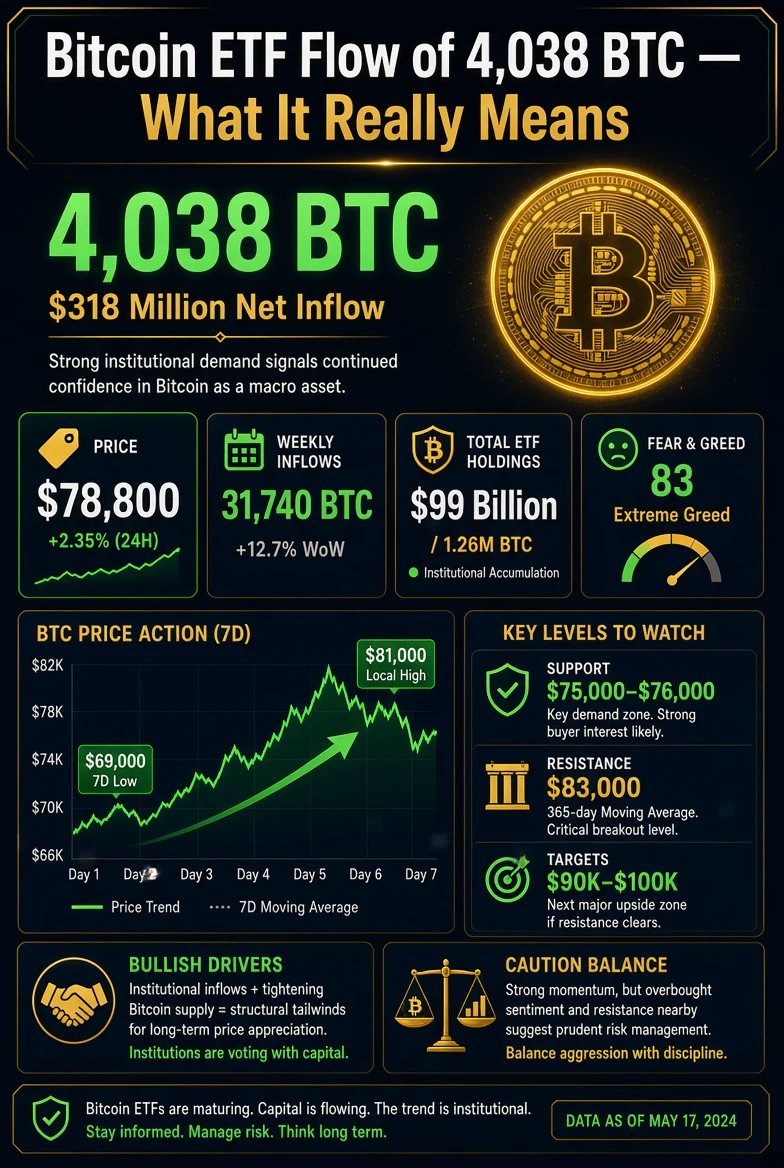
#BitcoinETFNetInflow4038BTC
Title: Bitcoin ETF Flow of 4,038 BTC — What It Really Means for the Next Move
First, let's make sure we understand the number correctly, because a lot of people confuse gross buying with net flow. When we say the U.S. spot Bitcoin ETFs recorded a net inflow of 4,038 BTC, that does not mean 4,038 BTC worth of new money came in and nothing left. It means that after subtracting all redemptions and outflows from the funds on that day, the net change in their Bitcoin holdings was plus 4,038 BTC. At the current spot price around $78,800, that is roughly $318 million of f
HighAmbition
#BitcoinETFNetInflow4038BTC
Title: Bitcoin ETF Flow of 4,038 BTC — What It Really Means for the Next Move
First, let's make sure we understand the number correctly, because a lot of people confuse gross buying with net flow. When we say the U.S. spot Bitcoin ETFs recorded a net inflow of 4,038 BTC, that does not mean 4,038 BTC worth of new money came in and nothing left. It means that after subtracting all redemptions and outflows from the funds on that day, the net change in their Bitcoin holdings was plus 4,038 BTC. At the current spot price around $78,800, that is roughly $318 million of fresh net demand into the product. The latest official print from the institutional data I track shows net inflow of roughly $314 million, which in BTC terms is about 3,990 coins — very close to your 4,038 figure, so the story is consistent whichever way you slice it.
Why does this matter at all? Because spot Bitcoin ETFs are not leverage products; they hold actual Bitcoin. When an ETF issuer receives net new subscriptions, it must go into the open market and buy Bitcoin to back those shares. That is real, unhedged spot demand that physically reduces the supply available to everyone else. So a day of solid net inflow like this is not just sentiment — it is direct buying pressure in the cash market. That is why the flow numbers carry more weight than a random tweet or a single whale wallet.
Now the bigger picture. We are not talking about one isolated day. The weekly picture is much stronger. Net inflows for spot Bitcoin ETFs came in at about 31,740 BTC over the course of last week, which was the strongest weekly inflow since October 2025. To put the scale into context, total assets held by the U.S. spot Bitcoin ETF complex now stand at roughly $99 billion, which is about 1.26 million Bitcoin. That is a massive, sticky pool of institutional capital that only grows when flows turn positive. Against that, a 4,000-coin daily inflow is meaningful but not enormous — it is roughly 0.3% of the total ETF holdings. The message is not that one day is explosive; the message is that the direction of flow has clearly flipped from the heavy outflows we saw in May and June back to sustained inflows.
Where is the price, and what have the flows already done? Bitcoin is trading right around $78,800 at this moment, down about 0.2% on the day but up roughly 13.9% over the past seven days. Let me be specific about the sequence, because it explains a lot. Just over a week ago, Bitcoin was sitting near $69,000. It then rallied through $69,000, broke $72,000, $75,000, and touched as high as about $81,000 this week before pulling back to the current $78,800 range. That is a move of roughly 15% to 17% off the lows, and more than $8,000 to $9,000 in dollar terms within about a week — one of the largest one-week dollar gains on record. The short-term move has been dramatic, and the pullback from the $81,000 high back to $78,800 is only about a 2.7% correction, which is a normal and healthy pause, not a breakdown.
What is driving all of this? The flows did not appear in a vacuum; they are reacting to a macro catalyst. The big trigger was the U.S. Treasury's announcement that it would roughly double its long-dated bond buyback operations — essentially a signal that the Treasury is willing to step into the market to push down longer-term yields. That is significant for Bitcoin for two reasons. First, when long-term government yields are capped and the dollar softens, money tends to rotate into scarce, hard assets. Second, it is a direct response to the fact that 30-year yields have been at their highest since 2007, which has been pressuring risk assets all through the first half of this year. Bitcoin spent months underperforming precisely because of that liquidity squeeze; the buyback signal reverses part of that pressure. Add on top of that positive regulatory momentum — a proposed SEC rule to ease crypto offerings, and the push for the Clarity Act moving toward a Senate vote in September — and you have a clear macro and policy tailwind.
Let me now give you my honest read on what the ETF inflow of 4,038 BTC actually changes, and what it does not change. It does change the supply-demand ledger in the short term: more institutional dollars are committed to holding physical Bitcoin, which tightens floating supply that is not already locked in exchanges or long-term holders. It strengthens the technical setup because sustained inflows tend to absorb selling and put a floor under pullbacks. But it does not, by itself, guarantee a straight line higher. You have to weigh it against a few very real headwinds. The market is short-term overheated. Trader unrealized profit margins have climbed to around 20.5%, the highest level since June 2025, and historically that sort of reading leads some holders to take profit. Short-term holders and newer whales have already started taking profits — they booked about $1.2 billion in realized gains over a few days last week, including a record single-day take of around $614 million. Exchange inflows have also spiked, which usually signals distribution intent rather than accumulation.
So here is the balanced picture. The medium-term case has genuinely improved: flows turned positive, sentiment flipped to Extreme Greed (the Fear and Greed Index is around 83), monthly demand is growing at the fastest pace since late last year, and Bitcoin has reclaimed its key moving averages in just four days — a pattern historically seen near the start of cyclical bull markets, matching echoes of October 2015, April 2020, and October 2023. That is a genuinely constructive signal, and I lean with the view that we are in the early phase of something that could become a new bull market rather than a dead-cat bounce.
But being honest about the near term: one data point does not change the weather. The single critical level to watch is the 365-day moving average, which sits around $83,000. In past cycles, closing above that line has been the "official" confirmation that a bear trend has flipped. Right now Bitcoin is about 5% below it at $78,800. Until we take out and hold above $83,000 on a daily close, we should treat the current move as an encouraging but unconfirmed trend change, and be ready for a possible early-bull correction. The realistic near-term range I see is roughly $76,000 to $83,000: support around $76,000 to $75,500, then the psychological $80,000 level, then the $83,000 confirmation zone overhead.
Now, the forecast question — how high can it go? On the strong side, if the Treasury buyback program is sustained, if the September PCE and CPI prints come in soft, and if the Clarity Act passes, the thesis of easing liquidity plus a shrinking dollar plus real institutional demand could carry Bitcoin well beyond the $83,000 confirmation line. In that scenario, I would map the next meaningful resistance areas at roughly $90,000, then $95,000 to $100,000, and the bulls would talk about a challenge of the all-time high region in the $120,000 to $124,000 zone over a longer horizon. Remember, Bitcoin is still about 36% below its all-time high, which means from $78,800 a return to the highs would be roughly a 55% move — that is a very big ask and would require the macro setup to stay cooperative for months, not weeks. On the weak side, if the buyback turns out to be a one-off, if inflation stays sticky, or if the U.S.-Iran situation escalates into a risk-off event, then Bitcoin could easily retest support near $75,000 to $72,000, and a broken trend would put the $69,000 to $70,000 zone back on the table. My base case is a gradual grind higher with consolidation — I see Bitcoin spending the coming weeks digesting between the mid-$70,000s and low-$80,000s before attempting a real break of $83,000.
On trading strategy, which is where most people lose discipline, let me be practical. If you are already holding or DCA-ing into Bitcoin, the healthy move is to not chase the spike. The market is overheated short-term, and buying right at the top of a 14% weekly move is how you get shaken out on the first pullback. Give the price room to establish a new base. The cleanest tactical setup is to wait for one of two things: either a decisive daily close above the $83,000 moving average — that is your confirmation to add on strength with momentum — or a pullback into the $75,000 to $76,000 support band, which is your lower-risk entry if the trend holds. If you want to be more conservative, scale in: add a small position on strength above $80,000 only if it holds, and add more on a dip rather than all at once. Avoid leverage at the current funding and liquidation environment, because sharp two-way volatility is exactly what wipes out over-leveraged positions; the squeeze on shorts has burned out a lot of that fuel, and what remains is mostly on the side of profit-taking, so you do not want to be the exit liquidity.
My opinion, plainly put: the 4,038 BTC inflow is a bullish data point that strengthens an already-improving case, but it is confirmation of a trend that is still unproven at the $83,000 line, not a green light to go all-in at the top of the week's move. Treat the current rally as early-cycle and constructive, not as a finished bull market. Position accordingly — respect the risk, keep dry powder, and let the price give you the confirmation before you give it your conviction. The real test comes over the next two to four weeks with the inflation prints and the post-Labor-Day liquidity backdrop, and that will tell us far more than any single day's flow figure. Watch $83,000, watch the September PCE read, and watch whether the Treasury actually delivers on the buyback expansion from September 9. Those three things decide whether this is the start of something big or just another bear-market rally.#BTC
repost-content-media
#TopFiveLeaguesPreMatchPredictor
Barcelona vs Athletic Bilbao — My Match Prediction
Barcelona vs Athletic Bilbao is one of those matches where the home advantage, recent form and head-to-head record all point in the same direction. In my opinion, Barcelona have the stronger chance of taking all three points at Camp Nou, and my prediction is Barcelona to win 3-1.
Barcelona started their 2026/27 La Liga campaign in excellent fashion with a dominant 5-0 victory over Elche. Their attacking football looked sharp, with Raphinha, Fermín López and Karim Adeyemi making a strong impact. Athletic Bilbao
HighAmbition
#TopFiveLeaguesPreMatchPredictor
Barcelona vs Athletic Bilbao — My Match Prediction
Barcelona vs Athletic Bilbao is one of those matches where the home advantage, recent form and head-to-head record all point in the same direction. In my opinion, Barcelona have the stronger chance of taking all three points at Camp Nou, and my prediction is Barcelona to win 3-1.
Barcelona started their 2026/27 La Liga campaign in excellent fashion with a dominant 5-0 victory over Elche. Their attacking football looked sharp, with Raphinha, Fermín López and Karim Adeyemi making a strong impact. Athletic Bilbao, on the other hand, suffered a 3-1 defeat against Sevilla in their opening game. Although that match was heavily influenced by an early red card, Athletic still have to face a much stronger attacking side in Barcelona.
The biggest reason behind my Barcelona prediction is their recent dominance in this fixture. Barcelona have won the last six meetings between these teams, scoring 17 goals while conceding only once. Athletic have also struggled to score against Barça, failing to find the net in five of their last six meetings. Barcelona are additionally unbeaten in their last 15 La Liga home meetings with Athletic, which makes Camp Nou a very difficult place for the visitors to get a result.
I also expect Lamine Yamal and Raphinha to be major threats. Barcelona have enough attacking quality to create chances from both wings, while their midfield can control possession and continuously put Athletic under pressure. Another interesting factor is Rodri, with Hansi Flick confirming that the plan is for him to play.
Even if he does not start, his presence could add another level of control to Barcelona's midfield.
However, I don't think Athletic Bilbao should be underestimated. They have dangerous players such as Nico Williams who can cause problems on the counter-attack, and their new coach Edin Terzic will want his team to respond after the disappointing opening defeat. Athletic also have the physical strength and intensity to make the match difficult, especially if Barcelona become too aggressive and leave space behind their defence.
My expected match pattern is Barcelona controlling possession from the beginning, creating several opportunities and eventually breaking Athletic's defensive structure. I expect Athletic to have moments where they threaten Barcelona, but over 90 minutes I believe Barça's superior attacking quality and home advantage will make the difference.
My Final Prediction: Barcelona 3-1 Athletic Bilbao
Winner: Barcelona 🔵🔴
My confidence: 8/10
For me, Barcelona are the clear favourite in this matchup. Athletic can fight and create problems, but considering Barcelona's current momentum, their recent dominance in this fixture and their exceptional home record, I expect the defending champions to start their home campaign with another important victory.
repost-content-media
#GateStockInsightsChallenge +#NVIDIA
NVIDIA Q2 FY2027 Earnings: Is the AI Boom Still Just Getting Started?
NVIDIA’s latest fiscal 2027 second-quarter earnings report has given the AI market another major reason to pay attention. On August 27 Beijing time, NVIDIA (NASDAQ: NVDA) reported quarterly revenue of $96.22 billion, representing a massive 106% increase from the same period last year and 18% growth from the previous quarter. The Data Center business remained the undisputed engine of the company, generating approximately $89 billion in revenue, up 117% year over year and representing arou
HighAmbition
#GateStockInsightsChallenge +#NVIDIA
NVIDIA Q2 FY2027 Earnings: Is the AI Boom Still Just Getting Started?
NVIDIA’s latest fiscal 2027 second-quarter earnings report has given the AI market another major reason to pay attention. On August 27 Beijing time, NVIDIA (NASDAQ: NVDA) reported quarterly revenue of $96.22 billion, representing a massive 106% increase from the same period last year and 18% growth from the previous quarter. The Data Center business remained the undisputed engine of the company, generating approximately $89 billion in revenue, up 117% year over year and representing around 92.5% of total revenue. NVIDIA shares initially closed regular trading at $209.66, down 1.59%, but after the earnings release the stock jumped 4.71% in after-hours trading to $219.53. In my view, however, the most important part of this report was not the quarterly beat itself. It was NVIDIA’s much stronger forward growth signal.
The market has become accustomed to NVIDIA producing spectacular numbers, so another strong quarter alone is no longer enough to completely change investor sentiment. What makes this report different is the company’s indication that fiscal 2028 revenue could grow by approximately 70%. That figure is particularly important because the market had previously been expecting growth closer to 45%. The gap between those two expectations is huge. It suggests that NVIDIA’s management believes the current AI infrastructure investment cycle has significantly more room to run than many investors previously assumed.
NVIDIA’s business structure also tells an important story. Data Center revenue of approximately $89 billion now represents about 92.5% of total quarterly revenue, showing just how deeply AI has become integrated into the company’s financial performance. Gaming and professional visualization together contributed only around $7.2 billion. NVIDIA is no longer simply benefiting from AI as one part of its business; AI infrastructure has effectively become the core of the entire company. This makes NVIDIA’s earnings increasingly important not only for semiconductor investors but also for the broader global technology sector.
Another encouraging signal comes from the composition of Data Center demand.
Hyperscale customers generated approximately $48.71 billion, while AI cloud, industrial and enterprise customers contributed around $40.31 billion. The second category reportedly grew 138% year over year. This is extremely significant because it indicates that AI spending is gradually spreading beyond the biggest cloud companies. If businesses across healthcare, finance, manufacturing, software and other industries continue building AI infrastructure, NVIDIA could benefit from a much wider customer base over the coming years.
The next-quarter guidance adds even more strength to the story. NVIDIA expects fiscal third-quarter revenue of approximately $108 billion, with a 2% upside or downside range. That compares with market expectations of roughly $104.2 billion. Once again, NVIDIA is setting a revenue target above what investors had already priced in. However, the company is also facing supply-side limitations. Memory shortages and higher memory costs remain important constraints. This creates an interesting situation: demand appears extremely strong, but NVIDIA’s ability to fully capture that demand depends partly on the capacity of the wider semiconductor supply chain. If these bottlenecks improve, there could potentially be additional upside to future revenue.
Margins are one area investors should monitor carefully. NVIDIA expects adjusted gross margin of approximately 74% for the third quarter, slightly below the market expectation of 74.77%. Higher component and memory costs could create some pressure even as revenue continues expanding rapidly. Another uncertainty is China, because the current guidance does not include Data Center computing revenue from the Chinese market.
Any change in regulatory conditions could therefore influence future estimates.
The valuation picture is also changing. NVIDIA’s regular-session close at $209.66 gave the company a market capitalization of roughly $5.07 trillion. Yet despite this enormous valuation, the earnings multiple has compressed as profits have grown at an extraordinary pace.
A P/E ratio below 27x, based on the figures presented, looks very different from the valuation environment during earlier stages of the AI rally. This is an important reminder that rapid earnings growth can bring down valuation multiples even when the share price continues moving higher.
Still, investors should not interpret the lower multiple as a guarantee that NVIDIA is cheap.
The market is becoming more focused on return on investment. Hyperscalers are spending hundreds of billions of dollars across AI chips, data centers, networking and power infrastructure. Eventually, investors will want clear evidence that these investments are generating sufficient revenue and profits. If AI monetization keeps accelerating, NVIDIA’s growth story could remain powerful. If customers eventually reduce capital expenditure because returns disappoint, the entire AI semiconductor cycle could face pressure.
Competition is another factor that cannot be ignored. NVIDIA currently has an extraordinary position in AI computing, but AMD, custom AI accelerators developed by major technology companies and future semiconductor architectures are all competing for part of the market. NVIDIA therefore needs to continue delivering faster, more efficient and more powerful platforms while maintaining its software ecosystem advantage. At its current scale, even a small slowdown in execution could have a meaningful impact on investor expectations.
For me, the biggest message from Jensen Huang and the latest earnings report is that AI is increasingly becoming a fundamental computing infrastructure cycle rather than a temporary technology trend. Companies need enormous amounts of computing power to train and operate increasingly sophisticated AI models, and NVIDIA remains one of the primary beneficiaries of that demand.
My outlook remains bullish, but I would avoid treating the earnings report as a guarantee of uninterrupted upside. The $219-$220 area is now an important near-term level after the after-hours jump. If buyers can establish strong support above $220, the next psychological targets could be around $225 and $230. On the other hand, if the post-earnings excitement fades, the $209-$210 area becomes an important support zone, followed by the psychological $200 level.
Overall, I believe this earnings report strengthens NVIDIA’s long-term investment story. $96.22 billion in quarterly revenue, $89 billion in Data Center revenue, 117% Data Center growth and an estimated 70% fiscal 2028 growth rate show that the AI spending cycle still has considerable momentum. The biggest question is no longer whether NVIDIA can grow rapidly; it is whether the company can maintain this extraordinary pace while supply constraints, competition, valuation expectations and AI investment returns become increasingly important.
My personal view: NVIDIA remains one of the strongest AI infrastructure plays in the market.
The earnings report gives the bulls another powerful argument, but at a $5 trillion-plus valuation, investors should expect exceptional execution. In my opinion, the real significance of this report is that NVIDIA has given the market a stronger reason to believe that the AI growth story could extend much further into the future.
#NVIDIAEarnings
repost-content-media
NVDA+0.69%
AMD+1.40%
#WarshJacksonHolePreviewMarketsFocusOnRates
Jackson Hole 2026: Warsh's Debut Speech Has the Whole Market Focused on Interest Rates
The Jackson Hole Economic Policy Symposium begins this week in Wyoming, running from August 27 to 29 under the theme “Financial Innovation: Implications for Payments and Policy.” But the official theme is not what markets are watching. The real focus is Federal Reserve Chair Kevin Warsh, who will deliver his first major Jackson Hole speech on Friday, August 28. Traders across stocks, bonds, currencies, gold and crypto are waiting for one thing: a clearer signal ab
HighAmbition
#WarshJacksonHolePreviewMarketsFocusOnRates
Jackson Hole 2026: Warsh's Debut Speech Has the Whole Market Focused on Interest Rates
The Jackson Hole Economic Policy Symposium begins this week in Wyoming, running from August 27 to 29 under the theme “Financial Innovation: Implications for Payments and Policy.” But the official theme is not what markets are watching. The real focus is Federal Reserve Chair Kevin Warsh, who will deliver his first major Jackson Hole speech on Friday, August 28. Traders across stocks, bonds, currencies, gold and crypto are waiting for one thing: a clearer signal about the future direction of US interest rates.
Warsh took over as Fed Chair on May 22, 2026, succeeding Jerome Powell. His Jackson Hole appearance comes only weeks before the September 15 FOMC meeting, making the speech particularly important. Markets are currently assigning roughly a one-in-three chance, around 33%, to a September rate hike.
That means investors are genuinely divided, and even a small change in Warsh’s language could trigger a major repricing across global markets.
The central problem is inflation. The latest July PCE data, the Federal Reserve’s preferred inflation measure, showed headline inflation around 3.7% year over year, while core inflation remained near 3.3%. Both are still significantly above the Fed’s 2% target. This leaves Warsh facing a difficult balancing act: inflation remains stubbornly high, but economic growth is showing signs of losing momentum.
The federal funds rate currently stands at 3.50% to 3.75% after the Fed held rates steady in late July with a 9-3 vote. The three dissenting officials favored a rate hike, highlighting how divided the committee has become. At the same time, labor-market data has weakened, with one recent payroll report showing a significant contraction in employment. GDP remains positive, but concerns about slower growth and even a possible mild recession are becoming harder for investors to ignore.
The Treasury market is therefore the most important battlefield ahead of Jackson Hole. The 10-year Treasury yield is around 4.67%, while the 2-year yield is near 4.23%. The 30-year yield remains above 5%, around the 5.18%-5.23% area. These elevated long-term yields directly affect mortgages, corporate borrowing, consumer loans and overall financial conditions.
Treasury Secretary Scott Bessent has also entered the picture. The Treasury announced increased buybacks of long-term bonds around August 20 in an effort to improve liquidity and reduce pressure in the long-end of the Treasury market. The move pushed long-term yields lower and contributed to weakness in the dollar while supporting gold and bitcoin. Investors interpreted the intervention as an attempt to ease financial conditions at a time when the bond market was becoming increasingly uncomfortable.
Prediction markets remain skeptical that the pressure will disappear. Kalshi traders have placed roughly 56% odds on the 10-year yield finishing 2026 at or above 4.75%, while Polymarket traders see roughly two-in-three odds of the yield crossing 4.8% at some point this year. The message is clear: even if yields fall temporarily, investors still expect structural pressure to remain.
That brings us to the dollar and gold. The US dollar has recovered part of its recent losses but remains under pressure for August. Concerns about US debt sustainability, Treasury yields and questions surrounding Fed independence have strengthened what traders increasingly describe as the “debasement trade” — moving away from cash and traditional dollar exposure toward scarce or hard assets.
Gold has been one of the biggest beneficiaries. Spot gold is trading around $4,653 per ounce and has gained more than 8% in 2026, with August alone producing a rise of more than 14%. After falling sharply from its earlier peak above $5,300, gold recovered from roughly $4,000 in June toward the $4,650 area. Lower real yields and dollar weakness have helped fuel the rebound.
Jackson Hole could now determine whether that gold rally accelerates or reverses. A hawkish Warsh would likely push yields and the dollar higher, creating pressure on gold. A dovish message could have the opposite effect, encouraging traders to increase exposure to gold as expectations for easier monetary policy and concerns over fiscal sustainability return to the forefront.
Bitcoin is responding to the same macro forces, but with much greater volatility. Bitcoin has recently traded around $78,694 after approaching $79,500 and challenging the psychologically important $80,000 level. It has gained roughly 23% over the past week and around 20.5% over the past month. Yet the broader picture remains volatile: bitcoin is still well below its previous cycle high near $124,753 and suffered a major decline toward the $60,000 area before this latest rebound.
The recent bitcoin rally was closely linked to the Treasury announcement, falling dollar and lower long-term yields. Spot Bitcoin ETFs also attracted roughly $1.6 billion in weekly inflows, while leveraged short positions were squeezed as prices moved higher. Ethereum has also participated in the recovery, trading around $2,486.
This is why Jackson Hole matters so much for crypto. Bitcoin is increasingly trading as a macro asset rather than being driven purely by adoption, technology or ETF flows. Treasury yields, dollar strength and Federal Reserve policy can now move BTC extremely quickly.
If Warsh delivers a dovish message and suggests that rate cuts remain possible, bitcoin and gold could receive another strong boost. A hawkish message could produce the opposite reaction, sending yields and the dollar higher while putting pressure on risk assets. Because bitcoin has already moved sharply higher in a short period, the reaction could be especially aggressive.
So what should investors actually expect from Warsh?
The consensus appears to favor a relatively neutral speech. Around 69% of surveyed fund managers expect Warsh to avoid directly telegraphing the September decision and instead focus on inflation, the Fed’s 2% target, long-term policy principles and central-bank independence. If that happens, the immediate reaction could be limited because the market has already priced in a neutral outcome.
The real opportunity — and risk — lies in the surprise.
A hawkish Warsh could emphasize that inflation above 3% is unacceptable and that the Fed must remain prepared to raise rates if necessary. Such language could push Treasury yields higher, strengthen the dollar and pressure equities, gold and bitcoin.
A dovish Warsh could argue that elevated long-term yields are already tightening financial conditions and doing some of the Fed’s work. If he suggests that the economy’s weakening momentum deserves greater attention, markets could quickly price out some of the expected rate-hike risk. That would likely mean lower yields, a weaker dollar and renewed strength in gold and crypto.
My own view is that Warsh is likely to keep September deliberately open. He has a reputation for being tough on inflation, so he cannot afford to appear complacent while inflation remains above target. But the weakening labor market and slowing economic conditions give him a reason to avoid committing to another hike.
There is also a major political backdrop. The Trump administration has openly pushed for lower rates, while Treasury intervention in the bond market has added another layer of complexity. With the midterm elections approaching, an immediate rate hike would carry significant political sensitivity. Economist Jeremy Siegel has also argued that he does not expect Warsh to raise rates before the midterms.
For traders, that means the speech should be treated as an expectations event rather than a policy decision. The actual decision comes on September 15. Jackson Hole is the signal that could reshape expectations ahead of that meeting.
Key levels will matter. For bitcoin, $80,000 is the immediate psychological resistance. A clean break and hold above that level after a dovish speech could extend the current squeeze higher. A hawkish reaction could send BTC back toward the $74,000-$75,000 area.
Gold faces a similar setup. Support around $4,050-$3,960 and then $3,930 could become important if yields rise sharply. On the upside, a dovish surprise could push gold toward fresh highs above $4,700.
The dollar should also be watched closely. A dovish Fed signal could weaken the dollar and support EUR/USD, while a hawkish surprise could produce a sharp dollar rebound. USD/JPY is particularly sensitive to changes in US rate expectations, so volatility there could be significant.
The biggest mistake would be to trade purely on the headline. The first market reaction after a major Fed speech can be extremely emotional. The more important move often develops later, once traders have had time to digest the full message and compare it with what was already priced into bonds and futures.
That is why position sizing matters. In an event this sensitive, smaller positions and patience can be more valuable than trying to predict the first one-minute candle. The market does not need Warsh to say “cut” or “hike.” Sometimes one sentence about inflation, financial conditions or the labor market is enough to completely change expectations.
My bias is slightly toward the dovish side, mainly because the market has already become increasingly concerned about the possibility of a hike while economic growth is showing signs of stress. A weaker labor market, slower housing activity and elevated long-term yields give Warsh reasons to remain patient. However, his inflation credentials mean I would not ignore the hawkish scenario.
In simple terms, I expect Warsh to try to keep both doors open. He may emphasize that inflation remains a serious problem while also acknowledging that financial conditions are restrictive and growth risks have increased. That approach would leave September undecided and keep volatility elevated.
For bitcoin and gold traders, this creates a fascinating setup. If Warsh sounds dovish, the dollar could weaken, yields could fall and the debasement trade could accelerate. If he sounds hawkish, yields could rise, the dollar could strengthen and the recent gains in BTC and gold could face a sharp correction.
The key lesson is that Jackson Hole is not about predicting the exact words Warsh will use. It is about understanding the difference between expectations and reality. A neutral speech may barely move markets because neutrality is already expected. A small hawkish or dovish surprise, however, could create a much larger reaction.
One speech in Wyoming therefore has the potential to influence the direction of bonds, the dollar, gold, equities and crypto for the remainder of 2026. With inflation still above 3%, the 10-year yield near 4.67%, the 30-year yield above 5%, gold near $4,653 and bitcoin testing $80,000, the market is already positioned for a major reaction.
For me, the message is simple: respect both sides of the trade, watch Treasury yields and the dollar alongside bitcoin and gold, and do not confuse Jackson Hole with the actual rate decision. Friday’s speech is the appetizer. September 15 is the main course.
The market is not waiting for Warsh to give it certainty. It is waiting for one small change in his tone that could tell traders which direction the Fed is most likely to move next.
repost-content-media
#NVIDIAEarnings
NVIDIA Q2 Earnings: The $96.2 Billion Quarter That Proved AI Is Still Just Getting Started
Jensen Huang did it again. On August 26, 2026, NVIDIA (NASDAQ: NVDA) delivered one of the most massive quarters any company has ever printed, and the stock still barely moved. That single fact tells you how extraordinarily high the bar has become for this $5.25 trillion machine. Let me break down the numbers, explain what the market got wrong, map out where the stock is headed, and give you an honest trading game plan I would run from here.
The Numbers That Made History
NVIDIA reported r
HighAmbition
#NVIDIAEarnings
NVIDIA Q2 Earnings: The $96.2 Billion Quarter That Proved AI Is Still Just Getting Started
Jensen Huang did it again. On August 26, 2026, NVIDIA (NASDAQ: NVDA) delivered one of the most massive quarters any company has ever printed, and the stock still barely moved. That single fact tells you how extraordinarily high the bar has become for this $5.25 trillion machine. Let me break down the numbers, explain what the market got wrong, map out where the stock is headed, and give you an honest trading game plan I would run from here.
The Numbers That Made History
NVIDIA reported revenue of $96.2 billion for its fiscal second quarter, which ended July 26, 2026. That is up 106% from the $46.7 billion posted a year earlier, and up 18% sequentially. To put it in perspective, NVIDIA added more revenue in a single quarter than most tech giants earn in an entire year. Wall Street was calling for roughly $92.2 billion, so NVIDIA beat the consensus by about $4 billion, an outperformance of just over 4%.
The engine behind the whole machine is the data center business, which generated $89.0 billion in revenue, up a staggering 117% year over year and up 18% sequentially. That means roughly 92.5% of total company revenue is now flowing from AI infrastructure. Blackwell chips remain in extraordinary demand, and the hyperscalers simply cannot buy enough of them.
Profitability is where NVIDIA truly separates itself from every peer. Adjusted earnings per share came in at $2.22 versus $1.05 a year ago, a jump of roughly 111%. That beat the consensus estimate of $2.09 by about 6%. On a GAAP basis, EPS was $2.46. Gross margins held at a very healthy 75.0% on both GAAP and non-GAAP, proving that NVIDIA is not giving away any pricing power even at massive scale.
On top of all that, the company returned roughly $26 billion to shareholders via buybacks and dividends during the quarter. At a time when many AI-adjacent companies are burning cash at alarming rates, NVIDIA is printing it and handing it back simultaneously. Net income also nearly doubled year over year, reinforcing that this is deeply profitable growth, not revenue for revenue's sake.
Why the Stock Barely Moved
Here is the honest and slightly frustrating part. NVIDIA has now fallen in response to earnings in six of the past eight quarters, including the last four in a row. Despite this blowout beat and strong guidance, the after-hours reaction was muted and the stock slipped slightly. The reason is simple and crucial: the market had already priced in perfection. Trading near $213 to $216 heading into the print, investors had baked in an enormous quarter. When you deliver 106% revenue growth and the stock does not rally, it is not because the news was bad, it is because everyone already knew. There was no surprise premium left to capture.
There is also a legitimate debate weighing on the tape around circular financing, capex sustainability, and whether hyperscalers can keep spending without a slowdown. NVIDIA also lowered its China outlook and did not assume any H20 shipments in guidance, adding a geopolitical overhang. But the core point remains: a stock going flat after a beat this massive is actually a positive long-term setup, because the multiple has compressed while earnings have exploded.
Valuation Is the Gift Nobody Is Talking About
This is where the thesis gets genuinely interesting. NVIDIA trades at roughly 23.6 times forward earnings based on fiscal 2027 consensus EPS of about $9.02. That is essentially in line with the S&P 500 multiple despite the company growing revenue more than 100% year over year. A company doubling its top line should not trade at a market-average multiple. Historically, NVIDIA re-rates to roughly 35 to 40 times forward earnings at year-end.
If NVIDIA returns to a 35 times forward multiple by late 2026, that implies a price near $315. At 40 times forward earnings, the stock would be worth around $360, roughly 67% above current levels. UBS analyst Tim Arcuri sees a path to EPS above $15 in fiscal 2027 and above $20 in fiscal 2028. Wall Street's average twelve-month target is around $305 to $317, roughly 43% to 49% upside. Analyst targets range from a bearish low near $180 to bullish highs of $500 and even $743. Consensus remains firmly Buy with essentially zero sell ratings.
How High Can It Really Go?
If hyperscalers follow through with data center spending projected to exceed $1 trillion in 2027 and scale toward $3 trillion to $4 trillion by 2030, NVIDIA's opportunity could expand roughly fivefold from 2026 levels, supporting a $6 trillion to $8 trillion market cap over two to three years. Near term, a return to 35 times forward earnings puts NVDA near $315. A $6 trillion market cap needs roughly a 14% gain. The aggressive end of the Street sees $500, about 135% upside. Q3 guidance of $108 billion, up about 12.3% sequentially and above the roughly $104.2 billion estimate, shows the engine is not slowing.
My honest outlook: NVDA trades meaningfully higher over the next six to twelve months, with $300 as a realistic first major target and $360 achievable if the market re-rates to historical norms. The base case is a grind higher rather than a vertical spike, because at this size every move requires enormous capital.
The Trading Strategy That Makes Sense
For traders, the muted post-earnings reaction creates opportunity. The stock consolidated in the low $210s after dipping about 5% since the May print. If NVDA holds the $207 to $210 support zone, that is a reasonable swing entry targeting $240 to $250 over the coming weeks as short positioning unwinds, with a stop below $205 keeping risk defined.
For longer-term investors, build positions on weakness and hold through volatility. At 23.6 times forward earnings against 100% plus growth, quality AI infrastructure is on sale. Dips toward $200 to $210 look like accumulation zones. If Q3 confirms the $108 billion guide and data center momentum continues, risk-reward tilts strongly to the upside. The honest risk: if hyperscaler capex disappoints this fall or China restrictions tighten, NVDA could retest $190 to $200 despite strong fundamentals.
My Personal Verdict
I will be direct: NVIDIA is the single most important company in tech right now, and its earnings are a referendum on the entire AI trade. This quarter proved demand is real, margins are intact, and growth is accelerating. The stock falling in response to earnings six of eight times is a behavioral quirk of a market pricing in perfection, not a broken company. The fundamentals are stronger than the price action suggests. I would buy on weakness, stay patient, and hold into next year targeting $300 to $360. The AI buildout is a multi-year infrastructure supercycle, and NVIDIA is the toll road every dollar of capex must cross. This is not financial advice, but owning NVIDIA at 23 times forward earnings is one of the more compelling structural opportunities in years. The next one, three, and five years favor the patient holder.
#GateStockInsightsChallenge +#NVIDIA
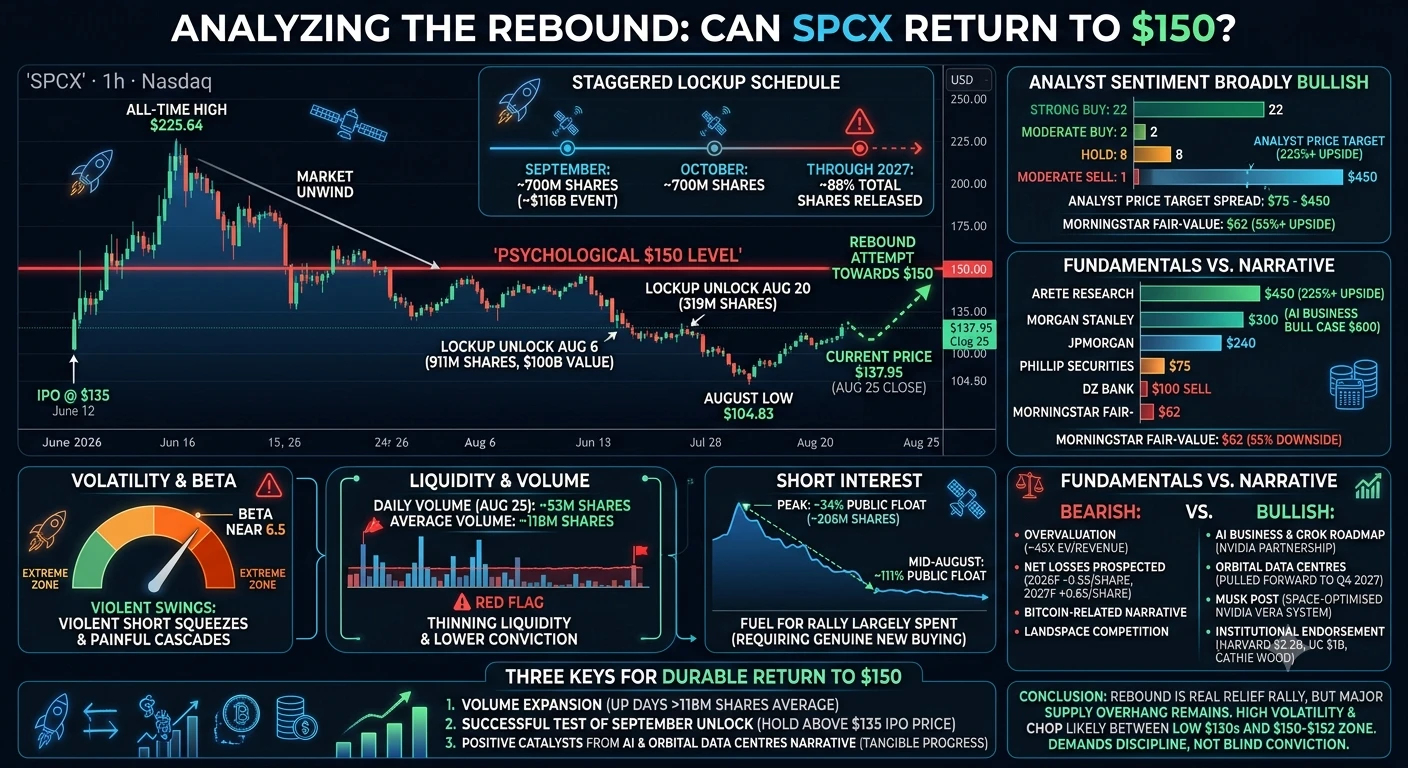
repost-content-media
#GateStockInsightsChallenge +#MRVL
MRVL Earnings Are Coming: Can the AI Chip Rally Last? A Complete Breakdown

Marvell Technology (NASDAQ: MRVL) heads into its fiscal Q2 2027 earnings report on August 27 after the market closes with one of the most explosive setups in semiconductors. The stock has already delivered a jaw-dropping 195.8% rally year to date and a 253.2% gain over the past twelve months, powered by custom AI accelerators, optical networking, and one of the biggest new partnerships in the industry. The real question is whether the momentum can outrun expectations that have grown
HighAmbition
#GateStockInsightsChallenge +#MRVL
MRVL Earnings Are Coming: Can the AI Chip Rally Last? A Complete Breakdown

Marvell Technology (NASDAQ: MRVL) heads into its fiscal Q2 2027 earnings report on August 27 after the market closes with one of the most explosive setups in semiconductors. The stock has already delivered a jaw-dropping 195.8% rally year to date and a 253.2% gain over the past twelve months, powered by custom AI accelerators, optical networking, and one of the biggest new partnerships in the industry. The real question is whether the momentum can outrun expectations that have grown very demanding. Here is the current price, the numbers that matter, the levels to watch, and the realistic scenarios.

CURRENT PRICE AND RECENT SWINGS

As of the latest session heading into earnings, MRVL is trading in the low-to-mid $230 to $240 range, having closed around $240 on a strong up day of roughly 4.8% in final August trading, with a mild pre-market pullback toward $237 to $238 before the print. The 52-week range runs from a low of $61.44 to an intraday high of $329.88, meaning the stock has more than quadrupled off its lows yet still sits roughly 27% below its all-time high. Along the way it has been extremely volatile, at one point giving back about 50% from the highs during an AI-chip sentiment shakeout before staging a powerful recovery. Over the past month MRVL has surged approximately 23%, and after the Google deal announcement on August 19 the stock spiked more than 12% in pre-market trading, peaked near $252, then pulled back to around $230 as investors sold the news and waited for real guidance.

THE GOOGLE DEAL THAT CHANGED THE STORY

The single biggest catalyst is the expansion of Marvell's AI chip relationship with Google. In mid-August, Marvell disclosed it issued Google a warrant to buy up to 58.97 million shares at a strike price of $206.58, roughly 6.7% of shares outstanding and worth about $12.2 billion if fully exercised. The warrant vests based on revenue Marvell generates from custom chip work for Google through fiscal 2033, covering AI accelerators, networking hardware, and memory products; beginning in fiscal Q3 2027, additional tranches unlock for every $500 million in custom product revenue booked from Google. Oppenheimer's Rick Shafer says this validates management's view that custom AI ASIC or XPU sales could double next year to more than $4 billion and exceed $10 billion by calendar 2028. UBS raised its target to $310, then trimmed it to $300, while Susquehanna lifted its target from $230 to $265 just days before earnings.

WHAT WALL STREET EXPECTS FROM THE PRINT

Consensus for the fiscal second quarter calls for revenue of roughly $2.71 billion, up about 35% year over year, and non-GAAP EPS of around $0.93, up about 39%. Management's guidance sits in that range at $2.70 billion plus or minus five percent and $0.93 plus or minus $0.05, and crucially the company has pointed to about $3 billion in quarterly revenue in fiscal Q3, a full quarter ahead of the prior internal outlook. The company has posted five beats and no misses across its last six reports. For the full fiscal year 2027, analysts forecast EPS near $3.07, roughly 42% growth over the $2.16 posted in fiscal 2026. The data center segment, the engine of the story, now accounts for roughly 74% to 76% of total revenue, and that is where custom silicon and optical interconnect demand flows.

THE PRICE MOVEMENT THE OPTIONS MARKET IS PRICING IN

The options market is pricing in a large move in either direction, around 12.4%, translating to roughly a $31 swing. At a base near $251, that implies upside close to $282 and downside near $220. On the bullish side, a strong beat with raised guidance could send the stock toward the $280 to $285 zone. On the bearish side, a modest beat, softer margins, or a slower custom-silicon ramp could trigger a sharp pullback toward $220 or lower, because after a nearly 200% year-to-date rally, valuation leaves almost no room for disappointment.

KEY LEVELS, SUPPORT AND RESISTANCE

For traders framing this with concrete numbers, the near-term technical levels are clear. Immediate support sits in the $234 to $235 area, which has acted as a short-term floor during the pullback off the $252 peak. Below that, the next support is the $222 to $220 zone, aligned with the downside the options market suggests on a disappointing print. The $206 to $208 area, right around the Google warrant strike price, is a psychological and structural floor on any deeper selloff. On the upside, the first resistance is the $252 to $253 peak from the Google deal spike; a decisive break above opens the door to the $265 to $268 zone, where the average analyst target and prior resistance cluster. Beyond that, the $282 to $288 zone is the bull-case earnings target, and the far horizon is the all-time high near $329.88, which several optimistic models see as reachable over a multi-year horizon if the custom AI ramp accelerates as projected.

FORECAST AND PRICE TARGETS FROM THE STREET

The analyst community is decisively bullish. Coverage includes roughly 38 Buy or Strong Buy ratings versus only five holds and zero sells, with an average price target in the $256 to $268 range, implying roughly 11% to 14% upside. More aggressive targets include UBS at $300 and the 24/7 Wall Street model at about $288, while the consensus one-year target is around $266. The valuation is rich, with a trailing P/E near 82 and a forward P/E around 58 to 62, but the market is willing to pay up because the growth runway is exceptional. The stock trades at a premium to peers, with a forward multiple far above Broadcom's roughly 20 times and NVIDIA's roughly 26 times, yet its smaller revenue base means every new chip socket won delivers a disproportionate boost to growth.

TRADING STRATEGY AND NEXT PLANS

This is a high-beta, binary event stock, and the earnings report is genuinely a near-term coin flip even though the long-term thesis is constructive. For long-term investors, dollar-cost averaging into MRVL on any post-earnings dip toward the $220 support or lower has historically been an effective way to build a position in a structural AI winner, given the 42% full-year EPS growth forecast and the Google-owned channel. For swing traders, the prudent play is to wait for the first hour after earnings to see where the stock settles rather than chasing the initial fireworks, and to respect the $220 downside level as a stop on a disappointment. For those already in the name, taking partial profits into any spike toward the $280 to $288 resistance zone is a reasonable way to lock in gains while keeping a core position for the longer-term upside.

HOW HIGH CAN IT GO?

If management delivers on its stated trajectory and the Google custom-chip revenue ramps as projected, the arithmetic supports a path back toward and potentially through the $300 mark over the next twelve months, with the most optimistic street models targeting $310 to $330 on a multi-year basis. The scenarios are three. The bull case, seeing revenue reach $3 billion in fiscal Q3, EPS guidance raised above $3.30, and sustained data center strength, could drive the stock toward the $280 to $300 zone within a few months. The base case, a solid in-line beat with steady guidance, likely keeps the stock in a $240 to $265 trading range as it consolidates enormous gains. The bear case, involving softer margins or a slower custom-silicon ramp, could easily take the stock back to the $220 to $235 shelf, and a severe disappointment could test the $206 to $208 warrant area. In all scenarios the stock will be volatile, so position sizing and a clear plan matter more than any single prediction.

FINAL TIPS AND RISKS TO WATCH

Watch the gross margin trend, because custom silicon deals tend to carry lower margins than standard products, and the market will penalize erosion even on a revenue beat. Watch the data center growth rate and any color on the Google revenue ramp. Watch for new design wins beyond the hyperscaler base, because diversification reduces concentration risk. On the risk side, the stock's beta is roughly 2.25, about twice the market, so broad semiconductor and macro swings will hit MRVL hard. A large part of the year-to-date gain already reflects optimism, and a binary earnings reaction can erase a month of gains in a single day. With a 12.4% implied move, anyone holding through the report should be prepared for meaningful swings in either direction. My honest read is that the long-term AI structural story for Marvell remains intact and constructive, with genuine upside toward the $280 to $300 zone on a strong print, but the immediate window is risky and best handled with position discipline.
repost-content-media
#GateStockInsightsChallenge +#MRVL
$MRVL Earnings Preview: Can the AI Chip Rally Continue After the Google Deal?
$MRVL earnings are finally here, and this is one of the most closely watched AI-chip events of the week. Marvell Technology is scheduled to report fiscal Q2 FY2027 results after the U.S. market close on August 27. The market is not simply looking for a revenue beat anymore. Traders want to know whether Marvell can turn the massive AI opportunity, especially its expanding Google relationship, into stronger future growth and guidance.
At the time of this analysis, I am using the curr
HighAmbition
#GateStockInsightsChallenge +#MRVL
$MRVL Earnings Preview: Can the AI Chip Rally Continue After the Google Deal?
$MRVL earnings are finally here, and this is one of the most closely watched AI-chip events of the week. Marvell Technology is scheduled to report fiscal Q2 FY2027 results after the U.S. market close on August 27. The market is not simply looking for a revenue beat anymore. Traders want to know whether Marvell can turn the massive AI opportunity, especially its expanding Google relationship, into stronger future growth and guidance.
At the time of this analysis, I am using the current MRVL price of around $257. That is important because the stock has already experienced a huge move this year. Marvell has risen roughly 180% year-to-date according to recent market coverage, meaning expectations are already extremely high. The big question is no longer just "Is Marvell growing?" The real question is "Can Marvell grow fast enough to justify the valuation at $257?"
Gate Question 1: Can the AI chip rally continue?
My answer: Yes, but the next leg higher needs confirmation from earnings and guidance.
Marvell is positioned directly inside the AI infrastructure expansion through custom silicon, networking, optical connectivity, memory-related solutions and data-center infrastructure. Its data-center business already represents a very large portion of revenue, while hyperscalers continue investing heavily in AI infrastructure. That gives MRVL a strong fundamental story beyond simply following Nvidia's GPU cycle.
The latest Google agreement makes the story even more interesting. Marvell and Google have a commercial agreement connected to Google's custom semiconductor products. Google received warrants for up to 58.97 million Marvell shares at $206.58, while the agreement could generate as much as $120 billion in custom-product revenue through fiscal 2033 if the relevant conditions are met.
This is a major long-term catalyst, but traders must remember one important point: future revenue is not the same thing as immediate revenue. The market can price future growth very aggressively before the actual earnings arrive.
Gate Question 2: Has the positive news already been priced in?
My answer: A large portion probably has been priced in, but not necessarily all of it.
This is where MRVL becomes interesting.
The stock has already rallied dramatically, and the Google announcement pushed investor expectations even higher. Recent options pricing suggested traders were preparing for a move of roughly 10% in either direction around earnings, with potential levels around $261 on the upside and below $214 on the downside.
That tells us something very important: the market is expecting a big reaction.
If Marvell reports exactly what investors already expect, the stock may struggle to rally because the good news is already reflected in the price. If revenue, EPS and especially forward guidance exceed expectations, however, short-term momentum traders could quickly push MRVL toward new highs.
So I would not treat the Google deal alone as a reason to chase the stock at $257.
Gate Question 3: What are traders expecting from earnings?
Current consensus expectations are around $2.71 billion in revenue and $0.93 adjusted EPS for fiscal Q2 FY2027. Marvell's own guidance was approximately $2.7 billion revenue, plus or minus 5%, and adjusted EPS of $0.93, plus or minus $0.05.
That means simply meeting guidance may not be enough to create a powerful upside move.
The market will be watching three things much more closely:
1. Revenue and EPS beat: A clear beat would strengthen the bullish case.
2. Data-center growth: Investors want evidence that AI infrastructure demand is accelerating rather than simply remaining strong.
3. Forward guidance: This may be the most important factor. A strong quarter followed by conservative guidance could still produce a sell-the-news reaction.
Marvell's previous quarter produced approximately $2.42 billion of revenue, with data-center revenue around $1.83 billion, up 27% year over year.
MRVL Technical Picture at $257
At $257, the stock is entering an extremely important zone.
The first major psychological resistance is $260. This is important because options positioning and market expectations are already concentrated around this area. A decisive breakout above $260 could open the door toward $270, followed by $280-$285.
Above $280, the next major target becomes the $300 psychological level.
And if momentum becomes extreme after earnings, a move toward $315-$330 cannot be ruled out. Marvell's previous 52-week/all-time high has been reported around $329, so that area represents a major supply zone rather than an easy target.
My bullish roadmap would therefore be:
$260 → $270 → $280 → $300 → $315 → $329
But these are resistance/target zones, not guaranteed prices.
Key Support Levels
On the downside, I would watch the following zones:
$250: First short-term support. Holding above this level would keep the immediate bullish structure intact.
$240-$245: Important technical support zone. A move back here after earnings could simply represent profit-taking rather than a complete trend reversal.
$230-$235: Stronger support. Losing this area would indicate that the post-earnings reaction is becoming more serious.
$215-$220: Major downside zone. Options markets have also been pointing toward the low-$210s as a possible earnings reaction area.
$200-$205: Major psychological and structural support. A move this low would significantly damage the short-term bullish setup.
The technical market was showing a generally constructive structure before earnings, with multiple moving averages providing bullish signals, although short-term indicators were more mixed.
RSI: Is MRVL Overbought?
This is another important point.
Recent technical readings around MRVL have placed the RSI(14) near the low-to-mid 50s, depending on the data source and calculation time. That means momentum is positive/neutral rather than sitting in an extreme overbought condition above 70.
That is actually a healthy setup if the earnings report provides another fundamental catalyst.
If RSI moves above 60-70 together with a breakout above $260, momentum traders could become more aggressive.
However, if price pushes higher while RSI fails to confirm the move, traders should watch for bearish divergence and profit-taking.
So I would not use RSI alone to buy or sell MRVL. Earnings guidance, price action and volume confirmation are much more important tonight.
What Is Market Sentiment Saying?
Sentiment is clearly bullish, but it is also crowded.
That distinction matters.
Analyst sentiment remains positive, with recent coverage showing the majority of tracked analysts carrying Buy ratings and an average target around the low-$270s. UBS has also maintained a positive view while lowering its target from $340 to $300.
At the same time, valuation is becoming a serious consideration. Recent analysis highlighted that MRVL is trading at a premium valuation after its enormous rally.
This creates a classic earnings situation:
Good results + strong guidance = potential breakout.
Good results + unchanged guidance = possible sell-the-news reaction.
Weak results or weak guidance = potentially sharp correction.
My MRVL Trading Strategy
Personally, I would avoid putting the entire position into MRVL immediately before earnings.
Why?
Because earnings can produce a gap that ignores normal support and resistance levels.
If I already held MRVL from lower prices, I would consider protecting part of the profit rather than trying to predict the exact top.
For a new position, my preferred approach would be to wait for the reaction.
Bullish Scenario
If MRVL beats expectations and guidance comes in stronger than expected, then I would watch $260 first.
A clean breakout and hold above $260 could target:
$270 → $280 → $300
If $300 breaks with strong volume, the previous high around $329 becomes the larger upside objective.
The key word is confirmation. I would rather buy a confirmed breakout than chase a temporary spike.
Neutral Scenario
If earnings are good but the stock opens around $255-$265 and fails to establish a new high, I would expect consolidation.
In that situation, the better strategy could be waiting for a pullback toward $245-$250 and watching whether buyers defend the area.
Bearish Scenario
If earnings disappoint or guidance is weaker than expected, the first area I would monitor is $240-$245.
If that fails, the next zones become $230-$235 and then $215-$220.
A break below $215 would significantly weaken the short-term bullish structure and could create a deeper retracement toward the $200 area.
How High Can MRVL Go?
My short-term bullish forecast is:
Base bullish target: $270-$280
Strong bullish target: $300
Extreme momentum target: $315-$330
A move from $257 to $300 would represent roughly 17% upside.
A move from $257 to $330 would represent roughly 28% upside.
But the same volatility works in both directions. A fall toward $230 would mean roughly a 10.5% decline, while a move toward $215 would be around a 16% correction from $257.
That is why position sizing matters more than trying to guess one exact number.
Final View
MRVL has one of the strongest AI infrastructure stories in the semiconductor space right now. The Google partnership adds a potentially massive long-term revenue opportunity, while Marvell's exposure to custom AI silicon, networking, optical connectivity and data-center infrastructure gives investors multiple ways to benefit from continued AI spending.
But the stock has already delivered an enormous rally, and expectations are now extremely high.
At $257, I would classify MRVL as bullish but high-risk around earnings.
My most important level is $260.
Above $260 with strong earnings and guidance: $270 → $280 → $300 becomes the bullish roadmap.
Failure around $260 followed by a break below $250: watch $240-$245.
Break below $235: risk increases toward $215-$220.
RSI around the low-to-mid 50s does not currently suggest an extreme overbought condition, but earnings volatility can completely change momentum within minutes.
The biggest lesson for traders is simple: do not trade the headline alone. Trade the reaction to the headline.
Google's partnership is already known. The market now wants proof through revenue, margins, AI demand, bookings and forward guidance.
If Marvell delivers that proof, the AI rally could have another leg higher.
If expectations are too high and management fails to raise the bar, even strong numbers could trigger profit-taking.
For me, the plan is therefore bullish above $260, cautious between $245-$260, and defensive below $240.
repost-content-media
#GateStockInsightsChallenge + #NVIDIA
NVIDIA is entering one of the most important weeks of the year with the stock trading around the $210–$215 zone ahead of its Q2 earnings report scheduled for August 26. NVDA recently pulled back from its 52-week high near $236.54 and closed around $214.72, leaving the stock roughly 9%–10% below its peak while still holding a gain of about 30% from the $164.07 52-week low. The current pullback does not automatically indicate a trend reversal. Instead, price action looks more like consolidation after a strong advance, with the market waiting for the next ma
HighAmbition
#GateStockInsightsChallenge + #NVIDIA
NVIDIA is entering one of the most important weeks of the year with the stock trading around the $210–$215 zone ahead of its Q2 earnings report scheduled for August 26. NVDA recently pulled back from its 52-week high near $236.54 and closed around $214.72, leaving the stock roughly 9%–10% below its peak while still holding a gain of about 30% from the $164.07 52-week low. The current pullback does not automatically indicate a trend reversal. Instead, price action looks more like consolidation after a strong advance, with the market waiting for the next major catalyst.
The fundamental backdrop remains powerful.
NVIDIA continues to benefit from exceptional demand for AI infrastructure, accelerated computing, Blackwell systems and the upcoming Vera Rubin platform. The reported possibility of NVIDIA increasing AI server system prices by more than 15% due to higher memory costs is particularly important because it suggests the company continues to have strong pricing power while AI infrastructure demand remains elevated. Higher system prices could also help protect margins if component costs continue rising.
TECHNICAL STRUCTURE
The daily chart currently shows a short-term correction from $236.54. Price is sitting near a critical technical area because the 200-day moving average is around $211.79. Holding this level would keep the broader bullish structure intact. Meanwhile, the 20-day moving average is around $217.14, the 50-day around $221.25 and the 100-day around $219.97. These moving averages create a significant resistance cluster directly above the current price.
Momentum indicators are relatively balanced. RSI around 51–54 is neutral, meaning NVDA is neither deeply overbought nor oversold. MACD remains above the zero line but has been losing some momentum. Stochastic around 54 and CCI around 17 also indicate a neutral market.
This combination suggests that the stock is waiting for a catalyst rather than showing a confirmed long-term breakdown.
KEY SUPPORT LEVELS
S1: $211–$212 This is the first and most important immediate support zone because it is closely aligned with the 200-day moving average near $211.79. If buyers defend this level and price starts recovering, the bullish structure remains intact.
S2: $205–$206 This is the next major support zone. A decisive daily close below $205 would indicate that sellers are gaining control and could increase the probability of a deeper correction.
S3: $194–$196 This is the major deeper support area. A decline toward this region would represent a substantial correction from current levels and would significantly weaken the short-term bullish setup.
KEY RESISTANCE LEVELS
R1: $218–$219 This is the first major hurdle. It sits around the 20-day moving average and represents the first confirmation level for a recovery. A strong daily close above $219 would be a bullish signal.
R2: $224–$225 This is the next resistance zone.
Breaking above it with strong volume could confirm that buyers have regained short-term control and potentially send NVDA toward $230+.
R3: $236–$237 This is the major breakout level and the recent 52-week high. A decisive breakout above $236.54 could open the door toward fresh highs and substantially higher price targets.
BULLISH SCENARIO
The strongest setup would be NVDA holding $211–$212, reclaiming $218–$219 and then breaking $224–$225. If that sequence occurs with strong volume after earnings, the next major target becomes $228–$230, followed by $236–$242.
A clean break above $236.54 would be particularly significant because it would remove the recent high as resistance and establish a new bullish price-discovery phase. In that scenario, $250 could become the next psychological target, followed by the $260–$270 region.
BEARISH SCENARIO
The main warning signal is a sustained daily close below $211.79. If the 200-day moving average fails to hold, NVDA could move toward $205–$206. Losing $205 would increase the probability of a deeper retracement toward $194–$196.
Therefore, $211 is the key line between short-term bullish continuation and increasing downside risk. Traders should avoid assuming that every pullback is a buying opportunity if the major support structure is broken.
TRADING PLAN
For a bullish setup, traders can watch the $212–$215 region for support, but the stronger confirmation comes from a daily close above $218–$219. Once $219 is reclaimed, the first upside objective is $228, followed by $236–$242.
For a more aggressive breakout strategy, a confirmed move above $224–$225 can provide additional confirmation that momentum is returning. The major breakout confirmation remains above $236.54.
SL1: $210.50 SL2: $204.50 SL3: $194.00
TP1: $228 TP2: $236–$242 TP3: $255–$260
EXTENDED UPSIDE TARGET
If earnings, guidance and AI demand expectations remain exceptionally strong, NVDA could eventually challenge $260–$270 over the coming months. Beyond that, the broader analyst target range around $300+ becomes relevant. However, these longer-term targets should not be treated as guaranteed levels because the stock's valuation and expectations are already elevated.
EARNINGS OUTLOOK
The August 26 earnings report is the biggest immediate catalyst. Strong revenue growth, robust Blackwell demand, positive guidance and evidence of sustained AI infrastructure spending could quickly shift sentiment back toward the buyers. A strong earnings reaction could push NVDA through $219, $225 and potentially toward $236.
On the other hand, even if the headline numbers are strong, weak guidance, margin concerns, supply constraints or softer-than-expected future demand could trigger profit-taking. In that case, $211 becomes the first critical defense, followed by $205 and then $194–$196.
FINAL VIEW
My overall view is cautiously bullish above $211.
The short-term chart is currently in correction consolidation mode, but the medium- and long-term structure remains constructive. The most important confirmation levels are $219, $225 and finally $236.54.
Above $219 → bullish momentum improves.
Above $225 → upside toward $230–$236 becomes more likely.
Above $236.54 → fresh highs and $250+ become possible.
Below $211 → caution increases.
Below $205 → deeper correction risk.
Below $194–$196 → the current bullish structure would face serious technical pressure.
The next few sessions are therefore extremely important. NVDA does not need to immediately reach $250 to remain bullish; the key requirement is that buyers defend the $211–$212 area and eventually reclaim the $218–$225 resistance cluster. If earnings provide a strong catalyst, the path toward $228, $236–$242 and eventually $255–$260 becomes increasingly attractive.
repost-content-media
NVDA+0.69%
#GateStockInsightsChallenge +#BMNR
BMNR MARKET ANALYSIS | CURRENT PRICE: $23.54
BitMine Immersion Technologies (BMNR) is showing strong bullish momentum, but after a sharp rally, the next move needs to be handled carefully. At the current price of $23.54, BMNR is trading near an important breakout zone, while the broader Ethereum rally remains the biggest fundamental catalyst. The company reported 5.85 million ETH holdings worth about $14.3B at the disclosed ETH price, representing approximately 4.8% of total ETH supply. Its total crypto, cash, marketable securities and other strategic holdin
HighAmbition
#GateStockInsightsChallenge +#BMNR
BMNR MARKET ANALYSIS | CURRENT PRICE: $23.54
BitMine Immersion Technologies (BMNR) is showing strong bullish momentum, but after a sharp rally, the next move needs to be handled carefully. At the current price of $23.54, BMNR is trading near an important breakout zone, while the broader Ethereum rally remains the biggest fundamental catalyst. The company reported 5.85 million ETH holdings worth about $14.3B at the disclosed ETH price, representing approximately 4.8% of total ETH supply. Its total crypto, cash, marketable securities and other strategic holdings reached about $14.9B.
BitMine also reported more than 5.06 million ETH staked, with projected annualized staking revenue currently around $330M.
The fundamental story is therefore strongly connected to ETH. If Ethereum continues higher, BMNR can benefit through both the rising value of its treasury and improving market sentiment toward ETH-focused equities. BitMine is also approaching its stated goal of controlling 5% of Ethereum supply, and management says ETH has gained around 30% over the past week.
This creates a powerful catalyst, although it also means BMNR can experience much higher volatility than ETH itself.
From a technical perspective, BMNR has made a significant recovery. The stock recently moved from the $18–$20 area toward $23.50+, with momentum supported by the wider crypto-market rally. Earlier technical data showed the 200-day EMA around $21.91, meaning the move above $22 is important because it shifts the short-term structure into a more bullish phase. RSI was also bullish rather than deeply overbought during the initial breakout, while MACD remained positive.
KEY SUPPORT LEVELS:
$22.00–$22.20 — First major support. Holding this zone would keep the breakout structure healthy.
$20.80–$21.30 — Stronger support and previous resistance area. A pullback toward this region could become a better risk-controlled entry if buyers defend it.
$19.50–$20.00 — Major downside support. Losing this area would weaken the current bullish structure and suggest that the recent rally is losing momentum.
KEY RESISTANCE LEVELS:
$23.90–$24.20 — Immediate resistance. BMNR is currently testing this region, so a clean breakout with strong volume would be an important bullish signal.
$25.00–$26.00 — Psychological and technical resistance zone. A sustained move above $25 could accelerate momentum.
$28.00–$30.00 — Major upside target zone. If ETH remains strong and BMNR breaks $26 convincingly, this becomes the next important expansion area.
$32.00–$35.00 — Extended bullish target. This would require continued ETH strength, strong trading volume and sustained investor demand.
TRADING PLAN:
The safer approach is not to chase a large green candle. If BMNR holds above $22 and then successfully breaks $24 with strong volume, the bullish continuation setup becomes stronger. A confirmed move above $24 can open the path toward $25–$26 first, followed by $28–$30.
For a pullback strategy, the $21–$22 region is more attractive because it provides a clearer risk/reward structure. If price reaches that zone and buyers step in, the setup becomes stronger.
If BMNR loses $20.80 and cannot quickly reclaim it, reducing exposure would be more prudent.
FORECAST:
Base bullish scenario: $25–$26.
Strong bullish scenario: $28–$30.
Extended bullish scenario: $32–$35 if ETH continues its powerful advance and BMNR maintains strong momentum.
A bearish reversal would become more concerning below $20.80, with $19.50–$20.00 becoming the next important area to defend.
TRADE LEVELS:
SL1: $21.80
SL2: $20.80
SL3: $19.40
TP1: $25.00
TP2: $28.00
TP3: $32.00
The key line to watch now is $24. If BMNR breaks and holds above $24, momentum can expand toward $25–$26 and potentially $28–$30. If it repeatedly fails around $24 and falls below $22, expect a consolidation or pullback toward $21–$20.80 before another attempt.
Overall, BMNR remains bullish above $22, while $20.80 is the major structure level. The strongest catalyst is still Ethereum: BitMine's enormous ETH treasury means that sustained ETH strength can directly improve the company's asset value and investor narrative.
repost-content-media
BMNR+1.77%
ETH-1.00%
#GOOG
GOOG is trading near $344.5, having pulled back from its 52-week high of $408.61. Over the recent weeks the stock has fallen roughly 3.8% on heavy volume, breaking below its short-term moving averages. The price sits below the 20-day and 50-day EMAs but remains comfortably above the 200-day EMA near $323.6, which means the longer-term uptrend is still technically intact while short-term momentum has rolled over. The stock currently trades at a P/E of roughly 17.9x, the lowest since 2019, against a business growing revenue about 24% year over year. This valuation gap is why most Street a
HighAmbition
#GOOG
GOOG is trading near $344.5, having pulled back from its 52-week high of $408.61. Over the recent weeks the stock has fallen roughly 3.8% on heavy volume, breaking below its short-term moving averages. The price sits below the 20-day and 50-day EMAs but remains comfortably above the 200-day EMA near $323.6, which means the longer-term uptrend is still technically intact while short-term momentum has rolled over. The stock currently trades at a P/E of roughly 17.9x, the lowest since 2019, against a business growing revenue about 24% year over year. This valuation gap is why most Street analysts remain constructive.
Fundamental Drivers and Price Forecast
The bull case is powered by Google Cloud. Cloud revenue jumped over 60% year over year in Q1 to $20.03 billion, with a massive ~$514 billion backlog and operating margin above 32%. Alphabet also lifted its 2026 capital expenditure guidance to $195–205 billion from $180–190 billion, which spooked the market because free cash flow margin compressed from 21% to roughly 9.2%. The market is selling partly on this capex concern, fearing AI infrastructure spend outruns monetization. However, analysts point out the capex is backed by committed customer infrastructure, including the $15 billion Anthropic campus deal.
Wall Street price targets are optimistic. The consensus sits around $413–427, with individual targets ranging from TD Cowen at $475 down to Bank of America at $370. Bullish firms see GOOG crossing $400 during Q4 2026 to early 2027, with a 12-month projection of about $461, implying roughly 29% upside from the recent lows. The realistic near-term path suggests a move toward $364 first before any substantial breakout, with consolidation likely near that level given overbought RSI readings on shorter timeframes.
Daily Chart Pattern and Key Levels
On the daily chart GOOG is forming a tightening consolidation range after a pullback, with reduced volatility and price compressing above a support cluster near $329–330. This pattern often precedes a breakout attempt. The daily pivot sits near $345, with RSI around 54 (neutral), MACD marginally bullish, while stochastic indicators show overbought signals — a mixed picture that favors range trading until a clear breakout.
Key support levels:
- S1 support at $338.5 (about 1.74% below)
- S2 support at $333.0 (about 3.34% below)
- S3 support at $329.4 (about 4.38% below)
Key resistance levels:
- R1 resistance at $353.8 (about 2.70% above)
- R2 resistance at $364.2 (about 5.72% above)
- R3 resistance at $376.0 (about 9.14% above)
Trading Strategy and Plan
Given the mixed signals, the strategy is: buy on a confirmed reclaim above $346.5 (just above the 10-day average) rather than chasing, with a breakout stop entry near $373.6 for momentum traders. For conservative traders, accumulating near S1–S2 around $338–333 offers a better risk-reward as long as the 200-day EMA at $323.6 holds.
Suggested risk framework with three stops and three targets:
- SL1 (protective stop) at $338.5, about 1.74% risk below current levels
- SL2 at $333.0, about 3.34% risk
- SL3 at $329.4, about 4.38% risk (trip closes the trade if it breaks)
Profit targets:
- TP1 at $353.8, about 2.70% upside
- TP2 at $364.2, about 5.72% upside
- TP3 at $376.0, about 9.14% upside
#GateStockInsightsChallenge
GOOG-1.04%
#GateStockInsightsChallenge +#usdjpy
USD/JPY is trading around 159.60, keeping the pair extremely close to the psychologically important 160.00 area. The short-term structure remains neutral-to-bullish, but this is also a high-risk zone because Japanese intervention concerns and expectations of further Bank of Japan tightening can create sharp reversals. Recent technical analysis has identified 159.54–159.65 as an important breakout area, while 160.50–160.85 is the next major resistance region.
MARKET STRUCTURE & SENTIMENT
At 159.60, USD/JPY bulls still have the advantage as long as price rem
HighAmbition
#GateStockInsightsChallenge +#usdjpy
USD/JPY is trading around 159.60, keeping the pair extremely close to the psychologically important 160.00 area. The short-term structure remains neutral-to-bullish, but this is also a high-risk zone because Japanese intervention concerns and expectations of further Bank of Japan tightening can create sharp reversals. Recent technical analysis has identified 159.54–159.65 as an important breakout area, while 160.50–160.85 is the next major resistance region.
MARKET STRUCTURE & SENTIMENT
At 159.60, USD/JPY bulls still have the advantage as long as price remains above the 158.50 region. A sustained break above 159.65 would strengthen the bullish setup and potentially open the way toward 160.50–160.85. Above 160.85, the next upside targets could extend toward 161.60–162.00 and potentially 162.70+ if momentum becomes strong.
However, traders should not blindly chase the pair near 160. The yen has recently received support from higher Japanese inflation and growing expectations that the BOJ could raise rates again. July Japanese inflation strengthened the case for a possible September hike, while markets are also watching U.S. Federal Reserve signals and Treasury yields.
FUNDAMENTAL PICTURE
The USD/JPY remains supported by the still-large U.S.–Japan interest-rate differential, which keeps the carry-trade argument alive. At the same time, the fundamental gap is becoming less one-sided because Japanese inflation has increased and expectations for additional BOJ tightening are growing. The BOJ held its policy rate around 1.0% at its July meeting, while one policymaker preferred a higher rate.
On the U.S. side, the dollar has recently faced pressure from concerns surrounding Treasury borrowing, buybacks and changing expectations about future Federal Reserve policy. Reuters reported today that the dollar was struggling to maintain recent gains, while the yen strengthened slightly. Investors are also waiting for Federal Reserve Chair Kevin Warsh’s Jackson Hole speech for clues about the future policy path.
KEY SUPPORT LEVELS
Support 1: 159.00–158.90
This is the first area bulls need to defend if the pair starts pulling back from 159.60.
Support 2: 158.50
This is the major short-term structural support. Multiple recent analyses identify 158.45–158.50 as an important pivot. A sustained move below it would weaken the bullish setup considerably.
Support 3: 157.30–157.40
A break below 158.50 could bring this zone into focus. Below it, the market could move toward 156.70 and potentially 155.50.
KEY RESISTANCE LEVELS
Resistance 1: 159.65
This is the immediate breakout line. A strong H1/H4 close above it would be a bullish signal.
Resistance 2: 160.50–160.85
This is the major target zone. Previous technical analysis has repeatedly highlighted approximately 160.50–160.85 as significant resistance.
Resistance 3: 161.60–162.00
If 160.85 breaks decisively, momentum could accelerate toward this area.
Resistance 4: 162.70–163.00
This becomes a higher bullish target if dollar strength remains aggressive. However, intervention risk becomes increasingly important at elevated levels.
BULLISH SCENARIO
The preferred bullish setup is NOT to chase 159.60 blindly. Instead, traders can watch 159.65 closely. If USD/JPY breaks above 159.65 and holds that level on an H1/H4 basis, bullish continuation becomes more attractive.
The first upside objective would be 160.50, followed by 160.85. If 160.85 is broken with strong momentum, 161.60–162.00 becomes the next potential zone.
A successful breakout could therefore produce roughly 0.6%–1.5% additional upside from the current 159.60 area, depending on momentum.
BEARISH / PULLBACK SCENARIO
If price repeatedly fails around 159.65–160.00 and then falls below 158.90, short-term bullish momentum would weaken. A decisive break below 158.50 would be much more important because it could signal that sellers are taking control.
Below 158.50, the next downside area is approximately 157.30–157.40. A deeper yen recovery could then expose 156.70 and eventually 155.50.
TRADING PLAN
Aggressive BUY: Consider only after a confirmed breakout above 159.65. Avoid entering simply because price is already close to 160.
Pullback BUY: A controlled retracement toward 159.00–158.90 followed by bullish price action could offer a better risk/reward entry.
Deep BUY: 158.50 is the major structural level. If buyers defend it strongly, another upside attempt becomes possible.
SELL setup: A rejection from 160.00–160.85 followed by a confirmed break below 158.90 can create a short-term bearish opportunity. A stronger sell signal would come below 158.50.
SL1: 158.90 — aggressive bullish-trade protection
SL2: 158.45 — safer structural protection
SL3: 157.30 — wider protection for a deeper swing setup
TP1: 160.50
TP2: 160.85
TP3: 161.60–162.00
FORECAST
Base case: USD/JPY remains bullish above 158.50 and attempts another test of 160.00.
Bullish breakout case: Above 159.65 → 160.50 → 160.85 → 161.60/162.00.
Bearish reversal case: Rejection around 160.00–160.85 → below 158.90 → 158.50 → 157.30.
The latest technical forecasts similarly point toward 160.68–160.85 as the near-term upside objective if the pair clears the 159.54–159.65 resistance zone.
WHAT ARE TRADERS THINKING?
The market is essentially divided between two forces. USD bulls are watching the interest-rate differential and looking for a breakout through 160. Meanwhile, yen bulls are watching Japanese inflation, possible BOJ tightening and the risk of another intervention if yen weakness becomes excessive. This makes 160 one of the most important psychological battlefields in the current USD/JPY market.
MY VIEW
At 159.60, I would rate the short-term sentiment as NEUTRAL-TO-BULLISH rather than aggressively bullish. The bullish setup becomes much stronger above 159.65, while 160.50–160.85 is the major test.
The best plan is patience: wait for confirmation rather than entering emotionally at 159.60. Above 159.65, look for continuation toward 160.50–160.85. Below 158.50, switch defensive/bearish and watch 157.30.
Most importantly, traders should reduce leverage around 160 because intervention headlines can cause extremely fast moves. The 160 area should be treated as a high-volatility zone, not an ordinary resistance level.
Overall outlook: BULLISH ABOVE 159.65
NEUTRAL BETWEEN 158.50–159.65
BEARISH BELOW 158.50.
repost-content-media
USDJPY0.00%
#GateStockInsightsChallenge +#US500
US500 is sitting at a critical decision zone around 7,650 after pulling back roughly 2.5% from its recent record high above 7,700. The bigger trend is still bullish, but short-term momentum has weakened and the index is now entering a highly event-driven period. PCE inflation, Nvidia earnings and the Jackson Hole Federal Reserve symposium are all arriving within days, meaning volatility can increase sharply in either direction.
The key question now is whether US500 can reclaim the 7,750–7,785 region and restart its record-high breakout, or whether sellers p
HighAmbition
#GateStockInsightsChallenge +#US500
US500 is sitting at a critical decision zone around 7,650 after pulling back roughly 2.5% from its recent record high above 7,700. The bigger trend is still bullish, but short-term momentum has weakened and the index is now entering a highly event-driven period. PCE inflation, Nvidia earnings and the Jackson Hole Federal Reserve symposium are all arriving within days, meaning volatility can increase sharply in either direction.
The key question now is whether US500 can reclaim the 7,750–7,785 region and restart its record-high breakout, or whether sellers push the index below the 7,460–7,400 support area and trigger a deeper correction.
MARKET SENTIMENT
Current sentiment is CAUTIOUSLY BULLISH.
Long-term investors remain constructive because the broader index trend is still upward, corporate earnings remain relatively strong and AI-related capital expenditure continues to support the technology sector. However, short-term traders are becoming more defensive because valuations are elevated, Treasury yields have been rising and several major catalysts are approaching.
The market is therefore not showing the kind of confidence where traders should blindly chase longs. Instead, many traders are waiting for confirmation from price action and upcoming economic data. A strong PCE report could revive expectations for easier monetary policy and support equities, while hotter inflation could push yields higher and increase pressure on US500.
TECHNICAL STRUCTURE
The first important resistance is 7,600. Since the current price is already around 7,650, the index needs to hold above this region rather than simply touch it.
The next major resistance is 7,750–7,785. This is the most important breakout zone. A decisive daily close above 7,785 would significantly strengthen the bullish structure and could open the door toward 7,830 and then the psychological 8,000 level.
Above 8,000, the next major projection zone is approximately 8,025–8,030. If momentum remains exceptionally strong, an extension toward 8,100+ cannot be ruled out, although that would require a powerful continuation of the AI/technology-led rally.
On the downside, 7,578 is the first important support. Below that, 7,460–7,475 becomes much more important because this region represents a major technical convergence zone.
If 7,460 breaks decisively, 7,400 becomes the next target. A sustained move below 7,400 would weaken the medium-term structure and increase the probability of a move toward 7,250.
The major deeper support is around 7,080–7,100. This is the zone where longer-term buyers could become much more aggressive if a larger correction develops.
KEY RESISTANCE LEVELS
R1: 7,700
R2: 7,750–7,785
R3: 7,830
R4: 8,000–8,030
Extended target: 8,100+
KEY SUPPORT LEVELS
S1: 7,600
S2: 7,578
S3: 7,460–7,475
S4: 7,400
S5: 7,250
Major support: 7,080–7,100
BULLISH SCENARIO
The strongest bullish setup would be a sustained move above 7,750–7,785. If US500 closes firmly above this region and buyers maintain momentum, the previous high can come back into focus.
The upside roadmap would then be:
7,785 → 7,830 → 8,000 → 8,030.
A move from 7,650 to 8,000 represents approximately 4.6% upside. A move toward 8,030 would represent roughly 5.0% from the current level.
If 8,030 breaks with strong volume and improving market sentiment, the next psychological target could be 8,100+, but traders should avoid assuming that this will happen immediately.
BEARISH SCENARIO
The bearish setup begins if US500 loses 7,578 and sellers gain momentum.
A stronger warning signal would be a decisive break below 7,460. That could send the index toward 7,400 and potentially 7,250.
If 7,400 also fails on a daily closing basis, the correction could become substantially deeper, with 7,080–7,100 becoming the major downside area.
Therefore, 7,460–7,400 is the key battlefield for bears and bulls. Holding above it keeps the broader bullish structure alive; losing it would materially change the short-term outlook.
TRADING STRATEGY
The best strategy at 7,650 is patience rather than emotional buying.
For aggressive traders, a bullish continuation setup can be considered only after confirmation above 7,750–7,785.
For pullback traders, the 7,600–7,578 area can be monitored for signs of buyers returning.
For stronger risk/reward opportunities, 7,460–7,475 is a much more important support zone, provided price action confirms that buyers are defending it.
If price reaches 7,750–7,785 but repeatedly fails to break higher, traders should be careful because a rejection could produce another pullback toward 7,600 and 7,578.
SL1: 7,575 — aggressive long setup
SL2: 7,455 — structural long protection
SL3: 7,385 — wider swing protection
TP1: 7,750
TP2: 7,830
TP3: 8,000–8,030
For a breakout trade, traders should consider moving the stop toward breakeven after TP1 rather than allowing a profitable position to turn into a loss.
MACRO CATALYSTS
The biggest short-term catalyst is inflation. A softer PCE reading could reduce pressure on yields and support risk assets, while a hotter-than-expected number could increase concerns about restrictive Fed policy.
Nvidia earnings are another major factor.
Because Nvidia and other mega-cap technology companies carry substantial weight in the index, a strong earnings report and positive forward guidance could provide a powerful boost to US500. Conversely, a weak outlook could pressure the entire technology sector and potentially accelerate the index correction.
Jackson Hole is the third major catalyst. Any meaningful shift in Federal Reserve communication regarding inflation, interest rates or future monetary policy could create a significant move in Treasury yields and equities.
WHAT ARE TRADERS WATCHING?
Traders are essentially watching three things: yields, technology stocks and the 7,750–7,785 resistance zone.
If yields stabilize, Nvidia delivers strong results and US500 breaks 7,785, the probability of a renewed bullish move increases significantly.
If yields rise, Nvidia disappoints and US500 loses 7,460–7,400, traders are likely to become much more defensive.
FORECAST
My base-case forecast is cautiously bullish while US500 remains above 7,400.
Short-term expected range: 7,400–7,785.
Bullish breakout target: 7,830.
Major upside target: 8,000–8,030.
Extended bullish target: 8,100+.
Correction targets: 7,250 and then 7,080–7,100.
The most important level to watch is 7,750–7,785 on the upside and 7,460–7,400 on the downside.
MY TRADING VIEW
At 7,650, I would not aggressively chase the market in either direction. The risk/reward becomes much clearer after confirmation.
Above 7,785: bullish continuation becomes the preferred setup, targeting 7,830 and potentially 8,000–8,030.
Between 7,578 and 7,785: expect consolidation and headline-driven volatility.
Below 7,460: caution increases substantially.
Below 7,400: bearish correction toward 7,250 becomes more likely.
Around 7,080–7,100: major long-term support becomes interesting again if the market experiences a larger selloff.
Overall sentiment: CAUTIOUSLY BULLISH.
The bigger trend has not been destroyed by the recent pullback. The market is simply testing whether buyers have enough strength to push US500 back toward record highs. The next major move should be decided by the combination of PCE inflation, Nvidia earnings, Treasury yields and Federal Reserve communication.
The key lesson for traders this week is simple: do not trade the headline, trade the confirmation. Let price prove the direction, control leverage, protect capital and avoid oversized positions immediately before major economic releases.
US500 remains bullish above 7,400, becomes significantly stronger above 7,785, and enters a much more serious correction phase below 7,400.
repost-content-media
US500+0.01%
NVDA+0.69%