#英伟达股价新高 #OneGate见证计划 NVIDIA Hits Another All-Time High: Behind Its $5.76 Trillion Market Cap, Is AI Truly Booming or Just a Bubble?
When computing power becomes the oil of a new era, whoever controls the refineries controls the pricing power.
Three months ago, Wall Street was still collectively “pouring cold water” on NVIDIA. In the summer of 2026, claims that the “AI bubble is about to burst” were everywhere. NVIDIA’s stock price retreated from its May record high, wiping out as much as approximately $1 trillion in market value. “Big Short” investor Michael Burry’s doubts, first raised at the beginning of the year, continued to gain traction, while debate over whether AI capital expenditures could generate returns grew increasingly heated.
And then?
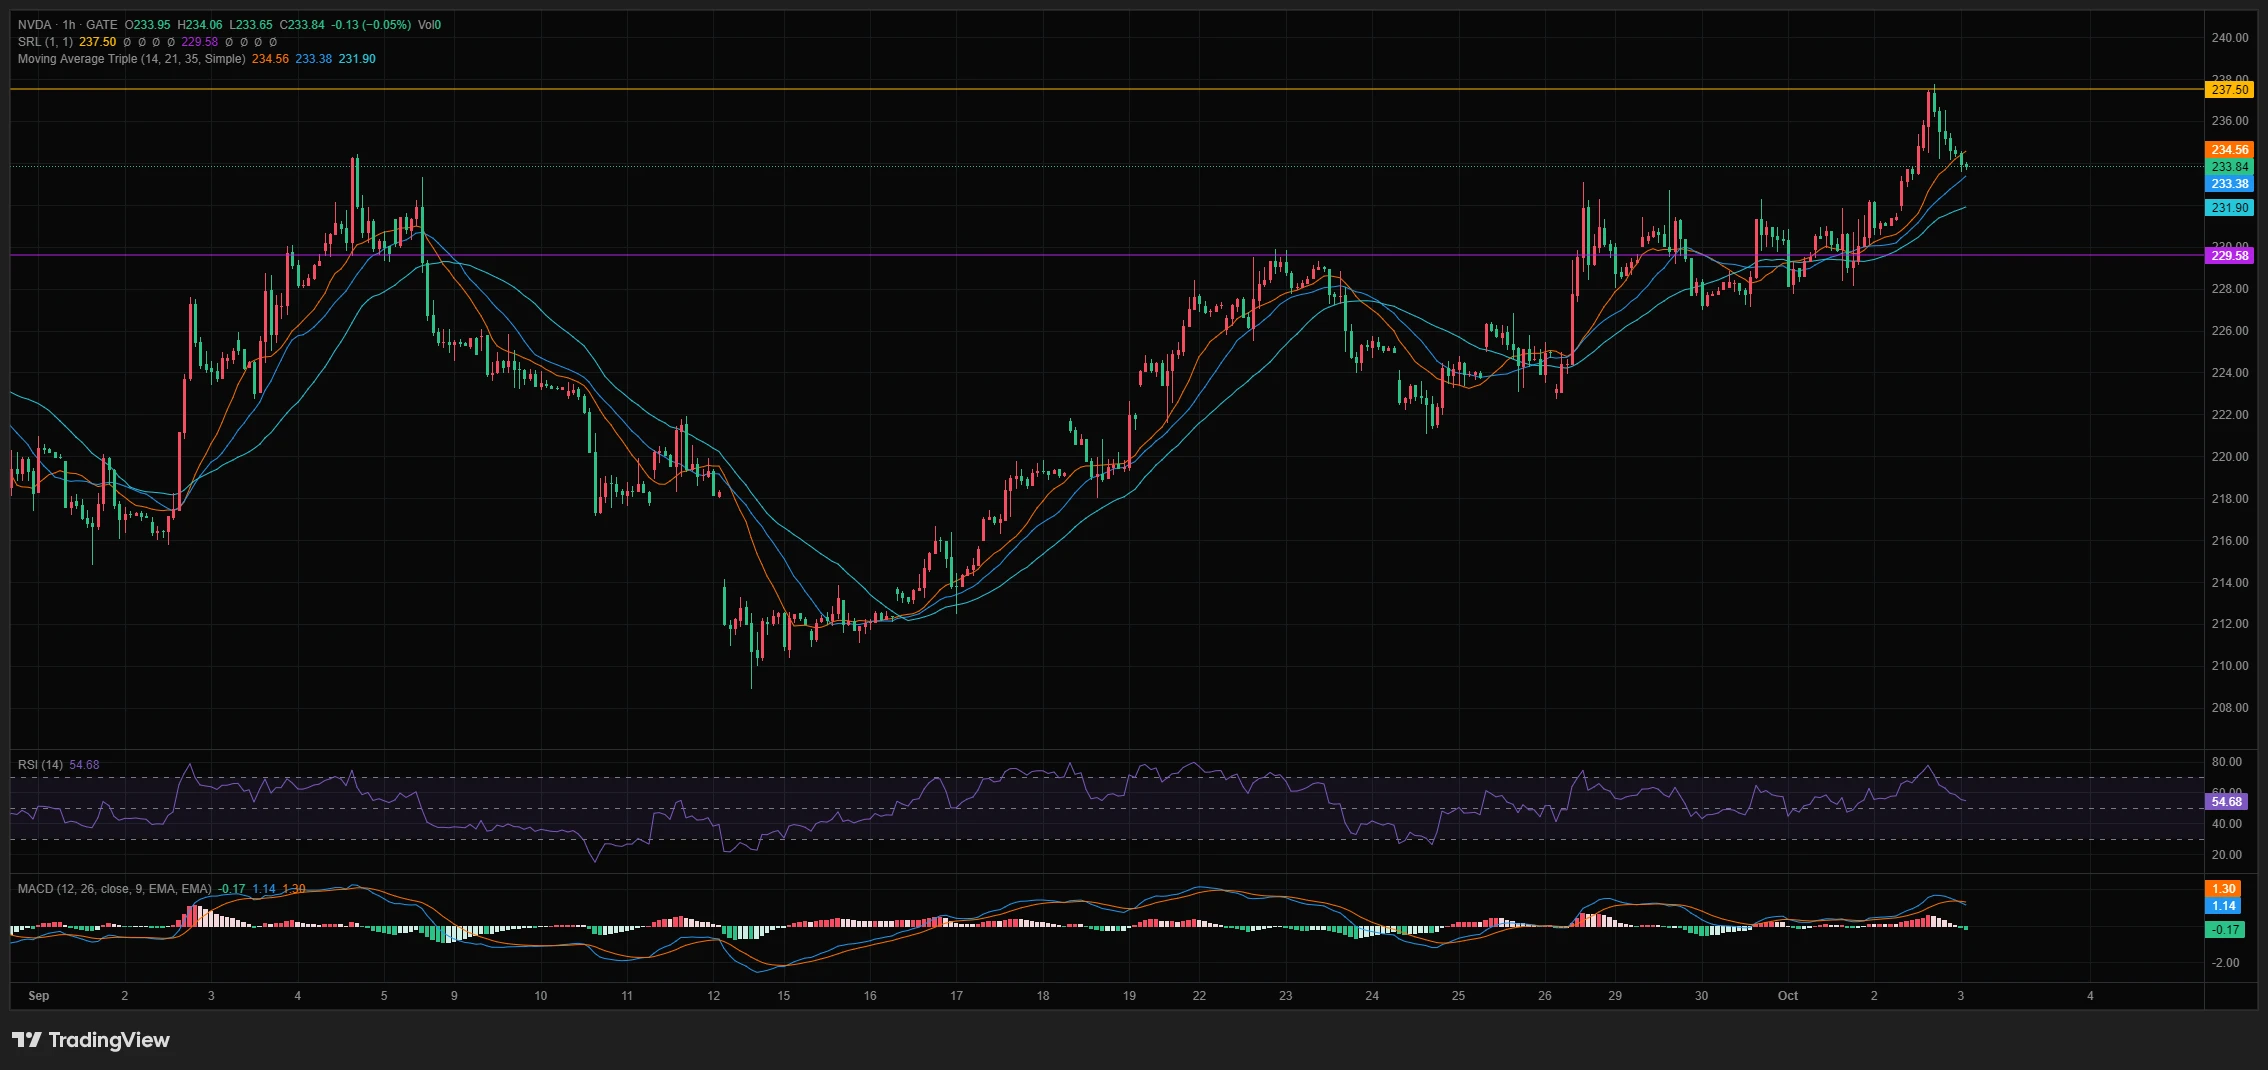
On October 5, U.S. Eastern Time Monday, NVIDIA closed at $238.90, up 2.12% on the day. It broke decisively above its May high during the session, with the closing price reaching a new all-time high. Its total market capitalization reached $5.76 trillion, firmly holding the top spot among publicly listed companies worldwide. It is now only approximately $230 billion away from $6 trillion—the threshold no company in human history has ever reached.
From wiping out $1 trillion to returning to its peak, it took less than one quarter. This is not the first time. Over the past three years, NVIDIA has faced a trial over the “bubble” almost every six months, then responded to the doubts with an earnings report.
But this time, the focus of the debate has changed. People are no longer asking whether “AI is real,” but rather: when a company earns more in one quarter than many countries produce in GDP in an entire year, where exactly is its ceiling?
01 From Wiping Out $1 Trillion to Returning to Its Peak: What Happened Over These Three Months
To understand the significance of this new high, we first need to look back at how dramatic the past few months have been. On May 14 this year, NVIDIA had just set a record closing high of $235.74, with market sentiment still at a boiling point. But once July arrived, the wind suddenly changed.
There were several triggers:
First, “Big Short” investor Michael Burry publicly raised doubts as early as February: NVIDIA’s purchase obligations had surged from $16.1 billion a year earlier to $95.2 billion. This meant NVIDIA had placed a large number of non-cancellable orders before demand had become clear. By summer, this logic was repeatedly cited and continued to gain traction in the market.
Second, earnings reports from major customers such as Amazon and Meta showed that free cash flow had either plunged or stagnated. The market began to worry: could these technology giants actually earn back the hundreds of billions they were spending on GPUs?
Third, monetization on the AI application side had consistently lagged behind capital expenditures on the hardware side, and doubts over “circular financing” grew louder—especially after NVIDIA announced in August that it would establish a computing-power financing platform exceeding $500 billion together with Apollo, BlackRock, Blackstone, Goldman Sachs, KKR, and other institutions.
Combined with external disruptions such as heightened geopolitical tensions in the Middle East, multiple pressures drove NVIDIA’s stock below $190 at one point in late July, a retreat of approximately 20% from its May high and a loss of approximately $1 trillion in market value. At that time, the “AI bubble” thesis was Wall Street’s most politically correct conclusion. The turning point came on August 26. After the market closed that day, NVIDIA released its second-quarter fiscal 2027 earnings report—the figures were explosive, and the stock rose approximately 5% after hours at one point. Then came what we are seeing now: the stock steadily recovered its losses, broke above its May high on heavy volume on October 5, and closed at a record $238.90, with its market capitalization climbing above $5.76 trillion. The Nasdaq index also hit an all-time high that day. From “the bubble is about to burst” to a record high, the script reversed faster than many had imagined. Every row of glowing racks is an AI factory processing Tokens.
02 Earning $59.69 Billion in One Quarter: Just How Astonishing Are These Numbers?
Let’s start with a set of figures to get a feel for what an “AI money-printing machine” looks like. NVIDIA’s core figures for the second quarter of fiscal 2027, ended July 26, 2026: total revenue of $96.22 billion, up 106% year over year and 18% quarter over quarter. Net profit of $59.69 billion, up 126% year over year. Gross margin of 75%—what does that mean? Apple’s gross margin is approximately 45%, while TSMC’s is approximately 55%. For a chipmaker to achieve a 75% gross margin means its products are in no danger of going unsold, and it has complete control over pricing.
But what is truly astonishing is the structure of its data-center business. Data-center revenue was $89 billion, up 117% year over year and 18% quarter over quarter, accounting for more than 90% of total revenue. Its revenue in a single quarter exceeds the annual revenue of many technology companies.
Breaking it down: hyperscale cloud service providers—major customers such as Google, Microsoft, and Amazon—contributed $48.7 billion, up 102% year over year. AI cloud, industrial, and enterprise customers contributed $40.3 billion, up 138% year over year. Note the second figure: enterprise and AI cloud customers are growing faster than hyperscalers.
What does this mean? It means demand for AI computing power is expanding from “a handful of technology giants spending heavily to build the foundation” to more industries and more companies. Demand is not narrowing; it is broadening. The core driver of this growth cycle is the ramp-up in shipments of chips based on the Blackwell Ultra architecture. At the same time, the next-generation Vera Rubin platform has entered full-scale mass production and will be deployed by partners including CoreWeave, Google Cloud, Microsoft Azure, Oracle OCI, and Nebius.
Simply put: the old products are still selling, while new products are already coming online.
Even more striking is the guidance: the company expects third-quarter revenue to reach $108 billion (±2%)—putting quarterly revenue above the $100 billion mark for the first time. Jensen Huang said on the earnings call that AI has reached an “inflection point” and that “computing power is being converted into revenue.” At the Goldman Sachs TMT conference in September, he put it even more directly: “The 70% revenue growth target we provided is a supply ceiling, not a demand ceiling.” In other words: it is not that the market does not want more chips; we simply cannot manufacture them fast enough. This is the underlying logic behind the stock’s continued rise—demand exceeds supply.
03 Bubble or Golden Age? Wall Street Is Divided
Every time NVIDIA hits a new high, the debate returns. But this time, the arguments on both sides are sharper than ever.
Let’s first look at the bullish case.
Hou Wey Fook, DBS Group’s chief investment officer, said publicly on October 5 that NVIDIA’s forward price-to-earnings ratio for the next 12 months was only 17x, while the market expected its earnings growth next year to remain at 70%. He compared it with the internet bubble: Cisco’s P/E ratio was approximately 100x before the bubble burst. “If NVIDIA is defined as the representative company in the AI sector and its current P/E ratio is only in the teens, how can this be called a bubble?”
Morgan Stanley maintained its “Overweight” rating on NVIDIA in its latest report on October 5, with a $300 price target, and once again listed it as its top pick in the semiconductor industry. Morgan Stanley also estimated that the 70% growth guidance reflected supply constraints, while actual demand growth was close to doubling.
Jensen Huang’s own statement was even more direct. At the Goldman Sachs TMT conference on September 10, he directly responded to the “circular financing” doubts: “I looked at the financial statements. We put in $1 and get back a $100 return. Is that circular financing? If it is, then we should do more.” He also emphasized that before investing, the company confirms that the recipient has genuine contracts. The total value of such high-confidence contracts he had seen had reached $100 billion. By 2030, the AI infrastructure market will reach $3 trillion to $4 trillion.
The concerns on the bearish side are not entirely without merit.
The first concern: the surge in purchase obligations. Michael Burry pointed out that NVIDIA’s purchase obligations had jumped from $16.1 billion a year earlier to $95.2 billion. His logic was that such a large volume of non-cancellable orders showed NVIDIA was betting on demand that had not yet been validated. Notably, the latest earnings report showed that NVIDIA’s long-term supply commitments had expanded further to approximately $279 billion, compared with only $119 billion one quarter earlier, primarily related to memory purchases.
The second concern: major customers’ cash flow. Companies such as Amazon and Meta, which are buying GPUs most aggressively, are all facing pressure on free cash flow. If they cannot earn back the money spent on chips, how long can this demand chain continue?
The third concern: monetization on the AI application side. Billions have been invested in hardware, but how many companies have actually made money from AI applications? Most AI startups are still in the cash-burning phase.
On the surface, this debate is about whether NVIDIA is expensive. In reality, it can be broken down into two deeper questions:
First, is AI infrastructure construction a decade-long cycle or a three-year bubble? Huang’s view is that it is “one of the largest infrastructure build-outs in human history,” measured in decades. Goldman Sachs also characterizes this cycle as an “investment supercycle” rather than a bubble. But history tells us that in every technological revolution, some people ultimately mistake a long-term trend for short-term performance and pay the price.
Second, when one company accounts for such a large share of global technology stocks, who bears the concentration risk? NVIDIA’s market capitalization is larger than that of the entire stock market in many countries. Its weighting in the Nasdaq index is rising.
This means that if something goes wrong at NVIDIA, the entire broader market will be shaken. It is still too early to draw a conclusion. But one thing is certain: this is not a story that can be simply summarized as either a “bubble” or a “golden age.”
04 Why This Is More Than Just a Single Company’s Stock Price Story
Many people view NVIDIA merely as a stock or an investment asset. But if you broaden your perspective, you will find that NVIDIA’s significance goes far beyond that. Huang has recently been repeatedly discussing a concept called the AI factory. He redefines the modern data center as a factory, with GPUs as the production machines and Tokens—the smallest computational units that generate code, generate content, and power AI applications—as the factory’s products. “Every Token is profit,” he said. What does this mean? It means AI has evolved from a concept in the laboratory into an industry that is already making money. Just as electricity entered factories 100 years ago and oil powered the entire industrial system 50 years ago, computing power is becoming the basic energy of a new era. And NVIDIA is the company selling the “refining equipment.” Huang himself has compared NVIDIA’s position in the AI supply chain with that of TSMC. The analogy is accurate: TSMC does not make phones or computers, but all chips must pass through its factories; NVIDIA does not build foundation models or applications, but nearly every AI company builds its business on NVIDIA’s platform. In an industrial chain, the most profitable player is often not the end brand, but the link that controls the core bottleneck. That is why NVIDIA can achieve a 75% gross margin—it has the entire AI industry by the throat. For ordinary people, the significance is that AI is no longer an abstract concept floating in the sky. It is becoming infrastructure like water, electricity, and oil, penetrating every industry. You may not buy NVIDIA stock, but every AI tool you use, every automated process you encounter at work, and every piece of AI-generated content you see is supported by computing costs. And behind those computing costs stands NVIDIA. That is why its stock price is not merely a Wall Street matter—it is a barometer of the entire AI industry’s health.
05 What Really Deserves Attention Next
It is too early to declare that the “AI bubble has burst” or that “NVIDIA will rise forever.” The following key milestones will be the variables that truly determine the direction:
First, the guidance in the next earnings report. In late November, NVIDIA will release its third-quarter fiscal 2027 earnings report. The market is watching not only how much the company earns in the quarter, but also whether its guidance can be delivered. The company has already forecast Q3 revenue of $108 billion. If management continues to raise expectations, it would show that demand is indeed strong; if it begins to take a more conservative stance, caution will be warranted.
Second, the pace of capital expenditures by major customers. NVIDIA expects capital expenditures by the five largest cloud providers to rise from approximately $800 billion this year to $1.3 trillion next year. Whether customers such as Google, Microsoft, Amazon, and Meta change their capital expenditure plans will directly determine NVIDIA’s order visibility.
Third, the production ramp-up of Vera Rubin. The next-generation platform has just entered full-scale mass production. Whether the ramp-up proceeds smoothly, how yields perform, and how quickly customers deploy the platform will determine the 2027 growth curve. Fourth, the $6 trillion threshold. It is now only approximately $230 billion away from $6 trillion. Whether it breaks through, and when, will become a landmark psychological milestone. No company in history has ever reached this level.
Fifth, the variable of the Chinese market. Export controls have always been a sword hanging over NVIDIA. The latest earnings report showed that shipments of data-center products to China accounted for less than 1%. The impact appears limited, but any policy change could cause short-term volatility.
Any inflection point in any one of these variables could alter the market consensus that currently prevails.
Every time NVIDIA hits a new high, it is accompanied by a debate over how “this time is different.” Some say it is the oil giant of a new era; others say it is the next Cisco—the king of the internet bubble era. After the bubble burst, Cisco’s stock price fell nearly 90%, and it then took a full 26 years, until 2026, to return to its 2000 high. History does not simply repeat itself, but it always rhymes.
Is NVIDIA today standing at the beginning of a decade-long supercycle, or on the eve of a bubble bursting? No one can provide a definitive answer. But at least one thing is clear: AI is no longer a question of whether to “believe in it,” but an industrial trend that is already redistributing wealth on a trillion-dollar scale. As for whether NVIDIA can remain at the top of the pyramid, time will provide the answer. $NVDA