
#美股AI概念股全线反弹 #Gate广场中秋团圆局 The Fed’s rate hike is delivered, and U.S. tech stocks explode!
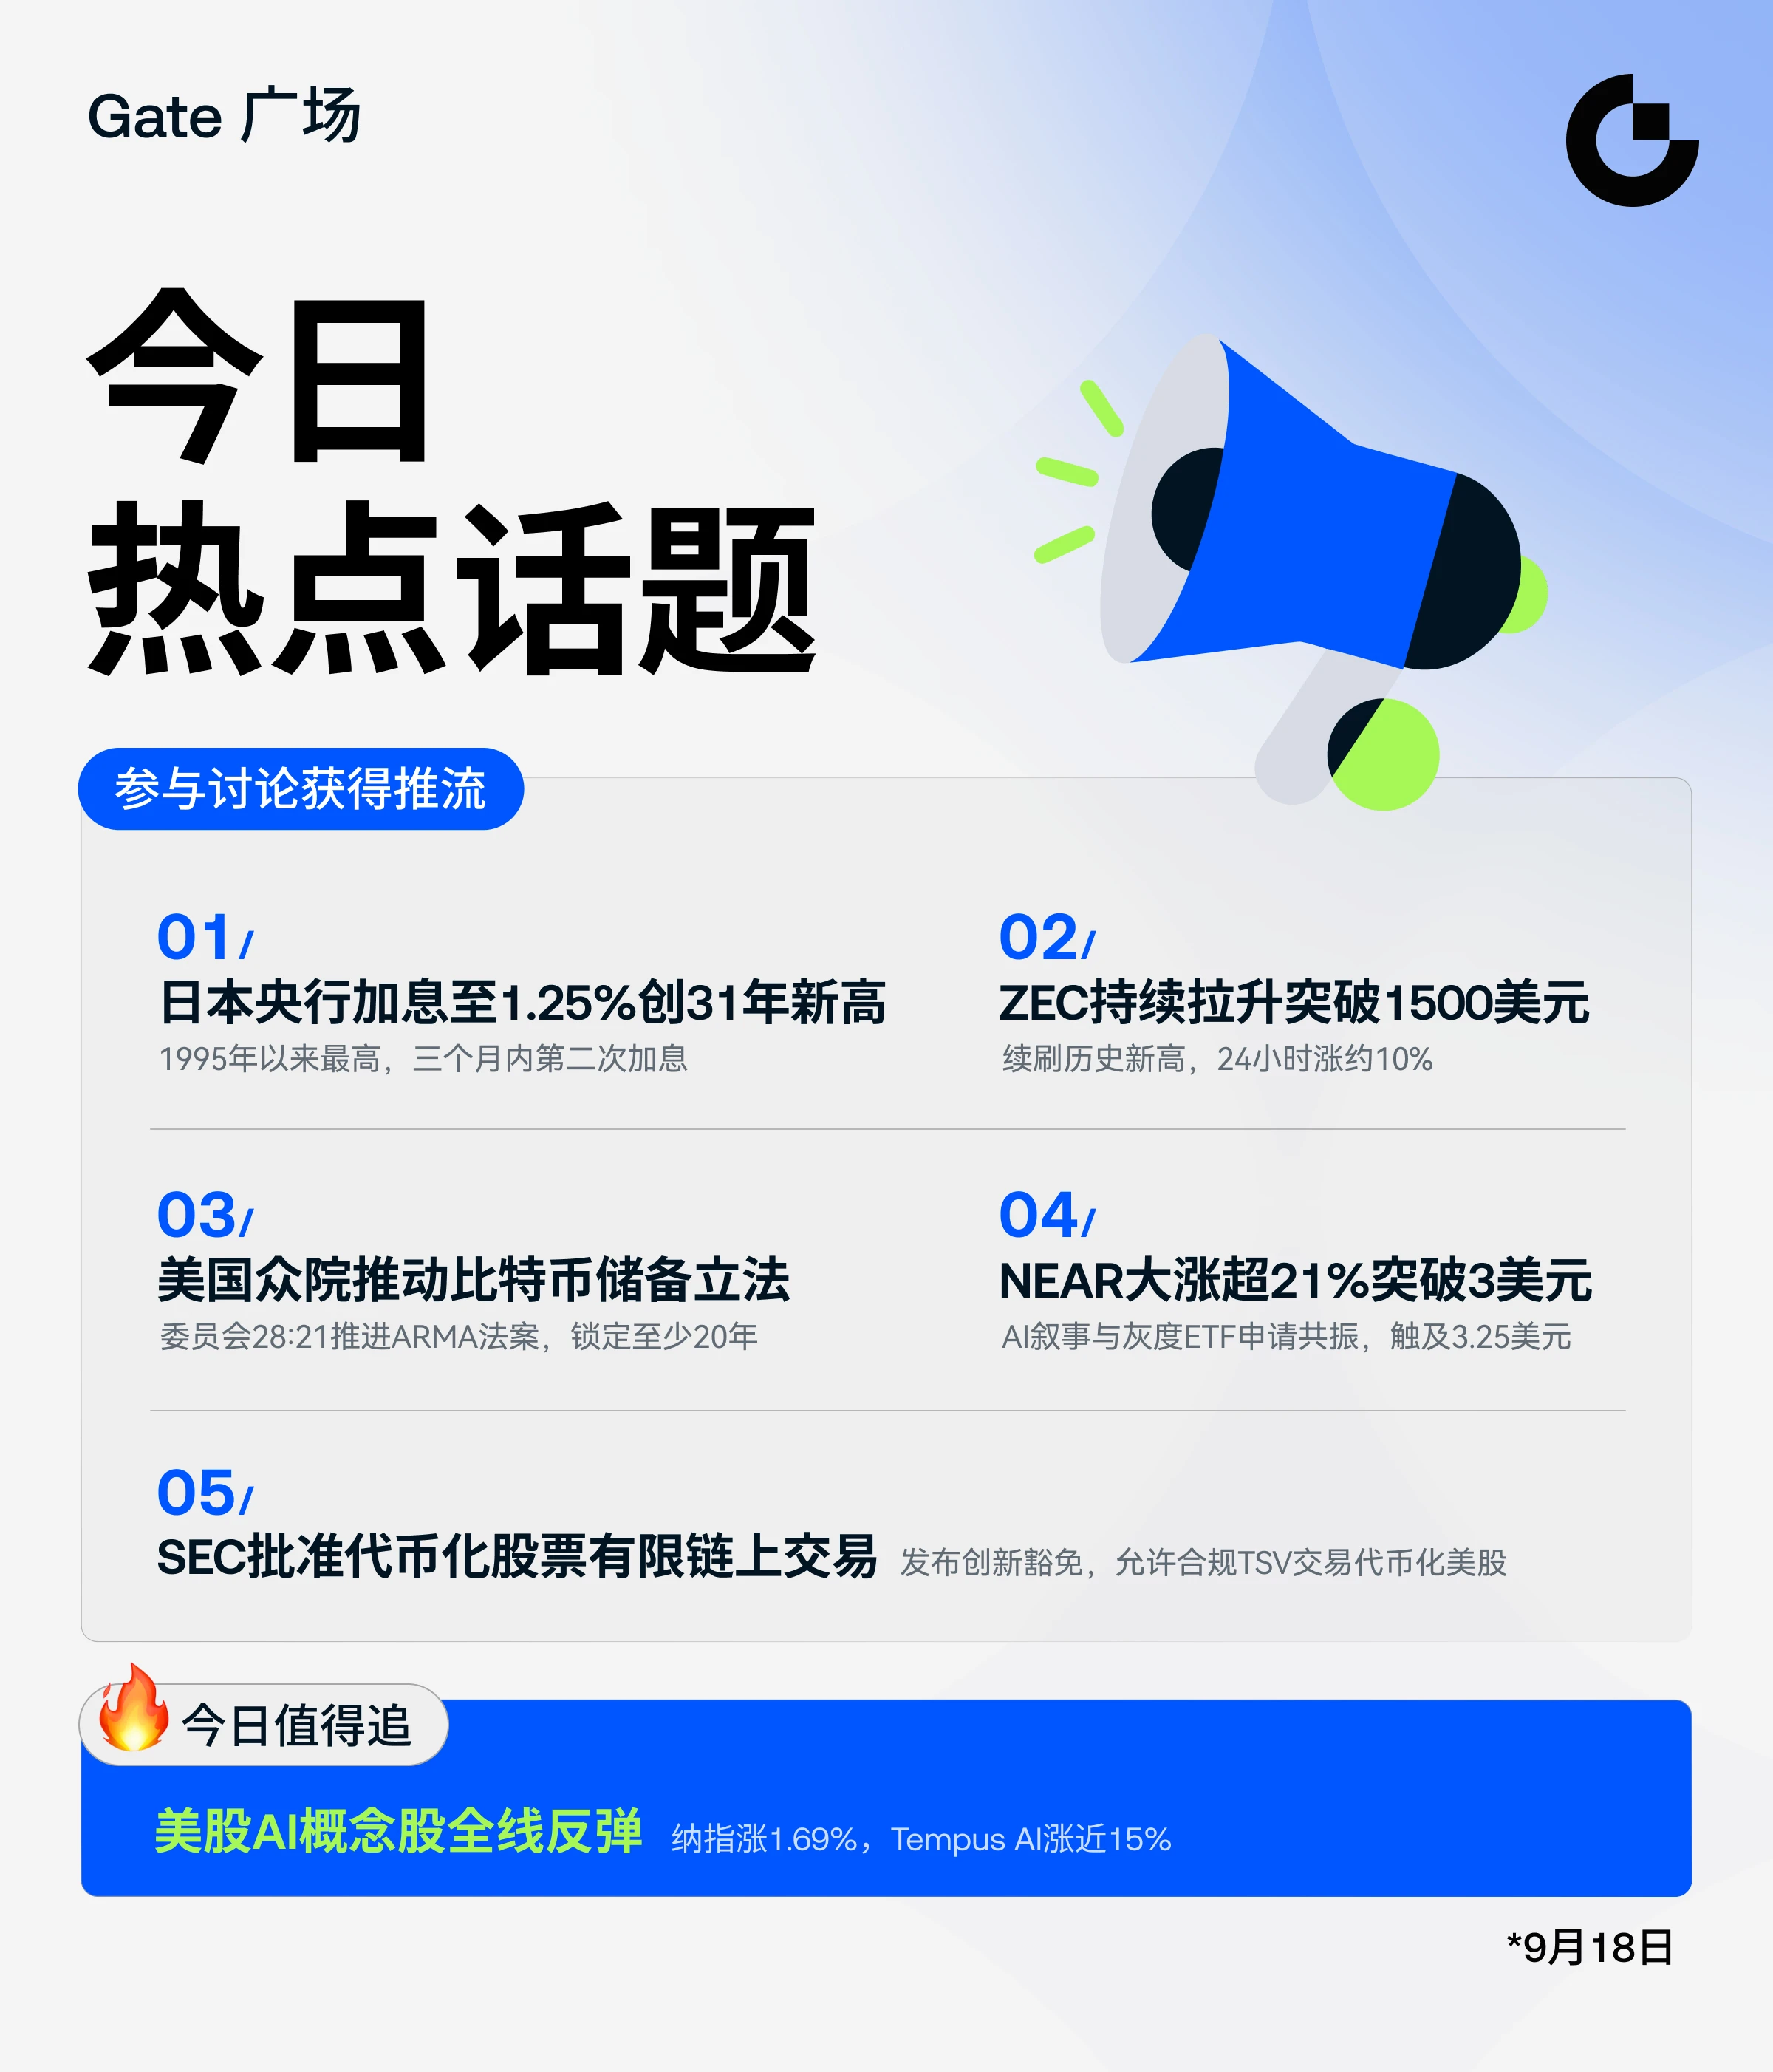
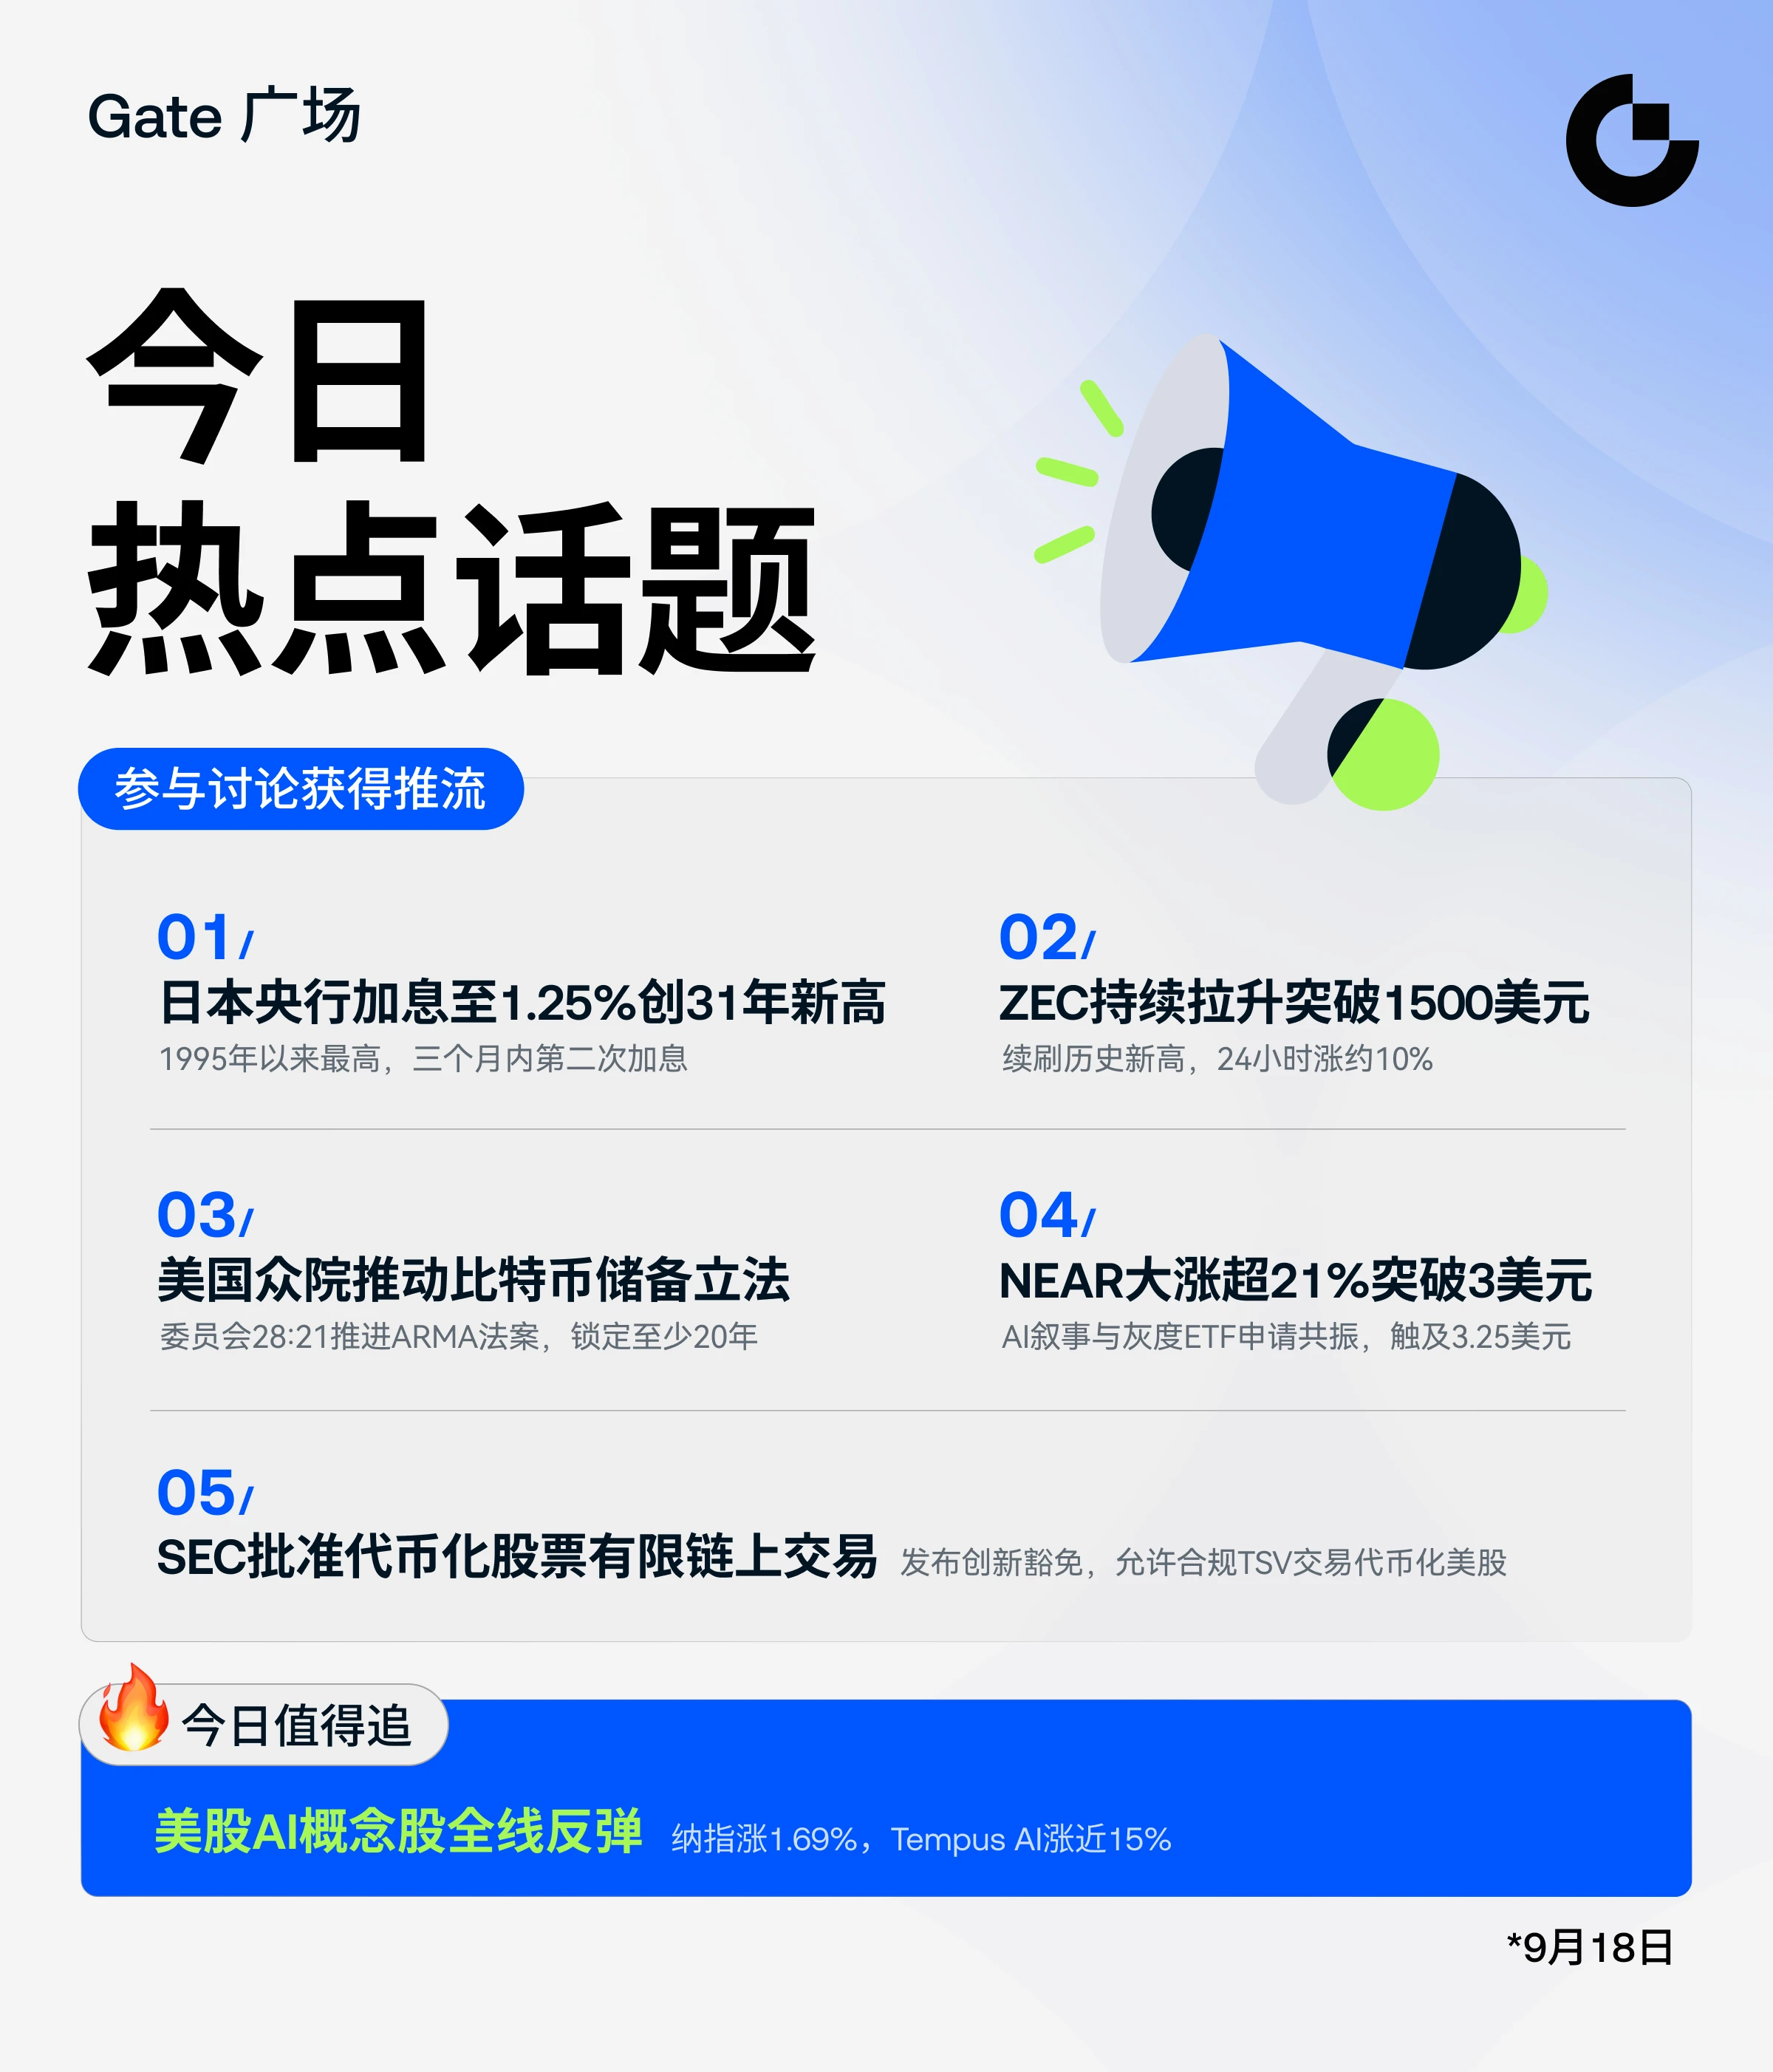
Many had initially predicted that U.S. stocks would remain under pressure and plunge after the hawkish statement. Unexpectedly, on the first trading day after the rate hike, U.S. stocks mounted a strong comeback, with tech stocks surging across the board. At the close, the Dow Jones Index rose 316.14 points, or 0.61%; the Nasdaq jumped 1.69%, gaining 439.88 points on the day; and the S&P 500 rose 1.14%.
Growth sectors rebounded across the board, with funds pouring back into the technology sector. Semiconductors and memory chips, the most interest-rate-sensitive segments, led the rally. The Philadelphia Semiconductor Index surged 3.14%, with stocks across the sector flourishing. Intel rose more than 7%, AMD jumped over 6%, SanDisk and Micron Technology gained nearly 6%, and SK Hynix also strengthened. AI computing power and the optical communications industry chain rose in tandem, with optical module companies such as Marvell and Coherent posting standout gains. The “Magnificent Seven” large-cap tech stocks all closed higher, with Nvidia up 2.54% and Tesla up 2.27%; Amazon, Microsoft, Apple, Meta, and Google also advanced in tandem, as AI leaders broadly recovered.
Many retail investors may wonder: With the Fed raising rates and remaining hawkish, why did high-valuation tech stocks surge instead?
The core explanation in one sentence: Expectations were priced in early, so the actual decision marked the end of the negative catalyst.
Before this meeting, the market had been trading rate-hike expectations for half a month, with roughly 90% probability already priced in. Funds had long anticipated this 25-basis-point hike and had fully absorbed the hawkish signal that another hike could come later this year. Once the decision was delivered, the negative catalyst was realized, and funds no longer continued panic selling.
This was compounded by falling U.S. Treasury yields. The decline in the 10-year Treasury yield directly eased valuation pressure on tech stocks, which are valued based on distant future cash flows, prompting funds to flow back into growth sectors.
Another key variable was the retreat in international oil prices.
The market’s biggest concern had been that persistently high oil prices would continue to push up inflation, forcing the Fed to keep tightening monetary policy. With oil prices falling, the risk of inflation spiraling further out of control declined, concerns about continued aggressive rate hikes eased, and risk appetite quickly recovered.
However, this rebound is a sentiment-repair rally, not the start of a new bull market.
Fed Chair Waller did not close the door on further rate hikes. The dot plot showed the interest-rate midpoint moving higher by the end of 2026, while the possibility of another hike later this year remained.
CME data shows that the market has already begun pricing in the probability of another hike in October. In other words, the high-rate environment will persist for a considerable period, and medium- to long-term pressure has not completely disappeared. This rebound in U.S. tech stocks is a trading-driven move, not a trend reversal, and volatility will continue. $INTC
Many had initially predicted that U.S. stocks would remain under pressure and plunge after the hawkish statement. Unexpectedly, on the first trading day after the rate hike, U.S. stocks mounted a strong comeback, with tech stocks surging across the board. At the close, the Dow Jones Index rose 316.14 points, or 0.61%; the Nasdaq jumped 1.69%, gaining 439.88 points on the day; and the S&P 500 rose 1.14%.
Growth sectors rebounded across the board, with funds pouring back into the technology sector. Semiconductors and memory chips, the most interest-rate-sensitive segments, led the rally. The Philadelphia Semiconductor Index surged 3.14%, with stocks across the sector flourishing. Intel rose more than 7%, AMD jumped over 6%, SanDisk and Micron Technology gained nearly 6%, and SK Hynix also strengthened. AI computing power and the optical communications industry chain rose in tandem, with optical module companies such as Marvell and Coherent posting standout gains. The “Magnificent Seven” large-cap tech stocks all closed higher, with Nvidia up 2.54% and Tesla up 2.27%; Amazon, Microsoft, Apple, Meta, and Google also advanced in tandem, as AI leaders broadly recovered.
Many retail investors may wonder: With the Fed raising rates and remaining hawkish, why did high-valuation tech stocks surge instead?
The core explanation in one sentence: Expectations were priced in early, so the actual decision marked the end of the negative catalyst.
Before this meeting, the market had been trading rate-hike expectations for half a month, with roughly 90% probability already priced in. Funds had long anticipated this 25-basis-point hike and had fully absorbed the hawkish signal that another hike could come later this year. Once the decision was delivered, the negative catalyst was realized, and funds no longer continued panic selling.
This was compounded by falling U.S. Treasury yields. The decline in the 10-year Treasury yield directly eased valuation pressure on tech stocks, which are valued based on distant future cash flows, prompting funds to flow back into growth sectors.
Another key variable was the retreat in international oil prices.
The market’s biggest concern had been that persistently high oil prices would continue to push up inflation, forcing the Fed to keep tightening monetary policy. With oil prices falling, the risk of inflation spiraling further out of control declined, concerns about continued aggressive rate hikes eased, and risk appetite quickly recovered.
However, this rebound is a sentiment-repair rally, not the start of a new bull market.
Fed Chair Waller did not close the door on further rate hikes. The dot plot showed the interest-rate midpoint moving higher by the end of 2026, while the possibility of another hike later this year remained.
CME data shows that the market has already begun pricing in the probability of another hike in October. In other words, the high-rate environment will persist for a considerable period, and medium- to long-term pressure has not completely disappeared. This rebound in U.S. tech stocks is a trading-driven move, not a trend reversal, and volatility will continue. $INTC