


Square
Following
Hot
News
Profile
Share your thoughts
placeholder
Article
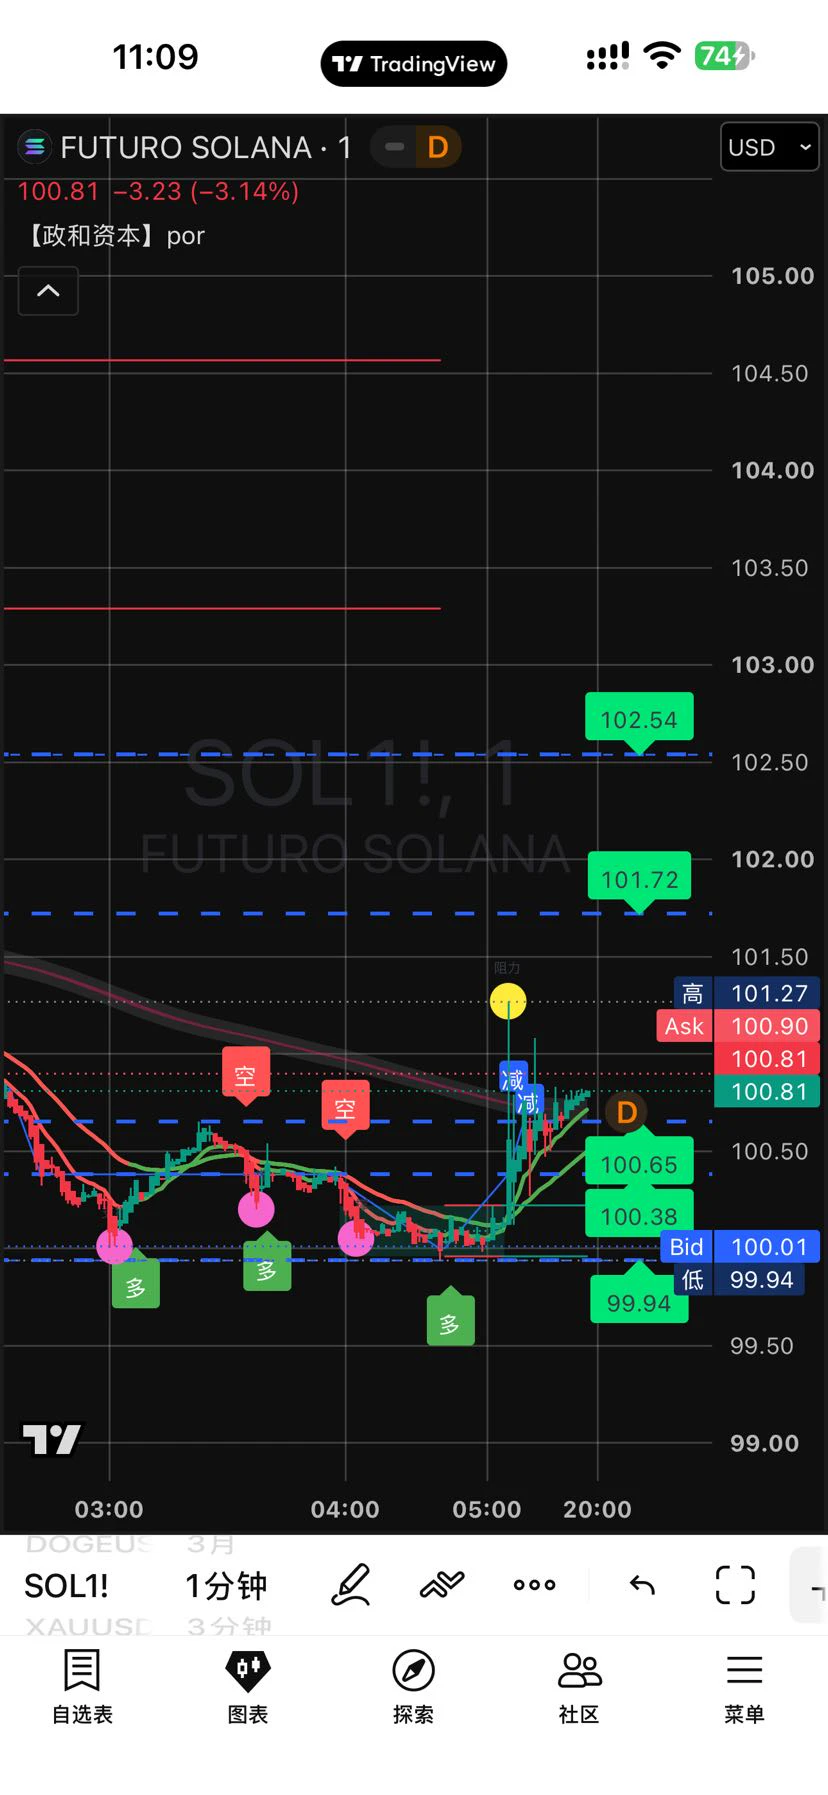
October 27, 2026 (Tuesday) SOL Futures Analysis and Strategy (as of approximately 11:13 HKT)
Current Market Overview
SOL is currently trading around $100.3–$101.0, with modest 24-hour fluctuations of approximately ±0.3–0.6%. After opening on Tuesday, the price stabilized around $100. Yesterday's low briefly touched approximately $99.7–$99.9, and the price is still trading below most short-term moving averages.
SOL has recently continued to retreat from highs of $108–$109, with a weak short-term structure and strong correlation with BTC and ETH. Funding rates are low, open interest has declined
post-image
SOL-0.77%
During bull markets, weekly charts can easily form double tops. If this is the start of a bull market, the subsequent decline probably won’t be very deep. Personally, I’m looking at 74–78 at most; I don’t see it starting with a 6. If the daily chart’s correction has run its course here, a new wave will probably begin 📈$BTC South Korea is reportedly considering postponing its crypto tax for the fourth time
post-image
BTC-0.67%
Trenches
STONK
S
bade
b
STONK
6GmA...UNgx
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
ZIG
Z
bade
b
ZIG
0x8c...1145
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
CNPY
C
bade
b
CNPY
0xc6...ddd2
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
Q
Q
bade
b
Q
0xc0...0589
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
LAUNCH
L
bade
b
LAUNCH
AhBi...Qj6C
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
$BTC #StriveCEO暗示继续增持比特币 #Gate广场万圣节 Institutional activity will provide some support, but it will be difficult to defend $80k through institutional buying alone. For now, it looks more like an attempt to provide a floor than a true bottom.
Strive is indeed buying. From October 12 to 16, it bought 4,045 coins at an average price of about $82,803, bringing its total holdings to 36,818 coins. The CEO’s goal is to become the second-largest publicly disclosed holder by year-end, but the company has not committed to using all newly raised funds to buy coins.
But institutions are not united overall.
post-image
BTC-0.67%
[New Streamer] Market Prediction
live-cover
LIVE1,724
🔴 $NEAR LONG SETUP — WILL BUYERS TRIGGER A POWERFUL BOUNCE? 🚀
NEAR has recorded a significant $24.154K long liquidation at $4.394, making this reference price worth monitoring for a potential volatility spike. If buyers reclaim the nearby levels and maintain momentum, a relief rally could follow. 📈 Support: $4.30–$4.39 | Resistance: $4.45–$4.55 | TP1: $4.45 | TP2: $4.52 | Final Target: $4.60 | Stop Loss: Below $4.25. 🎯 Next Move: Watch for a strong recovery above $4.45; losing the support zone could expose price to another bearish leg. 💡 Pro Tip: Larger liquidation figures can signal vol
post-image
NEAR+1.17%
MU+2.97%
HK50-0.20%
#btc Bitcoin is currently facing a severe test at the critical $80,000 support level. The short-term technical outlook is bearish, and the price is highly likely to consolidate within the $78,000 to $86,000 range this week. The market is holding its breath waiting for the Federal Reserve's interest rate decision and major tech earnings, as these macro events will directly determine the final direction of the bulls versus bears.
Currently, there are three core factors influencing the subsequent price action:
· Dense Macro Calendar, Direction Hinges on Data: This is one of the busiest macro trad
BTC-0.67%
MSFT+1.56%
GOOGL-1.05%
AMZN+0.40%
COIN-2.89%
#Gate广场万圣节 #BitcoinFallsBelow80K
Bitcoin at $80,036, Falling Highs, a Cost-Basis Test and a Macro Week That Decides the Next Move
Bitcoin is trading at about $80,036, just above the $80,000 line, after a session range of $79,338 to $80,673. That is a 1.7% swing around the level the whole market is watching. The $80,000 mark is more than a round number. After BTC slipped below it and printed $79,338 today, the market is testing whether buyers can defend this zone or whether another wave of selling pushes price toward lower support. The real question is not whether Bitcoin can touch $80,000, bu
Falcon_Official
#Gate广场万圣节 #BitcoinFallsBelow80K
Bitcoin is back under $80,000, trading near $79,673 after its weakest level since September 18. Round numbers attract headlines, so I looked at the structure underneath it. The chart reads like a small building: a floor that has been tested, a ceiling that keeps rejecting price, and a trapdoor a few percent below.
$80,000 and the cost-basis band
Bitcoin had closed above $80,000 every day since September 18, so the break carries more weight than a round number. The level is also where several groups bought. Glassnode estimates the average price paid by companies holding Bitcoin on their balance sheets at about $80,000, which puts the average corporate treasury position at a loss below it. Glassnode also described a cost-basis band between $80,000 and $81,500. By my math, $79,673 sits about 0.4% below $80,000 and about 2.2% below the top of that band.
The floor has been tested before. The same $79,800 to $80,000 zone stopped the decline on October 15, which makes Saturday the second test in ten days. Today is arguably a third look at the same area, and each test tends to weaken a floor.
The ceiling: $82,000 to $83,350
Overhead, several levels stack up. Bitcoin was rejected near $85,000 on October 21 and has dropped back under its 200-period exponential moving average on the 4-hour chart, now at $82,024. The 50-day average sits at $81,798 and the 20-day at $82,539, which means many recent buyers are underwater and short-term sellers have the advantage. Traders also pointed to resistance between $82,400 and $83,350. From $79,673, $82,024 is about 2.9% higher and $82,539 about 3.6% higher.
The structure is a descending staircase. Bitcoin has made lower highs since its $87,197 peak on October 2, with the $84,840 rejection extending that sequence, and it closed below its 50-day average for the first time since August. By my math, price is about 8.6% below the October 2 peak. Add the lows: $79,842 on October 15, then $79,146 on October 24, a lower low. Lower highs plus lower lows is the textbook definition of a downtrend.
The trapdoor: $77,500 to $78,400
If $80,000 gives way, the chart offers a few catch points. Glassnode's True Market Mean places the next major support at $77,600, roughly 3% below, and BeInCrypto flagged $77,876 as the next downside level, with a support zone between about $76,700 and $72,500 below that. Another reading puts support near $78,422. By my math, $78,400 is 1.6% below, $77,600 is 2.6% below and $75,000 is 5.9% below. Mid-September's consolidation near $78,000 before the run to $87,000 adds weight to that area.
Momentum
The 4-hour RSI sits at 33.21, showing that sellers have controlled most candles since Wednesday without yet reaching the near-30 readings that preceded the October 9 rebound to $84,000. A daily RSI near 43 points to weak but not extreme momentum. In plain words, the drop has room to run before it looks stretched.
Why it fell when yields did not
This is the useful puzzle. The 10-year Treasury yield fell to 4.96% on October 22 from 5.31% earlier in the month, and lower yields usually support Bitcoin. So rates are not the main driver this time. The drivers were flows, leverage and geopolitics. Spot Bitcoin ETFs lost about $773 million on Thursday and Friday after taking in more than $1 billion earlier in the week, more than $200 million of positions were liquidated in a single hour on Saturday, with $191.33 million of them longs, and more than $810 million was liquidated across 24 hours, including about $689 million in longs. Oil adds another layer, with Brent near $115 after a 6% weekly gain.
Distance from the highs
Bitcoin is about 36.8% below its all-time high of $126,080 by my arithmetic, which keeps the long-term picture a recovery story and not a new-high story.
The Fed meets October 27 and 28, and U.S. midterm elections follow on November 3. The decision is widely expected to be a hold, so tone matters more than the rate.
Risk and reward
A long from $79,673 with a stop under $78,400 risks about 1.6%. A target at $82,024 offers about 2.9%, a ratio near 1.8 to 1, while $84,840 offers about 6.5%, a ratio near 4 to 1. The second ratio only pays if the floor holds on a closing basis and the ceiling breaks.
Three scenarios
Floor holds: BTC closes back above $80,200 and $81,500, then challenges $82,024 to $82,539.
Range: price chops between $78,400 and $81,500 while the Fed and earnings dominate.
Trapdoor: a daily close below $79,000 opens $78,400, then $77,600 to $77,876, and a break there points toward $75,000.
ETF flows each morning, liquidation spikes near round numbers, the 4-hour 200 EMA near $82,024 and whether corporate-treasury selling appears. A reclaim of the 50-day average would be the first real sign of repair.
I would keep leverage low into the Fed decision, treat a daily close under $79,000 as the line that opens the trapdoor, and wait for a close above $82,539 before calling the downtrend over.
A floor that has been tested three times is not a wall, it is a negotiation. Sooner or later the buyers or the sellers stop showing up, and the useful habit is to decide in advance which one you will believe. #WCTCS9
repost-content-media
BTC-0.67%
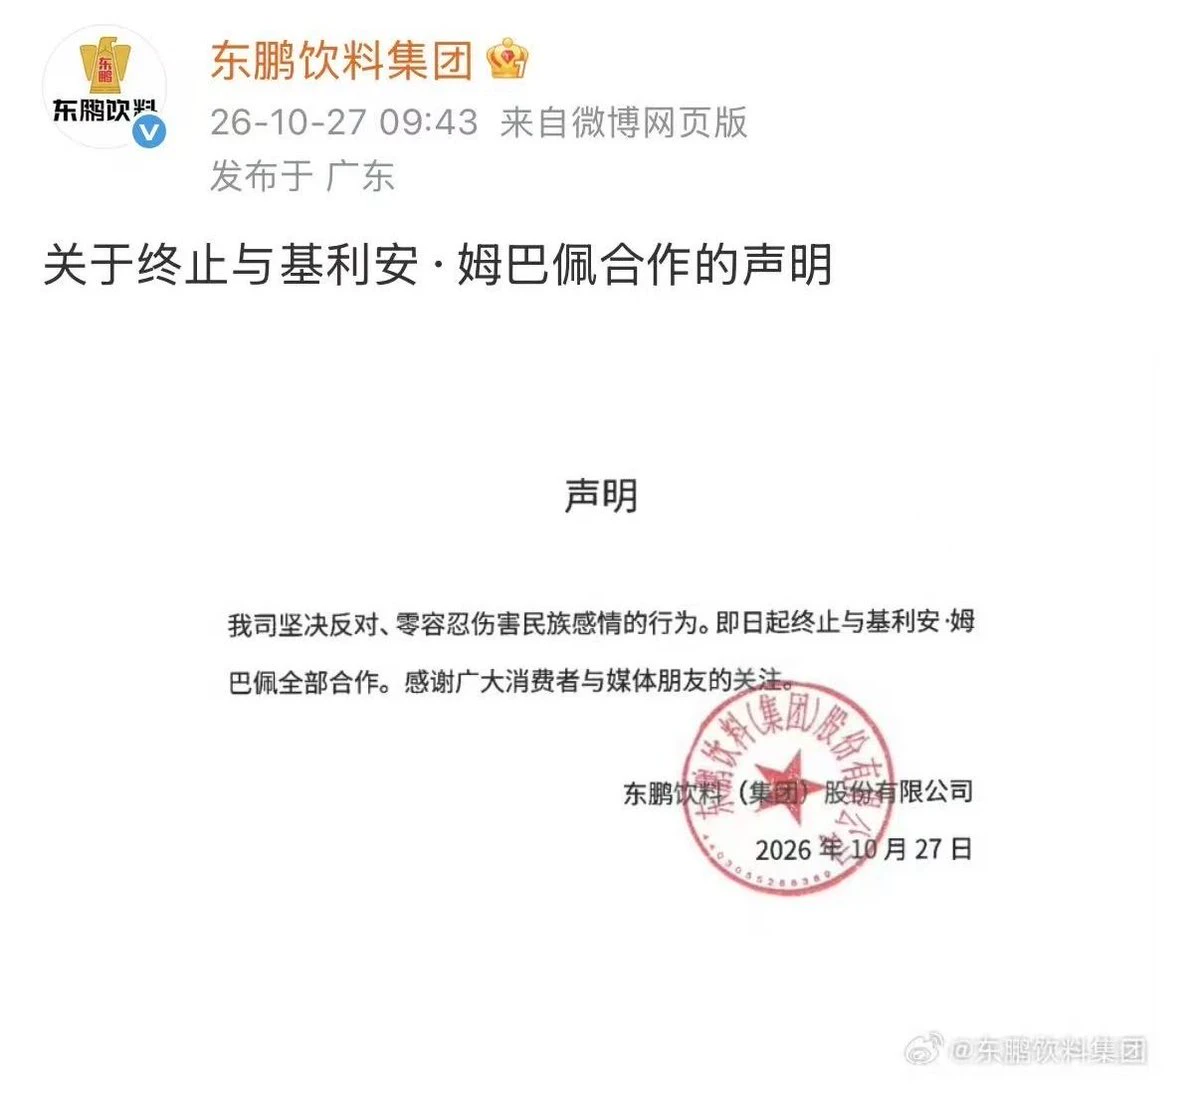
Dongpeng Special Drink really got caught in the crossfire
So will the electrolyte water produced earlier be sold at a discount?🤔
post-image
  • 1
BTC
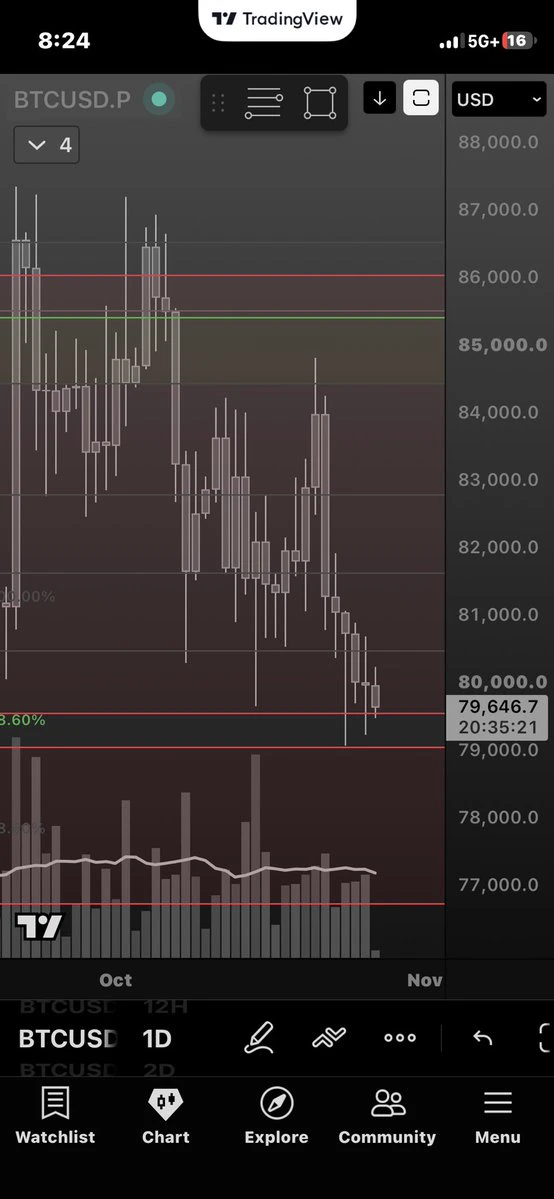
Hold this line on a daily close and 86k is the target ..Lose it on a daily close andd well ..ill be down some fn money
🫣🤣
post-image
BTC-0.67%
#美股财报季 #Gate广场万圣节 Google, Microsoft, Amazon Earnings Preview: Pessimism Could Be a “Godsend”
Hyperscaler Earnings Preview: When Valuation Science Becomes Valuation Art
Meta (NASDAQ: META) fired the first shot of hyperscaler earnings season last week, but the results were deeply disappointing—the stock plunged 9.4% in the week following its earnings release. Although actual free cash flow was far better than expected, substantial equity dilution from the issuance of new non-voting common shares was the main drag on the stock.
Ahead of the flood of Q3 earnings reports, a chart published by Bespo
post-image
ThisIsTranslateContent:
#美股财报季 #Gate广场万圣节 Google, Microsoft, Amazon Earnings Preview: Pessimism May Prove a “Godsend”
Megacap Cloud Earnings Preview: When Valuation Science Becomes Valuation Art
Meta (NASDAQ: META) fired the opening shot of megacap cloud earnings season last week, but the results were a major disappointment — its shares plunged 9.4% for the week after earnings. Although actual free cash flow was far better than expected, the main drag on the stock was the substantial equity dilution from the issuance of new non-voting common shares.
Ahead of the flurry of Q3 earnings reports, a chart published by Bespoke Report showing the trend in 5-year CDS (credit default swap) spreads for large-cap tech stocks may provide readers with a useful starting point. Notably, the investment thesis around large-cap tech stocks is evolving: market focus appears to be shifting from traditional revenue, EPS, operating profit growth, and guidance to industry capex, free cash flow, capex growth, debt issuance and financing capacity, and companies’ long-term credit quality — namely, the trajectory of senior unsecured bonds and long-term credit ratings. CoreWeave (NASDAQ: CRWV) has a market cap of $30 billion but $50 billion in debt outstanding, and its CDS spreads are widening rapidly, making it the latest risk focus in an already troubled megacap cloud subsector.
In the current environment, sticking with companies that have higher credit quality may help mitigate some downside risk. (Meta ranks sixth among 10 companies for the widening of CDS spreads, which raises the question of who ranks sixth through tenth.) Below are YTD total returns for common shares as of the close on October 23 (Friday): Alphabet (GOOGL): +2.51%; Microsoft (MSFT): +9.02%; Amazon (AMZN): +7.44%
Alphabet (GOOGL) Alphabet is scheduled to report earnings after the market close on October 28 (Wednesday).
According to the LSEG-compiled analyst consensus, EPS is expected to be $3.01 and revenue $128.1 billion, up 5% and 25% year over year, respectively; operating profit is expected to rise 23% year over year to $42.7 billion.
GOOGL delivered exceptionally strong results last Q3 (the quarter ended September 2025): actual EPS of $2.87 far exceeded expectations of $2.33, beating estimates by 23%; operating margin beat expectations by 160 basis points, and Google Cloud was a particular standout that quarter.
This September quarter’s 5% year-over-year EPS growth faces a tough comparison with last year’s high base. In the March and June quarters this year, Anthropic’s equity appreciation (unrealized gains) distorted GOOGL’s earnings growth. The current full-year consensus EPS estimate is $20.61, implying calendar-year growth of 91% — but excluding Anthropic’s unrealized gains, GOOGL’s core operating EPS growth in 2026 should be in the 35%–40% range.
For Q4, Meta has already raised its guidance, and the consensus estimate for GOOGL is EPS of $3.36 and revenue of $143 billion, representing year-over-year growth of 19% and 25%, respectively. Meta raised the lower end of its capex guidance, indicating that megacap cloud providers remain committed to massive investment. Anthropic is expected to IPO in November, and its equity appreciation gains are expected to be recognized again in the Q3 earnings report released Wednesday evening.
Valuation: GOOGL is not expensive on a PE basis — 16 times earnings against expected growth of 91% (although that figure is distorted by Anthropic); the 2017 baseline EPS of $15.27 implies a multiple of 21.
But cash flow is the core issue: GOOGL’s free cash flow turned negative last quarter, for the first time in a long while.
As of June 30, its FCF yield had fallen to 1%, its price-to-cash-flow ratio was 21 times, and its price-to-free-cash-flow ratio was as high as 73 times.
Morningstar estimates GOOGL’s fair value/intrinsic value at $433, 25% above the current share price.
Technically, the stock has fallen below its 200-day moving average — usually not a good sign; reclaiming it and breaking above the record high of $400 would be a significant positive.
GOOGL key metrics: TTM FCF yield: 1%Capex as a share of revenue: 30%Capex as a share of operating cash flow: 71%Full-year capex guidance: $180 billion–$190 billionLong-term debt: $80 billionCredit ratings: S&P AA+ / Moody’s Aa+GOOGL faces the same issue as most megacap cloud providers: shrinking free cash flow (negative in Q2), no buybacks to support the share price, rapidly rising capex, and long-term debt surging to $80 billion from $21 billion 4–5 quarters ago. Alphabet’s private assets — Anthropic, YouTube, Waymo, and SpaceX — may provide cash for buybacks and debt repayment in the future; its high credit rating is itself a safeguard and also supports GOOGL’s valuation.
Microsoft (MSFT) Microsoft will report FY27 Q1 earnings after the market close on October 28 (Wednesday).
Analyst consensus: EPS of $4.72, revenue of $90.6 billion, and operating profit of $44 billion, up 14%, 17%, and 16% year over year, respectively. After last quarter’s (FY26 Q4) earnings report, Microsoft’s share price surged from $400 to nearly $500 — EPS beat expectations by 6%, revenue by 3%, Azure growth was better than expected, and both the Productivity and Business Processes and More Personal Computing segments beat expectations.
Consensus for next quarter (FY27 Q2, ending December 31): revenue growth of 18%, operating profit growth of 17%, and EPS growth of 17%.
The most important point in Microsoft’s financial statements is that free cash flow remains quite healthy — FCF was $19.6 billion in FY26 Q4, the quarter ended in June, while Alphabet’s and Meta’s quarterly FCF have both turned negative.
Valuation: At the current share price of $525, the stock trades at 27 times FY27 expected EPS of $19.73 (distorted by OpenAI equity appreciation in December). Expected FY27 EPS growth is just 8%, far below Microsoft’s average annual EPS growth of 20% since FY20. FY27 Q1 capex guidance is $40 billion; the full-year FY27 slides only mention that capex will increase year over year, but given FY26 spending of $115 billion and Q1 alone reaching $40 billion, FY27 capex is expected to be in the $120 billion–$160 billion range (or even higher). Morningstar currently estimates MSFT’s fair value at $600, 10%–12% above the current share price.
MSFT key metrics: FCF yield: 2%Capex as a share of revenue: 35%Capex as a share of operating cash flow: 64%FY27 capex guidance: $120 billion–$160 billionLong-term debt: $31 billion (continuing to decline from its peak of $44 billion–$45 billion in the December 2023 quarter)Credit ratings: S&P AAA / Moody’s AaaMicrosoft remains one of the very few U.S. companies to hold the highest AAA/Aaa credit ratings from both S&P and Moody’s.
Amazon (AMZN) Amazon will report Q3 2026 earnings after the market close on October 29 (Thursday). Market consensus: EPS of $1.96 and revenue of $202 billion, up 1% and 12% year over year, respectively; operating profit is expected to rise 5% year over year. Q4 consensus: EPS growth of 26% and revenue growth of 15% — Amazon is entering the quarter when Anthropic equity appreciation contributes to earnings. Like GOOGL, Amazon is also affected by Anthropic equity appreciation, so 2027 EPS is expected to decline from 2026 — with nearly all of the drop attributable to Anthropic’s non-operating gains. Amazon’s expected EPS is $12.81 for 2026 and $10.62 for 2027, based on estimates as of the end of this week. In Q2, AWS (Amazon Web Services) recorded its fastest growth in 18 quarters on the earnings call, with AWS revenue and operating margin accounting for all of the quarter’s earnings strength. Internal data show that AWS now accounts for 21% of Amazon’s total revenue but contributed 62% of operating profit in the June quarter. (Interestingly, in the December 2022 quarter, AWS accounted for just 14% of total revenue but 59% of operating profit — revenue has grown substantially, yet its profit contribution has barely changed, reflecting the industry as a whole.)
Valuation: Amazon’s current share price represents 20 times 2026 expected EPS of $21.81, and 24 times next year’s depressed EPS of $10.62. Its price-to-cash-flow ratio is 18 times based on June-quarter operating cash flow, but its price-to-free-cash-flow ratio has turned negative — because Amazon’s FCF is negative. Morningstar estimates Amazon’s fair value at $300; the current share price is $248, a discount of around 18%.
AMZN key metrics: TTM FCF yield: -1%Capex as a share of revenue: 22%Capex as a share of operating cash flow: 108%Full-year capex guidance: no specific figure provided / year-end 2026 run rate of $225 billionLong-term debt: $129 billion (as of June), versus just $51 billion last JuneCredit ratings: S&P AA / Moody’s A1
The data above make it easy to understand why Amazon has cut Amazon Fresh and Amazon Go (its brick-and-mortar formats that compete directly with Walmart) and focused on its existing Whole Foods stores — AWS is consuming enormous amounts of capital.
It will be interesting to see what happens to e-commerce and automation, but efficiency gains in e-commerce may themselves be part of Amazon’s overall AI investment. Amazon could become the first U.S. company to exceed $1 trillion in annual revenue — possibly by the end of 2027, but more likely by the end of 2028. Although Amazon has surpassed Walmart to become the largest U.S. company by annual revenue, this is not a “retail versus retail” comparison: Walmart remains the largest retailer in the U.S. (and the world), with expected FY27 revenue of around $53 billion (ending in January 2027). Amazon’s capex-to-operating-cash-flow ratio of 108% is remarkable.
Summary
When capex determines free cash flow for AI-related stocks, and free cash flow in turn becomes a core valuation variable (at least in DCF models), valuation science becomes valuation art. The current situation resembles the internet bubble of the late 1990s — when even “eyeballs” were used as a valuation metric and chaos reigned. Capex pressure will only intensify, and capex guidance will become increasingly aggressive. Amazon’s capex-to-operating-cash-flow ratio of 108% says a lot.
Ignoring the apparent valuation discounts and ranking the three companies solely by willingness to hold them, the order is:
1. Microsoft: AAA/Aaa credit ratings, a remaining free cash flow cushion, a sustained reduction in long-term debt over the past 3–4 years (debt financing costs less than equity issuance), and the lowest capex-to-operating-cash-flow ratio of the three (61%).
2. Alphabet: Neck and neck with Amazon, but its capex-to-operating-cash-flow ratio of 71% is the most important factor in the ranking. GOOGL also has investments such as SpaceX, Waymo, and YouTube — all else being equal, these assets mean GOOGL’s current share price discount to intrinsic value is greater than it appears. Alphabet’s FCF only turned negative for the first time in the June quarter. 3. Amazon: FCF has been negative for two consecutive quarters, and its capex-to-operating-cash-flow ratio of 108% is the highest of the three.
All AI-related companies making massive capex expansions could end up in this position. Amazon itself is not a bad business, but how capital allocation in e-commerce/retail (78%–80% of revenue) will be coordinated with AWS remains an open question — is e-commerce retail competing with AWS for capital, or complementing it?
The ranking by S&P and Moody’s credit ratings is exactly the same as the ranking by capex ratio.
Looking ahead to this week’s earnings, Microsoft seems the safer choice; but a capex guidance beat (especially for calendar 2027, if the company is willing to provide it) will be the decisive variable. The larger the capex increase, the lower the forward free cash flow expectations.
Notably, Meta’s capex came in below expectations, leaving quarterly FCF at just -$2 billion, far better than the market expectation of -$8.5 billion. Apollo Capital Chief Economist Torsten Slok recently wrote that outside the AI sector, the rest of the S&P 500 has “yet to see any signs of returns from AI.”
repost-content-media
MSFT+1.56%
AMZN+0.40%
CRWV+1.73%
GOOGL-1.05%
  • 2
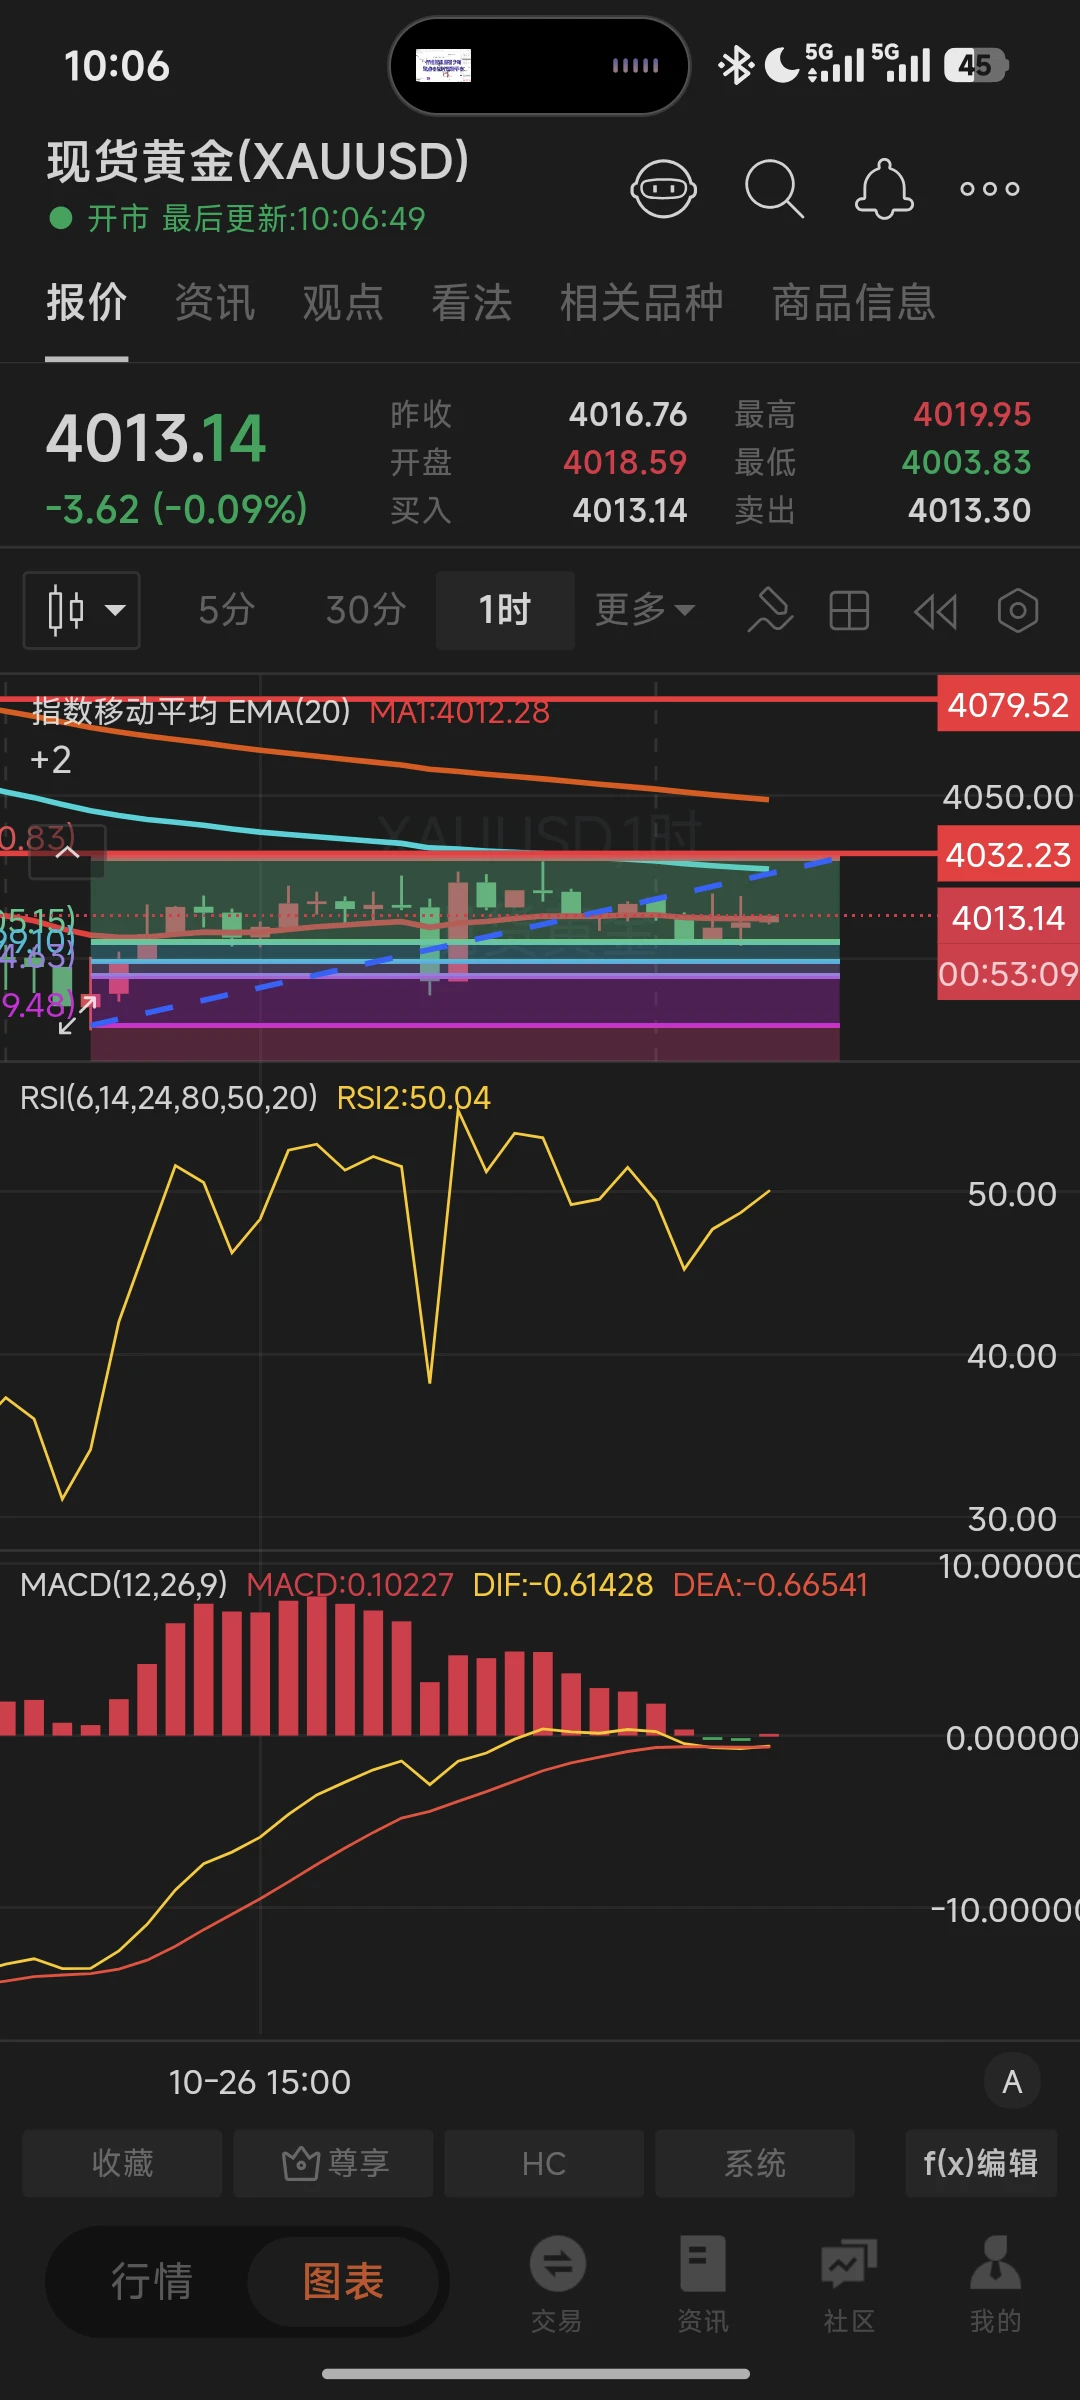
XAUUSD 10.27 Asia-Europe session outlook$XAUUSD
The market remains in a trading range and has not broken out. The smaller range is 4004-4020, and the larger range is 3980-4030.
Support: around 4004 (1h), 3980-3990 (1h, 4h), 3943-3963 (1day)
Resistance: 4032-4038 (1h), 4066-4080 (2h, 4h), 4104-4111 (4h), 4124-4142 (1day)
post-image
XAUUSD-0.02%
Is Gold About to Turn This Week? The Fed and Inflation Data Take the Stage—This Time, Gold Can't Rely Solely on Its Safe-Haven Halo!
Many people rush to buy gold whenever a major macro event comes along, as if the price automatically gets a boost whenever world leaders meet. Unfortunately, the market isn't so easily swayed. This week, what really matters for gold is the dollar, real interest rates, and the Fed's policy signals.
If the Fed signals a dovish tilt, or PCE comes in below expectations and bond yields fall, the opportunity cost of holding gold could decline, giving prices a chance to
3ULL-3.86%
  • 26
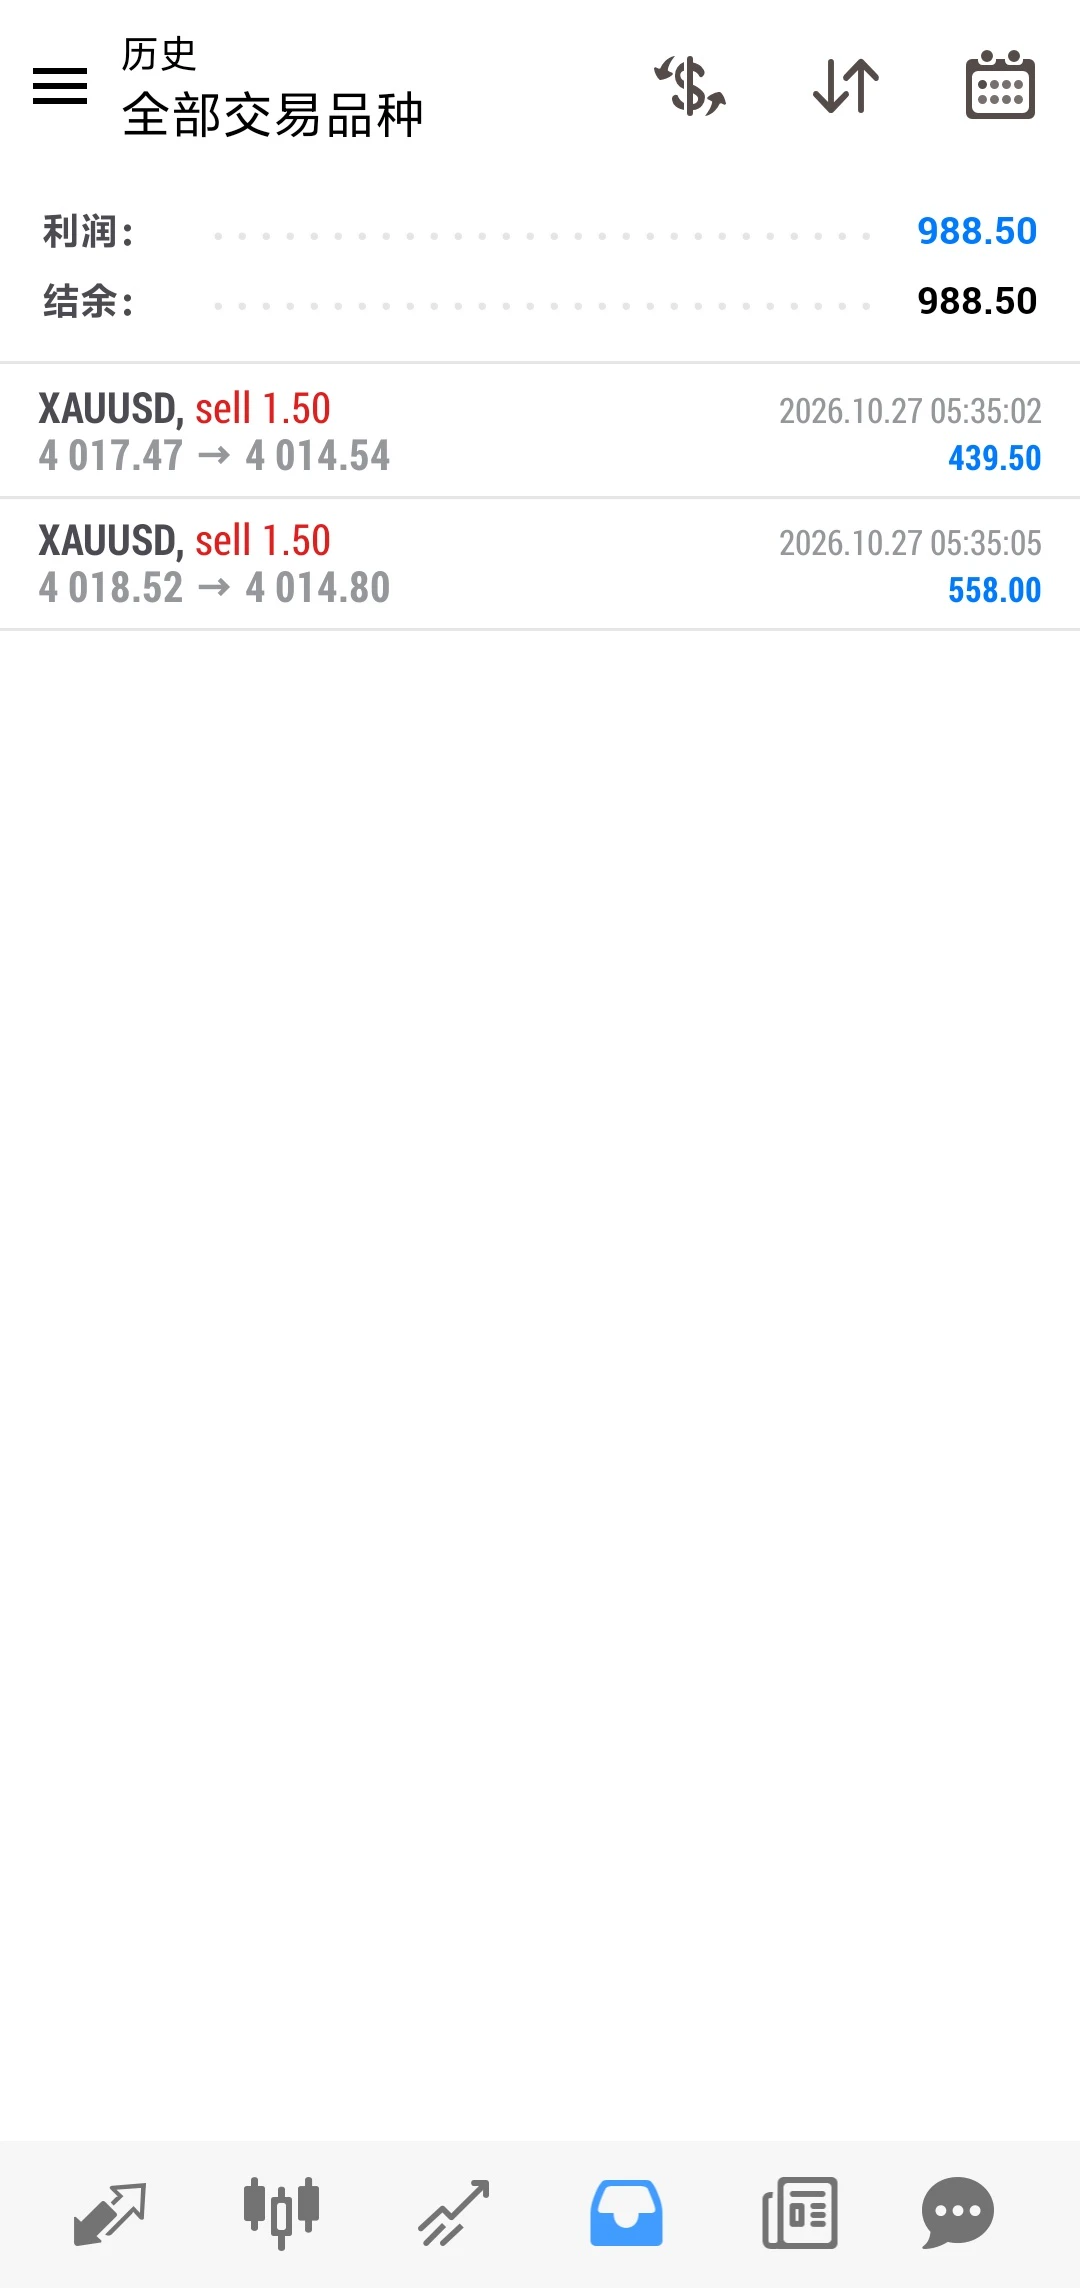
First win in two intraday gold trades
Short at 4017, exited at 4014, 3 points, 439🔪
Short at 4018, exited at 4014, 4 points, 558🔪$XAUT
post-image
XAUT+0.30%
HUGE RIPPLE XRP NEWS! OCC APPROVES RIPPLE BANK & TOKENIZATION ON THE XRP LEDGER!
WATCH ▶️
#crypto #cryptonews #xrp #ripple #occ #xrpledger #bitcoin #injective #bnb #tokenization #thinkingcrypto
post-image
XRP-1.15%
BTC-0.67%
INJ-1.67%
BNB-0.76%
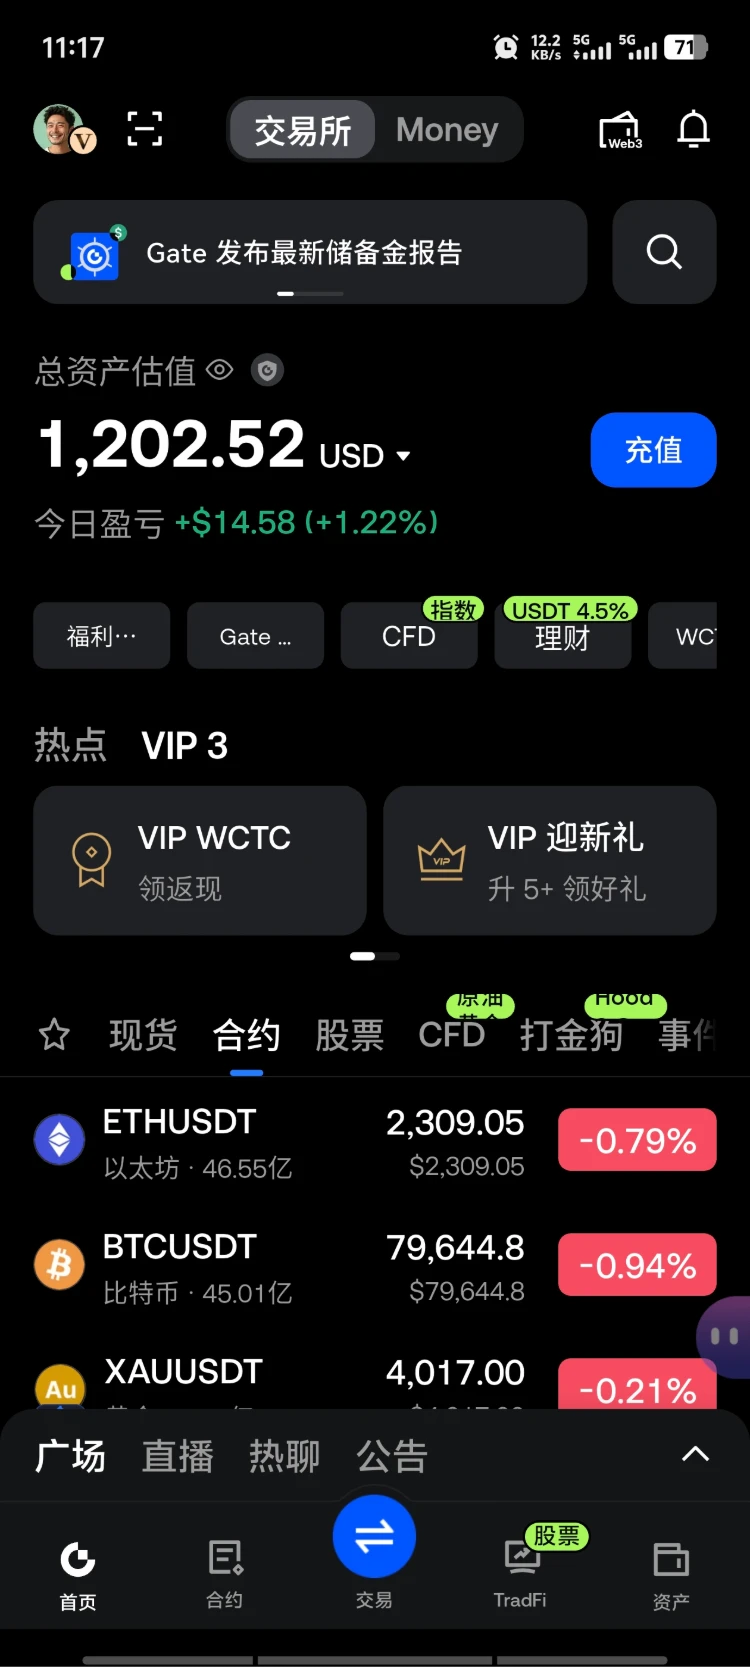
Tracking the journey from 800U to 8000U, trading only ETH and BTC. The account is at 1200U today. ETH and BTC are still moving sideways with a downward bias; the strategy remains to short at higher levels
post-image
ETH-1.26%
BTC-0.67%
#KeyMacroWeekAhead #宏观关键周 #WCTCS9 ‌The Hidden Test: Weak Consumers, Costly AI and a Midterm Vote in One Week
This week packs the Fed, GDP, inflation data, three mega-cap earnings reports and the November 3 midterms into seven days. Markets enter it with Brent above $115, the 10-year yield at 5% and consumer sentiment near multi-year lows. The S&P 500 closed Monday at 7,677 and the Nasdaq at 26,169, both after two weekly losses. The question is whether growth and the AI trade can absorb costlier money and costlier energy at once.
1. Consumers are strained
Conference Board confidence fell to 81
Falcon_Official
#KeyMacroWeekAhead #宏观关键周 #WCTCS9 The Fed, GDP and PCE: Three Tests That Could Reset Market Direction
Some weeks are driven by one headline. This one is different. Between October 27 and October 29, markets will receive a consumer-confidence reading, the Federal Reserve’s policy decision, and two major economic releases covering US growth and inflation. The challenge is that these indicators could point in different directions: the economy may remain resilient while inflation stays uncomfortable and financial markets struggle to find momentum.
My focus this week is not simply whether the data comes in hot or cool. It is whether the combined evidence changes expectations for interest rates, liquidity and the value of risk assets.
The starting point: markets are already cautious
On October 26, Bitcoin was trading around $80,000–$80,500 in the latest available market snapshots, while Ethereum was near $2,300. The Nasdaq Composite closed at 29,026.41 on October 23, down approximately 0.7% for the week. The US Dollar Index stood near 101.64, the 10-year Treasury yield was around 4.97%, and gold was near $3,986 per ounce in Monday’s market report.
These readings provide the starting line, not a prediction. Crypto trades continuously, whereas US equities have regular sessions, so exact prices and percentage changes depend on the timestamp. What matters next is how these markets respond after each release.
October 27 — Consumer confidence: the first signal
The Conference Board’s September Consumer Confidence Index fell to 81.9 from 88.6 in August, missing expectations and highlighting weaker household sentiment. The October reading is due Tuesday. Market-calendar estimates vary, so I would compare the actual release with the latest consensus available immediately before publication rather than treat one forecast as certain.
A further decline could raise concerns about future spending and economic growth. A recovery would suggest that households are becoming more optimistic despite cost pressures. Either result needs context: confidence measures how people feel, while actual spending data shows what they do.
October 28 — The Federal Reserve: the week’s policy pivot
The Fed’s decision and Chair Kevin Warsh’s press conference are the first major market test. The base case entering the week is that rates remain unchanged, which means the statement and the chair’s comments could matter more than the decision itself.
I will listen for three things: whether inflation is still described as persistent, whether policymakers see evidence of cooling demand, and whether the language leaves room for future easing or signals a longer period of restrictive policy.
A steady rate with a balanced message could support risk appetite if markets interpret it as reducing uncertainty. A steady rate accompanied by stronger inflation warnings could still pressure crypto and equities by lifting expectations for tighter policy. An unexpected change would likely produce a more immediate repricing across currencies, bonds and risk assets.
October 29 — Q3 GDP: growth versus expectations
The advance estimate for third-quarter US GDP is scheduled for Thursday. The previous quarter’s growth rate was 2.2% annualized, while a market-calendar estimate puts Q3 growth near 3.2%. That forecast is not the actual result and can change before release.
A stronger-than-expected number could support equities by showing that economic activity remains robust. But if strong growth also reinforces inflation concerns and delays expected rate cuts, the reaction could be less positive for high-risk assets.
A weaker reading could increase recession concerns, even as some investors begin to anticipate a more supportive future policy path. The details matter: consumer spending, business investment, inventories and trade can reveal whether growth is broad-based or concentrated in a few components.
October 29 — PCE inflation: the most important price-pressure check
The September Personal Consumption Expenditures report is the Fed’s preferred inflation measure. The latest published reading, for August, showed headline PCE inflation at 3.4% year over year and core PCE inflation at 3.0%. On a monthly basis, headline prices increased 0.3%, while core prices rose 0.2%.
The September report will show whether those pressures are easing, stabilizing or building again. I would focus on both monthly changes and annual rates, especially core PCE, which excludes food and energy.
Cooler-than-expected inflation could strengthen expectations for a less restrictive policy path. A hotter reading could keep Treasury yields elevated and put pressure on assets whose valuations depend heavily on future liquidity. A mixed result such as softer core inflation but stronger headline inflation would require a more careful interpretation rather than an automatic bullish or bearish reaction.
Consumer spending: is demand still holding up?
August personal spending rose 0.9% month over month, while inflation-adjusted spending increased 0.6%. That was a strong reading, but it also raises a question: can households continue spending at that pace if energy and other living costs remain elevated?
September spending will be released alongside PCE on October 29. Strong spending with cooling inflation would be a constructive combination. Strong spending with persistent inflation could complicate the Fed’s job, while weak spending alongside softer inflation could indicate that economic momentum is fading.
How I will read the reaction across markets
The US dollar, 10-year Treasury yield, Bitcoin, Ethereum, gold and Nasdaq will help reveal how investors interpret the same information.
If inflation cools and yields decline while the dollar weakens, crypto and growth stocks could find support—provided the data does not trigger serious growth fears. If inflation surprises higher and yields rise, the dollar may strengthen while risk assets face pressure. Gold could move differently depending on whether investors prioritize inflation protection, real yields or safe-haven demand.
That is why I will not assume every hot inflation print automatically sends Bitcoin lower or every soft print guarantees a rally. The surprise relative to expectations, the Fed’s response and the market’s positioning all matter.
Three scenarios I am watching
The constructive case: inflation cools, the Fed sounds balanced, and markets interpret GDP as sustainable growth rather than an inflation threat. Lower yields and improving risk appetite could support a recovery in BTC, ETH and the Nasdaq.
The mixed case: the Fed holds, GDP remains solid, but inflation stays sticky. Markets may remain volatile as investors debate whether rate relief will arrive soon enough.
The pressure case: PCE accelerates, the Fed emphasizes inflation risks, or growth weakens more sharply than expected. That combination could unsettle both risk appetite and the policy outlook.
My plan is to compare actual data with consensus, then watch the first market reaction and whether it holds after the initial volatility. I will pay particular attention to Treasury yields and the dollar before deciding whether a crypto or equity move has genuine macroeconomic support.
This is a week for evidence over assumptions. The Fed sets the tone, GDP tests the growth narrative, and PCE measures whether inflation is giving policymakers room to change direction. The most important signal may not be any single number, but the relationship between all three. @Gate_Square
$BTC ‌$ETH ‌$NAS100 ‌
repost-content-media
  • 3
new update
live-cover
LIVE1,997
#CanETHStabilizeAfterThePullback Ethereum’s $2,300 Test: A Rebound Is Possible, but Confirmation Matters
Ethereum is approaching a level where market behaviour matters more than optimistic predictions. With ETH around $2,316 in this analysis, the key question is not whether the price looks oversold. It is whether buyers can turn the $2,300 area into a reliable base after weeks of selling pressure.
My view is cautious: ETH is close to an important psychological support zone, but proximity to support does not automatically make it a buying opportunity. I want to see evidence that sellers are los
Falcon_Official
#CanETHStabilizeAfterThePullback
#WCTCS9 ‌ETH at $2,321: RSI Near Oversold, $2,280 Support and $2,371 Recovery Trigger
Ethereum is trading near $2,321, and the chart is approaching a critical short-term decision zone. My focus is on price structure, momentum, volume and liquidation pressure not simply whether ETH looks cheap after the pullback. My view is that ETH may stabilize temporarily, but further downside remains possible, while a sustained recovery could be difficult without stronger buying pressure and a clear technical breakout.
Support structure: $2,303–$2,280
ETH is trading close to the $2,300 psychological level. The first support zone is $2,303–$2,280. If buyers defend this area and ETH closes back above $2,303, a short-term recovery attempt becomes possible. A wick below support followed by a quick reclaim would suggest rejection of lower prices. However, a decisive breakdown followed by a failed retest would signal that former support is turning into resistance. In that case, $2,200 becomes the next downside reference not a guaranteed target.
Resistance levels that can change the structure
The first recovery trigger is $2,371. ETH needs to reclaim this level and hold it on a retest, preferably with increasing spot volume. The next resistance band is $2,400–$2,438. Rejection there would indicate that sellers remain active above the current price. A sustained break above $2,438 would provide stronger evidence of a short-term trend improvement, while the daily moving-average area near $2,436 and $2,541 remains important overhead resistance based on the available technical snapshot.
RSI and MACD: momentum still needs confirmation
The reported daily RSI near 32.5 places ETH close to oversold territory. That can precede a relief bounce, but oversold conditions can persist during strong downtrends. I would watch for RSI to turn upward and move back above 35–40 while price reclaims resistance.
Daily MACD remains bearish in the supplied technical snapshot, with the MACD line below the signal line. The key change to watch is whether the negative histogram starts contracting. That would indicate weakening bearish momentum, although a bullish crossover would still need price and volume confirmation.
Volume and candle confirmation
A move above $2,371 on weak volume is less convincing than a breakout supported by strong spot buying. I would look for a decisive candle close above resistance, followed by a retest that holds. On the downside, expanding sell volume below $2,280 would strengthen the breakdown case. A long lower wick alone is not enough; the following candles must show that buyers can maintain control.
Liquidations, open interest and funding
Recent market analysis identified leveraged long liquidations as a source of ETH selling pressure. The technical question is whether forced selling is easing. If ETH stabilizes while open interest declines, excessive leverage may be leaving the market. If price drops alongside rising sell pressure and fresh liquidations, downside risk remains elevated. Positive funding can also indicate that long positions are still paying to stay open, leaving them vulnerable to another sharp move. These indicators should be checked against current exchange data because readings differ by platform and update time.
Important: 😶😶
Geopolitical uncertainty and the midterm-election outlook
My personal view is that uncertainty surrounding the Iran–US conflict could keep risk sentiment fragile. I also expect the approach to the US midterm elections to remain an important political backdrop for markets. Under this scenario, ETH may stabilize at certain levels but still face further downside before a durable recovery develops. A temporary pause in selling does not necessarily mean that the market is ready to move higher. This is my market outlook, not a confirmed outcome; changes in the conflict, economic data or policy expectations could alter the picture.
The macro trigger: October 28–29
The Federal Reserve decision on October 28 and US PCE inflation release on October 29 could increase volatility. I would watch the dollar and Treasury yields alongside ETH rather than assume that any single economic result automatically sends crypto higher or lower. A supportive macro reaction could help ETH test resistance; an adverse reaction could put the $2,280 zone under renewed pressure.
My technical decision map is straightforward: above $2,371, watch for continuation toward $2,400–$2,438; between $2,303 and $2,371, expect an unresolved range; below $2,280 with a failed reclaim, watch the $2,200 area. These are conditional scenarios, not predictions.
At approximately $2,321, the chart has not confirmed a reversal yet. I would wait for the support reaction, RSI improvement, MACD stabilization and stronger spot volume to align. In my view, ETH could remain under pressure and fall further before a convincing recovery appears. The decisive signal is not how far ETH has already fallen it is whether buyers can reclaim broken levels and hold them. @Gate_Square
repost-content-media
ETH-3.15%
BTC-0.67%
  • 1
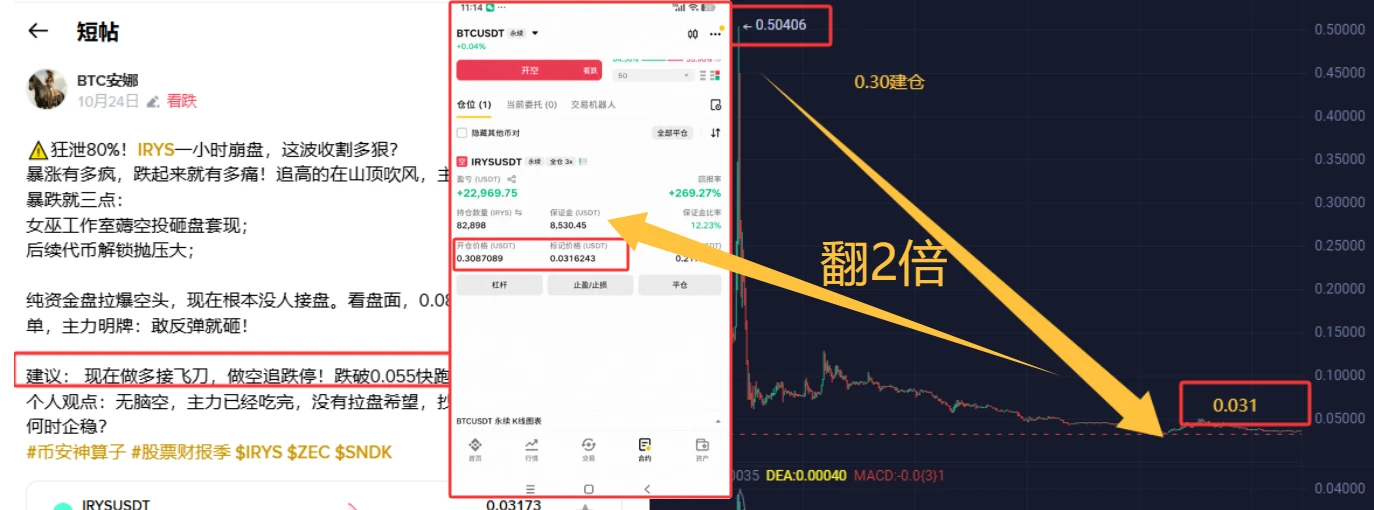
The Truth Behind IRYS’s Four-Day Crash: It Wasn’t a Pullback—A Short-Squeeze Bubble Got Popped!
The crazier the rally, the harder the fall.
IRYS has fallen for 4 straight days. Simply put, low circulating supply and high leverage fueled a short squeeze earlier on, sending it soaring even without fundamentals. Once the shorts were liquidated, forced buying disappeared and the bubble naturally burst. Then Sybil wallets dumped their airdrops en masse, token unlock expectations weighed on the price, and the Fed’s hawkish stance battered risk assets. Add shallow market depth and concentrated holdin
post-image
IRYS-21.17%
SNDK-0.18%
BIRB-15.48%
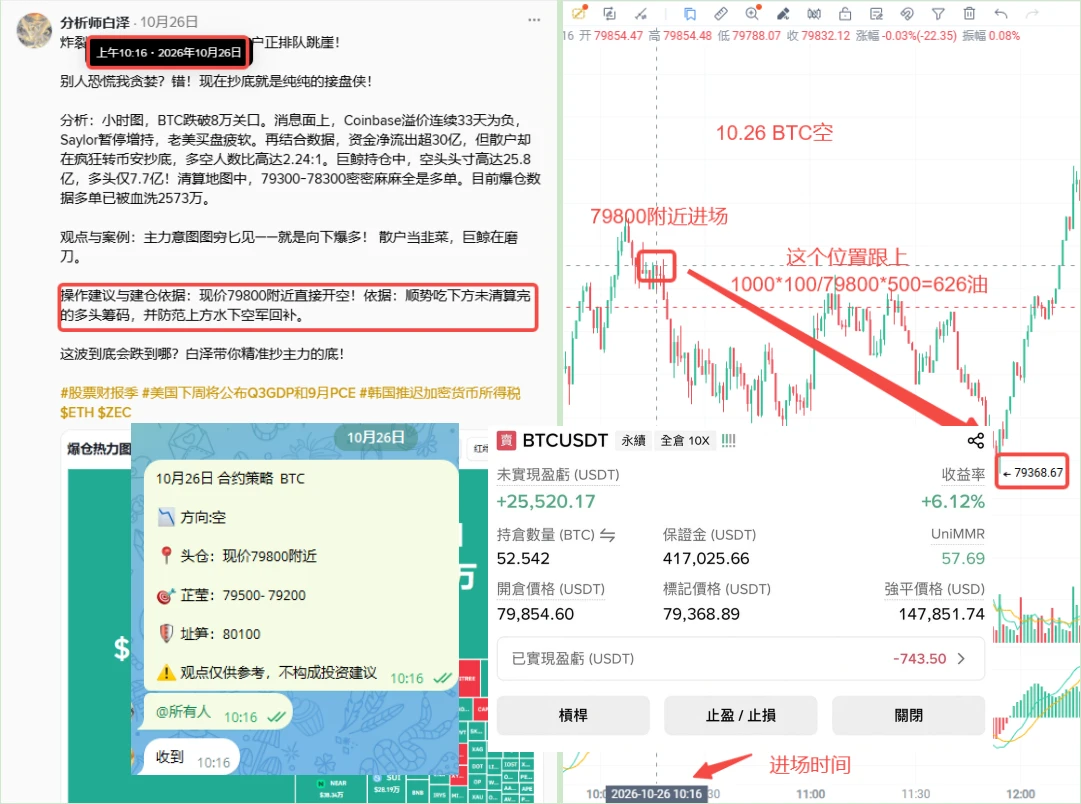
$BTC Bloodbath at $79,368! 190,000 liquidated, the $80,000 iron floor smashed!
At noon on the 26th, BTC flash-crashed to $79,368, driven mainly by risk-off capitulation ahead of the Fed’s rate decision and a collapse in AI tech stocks, compounded by 196,000 liquidations and $728 million wiped out (84% of them longs). Cascading leveraged liquidations directly broke through the psychological $80,000 threshold.
$80,000 has become strong resistance. If 78,400 fails to hold, the next stop is straight down to 75,000. Can your position withstand the other shoe dropping?#美股财报季
post-image
BTC-0.65%
Load More

Join 40 M users in our growing community

⚡️ Join 40 M users in the crypto craze discussion

💬 Engage with your favorite top creators

👍 See what interests you

Trending Topics

USEarningsSeason

157.1k Views2.38k Discussing

The U.S. Q3 earnings season is in full swing, with major tech companies including Tesla and Meta reporting results. Market focus is shifting beyond revenue and profit toward AI spending, capital expenditure, margins and forward guidance. Which company’s earnings are you watching most closely?

KeyMacroWeekAhead

7.63k Views980 Discussing

BTCBattlesFor80000

121.34k Views25.17k Discussing

View More