Square
Following
Hot
News
Profile
Share your thoughts
placeholder
Article
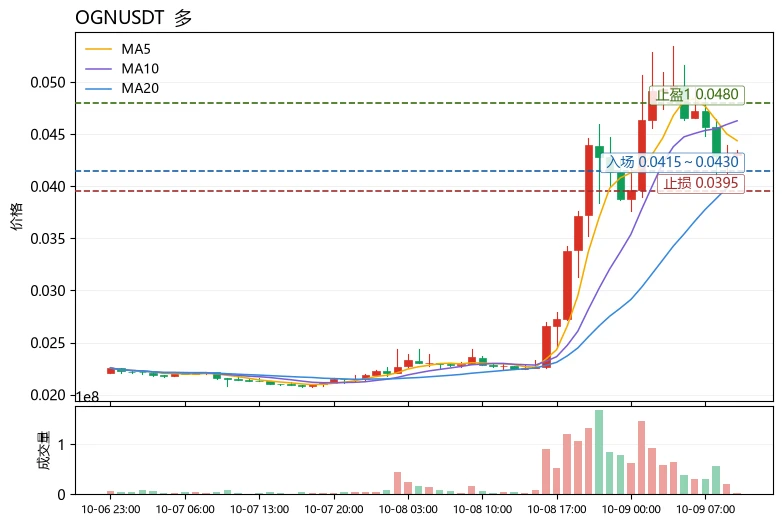
Guys, the moment we’ve been waiting for has finally arrived. I’m now preparing to open a short-term short position with 10x leverage on $OGN
…📉‼️My entry price: $0.0415 – $0.0425Take-profit 1: $0.0395Take-profit 2: $0.0370Take-profit 3: $0.0340Take-profit 4: $0.0300Stop-loss: $0.04774Click below and trade with me…👇Strategy logic:* $0.0415–$0.0425 is the key entry range for this short trade.* If the price fails to hold above $0.0425, selling pressure may increase.* If it breaks below $0.0395, the price may continue falling toward $0.0370 and $0.0340.* As required, the maximum downside target
post-image
OGN+92.64%
Is Lobster about to rebound? Its 4-hour open interest increased by 21%, the highest among all altcoins.
The long/short ratio is 138%, with 63 whales opening positions at around 0.045.
Can Lobster return this time? $Lobster ‌
龙虾+24.97%
Featured#美联储9月纪要偏鹰
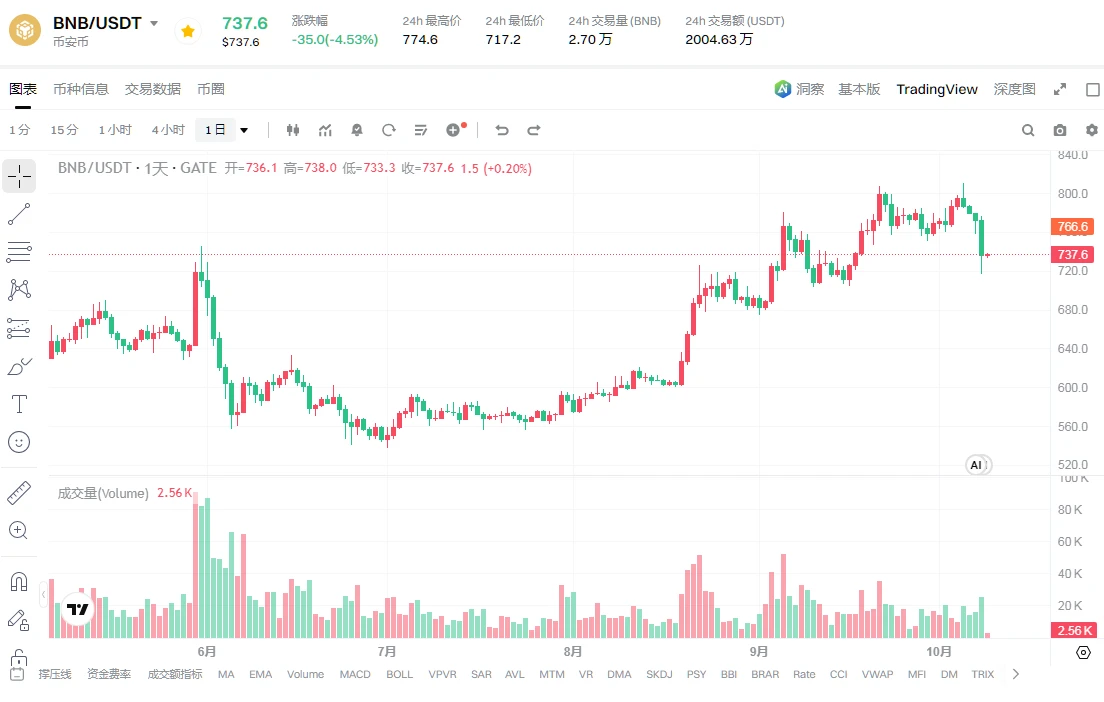
The US moving coins is scary; combined with the renewed US-Iran war and rate hikes, the broader market shudders and platform tokens get hit first. $BNB This bearish candle looks intimidating, but I’m not panicking: 811 was tested twice and failed to break through, so a pullback was only a matter of time; the key is the 716.85 wick, which landed right on the medium-term moving average and the 0.382 retracement of the 537→811 move, then reclaimed 734, clearly showing buyers below. Funding rates are nearly flat, which doesn’t look like an overleveraged long squeeze, but rather a stron
post-image
BNB-3.86%
  • 5
  • 2
always remember the best case scenario
post-image
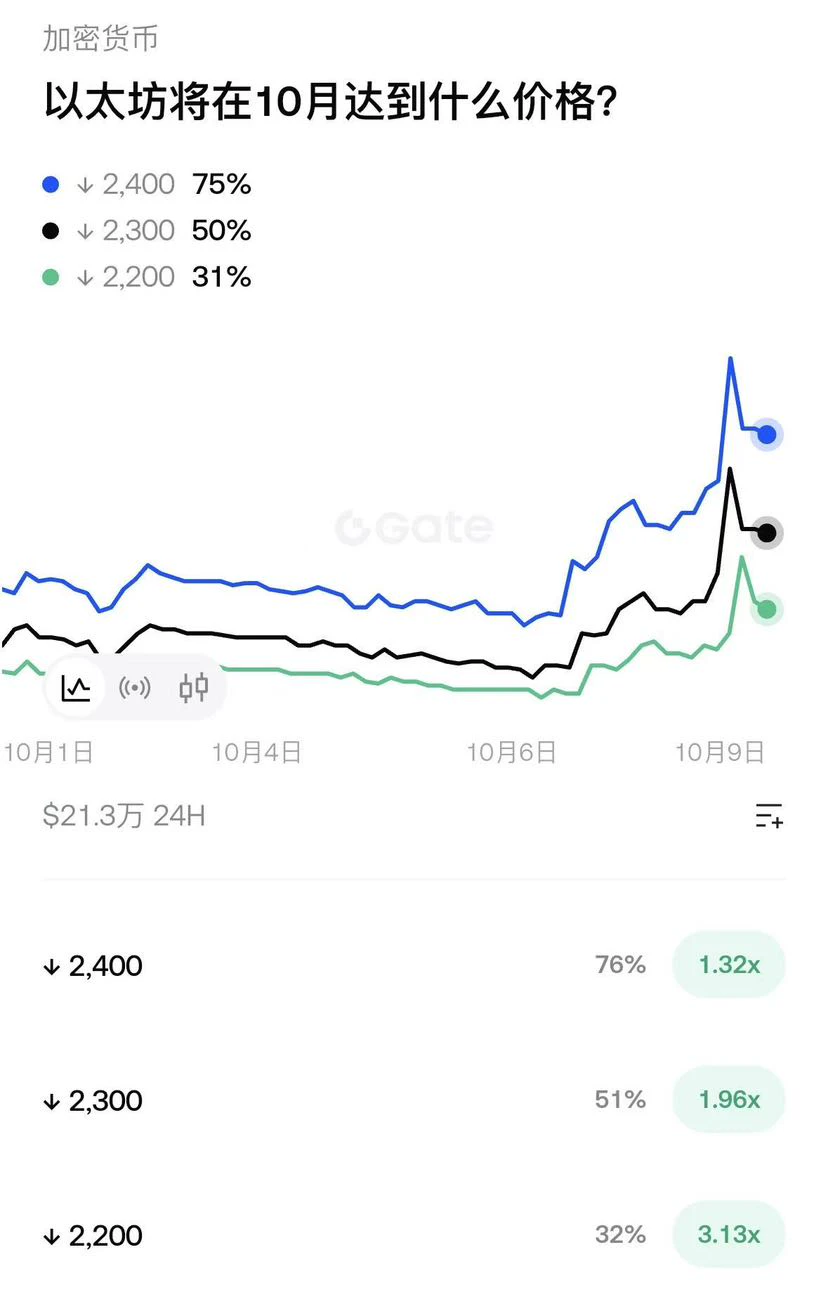
In October, market sentiment toward Ethereum is bearish, with the vast majority of participants believing ETH has momentum to test below 2400.
Breaking below 2400 is the baseline expectation; a further decline to 2300 or 2200 would be an unexpected downside move with a significant odds advantage.
Overall, short-term downside expectations are strong, but the probability of an extreme plunge is limited, with the main strategy focused on trading range-bound bottom-finding.
post-image
ETH-2.87%
10.9 Market Overview Analysis
ETH Silk Road Reference Setup
Rebound range: Long near 2460
Stop-loss: 2430
First target: 2500, second target: 2550
ETH is currently quoted near 2475. After the previous sharp decline, it tested a low of 2405.07 before forming a V-shaped short-term rebound. The MACD green bars continue to contract, indicating that bearish momentum has been fully released and that short-term rebound recovery is needed. However, the moving averages on the larger time frame are still trending downward. Overall, this is a weak rebound following a major decline. Long positions should o
BTC-0.46%
ETH-2.93%
Fear & Greed Index: 59, in the greed zone. BTC’s recent stabilization has driven rotational gains in the altcoin sector. $OGN surged 84.19% in 24 hours, with the current price at 0.04321 and trading volume reaching 59.2M USDT, showing a clear influx of funds. In terms of moving averages, MA5=0.04437 has crossed above MA20=0.040837, with a bullish alignment beginning to form; however, RSI=62.4 has not yet entered overbought territory, leaving room for further upside. The MACD histogram=-0.0006416 indicates potential divergence concerns in short-term momentum. The key signal is the funding rate
post-image
OGN+92.86%
DOGE-4.02%
RLC+37.26%
After retreating to the $81,000 level, Bitcoin recovered and settled around $82,000. The daily decline narrowed to 1.54%. However, the market remains focused on the $81,000 mark; this is precisely where buyers and sellers are squaring off.
The $81,000–$81,500 range is an area where buy orders have concentrated in recent days, with buyers increasing their positions there. Analysts identify the $81,119 level as support, while pointing to the $86,500–$86,750 range as resistance. In other words, $81,000 is not an arbitrary level; it is the floor that has held firm in recent weeks.
So, why did it d
post-image
User_any
#BTCPullsBackTo81000 Yo, so check it. Bitcoin slid under $82K for the first time in three weeks, and nah, it ain't one thing that did it. Three things hit at once, straight up.
First off, the Fed. Them September minutes dropped October 7, and all nineteen of 'em backed that quarter-point hike to 3.75–4.00%. Most said yeah, another one by year-end probably makes sense. But here's the thing — the market ain't buying it for October. Odds sitting at like 17% for October, but December? Around 70%. And that matters, 'cause when rates stay high, holding stuff that don't pay you nothing gets expensive. 10-year yield hanging near 5.3%, 30-year near 5.67%. That's decades-high type energy.
Second thing — Iran. Word is the White House told the Pentagon to get strike options ready, but nothing popping off before the midterms. Strait of Hormuz still a mess. Brent at $101.53, WTI at $89.39. Expensive oil means inflation ain't going nowhere, and that keeps the Fed chilling on the sidelines.
Third thing, and this the one that really hurt — leverage. Around $709 to $769 million in positions got liquidated in 24 hours. Longs took $647 to $685 million of that. Bitcoin longs alone, $172 million. Roughly 140,000 accounts got smoked. Open interest dropped 3.27% down to about $52.57 billion. That ain't people changing their minds — that's forced selling, plain and simple.
Institutional money? Mixed bag. US spot Bitcoin ETFs pulled in $118.86 million last session, total assets near $110.68 billion. But Ether ETFs? Lost $202 million same day. Them two ain't moving together no more.
Supply side — government wallets moved 12,267 BTC, 'bout $1.01 billion, to fresh addresses. No exchange deposit, so looks more like reshuffling than dumping.
Chart-wise, Bitcoin ran from $83,299 down to $80,397 before settling near $82,063. The $80,500 to $81,500 zone? That's where last month's highs sat, and that's what everybody watching. Hold there, we cool. Break it, and now we asking if the forced selling is done.
Next real test? October CPI and PPI. That's gonna tell us if inflation really cooling or if this pressure still building.
This ain't investment advice, just keeping it real.
$BTC ‌

BTC-0.40%
  • 4
  • 1
A technical analysis and a potential trade plan of $PI ‌
Chart Analysis
1. Higher Timeframe (1H Chart ):
· Trend: Bearish to Neutral. The price suffered a significant drop from ~0.088 to a low of 0.07749. It is currently attempting to recover.
· Moving Averages: The price (0.08150) is trading just above the MA5 (0.08122) and MA10 (0.08104), but slightly below the MA30 (0.08138). This indicates short-term consolidation and a potential fight for trend reversal.
· MACD: The MACD line (DIF) is below the signal line (DEA), and both are below the zero line. However, the histogram is showing signs o
PI+0.48%
MARKET UPDATES
live-cover
LIVE1,520
BTC and Ethereum market surges predictions
live-cover
LIVE2,428
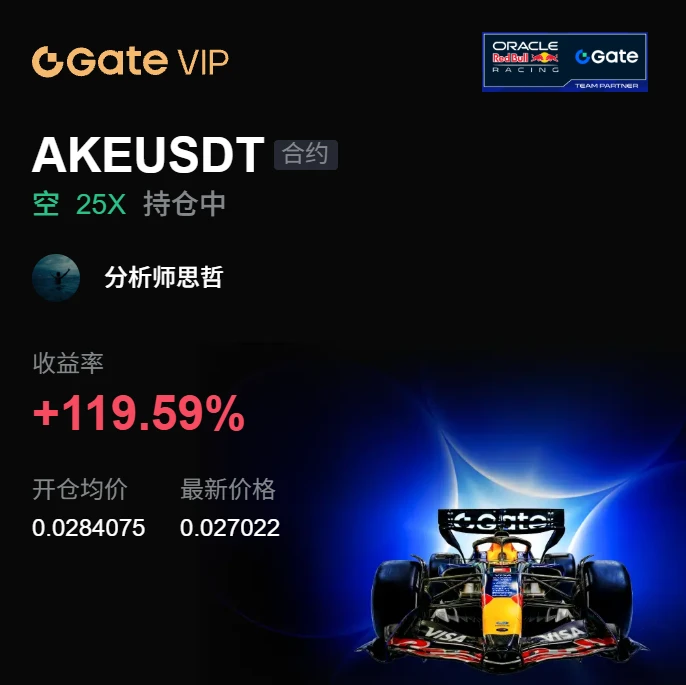
I only wanted to mooch a breakfast, but the market ended up trapping me for half a year. A few days ago, I stayed up before dawn watching $AKE surge to the highs. Volume failed to follow, and every push higher fell just short. I called it bullish at the time, but with clear resistance overhead—don't chase.

The market is waited out, and profits are held onto.

Shorting from 0.0284075 all the way down to 0.0270009, +117.87% says it all. That was a satisfying bite of profit. Those already in the trade should be waking up smiling. It was truly sluggish earlier, but the result is truly sweet. T
post-image
AKE-0.92%
ZEC-6.52%
LAB-0.85%
Guys, $KSM is rebounding strongly from the $4.45 support zone. Buyers are pushing the price higher, and if momentum continues, the next rally may be coming.
Entry: 4.75–4.78 Take Profit 1: 4.80 Take Profit 2: 4.85 Take Profit 3: 4.90 Stop Loss: 4.46 Buy and trade $KSM$ZE
post-image
KSM+1.14%
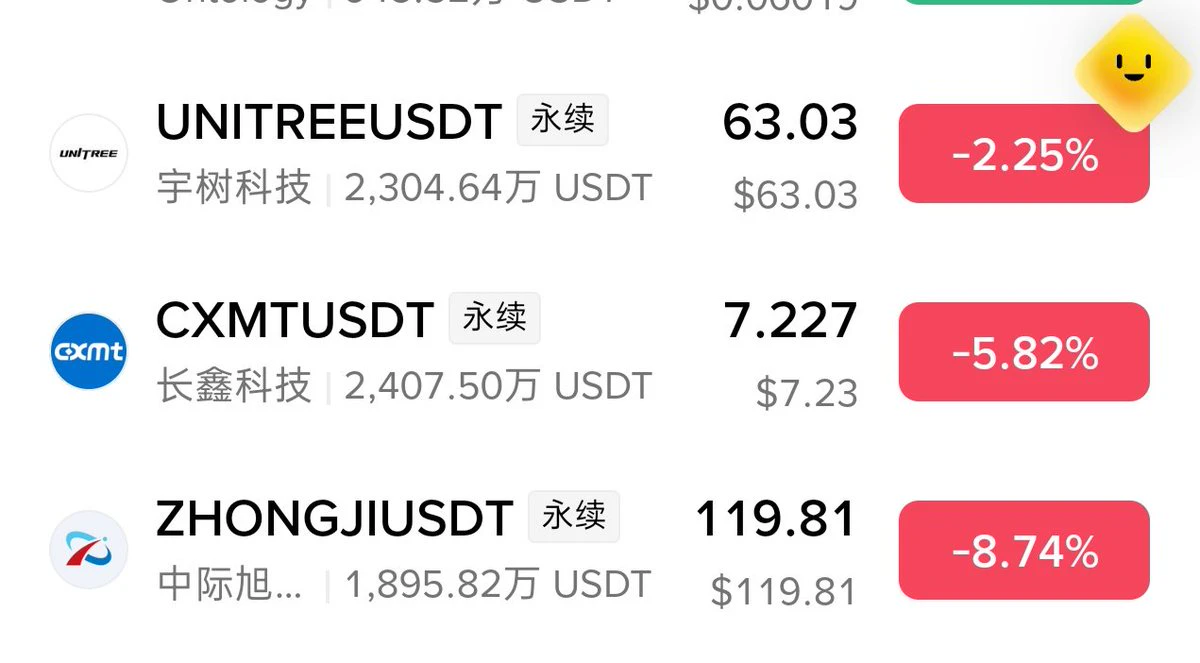
The three A-share stocks I have been shorting all along—ChangXin Memory Technologies (CXMT), Innolight Technology, and Yushu Technology—plunged today. It looks like the bubble in A-share tech stocks is about to burst!#CXMT
post-image
One benefit of being on the conference circuit is being able to stay in close contact with the old OGs when the market becomes highly volatile and ease the stress😆
Yesterday, I happened to be having dinner with Brother Sun when the crash hit. My phone kept lighting up with alerts, but fortunately all the strategies had already been set, so I knew which orders had been triggered without even checking.
I also chatted with a few old friends. Everyone was quite calm—eating and drinking as usual.
Recently, there have been quite a few objective negative factors affecting the market: the bill failed
post-image
BTC-0.40%
$UAI Breakout imminent! Technical indicators have all formed golden crosses—have you gotten on board? Where is the next target?#Gate.io 🔥🚀 #Gate广场中秋团圆局
UAI+14.75%
#浇朋友 #蓝v互关
The current employment environment~
I found a job in Chengdu with a monthly salary of 6000
Working hours are from 9 a.m. to 9 p.m. (with a three-hour break in between)—alternating one- and two-day weekends
The company provides afternoon tea, snacks, tea, coffee, and... every day
Most importantly, they provide cigarettes!!!
post-image
#美联储9月纪要偏鹰 #每周来晒 Fed's September Meeting Minutes Send Important Signal: “Insurance Rate Hikes” Are Making a Comeback!
The key change revealed in the Fed's September meeting minutes is not simply a “more hawkish” stance, but the return of risk-management thinking to policy decisions. Barclays believes the minutes show that the Fed is beginning to place greater emphasis on guarding against inflation risks in advance. Some officials believed further tightening remained necessary under the baseline scenario, while others viewed additional rate hikes as “insurance” against the risk of demand exceed
post-image
ThisIsTranslateContent:
#美联储9月纪要偏鹰 #每周来晒 The Fed’s September Minutes Send an Important Signal: “Insurance Rate Hikes” Are Making a Comeback!
The key change revealed in the Fed’s September meeting minutes is not merely a “more hawkish” stance, but the return of risk-management thinking to policymaking. Barclays believes the minutes show that the Fed is beginning to place greater emphasis on proactively guarding against inflation risks. Some officials believed further tightening remained necessary under the baseline scenario, while others viewed additional rate hikes as “insurance” against the risk of stronger-than-expected demand or renewed supply-side shocks. At the September meeting, the Fed raised the federal funds target range by 25 basis points to 3.75%-4.00%, with all participants supporting the decision; most officials believed that one more rate hike before year-end “could be appropriate.” The Committee also emphasized that subsequent policy would depend on economic data and the balance of risks. Goldman Sachs believes the minutes show a strong consensus among officials in favor of further tightening, but that “insurance rate hikes” do not mean future action has been determined, with whether to continue raising rates ultimately depending on inflation and economic data. The two institutions have broadly similar views on the near-term path: no move in October and one more rate hike in December. Their main difference is that Goldman Sachs believes the FOMC may ultimately conclude that no further tightening is necessary as the data change, while Barclays expects rates to remain unchanged for most of 2027 after a December hike.
I “Insurance Rate Hikes” Return: Risk Management Becomes the Policy Logic Again
The minutes show that many participants supported a higher policy-rate path, mainly for risk-management reasons. If demand remains stronger than expected or the supply side is hit by another shock, raising rates in advance could reduce the risk of inflation remaining above target for an extended period. However, some officials believed that further rate hikes were necessary under their baseline scenario, rather than merely serving to guard against potential risks. This distinction determines the flexibility of subsequent policy: if rate hikes are primarily a risk-management measure, the Fed can stop tightening once inflation data improve and the balance of risks changes; if further hikes are necessary under the baseline forecast, it means rates still have room to rise. Barclays believes this is the exact opposite of the logic during the previous rate-cutting cycle. At that time, the Fed believed downside employment risks outweighed upside inflation risks, allowing it to cut rates preemptively; now the balance of risks has tilted back toward inflation, and policy is once again leaving room in advance for a potential inflation rebound.
II Hawkish Bias Clear, but December Still Depends on the Data.
The hawkish judgments in the minutes mainly stemmed from inflation. All participants believed inflation remained elevated and that progress in reducing it had been insufficient in recent months; nearly all officials saw inflation risks as tilted to the upside, with some believing those risks had increased further. At the same time, risks in the labor market were viewed as “broadly balanced” and were no longer considered a major obstacle to further policy tightening. Several officials also believed that the policy rate before the hike was “not restrictive or only mildly restrictive,” while several others raised their estimates of the neutral rate. However, the minutes repeatedly emphasized that policy would “depend on the incoming data.” Goldman Sachs expects another 25-basis-point hike in December, but believes that as more data are released, the Fed will ultimately “likely conclude that further tightening is unnecessary.”
III AI Investment Becomes a New Inflation Variable
Another notable change in these minutes is that AI investment was explicitly identified as a potential source of inflation for the first time. Several officials pointed out that as the effects of AI infrastructure construction gradually emerge and the impact of tariffs gradually fades, core goods inflation could remain elevated; some officials warned that the AI construction boom could push aggregate demand above aggregate supply, creating new inflationary pressure. At the same time, some of the pressure on PCE inflation may simply reflect temporary distortions caused by statistical methodology. A few participants noted that software and asset-management fees had made significant contributions to recent PCE data, and that this impact was expected to fade as the U.S. Bureau of Economic Analysis (BEA) adjusted its statistical methods. According to a Barclays report, Fed staff expected at the September meeting that the BEA revision would lower year-over-year PCE and core PCE growth by approximately 0.2 percentage points, but the actual revision was about twice as large as expected, bringing year-over-year core PCE growth down to 3.0%, with the three-month annualized rate close to 2%. This means that the inflation backdrop at the September meeting was in fact more severe than indicated by the latest data: AI investment could generate genuine demand-driven inflationary pressure, while software and asset-management fees included a degree of statistical distortion. The revision to the latter weakened part of the basis for supporting further rate hikes at the time.
IV Economic Outlook Improves, Leaving Room for a Policy Shift
Fed staff raised their inflation forecasts for 2026 through 2028, expecting the effects of tariffs, geopolitics, and AI-related factors to gradually fade, with inflation eventually returning to the 2% target in 2029, though risks remained tilted to the upside. At the same time, the economic and employment outlook improved. Staff expected real GDP to rebound in the second half of this year and remain above potential growth through 2028; the unemployment rate was expected to remain below its long-run level through 2029. Goldman Sachs noted that some officials attributed the rise in long-term U.S. Treasury yields to a stronger economy, increased expectations of AI-related borrowing, and geopolitical factors, while most officials believed overall financial conditions remained supportive of economic growth. Barclays maintained its baseline expectation of a 25-basis-point hike in December, but believed that the inflation revisions, recent weakness in economic data, and a slowdown in labor supply could ultimately lead the Fed to abandon further rate hikes. Therefore, the current policy path is becoming clearer: the Fed is once again adopting a risk-management approach to rate hikes, but whether this “insurance” is actually needed still depends on subsequent data. If inflation continues to cool, the need for a December hike will diminish; if AI investment drives continued demand expansion and inflation comes under renewed pressure, the case for further tightening will strengthen.
repost-content-media
GS-0.60%
  • 3
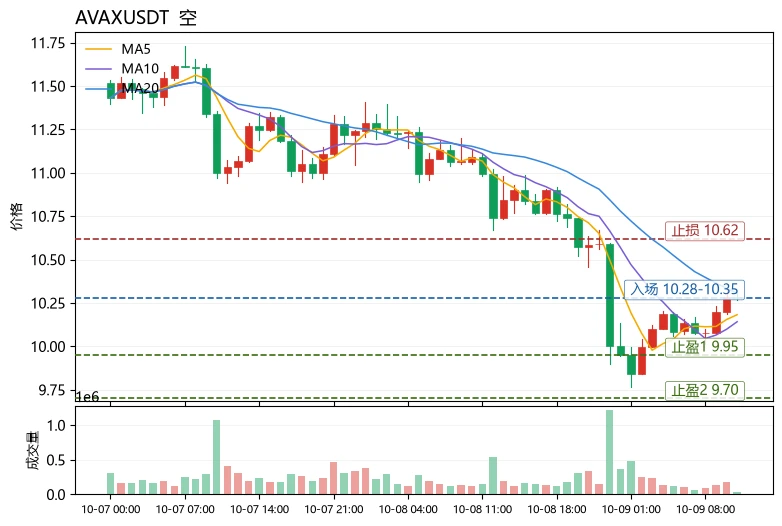
$AVAX Key short-term levels are 10.18 and 9.68: the current price is 10.277, MA5=10.1826 has crossed below MA20=10.3064, and the short-term moving averages are weakening. However, the price remains above MA5, indicating weak consolidation after a sharp decline. It is down 6.67% over 24h, with a trading volume of 61.3M USDT. The volume does not indicate panic selling, suggesting that selling pressure is mainly from long-position reductions rather than a broad-based exit.
From a fund-flow perspective, the Fear & Greed Index remains at 59, still in the greed range, meaning that bottom-fishing fu
post-image
AVAX-6.56%
ORCA-10.18%
STRK+32.16%
Load More

Join 40 M users in our growing community

⚡️ Join 40 M users in the crypto craze discussion

💬 Engage with your favorite top creators

👍 See what interests you

Trending Topics

Gate Money Officially Launches

3.49k Views12.91k Discussing

Gate officially launches Gate Money, a global integrated financial services app that brings digital assets, fiat, stocks, ETFs, gold, bank accounts, and payments into one Gate App. Users can manage assets, invest, send and receive funds, convert currencies, and make payments — all from a single account. Which use case are you most excited about? [👉 Learn more](https://www.gate.com/announcements/article/102094)

BTC Pulls Back to 81000

25.4k Views35.66k Discussing

AIStocksFallALABDropsOver9%

24.57k Views543 Discussing

View More