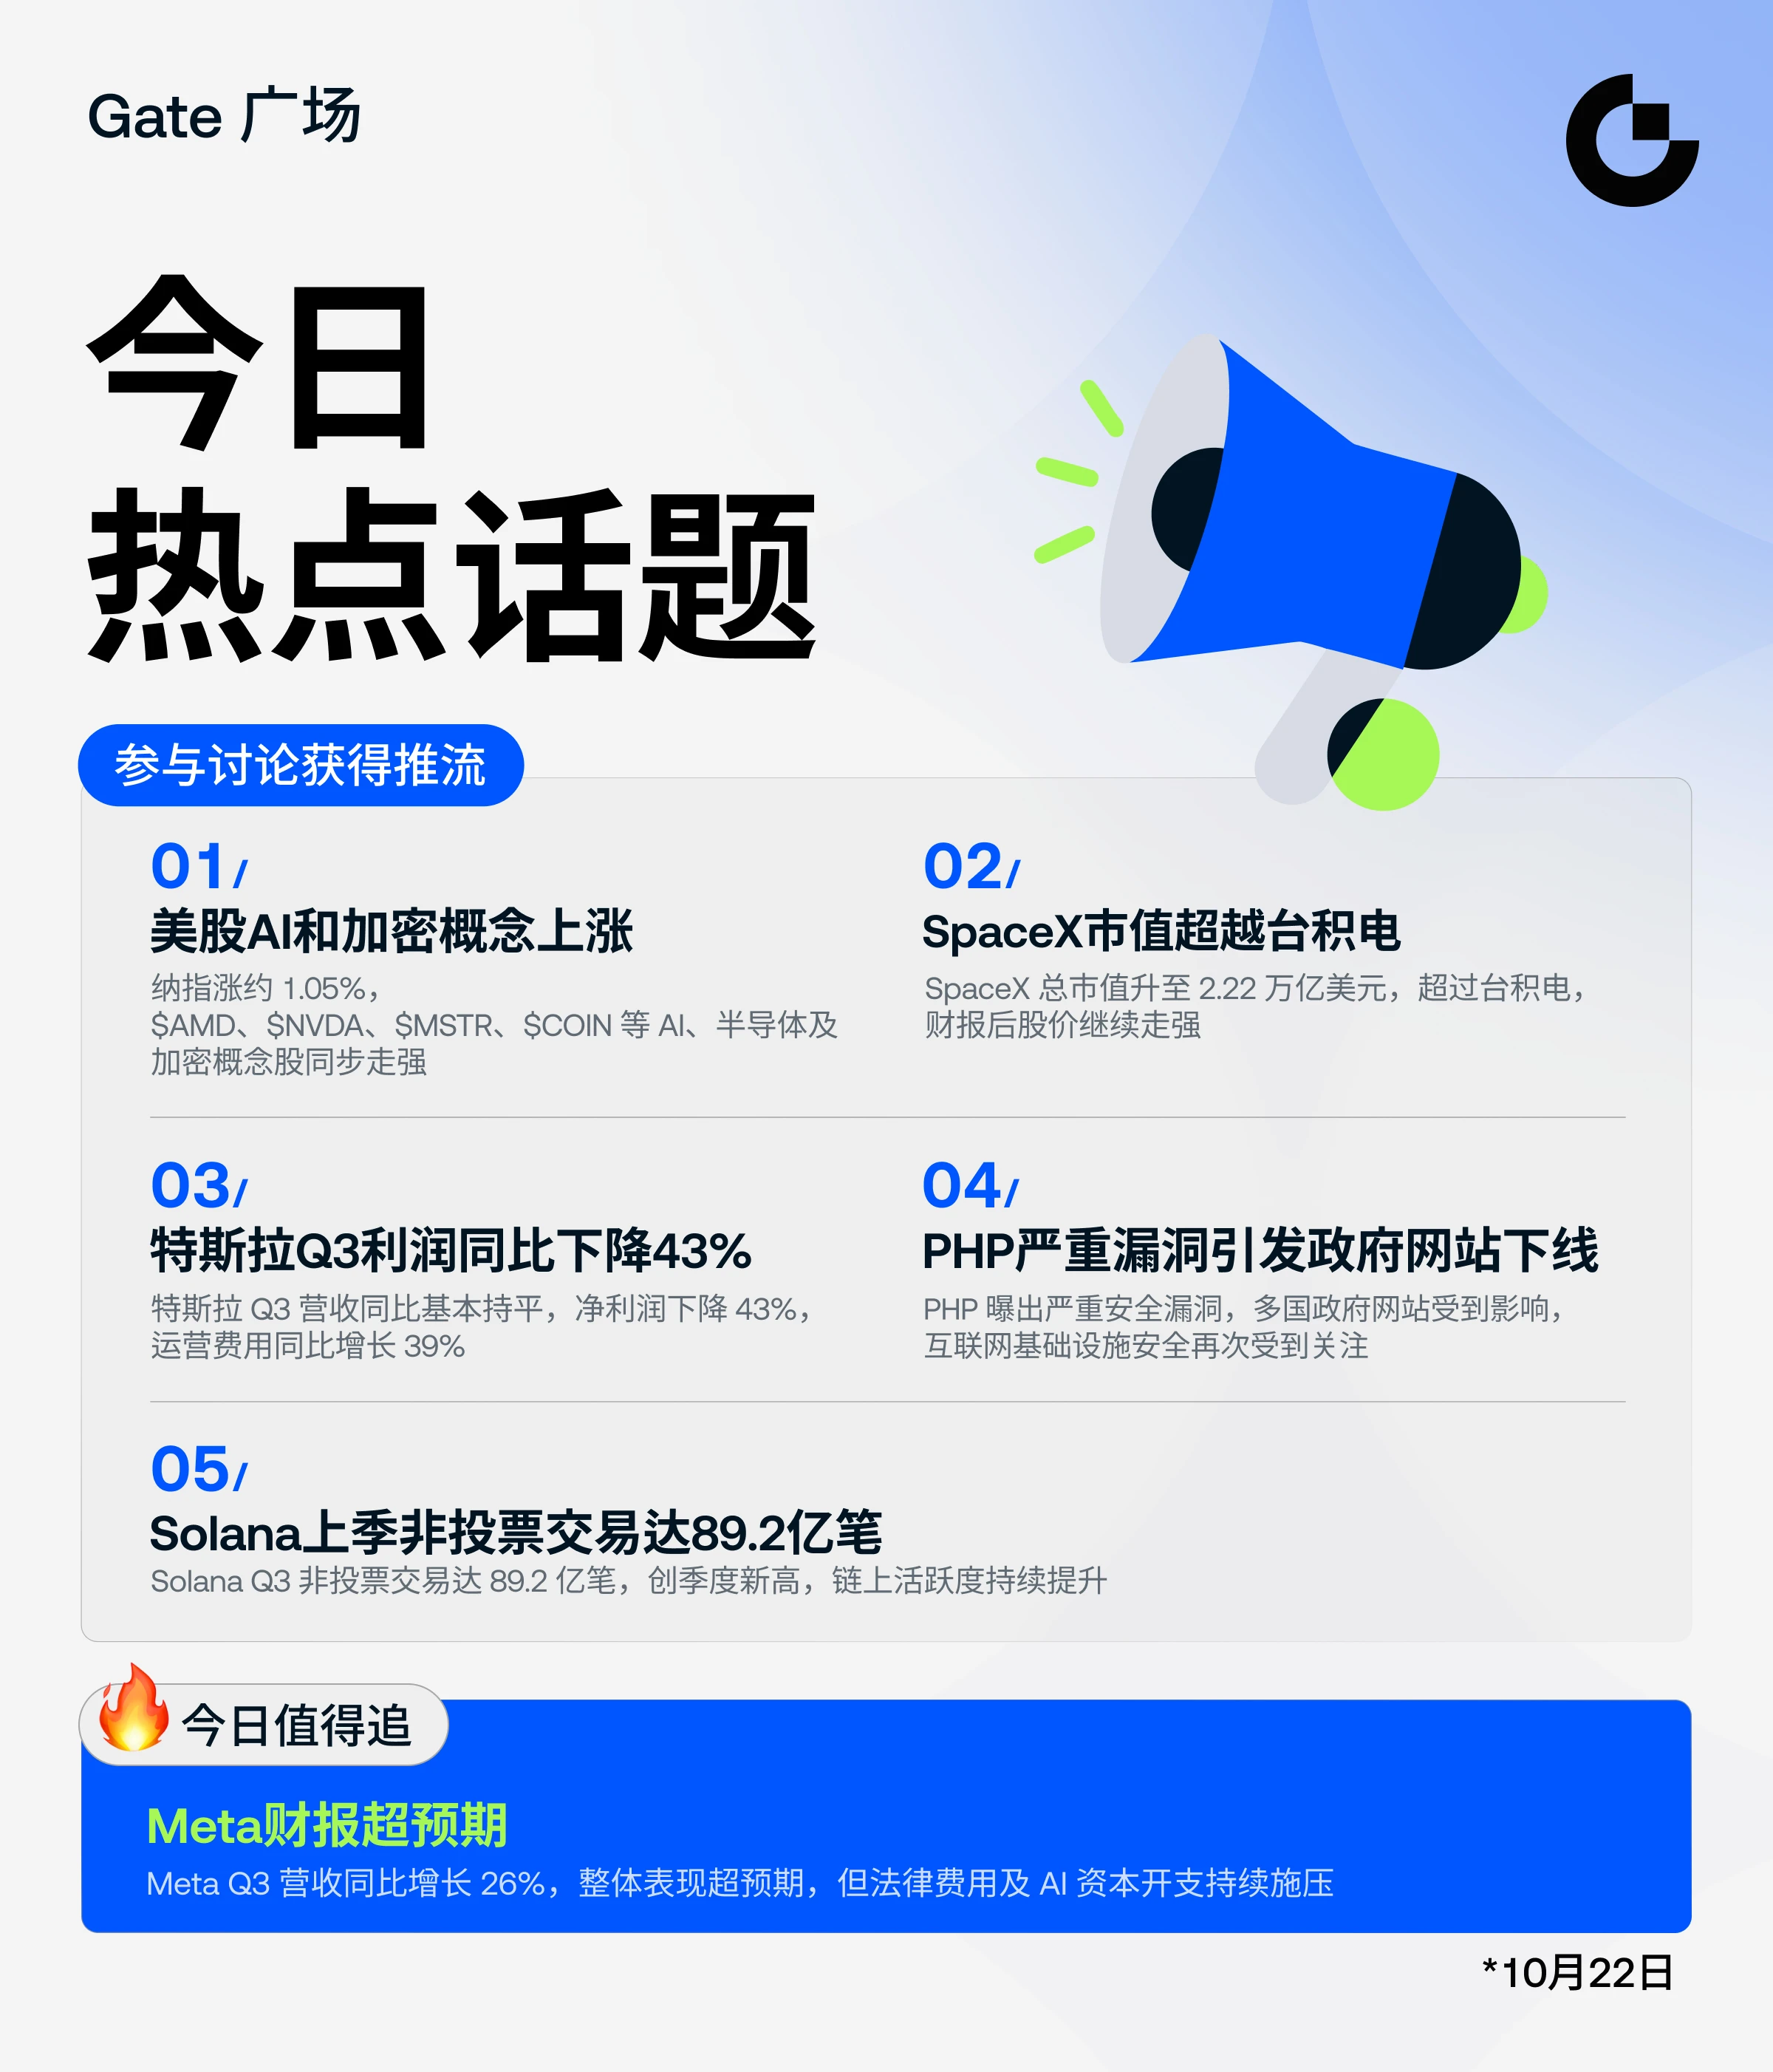






#SpaceXMarketCapSurpassesTSMC
#WCTCS9 SpaceX vs TSMC: the overtake that lasted a few hours, and where the gap stands at $155.75
SpaceX briefly passed TSMC in market value on Wednesday, and the headline spread fast. The margin was thin, though, so here are three snapshots, a check on what moved them, and the current gap.
The June peak
After its June debut, SpaceX shares ended one Monday nearly 20% higher, pushing market value to $2.52 trillion and past TSMC. That was the high point. By late July, shares had fallen roughly 50% from the peak reached the week after the IPO. The June overtake came on IPO excitement, not on earnings.
Early October
As of October 5, TSMC ranked sixth with a market value of about $2.45 trillion, and SpaceX ranked seventh at about $2.09 trillion. TSMC was ahead by roughly $360 billion.
Wednesday, October 21
Then SpaceX reported. Third-quarter revenue came in at $14.6 billion, up 161%, and shares surged more than 12% intraday to $165.641, the biggest single-day gain since August, with market value reaching $2.25 trillion. At one reading, SpaceX traded at $163.39 with a market cap of $2.22 trillion, against TSMC's $2.21 trillion at $426.535 per share. That was the overtake, and it was about $10 billion wide.
Why it did not hold
The gain narrowed through the session. It had faded to above 9% by publication time, and SPCX closed at $159.31, up 7.79%. At $155.75, I estimate market value at about $2.12 trillion, using the share count implied by the $2.22 trillion reading at $163.39. TSMC was near $2.21 trillion at the same time. By my math, SPCX needs about $162.60, roughly 4.4% higher, to match it again. Providers use different share counts, so treat the exact gap as approximate.
Why TSMC slipped
TSMC's own results were not the cause. It reported Q3 revenue of about $46.72 billion, up 41.2%, and guided Q4 revenue to $52.3 billion to $54.3 billion. Its market value fell from about $2.45 trillion on October 5 to about $2.21 trillion, roughly 10% lower by my math, during a broad pullback in AI chip shares. So the flip reflects TSMC's decline as much as SpaceX's rise.
The valuation gap behind the headline
SpaceX's Q3 revenue of $14.6 billion annualizes to about $58 billion, which puts its market value at roughly 36 times annualized sales. TSMC's $46.72 billion annualizes to about $187 billion, or roughly 12 times. By my calculation, the market pays about three times as much per dollar of revenue for SpaceX.
The reason is growth expectations. Musk projected annual recurring revenue could reach as much as $1 trillion by the end of 2027, and Q1 2027 revenue guidance is $33 billion to $37 billion. Investors are pricing a plan that has to be delivered.
The profit side
SpaceX posted its first profit as a public company, with operating income of $2.79 billion and net income of $4.4 billion, while guiding Q4 capital spending to $35 billion to $40 billion. Annualizing net income gives roughly $17.6 billion, which puts the stock near 120 times earnings by my arithmetic. TSMC is a mature profit engine with steady growth, which is why the two valuations differ so much.
What the ranking does and does not show
A market-cap ranking is share price times share count, and it changes every tick. It does not measure business size, profit stability or earnings quality. SPCX also remains well below its highs: against a 52-week high near $225.64, today's price is about 31% lower by my estimate.
Levels at $155.75
Resistance: $159.31 (Wednesday's close), then $162.60 (the level that matches TSMC), then the $163 to $166 intraday high zone.
Support: $150 to $152, then $147.79, the pre-earnings close. A break below $147.79 would erase the earnings gap.
What decides the next move
1. Capex funding. A $35 billion to $40 billion quarter needs a clear financing path.
2. Tesla merger committees. Both companies formed special committees, and any news could move the stock, though Musk said a deal is not a certainty.
3. TSMC's recovery. A rebound in chip shares would widen its lead again.
4. Execution. AI revenue growth and the Q1 guide of $33 billion to $37 billion are the proof points.
My take
The overtake was a momentum signal, not a verdict. The substance sits in revenue growth, profit and spending. I would track those, size small, and avoid chasing a stock that moved double digits in a single session.
SpaceX deserve a higher value than TSMC, and which level are you watching.
Manage your risk. #Shareweekly @Gate_Square