Square
Following
Hot
News
Profile

tiezhu

vip
Active for: 2.9y
Peak Tier 2
No content yet
11
Following
14
Followers
70
Liked
The main problem with this data is core CPI. This will further constrain the room for these officials’ previous public comments that they were “in no hurry.”
Perry Mehrling has passed away. I would like to pay special tribute to him.
He may be the teacher no one researching macroeconomics, money, and liquidity can avoid. Many people have probably watched the Bilibili course on money and banking more than once. His conversations with Zoltan are also well worth studying closely.
Perry Mehrling deeply influenced many of my analytical perspectives, especially the use of balance sheets as a foundational analytical tool. The concept of the hierarchy of money runs through all of my analyses of liquidity.
Many contradictions in the modern financial system,
Tomorrow, I’m going to give a class to students at Hong Kong Baptist University.
I asked the professor teaching the course to collect feedback in advance on what the students were interested in, but unfortunately, the feedback was that the graduate students knew absolutely nothing about Web3. I was actually quite surprised. I always feel that the stratification among those born after 2010 is quite pronounced as well; I’ve previously interacted with student groups from several universities in Hong Kong.
With some, you can feel their eagerness and ambition to give things a try; with others, you
Recently busy with other things, but now that they’re over, I’m back on x—time to start posting updates!
Thanks @moonkim for the invitation!
The new year of 2049, but doing the math, there are still 23 years until 2049. I really wonder what the world will look like 20 years from now.
I just responded to an inquiry from a foreign media outlet, which touched on the easing of market pressure for rate hikes, with Waller’s stance being particularly important.
Objectively speaking, Waller does not belong to the traditional hawkish or dovish camp, but is a centrist. Over the past four or five years, almost every one of his remarks has been broadly consistent with the FOMC’s final decision.
The key point is that he is a permanent voting member and a governor with genuine voting power. His remarks this time came after Warsh had taken a clearly hawkish stance. This means that the pa
Looking at Kevin Liu’s research report, I deeply agree with one line:
If Powell had delivered such hawkish remarks at Jackson Hole, a rate hike in September would have been a certainty.
Unfortunately, Warsh is not Powell. He repeatedly emphasized that people should not engage in forward guidance. But these remarks will still be interpreted as suggesting a possible rate hike in September.
One counterintuitive fact is that if Warsh/Trump/Bessent need a looser environment in the future, they must maintain an extremely hawkish stance for now.
However, if we look further at the probability priced i
Let's talk about the appreciation of the renminbi.
1. The renminbi's appreciation this year has mainly been driven by the surplus in foreign exchange settlement and sales. The figure for the first half of 2026 has basically already exceeded that of the whole of last year.
It is estimated that some existing dollar holdings are also being converted into renminbi amid the dollar's weakness. At the same time, it cannot be ignored that residents' foreign exchange purchases, overseas investments, and capital outflows are being strictly controlled.
In other words, the pressure of capital outflows was
Seriously, everyone should stop believing in the so-called independence of the Federal Reserve.
Independence is a narrative, not a fact. The Fed’s independence is relative; it has not actually detached itself from fiscal policy and operated independently.
It only means that the Fed has the authority to independently exercise monetary policy tools, but that does not mean its exercise of power is free from real-world constraints, especially fiscal constraints.
The coordination of fiscal and monetary policy is inevitable for modern economic development. Under normal circumstances, everyone makes
Last night’s discussion in the group. Let’s take a closer look at gold pricing and why the relationship between gold and real interest rates has changed.
1. Gold and interest rates have traditionally been inversely related. There are two underlying reasons. First, gold is a zero-yield asset, so when interest rates rise, the opportunity cost of holding gold increases on a relative basis, and gold should therefore be sold. Second, rising real interest rates are often accompanied by a stronger U.S. dollar, which also puts pressure on gold.
This was the main analytical framework used by financial
GLDX+0.11%
PAXG-0.38%
BLK+1.13%
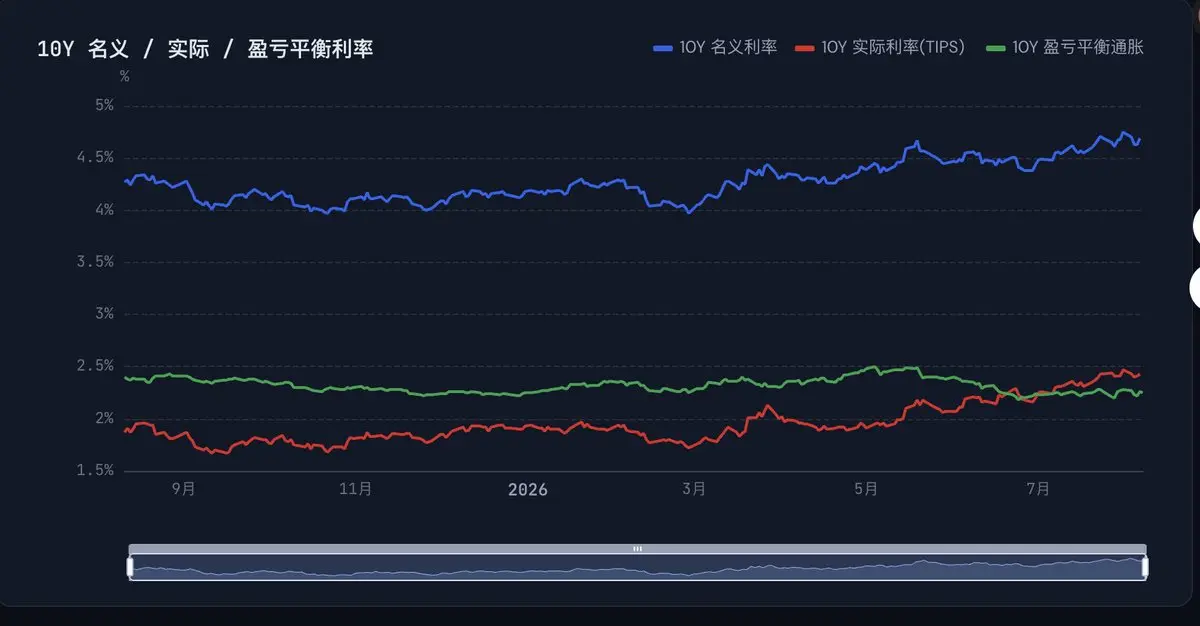
This wave of 10Y yields rising is basically being driven by real rates, rather than by higher inflation expectations.
This clearly expresses that the market believes that even if inflation returns to 2% in the future, the United States will still face a higher neutral rate, with even a tail risk of rate hikes.
If fiscal supply is taken into account, the issue becomes clear: while AI investment is driving strong capital demand from businesses and the private sector, the U.S. government also needs to compete for long-term funds by issuing debt on a large scale. The public and private sectors com
post-image
Tonight’s nonfarm payrolls are likely to come in below expectations, with both employment and core inflation weakening at the same time.
This month, we’re getting ready to go all in on posting about Wosh and the FOMC—why can’t it be as simple as a hawk/dove split? Also, why isn’t AI capex higher the better at this stage?
And the next half month will be an important phase from defense to offense. Everything is happening during the K-shaped divergence—technically, this is only the very beginning of technical introduction/penetration.
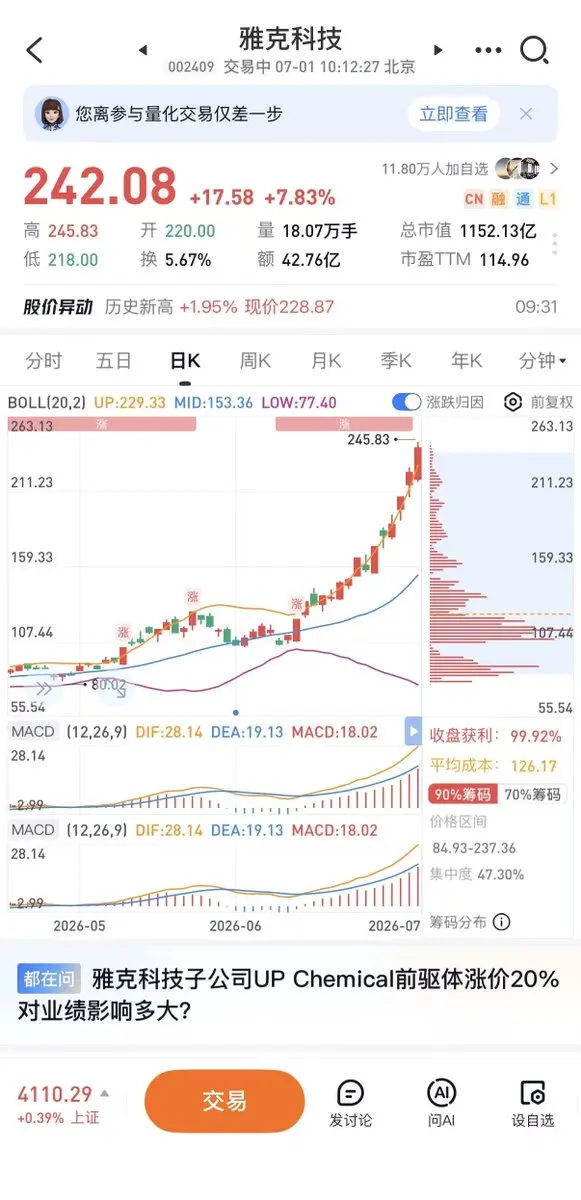
Meta renting computing power isn't something where the market can be wrong. It's basically people defending their own positions. It's just that when something goes up too much, it has to drop a bit.
As long as there are consecutive limit-ups, there will naturally be limit-downs. The only thing that needs to be distinguished is short-term, long-term, and positions.
What needs to be asked is: Is the AI narrative over? And has the narrative been fully converted into financial performance?
Conversely, even if the long-term narrative isn't over, it doesn't mean you don't need to take profits
META-3.68%
Speechless. According to the post published on May 27, Jacques has already achieved nearly 90%+ returns. Position opened at the beginning of the year, 3.5x leverage.
I have already stated the take-profit plan many times. Please stop sending me private messages asking about it.
To facilitate discussion, I will set up a group when I have time, where we can talk about macroeconomics and semiconductors together.
It will still be free. Do not trust any fake accounts charging you fees.
post-image
It seems that recently, the RMB is likely to be controlled a bit, devalued slightly, to stabilize exports, and most major public funds have basically increased some QDII quotas.
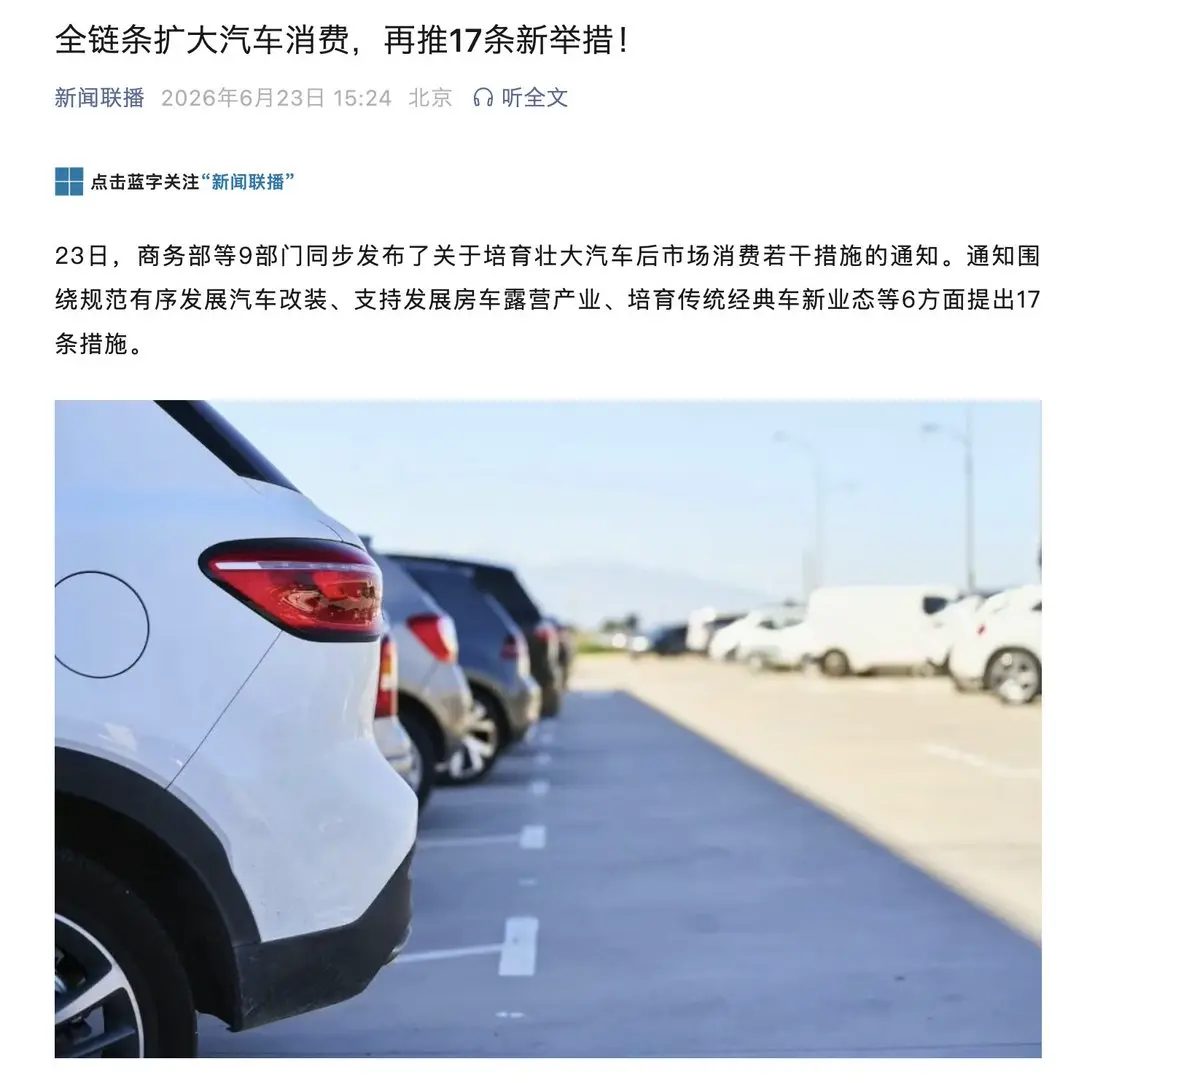
I previously had a policy reversal law. Whenever a policy reveals plans to promote xx to the countryside or similar consumption-expanding policies, related stocks immediately start to decline.
Whether it's new energy going to the countryside or home appliances going to the countryside, without exception. Because this essentially means that a large-scale elimination competition will enter the final sprint.
From a financial perspective, any stimulating behavior can be understood as leverage. Stimulating consumption is like giving residents leverage, and stimulating home purchases is similar.
post-image