Square
Following
Hot
News
Profile

M谋ngYueZen

vip
Peak Tier 0
Airdrop Hunter
Market Analyst
Match is match
83
Following
38
Followers
1.8k
Liked
$USDCAD
USDCAD has climbed from a low near 1.3759 to touch 1.42928, a move that carried the pair to a level it had not seen in months. The rally stalled at that peak, and the pullback that followed found buyers near the 200-hour moving average. Price has since pushed back above the 100-hour moving average, which sits around 1.42426. The pair is trading near 1.42561, and the structure of the move is worth understanding because it reflects a combination of technical and fundamental forces that have been building for weeks.
The peak at 1.42928 is not an arbitrary number. It represents the 61.8%
ToTheYUE
$USDCAD
USDCAD has climbed from a low near 1.3759 to touch 1.42928, a move that carried the pair to a level it had not seen in months. The rally stalled at that peak, and the pullback that followed found buyers near the 200-hour moving average. Price has since pushed back above the 100-hour moving average, which sits around 1.42426. The pair is trading near 1.42561, and the structure of the move is worth understanding because it reflects a combination of technical and fundamental forces that have been building for weeks.
The peak at 1.42928 is not an arbitrary number. It represents the 61.8% Fibonacci retracement of the decline from the late-January 2025 high to the late-January 2026 low. That retracement level often acts as a decision point, because it marks the zone where a countertrend rally either stalls or converts into a full reversal. The April 2025 swing high near 1.4295 sits almost exactly at the same level, which reinforces its significance as a resistance zone. The pair has now tested that area and backed away from it, which tells you that sellers were active there.
What makes the current setup interesting is the series of events that unfolded after the rejection. The initial decline gained momentum once price slipped below the 100-hour moving average, but the selling stopped near 1.4207 during the Asian-Pacific session, where the rising 200-hour moving average provided support. Buyers stepped in at that level and pushed the pair back above the 100-hour moving average. That sequence matters because it shows the 200-hour moving average is acting as a floor. As long as price holds above it, the near-term bias remains constructive.
The fundamental backdrop explains why the pair has been strong for weeks. The Federal Reserve raised rates in September, lifting the federal funds rate to a range of 3.75% to 4.00%. The Bank of Canada, by contrast, has held its policy rate at 2.25% for seven consecutive meetings. That leaves the US-Canada policy rate differential at roughly 1.625 percentage points, and the market expects the gap to persist through the winter, with both central banks projected to deliver about two quarter-point hikes by the end of January. When the yield advantage favors one currency, capital tends to flow toward it, and that dynamic has supported the dollar against the loonie.
Oil prices have added another layer of pressure on the Canadian dollar. Crude has been trading near a one-month low, and because Canada is a major energy exporter, a weaker oil price tends to weigh on the currency. The conflict in the Middle East had pushed oil higher earlier in the year, which briefly supported the loonie, but the recent pullback in crude has removed that support. The Bank of Canada has also noted that the pass-through from higher energy prices into broader inflation has been limited, which gives it room to keep rates steady while the Fed continues to tighten.
The Bank of Canada's next policy decision on October 28 is the next major event for the pair. Markets are currently pricing a modest probability of a hike at that meeting, with the odds rising for December and January. UBS expects the Bank of Canada to raise rates by a quarter point in October and again in January, taking the policy rate to 2.75%, and it projects Canadian inflation to rise to 3.3% in September. If those expectations shift, the yield gap that has supported the dollar could narrow, and that would change the calculus for USDCAD.
The technical levels to watch are well defined. On the upside, the 1.42928 level remains the resistance that needs to be cleared for the rally to extend. A sustained break above it would target the 100% projection of the move from 1.3480 to 1.4247, which comes in at 1.4497. On the downside, the 1.42426 level, which coincides with the 100-hour moving average, is the first support. Below that, the 1.4207 area near the 200-hour moving average is the more important line. A sustained break below the 200-hour moving average would weaken the recovery structure and open the way toward the 1.4130 level, which coincides with an ascending trendline from the recent rally. Below that, the 1.4000 psychological level and the 100-day moving average near 1.3980 come into focus.
The net read is that USDCAD is testing a resistance zone that has historical significance, and the pair's ability to hold above the 200-hour moving average suggests buyers are still present. The fundamental backdrop favors the dollar through the yield differential and the weak oil price, but the Bank of Canada's October meeting and the upcoming inflation data could shift that picture. The 1.42928 level is the line that matters most. A clear break above it would confirm the uptrend; a failure to hold the 200-hour moving average would signal that the rally has run its course for now.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
USDCAD-0.03%
$XAUT ‌$PAXG ‌China bought another 740,000 ounces of gold in September, extending its buying streak to 23 consecutive months. The purchase is the largest single monthly addition since October 2023, and it brings the People's Bank of China's total holdings to 77.47 million ounces, worth roughly $323.5 billion. What makes this accumulation worth understanding is not just the size of the purchase but the conditions under which it happened.
Gold prices fell 6.57% in September, closing the month at $4,157 an ounce and sliding toward $4,077 in early October. The dollar strengthened, Treasury yield
ToTheYUE
$XAU T ‌$PAXG ‌China bought another 740,000 ounces of gold in September, extending its buying streak to 23 consecutive months. The purchase is the largest single monthly addition since October 2023, and it brings the People's Bank of China's total holdings to 77.47 million ounces, worth roughly $323.5 billion. What makes this accumulation worth understanding is not just the size of the purchase but the conditions under which it happened.
Gold prices fell 6.57% in September, closing the month at $4,157 an ounce and sliding toward $4,077 in early October. The dollar strengthened, Treasury yields climbed, and the metal came under pressure from the same forces that have weighed on risk assets across the board. China bought into that weakness. The pattern is consistent with how central banks have behaved for the past several years: accumulating when prices fall, not when they rise. The World Gold Council reported that global central banks bought 39 tonnes net in August alone, with China leading the group, followed by Uzbekistan and Poland. On a year-to-date basis, central banks have reported total purchases of 170 tonnes.
The broader context for this accumulation is reserve diversification. About 65% of central bank respondents in a 2026 World Gold Council survey cited diversification as their primary reason for holding gold, followed by geopolitical risk management. China's gold reserves now stand at roughly 9% of its total reserves, or about 2,387 tonnes, according to the World Gold Council. Poland, which bought 8 tonnes in August, has accumulated 648 tonnes with a 700-tonne target in sight.
The timing of China's latest purchase coincided with the release of the Federal Reserve's September meeting minutes, which showed a committee divided on how much further to tighten. All 19 officials supported the quarter-point increase to a range of 3.75% to 4%, but the discussion behind that unanimity revealed a range of views. Several participants viewed the current rate as not restrictive or only mildly restrictive. A couple raised their estimates of the neutral rate. Inflation risks were described as skewed to the upside, with some participants concerned that after more than five years of above-target inflation, expectations and wage-and-price-setting behavior could be affected.
The reaction in the gold market was immediate and muted. Spot gold slipped about 0.3% to $4,150 an ounce ahead of the minutes, and a market analyst noted that the metal was likely to remain stable with a mild downside bias. The minutes themselves did not produce a sharp move in either direction, because the market had already priced in a pause for October and was looking for confirmation rather than surprise.
The more interesting development is happening beneath the surface of the gold market, in the tokenized gold sector. Tether Gold, known as XAUT, is one of the largest tokenized gold products, and its holder base has expanded sharply. The token now has roughly 61,057 holders on Ethereum alone, and the top 100 wallets control the entire supply. On one network, the holder count rose to 79,300, a nearly 29-fold increase over three months.
The connection between central bank buying and tokenized gold is indirect but real. When sovereign institutions accumulate physical gold, they validate the asset as a reserve instrument. That validation feeds into demand for gold-backed tokens, which offer exposure to the same underlying metal in a form that can be held, transferred, and used as collateral in digital markets. The two markets operate on different timelines and serve different purposes, but they are responding to the same underlying demand for hard assets that sit outside the traditional banking system.
The net read is that China's central bank is buying gold at a pace that has no recent precedent, and it is doing so while prices fall rather than while they rise. The Federal Reserve's minutes show a committee that is not yet ready to declare victory on inflation. The paper gold market is under pressure from the dollar and Treasury yields. And the tokenized gold market is expanding its holder base at a rapid pace. These forces are not aligned, and that divergence is what defines the current moment in the gold market.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$XAU ‌$XAUUSD ‌
XAUT-0.35%
PAXG-0.33%
SpaceX is in talks to raise approximately $40 billion in debt to purchase Nvidia chips, according to a report published by the Financial Times and later confirmed by Bloomberg. The financing would be led by Apollo Global Management, with about $10 billion in bank loans and $30 billion in investment-grade debt. The transaction is expected to close in 2027. The discussions are reportedly at an early stage and could end without an agreement.
The scale of the financing reflects the cost of building the computing infrastructure that underpins advanced artificial intelligence. Tech companies and AI
SaharaDreams
SpaceX is in talks to raise approximately $40 billion in debt to purchase Nvidia chips, according to a report published by the Financial Times and later confirmed by Bloomberg. The financing would be led by Apollo Global Management, with about $10 billion in bank loans and $30 billion in investment-grade debt. The transaction is expected to close in 2027. The discussions are reportedly at an early stage and could end without an agreement.
The scale of the financing reflects the cost of building the computing infrastructure that underpins advanced artificial intelligence. Tech companies and AI developers are investing and borrowing hundreds of billions of dollars to construct and lease large data centers filled with the chips needed to train and run AI systems. The worldwide expansion of computing capacity has pushed up the cost of land, chips, and power-generation equipment, and has triggered a series of large financing deals across the industry.
The backdrop to this move is a strategic decision made earlier this year. On the company's first earnings call as a public company in August, CEO Elon Musk stated that SpaceX had decided to build exclusively on Nvidia technology, citing the Vera Rubin architecture as the best option for its AI workloads. He described the relationship as a close partnership across multiple levels. The architecture, which includes the Vera CPU built specifically for AI agents, is designed to handle the orchestration, code execution, and data processing that surround model inference. SpaceX also plans to extend this architecture into space through its Starmax satellite program.
The spending commitments behind that decision are substantial. SpaceX spent $15.8 billion on AI computing during the second quarter of 2026, which represented 86% of its total capital expenditures for the period. The company expects to end 2026 with more than two gigawatts of computing capacity and to approach ten gigawatts by the end of 2027. It completed a $25 billion investment-grade bond offering in June 2026, shortly after its initial public offering, and the new financing would add to that debt load.
The funding structure has drawn attention from credit investors. SpaceX's existing bonds maturing in 2056 are trading at a discount to their face value, with a yield spread over Treasuries that resembles the level typically associated with junk-rated debt, even though the company holds an investment-grade rating. This gap between the rating and the market's pricing suggests that some investors are cautious about the company's mounting debt and its heavy capital expenditure.
The details of the planned financing are not yet final. The talks are ongoing, and the involvement of additional lenders, including bond fund PIMCO, has been reported. The deal, if completed, would rank among the largest debt financings tied to the AI infrastructure buildout. Whether it proceeds as described will depend on how the discussions develop and whether the terms attract sufficient investor demand.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$NVDA ‌$SPCX ‌#NvidiaHitsRecordHigh #ShareWeekly #PlanYourTradesThisWeek
SPCX-2.52%
NVDA-0.75%
APO-0.37%
The minutes from the Federal Reserve's September 15–16 meeting, released on October 7, 2026, show a committee that voted unanimously to raise rates but remained divided on why. All 19 officials supported the quarter-point increase to a range of 3.75% to 4.00%, the first hike in more than three years. The vote was 12–0 among voters, and the minutes note that all participants, including the seven non-voters, backed the move. Yet the discussion behind that unanimity reveals a range of views about the economy and the appropriate path forward.
Many participants assessed that another increase in the
Yuewen
The minutes from the Federal Reserve's September 15–16 meeting, released on October 7, 2026, show a committee that voted unanimously to raise rates but remained divided on why. All 19 officials supported the quarter-point increase to a range of 3.75% to 4.00%, the first hike in more than three years. The vote was 12–0 among voters, and the minutes note that all participants, including the seven non-voters, backed the move. Yet the discussion behind that unanimity reveals a range of views about the economy and the appropriate path forward.
Many participants assessed that another increase in the target range would likely be appropriate by the end of the year. The phrasing matters: by year-end, not at the next meeting. That distinction was reinforced by officials who have since stressed that the Fed does not need to rush. The minutes also showed that most participants saw a higher path as prudent on risk-management grounds, providing insurance against inflation remaining persistently above target due to stronger-than-expected demand or further adverse supply shocks. A number of officials said a higher path was needed based on their central outlook, not as insurance.
The committee's assessment of the current policy stance varied. Several participants viewed the current rate as not restrictive or only mildly restrictive. A couple raised their estimates of the neutral rate, the level that neither stimulates nor restrains the economy. This matters because if officials believe policy is barely restrictive, the threshold for further hikes is lower than it would be if they viewed rates as clearly tight.
On the labor market, almost all participants assessed that risks had diminished and were now broadly balanced, and a majority said the labor market had strengthened a bit recently. The minutes also noted that the labor market is close to maximum employment and that economic growth overall had picked up. Participants generally expect the labor market to remain stable, though they emphasized that decisions at future meetings would depend on incoming information.
Inflation risks were described as skewed to the upside, with some participants saying they had become more skewed in recent months. Several worried that after more than five years of above-target inflation, expectations and wage-and-price-setting behavior could be affected. Many also said that the longer energy prices stay high, the greater the risk of broader price pressures, and some noted that the artificial intelligence buildout could push demand ahead of supply over the medium term.
The minutes also touched on financial conditions and the Treasury market. Many participants said financial conditions remained supportive of growth despite higher Treasury yields. Officials discussed the rise in yields, attributing it to expectations for higher rates from the Fed as well as the AI buildout and solid economic growth. Staff economists noted that some of the surge in yields may have come from uncertainty related to the Treasury's announcement and implementation of its buyback program. Some participants described the Treasury market as functioning smoothly while emphasizing the need to prepare for possible market stress.
The minutes are a backward-looking document, and the market has already moved beyond parts of the conversation they record. Since the September meeting, softer inflation data and weaker-than-expected jobs numbers have reduced the probability of a hike at the October meeting to below one in four, while a December move remains more fully priced. The debate captured in the minutes, however, sets the terms for the meetings ahead. The committee is divided on whether the current rate is high enough to bring inflation back to target, and that division will shape how it interprets the data between now and the end of the year.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC $GT $ETH
#ShareWeekly #PlanYourTradesThisWeek
BTC-1.27%
GT-1.80%
ETH-1.74%
$XAUUSD ‌
Gold is trading near $4,102, down about 1.47% on the day, after touching $4,066 at its lowest point. The metal has fallen to its weakest level in two months, and the move is being driven by two forces that have little to do with gold itself: a strengthening dollar and rising Treasury yields. The dollar index climbed to 102.07, recovering from a brief slide, and the 10-year Treasury yield pushed back above 5.3%. When the risk-free rate is that elevated, the opportunity cost of holding an asset that pays no yield rises, and gold has paid the price.
The pressure on gold is not uniform
Yuewen
$XAU USD ‌
Gold is trading near $4,102, down about 1.47% on the day, after touching $4,066 at its lowest point. The metal has fallen to its weakest level in two months, and the move is being driven by two forces that have little to do with gold itself: a strengthening dollar and rising Treasury yields. The dollar index climbed to 102.07, recovering from a brief slide, and the 10-year Treasury yield pushed back above 5.3%. When the risk-free rate is that elevated, the opportunity cost of holding an asset that pays no yield rises, and gold has paid the price.
The pressure on gold is not uniform across all buyers. While the paper market sells off, central banks continue to accumulate. China's central bank added another 740,000 ounces of gold to its reserves in September, extending its buying streak to 23 consecutive months. Total purchases for 2026 have reached roughly 103 tonnes, and the People's Bank of China is now approaching two full years of uninterrupted accumulation. That buying is happening while prices fall, not while they rise, which is a different pattern from momentum-driven demand. Central banks are reserve managers, and their purchases are driven by long-term allocation decisions rather than short-term price action.
The divergence between paper and physical demand is the central tension in the gold market. The selloff is being driven by the dollar and yields, both of which are responding to the same macro forces: elevated oil prices, a Federal Reserve that has raised rates and may do so again, and a bond market that is repricing the entire rate path. The buying is coming from central banks and from institutional investors who view gold as a hedge against fiscal deterioration and currency debasement. These two groups are operating on different time horizons, and the paper market is currently setting the price.
Analysts have been adjusting their forecasts to reflect the new rate environment. HSBC lowered its average 2026 gold price forecast to $4,490 per ounce from $4,560, citing expectations of further rate hikes and higher oil prices, while keeping its longer-term view positive. The bank's 2027 forecast sits at $4,825 and its 2028 forecast at $5,200. At a precious metals conference, delegates surveyed for a 12-month outlook pointed to a price above $5,000. These forecasts are estimates, not guarantees, and they reflect a view that the current pressure is cyclical rather than structural.
The technical picture shows gold testing a support zone that has held for weeks. The immediate resistance sits at $4,165 to $4,185, and a four-hour close above that band would open the way toward $4,240 to $4,260. On the downside, the $4,110 level is the line that matters most. A sustained break below it would shift focus toward $4,027, the next target identified by technical analysts. The RSI is in oversold territory, which increases the likelihood of a short-term bounce, but oversold conditions can persist when the macro backdrop is unfavorable.
The net read is that gold is caught between two opposing forces. The dollar and Treasury yields are pushing prices lower in the short term, and those forces are unlikely to reverse quickly given the inflation and fiscal pressures that are driving them. At the same time, central banks are buying at a pace that has no recent precedent, and that provides a structural floor under the market that paper selling cannot easily break. The $4,110 support level is the variable to watch. If it holds, the metal can stabilize and wait for the macro pressure to ease. If it breaks, the correction extends toward the $4,000 area that central bank buyers have been targeting.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$AMD ‌
AMD is preparing a major expansion of its supply chain in Asia, with Chief Executive Lisa Su saying the company plans to invest tens of billions of dollars to secure the manufacturing capacity needed for its next generation of AI chips. The commitment builds on a $10 billion investment in Taiwan announced in May 2026, which Su confirmed remains on track and is now expected to increase as demand continues to outpace supply.
The centerpiece of the effort is a push to expand advanced packaging capacity with long-time manufacturing partner TSMC. Advanced packaging is the process of combini
Yuewen
$AMD ‌
AMD is preparing a major expansion of its supply chain in Asia, with Chief Executive Lisa Su saying the company plans to invest tens of billions of dollars to secure the manufacturing capacity needed for its next generation of AI chips. The commitment builds on a $10 billion investment in Taiwan announced in May 2026, which Su confirmed remains on track and is now expected to increase as demand continues to outpace supply.
The centerpiece of the effort is a push to expand advanced packaging capacity with long-time manufacturing partner TSMC. Advanced packaging is the process of combining multiple chips into a single package, a step that has become a critical bottleneck for AI accelerators. AMD's Helios rack-scale platform, which pairs its Venice server processors with the Instinct MI450X GPU, relies on this technology and is scheduled to begin multi-gigawatt deployments in the second half of 2026. Su said AMD is coordinating capacity across fabrication, packaging, and substrate suppliers, and that the company is planning three to five years ahead with its partners.
In South Korea, Su met with Samsung and SK Hynix, describing them as key AI partners and calling the country's supply chain indispensable. The focus of those discussions was high-bandwidth memory, or HBM, a specialized type of memory that sits next to AI processors and feeds them data at extremely high speeds. The latest generation, HBM4, is in short supply, and Su said AMD is encouraging memory producers to expand capacity as quickly as possible. Samsung has said it will triple its HBM production capacity by the end of 2026, while SK Hynix is also ramping its output.
The scale of the investment reflects the economics of the AI buildout. AMD's data center segment has become its largest source of revenue, and the company has secured multi-gigawatt deployment commitments from major customers. Those commitments cannot be fulfilled without a corresponding increase in manufacturing capacity, and capacity cannot be added quickly. Building a new fabrication line or a new packaging facility takes years, which is why AMD is locking in arrangements now for supply that will not be available until 2027 and beyond.
The strategy carries execution risk. AMD's investment commitment is large relative to its historical capital spending, and it depends on partners delivering on their own expansion plans. The memory market in particular has a history of sharp cycles, and a surge in capacity that arrives after demand has peaked can weigh on prices and margins across the industry. Su acknowledged that the company can use more supply than it currently has, even as it increases its output, which suggests that the near-term constraint is unlikely to be resolved quickly.
The move also places AMD in more direct competition with Nvidia for the same limited pool of advanced manufacturing capacity. Both companies rely on TSMC for leading-edge chips and on a small group of memory suppliers for HBM. When two of the largest AI chip designers are competing for the same capacity, the advantage goes to the one with the deepest relationships and the most credible volume commitments. AMD's tour of Asia is, in part, an effort to ensure it is not the one left waiting.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.

AMD-0.57%
TSM-2.12%
SK Hynix-2.43%
SKHY-2.37%
SKHYV-0.98%
#HYPETreasuryHoldingsTop$3.2B #HYPE财库公司持仓超32亿美元 #作手分析
🔥 HYPE treasury holdings surpass $3.2 billion! Breaking past the previous high against market pressure—how far can the long-term thesis go?
Trading watch: $HYPE $BTC $ETH
The hot topic on GATE Square is very interesting:
Nasdaq-listed treasury company Hyperliquid Strategies has once again increased its holdings by approximately 1.9 million HYPE, bringing its total holdings to approximately 37 million HYPE, worth more than $3.2 billion.
Many people may only think when they see this: “Another institution is footing the bill.”
But what I’
discovery
#HYPETreasuryHoldingsTop$3.2B #HYPE财库公司持仓超32亿美元 #作手分析
🔥 HYPE treasury holdings surpass $3.2 billion! Breaking past the previous high against market pressure—how far can the long-term thesis go?
Trading watch: $HYPE $BTC $ETH
The hot topic on GATE Square is very interesting:
Nasdaq-listed treasury company Hyperliquid Strategies has once again increased its holdings by approximately 1.9 million HYPE, bringing its total holdings to approximately 37 million HYPE, worth more than $3.2 billion.
Many people may only think when they see this: “Another institution is footing the bill.”
But what I’m more interested in is: What exactly is the relationship between this company and HYPE? And why do I remain bullish on HYPE over the long term despite recent macro market pressure?
📊 I. Unveiling the connection: HYPE’s “treasury proxy” in U.S. stocks
Hyperliquid is the protocol, HYPE is the native token, and Hyperliquid Strategies is an independent publicly listed digital asset treasury company.
One of its core businesses is continuously accumulating HYPE and participating in the ecosystem through staking and other means.
I prefer to understand it as HYPE’s “treasury proxy” in traditional capital markets.
To some extent, it plays a role similar to $MSTR ’s in the $BTC ecosystem—using the financing capabilities of traditional capital markets to continuously expand its HYPE treasury, allowing investors in traditional stock markets to gain HYPE exposure.
🔥 II. Breaking the previous bull-market high despite market pressure, demonstrating clear relative strength
According to market data, HYPE’s high during last year’s bull market was approximately $59.5.
After enduring the macro-driven market crash and washout in this cycle, HYPE not only avoided falling back to its starting point but instead broke back above $59.5 and continued to set new all-time highs.
The current price is around $90.6, just one step away from the all-time high of $98 set in September.
Breaking the previous bull-market high while the broader market is under pressure is not simply a matter of “rising more”; it shows that HYPE has demonstrated very clear relative strength.
💰 III. What really draws my attention: the value-return mechanism created by buybacks and burns
The Hyperliquid protocol currently allocates approximately 99% of protocol fees to the Assistance Fund, which is used to continuously buy back $HYPE , with some HYPE permanently removed; meanwhile, HyperEVM’s base fees and priority fees are also burned.
This means: increased protocol usage → increased fees → increased buyback demand → some HYPE permanently exits circulation.
This combination of “protocol revenue growth + buybacks and burns + treasury accumulation” is an important reason why I believe HYPE is worth tracking over the long term, creating a supply-and-demand mechanism worth monitoring over time.
Of course, this does not mean HYPE’s supply will decline unilaterally forever; factors such as unlocks and staking rewards still require attention.
🎯 IV. The trader’s strategy: bullish over the long term, but never chase highs from the left side
This is my clearest view on HYPE: bullish over the long term, but that does not mean blindly buying at the current price.
• If you already have a core position: Hold the long-term core position with the trend, trade the short-term position based on the structure, and use trailing profit-taking.
• If you are preparing to build a position: I still adhere to a right-side system: breakout → pullback → stabilization on declining volume → follow-up entry.
The overhead supply from HYPE’s previous all-time high is relatively limited, but profit-taking pressure and round-number levels during the new-high phase still require attention.
When HYPE continues to set new highs, I will not short it subjectively just because it has “risen too much”; if a major pullback occurs, I will not blindly buy the dip just because it has “fallen a lot.”
I would rather wait for: a key structure to emerge → selling pressure to be exhausted → pullback confirmation → then look for right-side opportunities worth closely monitoring.
What do you think of HYPE’s independent countertrend move?
A. Continued treasury accumulation, targeting the $100 mark 🚀
B. Volatility increases after the new high; waiting for a pullback 📉
C. Stronger buybacks and burns; remaining bullish over the long term 💎
D. Only trade the right side; waiting for structural confirmation 🛡️
Leave A / B / C / D and share your view 👇
(The above content is compiled based on public disclosures and my personal trading system, for discussion purposes only, and does not constitute investment advice. The crypto market is extremely volatile; please make independent judgments and manage risk appropriately.)
#PlanYourTradesThisWeek
#ShareWeekly
HYPE-3.66%
BTC-1.27%
ETH-1.74%
MSTR-6.83%
On-chain data confirms that BitMine Immersion Technologies acquired another 12,500 ETH, valued at approximately $33.65 million. The transaction was flagged by on-chain trackers and reported by market analysts. This purchase follows the company's established pattern of buying Ethereum every week since it launched its treasury strategy in June 2025.
As of October 4, BitMine held 6,016,414 ETH, which is roughly 4.9% of Ethereum's total supply. The company's stated goal is to reach 5%, a target its chairman Tom Lee refers to as the "Alchemy of 5%". Of its total holdings, 5,067,309 ETH, worth about
User_any
On-chain data confirms that BitMine Immersion Technologies acquired another 12,500 ETH, valued at approximately $33.65 million. The transaction was flagged by on-chain trackers and reported by market analysts. This purchase follows the company's established pattern of buying Ethereum every week since it launched its treasury strategy in June 2025.
As of October 4, BitMine held 6,016,414 ETH, which is roughly 4.9% of Ethereum's total supply. The company's stated goal is to reach 5%, a target its chairman Tom Lee refers to as the "Alchemy of 5%". Of its total holdings, 5,067,309 ETH, worth about $13.8 billion, are staked and earning rewards at an annualized yield of 2.63%.
The new purchase was funded through a combination of the company's cash reserves and at-the-market sales of its common stock. BitMine's total crypto, cash, and other holdings reached $17.4 billion as of October 4, including 214 Bitcoin, a $180 million stake in Beast Industries, a $117 million stake in Eightco Holdings, and $643 million in cash and marketable securities.
The structural feature that distinguishes BitMine's model from a Bitcoin treasury company is the staking yield. Bitcoin on a balance sheet does not generate income. Ethereum can be staked, and BitMine earns about 2.63% annually on its staked coins, which amounts to roughly $363 million per year. That revenue can be used to fund further purchases without relying solely on raising new capital.
The risks remain the same as before. Owning nearly 5% of a network's circulating supply means that if the company ever needed to exit, the market would feel it. The 84% staking ratio also means most of the tokens are locked in validators, which limits the company's ability to respond to a sudden need for liquidity. The staking yield itself is variable, depending on network conditions and the total amount of ETH staked. The revenue projection is an estimate, not a guarantee.
The purchase was a small increment relative to the company's total holdings, but it confirms that the accumulation strategy is still active. BitMine is now very close to its 5% target.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$ETH ‌#BitmineAddsMoreETH,HoldingsTop6.01M 🧐
BMNR-5.87%
ETH-1.74%
BTC-1.27%
The S&P 500 closed at 7,818.93, its first record since August and the 28th record close of 2026, while the Nasdaq Composite finished at 27,599.79 for its second consecutive all-time high. The Dow Jones Industrial Average added 253.38 points, or 0.49%, to close at 51,521.28. The gains were modest in percentage terms, but the context behind them is what makes the session worth understanding.
Two pressures that had been weighing on equities for weeks eased at the same time. The 10-year Treasury yield fell about 4 basis points to 5.262%, and the 30-year yield slipped to 5.631%, retreating from lev
User_any
The S&P 500 closed at 7,818.93, its first record since August and the 28th record close of 2026, while the Nasdaq Composite finished at 27,599.79 for its second consecutive all-time high. The Dow Jones Industrial Average added 253.38 points, or 0.49%, to close at 51,521.28. The gains were modest in percentage terms, but the context behind them is what makes the session worth understanding.
Two pressures that had been weighing on equities for weeks eased at the same time. The 10-year Treasury yield fell about 4 basis points to 5.262%, and the 30-year yield slipped to 5.631%, retreating from levels not seen since 2002. Crude prices also steadied, with Brent crude holding near $100.58 a barrel and WTI near $89.44, as increased exports from the Middle East and a coordinated release of strategic reserves by the G7 helped ease supply concerns. When oil stabilizes, the anxiety about energy-driven inflation fades, and that in turn takes pressure off bond yields. That chain reaction gave equities room to advance.
The more durable support came from earnings expectations. Goldman Sachs projects that S&P 500 companies will report a 27% year-over-year increase in third-quarter earnings per share, with companies benefiting from AI infrastructure investment accounting for more than half of the total profit growth. Analysts more broadly expect a roughly 25% increase in quarterly profits, according to data compiled by Bloomberg Intelligence. That is a substantial number, and it helps explain why stocks have held up even as borrowing costs remain elevated. As one portfolio manager put it, if profits are there, equities tend to stay resilient even when the economy is uneven.
The composition of the rally is worth noting. The advance has been driven primarily by a small group of large technology companies tied to the artificial intelligence buildout, which have shown a stronger ability to absorb higher energy and financing costs than the broader market. Nvidia's market value is approaching $6 trillion, and the so-called Magnificent Seven now account for more than 34% of the S&P 500's market capitalization, with their combined value reaching roughly $25 trillion. Marvell Technology rose 5.8% after raising its long-term revenue guidance, and AMD gained 3% as its CEO predicted very high chip demand in the coming years.
That concentration cuts both ways. When a handful of companies reach such enormous size, their daily moves naturally exert an outsized influence on the index. The Russell 2000, which tracks smaller companies, fell 0.59% on the same day, a reminder that the record highs do not reflect broad participation. A market strategist noted that technology and communications were the only two sectors to post significant gains last month while seven sectors declined, a pattern that does not resemble a healthy bull market.
The week ahead includes the release of the Federal Reserve's September meeting minutes, which may offer insight into the central bank's decision to raise rates and its view on further tightening. Futures markets currently price a roughly 19% probability of another rate hike at the October meeting, down from about 51% a week earlier. The earnings season beginning next week will provide the next concrete test of whether the profit growth that analysts expect actually materializes.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$NVDA ‌$MU ‌$NAS100 ‌#GateStockInsightsChallenge #ShareWeekly #PlanYourTradesThisWeek
repost-content-media
US500-0.26%
US30-0.59%
US2000-0.84%
NAS100-0.69%
NVDA-0.75%
The 10-year Treasury yield has retreated to around 5.28% after touching 5.34% earlier in the week, its highest level since 2002. The move marks a pause in a bond selloff that had pushed long-term borrowing costs to multi-decade highs, and it comes as two of the forces driving those yields have begun to ease.
Oil prices have slipped, with Brent crude falling below $100 a barrel at one point and WTI trading near $89. The decline followed two developments that added supply to the market. Middle East crude exports recovered toward pre-war levels, with Saudi Arabia's shipments returning to volumes
User_any
The 10-year Treasury yield has retreated to around 5.28% after touching 5.34% earlier in the week, its highest level since 2002. The move marks a pause in a bond selloff that had pushed long-term borrowing costs to multi-decade highs, and it comes as two of the forces driving those yields have begun to ease.
Oil prices have slipped, with Brent crude falling below $100 a barrel at one point and WTI trading near $89. The decline followed two developments that added supply to the market. Middle East crude exports recovered toward pre-war levels, with Saudi Arabia's shipments returning to volumes not seen since before the conflict began in February. In parallel, the Group of Seven nations agreed to release up to 100 million barrels of diesel and crude oil from emergency reserves over four months, with a substantial portion front-loaded into the first twenty days.
The retreat in yields and oil prices reflects a straightforward chain of cause and effect. When energy costs fall, the inflation expectations that had been feeding into long-term bond yields also ease. That reduces the pressure on the Federal Reserve to keep raising rates, which in turn lowers the opportunity cost of holding risk assets. The 2-year Treasury yield, the maturity most sensitive to Fed policy expectations, fell roughly two basis points to 4.8%, and the probability of an October rate hike has fallen to around 19% from roughly 51% a week earlier.
The pressures that drove yields to multi-decade highs have not disappeared. Government debt levels remain elevated across advanced economies. The artificial intelligence buildout continues to absorb capital. And inflation, while cooling at the margin, remains above the Federal Reserve's 2% target. The retreat is a pause, not a reversal, and the direction of the next move will depend on whether the supply improvements in energy markets hold and whether the incoming inflation data confirms that the recent softening is durable.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC $GT $ETH $SPCX $EURUSD
repost-content-media
BTC-1.27%
GT-1.80%
ETH-1.74%
SPCX-0.09%
EURUSD-0.03%
SpaceX is in talks to raise approximately $40 billion in debt to purchase Nvidia chips, according to a report published by the Financial Times and later confirmed by Bloomberg. The financing would be led by Apollo Global Management, with about $10 billion in bank loans and $30 billion in investment-grade debt. The transaction is expected to close in 2027. The discussions are reportedly at an early stage and could end without an agreement.
The scale of the financing reflects the cost of building the computing infrastructure that underpins advanced artificial intelligence. Tech companies and AI
User_any
SpaceX is in talks to raise approximately $40 billion in debt to purchase Nvidia chips, according to a report published by the Financial Times and later confirmed by Bloomberg. The financing would be led by Apollo Global Management, with about $10 billion in bank loans and $30 billion in investment-grade debt. The transaction is expected to close in 2027. The discussions are reportedly at an early stage and could end without an agreement.
The scale of the financing reflects the cost of building the computing infrastructure that underpins advanced artificial intelligence. Tech companies and AI developers are investing and borrowing hundreds of billions of dollars to construct and lease large data centers filled with the chips needed to train and run AI systems. The worldwide expansion of computing capacity has pushed up the cost of land, chips, and power-generation equipment, and has triggered a series of large financing deals across the industry.
The backdrop to this move is a strategic decision made earlier this year. On the company's first earnings call as a public company in August, CEO Elon Musk stated that SpaceX had decided to build exclusively on Nvidia technology, citing the Vera Rubin architecture as the best option for its AI workloads. He described the relationship as a close partnership across multiple levels. The architecture, which includes the Vera CPU built specifically for AI agents, is designed to handle the orchestration, code execution, and data processing that surround model inference. SpaceX also plans to extend this architecture into space through its Starmax satellite program.
The spending commitments behind that decision are substantial. SpaceX spent $15.8 billion on AI computing during the second quarter of 2026, which represented 86% of its total capital expenditures for the period. The company expects to end 2026 with more than two gigawatts of computing capacity and to approach ten gigawatts by the end of 2027. It completed a $25 billion investment-grade bond offering in June 2026, shortly after its initial public offering, and the new financing would add to that debt load.
The funding structure has drawn attention from credit investors. SpaceX's existing bonds maturing in 2056 are trading at a discount to their face value, with a yield spread over Treasuries that resembles the level typically associated with junk-rated debt, even though the company holds an investment-grade rating. This gap between the rating and the market's pricing suggests that some investors are cautious about the company's mounting debt and its heavy capital expenditure.
The details of the planned financing are not yet final. The talks are ongoing, and the involvement of additional lenders, including bond fund PIMCO, has been reported. The deal, if completed, would rank among the largest debt financings tied to the AI infrastructure buildout. Whether it proceeds as described will depend on how the discussions develop and whether the terms attract sufficient investor demand.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$NVDA ‌$SPCX ‌#NvidiaHitsRecordHigh #ShareWeekly #PlanYourTradesThisWeek
repost-content-media
SPCX-2.52%
NVDA-0.75%
APO-0.37%
Gate new futures listing: $AGENCY
🔹 Trading pair: $AGENCY / $USDT
🔹 Trading time: Live
🔹 Supports 1–10x leverage, trading bots, and copy trading
Trade $AGENCY: https://www.gate.com/zh/futures/USDT/AGENCY_USDT
More details: https://www.gate.com/zh/announcements/article/102085
GateLaunch
Gate new futures listing: $AGENCY
🔹 Trading pair: $AGENCY / $USDT
🔹 Trading time: Live
🔹 Supports 1–10x leverage, trading bots, and copy trading
Trade $AGENCY: https://www.gate.com/zh/futures/USDT/AGENCY_USDT
More details: https://www.gate.com/zh/announcements/article/102085
repost-content-media
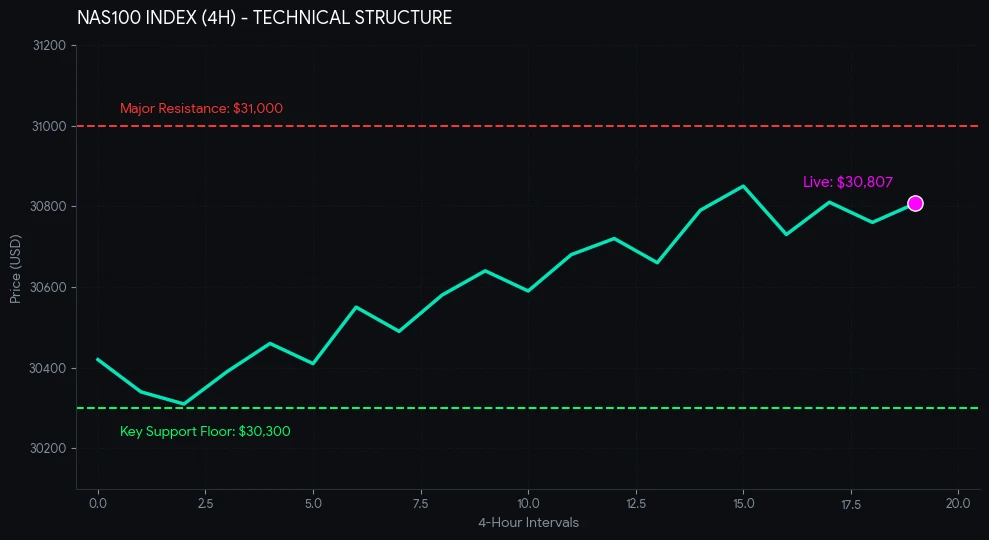
🚨 $NAS100 : Whales are cooking something massive at the highs!
Chart Update:
Price action looks clean as hell. The tech giants are aggressively loading up, and the order book is heavy on the bid side. We just printed a local structure shift after bouncing off the key support at $30,300.
Right now, $NAS100 is trading heavily around $30,807. The bears are trying to defend the major $31,000 resistance block, but liquidity is thin up there. If the bulls squeeze through $31,000, expect massive FOMO to trigger a violent multi-hundred point extension.
Key parameters on my radar:
- Accumulation zone:
kenanfb
🚨 $NAS100 : Whales are cooking something massive at the highs!
Chart Update:
Price action looks clean as hell. The tech giants are aggressively loading up, and the order book is heavy on the bid side. We just printed a local structure shift after bouncing off the key support at $30,300.
Right now, $NAS100 is trading heavily around $30,807. The bears are trying to defend the major $31,000 resistance block, but liquidity is thin up there. If the bulls squeeze through $31,000, expect massive FOMO to trigger a violent multi-hundred point extension.
Key parameters on my radar:
- Accumulation zone: $30,300 - $30,500
- Immediate target: $31,000
- Melt-up zone: $31,500+
Invalidation happens if we lose the $30,300 support floor on a daily close. Until then, the trend is your friend and the tech bid is real. Don't fight the macro momentum.
Are you buying this move or waiting for lower numbers? Let me know below! 👇
$NAS100 ‌
*Disclaimer: Market commentary based on current live data. Not financial advice. Always DYOR.*
#NAS100 #Trading #Crypto #TechnicalAnalysis
repost-content-media
NAS100-0.69%
📢 Reward Announcement | Gate Square New Creator Growth Plan
September weekly rewards (9.11–9.27) have been distributed. Congratulations to the winning creators! 🎉
Starting now, win up to 100 USDT every week 👉 https://www.gate.com/campaigns/6244
🎁 Generous rewards await
① Weekly Points Rewards: Earn points by posting, with up to 100 USDT
② Weekly TOP 10: Up to 300 USDT + VIP+1 trial card + creator benefits
③ Monthly TOP 3: Compete for the monthly leaderboard and enjoy 500 USDT + GT worth 30 USDT exclusively
🔥 Share your views with #每周来晒 and #市场回调如何布局 this week to win rewards!
👉 https://
GateSquare
📢 Reward Announcement | Gate Square New Creator Growth Plan
September weekly rewards (9.11–9.27) have been distributed. Congratulations to the winning creators! 🎉
Starting now, win up to 100 USDT every week 👉 https://www.gate.com/campaigns/6244
🎁 Generous rewards await
① Weekly Points Rewards: Earn points by posting, with up to 100 USDT
② Weekly TOP 10: Up to 300 USDT + VIP+1 trial card + creator benefits
③ Monthly TOP 3: Compete for the monthly leaderboard and enjoy 500 USDT + GT worth 30 USDT exclusively
Reward details:
https://docs.google.com/spreadsheets/d/1u4TWKlxBcKkeZGUvQXkMSMYifvYUdaCfON5oZE86q40/edit?hl=zh-CN&gid=0#gid=0
🔥 Share your views with #每周来晒 and #市场回调如何布局 this week to win rewards!
👉 https://www.gate.com/post
repost-content-media
GT-1.80%
Metaplanet sold 10,000 Bitcoin and then bought back 11,000 within the same quarter, a maneuver that ended with a net addition of 1,000 coins and a clear message to the credit rating agencies that the company is willing to convert its holdings into cash when it needs to. The Tokyo-listed firm disclosed the transactions on October 5, confirming that its total Bitcoin holdings reached 44,000 BTC as of September 30, 2026.
The mechanics of the trade are straightforward. Metaplanet sold 10,000 BTC for ¥124.7 billion, or roughly $790 million, at an average price of $78,925 per coin. It then repurchas
User_any
Metaplanet sold 10,000 Bitcoin and then bought back 11,000 within the same quarter, a maneuver that ended with a net addition of 1,000 coins and a clear message to the credit rating agencies that the company is willing to convert its holdings into cash when it needs to. The Tokyo-listed firm disclosed the transactions on October 5, confirming that its total Bitcoin holdings reached 44,000 BTC as of September 30, 2026.
The mechanics of the trade are straightforward. Metaplanet sold 10,000 BTC for ¥124.7 billion, or roughly $790 million, at an average price of $78,925 per coin. It then repurchased 11,000 BTC for ¥149.9 billion, or about $950 million, at an average of $86,246. The company temporarily held the proceeds in cash, but it did not use that cash to repay its outstanding bonds or borrowings. Instead, it kept the liabilities outstanding on their original terms and bought back more Bitcoin than it had sold. The net addition of 1,000 BTC cost the company ¥25.2 billion, or approximately $79 million.
The purpose of the round trip was not to generate a profit. Metaplanet sold at an average price below its own acquisition cost, which created a capital loss for U.S. tax purposes and a preliminary estimated deferred tax asset of roughly $97 million. The company also repurchased at prices roughly 9% above its selling price, meaning the net addition was executed at a higher cost than the disposal. The exercise was designed to demonstrate something specific: that Metaplanet is both able and willing to convert its Bitcoin into cash to meet obligations. CEO Simon Gerovich addressed this directly, saying that rating agencies and credit investors often ask whether a Bitcoin treasury company can and will sell Bitcoin to meet its debts. "We answered by doing it," he said.
That answer matters because Metaplanet is pursuing a credit rating and wants to broaden its financing options to include corporate bonds and preferred shares. The company's filing argues that Bitcoin's liquidity alone does not establish whether an issuer will actually sell the asset when obligations come due. A credit rating, in other words, cannot be built on the assumption that a company will never touch its reserve. By selling 10,000 BTC and then buying back more than it sold, Metaplanet proved the liquidity mechanism works while still ending the quarter with a larger position than it started.
The balance sheet context is worth noting. Metaplanet's liabilities, net of cash and dollar stablecoins, stood at ¥122.4 billion at the end of the quarter. The sale generated ¥124.7 billion in proceeds, which means the cash raised exceeded the net debt position. The company chose not to repay that debt, which preserves its leverage and keeps its capital deployed in Bitcoin. The cost basis of its total holdings is approximately $4.33 billion, or an average of $98,454 per BTC. With Bitcoin trading near $86,000, the portfolio is carrying an unrealized loss relative to its entry price, which is a detail that matters for how the market assesses the company's risk profile.
Metaplanet also introduced a Net Interest Income Strategy alongside the Bitcoin disclosure. The plan is to allocate 10% to 15% of total assets to strategic investments, including income-generating securities, while keeping 85% to 90% of assets in Bitcoin. The company intends to use capital raised from perpetual preferred stock, corporate bonds, and a Bitcoin-collateralized credit facility, and it will invest that money into assets expected to generate stable income. The target is to earn the difference between those yields and its funding costs. Preferred securities issued by other Bitcoin treasury companies are expected to be among the main investments. The goal is to build a recurring revenue stream that can service obligations and support further Bitcoin purchases without relying solely on the appreciation of the asset.
The scale of the operation places Metaplanet in a specific category. With 44,000 BTC, it is the second-largest publicly listed Bitcoin treasury company in the world, behind only Strategy. Its strategic ambition under the 555 Million Plan is to accumulate 210,000 BTC by the end of 2027, which would represent about 1% of the final Bitcoin supply, with a nearer-term target of 100,000 BTC by the end of 2026. The company holds its position through a combination of equity issuance, debt, and now a planned income strategy. The sale and repurchase exercise was a proof of concept for the credit side of that model, and the market's reaction was measured: Metaplanet shares closed 2% higher on Monday at 297 yen.
The risks in this structure are real and should not be overlooked. The company sold Bitcoin below its acquisition cost and bought back above its selling price, which means the net addition of 1,000 BTC came at a premium. If Bitcoin's price stays below the company's average cost basis of $98,454, the unrealized loss on the broader portfolio persists. The deferred tax asset of $97 million is preliminary and unaudited, and the company has noted that it may not be recognized at all. The Net Interest Income Strategy introduces a new layer of complexity and counterparty risk, because it depends on the yields generated by preferred securities issued by other Bitcoin treasury companies, a relatively new and untested asset class.
The net read is that Metaplanet executed a deliberate liquidity demonstration rather than a strategic shift away from Bitcoin. It sold a large block, held the cash to prove it could cover its debts, and then bought back more than it sold. The net effect was a 1,000 BTC increase and a clearer credit story for rating agencies. The company ended the quarter with 44,000 BTC, a new income strategy, and a capital allocation policy that keeps the vast majority of its assets in Bitcoin. Whether that structure holds up will depend on the price of Bitcoin relative to its cost basis and the willingness of credit markets to fund the next phase of accumulation.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC ‌
repost-content-media
BTC-1.27%
Strategy added another 334 Bitcoin to its treasury last week, a purchase that lifted its total holdings to exactly 848,000 BTC and extended a record that has now stood for three consecutive weeks. The buy was small relative to the company's recent pace, roughly a fifth the size of the 1,665 BTC it acquired the week before, and the filing disclosed something that has become just as important as the Bitcoin itself: Strategy spent more than six times as much buying back its own preferred stock.
The numbers are precise. Between October 1 and 4, Strategy acquired 334 BTC for $28.7 million at an ave
User_any
Strategy added another 334 Bitcoin to its treasury last week, a purchase that lifted its total holdings to exactly 848,000 BTC and extended a record that has now stood for three consecutive weeks. The buy was small relative to the company's recent pace, roughly a fifth the size of the 1,665 BTC it acquired the week before, and the filing disclosed something that has become just as important as the Bitcoin itself: Strategy spent more than six times as much buying back its own preferred stock.
The numbers are precise. Between October 1 and 4, Strategy acquired 334 BTC for $28.7 million at an average price of $85,838.80 per coin. That brings the company's total cost basis to approximately $63.97 billion, or $75,440.70 per Bitcoin across the entire position. At the current price of around $86,138, the stash is worth roughly $72.4 billion, which implies about $9 billion in paper gains. The purchase was funded through a combination of $15.7 million in net proceeds from selling 92,894 MSTR common shares and $13 million drawn from the company's USD Cash balance.
What makes this week's filing different from the ones that preceded it is the allocation of capital. Strategy repurchased 1,033,168 shares of its Stretch (STRC) preferred stock for $102.6 million in the final days of September, then bought back another 740,634 shares for $73.7 million in the first four days of October. The total repurchase came to $176.3 million, of which $154.1 million came from USD Cash and $22.2 million from interest earned on cash and short-term investments. The preferred buyback program still has $547.2 million remaining, and the MSTR common stock repurchase program has $1.0 billion left. None of the four preferred lines were sold through the at-the-market program during either window.
The shift toward preferred buybacks is not an accident. STRC pays a 12% annual dividend and has traded below its $100 par value for months. Strategy has said it will keep that rate until the stock trades steadily near its issue price. Buying back the shares at a discount reduces the company's future dividend obligations and signals confidence in its ability to manage the credit side of its balance sheet. Gold advocate Peter Schiff argued over the weekend that Strategy has lost its Bitcoin-buying power because STRC no longer raises fresh money, but the filing shows the company is still adding Bitcoin in small amounts while directing larger sums at the preferred stock that funds its dividend obligations.
The third-quarter numbers are the other half of the story. Strategy estimated a $20.91 billion gain on its digital assets for the quarter ended September 30, the largest figure in the filing. Because the company marks Bitcoin at fair value, that gain reflects price appreciation across the period. At the end of June, its Bitcoin was worth less than it paid. The rebound allowed Strategy to reverse a $4.12 billion deferred tax asset tied to that earlier loss and record a $1.88 billion deferred tax expense instead. The company estimated its digital asset carrying value at $70.82 billion as of September 30.
The cash position remains substantial. Strategy holds a $4.88 billion USD Reserve that covers preferred dividends and debt interest, and $833.4 million in USD Cash for general purposes including Bitcoin purchases. In the week to October 4, it drew $142.5 million from the reserve for dividends and interest. Shareholders will vote on October 28 on a plan to pay daily dividends across the company's four preferred stock lines, a proposal that arrives as more of Strategy's cash flow is directed toward servicing those shares than toward new Bitcoin.
The context of the broader Bitcoin treasury sector adds a useful comparison. Metaplanet, the Tokyo-listed firm that is the second-largest public holder of Bitcoin, sold 10,000 BTC and bought back 11,000 during its own third quarter, a round trip designed to show credit rating agencies that it could convert Bitcoin into cash on demand. Strive, a smaller rival, bought 2,000 BTC between September 28 and October 2 at an average of $84,422 each, lifting its holdings to 29,462 BTC. Both companies are now spending as much attention on the credit side of the balance sheet as on accumulation.
The net read is that Strategy is still accumulating Bitcoin, but the pace has slowed and the capital allocation has shifted. The company is adding coins above its own average cost basis in small amounts while directing larger sums at a preferred stock that has traded below par for months. The $20.91 billion quarterly gain reflects the recovery in Bitcoin's price, not a change in strategy. The vote on October 28 will determine how the company structures its dividend obligations going forward, and that decision will shape how much cash remains available for future Bitcoin purchases. For now, the treasury stands at 848,000 BTC, the cost basis is $63.97 billion, and the company is managing both sides of its balance sheet with equal attention.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC ‌
repost-content-media
BTC-1.27%
MSTR-6.83%
STRC-0.05%
ASST-5.26%
Strive added 2,000 Bitcoin last week for approximately $169 million at an average price of $84,422 per coin, lifting its total holdings to 29,462 BTC. The purchase, disclosed in an 8-K filing with the U.S. Securities and Exchange Commission on October 5, is the third-largest in the company's history, behind only the Bitcoin it acquired through its merger with Semler Scientific and a 2,500 BTC purchase in late May and early June of this year.
The funding structure behind the buy is worth understanding because it distinguishes Strive's model from that of a simple accumulation vehicle. Of the cap
User_any
Strive added 2,000 Bitcoin last week for approximately $169 million at an average price of $84,422 per coin, lifting its total holdings to 29,462 BTC. The purchase, disclosed in an 8-K filing with the U.S. Securities and Exchange Commission on October 5, is the third-largest in the company's history, behind only the Bitcoin it acquired through its merger with Semler Scientific and a 2,500 BTC purchase in late May and early June of this year.
The funding structure behind the buy is worth understanding because it distinguishes Strive's model from that of a simple accumulation vehicle. Of the capital raised, 61.5% came from SATA, the company's preferred equity subsidiary, with warrants generating $56.7 million. SATA is currently absorbing 90% of the daily Bitcoin mining output, a detail that points to a broader strategy of using multiple capital channels to accumulate the asset rather than relying on a single source.
The balance sheet context adds another layer. As of October 2, Strive held 29,462 Bitcoin, 505,000 shares of Strategy's STRC preferred stock worth approximately $50.2 million, and roughly $284.7 million in cash. The company ended the third quarter with 28,000 BTC valued at approximately $2.34 billion and an average cost basis of about $90,170. During the quarter, Strive added 8,137 Bitcoin at an average price of $78,885. Its Bitcoin-per-share metric rose 18.5% in the third quarter and 63.2% year-to-date.
The timing of this purchase is notable when viewed alongside the broader corporate treasury landscape. Strategy, the largest public holder of Bitcoin, bought just 334 BTC in the same week, a much smaller amount than Strive's 2,000. Strive has been ramping up its accumulation at moments when the largest corporate holder has slowed down, and the company now ranks as the sixth-largest corporate holder of Bitcoin globally. CEO Matt Cole hinted at further purchases on Sunday, posting a chart on X showing the company's holdings and writing "Strive for Amplified Bitcoin," a phrase that describes the company's strategy of offering leveraged Bitcoin exposure through its common stock, funded by preferred equity.
Beyond the Bitcoin purchases, Strive announced a preferred stock buyback program of up to $500 million and stated that its current objective is to maintain an accretion ratio above 60% while Bitcoin trades below $100,000. The company also said it intends to operate with no debt. That combination, preferred equity funding, a buyback program for that preferred stock, and a no-debt policy, gives Strive a capital structure that is deliberately different from some of its peers. It is raising money through equity-like instruments rather than borrowing, which reduces the risk of forced selling in a downturn.
The market's initial reaction was measured. Strive shares were up 3.30% in Monday's pre-market trading after closing 0.27% lower at $30.03 on Friday. Bitcoin itself was trading near $86,465, up about 1.5% over 24 hours. The stock's modest move reflects the fact that the purchase was widely anticipated after Cole's Sunday post, and that the broader macro environment remains a constraint on risk appetite. The 10-year Treasury yield is still above 5.2%, and the Federal Reserve's next move remains uncertain, which keeps a ceiling on how much the market is willing to pay for Bitcoin treasury exposure in the short term.
The net read is that Strive is executing a consistent accumulation strategy funded through preferred equity rather than debt, and it is doing so at a pace that exceeds the largest corporate holder of Bitcoin in weeks when that holder has slowed. The company's holdings now stand at 29,462 BTC, its cash position is close to $285 million, and it holds a meaningful stake in Strategy's preferred stock. The buyback program and the no-debt commitment suggest management is thinking about the durability of the structure, not just the pace of accumulation. Whether that approach delivers better results than the more leveraged models used by some peers will depend on how Bitcoin's price behaves over the next several quarters. For now, the company is buying, and it is doing so with capital that does not carry forced repayment obligations.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC ‌
repost-content-media
ASST-5.26%
SATA-0.50%
STRC-0.05%
BTC-1.27%
Remixpoint added 7.45 Bitcoin to its treasury on October 5, a purchase that lifted the Japanese energy and technology company's total holdings to 1,508.72 BTC and placed it 37th among the top 100 public companies by Bitcoin reserves. The buy is small in dollar terms, roughly $640,000 at current prices, and it would not register as notable if it were an isolated transaction. But it is not isolated. It is the latest step in a deliberate consolidation that has turned Remixpoint from a diversified crypto holder into a pure Bitcoin treasury company.
The shift happened on September 1, when the Tokyo
User_any
Remixpoint added 7.45 Bitcoin to its treasury on October 5, a purchase that lifted the Japanese energy and technology company's total holdings to 1,508.72 BTC and placed it 37th among the top 100 public companies by Bitcoin reserves. The buy is small in dollar terms, roughly $640,000 at current prices, and it would not register as notable if it were an isolated transaction. But it is not isolated. It is the latest step in a deliberate consolidation that has turned Remixpoint from a diversified crypto holder into a pure Bitcoin treasury company.
The shift happened on September 1, when the Tokyo-listed firm sold its entire holdings of Ethereum, Solana, XRP, and Dogecoin in a single session. The sale raised ¥879 million, or about $5.6 million, and generated a net gain of ¥117.8 million after accounting for the original book value. Ethereum produced the largest profit at ¥60.2 million, followed by Solana at ¥49.3 million and XRP at ¥11.5 million. Dogecoin was the only loser, posting a ¥3.3 million loss. The company said the decision to exit altcoins was based on market conditions, the risk-return profiles of the assets, and its financial strategy. After the sale, Bitcoin became the only cryptocurrency on its balance sheet.
That consolidation followed a broader review of the company's treasury approach. Remixpoint had initially pursued a multi-asset strategy in mid-2025, buying roughly 1.2 million XRP and adding Solana and Dogecoin to its balance sheet as a hedge against yen depreciation. Internal financial models projected crypto-segment revenue of up to ¥12.44 billion. But management shifted course over the summer, concluding that the volatility of alternative tokens introduced more risk than the strategy justified. The company adopted what it described as a "selection and concentration" approach, narrowing its exposure to the single asset it viewed as the most durable store of value.
The Bitcoin that remains is not sitting idle. Remixpoint has been lending its holdings through a program that generated 14.92 BTC in interest between February 24 and August 31, 2026. At applicable month-end exchange rates, those fees were valued at approximately ¥164.2 million, or about $1 million. That income was earned without selling any of the underlying asset, which means the company's Bitcoin position grew while its cost basis remained unchanged. The lending program converts a passive reserve into a yield-bearing one, a structure that has become increasingly common among corporate Bitcoin holders seeking to offset the opportunity cost of holding a non-yielding asset.
The company's leadership has aligned itself with the strategy in a way that few public companies have matched. President and CEO Yoshihiko Takahashi receives his entire executive compensation in Bitcoin, a decision announced in July 2025 that made Remixpoint the first listed company in Japan to adopt BTC-only compensation for its top executive. The company framed the move as a form of shareholder-oriented management, arguing that paying the CEO in Bitcoin ensures management shares the same economic risks and rewards as investors. Takahashi's salary rises and falls with the price of the asset he is responsible for accumulating.
The capital behind the Bitcoin position came from a ¥31.5 billion financing secured in July 2025, the proceeds of which were earmarked entirely for Bitcoin purchases. Remixpoint had set an initial target of accumulating 3,000 BTC. Its current holdings of 1,508.72 BTC represent roughly half of that goal. The company has not committed the proceeds from its altcoin sale to further Bitcoin purchases, instead directing those funds toward its core energy business, including grid-scale battery storage projects.
The ranking of 37th globally places Remixpoint in a specific tier of corporate Bitcoin holders. It is far behind Strategy, which holds 848,000 BTC, and Metaplanet, which holds 44,000 BTC. But it is ahead of many smaller treasury companies that have adopted similar strategies, and it is the kind of position that gives the company a meaningful exposure to Bitcoin's price movements relative to its market capitalization. The purchase of 7.45 BTC is a small increment in that context, but it confirms that the company is still accumulating, even as it directs the bulk of its resources toward its operating business.
The net read is that Remixpoint has completed a transition from a diversified crypto holder to a single-asset treasury company, and it is using that position to generate yield while its core energy business grows. The Bitcoin lending program has produced measurable income, the CEO's compensation structure aligns management with shareholders, and the company remains roughly halfway to its stated accumulation target. The small purchase on October 5 is not a headline event on its own. But it is a data point that shows the strategy is still active, and that the company's commitment to Bitcoin as its sole crypto reserve has not wavered.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
$BTC ‌#BTCBreaksThrough$86,000 #ShareWeekly #PlanYourTradesThisWeek
repost-content-media
BTC-1.27%
ETH-1.74%
SOL-2.62%
XRP-4.06%
DOGE-3.10%
The U.S. services sector didn't just grow in September. It grew at the fastest pace in more than four years, and the details inside the report tell a story that is more complicated than the headline number suggests. The S&P Global U.S. Services PMI came in at 58.8 for September, up sharply from 56.5 in August and slightly above the 58.7 flash estimate. The Composite PMI, which tracks both manufacturing and services, held at 58.4, matching the flash reading and marking the strongest expansion in private-sector business activity in over five years. Readings above 50 indicate growth, and these nu
User_any
The U.S. services sector didn't just grow in September. It grew at the fastest pace in more than four years, and the details inside the report tell a story that is more complicated than the headline number suggests. The S&P Global U.S. Services PMI came in at 58.8 for September, up sharply from 56.5 in August and slightly above the 58.7 flash estimate. The Composite PMI, which tracks both manufacturing and services, held at 58.4, matching the flash reading and marking the strongest expansion in private-sector business activity in over five years. Readings above 50 indicate growth, and these numbers are far above that threshold.
The engine behind the surge was domestic demand. New orders rose at their fastest rate in more than four years, driven primarily by U.S. consumers and businesses rather than by exports. Export orders were a weak spot, particularly in services, as unpredictable tariff policy kept international clients on the sidelines. The strength in domestic demand was enough to offset that drag. Services firms reported one of the strongest output expansions in the survey's history, and all five service categories reported higher activity for the first time in ten months, with transportation and storage returning to growth.
The hiring response was equally striking. Employment increased for a third consecutive month, with job creation reaching its fastest pace since June 2022. The surge in demand strained capacity, and backlogs of uncompleted work rose for the 19th consecutive month. Companies responded by adding staff at a rate not seen in more than four years, which tells you that businesses are treating this demand as durable rather than temporary. Business confidence climbed to a one-year high, reinforcing that view.
Then there is the part of the report that matters most for policy. Input costs accelerated to their fastest pace since October 2022, driven by higher fuel, transportation, and wage costs. The war in Iran pushed oil prices higher, and those costs fed directly into what service providers pay to operate. Businesses passed a portion of those costs on to customers, with selling price inflation rising at its second-fastest pace in just over a year. S&P Global characterized the September signal as being in rate-hike territory.
Chris Williamson, chief business economist at S&P Global Market Intelligence, summarized the tension in the data. He said the surveys pointed to accelerating momentum in the economy, with manufacturing and services data consistent with roughly 4% growth in the third quarter and about 5% growth in September alone. But he also noted that rising orders and confidence had pushed companies to hire at record speed, while price pressures continued to risk keeping inflation above the Fed's 2% target. The combination of fast output growth, supply bottlenecks, elevated energy and logistics costs, and rising selling prices is inflationary, especially in services, where price pressures tend to adjust more slowly.
The Federal Reserve's position is now more complicated. The central bank raised rates by 25 basis points to a range of 3.75% to 4.00% at its September meeting, citing elevated inflation, and projections pointed to a median federal funds rate of 4.1% at year-end, with most policymakers anticipating at least one more increase in 2026. Richmond Fed President Tom Barkin said the risks to inflation outweighed those to maximum employment, pointing to firming conditions and continued consumer strength. The services PMI data reinforces that view. When input costs are rising at their fastest pace in nearly three years and companies are passing those costs through, the case for holding rates steady becomes harder to make, even if growth is strong.
For markets, the strong-growth and higher-cost combination is generally hawkish. It reduces the case for near-term policy easing and can lift expectations for higher interest rates and bond yields. Equities face a mixed picture. Cyclically sensitive companies may benefit from strong activity, but higher rates and input costs can pressure long-duration growth stocks, highly leveraged firms, and housing-related activity. Energy and logistics costs were a major driver of September's input inflation, and those costs can feed quickly into delivered goods, travel, freight, and service prices. Trade policy uncertainty remains a drag on export orders, making domestic demand the key growth engine while raising risks for trade-exposed firms.
The net read is that the U.S. economy entered the fourth quarter with stronger momentum than most forecasters expected, and that momentum is being driven by the domestic consumer rather than by exports or manufacturing. The services sector is hiring, order books are filling, and backlogs are building. But the cost of that growth is rising inflation pressure, and that pressure is now showing up in the prices businesses charge their customers, not just in the costs they pay. The Fed's next move will depend on whether those price pressures persist or fade as energy costs stabilize. For now, the data supports the case for caution rather than easing, and the burden of proof has shifted to the inflation side of the mandate.
This article is not investment advice. Analysis is based on publicly available information and does not guarantee future outcomes.
repost-content-media
The U.S. Treasury Department announced on Thursday, October 1, that it planned to purchase up to $6 billion in 10- to 20-year Treasury bonds in a liquidity-backed buyback operation. The transaction took place between 1:40 PM and 2:00 PM Eastern Time and covered bonds maturing between 2037 and 2046. This operation was one of the first major implementations since the Department increased its buyback program from $2 billion to $6 billion last month. The Department reserves the right to evaluate offers from bondholders and reject any prices it deems unsuitable.
The primary goal of the program, as
User_any
The U.S. Treasury Department announced on Thursday, October 1, that it planned to purchase up to $6 billion in 10- to 20-year Treasury bonds in a liquidity-backed buyback operation. The transaction took place between 1:40 PM and 2:00 PM Eastern Time and covered bonds maturing between 2037 and 2046. This operation was one of the first major implementations since the Department increased its buyback program from $2 billion to $6 billion last month. The Department reserves the right to evaluate offers from bondholders and reject any prices it deems unsuitable.
The primary goal of the program, as emphasized by Treasury Secretary Scott Bessent, is to make it easier for investors to trade in less liquid, older bonds. This is a mechanism referred to in the market as "liquidity support" and is seen as part of the Treasury's debt management strategy. At first glance, the program appears to be fulfilling its function; Although bond yields have risen in recent weeks, it has been observed that investors, finding it difficult to trade in the market, have been able to buy and sell without making significant price concessions.
However, there are differing opinions among market participants regarding the size and impact of the operation. According to Reuters, the Treasury accepted only about half of the bonds offered in recent operations, falling below the announced buyback ceiling each time. Purchases were also concentrated on a small number of bonds. This has led some portfolio managers and analysts to question why the government has increased the size of the program but hasn't fully utilized its capacity.
Assessments on the matter suggest that the program's primary aim is not to directly suppress yields, but to support market functioning. ING analyst Padhraic Garvey stated that this flexibility is normal, saying, "The Treasury can rightfully buy less when conditions are not attractive, and it always has the option to buy more." Thomas Simons of Jefferies noted that previous long-term buyback operations had raised between $20 and $30 billion, while the latest operation saw bids drop to $10.47 billion. He suggested that the lower acceptance rate could be partly due to the fact that a significant portion of the most illiquid bonds in the market had already been withdrawn.
Another important aspect of this operation is the nature of the targeted bonds. Many of the bonds repurchased under the program are low-coupon bonds issued during the pandemic when interest rates were at historically low levels. Because market yields are currently much higher, these bonds are trading well below their face value, making them difficult to trade in large volumes. This creates both a liquidity boost and a debt management opportunity. According to John Luke Tyner of Aptus Capital Advisors, if the Treasury can repurchase these bonds at levels of 50-60% of their face value, this could be an effective debt management move. However, it should be noted that the Treasury may need to issue short-term debt instruments to finance these buybacks, and the yields on these instruments are much higher than the coupons on the bonds being repurchased.
In conclusion, the US Treasury Department's October 1st buyback operation stands out as a step towards achieving its liquidity support objective following the expansion of the program. Market players continue to monitor the consistency of the Treasury's strategy and its impact on long-term debt management, rather than the size of the operation. Inflation and employment data to be released in the coming days will more clearly reveal the direction and effectiveness of the support the Treasury provides to the market through such operations.
This article is not investment advice. The analysis is based on publicly available information and does not guarantee future results.
$BTC $NVDA $SPCX
repost-content-media
BTC-1.27%
NVDA-0.75%
SPCX-2.52%