Readers comparing the two licensed Hong Kong issuer paths can use HKDAP and HSBC RedCoin to separate the Anchorpoint distributor path from the HSBC bank-app path. A licence names who may issue. It does not open a wallet, a retail app, or an exchange order book.
During Beta Access, the transparency page is the public numerical check. As of 21 October 2026, Anchorpoint listed circulation of 6,106,921, reserves of 7,210,961, and a 30-day circulation change of +5,099,931 (source: Anchorpoint transparency page). No currency code sits beside those figures. With a par value of HKD 1.00, circulation is a token count until that week’s statement confirms the unit.
Key Takeaways
- HKDAP is a Hong Kong dollar stablecoin with a par value of HKD 1.00, issued by Anchorpoint Financial Limited under HKMA licence FRS01.
- End users do not open an account with Anchorpoint. Access runs through an authorised distributor after that firm’s own checks.
- A transfer needs whitelisted wallets. Sending HKDAP to an address no distributor has verified is rejected by the token rules.
- HKDAP is not described as a security or a yield product. Reserves sit in a trust, and redemption at par runs through distributors.
What Is HKDAP, and How Does It Relate to Anchorpoint and the Stablecoin Issuer Licence?
The Anchorpoint FAQ defines HKDAP (HKD At Par) as a token with a par value of HKD 1.00 on supported public blockchains, backed by a reserve pool whose value must be at least 100% of the par value of HKDAP in circulation and held in trust for holders. Anchorpoint Financial Limited issues that token under HKMA licence FRS01. The design goal is a settlement instrument for tokenised rails, not a claim that pays interest.
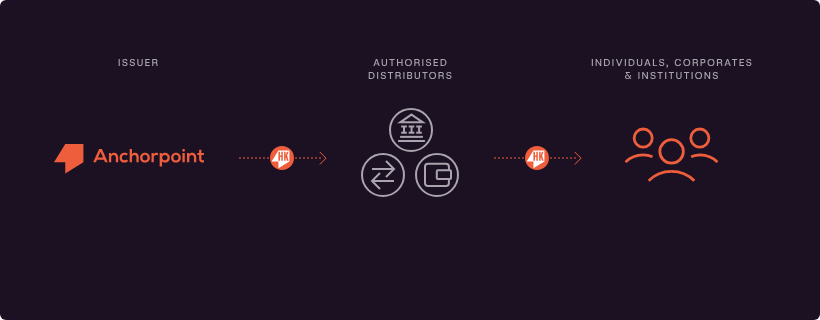
Corporate treasury teams, professional investors, and authorised distributors are the readers who need that boundary. HKDAP is a licensed fiat-referenced stablecoin, not a bank deposit, not the HKMA e-HKD, and not an unregulated offshore token.
Anchorpoint Financial Limited is the issuer, not a second name for the token. It is a Hong Kong company incorporated on 24 January 2025, majority owned by Standard Chartered Bank (Hong Kong) Limited, with Hong Kong Telecom and Animoca Brands as the other material shareholders. Those three firms took part in the HKMA Stablecoin Issuer Sandbox in 2024. The whitepaper lists Level 6, Standard Chartered Building, 4-4A Des Voeux Road, Hong Kong, and the contact contact@anchorpoint.hk.
The Hong Kong Monetary Authority (HKMA) granted licence FRS01 with effect from 10 April 2026 under the Stablecoins Ordinance (Cap. 656), which took effect on 1 August 2025. The HKMA register of licensed stablecoin issuers lists Anchorpoint as FRS01 and The Hongkong and Shanghai Banking Corporation Limited as FRS02. The Hongkong and Shanghai Banking Corporation Limited is a wholly owned subsidiary of HSBC Holdings plc. HSBC RedCoin is that separate HSBC path. HKDAP does not inherit HSBC’s app plan.
The whitepaper assigns Standard Chartered the banking, reserve, and related custody services role around HKDAP, but Anchorpoint Financial Limited remains the licensed issuer. Hong Kong Telecom and Animoca Brands are partners, not the licensed issuer. Holding HKDAP is not the same as holding a same-name deposit at Standard Chartered. Reserve assets sit in a trust, with Standard Chartered Trustee (Hong Kong) Limited holding them for HKDAP holders.
How Are HKDAP Tokens Issued, Distributed, and Redeemed for the Hong Kong Dollar?
Anchorpoint uses a wholesale distribution model. Only firms that finish its due diligence become authorised distributors. Those distributors, not the general public, hold the direct clearing account that can mint or redeem HKDAP at par with the issuer. The whitepaper calls this a pre-funded flow: redemption starts only after the tokens have arrived from a recognised whitelisted wallet and the on-chain deposit has been confirmed.
The distributor-side redemption path in the HKDAP whitepaper runs in three moves.
- The distributor sends HKDAP from an Anchorpoint-recognised whitelisted wallet to Anchorpoint’s designated client wallet.
- After that deposit is confirmed, the distributor submits a redemption request with the token, the network, the amount, and a whitelisted destination bank account. Anchorpoint’s ledger locks the amount. The tokens move to a redemption wallet and are burned.
- After the burn is confirmed, fiat proceeds move from Anchorpoint’s bank account to the distributor’s whitelisted bank account. Anchorpoint states an aim to process these redemption requests within one business day.
End users do not file that request with Anchorpoint. A holder asks the distributor they already use. That firm’s timeline and fees can differ from the one-business-day aim on the distributor-to-issuer leg.
If an exit or insolvency plan is activated, the whitepaper still describes redemption at par from trust assets, subject to distributor fees, plus a claim against the issuer if reserves fall short. A holder who does not redeem within six months of that process may be paid to the source bank account, or reminted to the source wallet if the fiat payment fails.
The whitepaper dates the public offer from 11 August 2026. The phase-1 announcement on 12 August 2026 describes Beta Access for institutional distributors and professional investors, after public-chain transfer tests in the second quarter of 2026. Retail access sits in a later Full Launch, which the issuer ties to end-2026 only if issuance, distribution, and custody are ready together.
Every HKDAP in circulation is supposed to be fully backed by reserve assets worth at least the par value of those tokens in circulation. The product page says the assets sit in a trust, legally segregated from Anchorpoint’s own assets and operating accounts. Standard Chartered Trustee (Hong Kong) Limited is named as trustee for the benefit of HKDAP holders. The whitepaper adds that Standard Chartered Bank (Hong Kong) is the intended custodian and trustee for non-digital reserves, and that digital reserves, if any, would sit with that bank or with Zodia Custody.
The whitepaper limits what can sit in the pool. The categories are the ones the Stablecoins Ordinance and HKMA guidance allow, not a free choice of risky assets.
| Reserve form |
Limit stated in the HKDAP whitepaper |
| Cash |
Part of the high-quality liquid pool |
| Bank deposits |
Term no longer than three months |
| Marketable debt securities |
Residual maturity no longer than one year, plus the credit-quality tests in the whitepaper |
| Overnight reverse repurchase agreements |
Collateralised by those permitted securities, with minimal counterparty risk |
| Dedicated investment funds |
Funds set up only to manage Anchorpoint’s reserve assets |
Anchorpoint may also hold other assets the HKMA accepts. The whitepaper says reserve cash is placed with banks rated no lower than A1/A+ and P-1/A-1. That backing is intended to maintain a stable value at HKD 1.00, subject to redemption mechanics and reserve sufficiency. Segregation does not remove price or liquidity risk. Holders bear a gap if a forced sale of reserves is not enough in an insolvency.
The same 21 October 2026 snapshot also lists cumulative transaction volume of 35,099,666, plus 30-day issuance of 8,750,323 against redemptions of 3,650,392. Those lines are unaudited. Independent attestations start after Full Launch. Confirm the unit in that week’s downloadable statement. The whitepaper points to the statements instead of printing a standing supply.
Who Can Use HKDAP, and How Do Authorised Distributors Fit In?
HKDAP is built for a business-to-business-to-consumer model. Anchorpoint faces the distributors. Distributors face their own clients. The FAQ draws a hard line: only authorised distributors have a direct account relationship with Anchorpoint. Individuals, companies, and most institutions use an account they already hold, or open, with one of those distributors, under that firm’s own onboarding.
Beta eligibility is corporates and professional investors. Retail individuals are described only for Full Launch.
Five names are listed on the FAQ as distributors that had enabled live access, in alphabetical order: Finloop, HashKey, OSL, Standard Chartered Hong Kong, and Yunfeng Financial. The list is a beta roster, not a promise that every one of their products, apps, or client segments already supports HKDAP. Any wider rollout through major digital channels would still depend on each distributor’s own interface, while the HSBC HK App sits in a separate context tied to HSBC’s planned stablecoin path rather than HKDAP. Each firm decides the interface, the client type, and whether a withdrawal to a private wallet is offered.
| Question |
End user |
Authorised distributor |
| Account with Anchorpoint |
No direct account |
Direct clearing account |
| How HKDAP is obtained |
Through the distributor’s own interface after that firm’s checks |
Mint and redeem at par with Anchorpoint |
| Wallet whitelist |
Requested from the distributor if it allows coin-out |
Can co-manage the HKDAP whitelist |
| Beta client type |
Corporates and professional investors |
Firms that pass Anchorpoint’s due diligence |
A would-be distributor needs a relevant licence: in Hong Kong, an HKMA authorised institution or stored-value facility, a Securities and Futures Commission Type 1 licence, or a licensed virtual-asset trading platform. Other markets are reviewed case by case. Intake is described as about eight weeks. That clock is for applicants, not for a client of a firm already on the list.
Standard Chartered Hong Kong has described tokenised money-market-fund settlement, intragroup settlement, and cross-border payments. HashKey and OSL are licensed trading platforms. Finloop and Yunfeng Financial complete the beta names. A Hong Kong licence is not a passport, and distributors can block restricted jurisdictions. Support hours in the whitepaper are 09:00 to 18:00 Hong Kong time.
How Does an On-Chain HKDAP Transfer Work?
During Beta Access, the FAQ publishes one official contract, on Ethereum mainnet: 0x87622385F960fcCB3121d6D0A9513bd1D9Bed6cA. Anchorpoint says each supported chain has exactly one official HKDAP contract. The FAQ presents HKDAP as a payment instrument for tokenised infrastructure, not simply a ticker. A token that uses the name, the symbol, or the branding from any other address is not HKDAP. The whitepaper says Ethereum is the first ledger and that further chains would be added in the whitepaper if they are added at all.
The transfer rule is a whitelist, not an open ERC-20 send. The user alert states that a holder’s wallet must be whitelisted by at least one authorised distributor before any HKDAP transaction can succeed. Two of a holder’s own wallets can move tokens between them if each address has been verified by at least one distributor, and the two distributors need not be the same firm. A send to an address that nobody has verified is rejected by the token’s controls. The FAQ’s wording is that the protocol rejects the transfer. Submitting a transaction on Ethereum can still consume a network fee even when the token movement does not complete, so a failed test send is not free.
Coin-out to a self-custodied wallet exists only if that distributor allows it, and only after wallet-ownership checks. A balance that never leaves the distributor is still HKDAP only when it is the official token. Whether that balance can be withdrawn depends on the distributor’s own rule.
The whitepaper also describes blacklist, freeze, and administrative override. Ethereum still orders transactions. A wallet or pool that is not whitelisted cannot receive a successful transfer.
What Are the Advantages and Risks of Using HKDAP as Tokenised Money?
The useful property is a licensed Hong Kong dollar token for payments, treasury, and tokenised-asset settlement. The issuer presents it as a general-purpose settlement tool with round-the-clock token movement and a public ledger. That does not remove the distributor, the whitelist, or the fiat banking cut-off.
Institutional uses sit in payments and settlement, not in a yield product. HKDAP is not legal tender and is not government-insured. The FAQ says it is not a security and not a yield-bearing product. A return offered by a distributor or a fund is that firm’s product. Par value is a redemption design, not a promise that every secondary quote will print HKD 1.00.
Risks sit in four places.
- Reserve and redemption risk. Price moves, issuer credit, or a rush of redemptions can delay payment or leave a shortfall. Trust segregation is the first protection. A claim against Anchorpoint covers only the unpaid gap in an insolvency.
- Operational risk. Outages and cyber incidents sit with the issuer. Mint keys are described as staying in hardware security modules. A holder who loses a self-custodied key does not get it back. The token is a bearer instrument.
- Control risk. Freeze, blacklist, and pause let the issuer meet a legal order. Terms can change when a new version is published. Continued use is treated as acceptance.
- Chain risk. Forks, congestion, and contract defects sit outside the reserve account. Penetration-test findings were fixed before the Ethereum deployment. That is not a permanent warranty.
Access problems go to the distributor. Complaints about the token can use the form on anchorpoint.hk. The whitepaper aims for a written reply within 30 business days, or 60 if more time is needed. HKMA-referred complaints go to the chief risk officer. Records are kept for at least two years.
How Can You Tell Genuine HKDAP From a Lookalike Token?
Genuine HKDAP exists only in the official contract for each chain Anchorpoint supports. During Beta Access that published address is the Ethereum mainnet contract above. Matching the ticker is not enough. Matching a logo is not enough. A different contract address is a different asset, whatever the token name says.
Check in order: licence FRS01 on the HKMA register, the contract on the Anchorpoint FAQ, the distributor list, then the whitelist if tokens are supposed to leave a platform. Stop if any step fails. On 28 April 2026 the HKMA warned that lookalike tokens were already using the HKDAP name while both licensees said they had not yet issued. Beta issuance came later. A lookalike can keep circulating after the real contract exists.
The 2 July 2026 alert repeats the contract test. A transfer between people does not change the contract address. Yield, a private subscription, or an “early access code” is not part of the issuer’s description of HKDAP.
Summary
HKDAP, as Anchorpoint Financial Limited’s Hong Kong dollar stablecoin, carries a par value of HKD 1.00, issuer licence FRS01, and reserves held in trust. Distribution runs through authorised distributors rather than an open exchange listing. Beta Access is the corporate and professional-investor phase. Retail access is a later Full Launch question. Redemption at par is a distributor process that ends in an on-chain burn and a fiat payment to a whitelisted bank account.
Whether a token is HKDAP depends on the contract, the distributor, and the whitelist. Whether a user can hold it depends on eligibility at one of the named firms. Those checks are not a view on whether to hold the token.
FAQ
What is HKDAP?
HKDAP (HKD At Par) refers to the Hong Kong dollar-backed stablecoin issued by Anchorpoint Financial Limited. Each token has a par value of HKD 1.00, and the issuer describes redemption one-for-one for Hong Kong dollars. Anchorpoint holds HKMA stablecoin issuer licence FRS01 under the Stablecoins Ordinance (Cap. 656).
Is HKDAP an investment or a yield-bearing product?
No. Anchorpoint states that HKDAP is not a security, not a speculative investment tool, and not a yield-bearing product, and that the token itself does not pay holders a capital gain. It is designed as a settlement token pegged to the Hong Kong dollar. A yield offered somewhere else is a separate product.
Who can use HKDAP, and do users open an account with Anchorpoint?
Beta Access is for companies, institutions, and other eligible financial institutions, through authorised distributors. Retail access is described for a later Full Launch, and access is limited to entities granted onboarding approval by the relevant distributor after its checks. End users do not open an account with Anchorpoint. They use a distributor such as one of the firms named on the FAQ, and that firm does the client checks.
What happens if HKDAP is sent to an unverified wallet?
The transfer is rejected. Anchorpoint requires each holder wallet to be whitelisted by at least one authorised distributor before a transaction can succeed. A rejected token transfer can still be submitted to Ethereum, so a network fee may be spent even though no HKDAP moves.
How do you tell genuine HKDAP from a fake token?
Match the contract, not the ticker. During Beta Access the official token is the Ethereum mainnet contract published on the Anchorpoint FAQ, 0x87622385F960fcCB3121d6D0A9513bd1D9Bed6cA. Any other contract using the HKDAP name is not HKDAP. Also check HKMA licence FRS01 and the authorised-distributor list before sending funds.