

Square
Following
Hot
News
Profile
Share your thoughts
placeholder
Article
Still sleeping through range-bound chop? Before Aster surges back to its highs, buy the middle of the range! Go long short-term $ASTE .
Entry: 0.7000 - 0.7035 Take profit: 0.7357 - 0.7629 Stop loss: 0.6790 Please note: Low volume and tangled moving averages increase the risk of false breakouts and sideways chop. Don’t go all in, friends. Position size should match your account size. Waiting for the pump. 👇👇👇 Monitoring $SO and $EPIC throughout the day.
post-image
ASTER+0.11%
EPIC+21.55%
🌐 ONEA NETWORK—the future of digital communities should be about more than communication.
Today, online communities bring together people with shared interests, ideas, and goals.
But what if communities could be more than places to chat—what if they could become gateways to services and the digital economy?
Creators could share digital services, members could support valuable projects, businesses could connect with their users, and everyone could potentially participate in broader digital economic activities.
What is truly worth exploring is not just building bigger communities.
It is making
post-image
Trenches
AGT
A
bade
b
AGT
0x5d...e274
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
CNPY
C
bade
b
CNPY
0xc6...ddd2
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
Q
Q
bade
b
Q
0xc0...0589
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
Gato
G
bade
b
Gato
55A3...pump
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
TSI
T
bade
b
TSI
AcV6...pump
Market Cap
$.
Change
.
24h Vol
$.
Holders
.
Crypto Whales Are Making Big Moves — Is a Major Market Reversal Coming?
live-cover
LIVE2,781
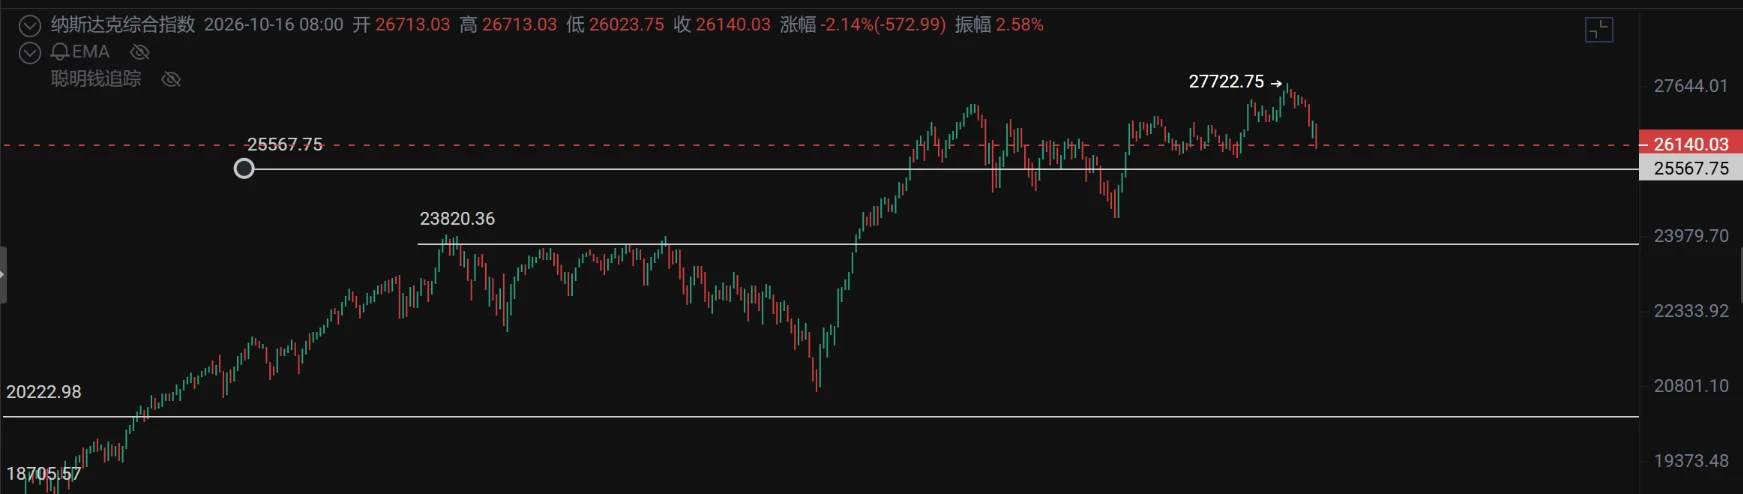
The Nasdaq has started a correction. A weekly bearish divergence is a correction signal, and this correction could be somewhat stronger. It is a multi-timeframe confluence signal, with support at 25,600-24,300-23,800
The question to consider here is: will a U.S. stock market correction spill over to other assets? ❓️
U.S. Treasury yields: The 10-year yield is around 5.09–5.10%, near its highest levels in recent years, putting sustained pressure on high-valuation, long-duration risk assets (tech stocks and crypto)
U.S. Dollar Index: Around 101.8, neutral to firm, with no extreme appreciation
S&P
post-image
SPYX-0.58%
BTC+0.36%
This week, Bitcoin and Ethereum spot ETFs recorded a total of $548.55 million in outflows.
$BTC spot ETFs recorded a total outflow of $228.58 million, while $ETH spot ETFs recorded a total outflow of $319.97 million.
post-image
BTC-0.96%
ETH-1.64%
  • 2
#BTC跌破8.2万 Technical read at $81,668: what the chart says about 81K and 80K
BTC is trading near $81,668, and the question on everyone's screen is whether 81K can hold or 80K gets tested next. Here is the technical picture, level by level, with no guesswork.
Where we came from
Early October looked bullish. BTC ran toward $87,000, then was rejected near that level on October 5, which triggered a cascade of leveraged long liquidations. The week's high was $84,323.70 on October 12, and the low was $79,841.60 on October 15, right after the hot CPI (3.7% year over year, core 2.6%). That is a 5.6% we
post-image
Falcon_Official
#BTC跌破8.2万 Bitcoin at $81,570: Has the CPI Shock Been Priced In, or Is $80,000 the Next Test?
Bitcoin’s move below $82,000 has shifted the market’s focus from the possibility of a $90,000 rally to the strength of the current support structure. Trading near $81,570, BTC is facing a combination of renewed US inflation pressure, changing Federal Reserve expectations, and uncertainty over leveraged positioning. The critical distinction is whether the market has already absorbed the inflation shock or whether another round of selling could follow.
September CPI Changed the Macro Picture
The US Bureau of Labor Statistics reported that headline CPI increased 3.7% year over year in September, accelerating from 3.4% in August. Monthly inflation reached 0.6%, compared with 0.4% previously. Core CPI, excluding food and energy, rose 2.6% annually and 0.3% monthly.
Energy was a major contributor. Gasoline prices climbed 9.1% in September, accounting for more than half of the monthly increase in headline CPI. The energy index advanced 5.2% during the month, while shelter costs increased 0.4%.
These figures complicate the outlook for monetary easing. Persistent inflation can keep interest rates restrictive for longer, potentially supporting the dollar and Treasury yields while reducing investors’ appetite for risk-sensitive assets.
However, the inflation report does not automatically guarantee another rate hike. The Fed must evaluate incoming economic data, employment conditions, and the persistence of price pressures before determining its next move.
Why BTC Fell Below $82,000
Bitcoin’s decline reflects the sensitivity of crypto valuations to macroeconomic expectations. When inflation exceeds forecasts, markets may reassess the timing of rate cuts or the possibility of further tightening. Higher expected borrowing costs can make speculative positions less attractive, particularly when leverage is elevated.
Market reporting following the CPI release showed Bitcoin falling to approximately $80,247 before trading around $80,743 in the subsequent session. BTC has since approached the $81,570 level referenced here, but a recovery from the lows alone does not confirm a trend reversal.
The key question is whether buyers are returning through sustained spot demand or whether the rebound is primarily driven by short covering. These two scenarios can produce similar price action initially but have different implications for durability.
The $81,000–$80,000 Support Test
At approximately $81,570, Bitcoin is close to an important psychological area. The $81,000 region deserves attention as a near-term reference, while $80,000 is the next major round-number level traders may monitor if selling pressure resumes.
A sustained recovery above $82,000, supported by stronger spot volume and improving market breadth, would help repair the short-term structure. If BTC repeatedly fails to reclaim that level, sellers may retain control and the market could revisit lower support.
A break below $80,000 would increase downside risk, but it would not automatically establish a prolonged bearish trend. Confirmation would require examining subsequent price acceptance, trading volume, and whether buyers defend the breakdown area.
These levels are technical reference points, not guaranteed turning points.
Liquidations and Leverage: The Hidden Risk
During sharp declines, leveraged long positions can face liquidation as collateral becomes insufficient. Forced selling can amplify downward momentum, creating a feedback loop in which falling prices trigger further position closures.
Open interest helps distinguish between different forms of selling pressure. If BTC declines while open interest contracts sharply, traders may be closing positions or being liquidated. If open interest rises during the decline, new positions may be entering the market, although the direction of those positions cannot be established from open interest alone.
Funding rates provide additional context. Persistently positive funding during weakening price action may indicate that long exposure remains crowded. A reduction in funding and leverage could help stabilize market conditions, but it would not independently confirm a bottom.
Is the CPI Shock Already Priced In?
Markets often react to the difference between expectations and actual data, not simply to whether a headline looks positive or negative. Some of the inflation risk may already be reflected in Bitcoin’s decline, but that cannot be established from price alone.
If Treasury yields stabilize, the dollar loses momentum, and BTC reclaims $82,000 with credible spot demand, the market could begin recovering from the initial shock. If inflation concerns intensify and leveraged positions continue unwinding, $80,000 may come into focus instead.
The most important signal is confirmation across macroeconomic conditions, spot activity, and derivatives positioning.
At $81,570, Bitcoin is at a decision point rather than a confirmed bottom. Preserving capital, controlling leverage, and waiting for price confirmation are more defensible approaches than assuming either an immediate rebound or an inevitable breakdown.
repost-content-media
BTC+0.36%
How long will it take you to figure out where the problem is?
post-image
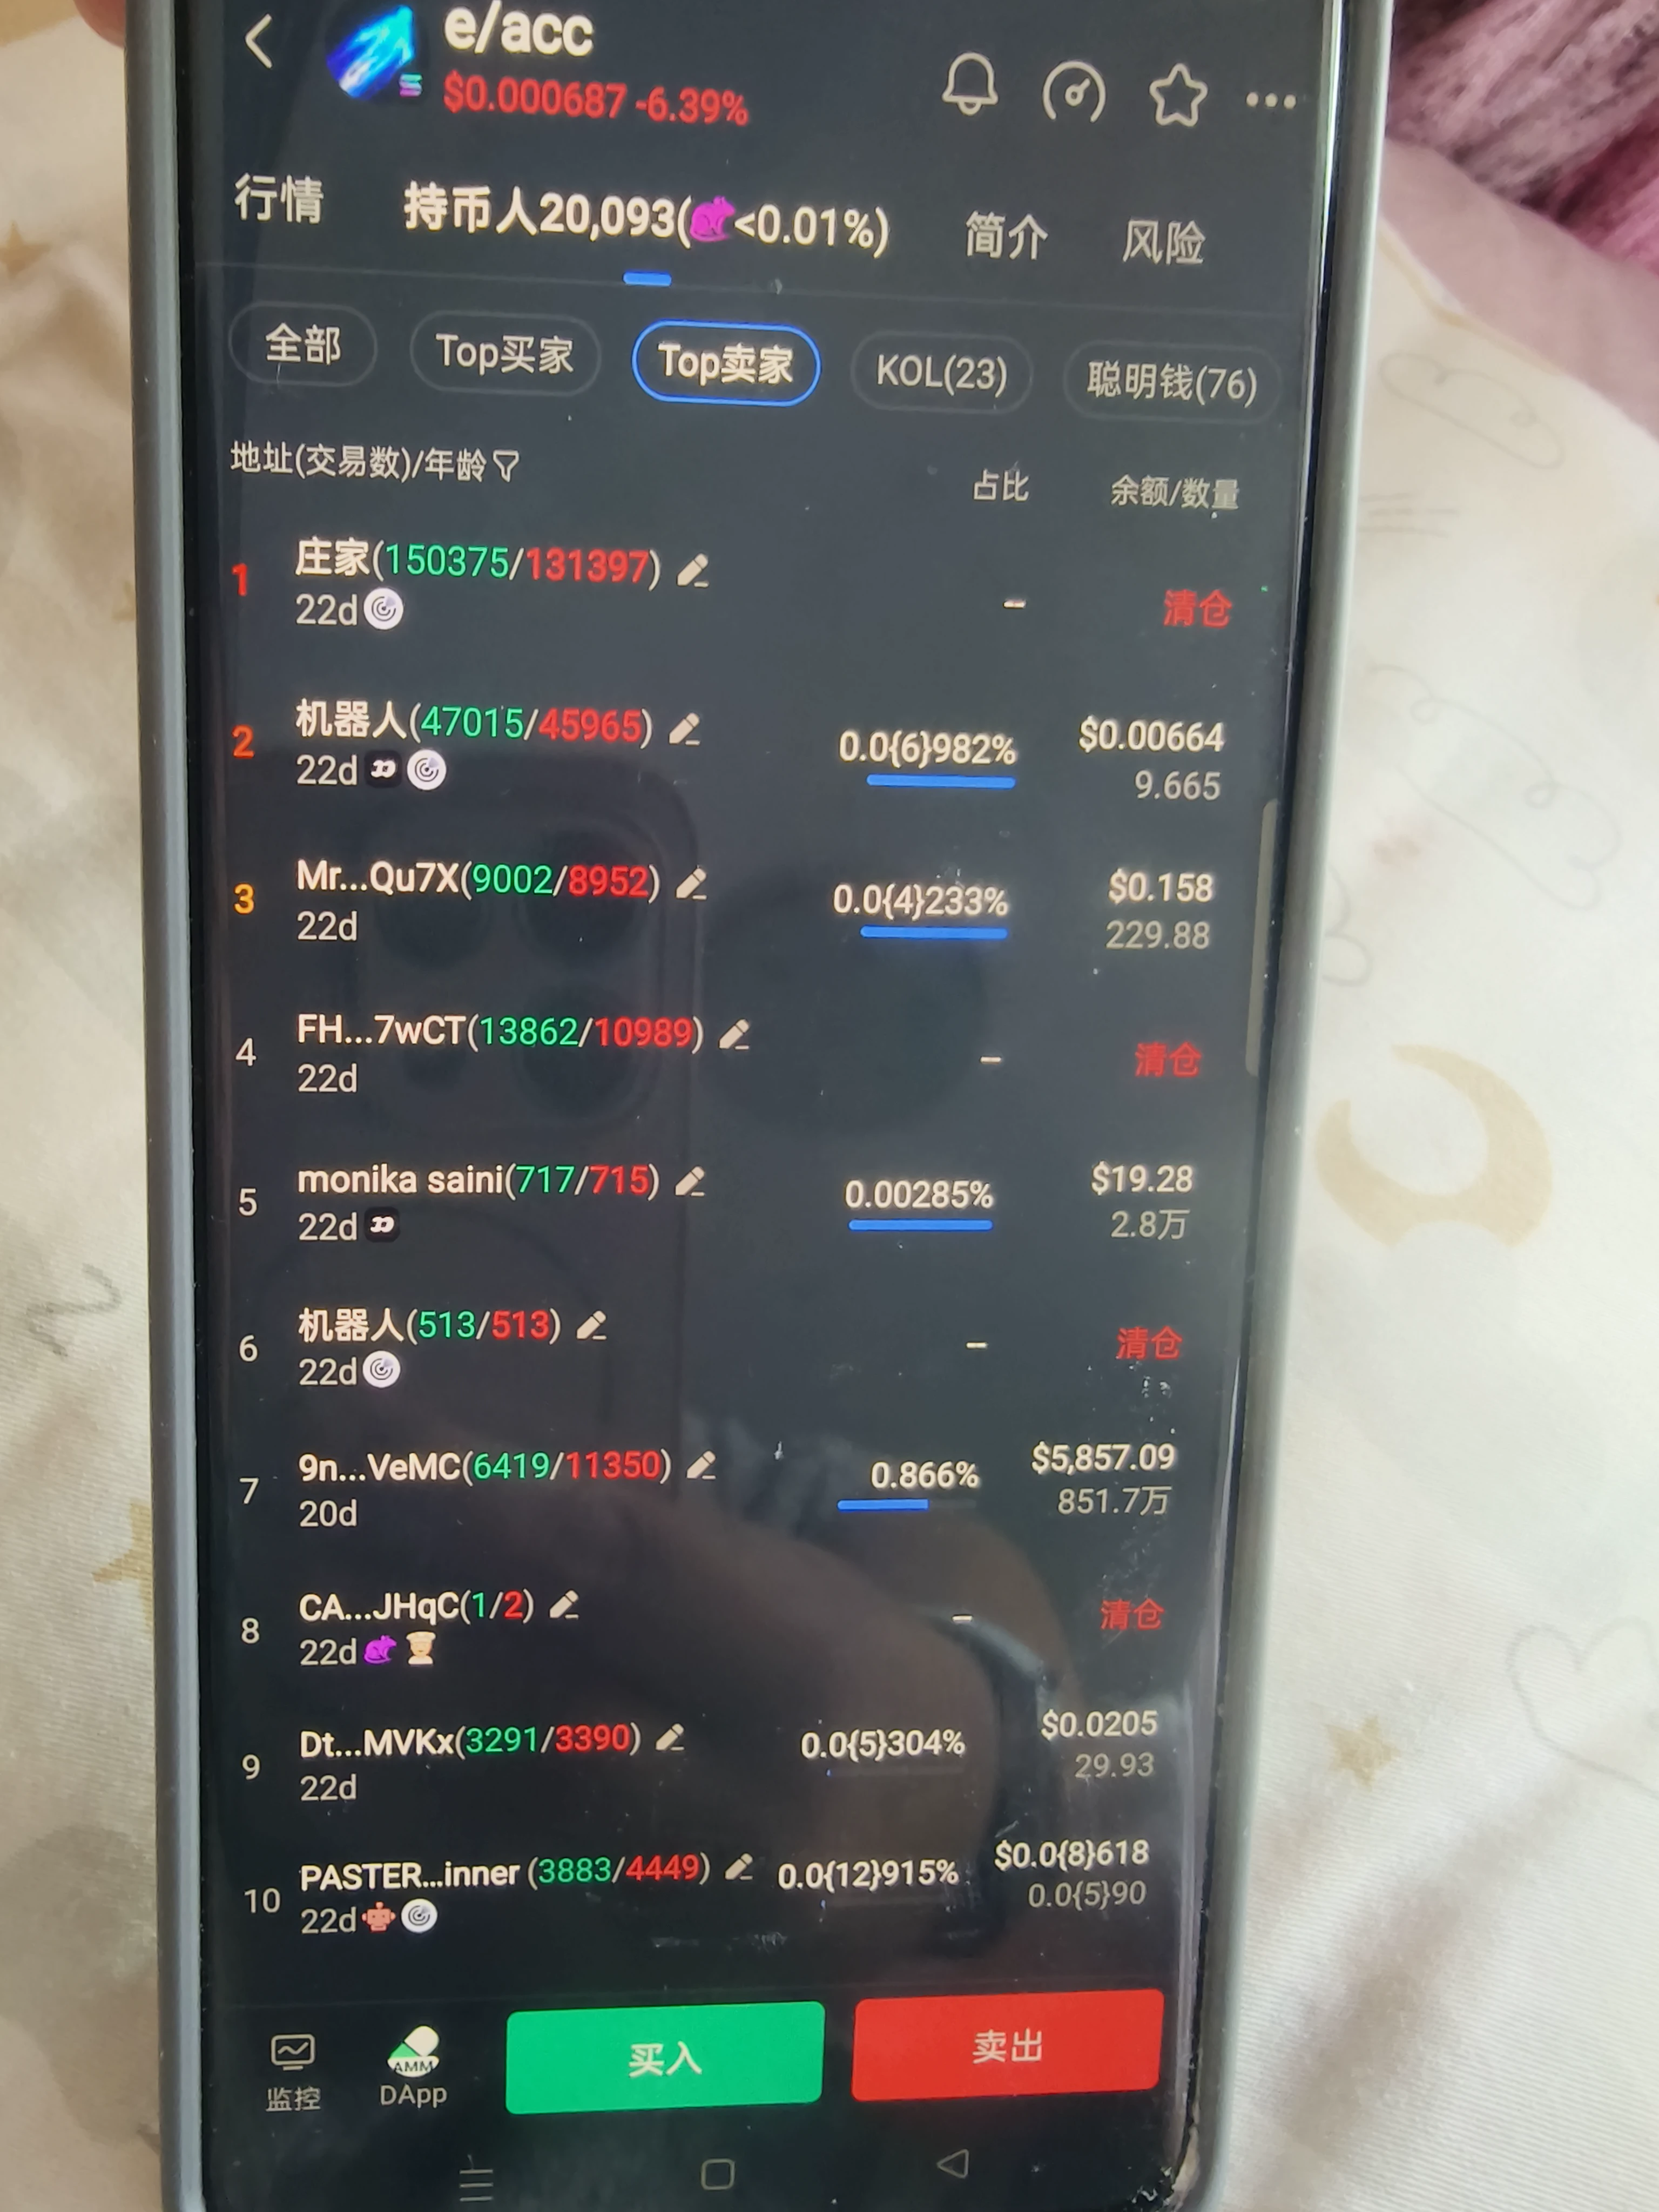
$EACC is about to be delisted, and its market cap will soon hit zero. Going long on this dumbass shit cost me a few hundred bucks—fucking disgusting. The scumbag market maker has already cashed out, making less than $2 million. What a fucking lack of vision
post-image
EACC-15.49%
$BTC BOOM💣It's about to explode soon; the big player is starting to accumulate, forming a daily double bottom, with a large pool of liquidity above🤩
Long, long, long🔥🔥TP1: 82500 TP2: 84000 TP3: 87000-90000 SL: 78200$AG $ETH
post-image
BTC+0.36%
AG-0.65%
ETH-0.28%
During the 2021 bull market, $SHIB rose 111,468,947%, $GALA rose 52,000%, and $DOGE rose 38,700%. Which 3 altcoins could rise the most in the 2026 bull market?
post-image
SHIB-1.89%
GALA-3.39%
DOGE-0.76%
#美股存储板块跌幅扩大 Friday's session gave me a clear answer on how deep this storage selloff really is, so I rebuilt my sector notes from the numbers. Here is where I stand after the close on October 16.
The damage is big. Micron fell 5.63% on Friday and 14.6% on the week, while SanDisk dropped 6.85%, Western Digital about 7% and Seagate more than 7%, with the storage chip index down 17.6% on the week. SanDisk closed at $1,299.30, its seventh lower close between October 8 and October 16. Against its June high close of $2,335, that is about 44% lower by my math.
The bigger picture is even harsher. Six
Falcon_Official
#美股存储板块跌幅扩大 The Nature of the U.S. Tech Pullback Is Shifting: From Valuation Repricing to Credit-Chain Repricing
Many people are still viewing U.S. stocks through the old “AI pullback = buying opportunity” playbook. But if you only watch the Nasdaq and the Philadelphia Semiconductor Index, you may miss the most important change:
July was “AI valuation/positioning repricing”; October is a triple hit from “the AI credit chain + high interest rates + geopolitics/oil prices.” The latter is closer to a “credit-side preview” of the bursting of the 2000 internet bubble, but we’re not yet in a full-blown bear market.
I. July pullback: Expensive, crowded, but no blowup!
Trigger: Google/Meta/Tesla raised CAPEX forecasts, FCF turned negative, and the market asked, “When will AI spending pay off?”
QQQ fell from a June high of ~$748.65 to a July 29 low of $661.14, a peak-to-trough decline of 11.7%; QQQ fell 6.5% for the full month of July, and SOXX fell 21%.
The 10-year Treasury yield was at 4.6–4.75%; the VIX spiked to 20.66 on a weekly basis (+24%), but the broad VIX did not stay above 22. VXN reached 26, but there was no panic spike.
The S&P edged down, while equal-weight stocks rose; money rotated within equities (tech → Dow/healthcare/consumer). Bonds didn’t rally, and yields rose → this wasn’t a flight to safety, but “semiconductors are too crowded, trim them first.”
Outcome: The 200-day moving average at $645 held, and stocks recovered after August. This was a correction that could be bought.
II. October pullback: From “valuation” to “who can’t repay their loans?”
The logic behind this tech pullback since October is more like:
Borrow at a 15% cost to build compute capacity → rental income can’t cover interest → credit cracks appear first → semiconductor order expectations get cut → quite a few sell-side firms are using the 2000 internet bubble as a reference (the Nasdaq crashed, while long-bond yields fell from 6.5% to the mid-4% range).
Market action: It’s not a broad selloff; “highly leveraged growth + AI infrastructure” are being singled out for punishment. From 10/14–10/16, the Dow rose 0.67% for the week, XLV/energy were strong, the SPX fell ~1.95% for the week, and the Nasdaq fell 4.48% for the week (its worst since June); the Philadelphia Semiconductor Index (SOX) fell for 8 straight days (the longest streak since 2008);
Among individual stocks: CRWV fell 25% for the week, CDS breached 1000bp, and its 5-year default probability was priced at 60%+.
The 10-year Treasury yield fell from 5.3% to 5.07–5.19%, but this was a safe-haven decline as stocks fell and money fled into Treasuries, not a central-bank rescue; the VIX broke above 22, Brent crude topped 110, and tensions in the Middle East and Russia-Ukraine escalated.
Investor sentiment: the CNN Fear & Greed Index fell to 18, but it’s not yet at the extreme “2–4” levels seen in 2018/2020—meaning the market is shifting from “uncomfortably expensive” to “a little worried about credit,” but this is not a COVID-style liquidity collapse.
III. How have similar “credit-side + tech selloff” pullbacks played out historically?
The 2000 internet bubble burst: The Nasdaq was cut in half, then cut in half again from its peak, while the S&P lagged; valuations were hit first, then earnings, then credit, and bonds ultimately entered a bull market. The difference today: major tech issuers aren’t pure concepts; their cash flows/cloud revenues are real. So this isn’t a repeat of 2000, but “the 2000 credit playbook + the 2022 interest-rate playbook.”
The 2022 rate-driven growth selloff: The 10-year Treasury yield surged from 1.5% to 4.3%, QQQ fell 35% from its peak, and SPY fell 25%; the core issue was the “discount rate,” not credit defaults. The 10-year Treasury yield is now above 5%; megacaps are hurting, but banks/consumer/healthcare haven’t collapsed.
2018 Q4 deleveraging: The VIX spiked to 35, QQQ fell about 20% for the quarter, and stocks made a V-shaped recovery after the Fed turned dovish; the Fed isn’t as hawkish now, but inflation + oil prices mean it can’t turn dovish freely.
March 2020 liquidity black hole: The VIX hit 80, and stocks, bonds, and gold all fell together, with the Fed providing a backstop; there’s no COVID-style liquidity freeze now, and CRWV is an individual credit event, not a market-wide counterparty crisis.
Historical rules of thumb
“VIX above 20 + 10-year Treasury yield rising + tech leading declines” → usually the middle of a pullback, not the bottom.
“VIX plateauing at high levels + 10-year Treasury yield starting to fall + semiconductors no longer making new lows” → only then is it a signal to add to QQQ.
Until credit events (CDS widening, high-yield bond spreads widening) stabilize, every QQQ rebound is prone to being sold.
Historical timing reference: the July pullback took 3–5 weeks to recover; with an October-style “credit + rates + geopolitics” combination, a bottom usually isn’t in until the VIX returns to 16–18, CRWV bonds stop falling, and SOXX posts a high-volume candle without making a new low. This often takes 3–8 weeks; if credit spreads widen to Oracle/major tech bonds, it can drag on for a quarter.
IV. The counterintuitive point during earnings season: stock prices are falling, but earnings haven’t collapsed. In the first week of the new 26Q3 earnings season, about 9% of large S&P 500 companies had reported earnings. Stock prices are falling, but earnings haven’t collapsed—the declines reflect “discount rates + credit expectations,” not “current results.”
Companies that have reported: earnings up 29% year over year, revenue up 12.6%;
26Q1 earnings up 28.6%, 26Q2 up 50.4% → the strongest earnings cycle since 2021Q2;
Market pricing for full-year 2026: earnings up 32.8%, revenue up 12.7%;
Q3/Q4 earnings expectations: +29% / +28.6%;
The S&P’s forward P/E is 19.0: below the 10-year average of 19.1 and the 5-year average of 19.8.
This isn’t an “earnings collapse”; the market is getting ahead of three fears:
① AI CAPEX returns in 2027 will fall short of expectations;
② 10-year Treasury yields at 5%+ will discount long-duration assets;
③ AI credit-chain players like CoreWeave will blow up first.
So this is neither 2000 (earnings fraud/disappearance) nor 2022 (earnings downgrades + interest-rate battering). It’s “earnings are very strong, but valuation logic is being repriced for credit risk.”
V. Why is the week of October 19–23 a turning point?
This isn’t an ordinary earnings week. It’s a week to “use real-economy cash flows to rescue tech valuations.”
1) Wednesday’s two pillars: META + TSLA
What to watch for in META:
Will CAPEX be revised higher again, how are advertising/AI monetization progressing, and what is happening with free cash flow?
If it says “we’re continuing to invest more in AI, but ROI is clear” → it eases July-style spending concerns;
If it says “returns are slower than expected” → QQQ could sell off again.
What to watch for in TSLA:
It’s not just a car company; it’s a high-beta proxy for “AI / robotics / energy storage.”
Deliveries, gross margin, FSD, and what it says about Optimus matter more than sales volume.
A weak TSLA → high-beta tech sentiment could collapse again.
2) Industrial / defense / payments: proof that “the non-AI parts of the economy are holding up”
GE, RTX, NOC, LMT, MMM, UNP, CAT names (URI), AXP, COF:
Industrial orders = the temperature of the real economy;
Credit cards (AXP/COF) = consumer resilience and delinquencies;
Defense (RTX/NOC/LMT) = a geopolitical premium, but with budget constraints.
If they hold up, investors will be more willing to stay in SPY / XLI / XLV rather than go back to catch the falling knife in QQQ.
3) Macro anchors
Tuesday: housing starts / existing-home sales → has housing frozen under 5%+ rates?
Thursday: initial jobless claims + leading indicators → are there cracks in employment?
Friday: manufacturing / services PMI → soft landing or a second downturn in manufacturing?
These data will determine whether the 10-year Treasury yield holds 5.0% or surges to 5.3%–5.5%, and will directly determine the discount rates for SPY / QQQ.#WCTCS9
MU-5.66%
STX-7.45%
🌐 ONEA NETWORK—Connection is just the beginning.
The digital economy continues to evolve, but connecting different systems is only part of the challenge.
What is truly worth considering is whether these systems can work together effectively.
Payment services can connect users and merchants, digital platforms can connect creators and audiences, and communities can bring together people with shared interests.
But if these experiences remain isolated from one another, users may still face unnecessary steps and barriers.
🔗 Why does interoperability matter?
Simply put, interoperability means enab
post-image
#KOSPIJumps3.3% 📈🇰🇷 | South Korea’s Stock Market Strikes Back!
After a brutal sell-off, South Korea’s KOSPI delivered a powerful rebound on October 16, climbing as much as 3.31% to 5,738.18 during the session. The bounce followed a 7.57% plunge the previous day that rattled investors and triggered a temporary trading halt.
🔍 What Fueled the Recovery?
🇺🇸 Wall Street offered relief: Gains in US equities helped restore some confidence across Asian markets.
💻 Chip stocks bounced: Samsung Electronics and SK Hynix recovered as investors r
post-image
  • 1
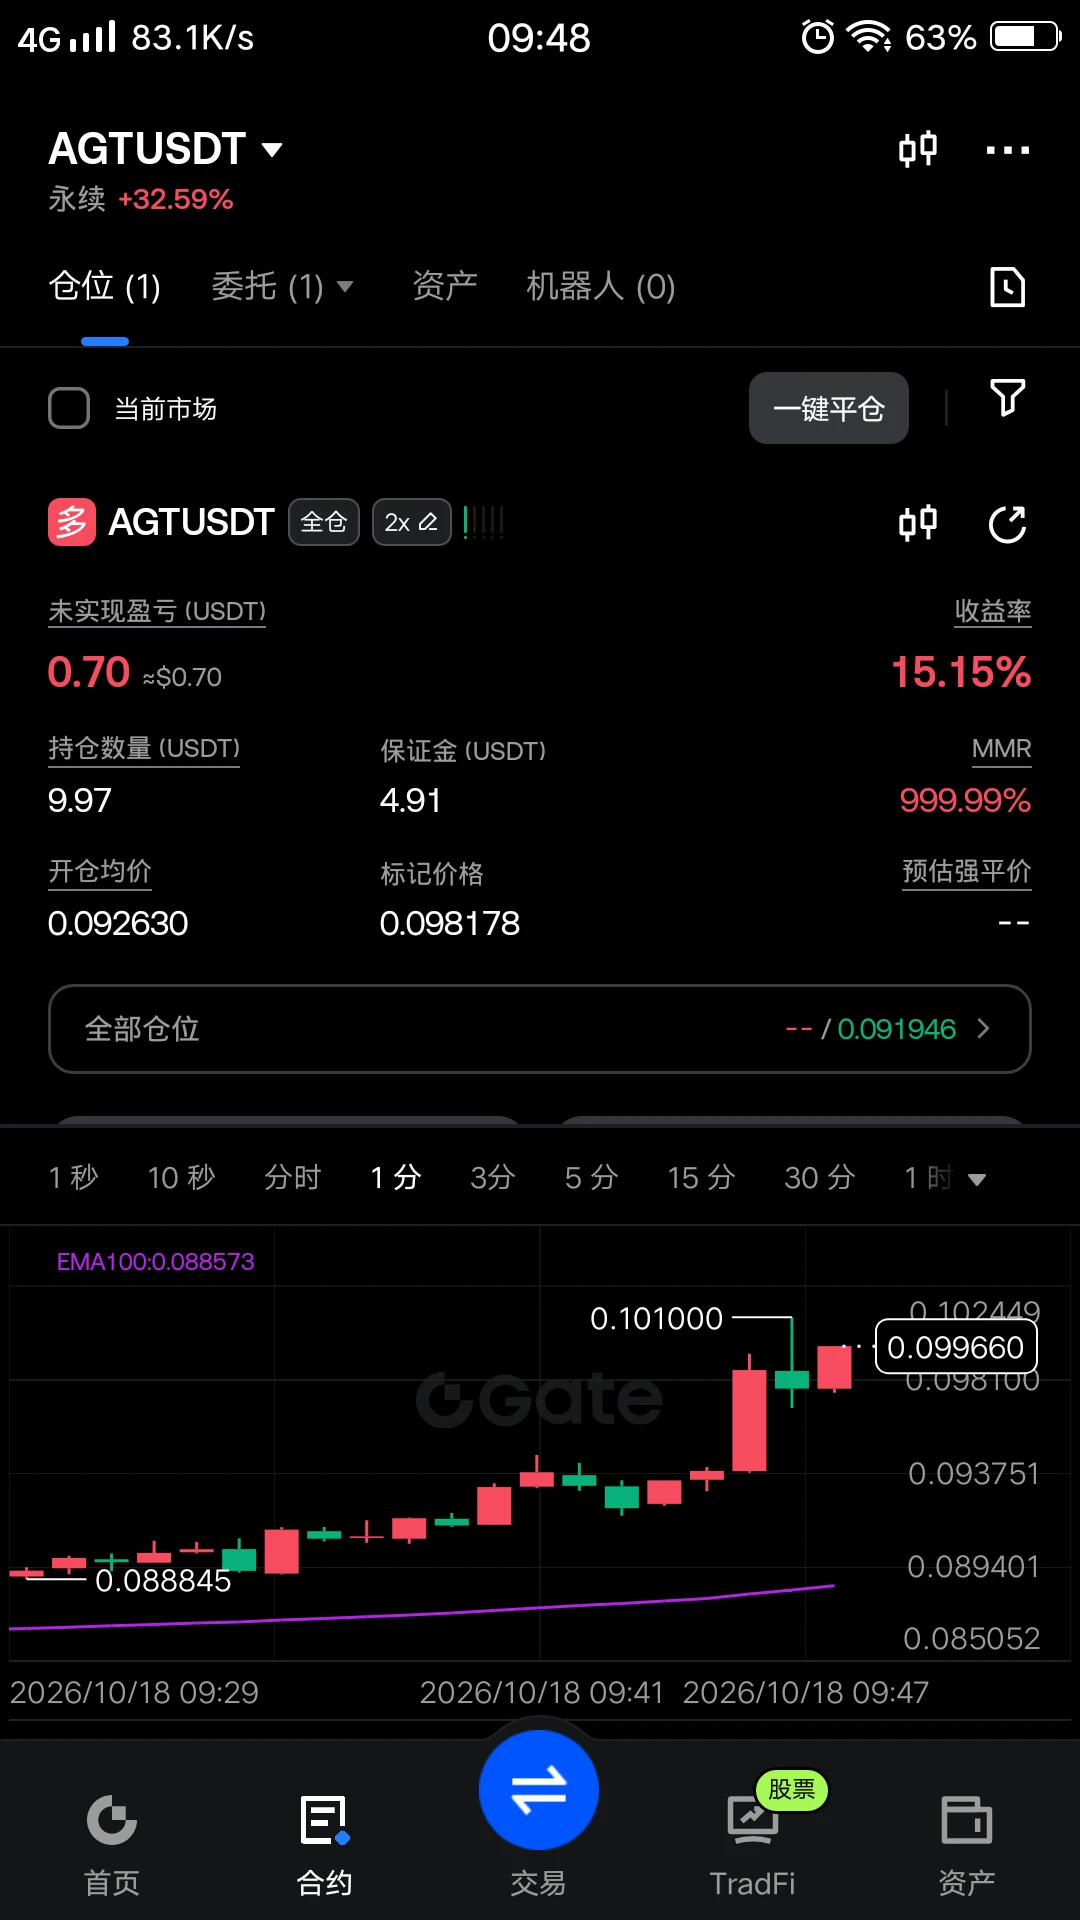
$AGT Made a killing with a tiny position, got wrecked with a large one
post-image
AGT+9.92%
BTC MARKET UPDATE
live-cover
LIVE1,394
$BR This wick was beautifully drawn by the market maker. After sweeping 0.3541, it shot straight back to 0.4684. A 22.68% 24-hour range and 112.5M in trading volume: retail investors see a massive surge; I see a script.
Let’s run through the market maker’s playbook: place fake buy orders around 0.35 to prop up the market and get panic sellers to capitulate, then use wash trading to pump volume and push past 0.45, triggering short stop-losses, before using the 22% gain to stoke FOMO. The 24-hour high of 0.5370 is a test level. There isn’t much overhead supply, but the 0.50–0.53 range is crowded
BR+23.37%
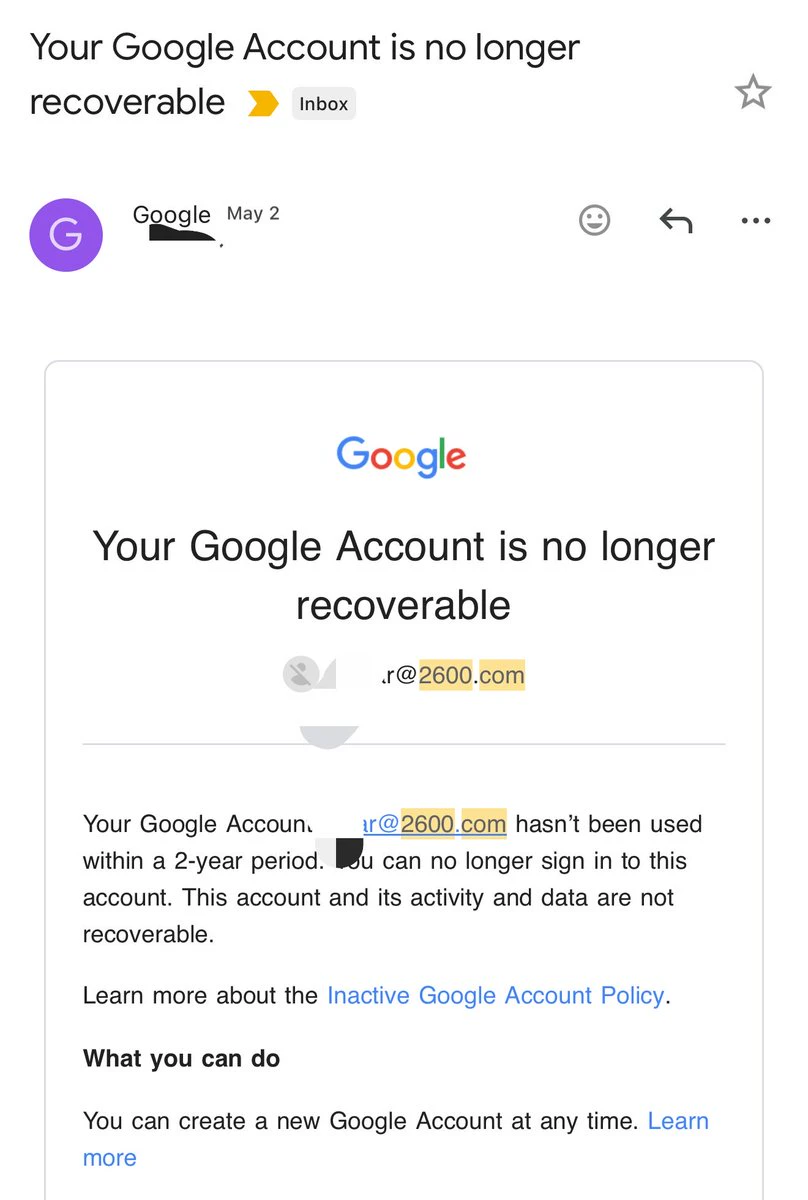
I forgot I had a email address😂😭
post-image
#GateWCTCS9全球交易赛
This weekend’s market action has really worn both bulls and bears down.
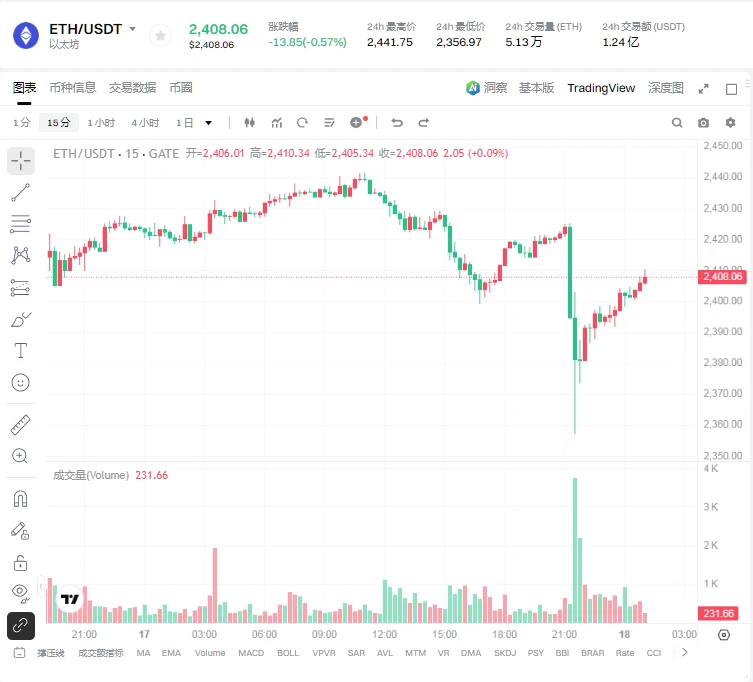
Watching BTC hover around $81k feels like waiting for the other shoe to drop. Another huge bearish wick appeared overnight. It looked scary, but after breaking below $81k, the price was yanked back up, reclaiming $81.4k in under half an hour. Volume didn’t explode out of control, and a pile of buy orders at lower levels was absorbing the selling. To me, this looks more like a “liquidation-driven fakeout” than a downward trend reversal.
It feels like big money used the panic to carry out a massive rotation
post-image
ETH-0.21%
  • 9
  • 1
Those who’ve studied abroad really are different.
They swallowed it whole with ease.
Load More

Join 40 M users in our growing community

⚡️ Join 40 M users in the crypto craze discussion

💬 Engage with your favorite top creators

👍 See what interests you

Trending Topics

USSeptemberPPIBeatsExpectations

91.35k Views1.93k Discussing

US September PPI came in at 6.3% YoY, well above the 5.3% market expectation, pointing to renewed producer-side inflation pressure. Weekly jobless claims were 199K, broadly in line with forecasts. Could hotter inflation further reduce room for rate cuts, and what does it mean for $BTC, US stocks, and gold?

GateWCTCS9GlobalTradingCompetition

37.87k Views6.7k Discussing

GateBTCAndETHFuturesVolumeRanksTop3

53.8k Views1.83k Discussing

View More