#Gate股票观点挑战 |
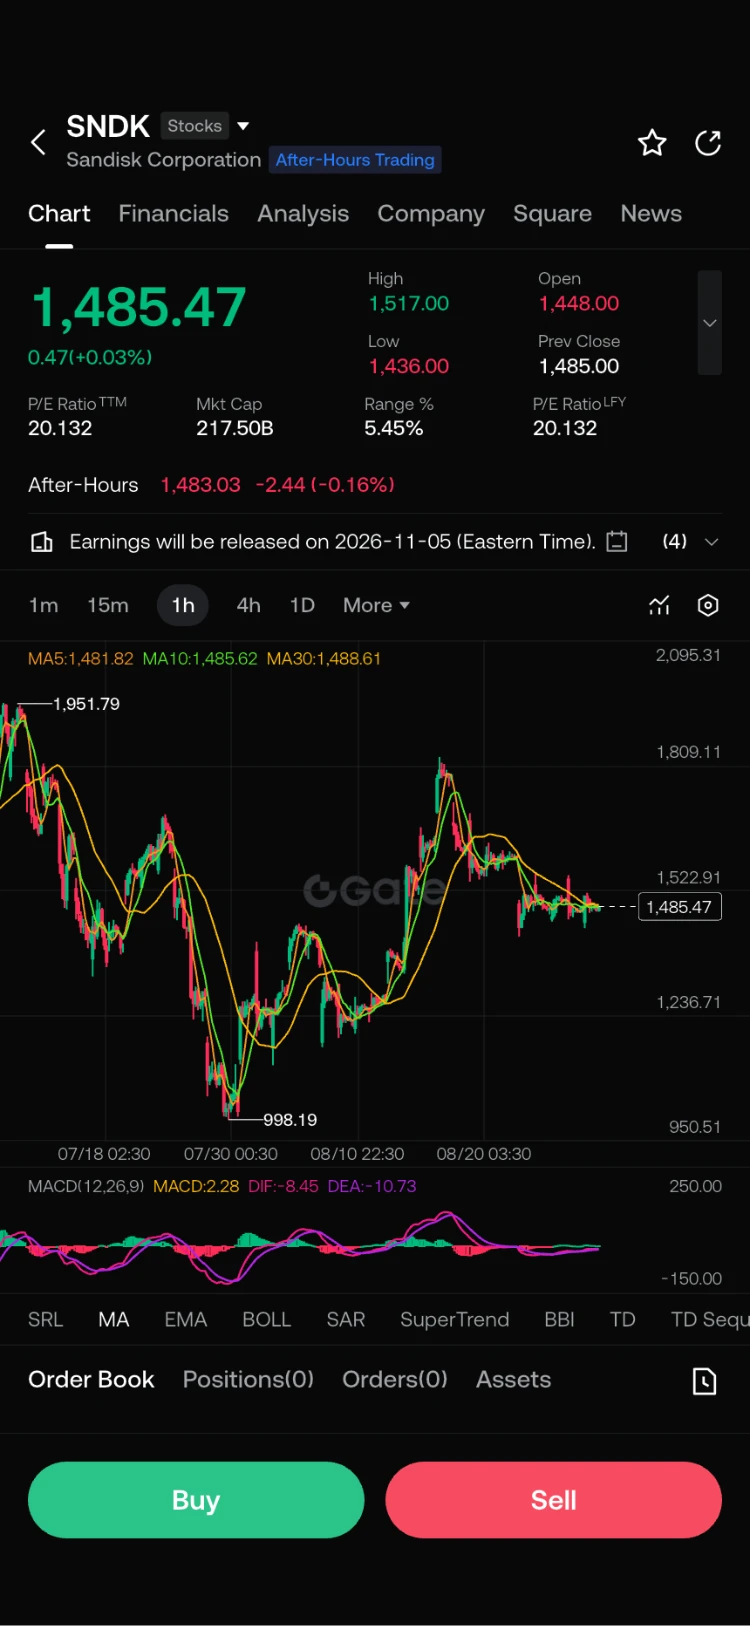
$SNDK DID SNDK BECOME CHEAP JUST BECAUSE IT FELL 9%?
I think this is the real question.
It is difficult to see any serious deterioration in SanDisk’s core story at the moment:
📌 Q4 revenue was $8.97 billion, with 51% quarterly growth.
📌 FY2026 revenue guidance is $20.25 billion → a 175% annual increase.
📌 Q1 FY2027 revenue guidance is $10.3–$10.8 billion.
📌 Data center demand is said to be accelerating.
📌 Multi-year agreements covering more than 50% of FY2027 bits are in place.
In other words, the company’s story features a strong combination of AI + data center + NAND demand.
But the market sometimes buys not the company’s present, but how much of its future expectations have already been priced in.
And this is exactly the point to pay attention to with SNDK.
🟢 BULL CASE
AI and data center investments accelerate → SSD demand grows → NAND supply remains tight → pricing power is maintained.
In this scenario, the current fundamental story could strengthen further.
🟡 NEUTRAL CASE
Fundamentals remain strong, but the stock already carries high expectations.
Even if the company continues to perform well, the stock may not react the same way if it fails to exceed expectations.
🔴 BEAR CASE
NAND is cyclical.
If prices soften, storage costs create pressure, or AI-driven demand falls short of expectations, today’s high multiples could be repriced very quickly.
That is why my approach is:
Rather than chasing the initial 9% drop, wait to see where the price stabilizes.
Because a 9% drop in a stock does not, by itself, mean that it has become “cheap.”
Sometimes it only says:
Expectations have moved ahead of the price.
The long-term story for SNDK still looks strong.
But a strong story ≠ unlimited valuation.
For me, this is not a “back up the truck” zone; it is a zone to watch for the possibility of controlled buying at the bottom. 👀
$SNDK