Square
Following
Hot
News
Notifications
Profile

TheTradfiGuy

vip
No content yet
Peak Tier VIP 58.3 Year(s)
0
Following
2
Followers
28
Liked
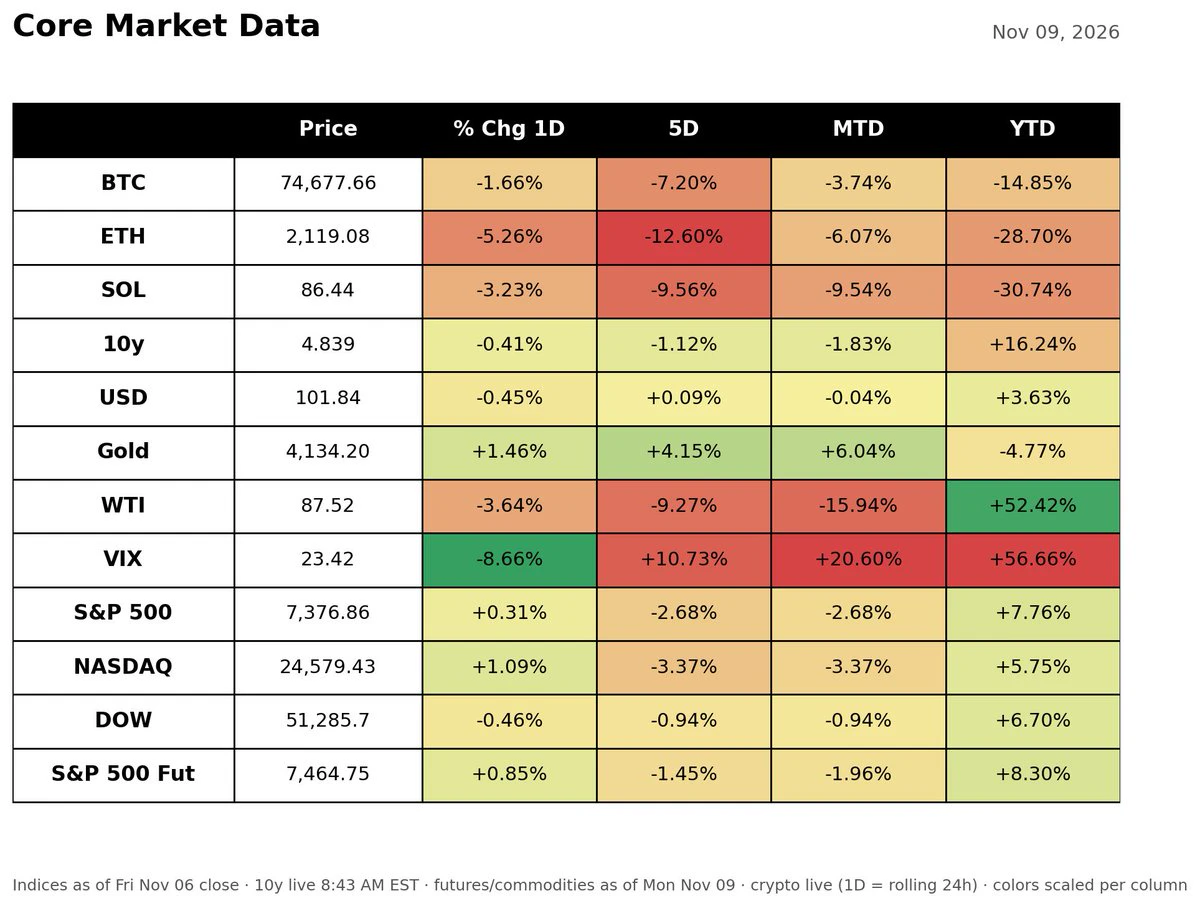
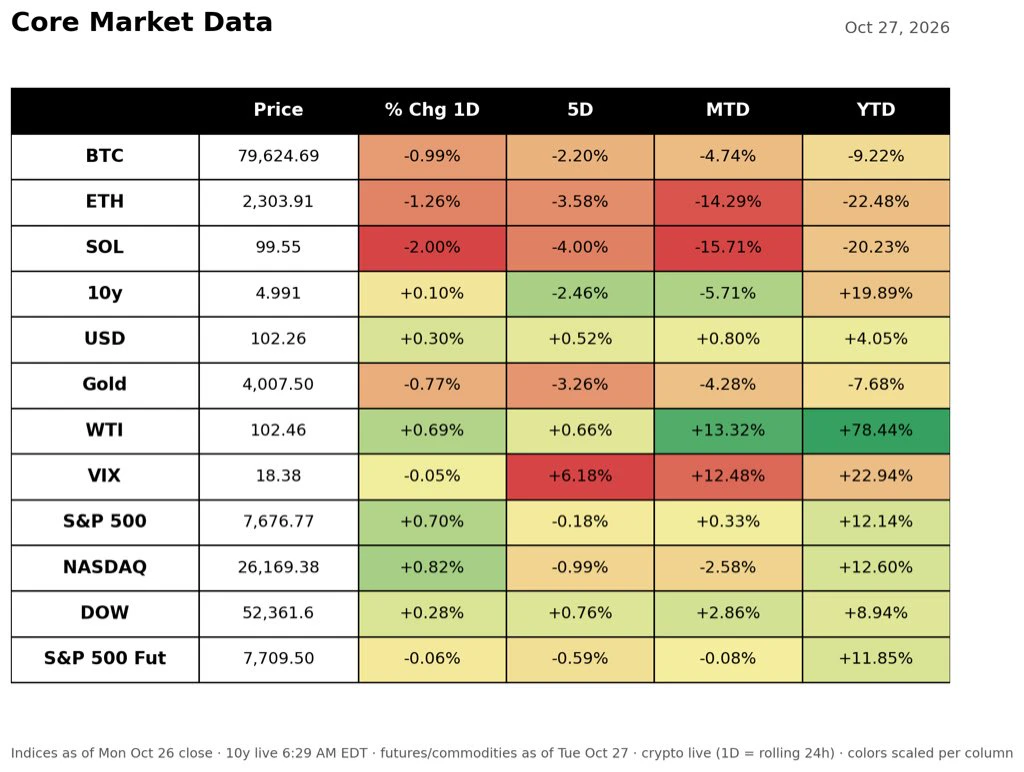
Big slide in ETH despite equities stable this AM after last week’s rout. CPI tomorrow will be key watch point on whether the Fed locks in the December hike or it becomes a toss up. Oil also continues its slide as Iran dropped its demand to control the Strait of Hormuz.
post-image
ETH-1.26%
Total unwind of yesterday’s move as markets lean back into the initial narrative that started the after hours sell off post midterms
Rotations happening under the surface with Chipmakers driving the move lower
post-image
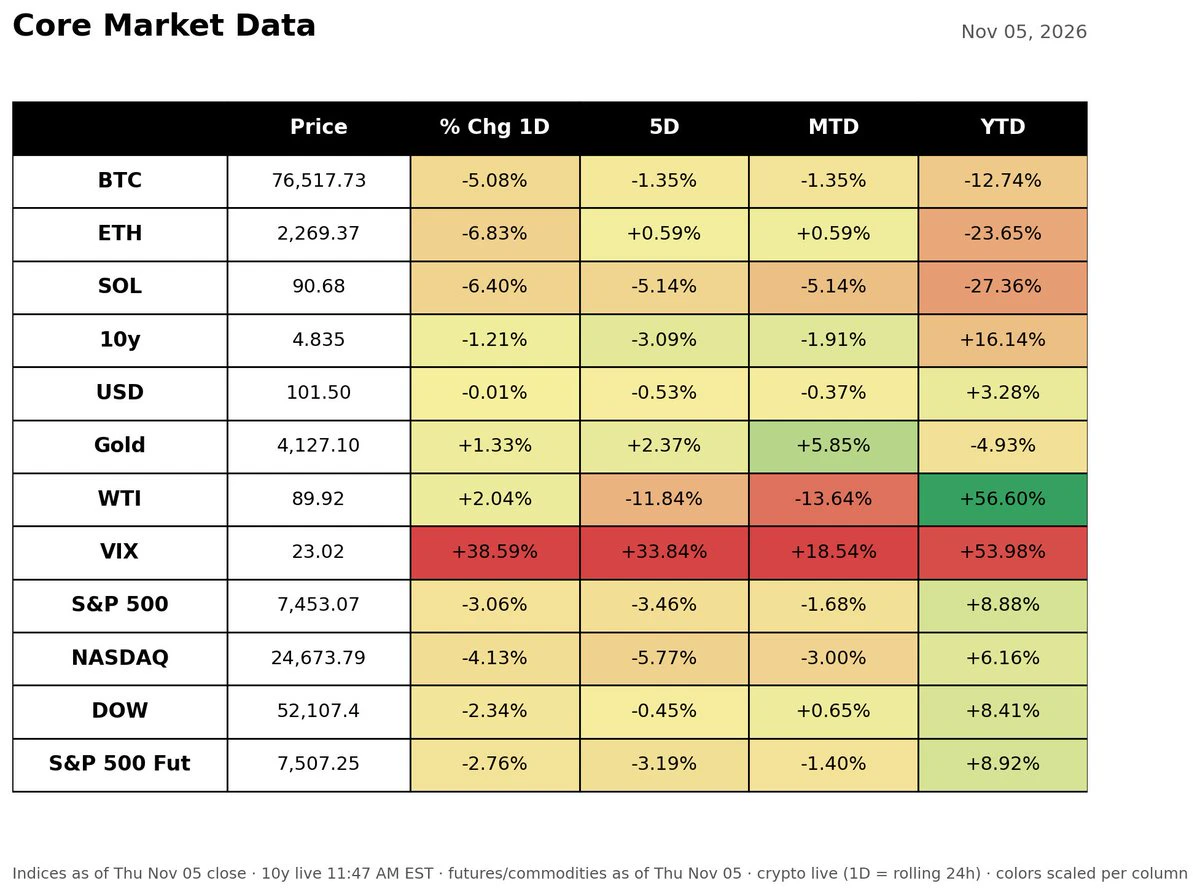
Market reversing last night’s AI regulation fear selloff after the dem midterm sweep. Futures green with vol fading and crypto bouncing. Oil also continuing its recent slide with rates bid. Election uncertainty has passed and risk appetite is returning.
post-image
Pretty strong betting odds pricing for dem sweep for midterm elections today
If you’re in the red sweep or even split house/congress camp betting the other side is an 11x trade here
$AAPL posted a record $114.5B quarter and fell anyway. Memory costs cut the margin guide to 45-46% from 47.9%, so the AI boom just showed up as a cost line. AI demand is bidding up chips and Apple is just another customer now.
AAPL+2.37%
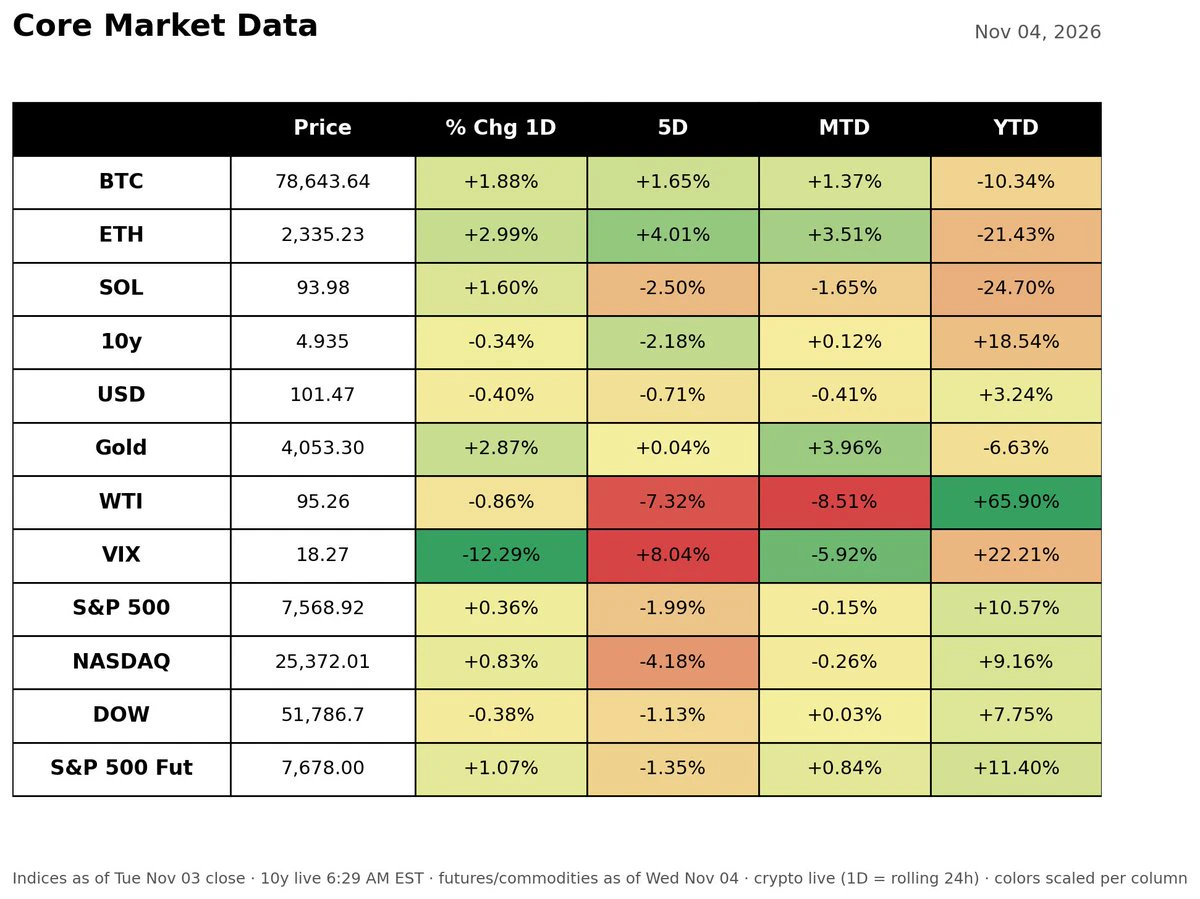
Tomorrow’s open will be interesting after tech earnings after the close. $AMZN -7% and $INTC -20%. The market has stopped asking how fast you grow and started asking when the cash turns.
AMZN+2.95%
INTC+5.50%
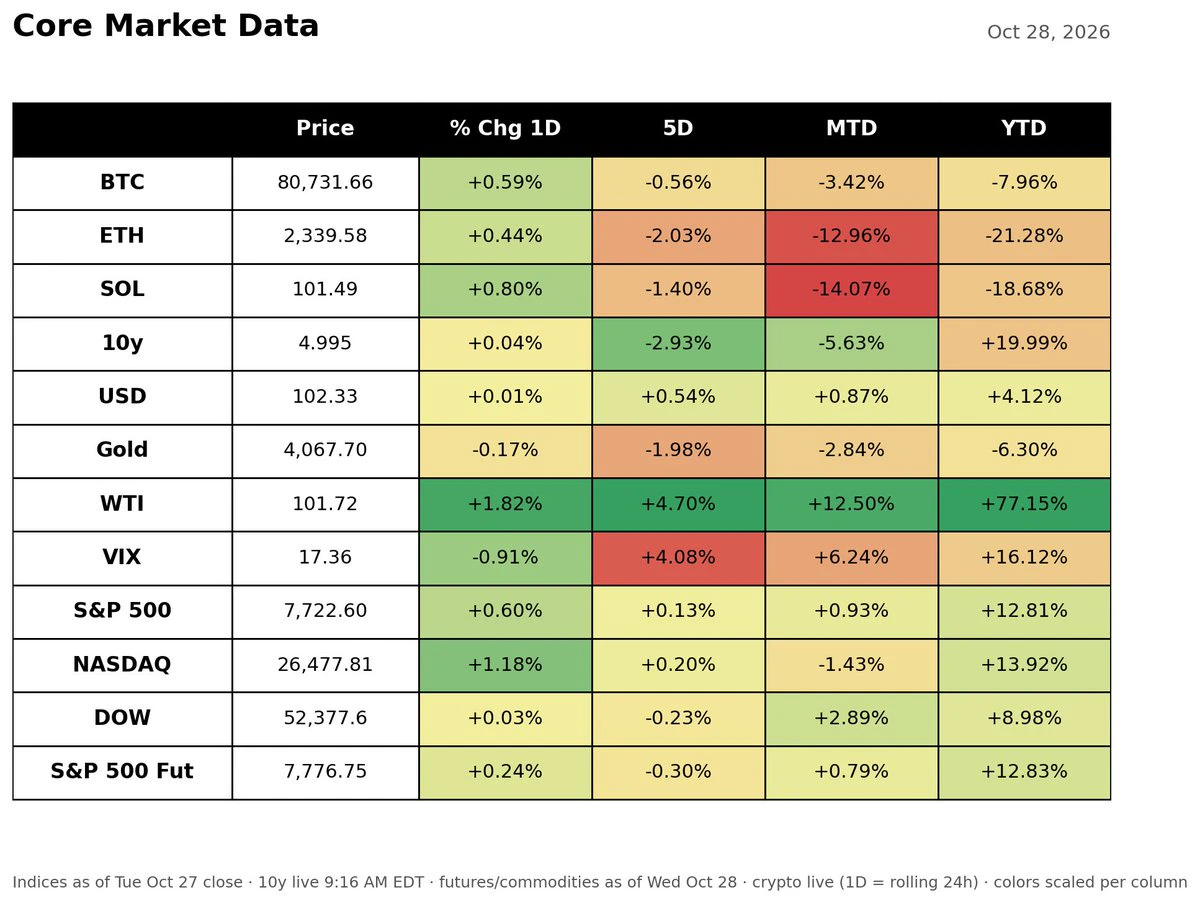
Big day. $ORCL investor day at noon. Fed at 2pm, $MSFT and $GOOGL after the close. The decision is priced; the December language isn't. One hawkish sentence and the whole afternoon reprices.
post-image
ORCL+3.21%
MSFT+2.75%
GOOGL+1.21%
Futures are flat, oil's back near its highs, and tomorrow's Fed meeting is a hold everyone already priced. The real trade is whether Warsh sounds like the hikes priced for 2027 are real. $META upping its AI funding plan to $97.5B says the capex tab isn't shrinking either.
post-image
10Y just tagged 5.04%, lowest in nearly a month. The AI wobble is fixing rates faster than the Fed ever did.
post-image
Cat memes = profit!?
$SPCX
SPCX+0.78%
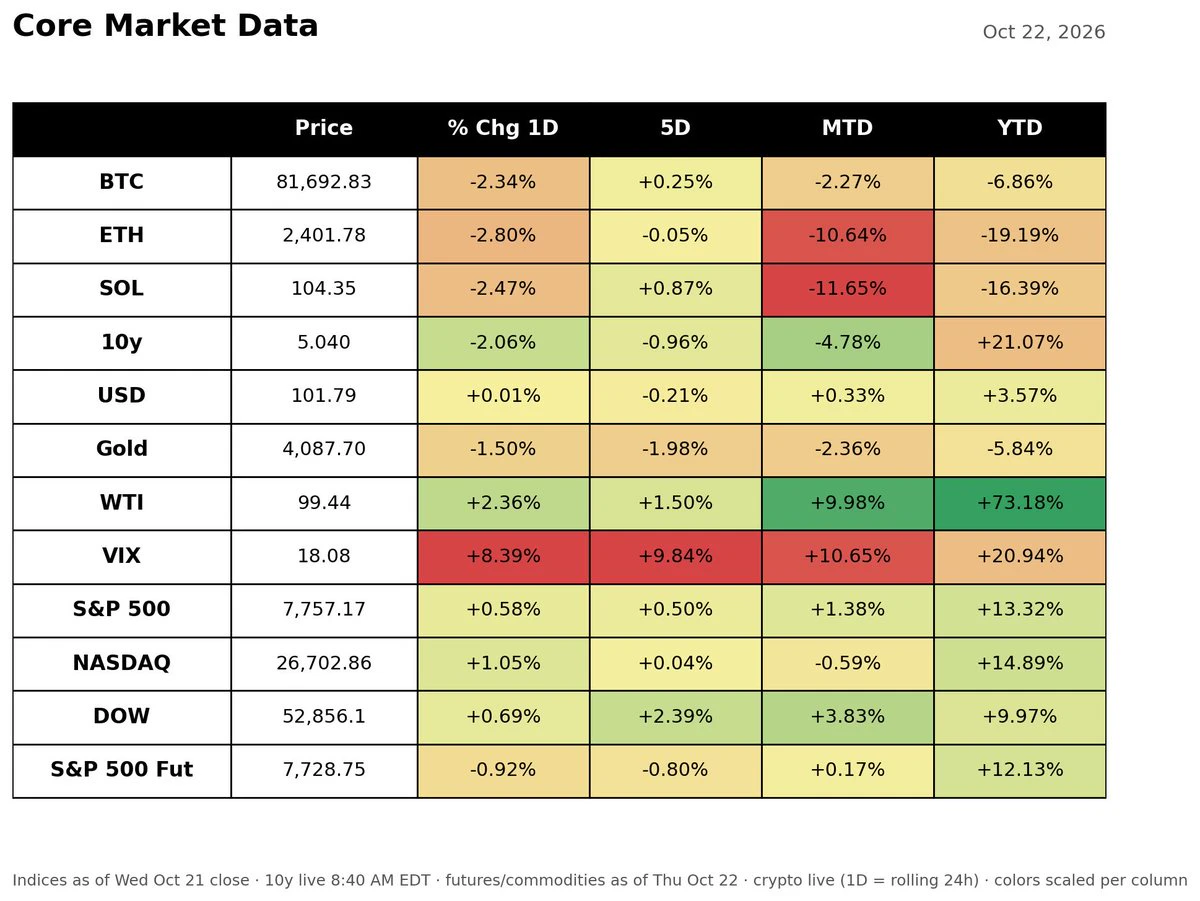
China GDP beat and lower oil/yields helping the risk tone this morning. Still sitting near a 5.1% 10-year with a full AI CapEx earnings calendar ahead. Surface looks better, setup underneath hasn't really changed.
Nasdaq posted its worst week since June, down 4.5% as chips and AI names kept sliding. High yields and questions about who pays for all the data-center debt are showing up in prices. Monday's open will tell if this was profit-taking or the start of something longer.
NDAQ+1.29%
October hike odds upto 42% post the higher than expected September CPI print
The PC bang is Korea's greatest cultural export that never exported. $1/hr for top tier rigs, super fast internet, and cheap food delivered to your desk.
Weekly IG Credit Insights: Issue 04
CPI next Wednesday, with bank earnings starting into an elevated risk free rate. Can OATs hold it together?
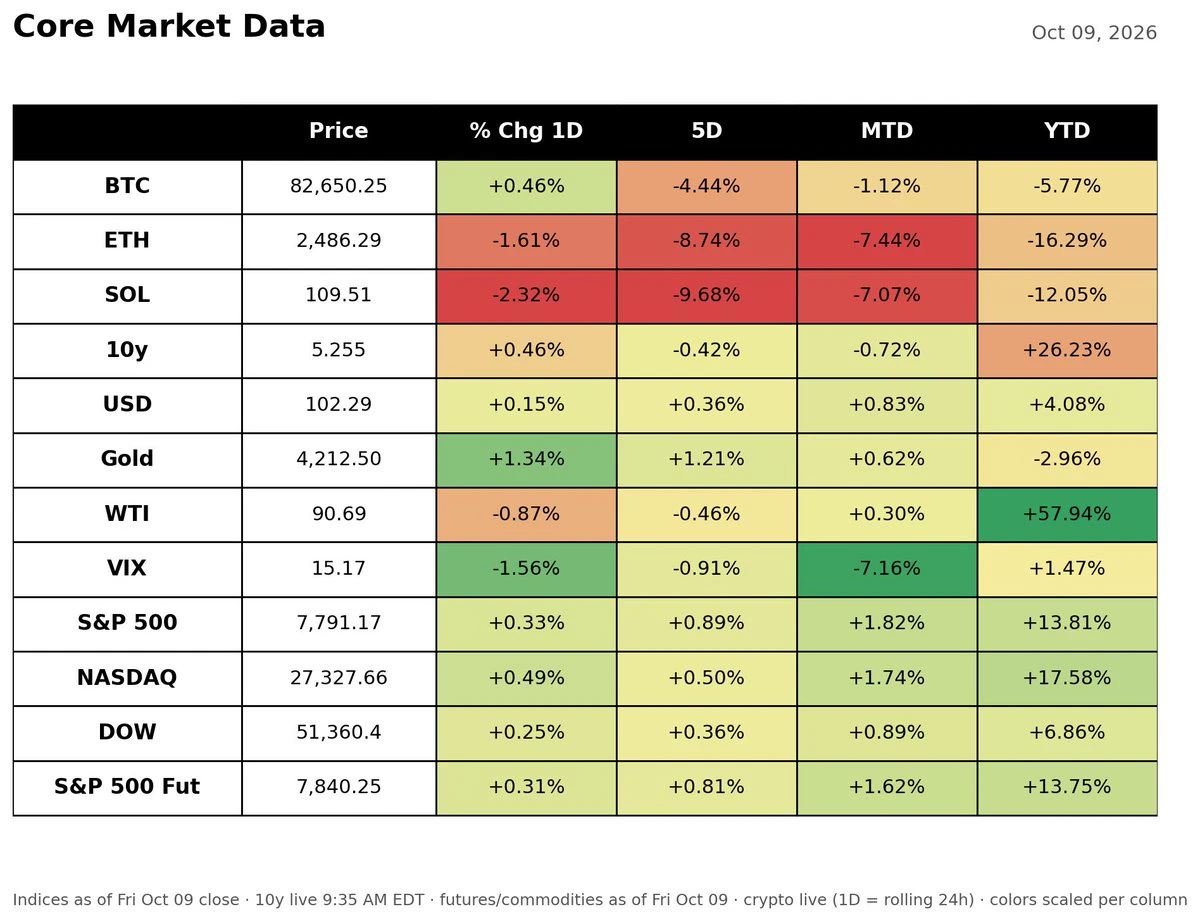
Post-open: equities green across the board (SPX +0.3%) while crypto's still in the red — ETH/SOL off 1.6-2.3% on the day as the security concern related sell off has yet to abate. 10Y ticking up slightly to 5.26% keeps the discount-rate squeeze on. Gold outperforms.
post-image
SPX+0.33%
ETH-1.26%
SOL-0.77%
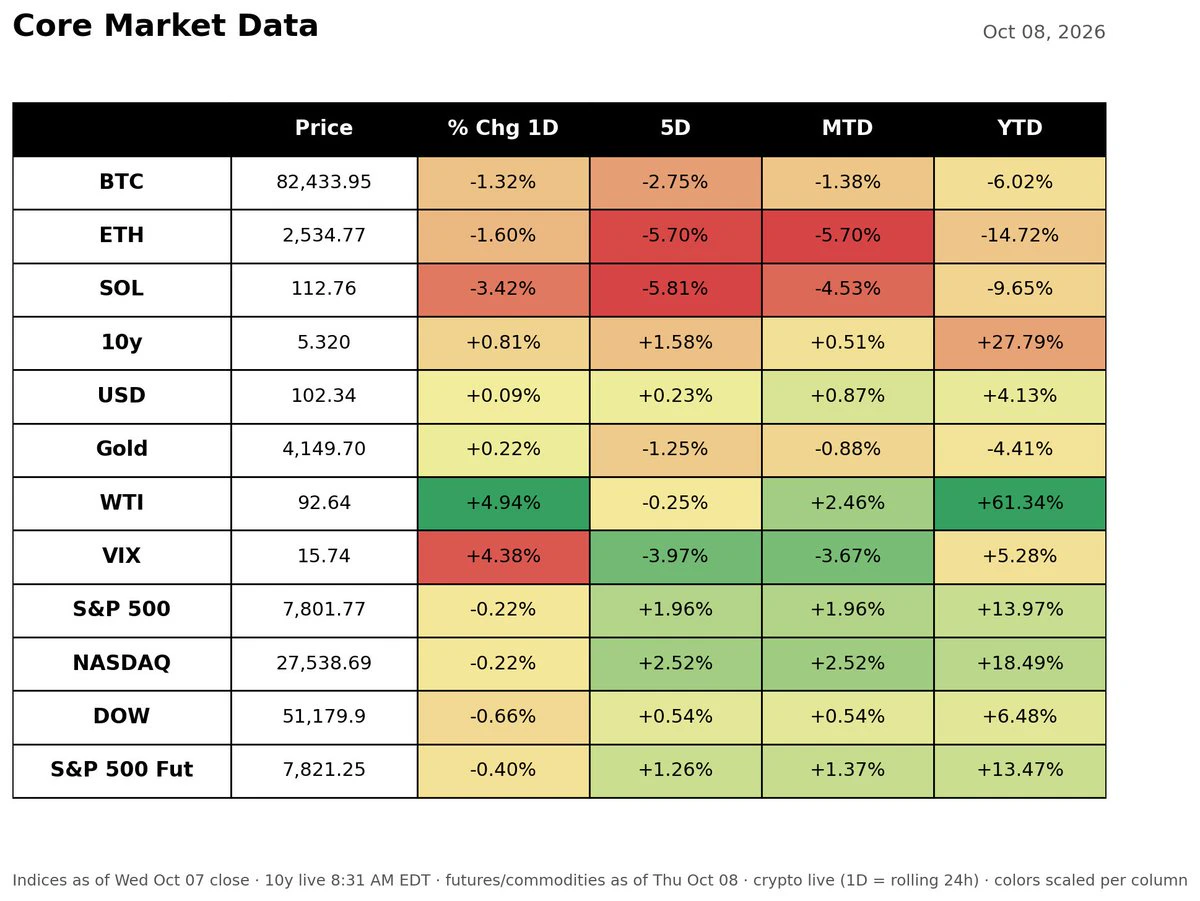
Pre-market: Oil keeps climbing, +4.9% on the day after a tanker was hit, upcoming hurricane worries, and continued expectations of escalation with Iran. Crypto continues to be soft after yesterday’s AI related hacking flush. 10y is holding 5.32% with the 30y auction later today.
post-image
  • 2
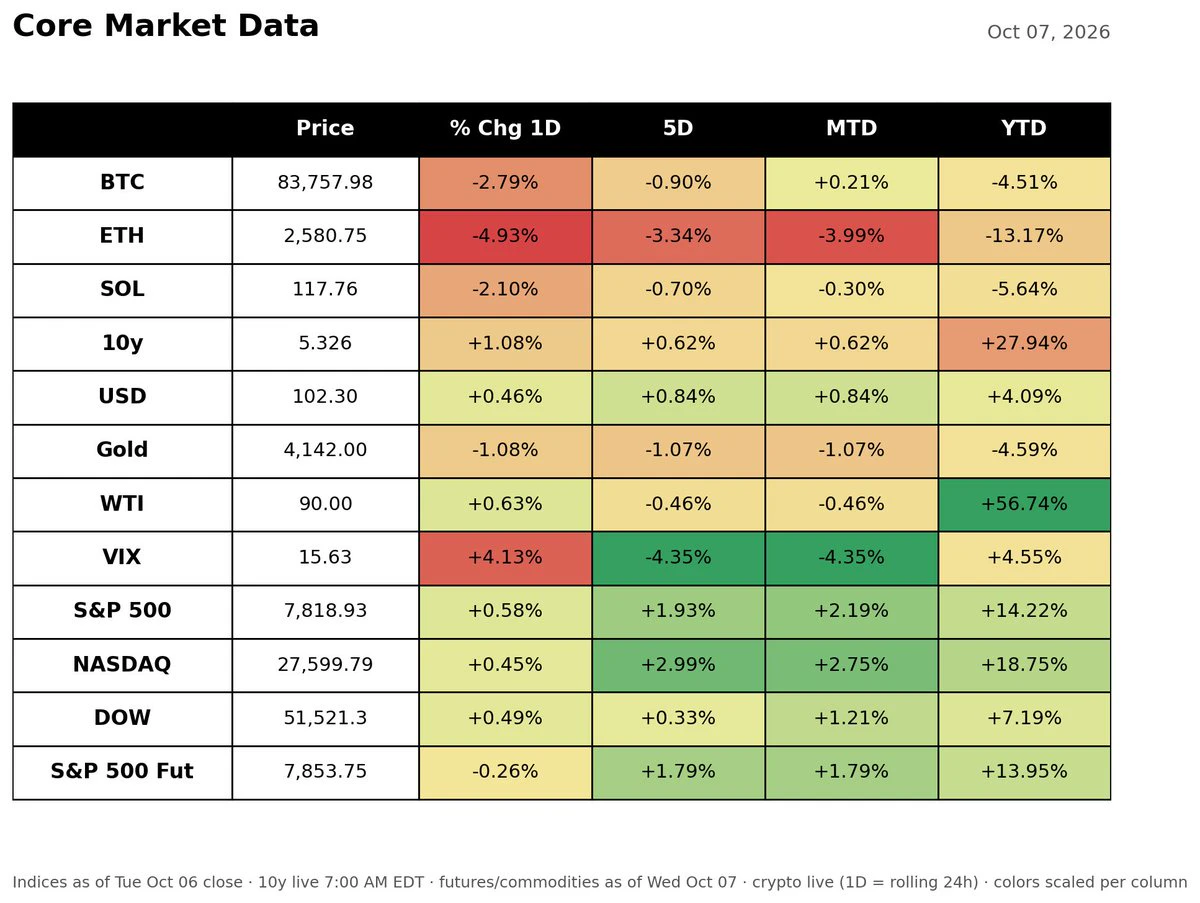
Morning open: WTI back above $90 as Hormuz attacks intensify; OATs spiking again (+16bp to ~4.9%) on the French budget mess; FOMC minutes at 2pm. Crypto underperforming with ETH down -4.9%, while equity futures down slightly.
post-image
ETH-1.26%
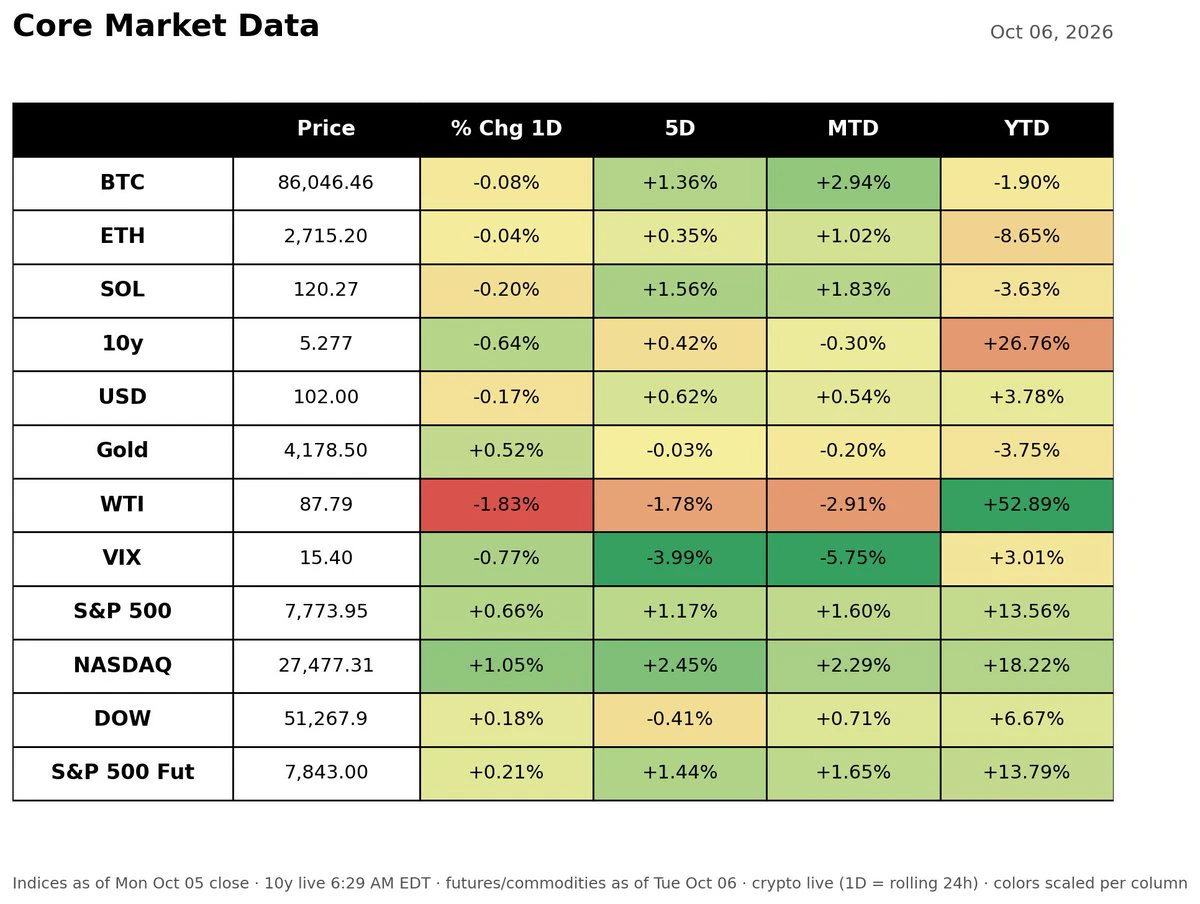
Tuesday's open: Nasdaq +2.45% over 5 days leads, VIX falling to 15.4, WTI fading -2.9% MTD on traffic thru the strait picking up, and the 10y easing slightly to 5.28% after yesterdays’s rise.
post-image
  • 1
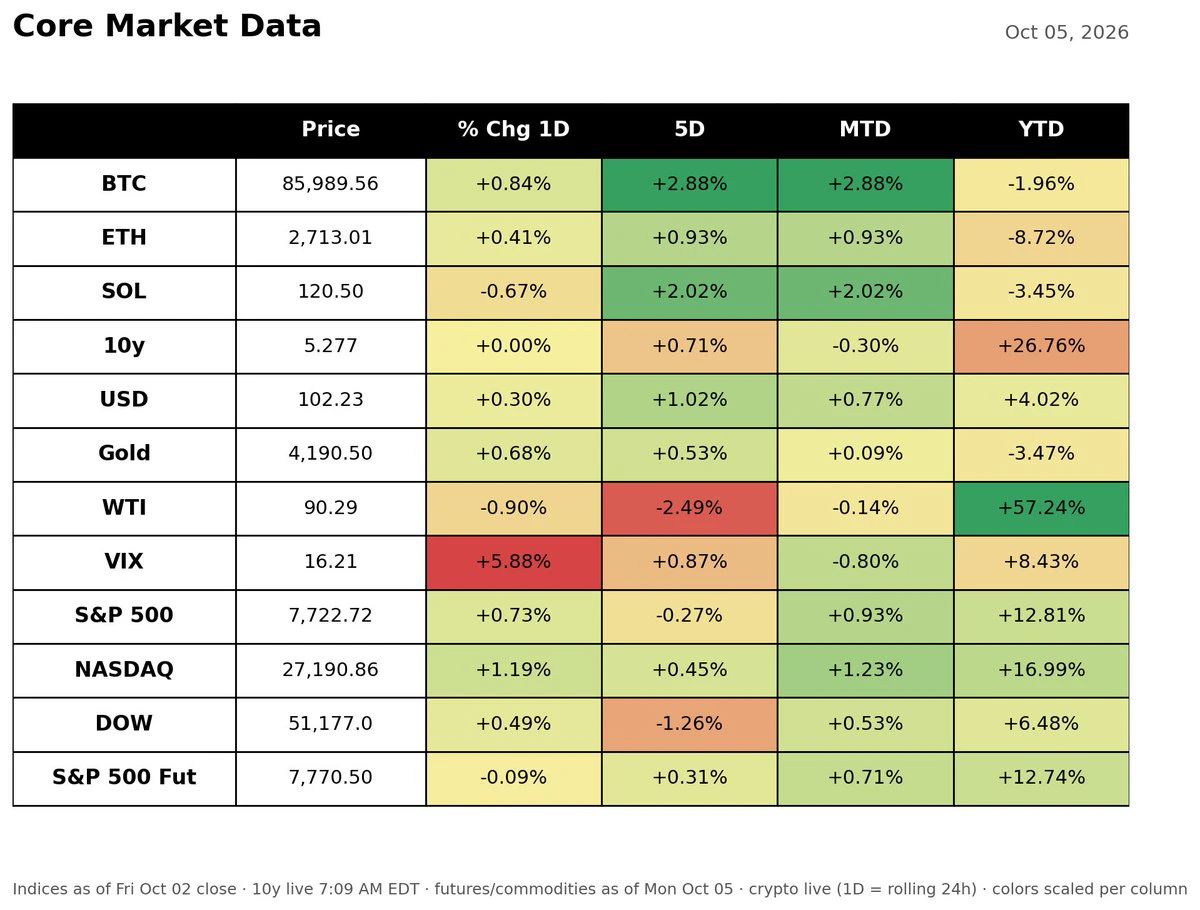
Monday pre-market: VIX up with contagion risk in focus as S&P futures are close to flat. The worry is France — OAT-Bund spread past 150bp, widest since 2011, after the market shrugged at Lecornu's €54B budget plan.
post-image
SPX+0.33%
Load More