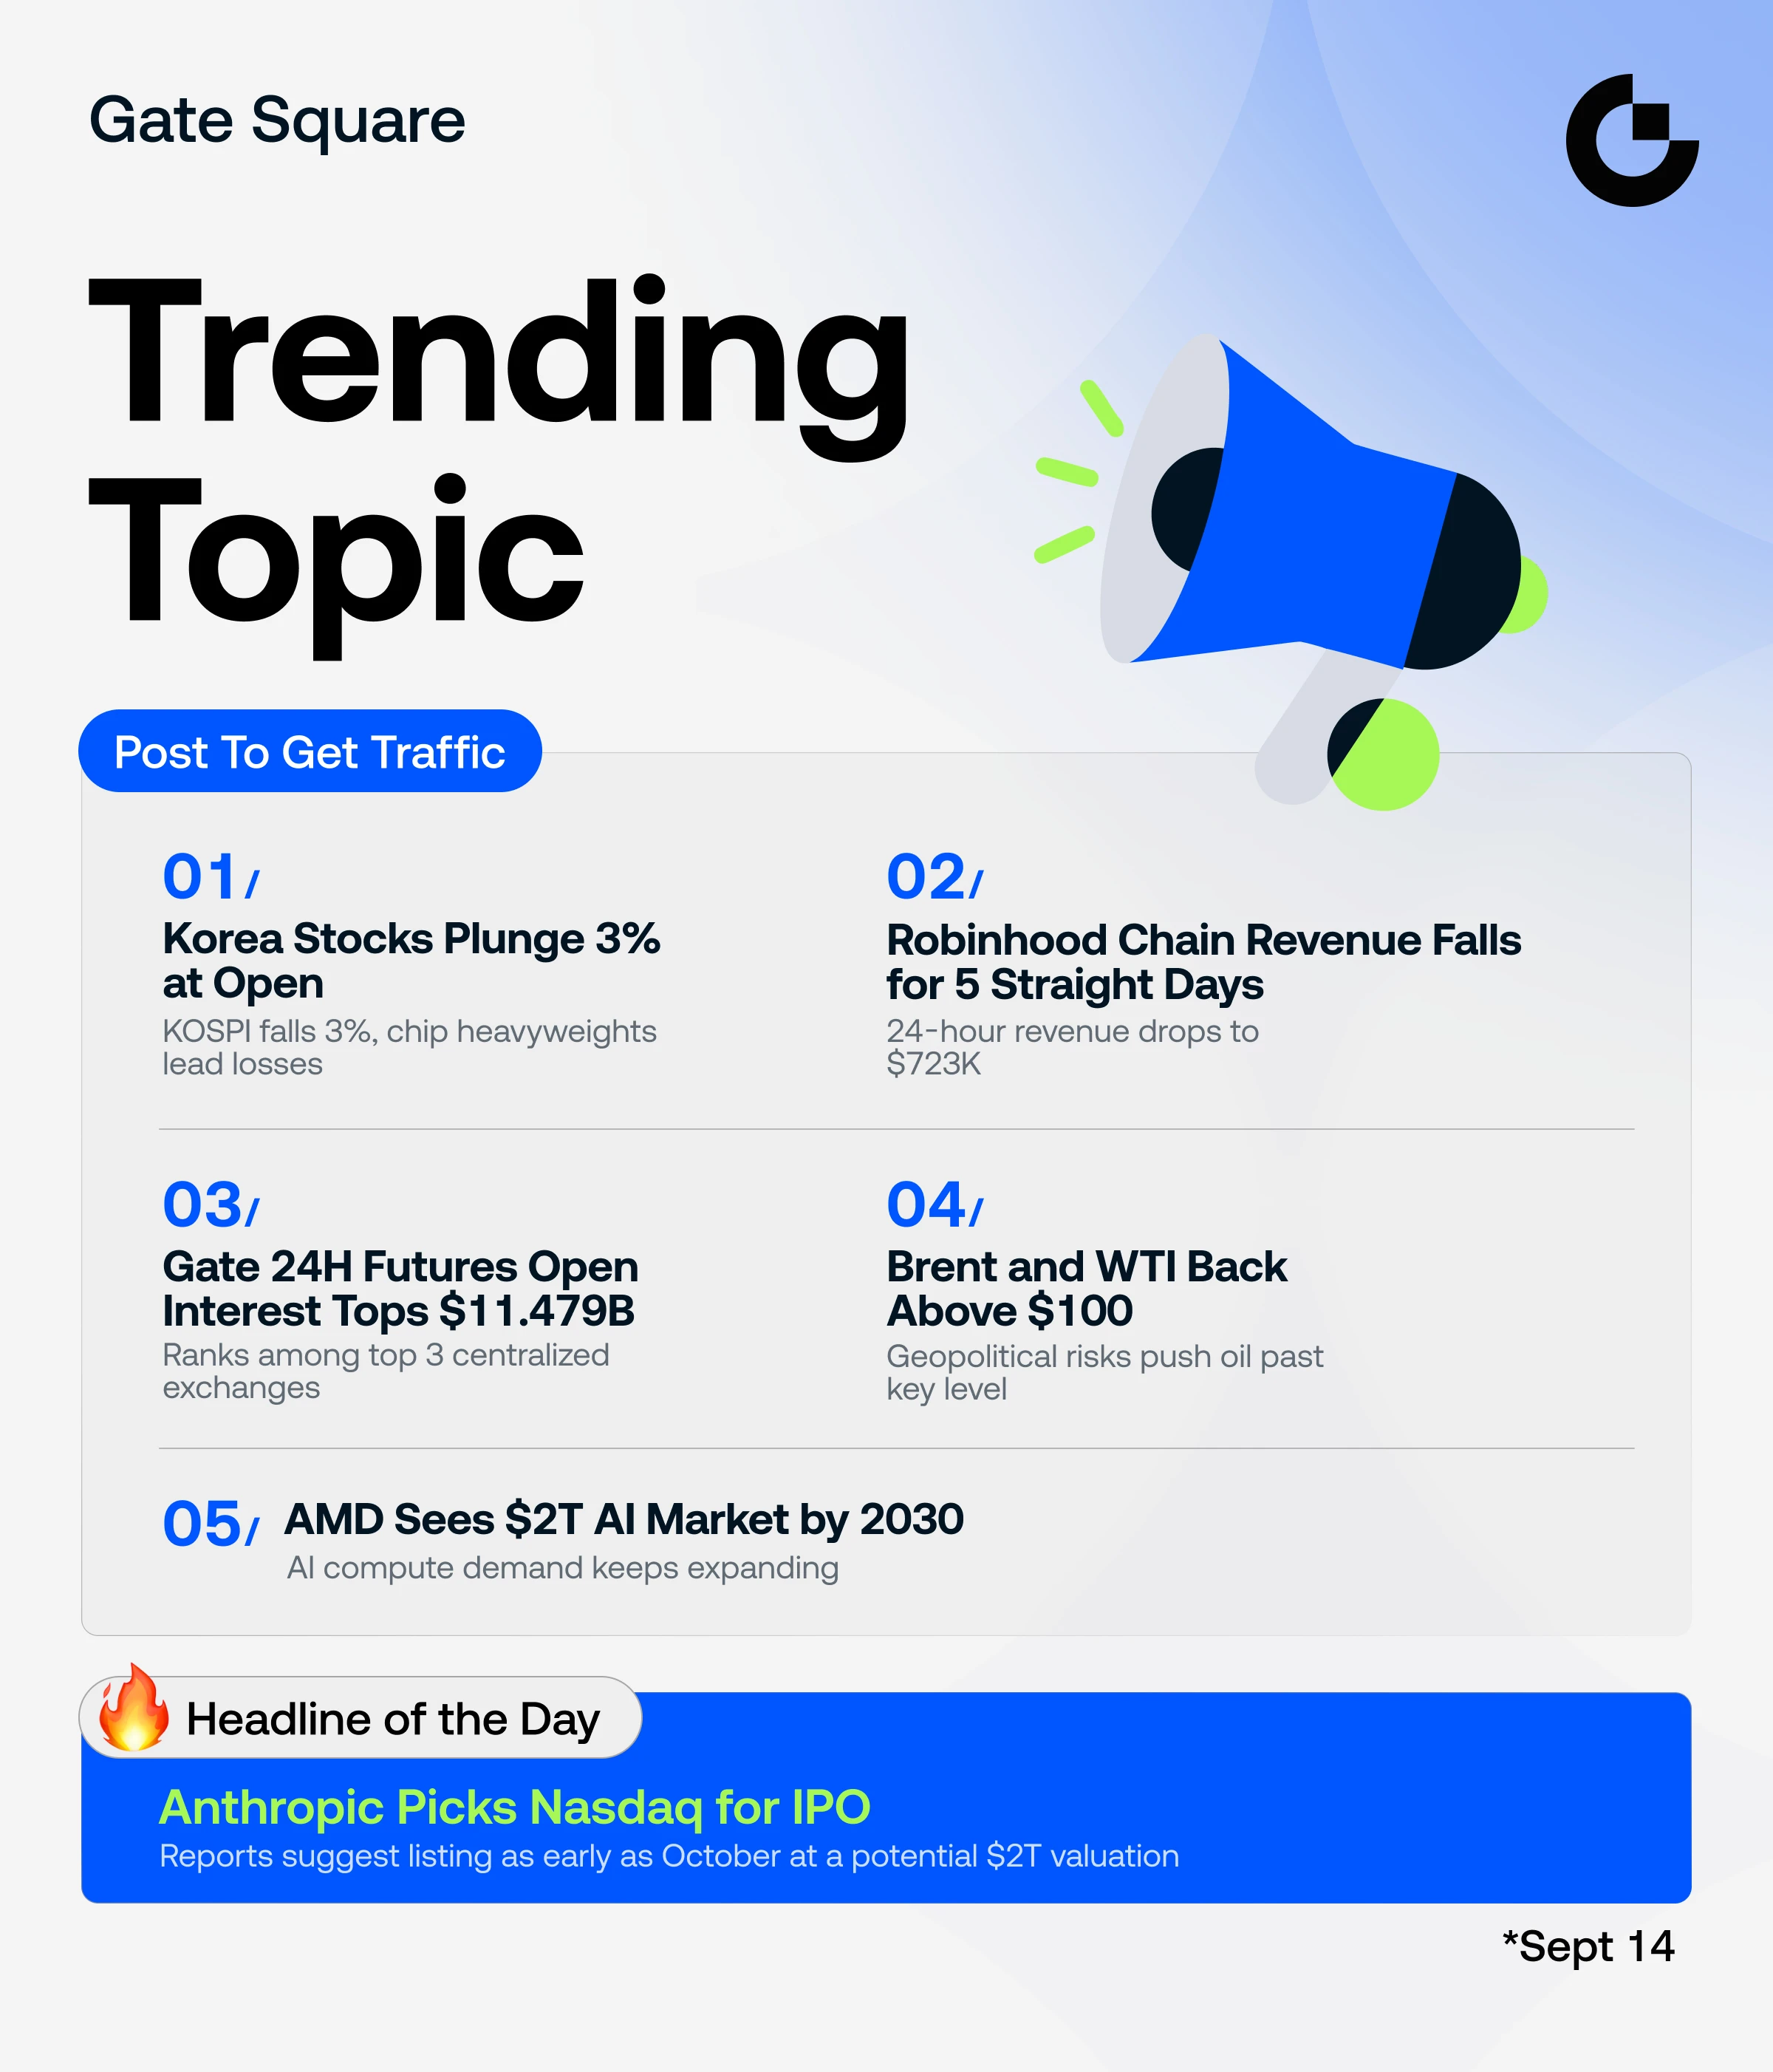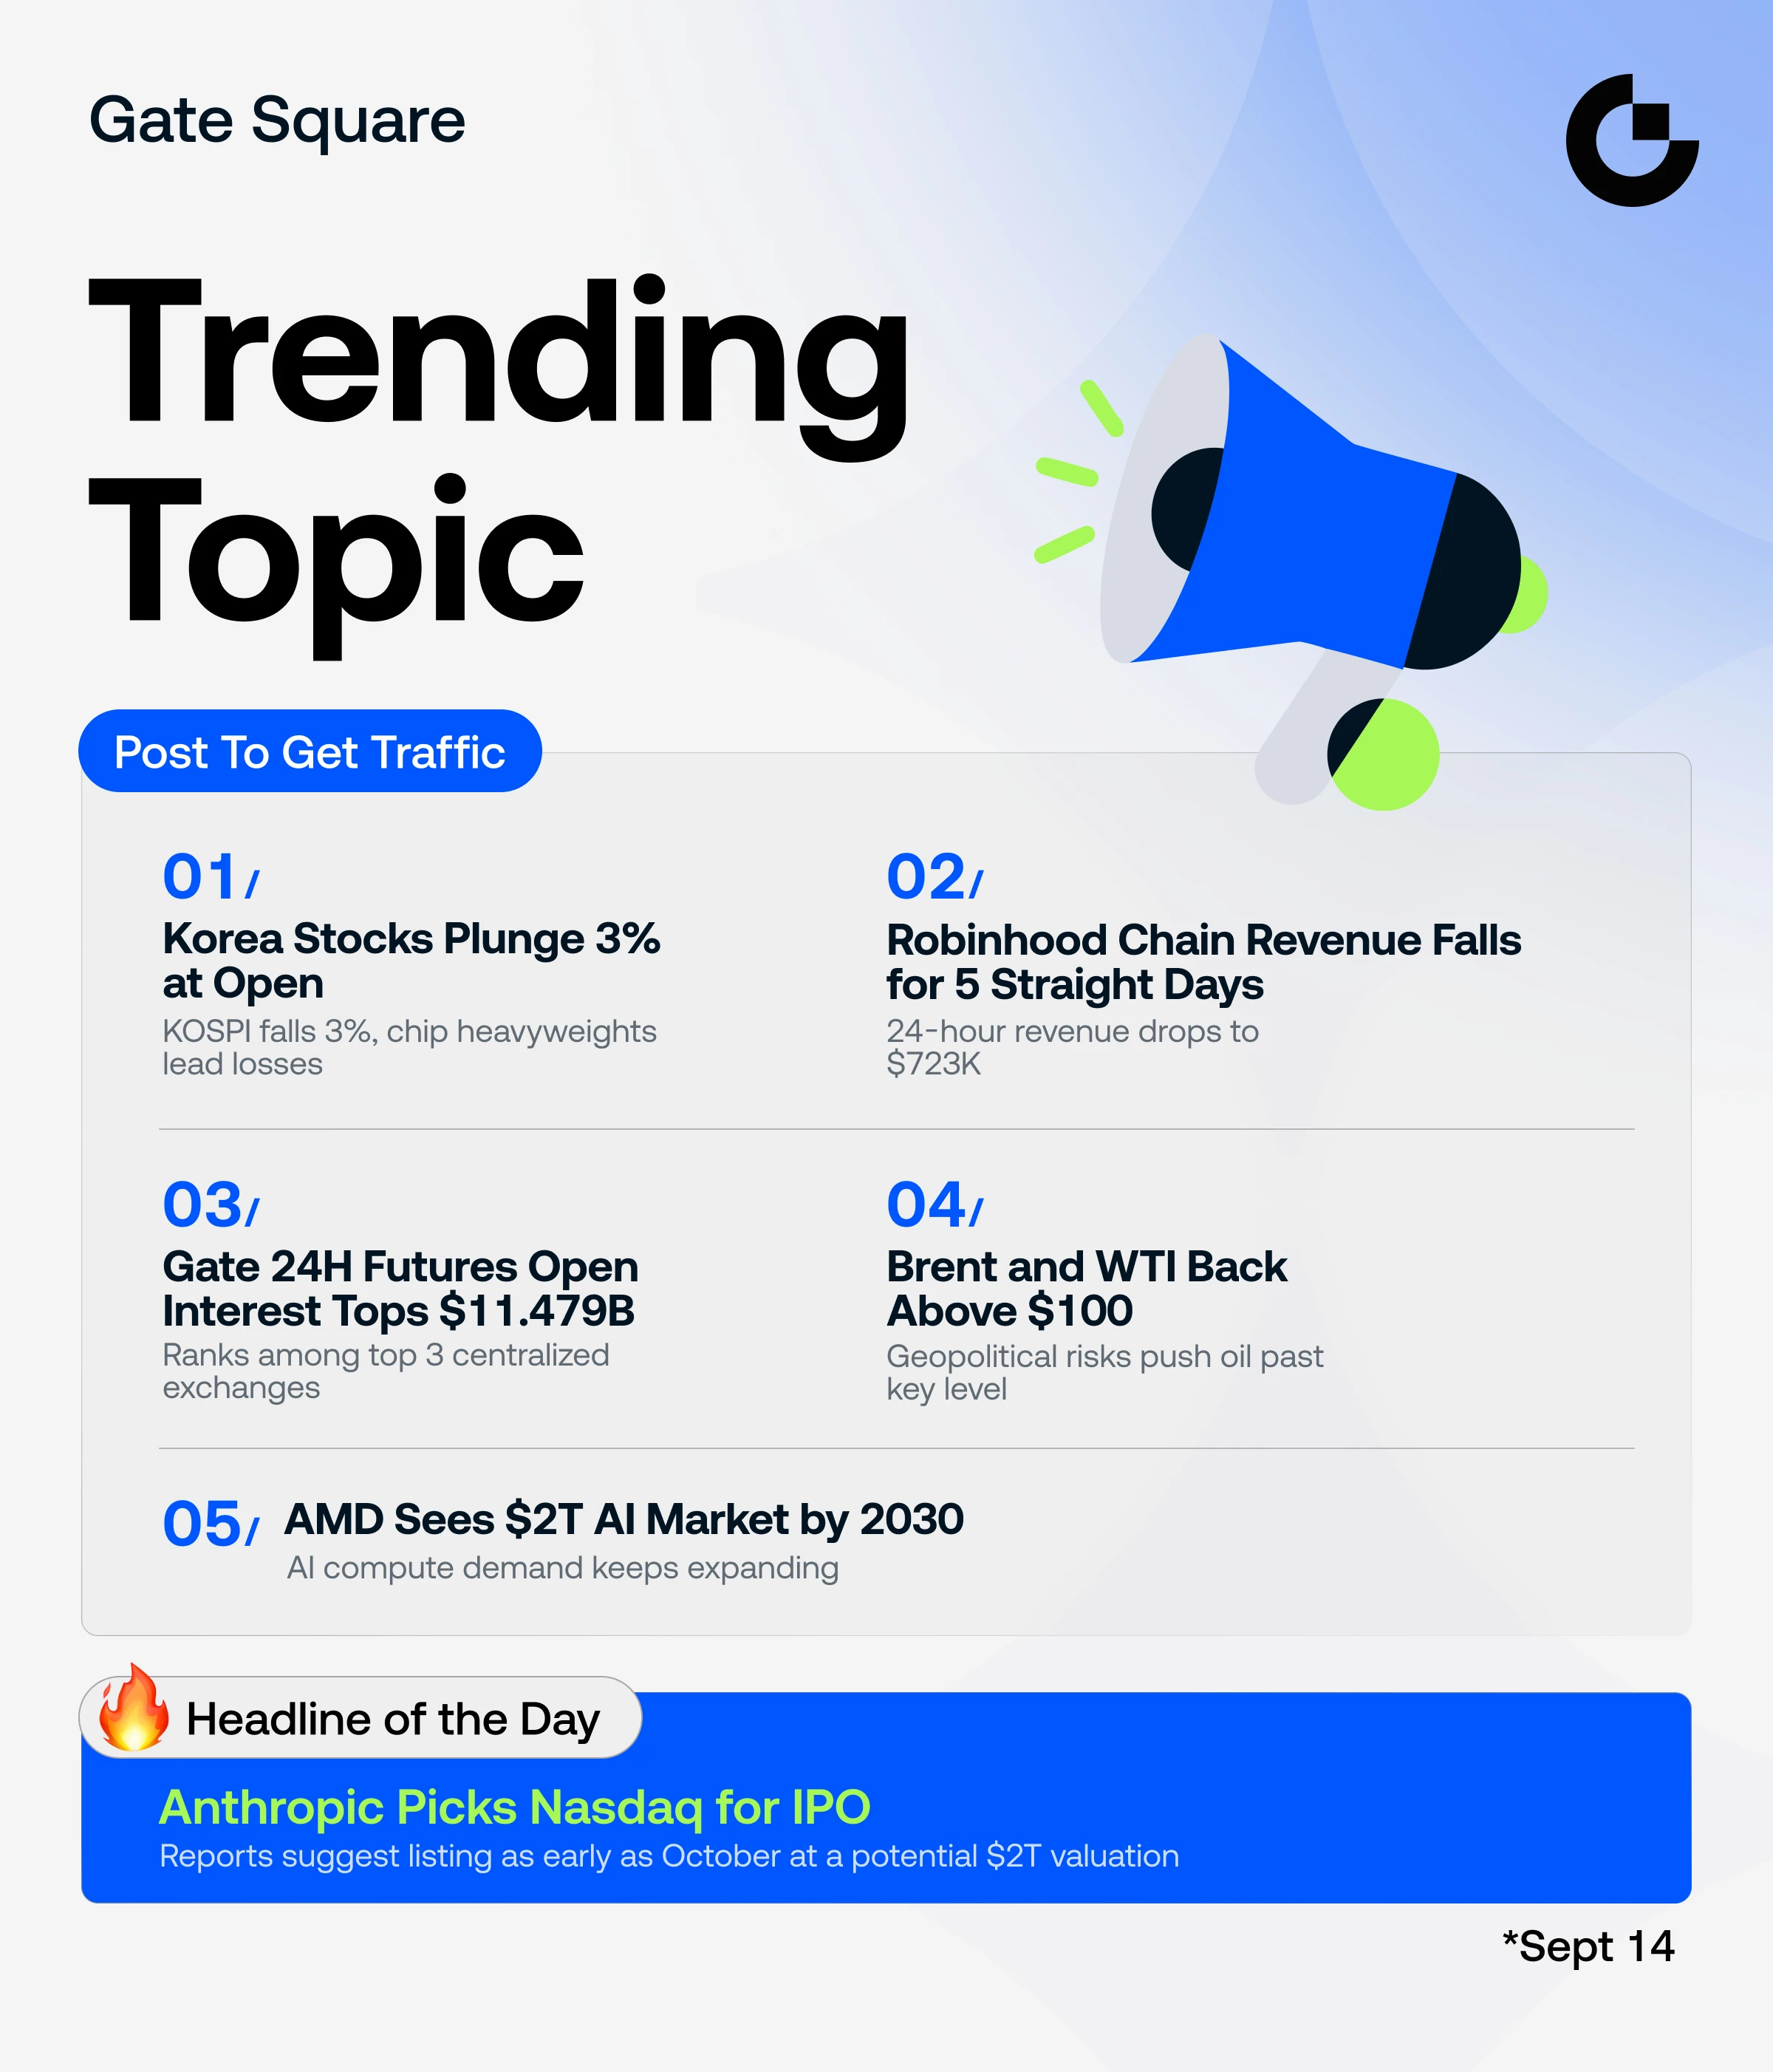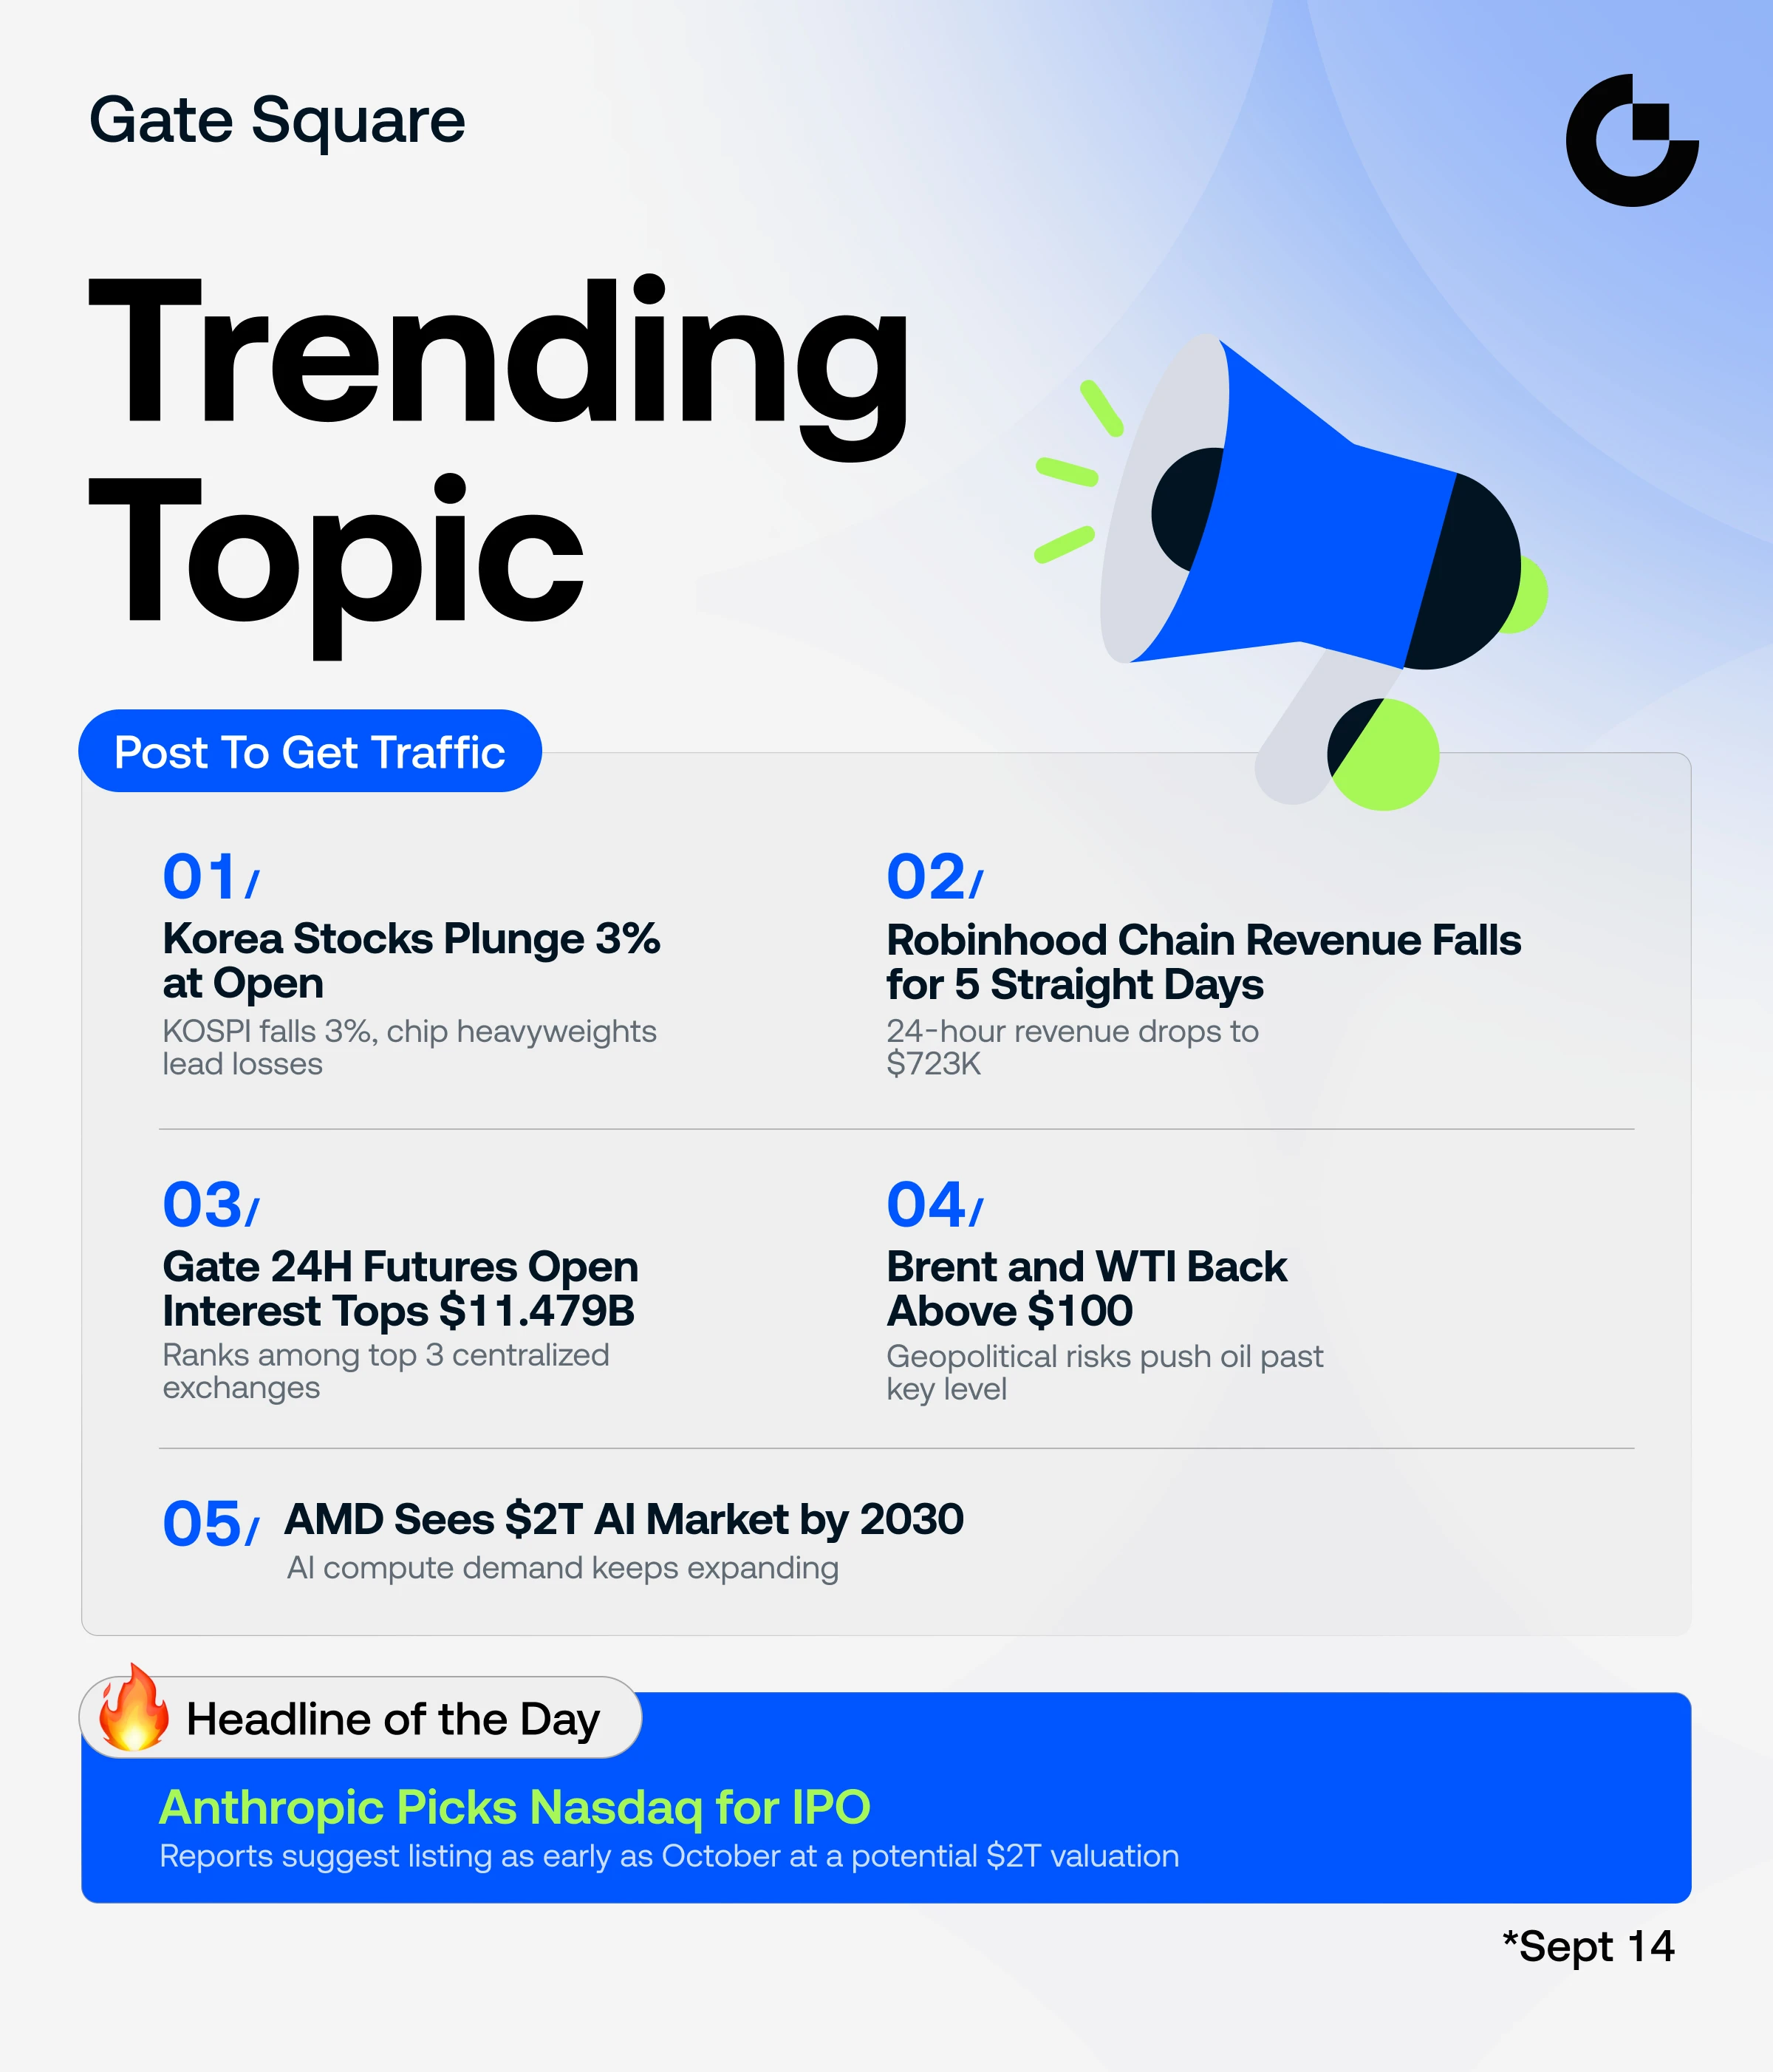

#Korea Stocks Plunge 3.14% at Open
The Morning Korea Woke Up to a Different Market
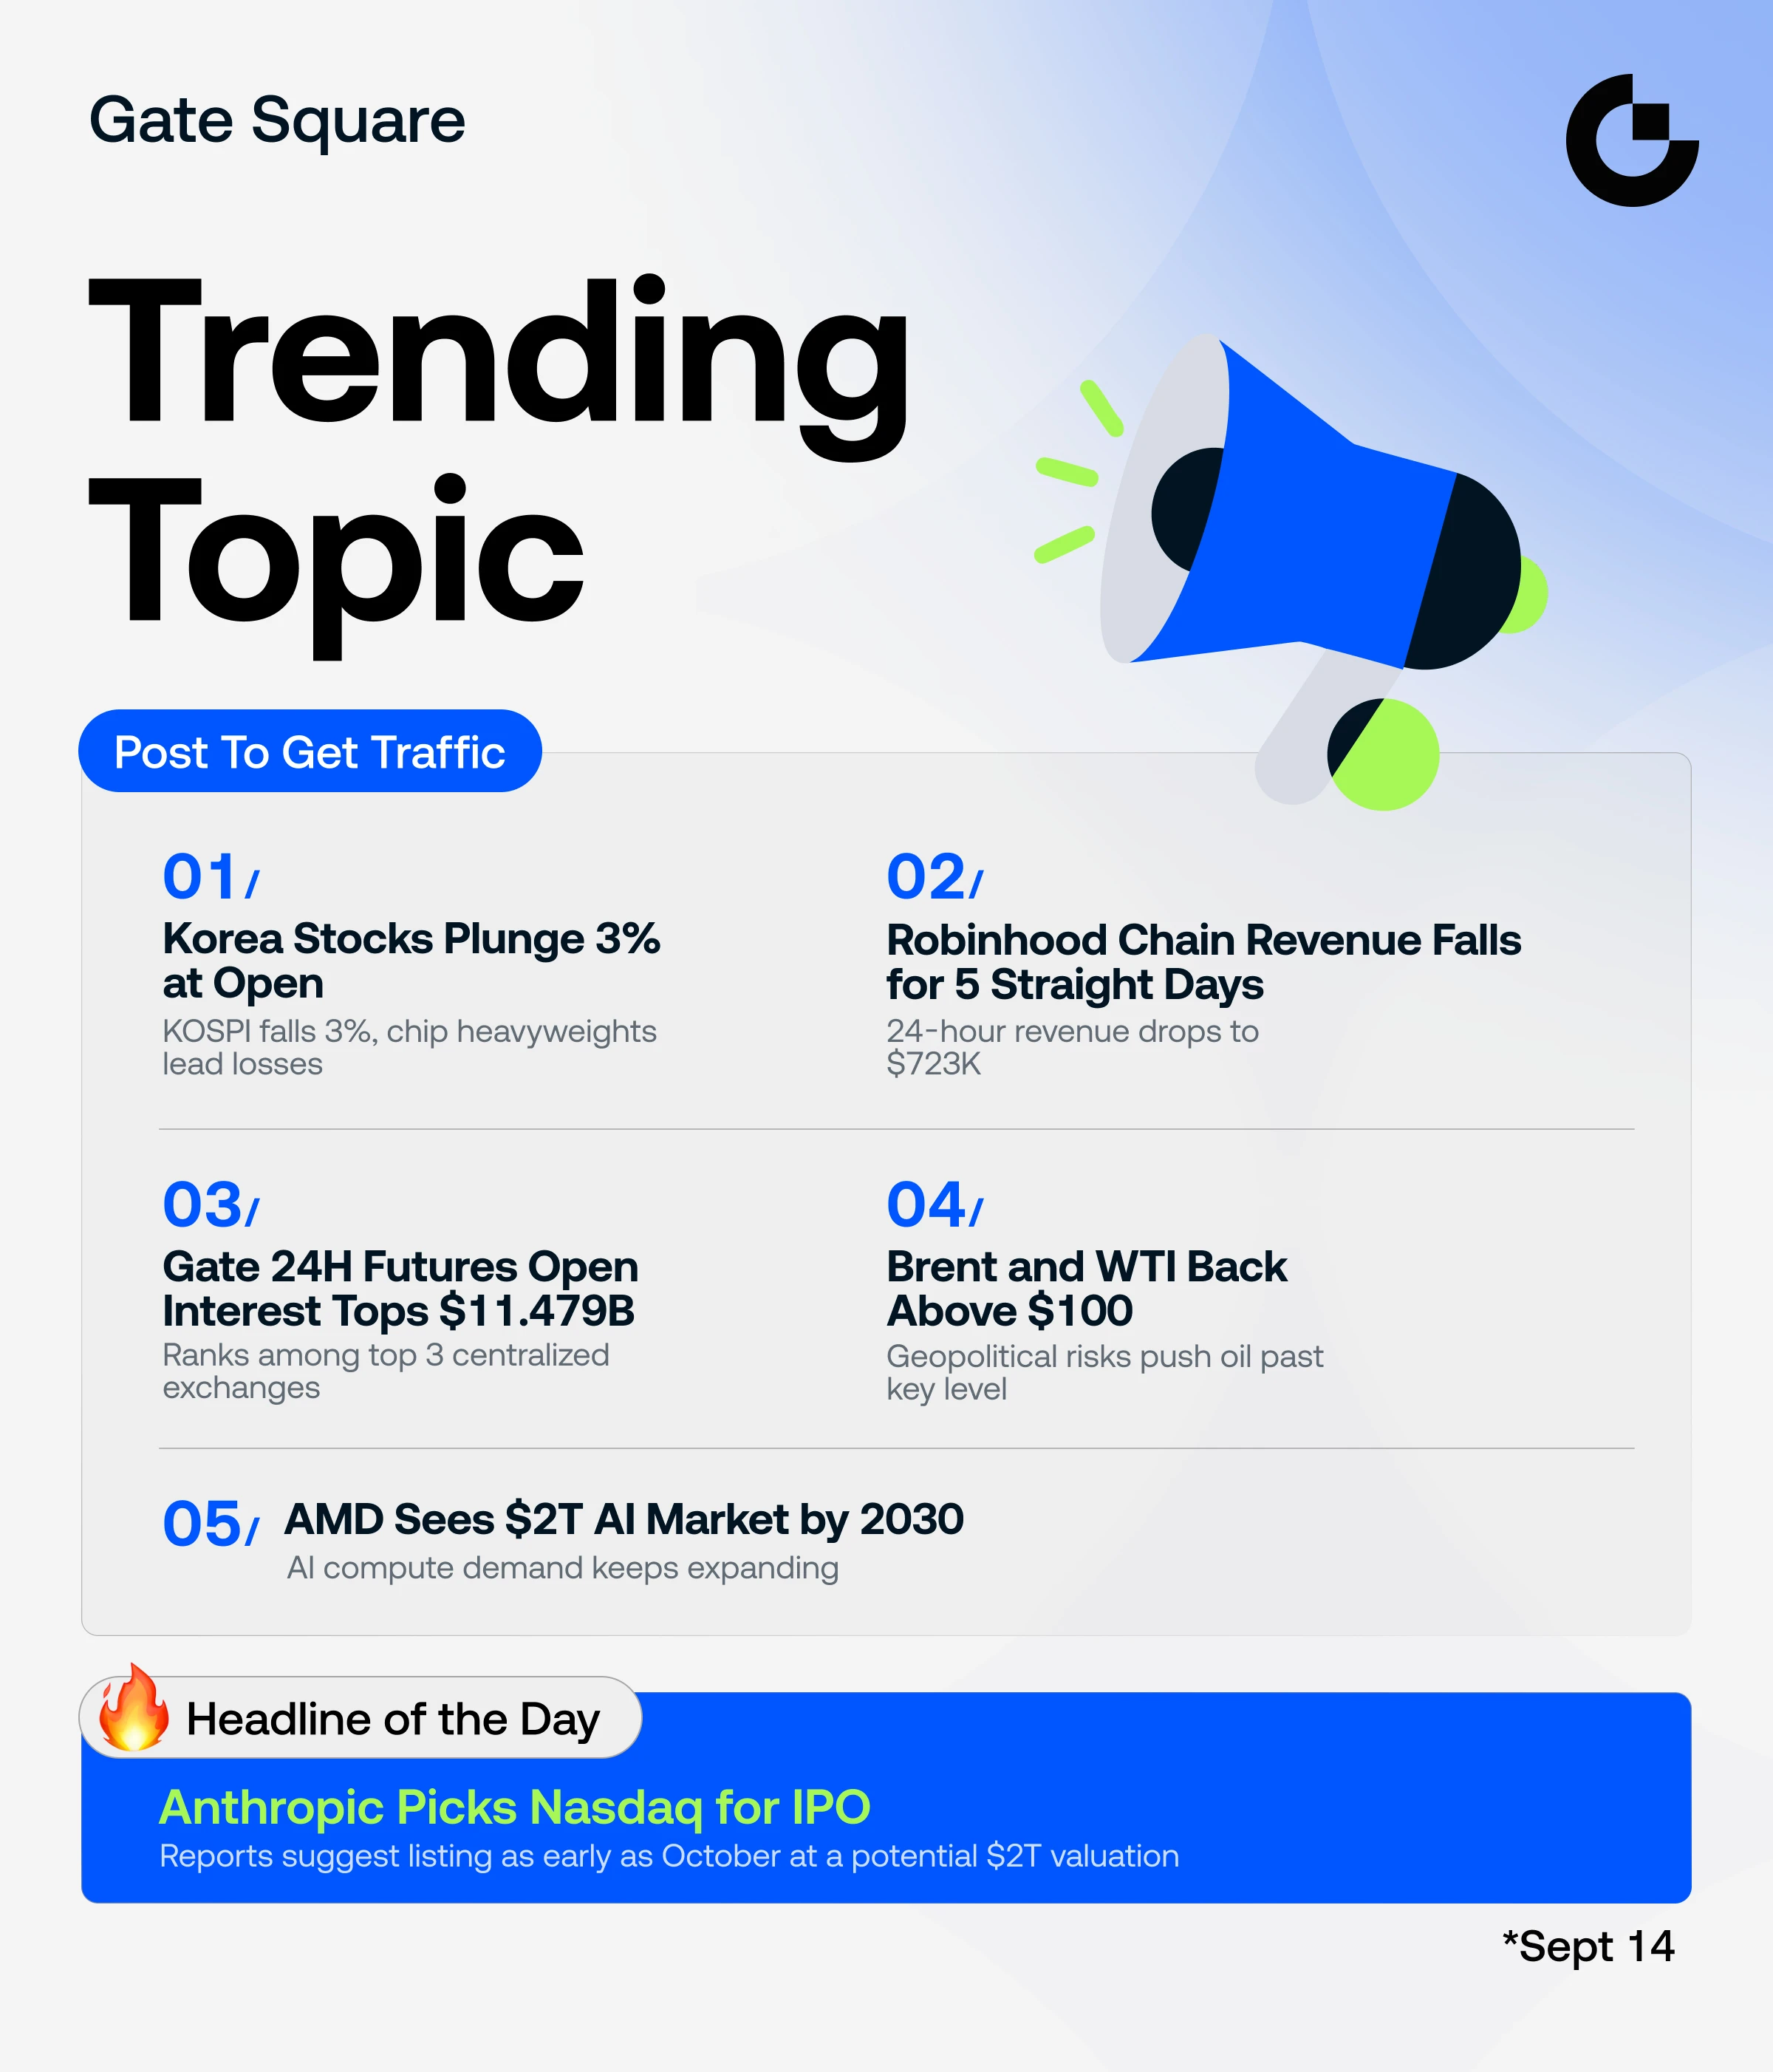
There is a particular kind of quiet that falls over a trading floor when the opening bell rings and the screens are already red. It is not panic. It is something closer to recognition, the collective understanding that the weekend brought news that cannot be ignored. That was the atmosphere in Seoul on Monday, September 14, when the KOSPI opened 3.14 percent lower, falling below the 6,700 mark for the first time in weeks. By the close, the index had settled at 6,684.37, a decline of 3.26 percent, its third consecutive losing session.
The numbers alone do not explain the weight of the moment. What matters is what they represent: the convergence of three separate pressures that had been building for days, each of which would have been manageable on its own, but which together proved too much for a market that had been trading near record highs just weeks earlier.
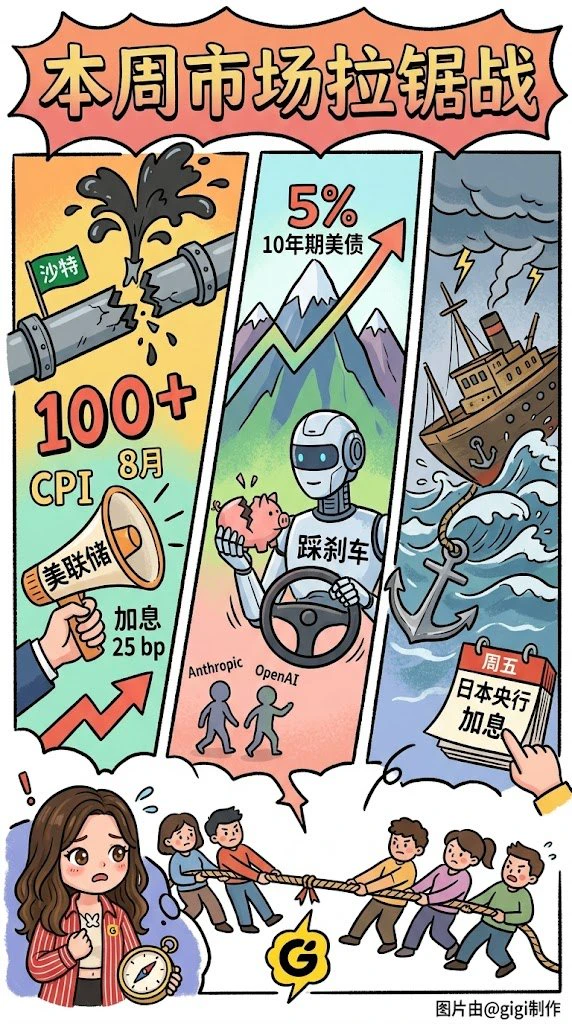
Start with the most immediate catalyst, which arrived from the Middle East over the weekend. Hopes had been rising that Gulf diplomats and Iranian officials would meet on Monday to discuss plans to reopen the Strait of Hormuz, the critical waterway that carries roughly a fifth of global oil supply. That meeting was indefinitely suspended, according to Oman's foreign minister, removing the most promising near-term path to reducing the geopolitical risk premium embedded in energy prices. Crude oil responded immediately. Brent crude climbed above 108 dollars a barrel in Asian trading, while West Texas Intermediate pushed past 103 dollars. For South Korea, which imports virtually all of its crude, the implications are direct and painful. Higher energy costs feed into transportation, manufacturing, and utility expenses, compressing margins across the industrial economy and weighing on a trade balance that is already sensitive to external shocks.
The second pressure came from the technology sector, and it is here that the story becomes more nuanced. Over the weekend, the leaders of three of the most prominent artificial intelligence companies publicly called for a slower pace of development, citing safety concerns. Dario Amodei of Anthropic urged the industry to take a more deliberate approach to improving its most advanced models. Sam Altman of OpenAI said his company would not pursue a public listing this year, citing the same concerns. Elon Musk expressed support for these positions. For a market like South Korea's, which has become deeply intertwined with the AI supply chain, these statements landed with unusual force. Samsung Electronics and SK hynix, the two companies that dominate the memory chip market that AI accelerators depend on, fell 3.66 percent and 6.07 percent respectively. SK Square, the holding company for SK hynix, dropped 7.25 percent.
The logic connecting these two developments is not as straightforward as it might appear. The AI safety debate is not a demand shock. No customer has cancelled an order. No data center has been shut down. What the statements represent is uncertainty about the pace of future investment, and in a market that has priced in years of aggressive capital expenditure, uncertainty is its own kind of pressure. As one analyst at Shinhan Investment & Securities put it, the semiconductor-centered AI value chain is declining due to a combination of macroeconomic pressure and AI concerns. The foreign investors who had driven the KOSPI to its highs earlier this year are now selling both spot stocks and futures, and they are doing so in size.
That selling is the third pressure, and it is the one that ultimately determines the day's outcome. Foreign investors net sold approximately 1.33 trillion won in the main stock market by the morning session, with institutions adding another 413 billion won in net sales. Individual investors, as they have throughout this selloff, absorbed the supply, net buying 1.54 trillion won. By the close, the scale of foreign selling had reached 3.5 trillion won. This is not a one-day event. Foreigners have been net sellers for four consecutive sessions, and the pattern reflects a broader reassessment of risk appetite as the Federal Reserve prepares for what is expected to be a rate increase at its meeting on September 16. Market-implied odds of a quarter-point hike now sit near 86 percent, and the combination of higher energy costs, rising Treasury yields, and uncertainty about the AI investment cycle has made Korean equities, which had been among the best performers in Asia this year, a natural target for profit-taking.
The won weakened alongside the index, trading at 1,346.8 against the dollar, down 2.7 won from the previous session. A weaker currency compounds the pressure on foreign investors, who face the prospect of currency losses on top of equity declines. It also raises the cost of imported energy, reinforcing the inflationary impulse that the central bank is already watching.
What should a careful observer take from this moment? Three things, I would suggest. First, the KOSPI's decline is not a verdict on the Korean economy. It is a repricing of risk in a market that had risen quickly and was vulnerable to exactly this combination of external shocks. The underlying fundamentals, a competitive export sector, a strong semiconductor franchise, and a central bank with room to maneuver, remain intact. Second, the AI safety debate is now a market factor. Whether the calls for a slower pace of development translate into actual changes in capital expenditure remains to be seen, but the market is treating them as a signal rather than noise. That is a meaningful shift. Third, the Fed's decision on Wednesday will set the tone for the weeks ahead. If Chair Kevin Warsh signals that the rate increase is a one-time adjustment rather than the beginning of a new tightening cycle, risk assets across Asia could find relief. If he leaves the door open to further hikes, the pressure will persist.
The deeper truth is that the Korean market is being asked to absorb a convergence of forces that originate far beyond its borders. A conflict in the Middle East that disrupts energy flows. A technology debate in Silicon Valley that reshapes expectations for the AI investment cycle. A monetary policy decision in Washington that determines the cost of capital for every economy connected to the dollar system. South Korea is not the author of any of these developments. It is a participant in all of them. And on Monday morning, the market priced that participation accordingly.
DYOR 🔎
#ShareWeekly $Exgate $Woori Financial Group $BH
The Morning Korea Woke Up to a Different Market
There is a particular kind of quiet that falls over a trading floor when the opening bell rings and the screens are already red. It is not panic. It is something closer to recognition, the collective understanding that the weekend brought news that cannot be ignored. That was the atmosphere in Seoul on Monday, September 14, when the KOSPI opened 3.14 percent lower, falling below the 6,700 mark for the first time in weeks. By the close, the index had settled at 6,684.37, a decline of 3.26 percent, its third consecutive losing session.
The numbers alone do not explain the weight of the moment. What matters is what they represent: the convergence of three separate pressures that had been building for days, each of which would have been manageable on its own, but which together proved too much for a market that had been trading near record highs just weeks earlier.
Start with the most immediate catalyst, which arrived from the Middle East over the weekend. Hopes had been rising that Gulf diplomats and Iranian officials would meet on Monday to discuss plans to reopen the Strait of Hormuz, the critical waterway that carries roughly a fifth of global oil supply. That meeting was indefinitely suspended, according to Oman's foreign minister, removing the most promising near-term path to reducing the geopolitical risk premium embedded in energy prices. Crude oil responded immediately. Brent crude climbed above 108 dollars a barrel in Asian trading, while West Texas Intermediate pushed past 103 dollars. For South Korea, which imports virtually all of its crude, the implications are direct and painful. Higher energy costs feed into transportation, manufacturing, and utility expenses, compressing margins across the industrial economy and weighing on a trade balance that is already sensitive to external shocks.
The second pressure came from the technology sector, and it is here that the story becomes more nuanced. Over the weekend, the leaders of three of the most prominent artificial intelligence companies publicly called for a slower pace of development, citing safety concerns. Dario Amodei of Anthropic urged the industry to take a more deliberate approach to improving its most advanced models. Sam Altman of OpenAI said his company would not pursue a public listing this year, citing the same concerns. Elon Musk expressed support for these positions. For a market like South Korea's, which has become deeply intertwined with the AI supply chain, these statements landed with unusual force. Samsung Electronics and SK hynix, the two companies that dominate the memory chip market that AI accelerators depend on, fell 3.66 percent and 6.07 percent respectively. SK Square, the holding company for SK hynix, dropped 7.25 percent.
The logic connecting these two developments is not as straightforward as it might appear. The AI safety debate is not a demand shock. No customer has cancelled an order. No data center has been shut down. What the statements represent is uncertainty about the pace of future investment, and in a market that has priced in years of aggressive capital expenditure, uncertainty is its own kind of pressure. As one analyst at Shinhan Investment & Securities put it, the semiconductor-centered AI value chain is declining due to a combination of macroeconomic pressure and AI concerns. The foreign investors who had driven the KOSPI to its highs earlier this year are now selling both spot stocks and futures, and they are doing so in size.
That selling is the third pressure, and it is the one that ultimately determines the day's outcome. Foreign investors net sold approximately 1.33 trillion won in the main stock market by the morning session, with institutions adding another 413 billion won in net sales. Individual investors, as they have throughout this selloff, absorbed the supply, net buying 1.54 trillion won. By the close, the scale of foreign selling had reached 3.5 trillion won. This is not a one-day event. Foreigners have been net sellers for four consecutive sessions, and the pattern reflects a broader reassessment of risk appetite as the Federal Reserve prepares for what is expected to be a rate increase at its meeting on September 16. Market-implied odds of a quarter-point hike now sit near 86 percent, and the combination of higher energy costs, rising Treasury yields, and uncertainty about the AI investment cycle has made Korean equities, which had been among the best performers in Asia this year, a natural target for profit-taking.
The won weakened alongside the index, trading at 1,346.8 against the dollar, down 2.7 won from the previous session. A weaker currency compounds the pressure on foreign investors, who face the prospect of currency losses on top of equity declines. It also raises the cost of imported energy, reinforcing the inflationary impulse that the central bank is already watching.
What should a careful observer take from this moment? Three things, I would suggest. First, the KOSPI's decline is not a verdict on the Korean economy. It is a repricing of risk in a market that had risen quickly and was vulnerable to exactly this combination of external shocks. The underlying fundamentals, a competitive export sector, a strong semiconductor franchise, and a central bank with room to maneuver, remain intact. Second, the AI safety debate is now a market factor. Whether the calls for a slower pace of development translate into actual changes in capital expenditure remains to be seen, but the market is treating them as a signal rather than noise. That is a meaningful shift. Third, the Fed's decision on Wednesday will set the tone for the weeks ahead. If Chair Kevin Warsh signals that the rate increase is a one-time adjustment rather than the beginning of a new tightening cycle, risk assets across Asia could find relief. If he leaves the door open to further hikes, the pressure will persist.
The deeper truth is that the Korean market is being asked to absorb a convergence of forces that originate far beyond its borders. A conflict in the Middle East that disrupts energy flows. A technology debate in Silicon Valley that reshapes expectations for the AI investment cycle. A monetary policy decision in Washington that determines the cost of capital for every economy connected to the dollar system. South Korea is not the author of any of these developments. It is a participant in all of them. And on Monday morning, the market priced that participation accordingly.
DYOR 🔎
#ShareWeekly $Exgate $Woori Financial Group $BH