What Is (3,3)? DeFi Game Theory Concept, OlympusDAO, and ve(3,3) Explained
What Is (3,3): Definition and Context
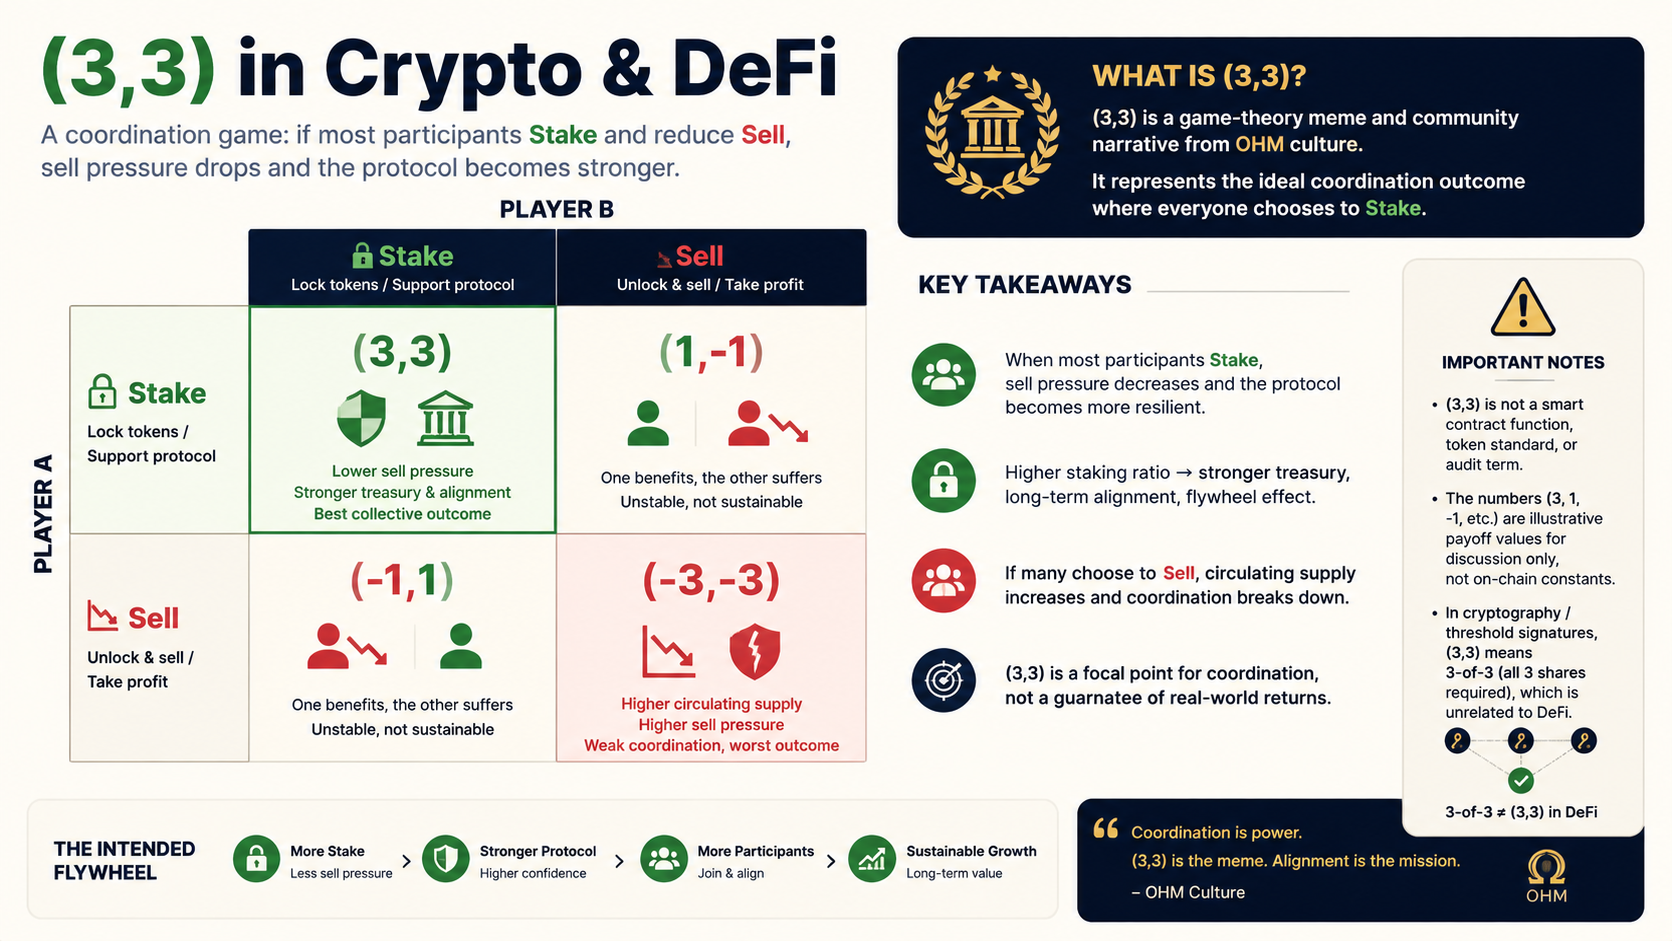
In the context of cryptocurrency and Decentralized Finance (DeFi), (3,3) primarily refers to a game-theoretic metaphor and community consensus symbol used to describe the following: if market participants broadly choose to Stake and reduce Selling, circulating sell pressure declines, protocol lock-up ratios increase, and under certain models this may create a more favorable scenario for both the protocol and token holders.
Boundary definitions are necessary:
- (3,3) is not a Smart Contract interface name, Token Standard, or audit term.
- The numbers in the matrix (e.g., 3, 1, -1) are illustrative utility scores for communication and discussion, not on-chain queryable constants.
- The same notation (3,3) in cryptography / threshold signatures often denotes 3-of-3 (three shards required), which is unrelated to the DeFi meaning (see Section 7).
Thus, in professional discourse, (3,3) should be understood as: a “focal outcome” narrative within coordination games, combined with an abbreviation for OHM-based mechanism culture—rather than a reproducible mathematical theorem or investment strategy.
Origin: OlympusDAO and the OHM Ecosystem

The widespread adoption of (3,3) is closely tied to OlympusDAO and its token OHM. Around 2021, OHM—as one of the algorithmic stablecoin/reserve currency experiments—sought to partially decouple token price and narrative from pure secondary market activity through mechanisms such as a Treasury, high staking returns, and Bond.
To condense the complex mechanism into a shareable slogan, the community introduced a 2×2 payoff matrix and labeled the optimal cell—where “both parties stake”—as (3,3). During the same period, numerous OHM forks emerged, reusing the (3,3) rhetoric to promote long-term lock-up and liquidity provision models.
Historically, the popularity of (3,3) coincided with the 2021–2022 DeFi high APY (Annual Percentage Yield), rebasing, and DAO governance boom; its subsequent price and TVL (Total Value Locked) both experienced significant cyclical swings, illustrating that narrative strength does not guarantee long-term equilibrium stability.
Game Theory Framework: Payoff Matrix and Nash Equilibrium
Relationship with Prisoner’s Dilemma and Nash Equilibrium
Discussions of (3,3) often draw on the Prisoner’s Dilemma and Nash Equilibrium: in the absence of credible coordination, individuals may choose to sell; if both parties can commit—or if social norms reinforce staking—a higher joint utility for both may emerge.
Typical simplified matrix (behaviors and scores are illustrative):
| Other: Stake | Other: Bond | Other: Sell | |
|---|---|---|---|
| Self: Stake | (3, 3) | (3, 1) | (3, -1) |
| Self: Bond | (1, 3) | (1, 1) | (1, -1) |
| Self: Sell | (-1, 3) | (-1, 1) | (-1, -1) |
Score conventions (community common expressions):
- Stake: approximately +3
- Bond: approximately +1
- Sell: approximately -1
“Other” may refer to another trader or abstractly to the “user–protocol” whole; the matrix is used for behavioral advocacy, not rigorous empirical calibration.
Position of (3,3) in Equilibrium Discussions
In the narrative, the (3,3) cell is presented as a cooperative solution in the sense of Pareto improvement: when both parties stake, protocol lock-up rises, the sell-pressure narrative weakens, and token holders enjoy staking returns and scarcity expectations.
Objectively, note:
- This result is not a contractually enforceable equilibrium; the chain cannot compel others to stake.
- (-1, -1) (both sell) has occurred in practice in multiple projects, corresponding to sell pressure and price declines.
- Under information asymmetry, the incentives of whales, insiders, and retail investors are not symmetric, and the matrix cannot capture power structures.
Therefore, a professional expression is: (3,3) is a normative equilibrium narrative hoping for coordination toward “dual staking,” not a unique Nash solution repeatedly validated by the market.
Mechanism Correspondence: Stake, Bond, and Sell
Understanding (3,3) requires combining the three typical behaviors of OHM-like systems (parameters vary by fork, logic similar).
Staking
Users stake tokens like OHM into the protocol, receive sOHM, gOHM, or similar vouchers, and obtain rebasing or fixed/floating APY.
Mechanism effect: The immediately sellable circulating share decreases (depending on the specific token accounting), supporting the protocol’s “lock-up consensus” narrative.
Matrix mapping: +3, directly corresponding to the (3,3) slogan.
Bonding
Users exchange assets such as DAI, ETH, or LP tokens with the Treasury at a discounted price, usually subject to a vesting period.
Mechanism effect: Adds assets to the Treasury, at the cost of tokens released in the future; return depends on the discount, vesting period, and market price.
Matrix mapping: Often +1, better than the sell narrative but lower than the advocacy priority of “dual staking.”
Selling
Selling on a DEX or CEX. Mechanism effect: Increases immediate supply, potentially triggering a panic sell-off under pessimistic expectations.
Matrix mapping: -1; (-1, -1) is used as a cautionary outcome of mutual harm.
In summary, at the mechanism level, (3,3) corresponds to “staking primarily, bonding secondarily, avoiding selling” as a product and community discipline; its actual effect still depends on Treasury quality, token inflation, demand-side capital, and macro liquidity.
ve(3,3): Name Continuation and Mechanism Differences
Starting around 2022, the ve(3,3) model promoted by Andre Cronje and others (first represented by Solidly, later Velodrome, etc.) adopted the (3,3) name, but its core mechanism differs from the OHM narrative.
| Dimension | OHM-based (3,3) | ve(3,3) |
|---|---|---|
| Focus | Staking, less selling, Treasury narrative | veToken lock-up governance + liquidity incentives |
| Tools | Stake / Bond / Treasury | vote-escrow, Gauge, bribes |
| Goal | Coordinate token holder behavior | Align interests of LPs, protocols, and lock-up voters |
| Name | Optimal cell in game matrix | Metaphor for a “multi-party win” design philosophy |
ve originates from Curve’s vote-escrow: users lock tokens to receive veNFT/veToken, and use voting rights to direct token emissions to specific trading pairs/pools; third parties can pay bribes to ve holders to secure votes.
In professional writing and SEO content, clearly distinguish “OHM (3,3)” from “ve(3,3)” to avoid readers equating them as the same investment strategy or contract architecture.
Propagation Logic and Real-World Limitations
Propagation Factors
- Low cognitive cost: two numbers, one table, suitable for social media.
- Positive-sum game framing: presents speculative games as a win-win cooperation.
- High return expectations: early OHM had extremely high APY, reinforcing the “staking is rational” narrative.
- Fork replication: numerous projects reused the label, forming a meme and discourse inertia.
Limitations and Criticism
- Sustainability: If returns rely mainly on newly minted tokens / rebasing, continuous capital inflow or Bond is needed; when expectations reverse, sharp price corrections are likely.
- Coordination failure: Slogans cannot replace market mechanisms such as liquidation, deleveraging, or panic selling.
- Terminology dilution: Not all projects labeled (3,3) have consistent mechanisms or disclosure quality.
- Regulation and compliance: High APY, algorithmic stablecoins, etc., face different compliance discussions across jurisdictions; readers should assess for themselves.
In industry retrospect, (3,3) is still frequently cited as a cultural symbol; as a “risk-free optimal strategy,” it has been widely questioned. Objective articles should state its historical role and structural risks, rather than replicating the promotional tone of that era.
Distinction from Cryptographic (3,3)
In documents on MPC (Multi-Party Computation), threshold signatures, Shamir’s Secret Sharing, etc., (3,3) or (t, n) = (3, 3) indicates:
- n = 3: The key or secret is split into 3 shares;
- t = 3: Recovery or signature requires all 3 shares (no fault tolerance).
This has no mechanical connection to the DeFi “optimal dual-staking cell.” In technical writing and SEO, use subtitles or keywords to distinguish: “DeFi 3,3,” “Olympus 3,3,” “threshold 3-of-3” to reduce cross-domain misinterpretation.
Summary
In Crypto/DeFi, (3,3) is a cooperative narrative derived from a game theory metaphor: the cell where both parties stake, labeled (3,3), is used to advocate long-term lock-up, reduced sell pressure, and alignment with protocol interests. It gained widespread traction through OlympusDAO and its fork ecosystem, and was later borrowed by ve(3,3) for ve governance and liquidity incentives, but the mechanisms and risk profiles differ.
Professional readers should grasp three points:
- Definition level: Cultural symbol + mechanism advocacy, not a technical standard.
- Mechanism level: Corresponds to behavioral categories like Stake/Bond/Sell; effect depends on Treasury, inflation, and market conditions.
- Risk level: (-1, -1) has occurred historically; (3,3) cannot substitute for due diligence and risk management.
One-sentence summary: (3,3) describes “if everyone coordinates on staking, the narrative joint return is higher”; whether the real market achieves that coordination is determined by liquidity, expectations, and mechanism design.
Disclaimer: This article is for educational and conceptual overview only and does not constitute investment advice. DeFi project mechanisms, tokenomics, and regulatory environments change over time; please refer to official documentation and on-chain data.
* The information is not intended to be and does not constitute financial advice or any other recommendation of any sort offered or endorsed by Gate Australia.
* This article may not be reproduced, transmitted or copied without referencing Gate Australia. Contravention is an infringement of Copyright Act and may be subject to legal action.
Share
Content


Related Articles
What Is Bitcoin? Understanding How Decentralized Digital Currency Works and Where Its Value Comes From
What Is Ethereum? ETH, Smart Contracts, and the Ethereum Ecosystem Explained
What Is Litecoin (LTC)? Understanding Its Technology, Use Cases, and Investment Value
What Is Solana (SOL)? A Comprehensive Guide to Its Technical Architecture, Consensus Mechanism, and Ecosystem
What Is Ripple (XRP)? A Global Payment Infrastructure Built on Blockchain Technology