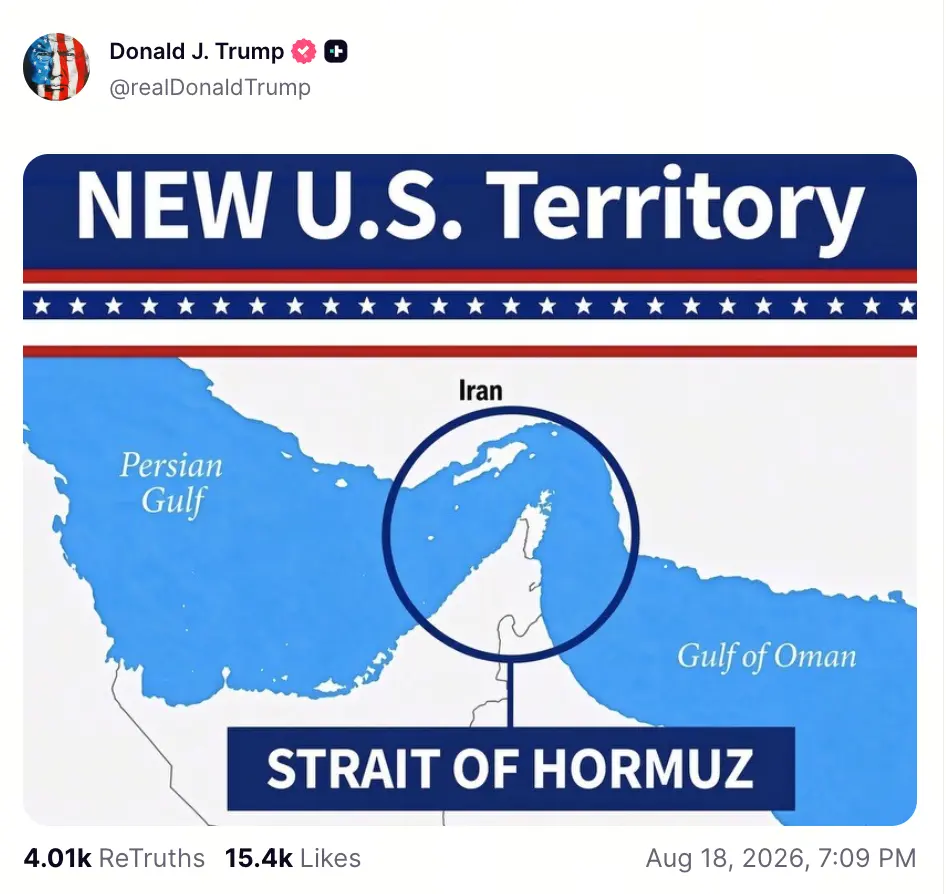
On August 18, 2026, the U.S.-Iran standoff escalated dramatically. U.S. President Trump posted a map on social media labeling the Strait of Hormuz as “America’s new territory.” Four days earlier, Trump had previewed the move, saying, “Soon I will announce the Strait of Hormuz as U.S. territory,” and adding, “This is real.” Iran’s Fars News Agency immediately dismissed the claim as “delusional,” responding that “Trump continues to claim in his delusion that ‘the Strait of Hormuz is U.S. territory.’”
That same day, Iranian Parliament Speaker and chief negotiator Mohammad Bagher Ghalibaf stated in parliament that the Strait of Hormuz would not reopen until the United States fulfilled the conditions promised in the June memorandum of understanding—including lifting the maritime blockade and oil sanctions against Iran, releasing Iran’s frozen assets, and halting military operations on all fronts.
Meanwhile, U.S. officials told the media that Trump had asked his negotiating team—including Vice President JD Vance, envoy Steve Witkoff, and son-in-law Jared Kushner—to suspend contact with Iran. Trump himself also said on social media that there would be no talks or dialogue with Iran either now or in the future. People familiar with the matter said the White House was adjusting its strategy toward Iran, shifting from “crippling Iran as quickly as possible” to “gradually strangling Iran.” Just one day earlier, Trump had said the U.S. was engaging with Iran through “secret channels,” while Kushner said negotiations “could be more active than ever.”
Diplomatic signals swung from “secret contacts” to a “complete suspension” within 48 hours, driving Brent crude higher for consecutive sessions. As of August 19, Brent crude futures had risen 1% to $91.95 per barrel.
What the market is pricing in is not an actual shortage of current crude supplies, but a more systemic question: What will happen to global energy supply chains if normal shipping through the Strait of Hormuz cannot be restored for an extended period?
Why the Strait of Hormuz Has Become the “Storm Center” of Oil Prices
The Strait of Hormuz is the world’s most critical energy transportation chokepoint. Before the war, about 110 commercial vessels passed through the narrow waterway each day, carrying roughly one-fifth of the world’s crude oil and liquefied natural gas. The exports of major Middle Eastern oil producers are highly dependent on this route.
After Trump posted the “America’s new territory” map on August 18, Iran responded by calling it “delusional,” but the market was more focused on actual shipping data. Over the past weekend, commercial shipping through the strait nearly ground to a halt. Kpler vessel-tracking data showed that only five commodity vessels transited on August 15 (Saturday), while none were recorded on August 16 (Sunday), far below the 31 vessels recorded during the previous weekend and sharply contrasting with the prewar normal flow of more than 110 vessels per day.
MarineTraffic data showed that at least three commercial vessels passed through the Strait of Hormuz during the 24 hours through August 17, with traffic shrinking by approximately 97% from prewar levels. Traffic edged up to six vessels on August 17 (Monday), but remained in the single digits. Monitoring by Straits.live indicated that commercial transits were approximately 1% of typical pre-crisis levels, with around 430 vessels stranded at anchorages or away from berths.
The plunge occurred after several tankers belonging to the UAE’s national oil company, ADNOC, were attacked in the strait. Vessels including Navig8 Messi and Tarif were attacked in succession, and the UAE pointed to Iran as responsible. Four of the nine major container shipping companies explicitly stopped using the strait, leaving at least 41 container ships trapped in the Gulf and affecting more than 200k TEU of capacity. War-risk insurance rates had risen to 30 times their normal levels.
The market’s logic is not complicated: the core driver of higher oil prices is not that “there is not enough oil,” but whether “the oil can be transported out safely.” This distinction determines the nature of the current price increase—it is driven by a supply risk premium, rather than an immediate decline in actual inventories.
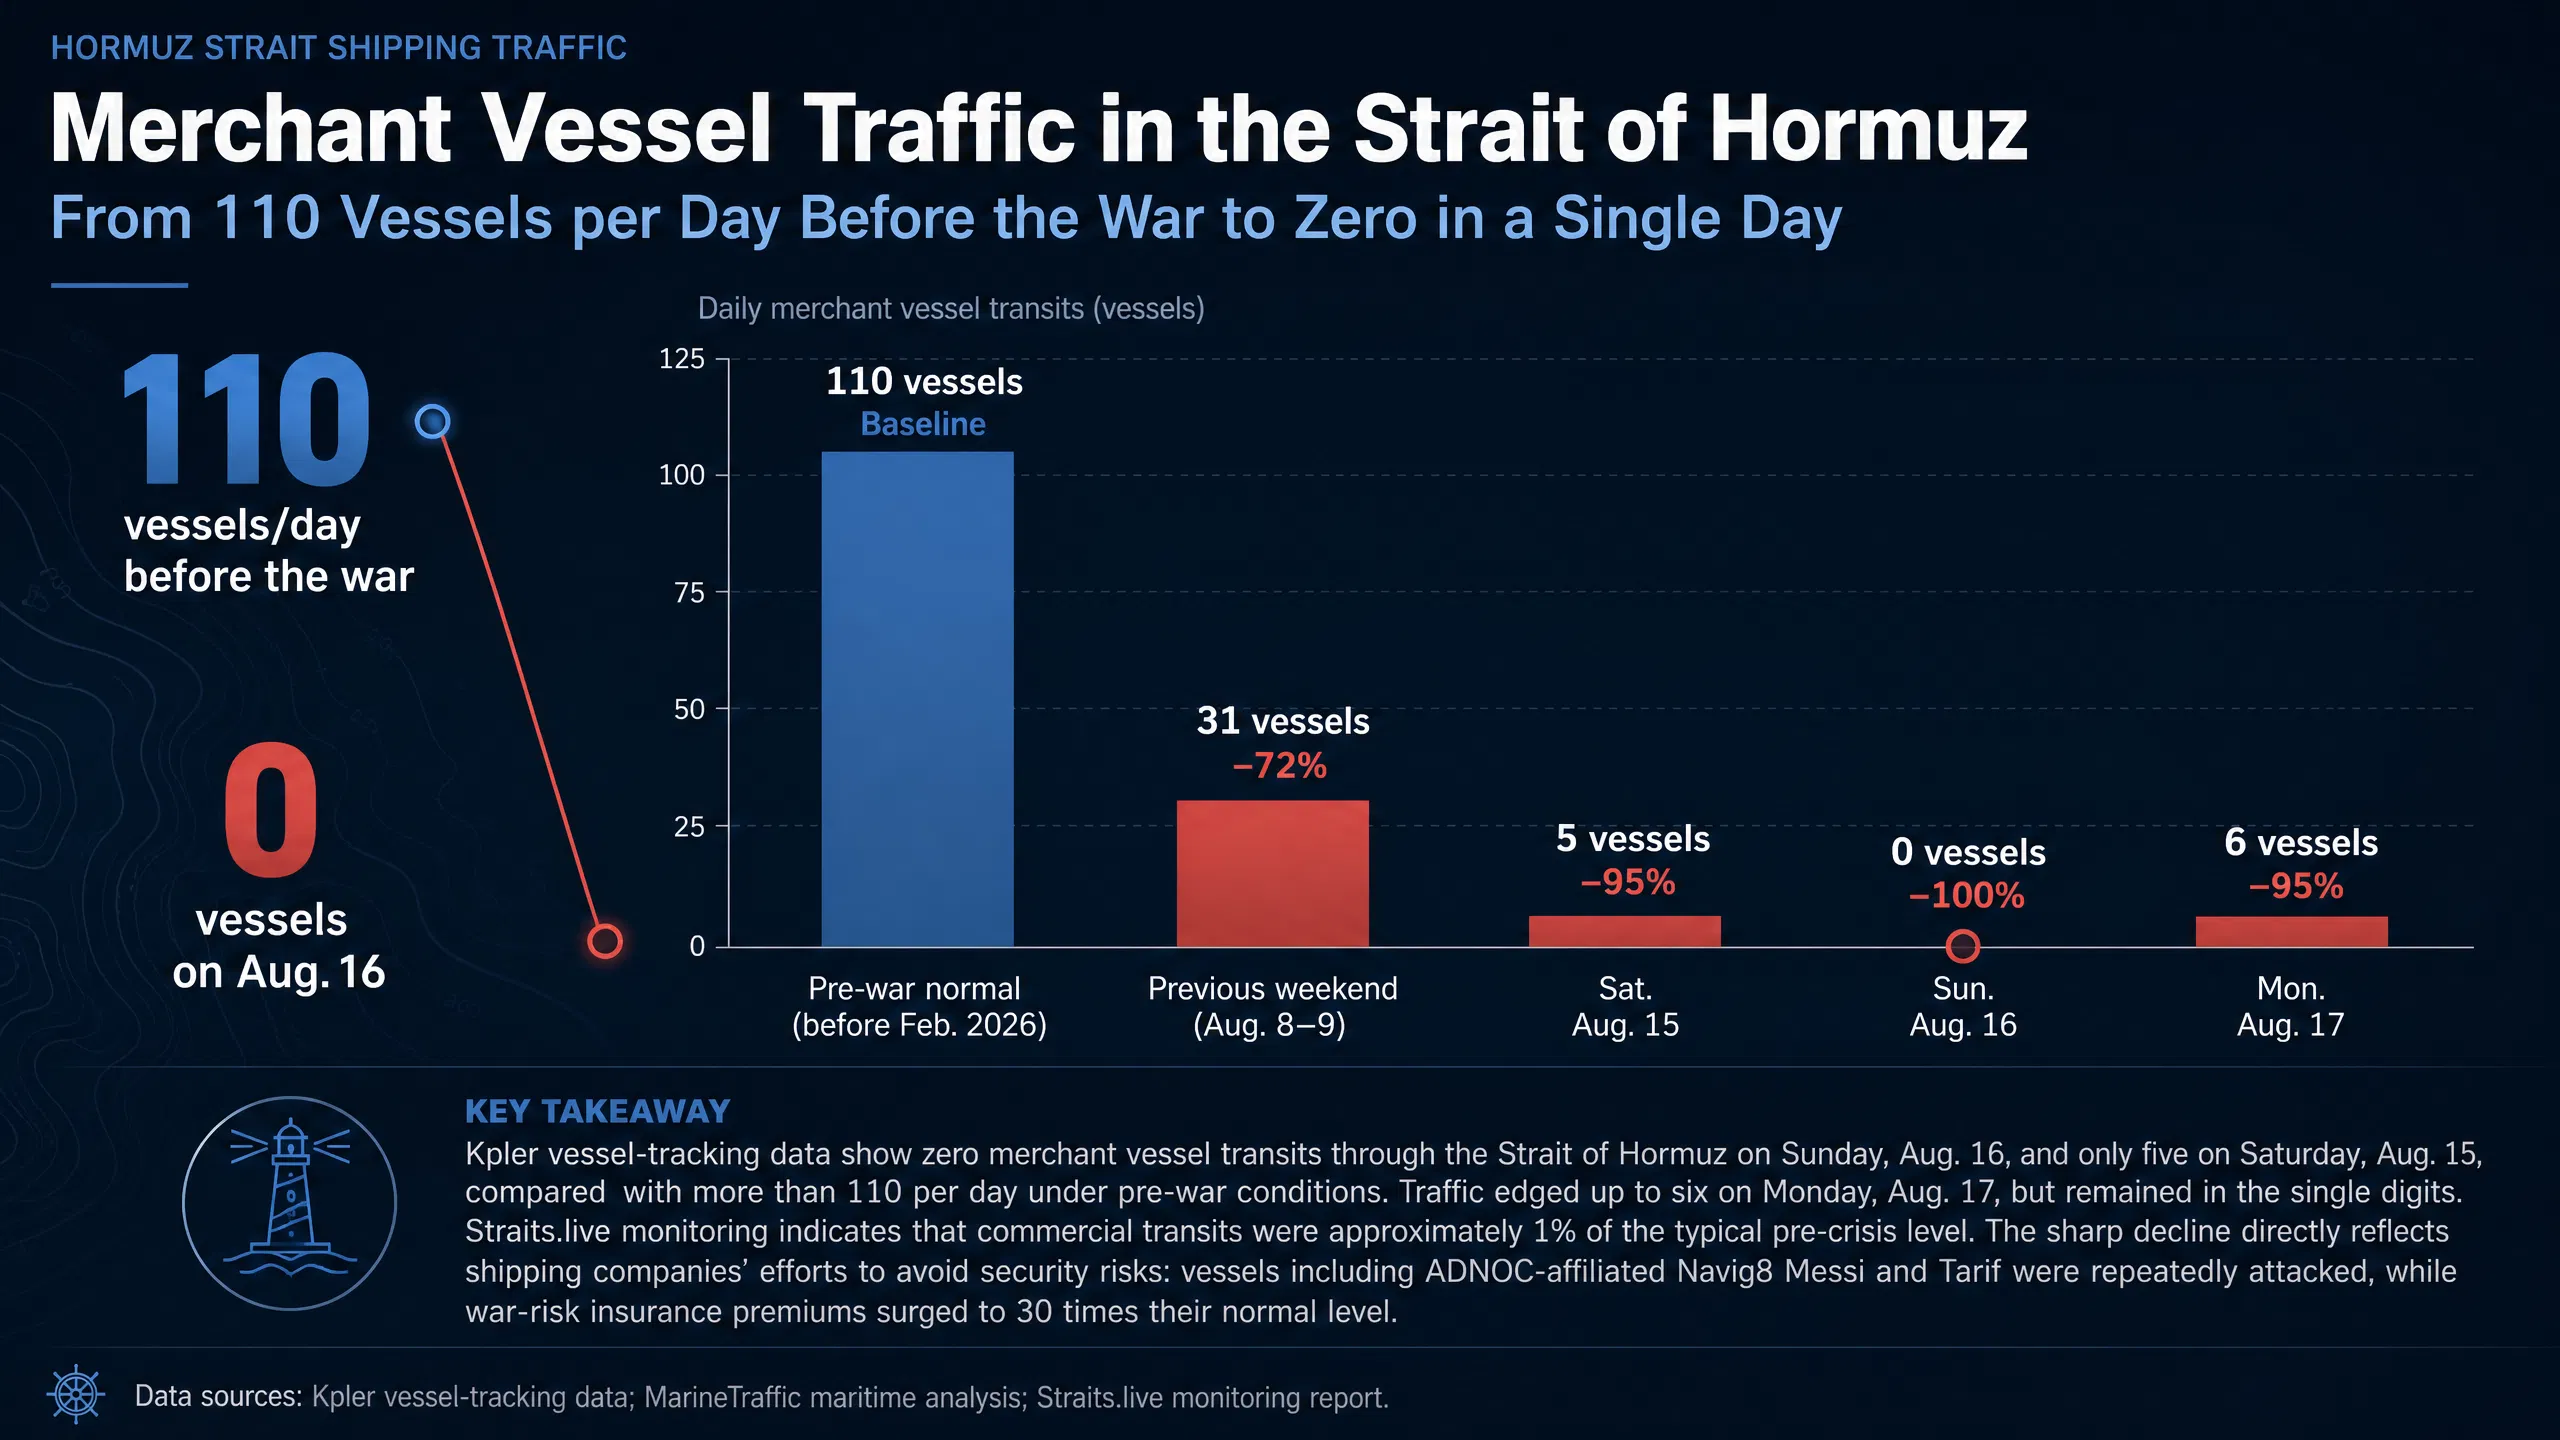
The cliff-like decline in vessel traffic through the Strait of Hormuz
U.S.-Iran Talks Fully Suspended: From “Secret Contacts” to a “Strangulation Strategy”
Over the past week, signals from the U.S. side have been contradictory, causing market expectations to swing sharply.
On August 17, Trump said the U.S. was engaging with Iran’s Islamic Revolutionary Guard Corps through “secret channels”; Kushner said U.S.-Iran communications “could be more active than ever.” Iran immediately denied that the two sides were holding direct negotiations.
On August 18, the 60-day memorandum of understanding formally expired. Trump said the United States was not seeking an extension and demanded that Iran “surrender and wave a white flag.” Later that day, Trump changed his wording on social media, saying that there were “currently no negotiations or dialogue with Iran, nor are any negotiations scheduled,” and announced that the Strait of Hormuz “is already open and operating normally, with all mines cleared or detonated”—a claim directly contradicted by data from shipping-tracking agencies.
U.S. officials subsequently clarified to the media that the U.S. and Iran had indeed held “active discussions,” but Trump had decided to suspend contact while waiting for Iran to signal its willingness to reach an agreement. White House officials told political allies that the U.S. was shifting from “crippling Iran as quickly as possible” to “gradually strangling Iran.” U.S. Treasury Secretary Bessent warned that “unprecedented” economic isolation measures would be announced in the coming week; Defense Secretary Pete Hegseth said the U.S. military could maintain the maritime blockade of Iran “indefinitely.”
Iran, meanwhile, adopted a harder-line posture. A senior Iranian official told Reuters that, as diplomacy had reached an impasse, Iran was shifting toward a military posture of “full-scale offensive.” Iran’s Foreign Ministry said the U.S. had seriously violated its commitments after signing the memorandum, that the two sides had not actually begun the planned dialogue, and that the supposed 60-day deadline had lost its meaning.
The market’s previous “peace expectations” were completely revised. Funds moved back into energy risk assets, creating a pricing logic of “the return of the risk premium.” Brent crude’s rise from above $90 on August 17 to $91.95 on August 19 was a concentrated expression of this logic.
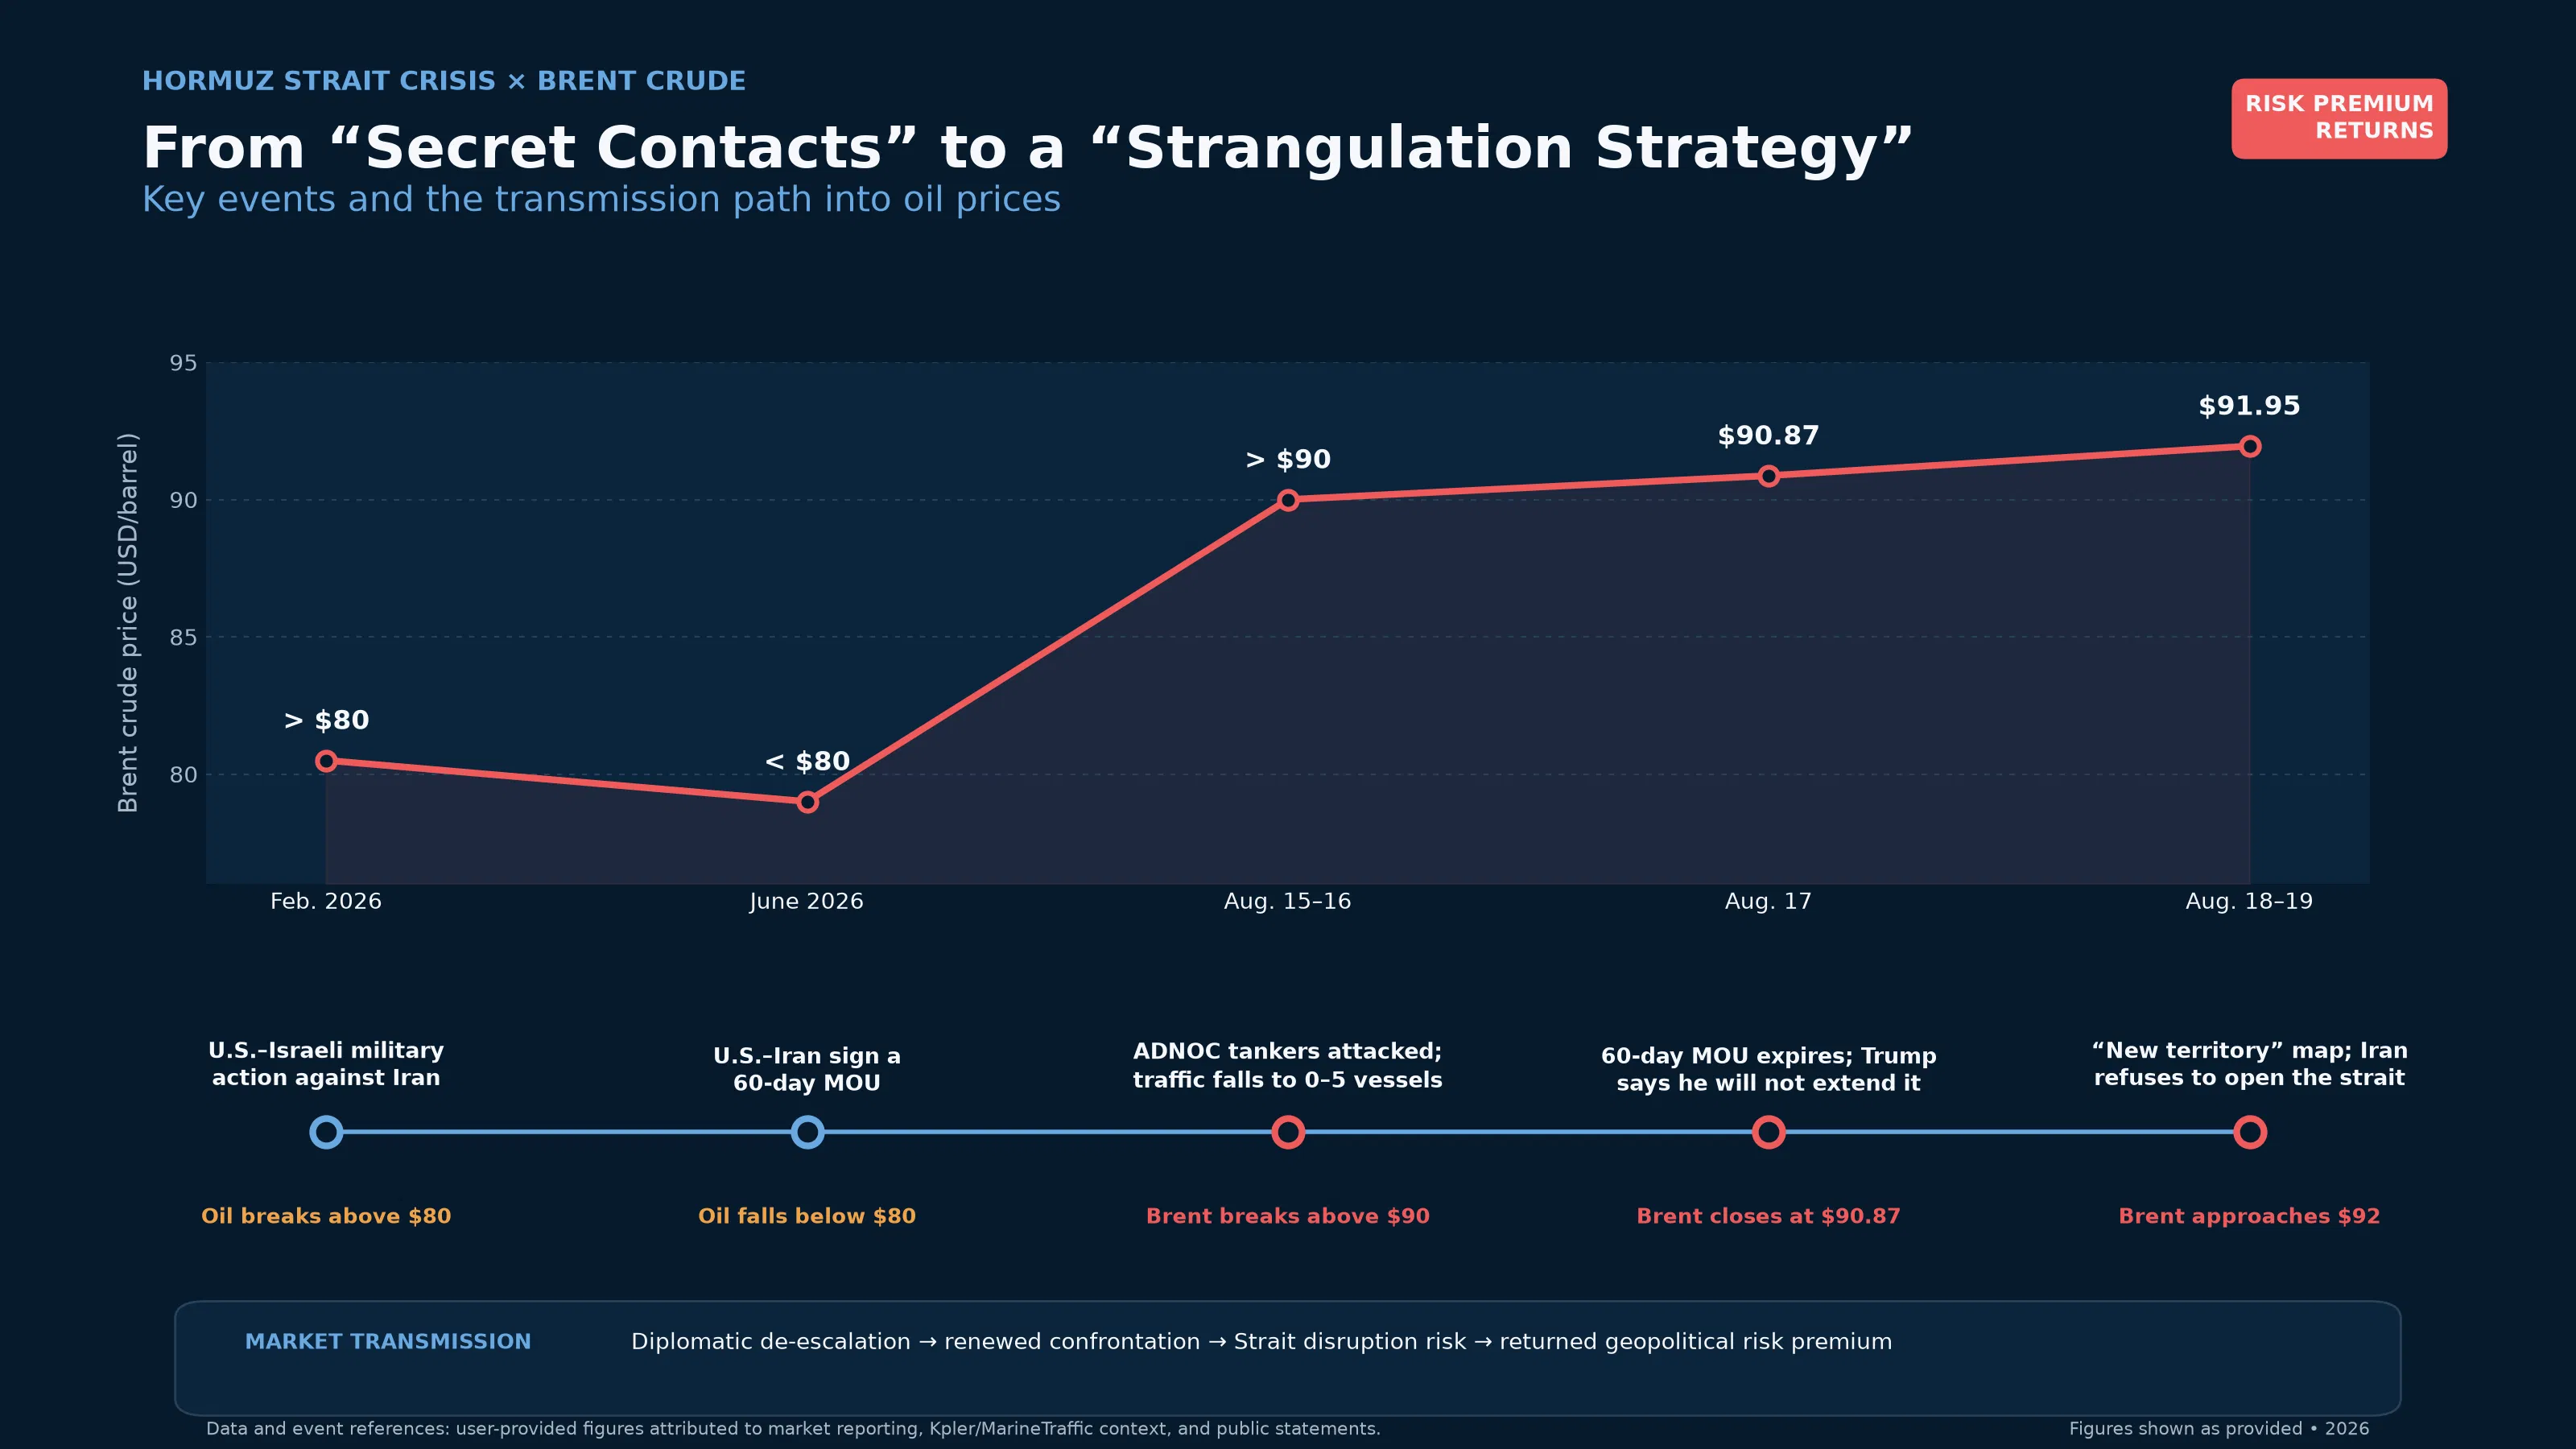
Timeline of the Strait of Hormuz crisis and its link to oil prices
Three Key Variables Determining the Direction of Oil Prices
The market’s core disagreement is whether $92 is a temporary peak or the starting point of a new rally. That depends on the direction in which three variables evolve.
Variable One: Can the diplomatic deadlock be broken?
Trump has explicitly ordered his negotiating team to suspend contact, while the White House strategy has shifted from “crippling” Iran to “strangling” it. Iran has directly linked reopening the strait to the lifting of sanctions and the blockade. Neither side has shown room for compromise on the core conditions. A U.S. official said Trump wants to resume contact after Iran’s leaders express a new willingness to negotiate and indicate that they are prepared to reach the agreement he seeks, but no such signal has been seen so far.
Under this scenario, oil prices could remain volatile above $90.
Variable Two: Can shipping through the strait be restored?
Shipping data shows that traffic through the strait has fallen to between 1% and 3% of prewar levels. Some vessels may transit in “dark mode” with their AIS (Automatic Identification System) turned off, meaning official tracking figures could slightly understate traffic, but overall flows remain far below prewar levels. As long as war-risk insurance rates remain 30 times their normal levels, most operators will continue to view the cost of transiting as prohibitive.
Variable Three: Will the conflict escalate further?
Trump’s move to label the Strait of Hormuz as “America’s new territory” on social media has already crossed the previous boundaries of confrontation at the diplomatic level. Iran responded by calling it “delusional,” but has not yet taken direct military countermeasures. However, Iran is shifting toward a military posture of “full-scale offensive,” tankers linked to the UAE have been attacked in succession, and Israel and Houthi forces are also becoming involved. If more serious shipping security incidents or military strikes occur, the market will be forced to reprice the risk of supply disruptions, and Brent crude could test the $100 mark.
Higher Oil Prices Do Not Equal a “Supercycle”
It should be noted that the current rise in oil prices is more consistent with a “risk-premium-driven rebound” than with a structural energy crisis like that of the 1970s. The difference is as follows:
Factors supporting higher oil prices include geopolitical risk premiums and supply uncertainty caused by shipping restrictions. Restrictions on transit through the strait have already contributed to a 69 million-barrel decline in observable global oil inventories in July, according to EIA data.
However, there are multiple constraints: the IEA forecasts that global oil demand will decline by 1.6 million barrels per day in 2026; OPEC has cut its forecast for 2026 global oil demand growth from 800k barrels per day to 600k barrels per day. The elasticity of U.S. shale oil supply, OPEC’s spare capacity, and the ability to release strategic oil reserves all limit how far oil prices can rise.
FAQ
1. What impact will Trump labeling the Strait of Hormuz as “America’s new territory” have on oil prices?
On August 18, Trump posted a map on social media labeling the Strait of Hormuz as “America’s new territory,” prompting an Iranian rebuttal. The move significantly escalated the intensity of the confrontation diplomatically, heightening market concerns about supply disruption risks and pushing Brent crude to $91.95 on August 19.
2. What is the current shipping situation in the Strait of Hormuz?
Only five commercial vessels passed through on August 15 (Saturday), none on August 16 (Sunday), and traffic recovered to six vessels on August 17 (Monday), compared with an average of about 110 vessels per day before the war. Traffic has contracted by approximately 95% to 97% from prewar levels, while war-risk insurance rates have risen to 30 times their normal levels.
3. What is the current status of U.S.-Iran negotiations?
On August 18, Trump publicly said that the U.S. and Iran had “no talks underway or scheduled.” U.S. officials confirmed that Trump had ordered the negotiating team—including Vance, Witkoff, and Kushner—to suspend contact with Iran. The White House strategy is shifting from “crippling Iran as quickly as possible” to “gradually strangling” it.
4. Could oil prices rise to $100?
If restrictions on the strait persist or the conflict escalates further, the market will reprice the risk of supply disruptions, and oil prices could test $100. But if diplomacy breaks through, the risk premium will quickly fade. The core variables are whether the U.S. and Iran resume contact, what shipping data from the strait shows, and whether the United States escalates military action.
5. How does the current rise in oil prices differ from the energy crisis of the 1970s?
The current rise in oil prices is primarily driven by geopolitical risk premiums rather than a structural supply-demand imbalance. Global demand is being constrained by high oil prices and slowing economic growth, while U.S. shale oil supply, OPEC spare capacity, and the ability to release strategic reserves all limit how far oil prices can rise.


