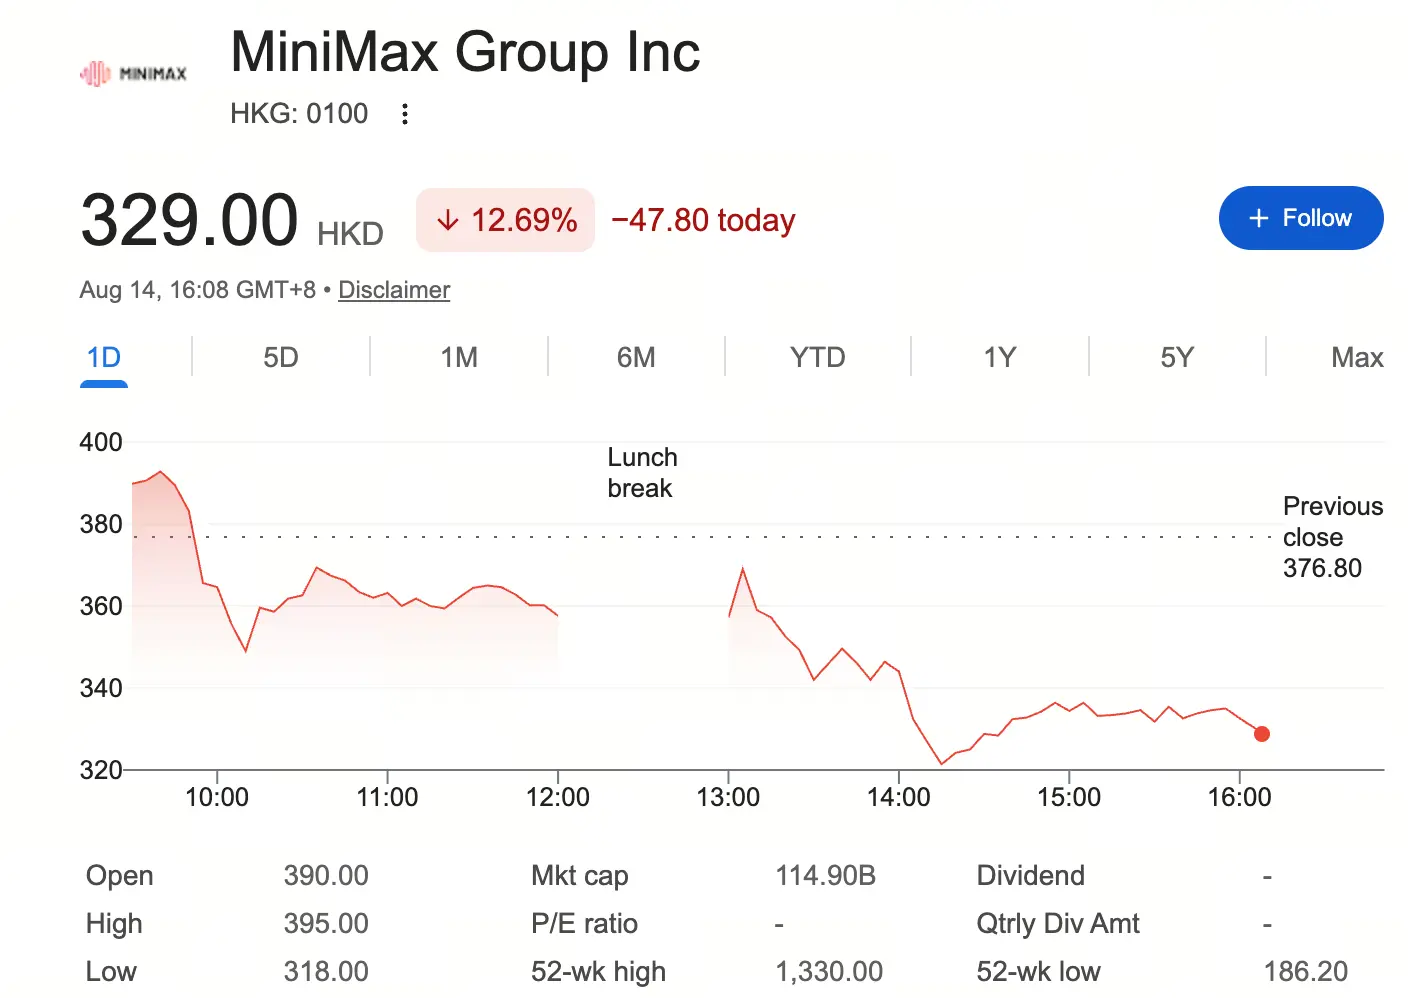
Source: Google Finance
The market is undergoing a concentrated reassessment of the valuation logic for AI assets. From “technological leadership” to “commercial execution,” and from “concept premiums” to “discounted cash flow,” the essence of this adjustment is a shift in the anchor for market pricing.
HK$16 Billion Financing Plan: A Dual Narrative of Replenishing Capital and Dilution Pressure
On July 10, MiniMax announced a financing plan totaling more than HK$16 billion, including approximately HK$9.54B from a share placement and HK$6.5 billion in zero-coupon convertible bonds. The placement involves 35.6 million new Class A shares at HK$268 per share, representing a discount of approximately 9.89% to the closing price before the announcement. The initial conversion price of the convertible bonds is HK$335 per share.
Approximately 80% of the net proceeds will be invested in AI infrastructure and model research and development, 10% will be used for global business expansion, and 10% will supplement working capital. The financing attracted participation from more than 20 international sovereign wealth funds and long-term investment funds and was approximately seven times oversubscribed. The final issuance size was increased from the initial $1.8 billion to more than $2 billion.
The capital market offered sharply divergent interpretations. Optimists believe that the oversubscription by top-tier institutions shows that long-term capital remains confident in MiniMax’s medium-term fundamentals. Pessimists, meanwhile, are focused on the dilution effect: after completion of the placement, the new investors will hold approximately 10.19% of the company, while future conversion of the convertible bonds could cause further dilution and put pressure on existing shareholders’ equity.
The timing of the financing also warrants attention. Just one day before the announcement, on July 9, MiniMax saw the first large-scale expiration of lock-up restrictions since its IPO, with approximately 153 million shares, or 48.9% of total share capital, becoming tradable. The share price fell 17.98% that day. The overlap between the financing announcement and the lock-up expiration heightened market concerns about share-supply pressure.
AI Competition Enters a New Phase: From Model Parameters to Unit Economics
Industry changes since 2026 show that the main axis of competition in the AI large-model sector is undergoing a structural shift.
A pricing inflection point is emerging. A Morgan Stanley research report on August 9 pointed out that the average API output price for Chinese large models had risen from approximately 12.2 yuan per million tokens in the first quarter of 2025 to 21.9 yuan per million tokens in the second quarter of 2026. DeepSeek announced a substantial API price increase in August, only about three weeks after introducing peak- and off-peak pricing in mid-July. Institutional analysts believe this marks the transition of domestic large models from extensive competition based on “low prices for scale” to a stage of value monetization based on model capabilities and service quality.
Open-source licensing models are becoming more restrictive. Previously permissive Apache 2.0 or MIT licenses are shifting toward L2- or L3-level licenses. In the case of Moonshot AI’s K3, MaaS providers with annual revenue exceeding $20 million must sign separate commercial agreements. Alibaba’s Qwen has also introduced a revenue-sharing mechanism for customers whose annual API usage exceeds $5 million. This means model providers’ monetization strategies are expanding beyond direct API sales to include revenue sharing with cloud service providers and aggregation platforms, thereby expanding the addressable revenue pool.
The competitive dimension is shifting from “model capabilities” to “deployment costs and enterprise services.” Industry analysts point out that AI competition has shifted from “whose model is the strongest” to “who can bring AI into core enterprise processes at lower cost and with greater flexibility.” Open-weight models allow enterprises to deploy models on their own servers or private clouds, retaining data sovereignty while bringing AI capabilities in-house. The model itself may no longer be the final product, but rather the entry point into the enterprise market.
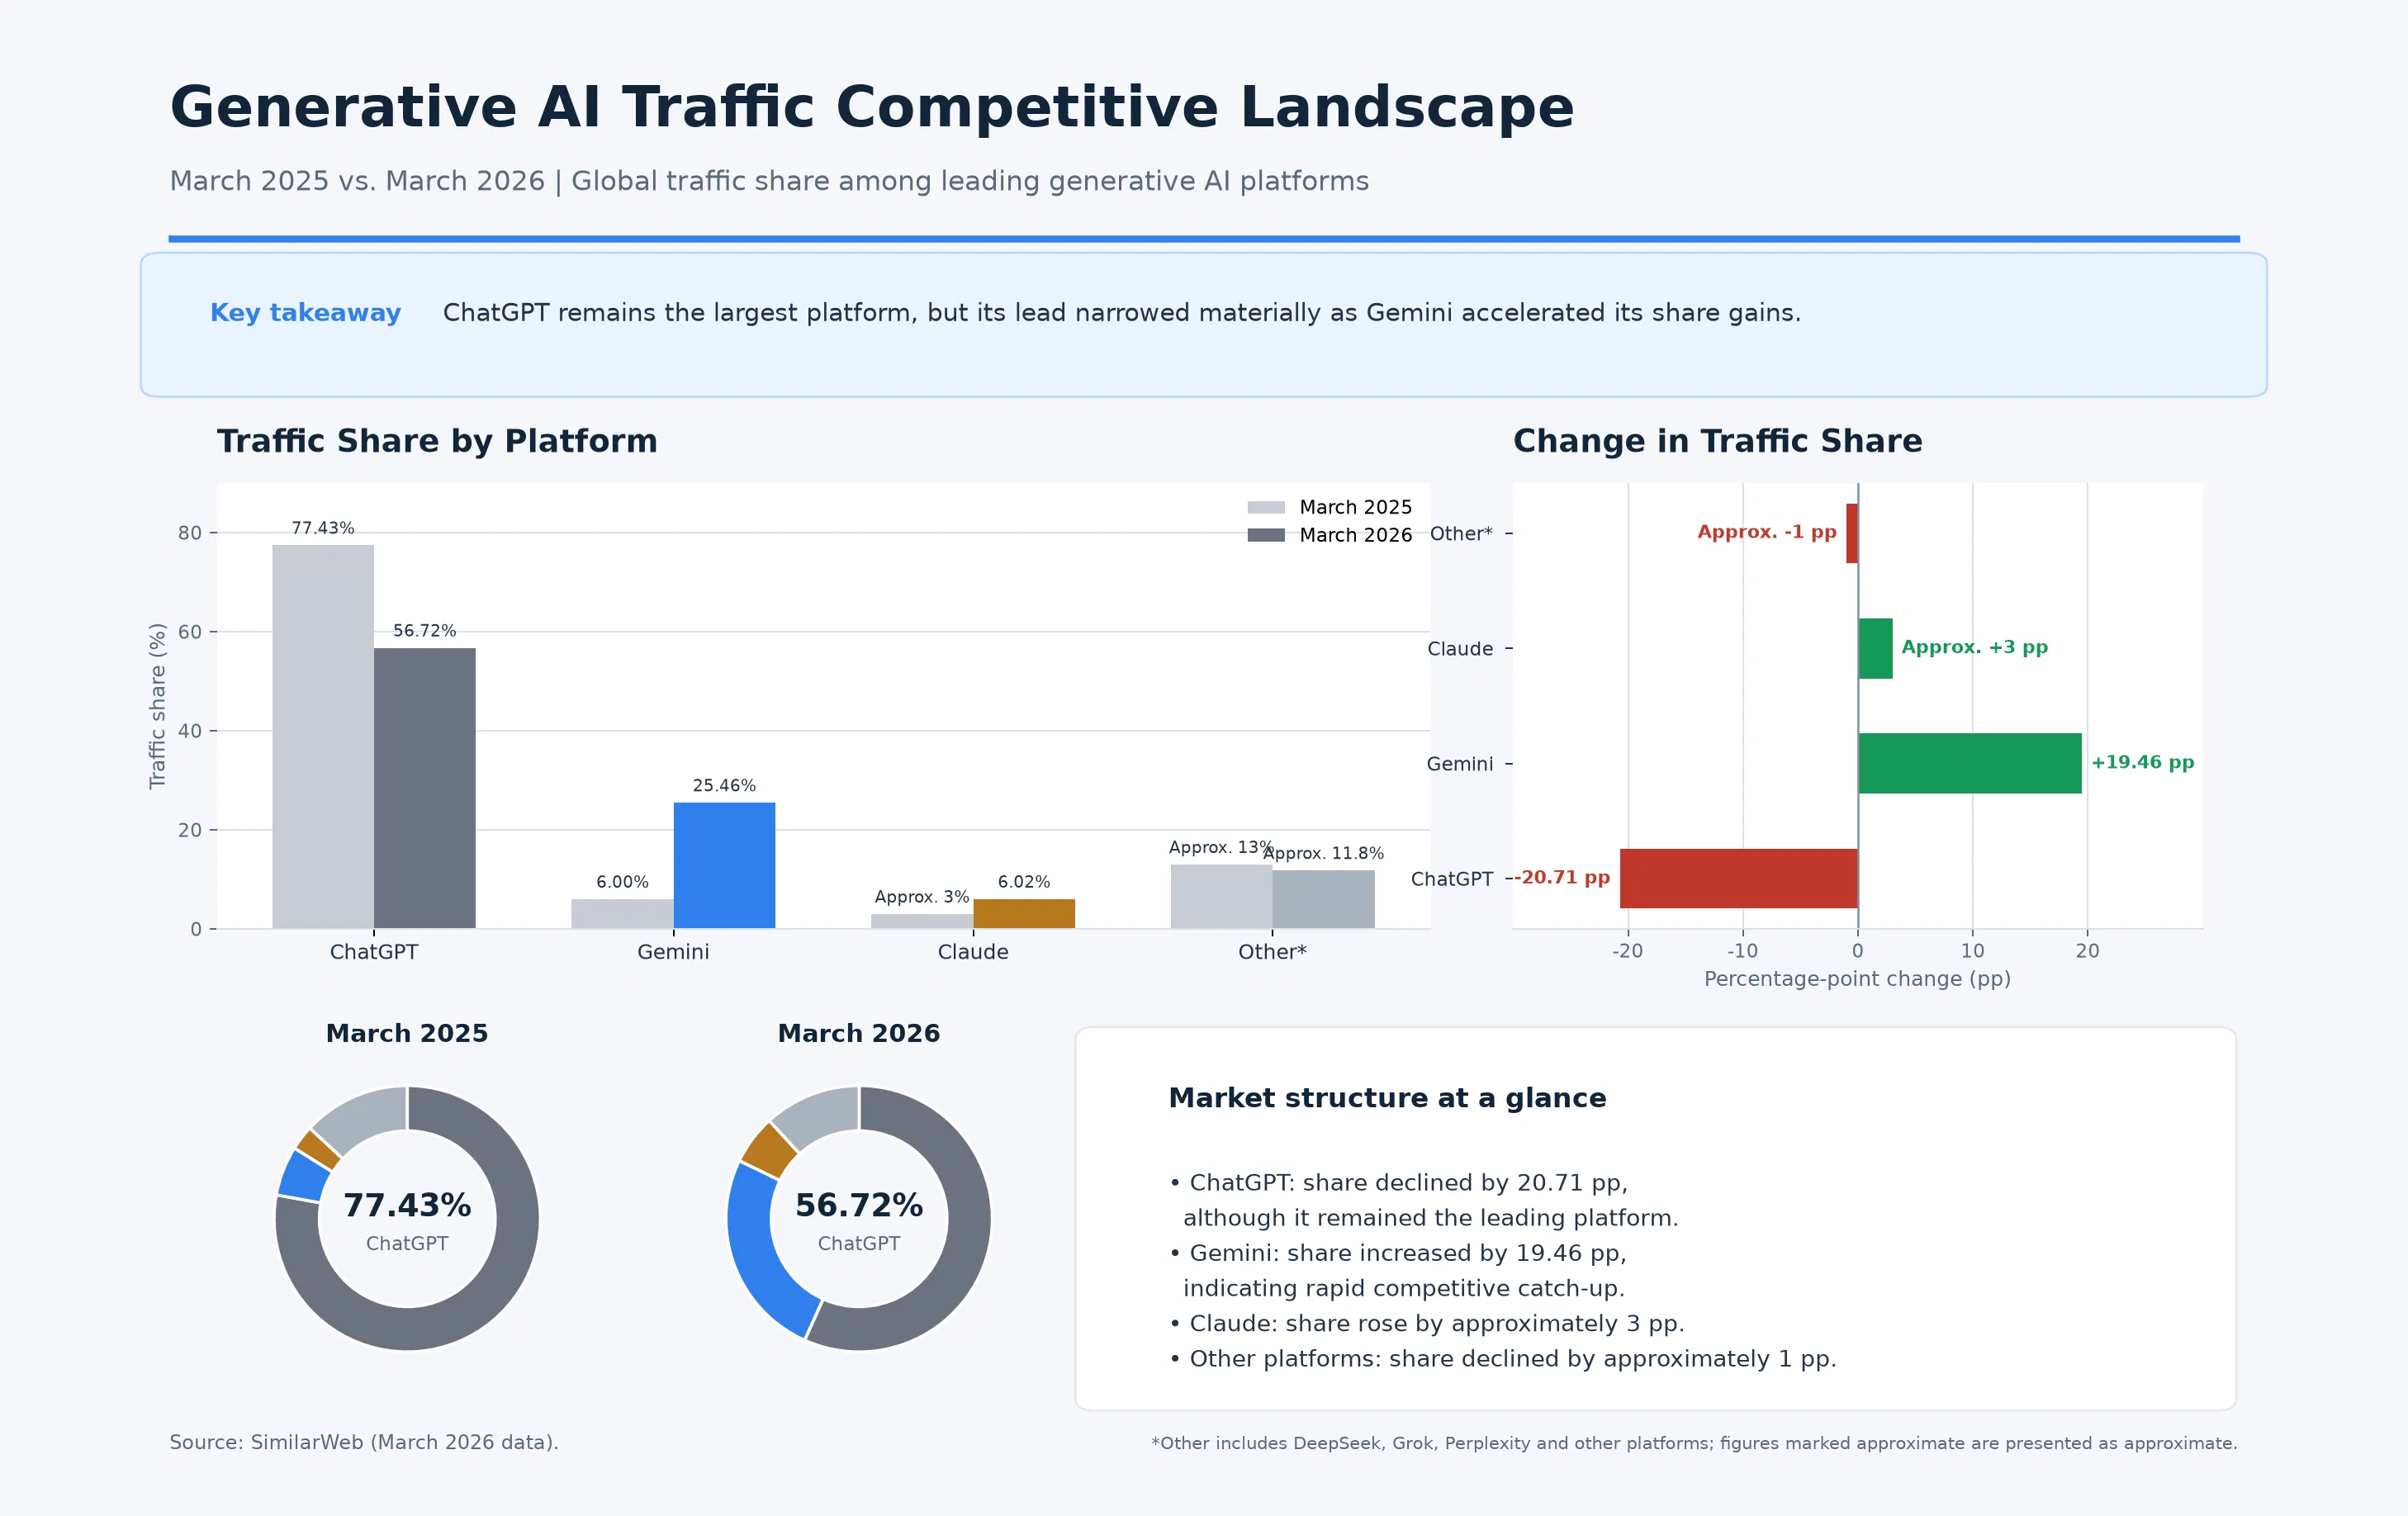
Changes in the competitive landscape for generative AI traffic (March 2025 vs. March 2026)
MiniMax’s Differentiated Positioning and Commercialization Milestones
MiniMax’s technology and business-model choices determine the valuation-validation stage it is currently in.
The multimodal path of the H3 model. On July 31, MiniMax released its next-generation multimodal generative model, H3, which supports multiple input formats, including text, images, audio, and video, and can generate audiovisual content up to 15 seconds long. Video generation is priced at 0.8 yuan per second at 2K resolution, approximately one-third the price of comparable flagship products. H3 also adopts an open-weight strategy, allowing enterprises to deploy and optimize it locally. This combination of “low cost + open deployment” is intended to lower the barrier to enterprise adoption, but it also faces the test of commercialization efficiency.
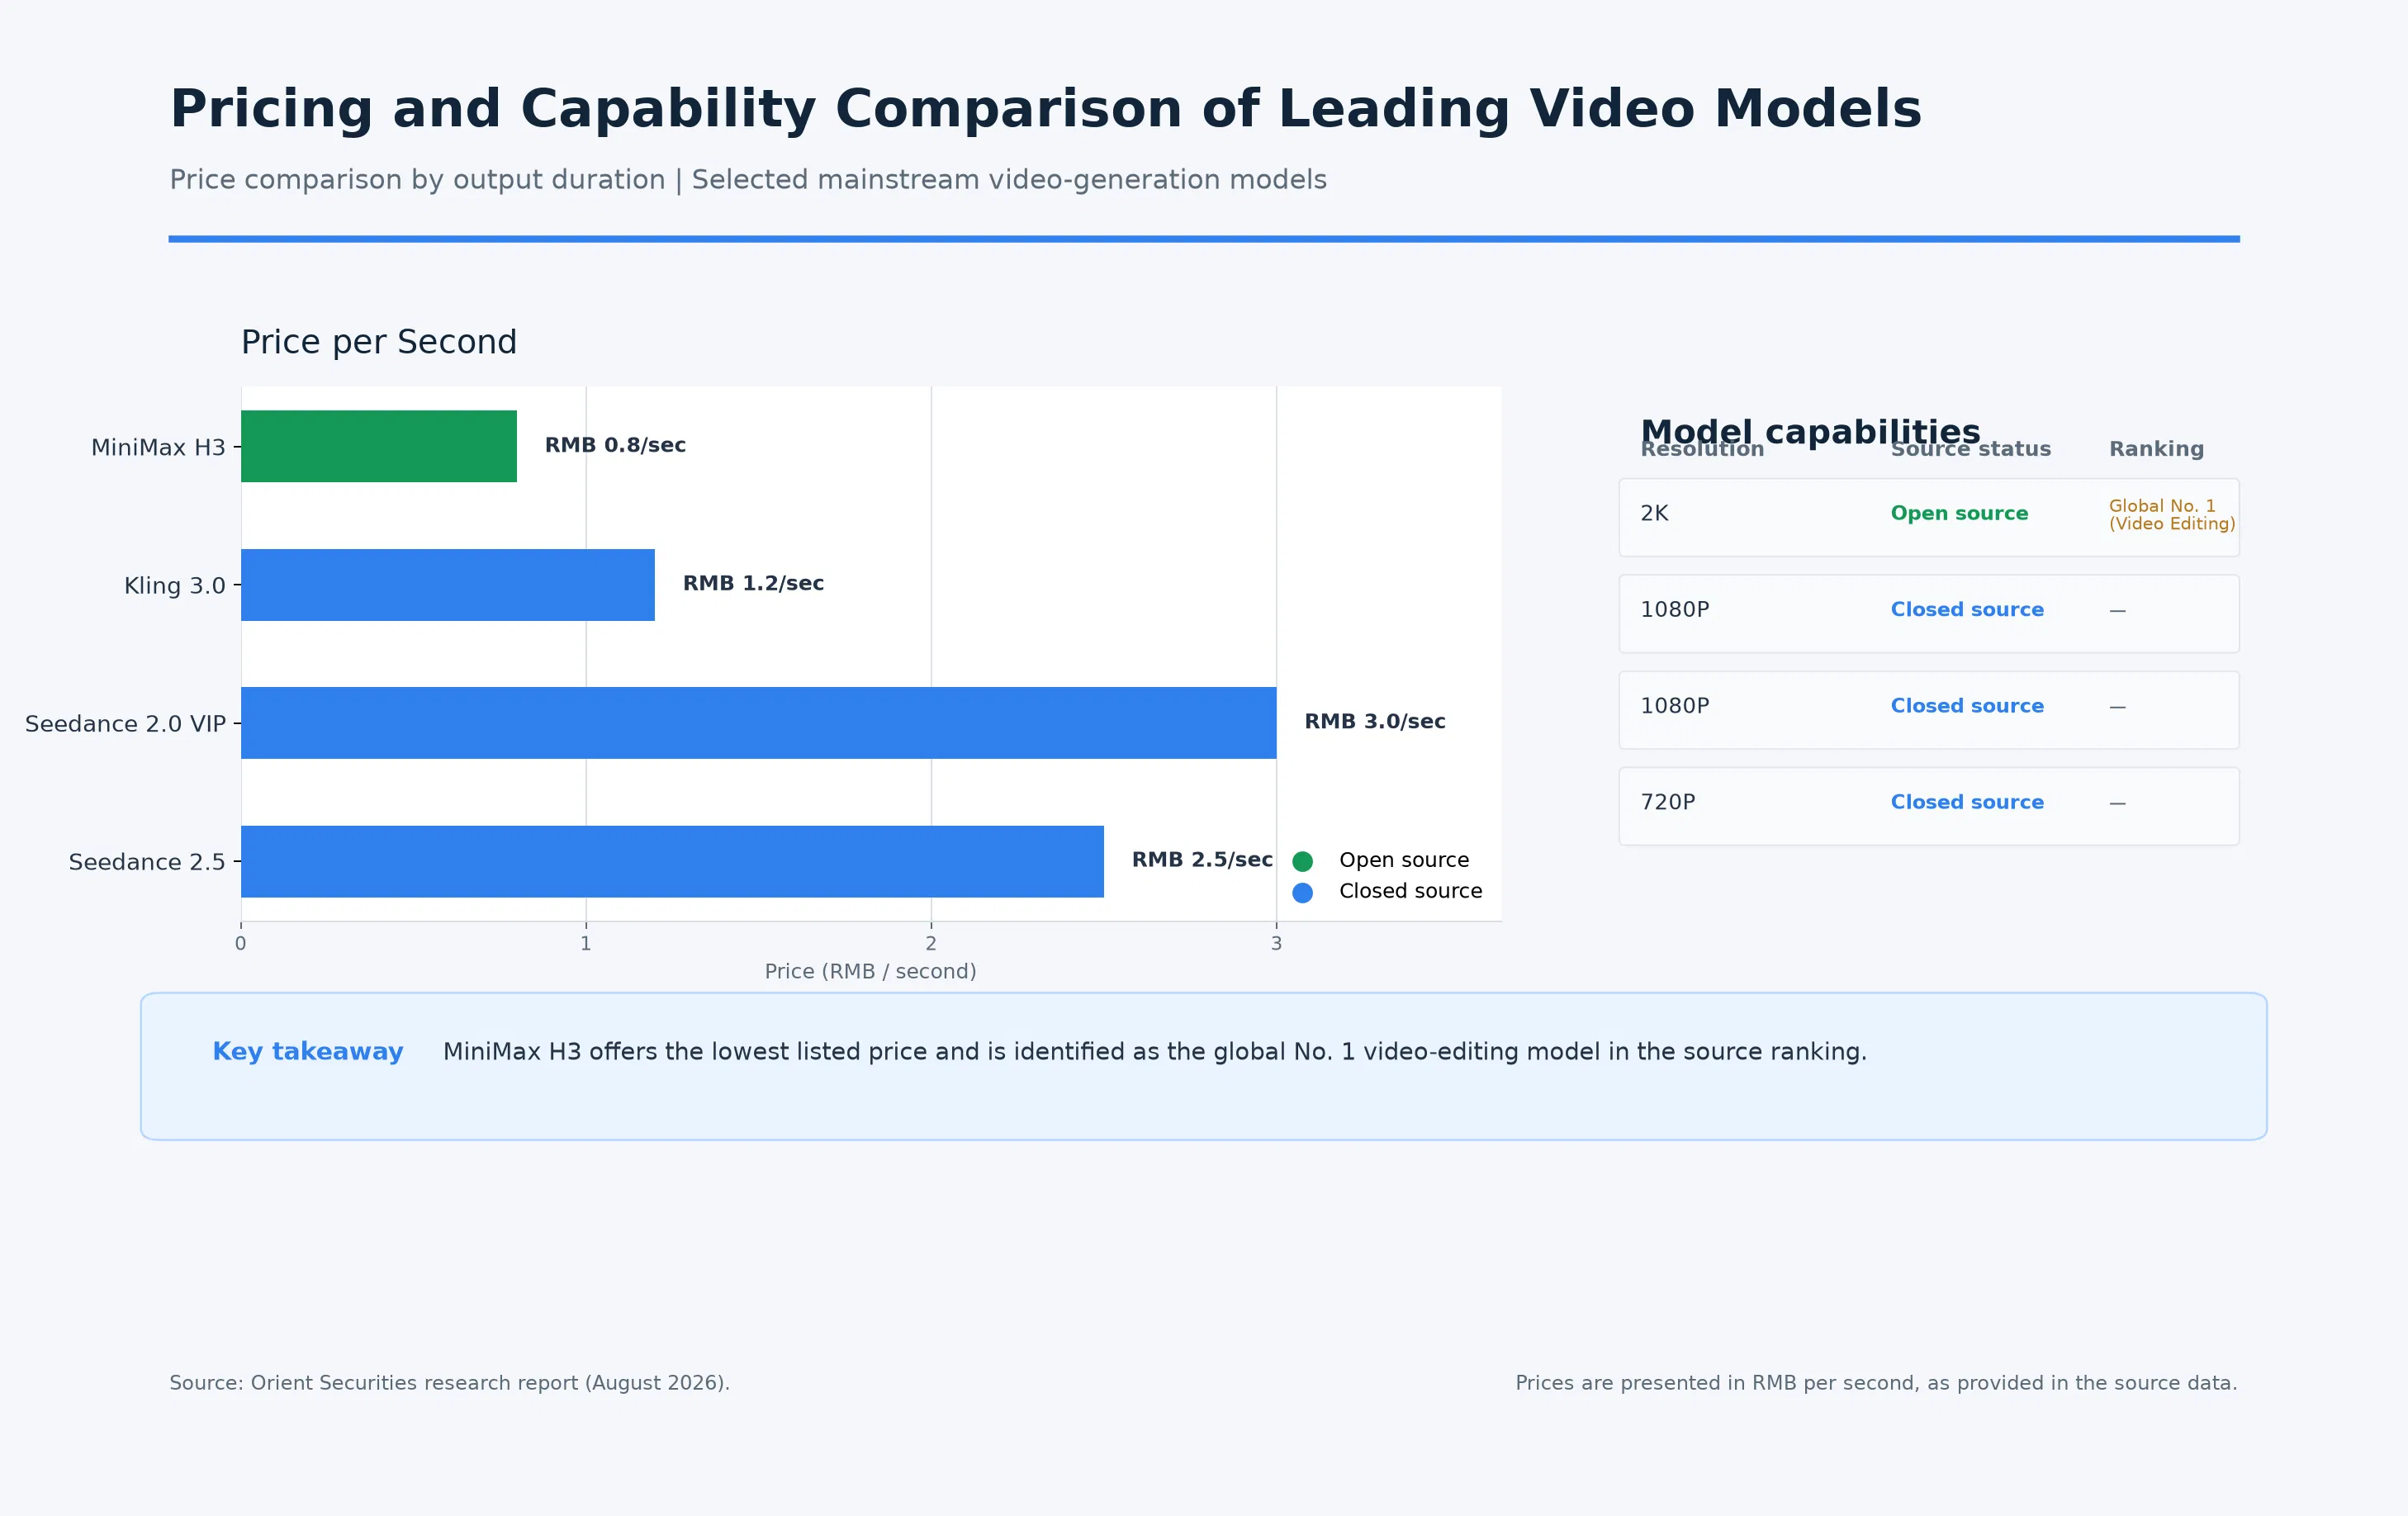
Comparison of mainstream video-model pricing and capabilities
Uncertainty arising from intellectual-property disputes. H3’s commercial-use license excludes the European Union, the United Kingdom, South Korea, and the United States from the authorized regions and also prohibits the use of model outputs outside those regions. The head of developer relations publicly stated that the geographic restrictions stem from copyright litigation over generated videos involving major Hollywood film companies. In September 2025, Disney, Universal Pictures, and Warner Bros. Discovery sued MiniMax over Hailuo in the U.S. District Court for the Central District of California. In May 2026, the court denied MiniMax’s motion to dismiss, and the case entered the discovery phase. The potential constraints that legal risks could place on overseas expansion cannot be overlooked in the commercialization process.
The Shift in the Valuation Anchor: From “AI Narrative” to “Cash Flow Logic”
The pricing logic for the AI sector is currently undergoing a systematic reshaping.
The factors that previously drove MiniMax’s rise—breakthroughs in model capabilities, the Hong Kong stock market’s AI investment boom, and the opening of the southbound capital-allocation channel—all depended to varying degrees on the narrative of the AI sector’s long-term growth potential. After the previous sharp rally, however, the market has begun to assess more cautiously the relationship between capital investment and commercial returns.
Institutional views are diverging. JPMorgan has sharply raised its target price for Zhipu from HK$400 to HK$1,800 while downgrading MiniMax. CITIC Securities pointed out that the center of AI asset valuation is shifting from the input side, represented by infrastructure investment, to the output side, represented by commercial monetization. Haitong International, meanwhile, believes that the market should shift from thematic speculation to fundamental investment based on medium-term performance and valuation appeal, with market performance likely to diverge significantly.
Key Indicators to Watch Going Forward
For MiniMax, market attention is shifting from “what models it releases” to “how much revenue it generates.” Data across the following dimensions will determine the direction of its valuation:
API revenue and enterprise-customer growth. Call volumes continued to grow after DeepSeek raised prices, indicating that some enterprise customers can bear the cost of high-quality model services. Whether MiniMax can achieve sustained growth in API call volumes and enterprise-customer numbers after the release of H3 will be the most direct demonstration of its commercialization capabilities.
User retention and the application ecosystem. The long-term moat of an AI company lies not in the model itself, but in user access points and ecosystem stickiness. Active-user numbers, usage frequency, and commercial-customer renewal rates are key indicators of productization capabilities.
R&D investment efficiency. The market needs to see a positive correlation between R&D investment and revenue growth. If the pace of capital investment continues to exceed the pace of revenue growth, the valuation premium will be difficult to sustain.
Financing pace and cash-flow management. Large models remain capital-intensive, and future financing needs, the rate of cash burn, and equity-dilution risks are all core variables affecting valuation.
Conclusion
MiniMax’s 12.69% one-day decline is essentially a market expression of a shift in valuation logic. Its previous rise was built on the AI sector’s vast imagined potential, while the market is now asking a more fundamental question: Can technological capabilities be converted into commercial cash flow with predictable efficiency?
The AI industry remains in a stage in which rapid iteration and business-model validation are progressing in parallel. For investors, this adjustment means they need to distinguish more carefully between “AI technology companies” and “AI platform companies”—the former derive their valuations from technological narratives, while the latter are priced on the basis of sustained commercial cash flow. MiniMax’s biggest future attraction is not its next model release, but whether it can establish a sustainable positive cycle between computing-power investment and revenue growth.
FAQ
1. What is the core reason for MiniMax’s decline this time?
The direct trigger was concern over equity dilution caused by the HK$16 billion financing plan, compounded by share-supply pressure from the first large-scale expiration of lock-up restrictions. The deeper reason is that market pricing logic is shifting from an “AI concept premium” to scrutiny of commercialization capabilities and cash flow, reflecting a broader shift in the valuation anchor for the AI sector.
2. What does the HK$16 billion financing mean for MiniMax?
Approximately 80% of the financing will be invested in AI infrastructure and model research and development. Although it will dilute equity in the short term, it represents necessary investment to maintain computing-power competitiveness over the long term. The participation of multiple international sovereign wealth funds and long-term investment funds, along with sevenfold oversubscription, indicates that long-term capital remains confident in the company’s medium-term fundamentals.
3. What changes have occurred in the competitive landscape of the AI large-model industry?
Competition is shifting from “model parameter scale” to “commercial monetization efficiency.” Industry pricing has bottomed out and begun to recover, open-source licensing models are shifting from permissive licenses to commercial revenue sharing, and leading companies are moving from “low prices for scale” toward value monetization based on model capabilities and service quality.
4. What are the main risks currently facing MiniMax?
The main risks include the pace of commercialization validation—whether API revenue and enterprise-customer growth can match capital investment; overseas litigation—copyright disputes with Hollywood film companies could constrain international expansion; and industry competition—pressure from domestic and overseas model companies and open-source ecosystems.
5. Which indicators should investors focus on to assess MiniMax’s future performance?
Commercial revenue data, including API revenue, enterprise-customer numbers, and subscription revenue; user retention and renewal rates; R&D investment efficiency; cash-burn rate; and financing pace. The impact of model-release news is declining, while financial data will be the core basis for future pricing.