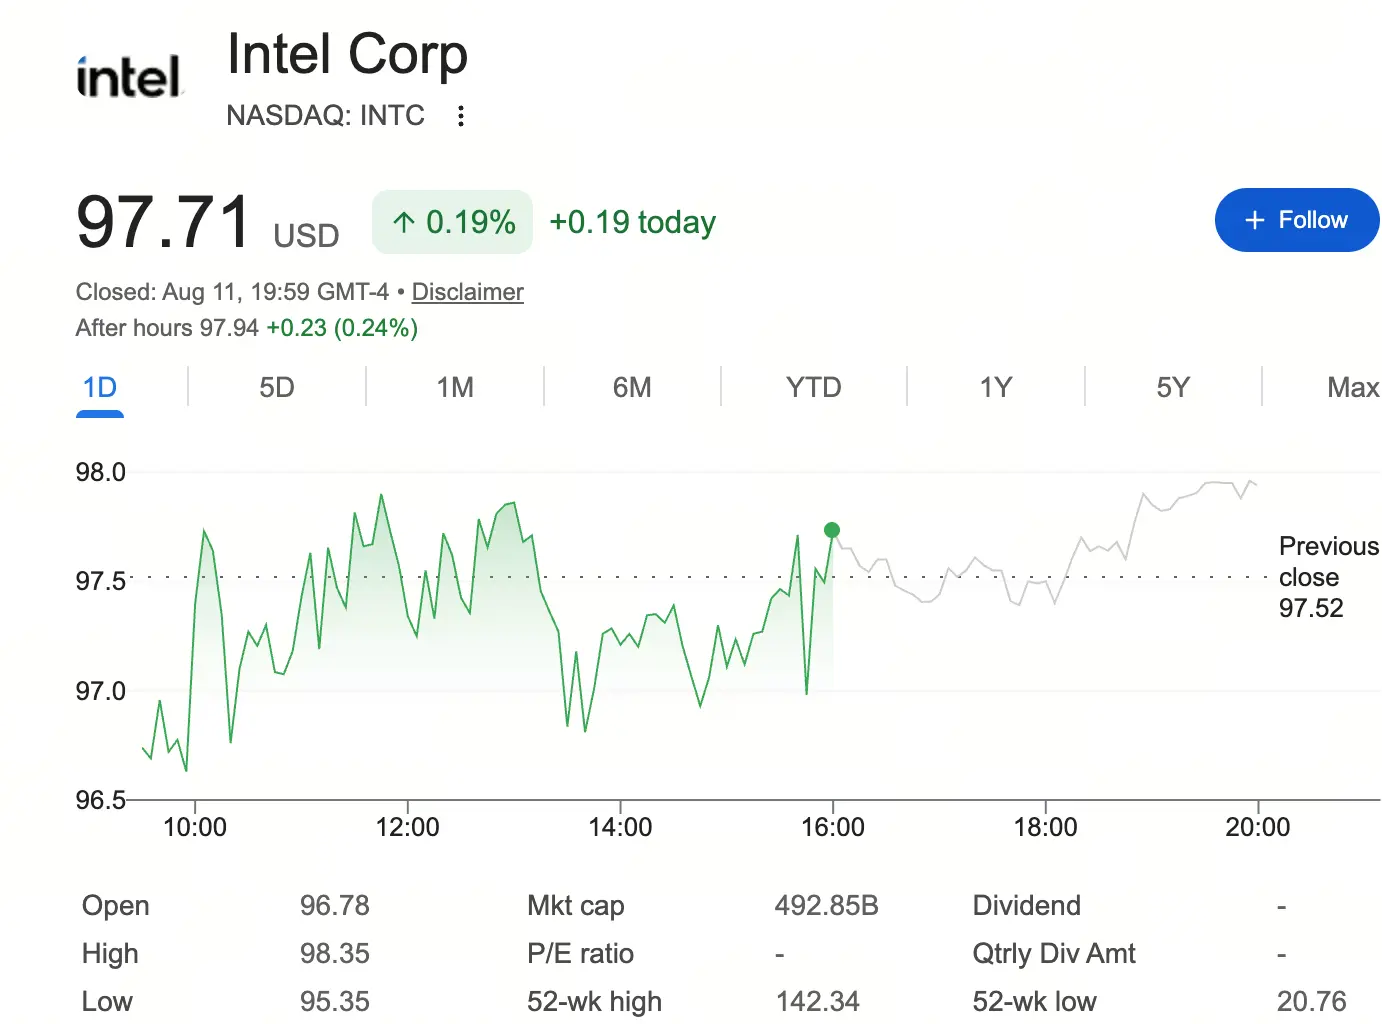
Source: Google Finance
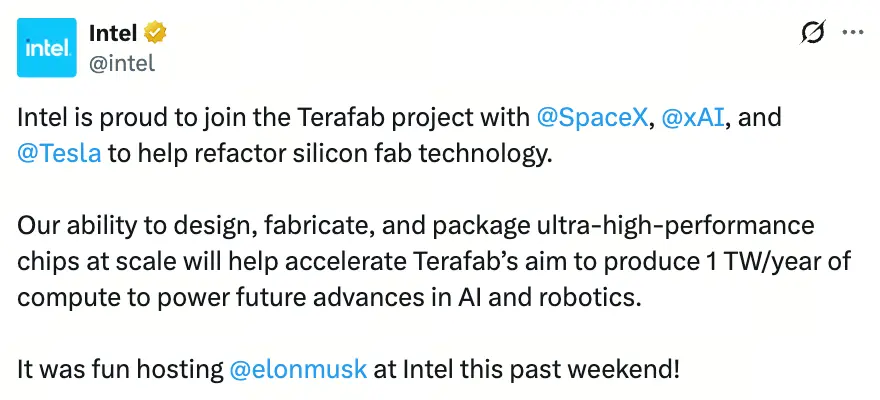
In addition to the layoffs, restructuring, and financial improvements led by CEO Lip-Bu Tan, the Terafab project’s endorsement was one of the most symbolic catalysts behind this rally. In April this year, a photo of Intel CEO Lip-Bu Tan meeting with Elon Musk was made public, and Intel’s official account announced, “We are honored to join the Terafab project and work with SpaceX, xAI, and Tesla to reshape chip manufacturing technology.” Tan commented: “Elon Musk has a proven record of disrupting entire industries, which is exactly what semiconductor manufacturing needs today. Terafab represents a paradigm shift in how logic chips, memory, and packaging are manufactured.”
But the market needs to clarify one point: As of now, Intel and Terafab have not signed a binding long-term commercial contract. SpaceX’s filings have explicitly warned that Terafab’s partners are not obligated to continue pursuing the collaboration, and a final agreement may never be signed. In other words, Musk’s support for 14A currently remains at the framework level rather than representing a confirmed order.
What does this mean for Intel? The answer is: validation, not revenue.
Intel’s foundry business generated only approximately $307 million in external customer revenue for all of 2025, while the foundry division posted a loss of as much as $10.3 billion. Developing and mass-producing the 14A process requires enormous capital expenditures—Intel has raised its 2026 capital expenditure target from $18 billion to more than $20 billion. Without commitments from major external customers, the commercial viability of 14A will remain in question. Musk’s choice has sent precisely this signal to the market: the customer with the most urgent global demand for AI computing power has, at least from a technological standpoint, recognized Intel’s 14A process.
The 14A Process Technology Timeline and Yield Challenges
Intel’s mass-production timeline for the 14A process has been clarified. According to CEO Lip-Bu Tan’s confirmation during the company’s second-quarter 2026 earnings call, risk production for the 14A process is scheduled to begin in the second half of 2027, with mass production targeted for 2028. This is earlier than the previous plan, which called for risk production in 2028 and mass production in 2029.
In terms of technological progress, version 0.5 of the 14A process design kit (PDK) has been made available to customers, while version 0.9 is expected to be released in October 2026. Intel said that 14A has already outperformed 18A in terms of defect density and transistor performance.
But yield remains the most critical variable. Based on calculations using the current defect rate of approximately 0.5 for 14A, the estimated yield for the 114.304-square-millimeter Panther Lake compute die is approximately 56.45%. Intel plans to reduce the defect rate to 0.1 before entering full-scale mass production, raising yield to between 80% and 90%. The leap from 55% to 85% involves systematic optimization of materials, equipment, and process parameters. This requires time for validation and remains subject to uncertainty.
By contrast, consider the progress of TSMC’s 2nm process. TSMC’s customer ecosystem, mass-production experience, and yield-control capabilities in advanced processes remain gaps that Intel will find difficult to overcome in the short term. In 2025, TSMC’s foundry revenue was more than 100 times that of Intel’s foundry division. To achieve a customer breakthrough with 14A, Intel needs more than Musk’s statement—it needs actual orders and a stable yield ramp.
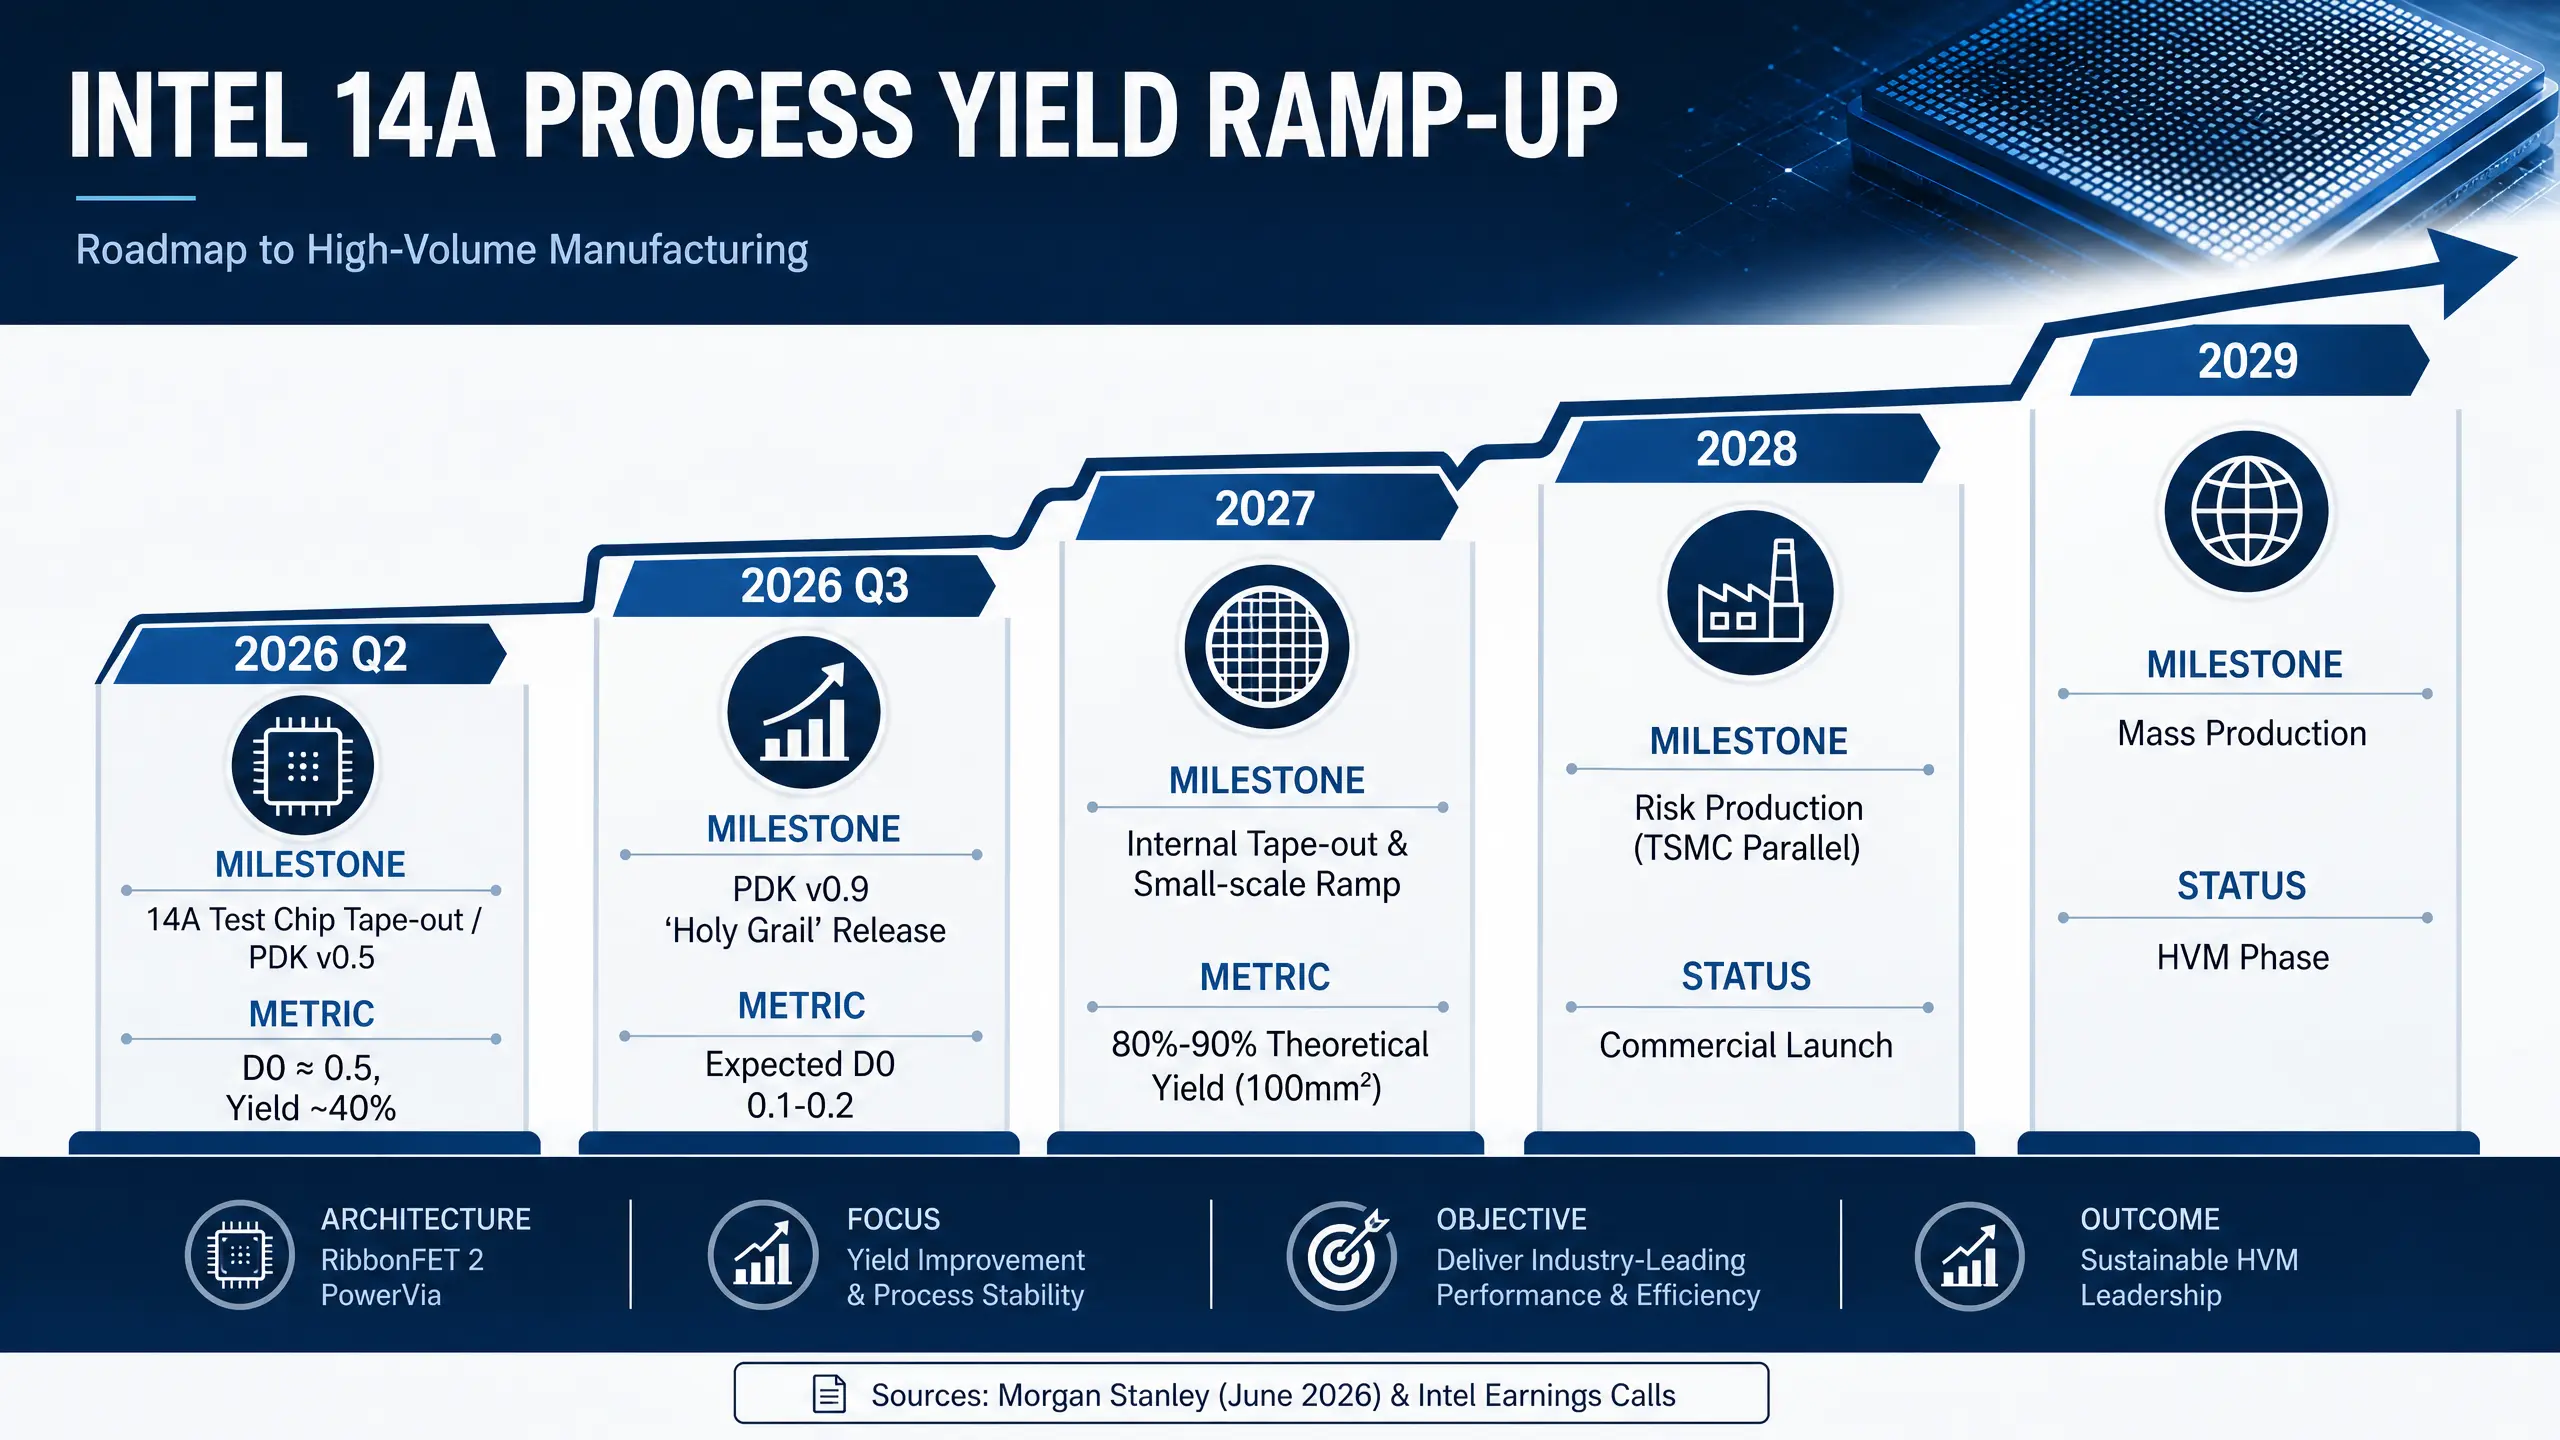
Intel 14A Process Yield Ramp Roadmap
Can Intel’s Improving Fundamentals Support Its Valuation?
Financial data shows that Intel’s fundamentals have indeed improved. Second-quarter 2026 revenue increased 25% year over year to $16.1 billion. Although the foundry business still posted a loss of as much as $2.1 billion, the market is more focused on the improvement trend than on the absolute figure. In the data center CPU sector, Intel has benefited from the expansion of AI inference and agent workloads, with demand for its Xeon processors continuing to grow. In July 2026, HSBC raised its price target for Intel to $200, with one of its core rationales being the positive progress in the data center CPU business and the foundry business being factored back into the valuation.
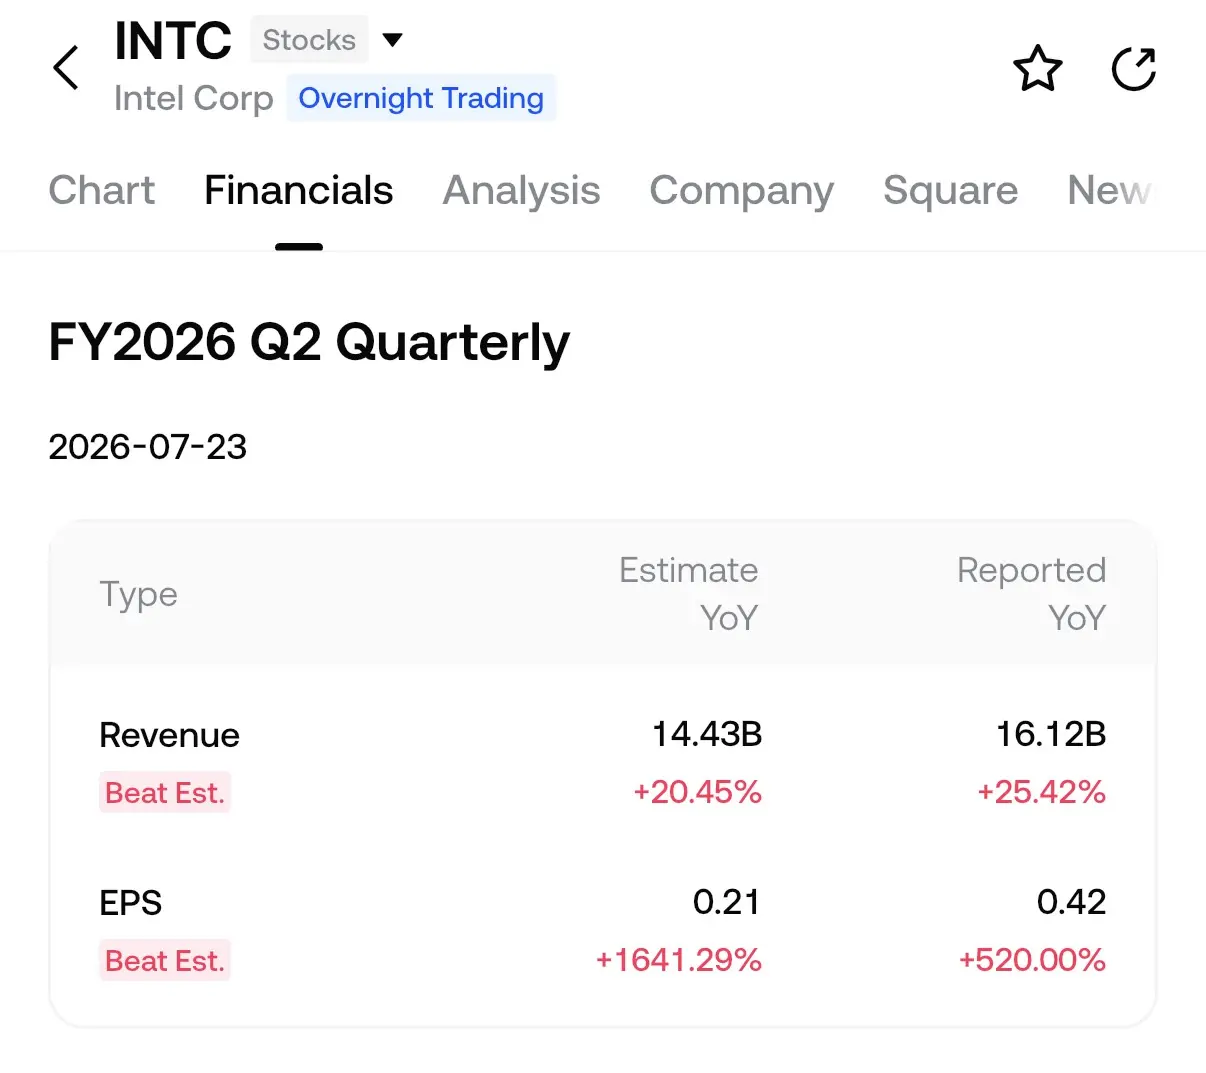
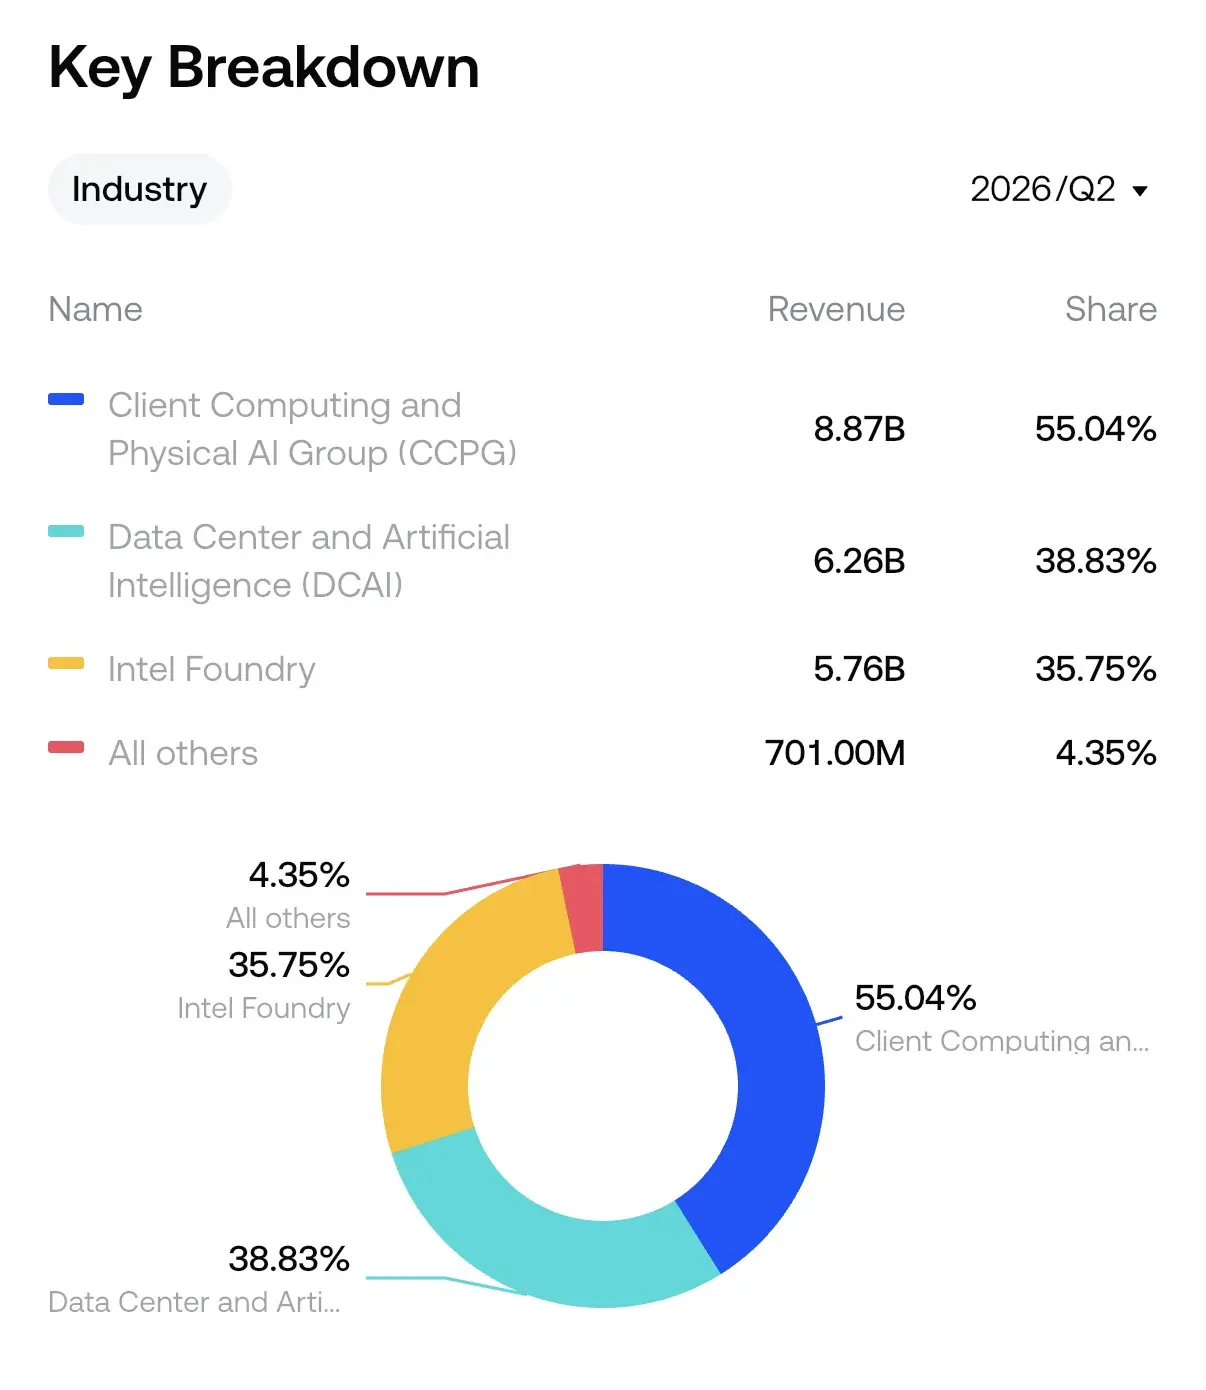
Source: Gate App stock price data; compiled from company financial reports
But the risks embedded in this valuation are equally clear. Wall Street’s views on Intel remain sharply divided: As of July 28, JPMorgan gave the stock a “Sell” rating with a price target of $85, while Bank of America recommended “Buy” with a price target of $160. Signals from the options market have also become more cautious—since the earnings report was released on July 23, the put/call trading volume ratio has climbed to 0.79, while the open interest ratio has reached 1.01, indicating that traders are not sufficiently confident in a short-term rally.
Technically, Intel’s stock price has formed an inverse head-and-shoulders pattern since mid-July, with the left shoulder near $89, the head at $81, the right shoulder near $96, and the neckline at $104. If the closing price moves above the $104 neckline on increased volume, it could open upside targets at $109, $113, and $118. However, if the stock falls below the $96 right-shoulder support, $89 and $81 will become downside defenses.
Conclusion: Strategic Option or Fundamental Inflection Point?
Intel’s current stock-price rally is driven more by the market’s repricing of the strategic value of its AI chip manufacturing business than by the realization of near-term earnings power. Terafab gives Intel an “entry ticket” to the core supply chain of AI infrastructure—it validates the technical feasibility of the 14A process in the eyes of top-tier customers, but there remains considerable distance before this can translate into substantial revenue and profits.
Investors need to focus on three core variables: First, whether the Terafab project evolves from a framework agreement into a formal commercial contract; second, whether the 14A process can complete its yield ramp and achieve mass production as planned between 2027 and 2028; and third, whether the AI capital expenditure cycle can continue to support a valuation premium for advanced-process manufacturing capacity.
If all three factors receive positive validation, Intel’s AI manufacturing narrative will gain fundamental support. Otherwise, the optimistic expectations embedded in the current stock price will face the risk of a correction. For Intel, Terafab’s value lies not in the present moment, but in whether it becomes the first step toward the future.
FAQ
1. What is the initial investment in the Terafab project? What role does Intel play in it?
The initial investment in Terafab is $16.8 billion, jointly funded by SpaceX and Tesla. Intel is Terafab’s technology partner, with its 14A process positioned as the factory’s core manufacturing technology, but the two sides have not yet signed a binding long-term contract.
2. When will Intel’s 14A process enter mass production?
Risk production for the 14A process is scheduled to begin in the second half of 2027, with mass production targeted for 2028. Version 0.5 of the PDK has been made available to customers, while version 0.9 is expected to be released in October 2026.
3. What level is Intel’s stock price currently at?
As of August 12, 2026 Beijing Time, Intel shares were priced at $97.71, with a market cap of approximately $492.85 billion. The 52-week range is $20.76 to $142.35.
4. Why are Wall Street’s views on Intel so sharply divided?
JPMorgan gave Intel a “Sell” rating and an $85 price target, while Bank of America recommended “Buy” with a $160 price target. The disagreement centers on the pace of commercialization of Intel’s foundry business, the mass-production capabilities of the 14A process, and the sustainability of the AI capital expenditure cycle.
5. What is the biggest risk of investing in Intel?
The biggest risks are that the Terafab collaboration fails to translate into substantive orders, that lower-than-expected 14A mass-production yields keep costs elevated, and that a slowdown in AI infrastructure investment could suppress valuations across the entire sector.