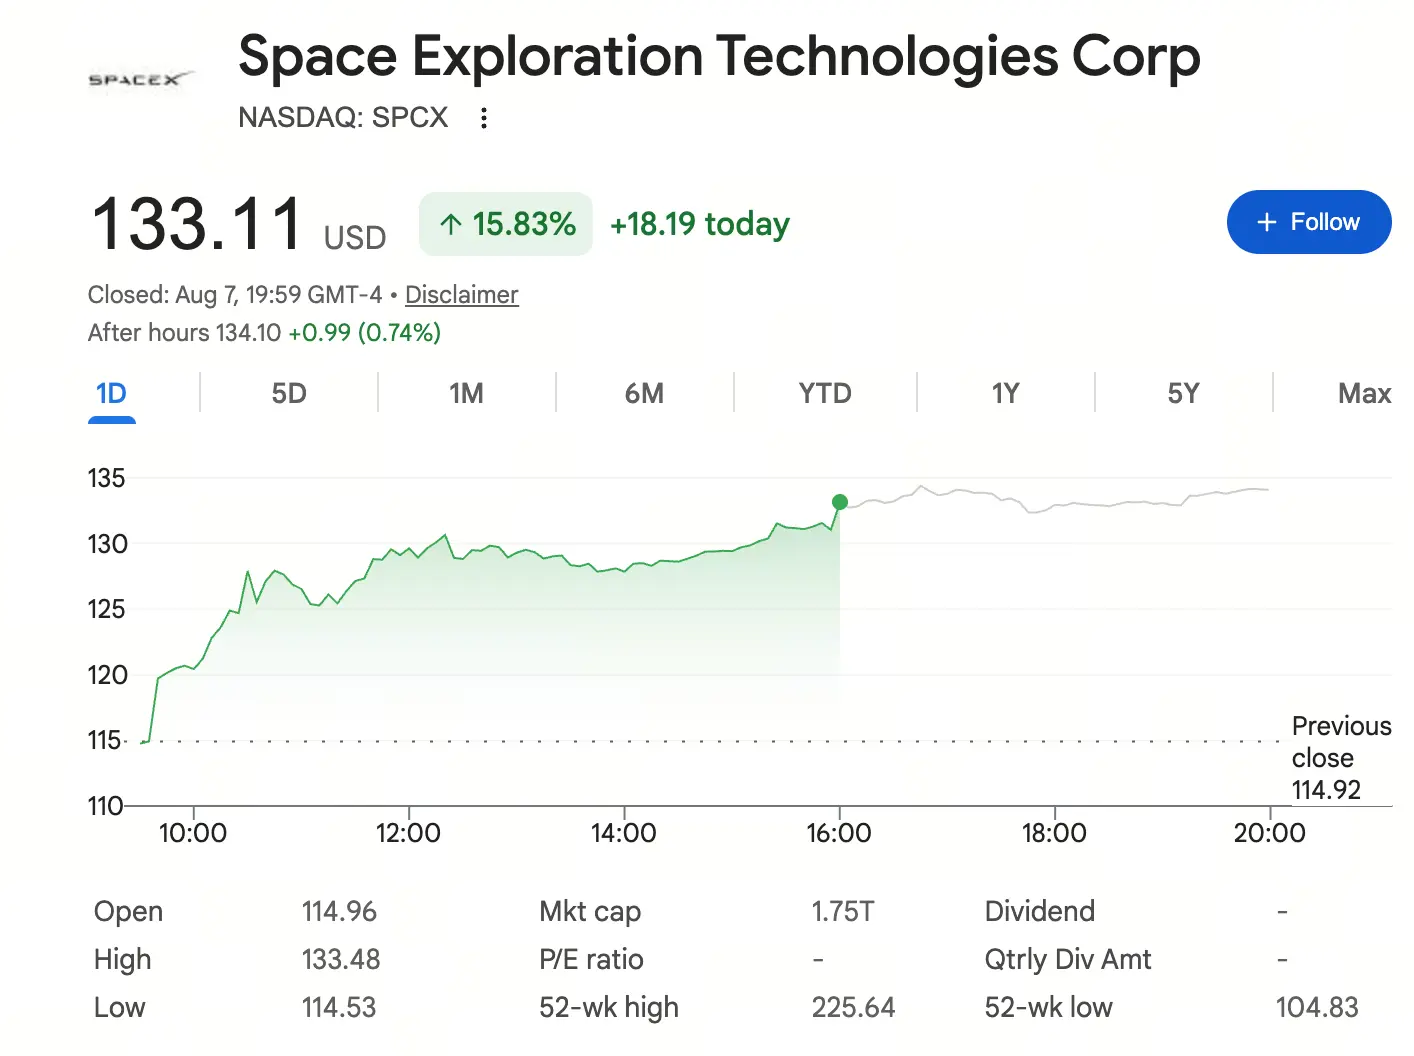
Source: Google Finance
On August 6, Beijing time, SpaceX’s first large-scale post-IPO lock-up period expired. Approximately 911.5 million shares held by insiders became eligible for trading, lifting the company’s free-float ratio from 4.9% to 11.8% and releasing approximately $100 billion worth of shares. Under traditional market logic, a large-scale unlock represents a new supply shock that typically pressures the stock price. But SpaceX followed a completely different trajectory: the stock rebounded about 4% on the day of the unlock and accelerated nearly 16% higher the next day.
Behind this unusual move were a reset in market expectations, solid fundamentals, and converging capital flows.
Why Did SpaceX Stock Rise After the Unlock?
Unlocking risk had already been priced in
SpaceX股价 underwent a deep correction ahead of the unlock. From its all-time high of $225.61 in June to a low near $105 at the beginning of this week, its maximum drawdown over the period exceeded 53%. The core driver of this decline was the market’s preemptive trading around the unlock. Morningstar analyst Nicholas Owens told Yahoo Finance that “the stock market’s recent sharp decline was largely due to expectations that the shares would be diluted.” Once the biggest uncertainty had materialized and actual selling was far below expectations, the market instead chose to refocus on the company’s long-term value.
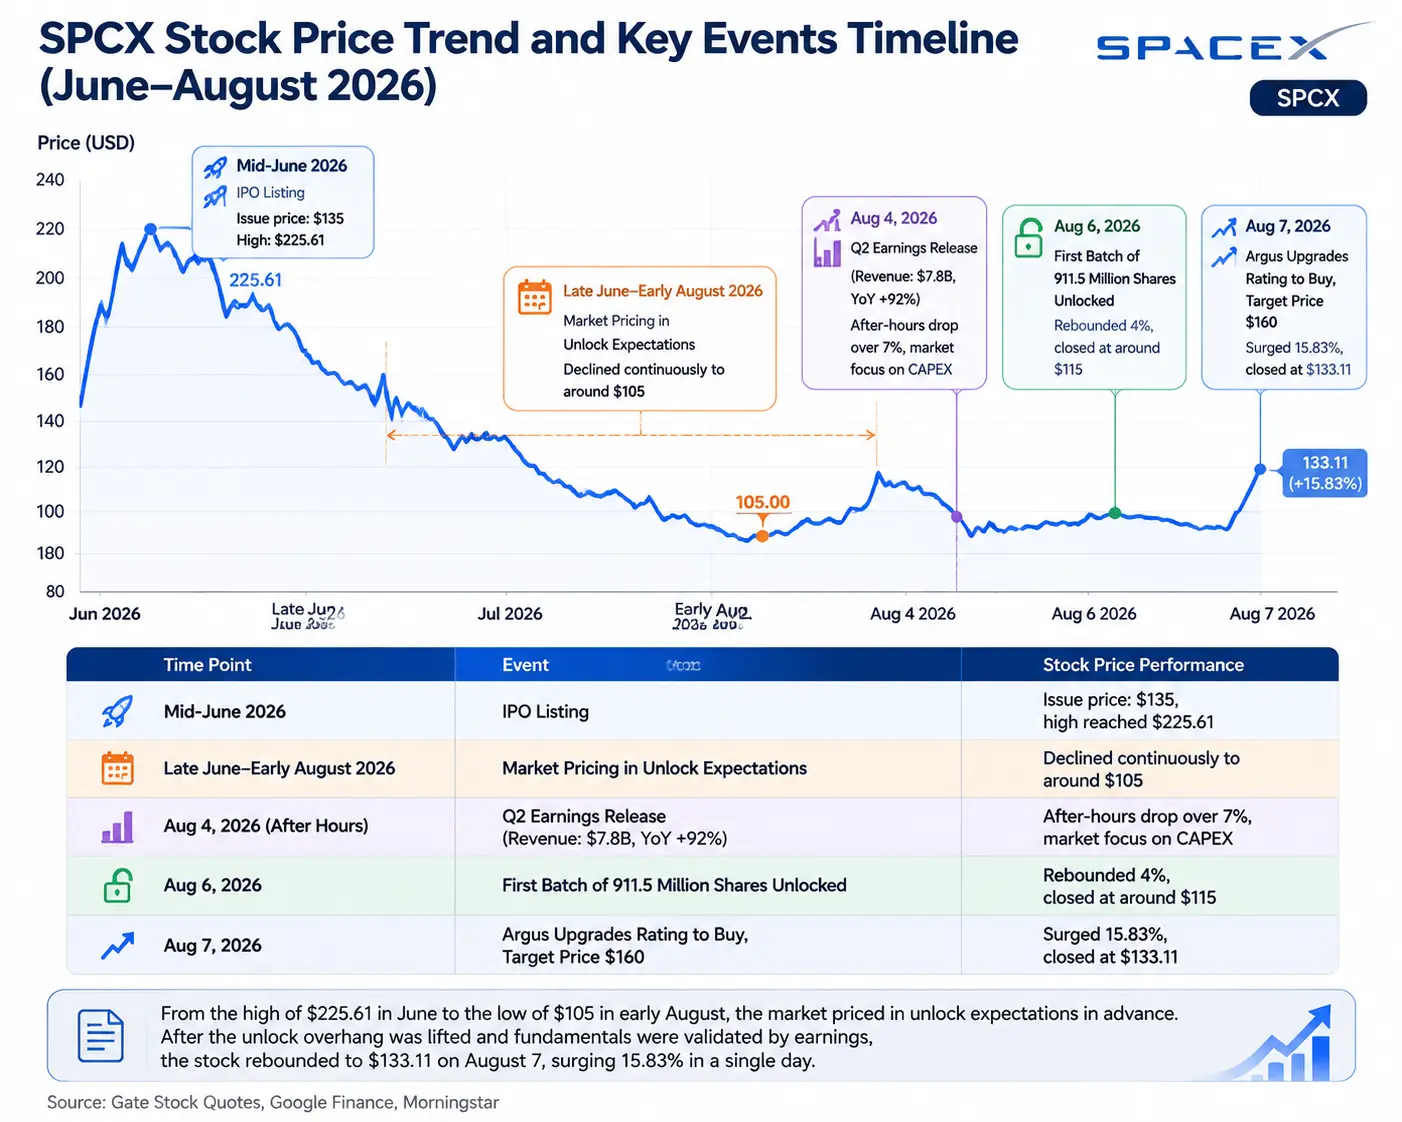
Chart of SPCX price movements and key events
Actual selling pressure was lower than expected
The fact that 911.5 million shares became eligible for trading does not mean they all entered the market. Long-term investors, employees, and early shareholders may choose to continue holding after assessing the company’s fundamentals. In addition, the more than 6 billion shares held by Elon Musk remain subject to lock-up restrictions and cannot be traded until June 2027. The actual new supply entering the secondary market was far below the theoretical amount, prompting the market to reprice the event from “unlocking sell-off risk” to “the unlock releases liquidity and improves market trading efficiency.”
Better-than-expected earnings strengthened investor confidence
The earnings report released ahead of the unlock provided crucial support. The second-quarter 2026 earnings report, released on August 4, showed that the company generated $7.81B in revenue, up 92% year over year and above the market expectation of approximately $6.9 billion. Adjusted EBITDA reached $3.54B, up 191% year over year. Although the company posted a net loss of $541 million for the quarter, that was significantly narrower than the $1.01B loss in the same period last year. At this sensitive moment, when the unlock window opened, strong financial performance gave the market a fundamental reason to “hold rather than sell.”
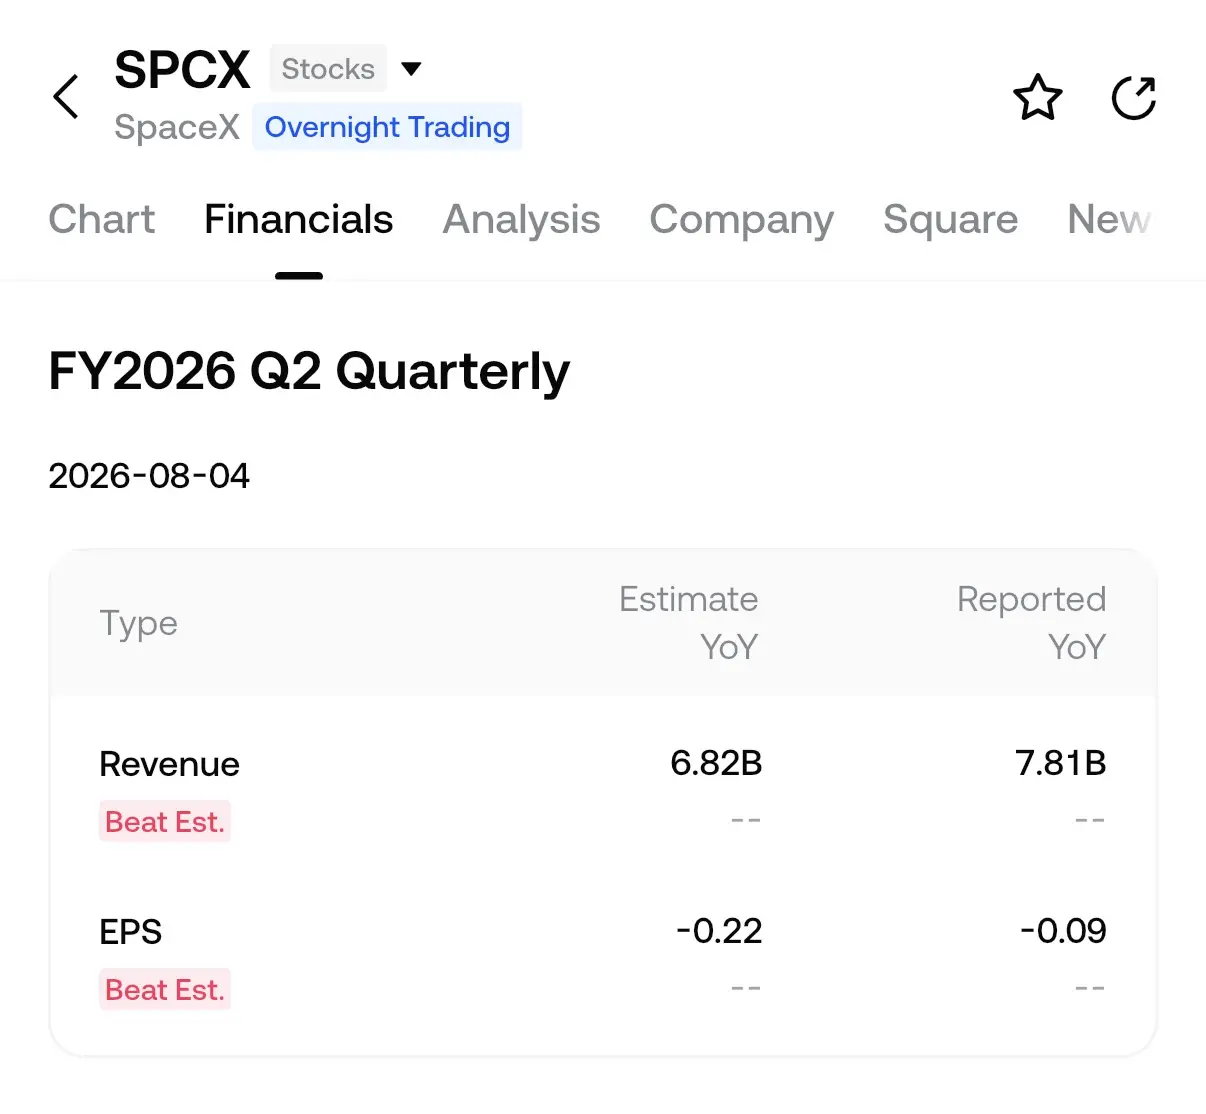
Source: Gate App 股票行情 data; compiled from company earnings data
Higher institutional ratings and renewed capital inflows
On the day after the unlock, Argus analyst Steven Silver raised SPCX’s rating from “Hold” to “Buy” and set a price target of $160, explicitly noting that the company’s heavy investment in AI infrastructure was already beginning to deliver results. The rating adjustment prompted investors to reassess SpaceX’s valuation anchor.
SpaceX’s Core Growth Thesis: Why Is the Market Willing to Assign a High Valuation?
Starlink: Satellite internet enters an accelerated commercialization phase
Starlink is currently SpaceX’s most stable source of revenue and profit. In the second quarter, connectivity business revenue, primarily from Starlink, reached $4.29B, up 66% year over year and accounting for approximately 55% of total revenue. Operating profit reached $1.66B, up 79% year over year, with an operating margin of approximately 38.6%. As of the end of the second quarter, Starlink had 12 million users globally, adding more than 1.7 million net users quarter over quarter—a single-quarter record.
The performance of its enterprise and government business was even more noteworthy. Revenue from this segment reached $1.81B, up 108% year over year, and accounted for more than 40% of connectivity revenue. The Starshield project secured more than $6 billion in multiyear contracts from the U.S. government. In aviation, Starlink signed an important agreement with American Airlines, while services with Southwest Airlines, Virgin Atlantic, and other airlines have also launched. Current market penetration in the aviation sector is only about 10%.
On the earnings call, Musk disclosed an even more ambitious direction: Starlink v3 satellites will have approximately an order of magnitude more capacity than v2, the planned launch volume will also increase by approximately an order of magnitude, and total bandwidth will rise by approximately two orders of magnitude. He expects that “at some point, it is not impossible for Starlink to carry most of the world’s internet traffic… This will not be in the distant future, but within less than 10 years.”
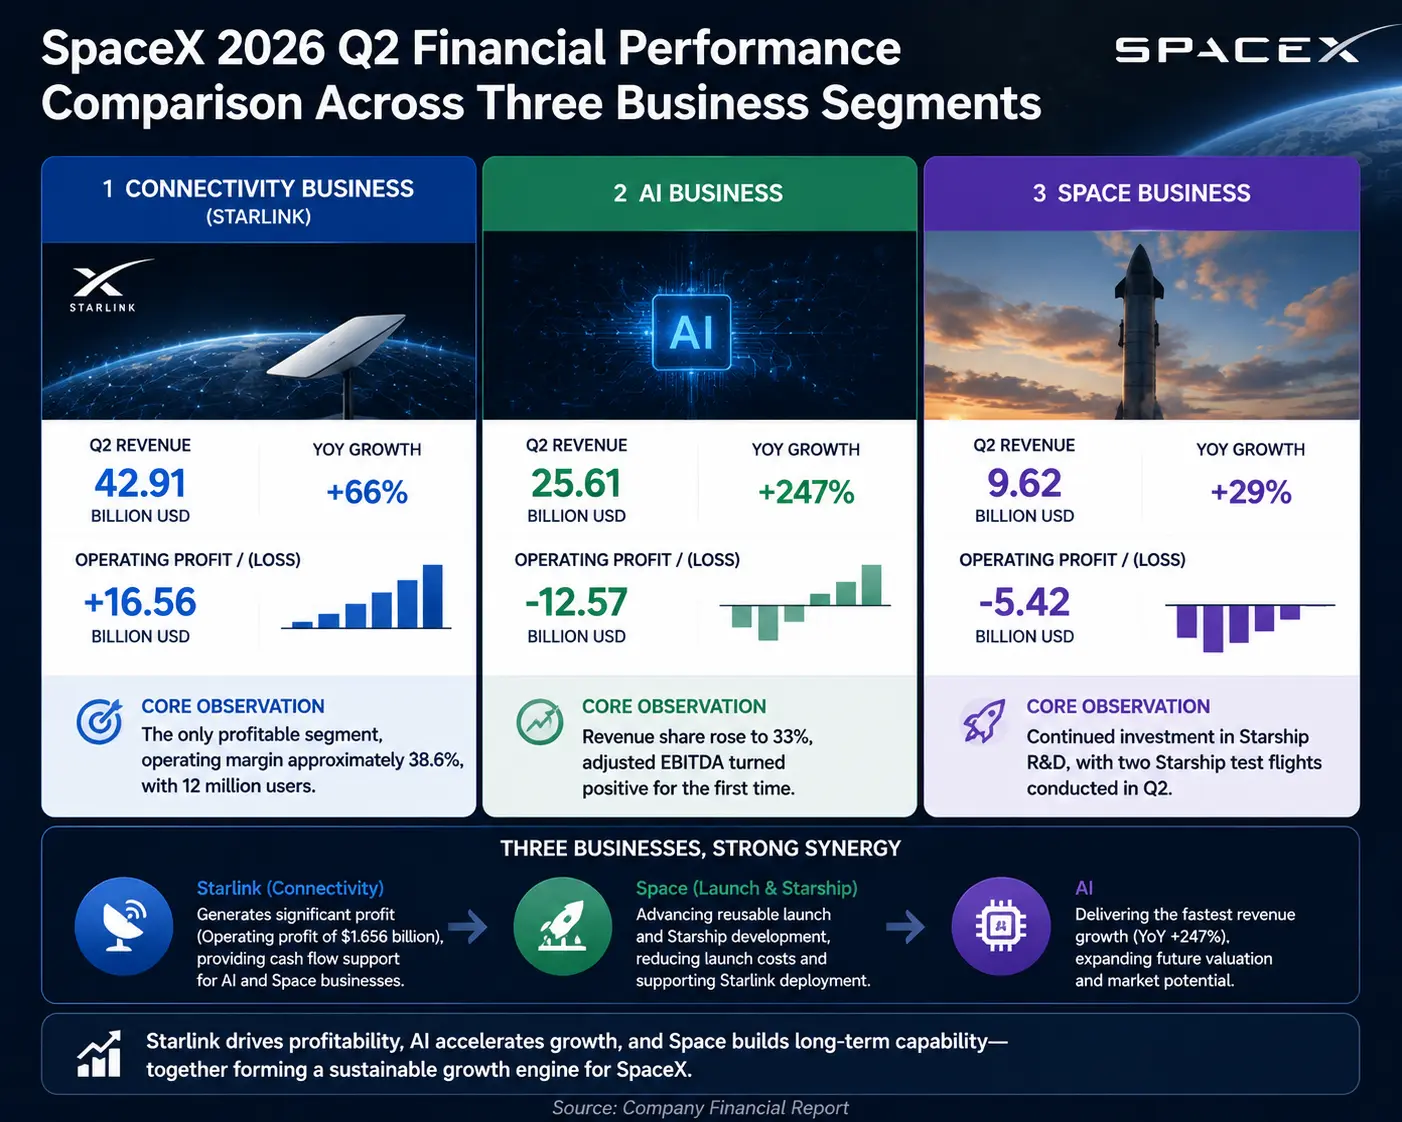
Chart comparing the financial performance of SpaceX’s three major business segments
AI infrastructure: Building a second growth curve
The biggest upside surprise in this earnings report came from the AI business. In the second quarter, SpaceX’s AI business, including xAI, Grok, the X platform, and AI computing infrastructure, generated $2.56B in revenue, up 247% year over year and 213% quarter over quarter, lifting its share of total revenue to approximately 33%. Adjusted EBITDA for the AI business turned positive for the first time, reaching $18.37B.
However, the market’s concerns about the AI business were equally clear. Capital expenditures reached $18.37B during the quarter, of which approximately $15.8 billion was invested in AI computing infrastructure—more than six times the AI business’s quarterly revenue. This enormous capital outlay triggered a more than 7% decline in the stock price after hours.
Musk explained the logic on the earnings call: AI demand is growing 200% annually, and computing prices will rise accordingly. SpaceX will build the world’s largest computing cluster and co-design AI satellite computing payloads for Starlink with NVIDIA, while the Starmind project could begin its first deployments as early as 2027. The core commercial logic is that if Starship significantly lowers the cost of putting payloads into orbit, space could become the next site for next-generation computing infrastructure. AI computing satellites would create substantial internal launch demand for Starship, replicating the industrial cycle of “Falcon 9 launches Starlink, and Starlink supports the rockets.”
As of the end of the second quarter, SpaceX’s nameplate computing capacity reached 1.4 gigawatts, 3.5 times the level of a year earlier. The company has signed cloud service contracts totaling $14.1 billion, generated approximately $1.6 billion in AI infrastructure revenue during the second quarter, and signed an additional $6.7 billion in contracts after the earnings period.
Is SpaceX Stock Worth Buying? What Risks Should Investors Watch?
Bullish factors
In terms of long-term growth potential, global Starlink expansion, growth in the commercial space market, and demand for AI infrastructure are all still in their early stages. SpaceX simultaneously covers the aerospace, communications, and AI infrastructure sectors, with virtually no comparable assets in the market.
On the short-selling side, as of July 29, approximately 219.3 million SPCX shares were sold short, worth $24.6 billion and representing about 34% of the public float. If the stock continues rising, short covering could be triggered, further driving short-term gains.
In the options market, among contracts expiring on August 14, 21, and 28, call-option open interest is concentrated in the $130–$160 range, with the greatest concentration around $150 and $160. Some speculative call positions even reach $200, $250, and $450. The put/call ratio is 0.44, showing that short-term market sentiment is tilted bullish.
Risk factors
High valuation is the core conflict. SpaceX’s current valuation already reflects substantial expectations for future growth. Although revenue growth is strong, second-quarter net loss still reached $541 million, while capital expenditures were 2.35 times revenue. Connectivity business adjusted EBITDA was $2.6 billion, while group capital expenditures during the same period reached $10k, leaving a massive free cash flow gap.
The pressure from subsequent unlocking supply cannot be ignored. The first unlock is only the initial phase. According to the unlock schedule, several more rounds are expected this year: approximately 960 million shares from August through mid-October; approximately 1.28 billion to 1.3 billion shares from late October through early November; and approximately 1.15 billion to 1.2 billion shares on December 8. By December 8, up to 40% of the company’s shares could enter circulation. Whether new demand can continue absorbing this supply will determine whether the stock can hold at higher price levels.
The pace of commercialization remains uncertain. The progress of Starship’s development, whether Starlink can maintain profitability amid a downward trend in prices, and whether its AI infrastructure strategy can generate sustainable revenue contributions are all issues requiring continued validation. Management expects to reach an annual revenue run rate of $100 billion by year-end, with a long-term target of $1 trillion in annual revenue. Internally, the expected timeline has been brought forward from 2031 to 2030. Achieving these figures will require extremely demanding execution.
SpaceX Stock Outlook: Where Is the Upside in August?
Key technical levels
SPCX has broken out of the descending channel in place since mid-June. The next resistance level is near $137.69; above that, $150.98 is the 61.8% Fibonacci retracement level, roughly corresponding to the opening price on the first day of listing. If it breaks above $165.23, the midpoint of the entire decline, it may once again challenge the all-time high of $225.61.
The current RSI is 68.37, just below overbought territory, indicating that the rebound may consolidate briefly before continuing. Immediate support is near $126.88. If the daily close falls below this level, the rally may be delayed, and the stock could retest the pre-unlocking low of $108.09.
Capital flow observations
Increasing call-option open interest, a high short-interest ratio, and expanding trading volume constitute short-term bullish signals. However, the RSI’s proximity to overbought territory and the release of supply from multiple subsequent unlocks are cautionary signals. Trading volume on August 7 exceeded 107 million shares, reflecting intense competition among market participants.
How Should Investors Position Themselves?
Long-term investors should focus on the pace of Starlink’s commercialization, revenue growth trends, and AI infrastructure strategy, paying greater attention to the evolution of the company’s long-term value rather than price fluctuations after a single unlocking event.
Short-term traders can monitor changes in trading volume after the unlock, technical breakout levels, and the direction of options capital, but should beware of the risk of a pullback after the RSI becomes overbought.
Investors with lower risk tolerance may wait for a valuation adjustment, validation from subsequent earnings reports, and further realization of revenue from new businesses before making a decision.
SpaceX’s rise was not simply an unlocking rally, but the result of the market repricing its long-term value after the company delivered quarterly revenue of $7.8 billion. In the short term, the stock remains affected by subsequent unlocking supply and high-valuation pressure; in the long term, Starlink’s global expansion, the cost revolution in commercial spaceflight, and the deployment of AI infrastructure in space could become the core drivers of continued growth in SpaceX’s valuation.
For investors, the key is not predicting where a single rally will end, but assessing a fundamental question: Can SpaceX grow from a leading aerospace company into a next-generation global infrastructure platform?
FAQ
1. Why did SpaceX stock surge after the unlocking?
The market had already priced in the risk of an unlocking sell-off, with the stock falling from a high of $225.61 to around $105, representing a maximum drawdown of more than 53%. After the actual unlocking, insider selling was far below expectations. Combined with fundamental support from second-quarter revenue of $7.8 billion, up 92% year over year, and a capital-market catalyst from institutions including Argus raising their ratings to Buy with a $160 price target, multiple factors drove the stock to rebound against the broader trend.
2. How large is SpaceX’s AI business now?
In the second quarter of 2026, SpaceX’s AI business generated $18.37B in revenue, up 247% year over year and 213% quarter over quarter, accounting for approximately 33% of total revenue. Adjusted EBITDA turned positive for the first time at $4.29B. The company has signed cloud service contracts totaling $14.1 billion, invested $15.8 billion of second-quarter capital expenditures in AI infrastructure, and reached 1.4 gigawatts of nameplate computing capacity.
3. What unlocking pressure remains for SpaceX?
After the first unlocking, three major unlocking rounds remain in 2026: approximately 960 million shares from August through mid-October, approximately 1.28 billion to 1.3 billion shares from late October through early November, and approximately 1.15 billion to 1.2 billion shares on December 8. By December 8, up to 40% of the company’s shares could enter circulation. The lock-up period on Musk’s more than 6 billion shares lasts until June 2027.
4. Is SpaceX’s current valuation already too high?
SpaceX’s current valuation already reflects substantial expectations for future growth. Although second-quarter revenue was $7.8 billion, up 92% year over year, net loss was $541 million and capital expenditures of $18.369 billion were 2.35 times revenue. There is a massive gap between connectivity business EBITDA of $2.6 billion and capital expenditures. Investors need to continue tracking whether revenue growth can keep pace with valuation expansion.
5. What is the latest development in the Starlink business?
Starlink users reached 12 million in the second quarter, with a record quarterly net increase of 1.7 million users. Connectivity business revenue reached $4.291 billion, up 66% year over year; enterprise and government revenue grew 108% year over year and accounted for more than 40% of connectivity revenue. Starlink v3 satellite bandwidth is expected to increase by approximately 100 times, and Musk expects Starlink could carry most of the world’s internet traffic within less than 10 years.