STONKBROKER’s significance lies in its role as the unified settlement asset spanning multiple products. NFT purchases fuel token demand, activation fees trigger token burns, ecosystem pairs expand its application scenarios, and protocol revenue is influenced by the token price. As such, STONKBROKER’s tokenomics aren’t an independent issuance structure; they are fundamentally the engine of the entire StonkBrokers cycle.
Assessing STONKBROKER’s value requires more than simply tracking burn or trading volume. Its economic sustainability hinges on several factors: supply structure, external asset revenue, token-denominated fees, NFT turnover rate, liquidity depth, and future issuance schedule.
Key Points
- Primary demand for STONKBROKER originates from Broker NFT purchases, activation, liquidity, and ecosystem pairings.
- 50% of activation fees are burned, but this burn has lasting impact only if driven by continual real-world usage.
- Over the past 30 days, fees totaled roughly $1.89 million, with about $1.28 million in token-denominated activation fees.
- FDV exceeds circulating market cap; future prices will be shaped by remaining supply, liquidity, and ecosystem engagement.
What Is STONKBROKER
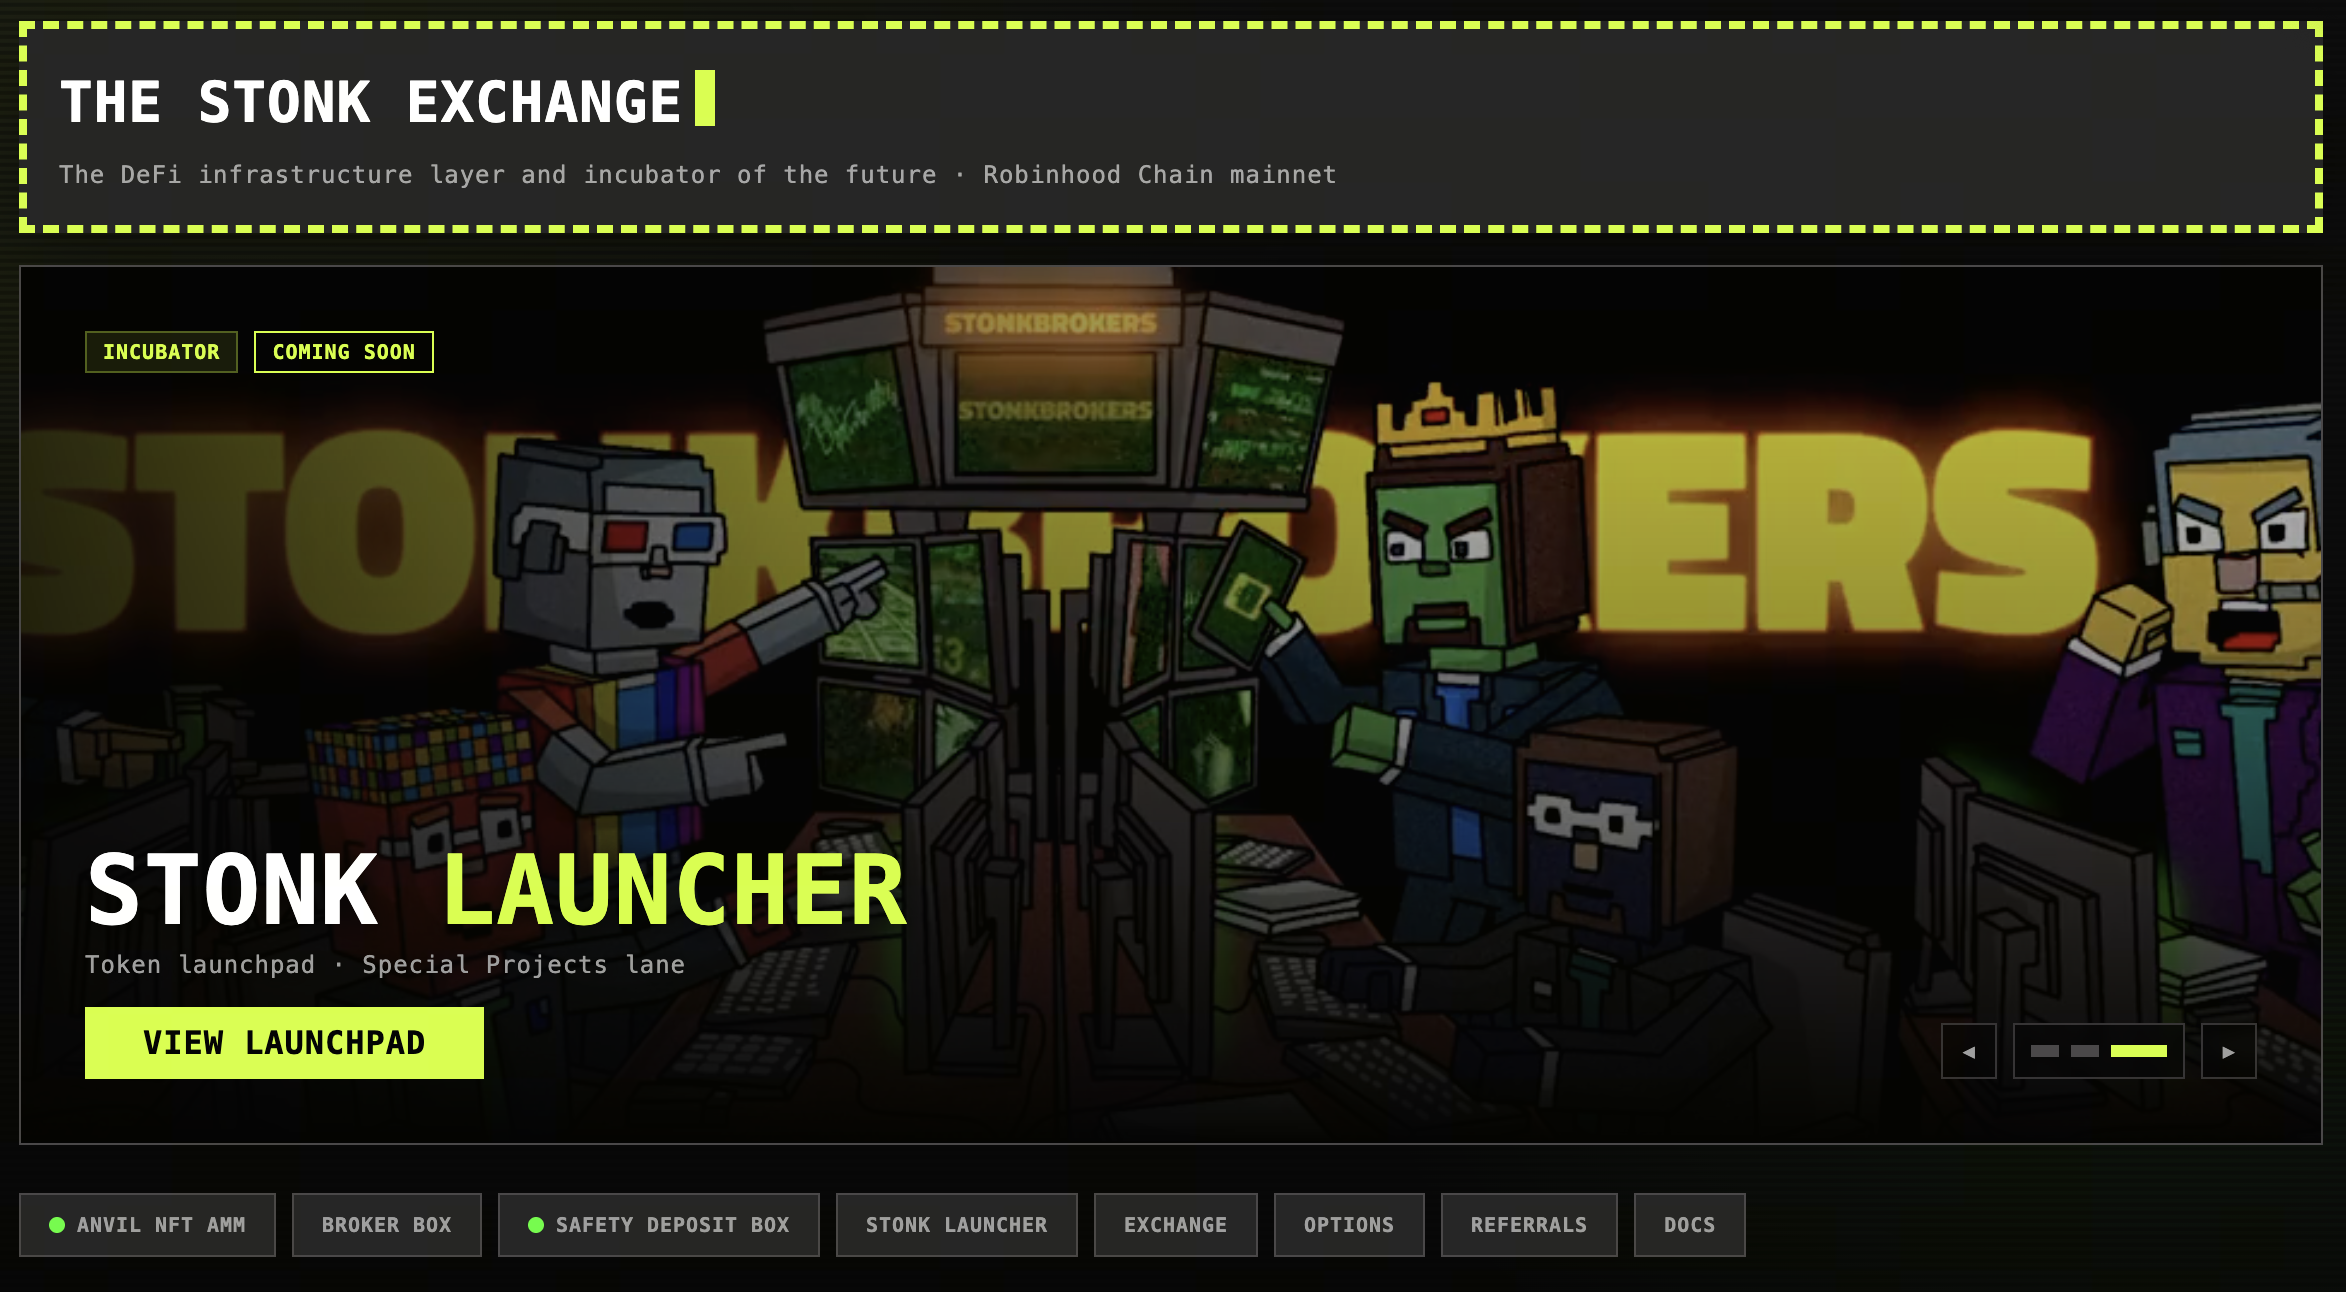
STONKBROKER serves as the coordination token for both function and value within the StonkBrokers ecosystem. It does not represent Robinhood equity nor is it the Robinhood Stock Token.
STONKBROKER’s primary roles include:
- Quotation and settlement asset for NFT AMMs
- Activation fee payment for Broker NFTs
- Ecosystem project pairing asset
- Liquidity and DEX trading asset
- Partial governance and fee routing
- Base asset for the prospective Launcher ecosystem
Notably, demand for STONKBROKER stems mainly from within the protocol, distinguishing it from tokens driven by external payments or traditional business revenue. Product activity therefore exerts a direct influence on token value.
Main Uses of STONKBROKER
Buying Broker NFTs
The Anvil NFT AMM prices Broker NFTs with a fixed amount of STONKBROKER—according to the official docs, the base price is 666,666 STONKBROKER, plus an additional ETH fee.
Activating Broker NFTs
Token holders must pay varying amounts of STONKBROKER to unlock stock token rewards, with higher-level activations requiring more tokens and offering greater allocation weight.
Providing Liquidity
STONKBROKER liquidity pools are live on Uniswap V3, Uniswap V4, and Up V3 on Robinhood Chain.
Supporting Ecosystem Projects
Certain Special Projects are required by the roadmap to establish STONKBROKER liquidity pairs at launch. While use by the Launcher could increase token demand, it may also expose STONKBROKER to heightened price risk from new projects.
Governance Within the Ecosystem
STONKBROKER is linked to Stonk Exchange fees and liquidity routing. However, governance scope, voting power, and execution ultimately depend on contract specifics, which require ongoing evaluation.
Token Supply Structure
CoinGecko data as of audit time:
| Metric |
Value |
| Circulating supply |
~1.573 billion |
| Total supply |
~2.717 billion |
| Circulation ratio |
~57.9% |
| Circulating market cap |
~$40 million |
| FDV |
~$69 million |
| Market Cap/FDV |
~0.58 |
Roughly 1.143 billion tokens are flagged as reserved. Critical valuation factors include whether and when the remaining supply is unlocked, for what purpose, and if it may reach the market.
FDV is not a guaranteed future market cap, but a theoretical valuation under total supply circulation. Rapid market entry of the remaining tokens, without proportional demand growth, may dilute token price per unit.
Impact of Activation Fee Burns on Supply
Broker NFT activation and upgrade fees are allocated 50/50:
- 50% burned permanently
- 50% retained by the protocol
Burns decrease on-chain supply, creating theoretical scarcity for holders. The long-term effectiveness of burns, however, depends on:
- Whether burns consistently exceed new token issuance to circulation
- If burns are driven by genuine user engagement, not short-term speculation
- Whether retained protocol tokens are reintroduced to the market
If NFT activity slows, activation demand and burn rate decline. Should the protocol sell retained tokens to fund operations, burn-induced scarcity may simply be offset by new sell pressure.
Thus, burning alone is not an automatic value driver—it is an outcome of actual product usage impacting supply.
StonkBrokers’ Revenue Sources
According to DefiLlama, project revenue breaks down as follows:
- ETH transaction fees from NFT AMM
- STONKBROKER activation and upgrade fees
- NFT collateralized lending fees
- 1% application fee from Swap Desk
- Broker Box spreads and voucher fees
- Fees for liquidity locking
As of August 13, 2026, last 30-day data from DefiLlama:
| Revenue category |
Est. value |
| Total fees |
~$1.89 million |
| Protocol revenue |
~$1.45 million |
| Activation fees |
~$1.28 million |
| NFT AMM fees |
~$567,000 |
| Swap Desk fees |
~$27,600 |
| Liquidity locking |
~$11,200 |
| NFT lending/other |
Minimal |
Activation fees account for the lion’s share of revenue, significantly outpacing lending, Broker Box, and liquidity locking.
Protocol Revenue vs. Real Cash Flow
Protocol revenue does not equal liquid cash flow for salaries or operating costs.
STONKBROKER activation fees can be valued in USD at market rates, but their value fluctuates with token price. If protocol-held STONKBROKER can’t be sold without price impact, reported income may overstate actual liquidity.
Revenue falls into three types:
- External asset revenue (e.g., ETH, USDC)
- Native token revenue (STONKBROKER activation fees)
- Holder value (burned STONKBROKER)
External asset revenue is closest to traditional cash flow. Native token income is highly liquidity-dependent. Burns are only latent value capture and do not fund operations.
DefiLlama’s annualized figures extrapolate from recent activity, which can overstate long-term stability in early-stage or highly volatile projects.
Interpreting Market Cap and FDV
Circulating market cap: current price × circulating supply
FDV: current price × total supply
STONKBROKER’s current market cap/FDV is about 0.58—implying approx. 42% of theoretical supply is not yet counted in the circulating market cap.
For valuation, compare:
- Circulating market cap to protocol external asset revenue
- FDV to total protocol income
- Holder burn value
- Release plan for the remaining tokens
- DEX liquidity
- Continued NFT and Launcher usage
Use protocol revenue multiples with caution—most revenue is denominated in STONKBROKER, so price growth can artificially inflate both income and market cap, potentially masking underlying fundamentals.
Key Price Drivers for STONKBROKER
Broker NFT Demand
Buying NFTs requires STONKBROKER. Rising floor prices or higher NFT turnover expands token demand.
Activation/Re-activation Needs
NFT transfers reset activation status, so new owners must pay tokens again. Vibrant secondary markets drive both activation demand and token burns.
Stonk Launcher Rollout
If new projects require STONKBROKER for trading pairs, Launcher adoption could broaden liquidity use cases—subject to project quality and capital inflows.
Protocol Fee Growth
Greater external asset fee inflows improve revenue quality and reduce dependence on native token economics.
Robinhood Chain Activity
STONKBROKER’s core markets and products are on Robinhood Chain. Growth in users, assets, and liquidity influences the ecosystem’s growth trajectory.
Market Narrative
NFTs, RWAs, stock tokens, and Robinhood Chain enjoy compelling narratives. Prices may move ahead of launches and become volatile around product rollouts.
Principal Risks for STONKBROKER
Uncirculated supply risk: Substantial supply remains locked; ongoing monitoring of release mechanics is critical.
Native token revenue risk: Activation fees fluctuate with STONKBROKER price and cannot be viewed as stable USD income.
Liquidity risk: Most trading occurs on DEXes on a nascent chain; large orders may face serious slippage or illiquidity.
Demand concentration risk: Broker NFT purchase and activation dominate token utility; waning NFT interest impacts usage.
Product delivery risk: Launcher, Options, and some modules remain unreleased.
Smart contract risk: STONKBROKER interacts with NFT AMM, lending, staking, and Launcher contracts, heightening composability risks.
Base chain risk: Stability and infrastructure on Robinhood Chain and cross-chain support are ecosystem-critical.
Legal risk: Use of stock tokens and financial modules could invite a range of regulatory approaches.
Price reflexivity risk: Token rallies inflate NFT USD prices and activation revenue, fueling speculation; downturns risk negative feedback loops.
Tracking STONKBROKER Over Time
Key metrics to monitor include:
- Circulating and burned STONKBROKER volumes
- Reserve address balance changes
- Protocol-retained vs. burned activation fee ratios
- Weekly NFT sales and repeated activations
- External asset fee proportion of total revenue
- Key DEX pool depth
- 30-day protocol fees/revenue (DefiLlama)
- Actual Launcher issuance and graduation rates
- Robinhood Chain user counts and stablecoin volume
- Contract upgrades, audits, and admin authorization changes
STONKBROKER’s long-term value is dependent on ongoing external user-generated fee income—not one-off token burns. Reliance on native token revenues creates a reflexive, procyclical feedback loop; greater ETH, USDC, and real transaction fees create economic sustainability.
Conclusion
STONKBROKER’s value isn’t simply about burns or short-term market hype—it is fundamentally aligned with sustained growth in StonkBrokers ecosystem demand. As a central medium for Broker NFT purchase, activation, liquidity pairing, and future products, STONKBROKER links NFTs, stock tokens, and on-chain financial modules, enabling a usage-driven economic model.
Token burns alone do not assure price appreciation. While 50% activation fee burns reduce supply, their long-term effect depends on balancing NFT engagement, user demand, and new token supply. Currently, most protocol revenue is earned via STONKBROKER-denominated activation fees, whose value depends on token price and liquidity; this is not equivalent to cash flow at a traditional business.
Comprehensive STONKBROKER valuation requires tracking circulating supply, FDV, token release schedules, protocol external revenue, NFT trading activity, DEX liquidity, and future product rollouts. If StonkBrokers keeps attracting real users and generates meaningful external asset revenue via NFTs, stock tokenization, and Launchpad, STONKBROKER’s economic model could strengthen. If on the contrary, demand relies on token price performance and internal cycling, the system may face pronounced reflexivity risks.
Broadly, STONKBROKER represents an emerging model for on-chain assets: tokens are evolving from pure governance or speculation vehicles into essential infrastructure for NFTs, RWAs, DeFi, and TradFi products. Its long-term value will ultimately be defined by the ecosystem’s ability to transition from “token-driven” to “utility-driven” demand.