Gate Pre-IPOs, traditional IPO participation, and pre-market trading are three different routes, not three names for the same early-access trade. Gate Pre-IPOs uses a Mirror Note product on Gate, traditional IPO participation seeks actual issuer shares through broker or underwriter channels, and pre-market trading usually refers to market-session execution in already listed shares.
This comparison uses Gate Pre-IPOs as the reference product path because it is the clearest example in the current Moonshot AI (KIMI) theme. Readers who need the full product mechanics can first review the Gate Pre-IPOs Moonshot AI (KIMI) overview. Readers who want only the operational flow can continue with How to subscribe to Moonshot AI (KIMI).
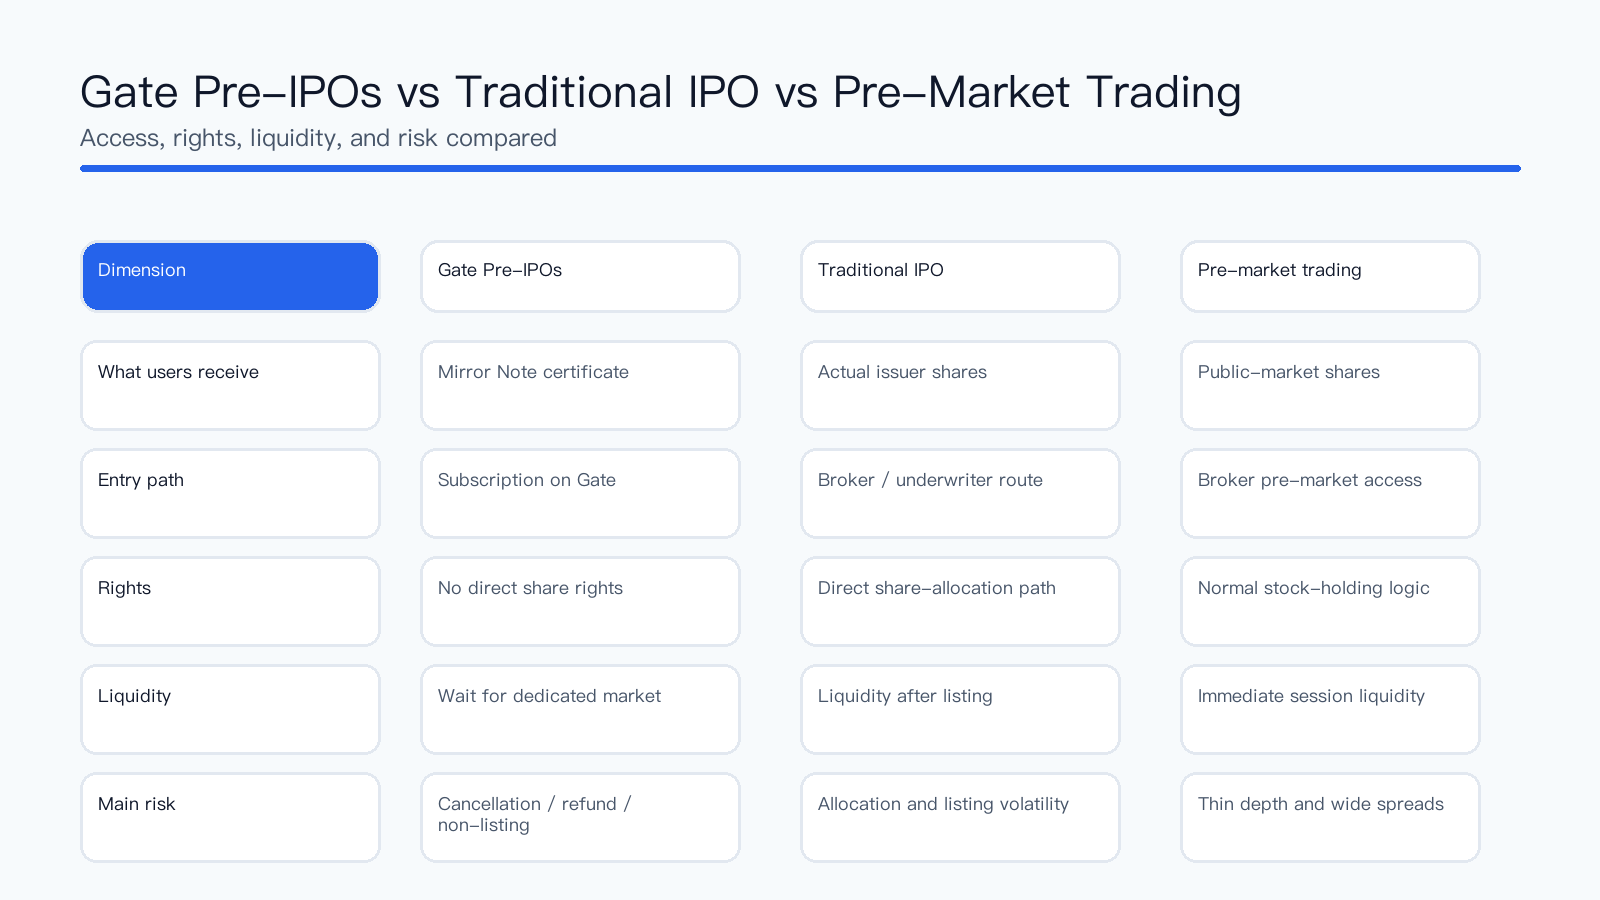
Figure 1. This matrix compares instrument type, legal rights, liquidity timing, and route-specific risks across the three paths.
Key takeaways
- Gate Pre-IPOs gives users a platform-based Mirror Note product rather than direct issuer shares.
- Traditional IPO participation usually provides a path to real share allocation through regulated broker or underwriter channels.
- Pre-market trading usually refers to market-session trading around listed equities, not a pre-listing Mirror Note structure.
- Liquidity, legal rights, refund rules, and downside scenarios differ enough that one route should not be evaluated with another route's assumptions.
What is Gate Pre-IPOs, and how is it different at the product level?
Gate Pre-IPOs is a launch-style channel on Gate that offers pre-listing value-tracking products such as Moonshot AI (KIMI). In the Moonshot AI announcement, Gate defines KIMI as a Mirror Note and says it does not represent actual stocks or shares in Moonshot AI. That one sentence already separates the path from a traditional broker IPO allocation.
The product is therefore a platform-issued structure tied to a target company's value path rather than direct share ownership. It may include subscription windows, pool-specific rules, dedicated secondary-market trading, carry, and refund triggers. The route is accessible through a crypto-platform workflow rather than a traditional brokerage-bookbuilding workflow. For investors comparing early-stage companies, this difference is important because the product can offer access to private-company exposure without offering the same legal rights that come with public shares.
What is traditional IPO participation?
Traditional IPO participation usually means entering a broker, bank, or underwriter-linked allocation process for actual shares in a company that is about to list on a public exchange. Investors submit interest under the broker's rules, and successful allocation leads to actual listed shares rather than a value-mirroring note.
That route is usually narrower in access and often depends on jurisdiction, broker relationships, account status, and offering rules. Allocation can still be limited or uncertain, but the legal object is fundamentally different from a Mirror Note. The investor is seeking actual issuer shares when the listing process completes, and the company is making a public offer that can lead to normal exchange trading once the IPO is done.
What is pre-market trading?
Pre-market trading usually refers to trading during a pre-open market session for already listed equities or newly listed shares around exchange trading hours. It is a market-session concept rather than a structured pre-listing note concept. Liquidity can be thinner, spreads can be wider, and participation depends on the broker and market involved.
That means pre-market trading is not a synonym for pre-IPO access. A user trading in a pre-market session is usually interacting with a listed security in a time window outside regular market hours, not subscribing to a pre-listing instrument whose terms may include refunds, carry, or cancellation triggers. The trade can still involve fast price changes, thin books, and a need for investors to check whether the market really offers enough depth before entering an investment decision.
Gate Pre-IPOs vs traditional IPO vs pre-market trading: side-by-side comparison
Gate Pre-IPOs, traditional IPO access, and pre-market trading all sit near the listing timeline, but the investor relationship changes in every column. The table below highlights the main distinctions.
| Dimension |
Gate Pre-IPOs |
Traditional IPO |
Pre-market trading |
| Core instrument |
Mirror Note / asset certificate |
Actual issuer shares if allocated |
Trading session for listed shares |
| Legal relationship |
No direct issuer share ownership |
Direct share allocation path |
Standard market trading in a special session |
| Entry path |
Platform subscription on Gate |
Broker / bank / underwriter channel |
Broker-enabled market session |
| Timing |
Before listing |
Around the formal listing process |
Before regular market open on trading days |
| Liquidity path |
Dedicated secondary market may open later |
Liquidity usually starts after listing |
Liquidity depends on session depth |
| Refund or cancellation rules |
Product-specific and may include refunds |
Broker or offering rules apply |
Standard trade execution rules apply |
| Profit sharing / carry |
May exist under product terms |
Not typically a carry model |
No carry structure; normal trading economics |
| Key educational risk |
Confusing note exposure with stock ownership |
Confusing indication of interest with guaranteed allocation |
Confusing thin-session price action with normal market depth |
The most useful reading method is to start with the first row and ask what users actually receive. If the answer is not "actual shares," then the route should not be evaluated as if it were standard IPO allocation. That simple check helps investors compare companies more carefully and keeps a private-company access offer from being confused with a public-share trade.
How do access, rights, and liquidity differ?
Access differs first. Gate Pre-IPOs uses a platform-based subscription flow with stablecoin funding and product-specific eligibility. Traditional IPO access usually depends on a regulated broker relationship and often tighter qualification rules. Pre-market trading usually requires a brokerage feature that allows execution outside standard market hours. Investors should therefore check not only whether a company is interesting, but also what channel actually offers access to the company, what investment rules apply, and whether that route supports the kind of trade they expect to make.
Rights differ second. Traditional IPO allocation can lead to actual listed shares. Gate Pre-IPOs Moonshot AI (KIMI) does not, according to Gate's own disclaimer. Pre-market trading also involves actual tradable listed shares, but only after the security is already in a public-market framework.
Liquidity differs third. Gate Pre-IPOs may postpone tradability until a dedicated secondary market opens. Traditional IPO liquidity usually begins after the public listing. Pre-market liquidity exists only within that session and can be thinner than normal-hours liquidity, with wider spreads and less stable depth. For investors, that means the same company can show very different price behavior depending on whether the route is a private-company product, a public-share IPO, or a pre-market trade after listing.
Which risks are unique to each route?
Gate Pre-IPOs carries product-structure risk. Users face listing uncertainty, cancellation or ROFR-trigger refund paths, secondary-market timing uncertainty, and the possibility that the note's reference value changes because of share issuance, splits, or company outcomes. Those are in addition to normal market risk.
Traditional IPO participation carries allocation uncertainty, valuation risk, and post-listing volatility risk, but it does not usually ask users to evaluate a Mirror Note structure. Pre-market trading carries execution risk, thin liquidity, and spread risk. A fast price move in a thin session is not the same risk event as a refund-triggered cancellation in a pre-IPO note product.
The strongest comparison habit is therefore to match risk to route. Product-structure risk belongs to Gate Pre-IPOs. Allocation-and-listing risk belongs to traditional IPOs. Session-liquidity risk belongs to pre-market trading. This habit helps investors avoid treating every offer around new companies as the same investment simply because each route appears near an IPO timeline. It also helps when investors compare private companies with public companies, because the trade path, the offer structure, and the price behavior can change from one route to the next.
Which route fits which user question?
A user asking, "How can I use Gate to access a value-tracking product before a listing?" is asking about Gate Pre-IPOs. A user asking, "How do I apply for actual shares at IPO?" is asking about a traditional broker-led IPO route. A user asking, "Can I trade the stock before the regular session opens?" is asking about pre-market trading. Those are three different investment questions, and each question leads investors to a different type of company access, price path, and trade workflow.
This language discipline matters because similar labels create false equivalence. Readers who want Moonshot AI (KIMI) specifics should stay inside the Gate Pre-IPOs lens rather than borrowing assumptions from public-equity pre-market sessions. For investors, that discipline is helpful because it keeps the company story, the IPO path, and the actual trade mechanics in the right order.
Summary
Gate Pre-IPOs, traditional IPO participation, and pre-market trading all sit close to the listing timeline, but they are different products with different rights, liquidity paths, and risks. Gate Pre-IPOs is a Mirror Note route on Gate, traditional IPO participation is a direct-share allocation path through brokers or underwriters, and pre-market trading is a market session for already listed shares.
The cleanest way to compare them is to ask four questions: What do users receive, what legal rights come with it, when does liquidity appear, and what happens if the listing path changes? Those answers usually make the product differences much clearer than the labels alone.
FAQ
Is Gate Pre-IPOs the same as buying IPO shares?
No. Gate states that products such as Moonshot AI (KIMI) are Mirror Notes and do not represent actual stocks or shares in the target company. Traditional IPO participation seeks actual shares through a broker or underwriter channel.
Is pre-market trading the same as pre-IPO access?
No. Pre-market trading usually refers to trading listed shares during a special market session before the regular open. It is not the same as subscribing to a pre-listing structured product.
Which route gives direct issuer-share ownership?
Traditional IPO allocation is the route most directly associated with actual issuer-share ownership if allocation is received. Gate Pre-IPOs Moonshot AI (KIMI) does not provide that direct share relationship under Gate's own disclaimer.
Why can Gate Pre-IPOs have refund rules while pre-market trades do not?
Gate Pre-IPOs is a product with platform-defined subscription and settlement terms, so it can include cancellation and refund triggers in the product design. Pre-market trading is ordinary market execution inside a special session, so it follows normal trade mechanics rather than note-product refund mechanics.
How do companies reach investors in each route?
Companies do not reach investors in the same way across these routes. In a traditional IPO, the company and its underwriters make a public offer that can place shares with investors before exchange trading starts. In Gate Pre-IPOs, the platform offers a Mirror Note product tied to the company rather than direct company-issued shares. In pre-market trading, investors trade after a public market framework already exists and price discovery is already underway.
What should investors review before investing through any of these routes?
Investors should review what instrument is being offered, whether the company is still private or already public, how shares or note exposure are created, what price mechanism applies, and what risks belong to that route. This review helps separate a public-share investment from a private-company access product and from a time-window trade in a pre-market session. It is especially helpful when companies receive a lot of attention before listing, because attention alone does not tell investors what the actual offer is or how the trade will work.
Are there alternatives to investing in an IPO directly?
Yes. Gate Pre-IPOs is one example of an alternative route that offers exposure tied to companies before listing without becoming a standard IPO share allocation. Pre-market trading is another alternative activity, but it belongs to public-market trading rather than private-company access. Investors should compare the investment objective, rights, trade timing, and price behavior before deciding which route best fits the company and the market they want to follow. In some cases, waiting until the public stock starts to trade can be a clearer choice than using a private-company note or a thin pre-market trade.
What should investors know before investing in an IPO?
Investors should know how the IPO offer works, whether allocation is likely, how the company plans to use the public market, and what price and volatility risks can follow after listing. The right review is not only about the company but also about how the offer reaches investors and when actual public trading begins.
Why do some investors use alternatives to investing in an IPO?
Some investors use alternatives because direct IPO allocation can be limited, company access can be uneven, and public-share offers may not be available to every account. Gate Pre-IPOs is one alternative that gives investors access to companies through a structured note, while pre-market trading gives investors a chance to trade after a public market framework already exists.
How does pre-market trading work compared with an IPO offer?
Pre-market trading works through a market session where investors trade a stock before the regular open, often with thinner liquidity and wider price spreads. An IPO offer, by contrast, is the structured process through which shares are allocated before or at listing. The difference matters because the trade mechanics, the price discovery, and the investor experience are not the same.