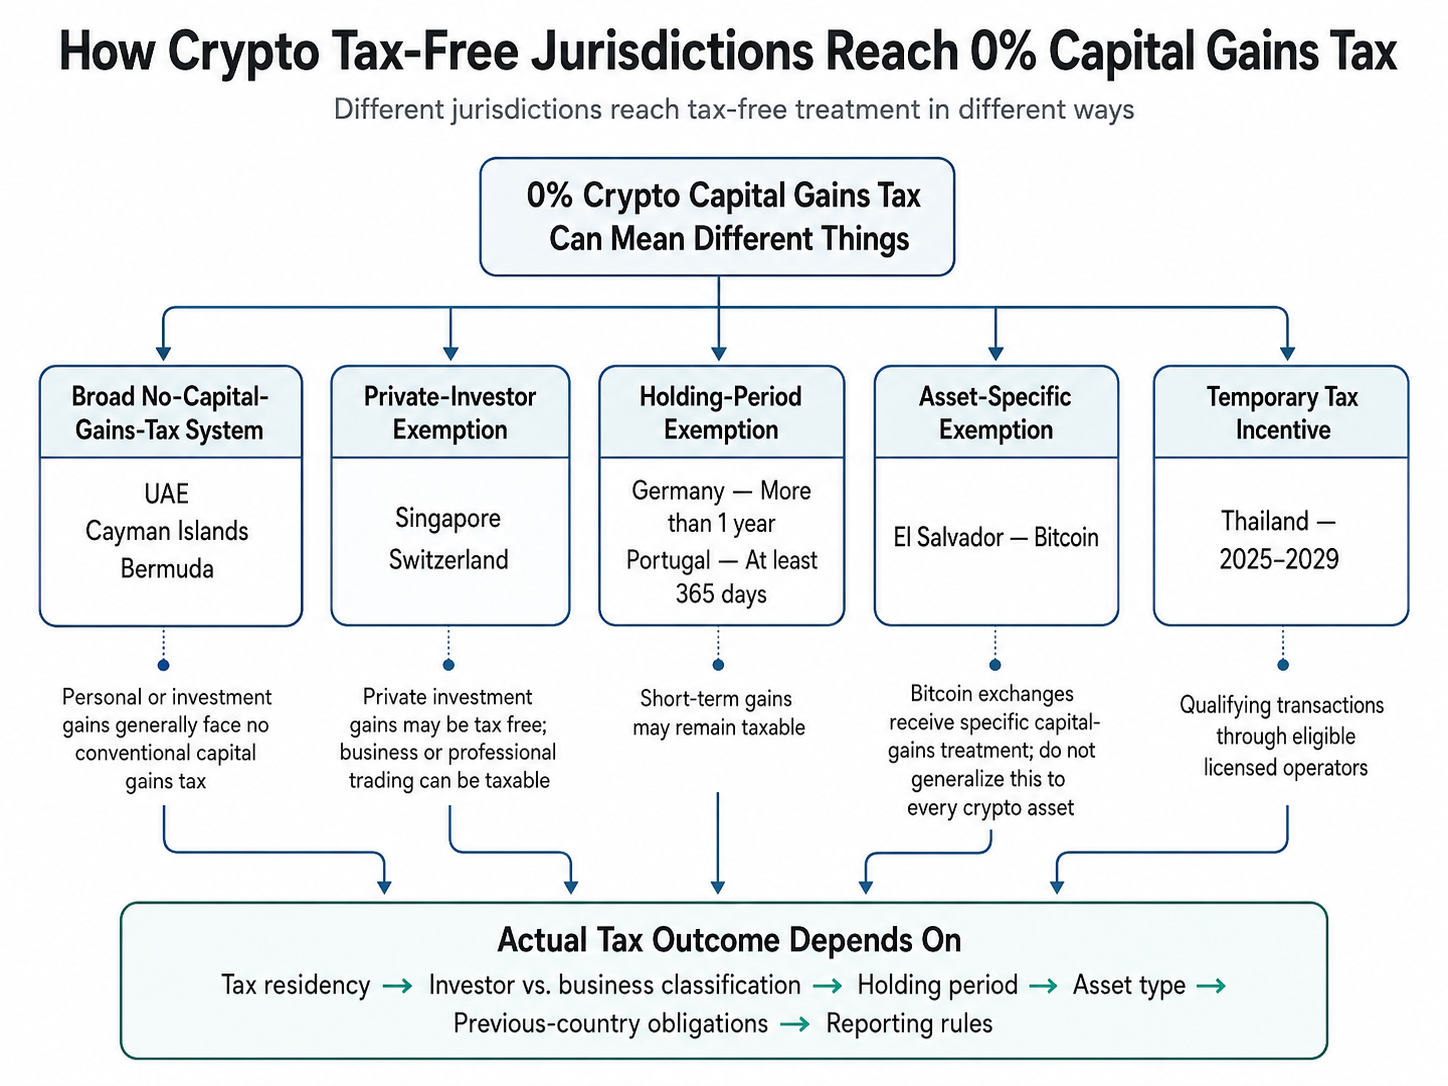
Countries with no crypto capital gains tax include jurisdictions where qualifying personal investment gains are generally untaxed, such as the UAE, Singapore, Switzerland, Cayman Islands, and Bermuda, while Germany, Portugal, El Salvador, and Thailand provide narrower or conditional advantages. However, crypto tax free rarely means every investor, asset, or transaction can avoid tax.
For crypto investors, foreign investors, internationally mobile professionals, and founders comparing crypto tax-free countries, the key questions are where they hold tax residency, whether digital asset profits are treated as capital gains or business income, how long crypto was held, and whether specific crypto tax legislation creates exclusions. These distinctions determine whether someone must pay capital gains tax, pay income tax, or has no local tax liability at all.
Key Takeaways
The UAE does not impose a conventional federal personal income tax, while qualifying personal investment income generally falls outside corporate tax for natural persons.
Singapore and Switzerland generally do not impose capital gains tax on qualifying personal crypto investments, although professional or business activity can become taxable.
Germany generally exempts qualifying private crypto gains after more than one year, while Portugal generally excludes qualifying crypto gains after a 365-day holding period.
El Salvador's Bitcoin Law exempts Bitcoin exchanges from capital gains tax, although the law was amended in 2025 to make private-sector acceptance voluntary.
Cayman Islands and Bermuda have broad low-tax systems without conventional individual income or capital gains taxes, but foreign tax obligations can still follow an investor across borders.
Countries With No Crypto Capital Gains Tax Compared
Most countries tax crypto according to ordinary capital gains, income, or property rules. A smaller group either does not impose capital gains tax at all or creates exemptions for certain crypto transactions.
Jurisdiction
Typical individual crypto treatment
Important limitation
UAE
Personal investment gains generally face no personal income or capital gains tax
Business activity can fall under corporate tax
Singapore
Capital gains generally untaxed
Business-like crypto trading can be taxable income
Switzerland
Private capital gains generally tax free
Professional trading and wealth tax can apply
Cayman Islands
No conventional individual income or capital gains tax
Foreign tax obligations and residency still matter
Bermuda
No conventional individual income or capital gains tax
Other local taxes may apply
Germany
Qualifying gains generally tax free after more than one year
Short-term disposals may be taxable
Portugal
Qualifying gains generally excluded after 365 days
Short-term qualifying gains generally face a 28% rate
El Salvador
Bitcoin exchanges exempt from capital gains tax
Exemption specifically concerns Bitcoin
Thailand
Temporary exemption for qualifying crypto gains
Limited to eligible transactions and 2025–2029 period
A country's headline gains tax rate therefore provides only part of the answer. The broader rules governing crypto capital gains tax determine when cryptocurrency acts as a capital asset, business income, miscellaneous income, or another category of taxable income.
UAE: Why Dubai Is Considered Crypto Tax Free
The United Arab Emirates is one of the strongest examples behind searches for Dubai crypto tax free. Individuals do not face a conventional UAE federal personal income tax or federal income tax rate on salary or personal investments, and personal investment income is generally excluded when determining whether a natural person is carrying on a business for UAE corporate tax purposes.
Natural persons generally become subject to UAE corporate tax when they conduct a business or business activity and annual turnover exceeds AED 1 million. Wages, personal investment income, and qualifying real-estate investment income are excluded from that calculation.
The distinction is important because having no personal income tax rate or personal income tax rate does not mean every crypto company faces a zero tax rate. Crypto businesses may encounter corporate income tax, licensing requirements, VAT, and other obligations depending on their activities.
The UAE also uses residency programmes as part of its broader investment environment. Certain Golden Visa investor routes require qualifying investment of at least AED 2 million. Tax policy, regulatory clarity, investment access, and infrastructure together help explain why some global crypto hubs attract both capital and technology businesses.
Singapore: No Capital Gains Tax, but Trading Can Become Income
Singapore does not maintain a general capital gains tax. As a result, individuals who hold cryptocurrency as a personal investment generally do not owe capital gains tax when disposing of it for a gain.
The distinction changes if crypto trading amounts to a trade or business. Singapore's Inland Revenue Authority considers factors such as transaction frequency, holding period, reason for acquisition, and circumstances of disposal when distinguishing investment from business activity.
A trader may therefore have to pay income tax even though Singapore has no general capital gains tax. For active crypto trading, the economic substance of the activity matters more than simply describing digital assets as investments.
Singapore also illustrates how favorable taxation can coexist with substantial residency barriers. Its Global Investor Programme requires significant investment, with one route requiring at least S$10 million in a qualifying business.
Switzerland: Tax-Free Capital Gains for Private Investors
Switzerland generally does not tax capital gains earned by private individuals from qualifying personal crypto investments. However, its national and cantonal tax system distinguishes private wealth management from professional securities or crypto trading.
Someone classified as a professional trader may face ordinary income taxation instead of the tax-free treatment applied to private capital gains. Cryptocurrency held as private wealth may also contribute to cantonal wealth tax.
Switzerland therefore offers a favorable tax environment without being completely crypto tax free. Its broader Crypto Valley ecosystem combines tax treatment with regulatory certainty, financial services, company formation, and digital-asset infrastructure.
The distinction is useful for anyone comparing a genuine crypto tax haven with a jurisdiction that simply gives individual investors favorable treatment.
Cayman Islands and Bermuda: Broad Low-Tax Systems
Cayman Islands and Bermuda are closer to classic tax-haven structures because residents generally face neither conventional personal income tax nor capital gains tax.
The Cayman Islands does not levy individual income, capital gains, inheritance, or wealth taxes. Its financial sector is regulated separately by the Cayman Islands Monetary Authority, showing that absence of individual capital gains taxation does not mean the crypto market operates without financial regulation.
Corporate structures also require separate analysis. A jurisdiction may have no conventional corporate tax rate or standard corporate tax rate on ordinary companies while still imposing licensing fees, economic-substance requirements, payroll charges, or sector-specific obligations.
Bermuda similarly relies on other sources of government revenue instead of conventional personal income and capital gains taxes.
For tax residents, these systems can substantially reduce local taxation of crypto gains, but they do not automatically cancel liabilities created by another country's tax laws.
Germany and Portugal: Crypto Gains After One Year
Germany and Portugal are often grouped with tax-free crypto countries, but neither offers an unrestricted zero-tax regime.
In Germany, qualifying crypto gains realized by private individuals after a holding period exceeding one year are generally outside taxation under the current framework. Disposals within the relevant shorter period can instead create taxable gains.
Germany also offers a residence route for people establishing a business or working on a self-employed basis. Its self-employment residence permit requires factors such as financing, economic or regional demand, and a positive expected effect on the economy; Germany does not specify a universal fixed minimum business investment for this route.
Portugal uses a similar long-term distinction. Qualifying crypto assets held for at least 365 days can generally be disposed of without capital gains taxation, whereas qualifying gains on assets held for less than one year are generally taxed at 28%.
Portugal's D7 residence route is commonly associated with applicants who can demonstrate recurring passive income. For 2026, the baseline commonly cited for a single applicant is €920 per month, reflecting Portugal's minimum-wage benchmark, although consular documentation and financial requirements should always be checked when applying.
These rules show why long-term holding periods can create tax benefits even in countries that normally require investors to pay tax.
El Salvador: Bitcoin Capital Gains Remain Exempt
El Salvador provides one of the clearest examples of specific crypto tax legislation.
The country's Bitcoin Law states that exchanges involving Bitcoin are not subject to capital gains tax. Bitcoin was originally established as legal tender in 2021, and the tax exemption was retained when the law was amended in 2025. The reforms made private-sector acceptance voluntary and changed several aspects of the state's role in Bitcoin transactions.
This means the statement that El Salvador eliminated capital gains tax on Bitcoin transactions remains broadly accurate for the Bitcoin exchanges covered by the law. It should not, however, be expanded into a claim that all cryptocurrencies, all crypto income, or every form of business income is tax free.
El Salvador's general tax system still taxes other forms of income and capital gains. An OECD review, for example, documented a general individual income-tax system and separate taxation of capital gains outside the Bitcoin exemption.
The distinction between Bitcoin and the wider crypto market is therefore essential.
El Salvador also operates the Freedom Passport programme, under which qualifying applicants make a $1 million contribution denominated in Bitcoin or USDT for a citizenship pathway. Current programme information continues to state the $1 million contribution requirement.
Malta: Regulation Does Not Automatically Mean Zero Tax
Malta is sometimes included in lists of crypto-friendly jurisdictions because of its Virtual Financial Assets Act, which established a specific regulatory framework for virtual financial assets and related service providers. The law remains in force and has been amended several times since its original 2018 enactment.
However, the Virtual Financial Assets Act should not be interpreted as creating blanket tax-free treatment for crypto gains. Malta's tax treatment depends on the character of the transaction, residency, domicile, and whether gains or receipts constitute taxable income.
Its Malta Permanent Residence Programme provides a separate residency pathway. Current programme regulations define qualifying owned residential property as property purchased for at least €375,000 in Malta or Gozo.
That makes Malta useful in a jurisdiction comparison, but immigration eligibility, crypto regulation, and tax liability remain separate questions.
Why Tax Residency Matters More Than Where Crypto Is Held
Holding crypto on an overseas platform does not usually determine where someone must pay tax. Tax residency, citizenship in certain systems, domicile, source of income, and treaty provisions can matter more.
For example, someone leaving a country with a high federal income tax rate or standard income tax rates cannot assume that becoming an immigration resident elsewhere immediately removes the home country's taxing rights. A home country's tax authority or national tax service may examine when gains accrued, when residence ended, and whether exit-tax or worldwide-income rules continue to apply.
Crypto may also be characterized differently across borders. A country may treat it as a capital asset, digital property, virtual financial asset, business inventory, or in some contexts a form of private money. El Salvador provides an unusual case because its Bitcoin legislation gave Bitcoin a specific monetary status rather than applying only general crypto tax rules.
For practical records, a trader can use a BTC/USDT market chart on an exchange like Gate to reconstruct market prices around transactions. However, wallet records, exchange statements, acquisition cost, transaction fees, disposal dates, and tax-residency records are needed to determine actual tax liability.
International reporting is also reducing the value of hiding assets offshore. Frameworks such as the OECD Crypto-Asset Reporting Framework are designed to increase cross-border transparency for crypto transactions.
How to Compare Crypto Tax-Free Countries
Before choosing between countries with no crypto capital gains tax, investors should test six conditions:
Residency: Does the 0% treatment require genuine tax residency rather than only a visa or residence permit?
Asset scope: Does the exemption cover all crypto assets, or only Bitcoin or qualifying digital assets?
Holding period: Must investors hold crypto for 12 months or longer?
Activity classification: Could frequent trading be treated as business income or miscellaneous income?
Other taxes: Could wealth tax, corporate income tax, indirect taxes, or a standard corporate tax rate still apply?
Previous jurisdiction: Could gains remain taxable by the country where they accrued?
These conditions explain why jurisdictions offering zero capital gains tax alongside predictable regulation can attract crypto companies, venture capital, entrepreneurs, and individual investors. The wider global virtual-asset regulatory landscape also affects licensing, custody, reporting, and operating costs even when personal crypto gains receive favorable tax treatment.
Risks and Limitations of Crypto Tax Havens
The first limitation is change. Governments can introduce new taxes, remove holding-period exemptions, narrow eligibility, or create new reporting requirements. Temporary rules such as Thailand's current crypto incentive demonstrate why a zero-tax headline should always be attached to a date and legal condition.
Second, capital gains treatment does not determine every crypto tax. Mining rewards, staking income, salaries paid in crypto, professional trading, lending income, business receipts, and some airdrops can face income tax even where long-term investment gains are exempt.
Third, residency programmes do not themselves determine tax residency. Immigration residence, permanent residence, citizenship, and tax residence are legally distinct concepts.
Finally, foreign investors may still owe tax to another jurisdiction. Anyone considering relocation to legally reduce crypto tax should review departure-country rules, destination-country rules, treaties, asset classification, and the timing of disposals with a qualified tax professional.
Conclusion
Countries with no crypto capital gains tax use several different models. The UAE, Cayman Islands, and Bermuda operate broad low-tax systems; Singapore and Switzerland generally exempt private capital gains but can tax business-like trading; Germany and Portugal reward longer holding periods; and El Salvador provides a specific statutory capital gains exemption for Bitcoin.
The practical advantage of a tax-free jurisdiction therefore depends less on the headline 0% rate than on tax residency, asset classification, holding period, business activity, and obligations retained by another country. Crypto investors should compare those conditions together before assuming they will not pay capital gains tax or income tax.
FAQ
Which countries have no crypto capital gains tax?
The UAE, Singapore, Switzerland, Cayman Islands, and Bermuda can provide zero capital gains tax treatment for qualifying personal investment gains. Germany and Portugal offer important holding-period exemptions, while El Salvador specifically exempts Bitcoin exchanges from capital gains tax.
Is Dubai crypto tax free?
The UAE does not impose a conventional personal income tax on individuals, and qualifying personal investment income generally falls outside corporate tax rules for natural persons. Commercial activity conducted as a business can receive different treatment.
Does Germany tax crypto after one year?
Qualifying private crypto gains are generally tax free after a holding period exceeding one year under Germany's current rules. Shorter-term disposals can create taxable income or gains depending on the circumstances.
Does Portugal tax crypto held for less than 12 months?
Yes. Qualifying gains from crypto assets held for less than 365 days are generally subject to a 28% rate, while qualifying assets held for at least 365 days can benefit from the long-term exclusion.
Does El Salvador have capital gains tax on Bitcoin?
The Bitcoin Law provides that exchanges involving Bitcoin are not subject to capital gains tax. The 2025 amendments changed Bitcoin's acceptance rules but retained that tax exemption.
Does Malta's Virtual Financial Assets Act make crypto tax free?
No. Malta's Virtual Financial Assets Act primarily establishes regulation for virtual financial assets and associated services. It should not be interpreted as a general exemption from Maltese income or capital-gains taxation.
Disclaimer:This content is educational and does not constitute tax, legal, immigration, or financial advice. Tax treatment depends on residency, transaction type, individual circumstances, and changing legislation. Consult qualified tax and immigration professionals before making relocation or disposal decisions.
Author: Jared
Disclaimer
* The information is not intended to be and does not constitute financial advice or any other recommendation of any sort offered or endorsed by Gate.
* This article may not be reproduced, transmitted or copied without referencing Gate. Contravention is an infringement of Copyright Act and may be subject to legal action.
Stablecoins were originally designed as dollar substitutes within exchanges, primarily used for asset pricing and trade settlement. As on-chain financial ecosystems have matured, their role has expanded beyond simple payments to include collateral assets, cross-chain liquidity mediums, and unified settlement units. In particular, as AI systems and automated agents begin to participate directly in economic activity, demand has risen sharply for programmable value units capable of instant settlement. This shift is pushing stablecoins toward the role of foundational financial infrastructure.
In the competition for DeFi liquidity, high-inflation mining alone is no longer enough to build lasting advantages. Aerodrome applies the ve(3,3) economic model to redesign token emissions, voting mechanisms, and revenue distribution, creating a liquidity flywheel centered on governance and cash flow. This article examines AERO tokenomics, the veAERO locking mechanism, and protocol revenue models to explain how Aerodrome builds a sustainable DeFi economic system.
PAXG (Pax Gold) is a tokenized asset backed by physical gold, issued by the fintech company Paxos and traded on the Ethereum blockchain as an ERC-20 token. The core concept is to tokenize physical gold on-chain, with each PAXG token representing ownership of a certain amount of gold. This structure enables investors to hold and trade gold in the form of a digital asset.
AERO is the native token of Aerodrome Finance, a core decentralized exchange and liquidity protocol in the Base ecosystem. It is primarily used for liquidity incentives and ecosystem operations. veAERO is a governance NFT that users receive by locking AERO, representing both voting power and the right to share protocol revenue. Through a dual track structure of AERO as a utility token and veAERO as a governance credential, Aerodrome separates liquidity usage value from long term governance power, allowing participants to act as liquidity providers, governance decision makers, and revenue sharers within the same system.
PAXG (Pax Gold) is a tokenized asset backed by physical gold reserves, launched by fintech firm Paxos and issued as an ERC-20 token on the Ethereum blockchain. The core concept is to digitally represent real-world gold assets, allowing investors to hold and trade gold via the blockchain network. Because each PAXG token corresponds to a specific quantity of physical gold, its price is theoretically expected to closely track the global gold market.
In the early stages of the crypto market, traditional stablecoins mainly relied on single-reserve or single-collateral models. Their primary focus was price stability and payment convenience, which allowed them to become foundational tools for on-chain trading and capital flows. As the market has entered a more mature financial phase, however, this structure has begun to reveal limitations, including high concentration risk and the difficulty of balancing liquidity with yield. These constraints have driven the evolution toward multi-layer collateral and portfolio-based designs, such as the dual-layer hybrid collateral architecture proposed by United Stables, which seeks to redefine the underlying logic of stable assets.